
 Digital Class-D Amplifier Market | 2026-2036
Digital Class-D Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Class-D Amplifier Market Insights
East Asian foundry capacity is pivoting toward gallium-nitride compatible processes for high-efficiency audio switching. Infineon Technologies AG leverages its vertical power semiconductor footprint to dominate automotive-grade module supply. Texas Instruments sustains broad catalog coverage across integrated and standalone architectures. STMicroelectronics anchors European design-ins through its MEMS and audio convergence portfolio.
A digital Class-D amplifier converts pulse-code modulation streams into power-stage switching waveforms through sigma-delta or pulse-width modulation topologies, achieving efficiencies exceeding 90 percent while minimizing thermal dissipation in space-constrained enclosures. Integrated devices command the largest revenue pool by collapsing gate drivers, power stages, and protection logic into single packages, though standalone driver ICs capture design wins where thermal separation or voltage scalability matters. Consumer electronics and automotive audio end-use segments diverge sharply in qualification requirements, with the latter demanding AEC-Q100 compliance and functional-safety documentation that elongate design cycles but protect margin structures.
The EPA, EU Green Deal efficiency frameworks, and China's MIIT dual-carbon targets collectively elevate minimum performance thresholds for audio subsystems in vehicles and appliances. REACH substance restrictions and RoHS lead-free mandates constrain solder and substrate choices, pushing suppliers toward halogen-free laminates and tin-silver-copper alloys. Stakeholders must track GaN power-device cost curves and AEC-Q100 revision timelines to time capacity commitments and qualification investments.
Market Dynamics
Electrification of vehicle architectures is reallocating thermal budgets toward cabin electronics, forcing audio subsystem designers toward switch-mode topologies that minimize heat dissipation in constrained enclosures. This thermal imperative now governs procurement specifications across automotive tiers.
Growth Catalysts
- EU Green Deal efficiency mandates:European OEMs must reduce vehicle energy consumption, compelling adoption of Class-D amplification in premium audio configurations.
- GaN power-device maturation:Gallium-nitride switching transistors enable higher frequencies with lower losses, opening design space for compact multichannel modules.
- China's MIIT dual-carbon targets:Appliance manufacturers face binding efficiency thresholds that favor digital amplification in white goods and consumer electronics.
Market Restraints
- Silicon substrate cost volatility:Wafer pricing fluctuations compress margin buffers for integrated module suppliers dependent on 200mm foundry capacity.
- East Asian foundry concentration:Taiwan and South Korea control critical BCD and HV-CMOS process nodes, creating geographic supply vulnerability.
- EMI suppression complexity:Switching noise at higher frequencies demands ferrite and shielding materials that add BOM cost and assembly steps.
Strategic Opportunities
- India's PLI scheme for electronics:Manufacturing incentives attract module assembly investments targeting domestic automotive and appliance demand.
- Functional-safety convergence:AEC-Q100 qualification opens adjacent markets in industrial audio and medical alert systems requiring documented reliability.
- Direct-to-tier procurement:OEMs are bypassing traditional distributor channels for high-volume driver IC contracts, compressing channel margins.
Industry Challenges
- EMC engineering talent scarcity:Qualified engineers who can optimize switching waveforms for CISPR 25 automotive emissions limits command premium compensation.
- AEC-Q100 revision timelines:Extended qualification cycles delay revenue recognition for new process nodes and package innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Class-D Amplifier Market |
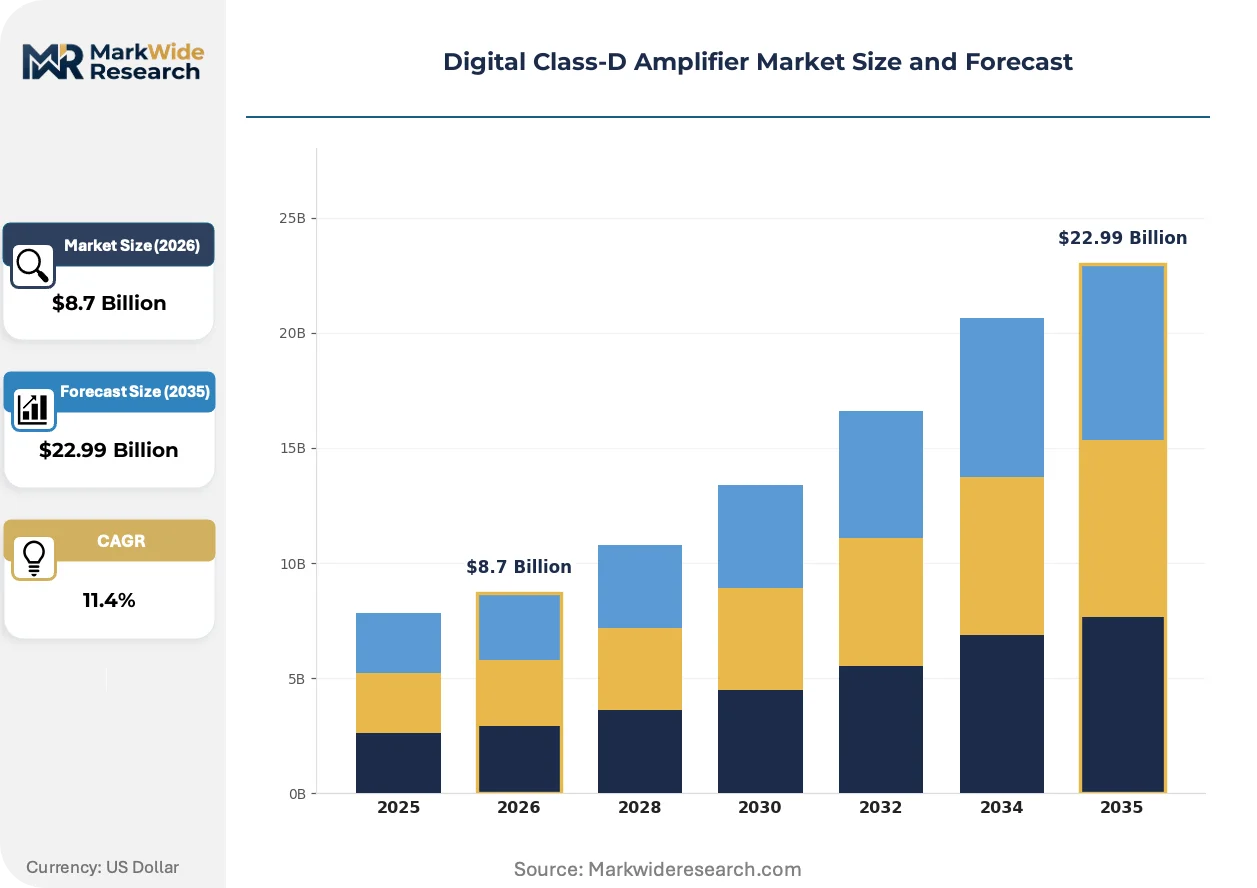
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated, Module, Standalone, Driver Technology: Analog, Digital Signal Processing, Pulse Width Modulation, Hybrid End User: Consumer Electronics, Automotive Audio, Professional Audio, Home Theater Application: Television, Sound Systems, Musical Instruments, Home Automation |
| Companies Covered | Infineon Technologies AG, Analog Devices Inc., NXP Semiconductors, ON Semiconductor, ROHM Semiconductors, Texas Instruments, STMicroelectronics, Renesas Electronics, Qualcomm Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Class-D Amplifier Market Trends and Innovations
Audio amplification is undergoing a materials and architecture transition that redefines competitive positioning. Three concurrent developments are compressing traditional design cycles and opening new specification tiers.
Gallium-nitride power stages are consolidating high-frequency switching performance into smaller thermal footprints. Automotive tier-1 suppliers are adopting GaN drivers for premium multichannel configurations ahead of mass-market silicon solutions. This transition is consolidating module supplier margins around process expertise rather than discrete component sourcing.
REACH substance restrictions and RoHS lead-free mandates are constraining solder alloy selection across European supply chains. Manufacturers must validate tin-silver-copper joints under thermal cycling conditions that exceed legacy tin-lead reliability. Automotive audio modules face the strictest compliance verification, with German OEMs demanding full material disclosure back to smelter origins.
Fleet procurement contracts are compressing supplier qualification windows as electrified vehicle platforms accelerate launch schedules. Tier-1 audio integrators now demand concurrent engineering support from semiconductor vendors rather than sequential sampling programs. This pattern is most pronounced in China, where domestic EV brands compress traditional 18-month design cycles to 10 months.
Digital Class-D Amplifier Market Segmentation
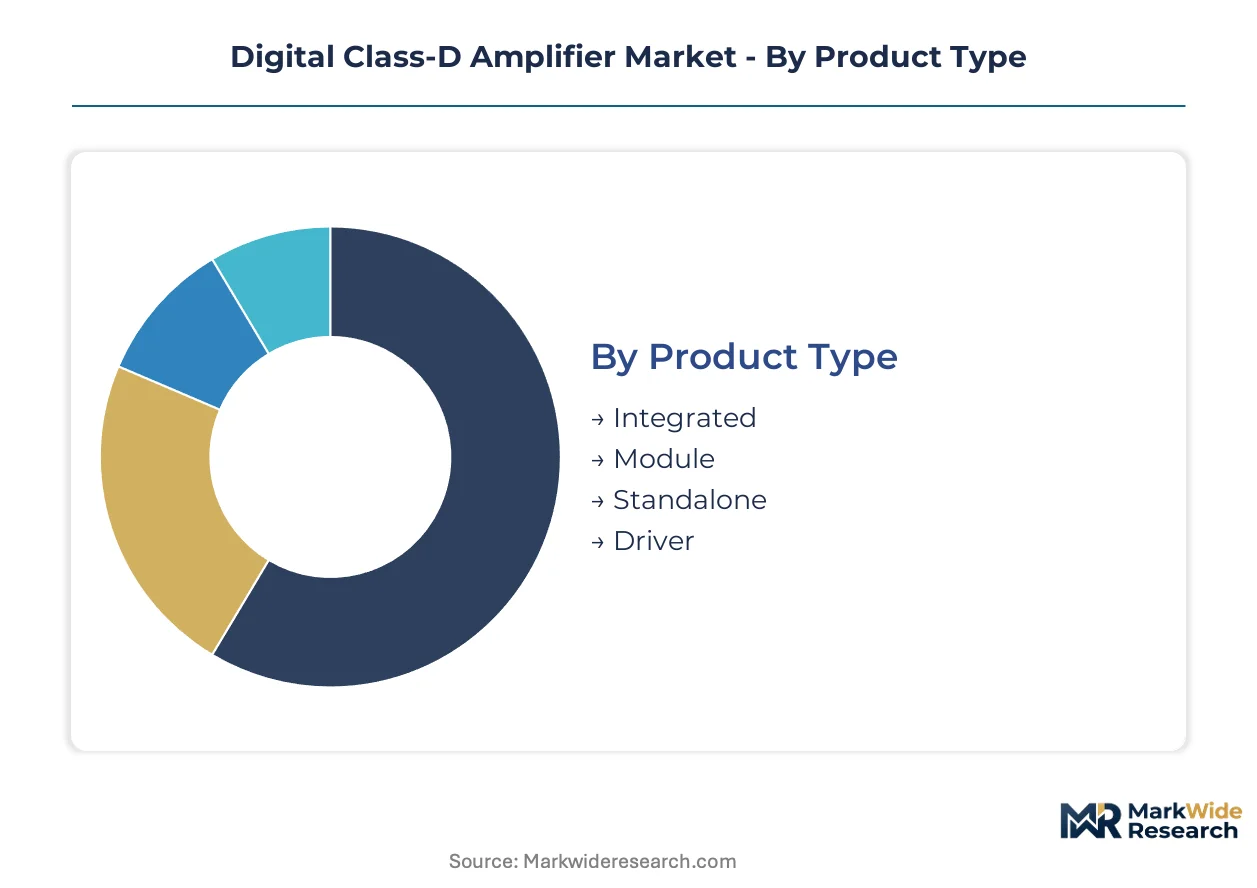
Digital Class-D amplifier segmentation reflects divergent thermal, integration, and qualification requirements across automotive, consumer, and professional audio ecosystems. Technology choices and product architectures determine supplier margins and design-cycle duration.
Product Type:
Integration density defines cost structure and thermal management strategy.
- Integrated:Collapses gate drivers, power stages, and protection logic into single packages. Consumer electronics manufacturers in China absorb the highest volumes as white-goods electrification accelerates under MIIT efficiency mandates.
- Module:Pre-validated multichannel assemblies with isolated thermal interfaces. German automotive tier-1s specify these for premium EV audio configurations where AEC-Q100 compliance and ferrite shielding integration reduce EMC engineering cycles.
- Standalone:Discrete power stages requiring external gate drive and protection circuitry. Professional audio OEMs favor these for voltage scalability in touring-grade amplifier racks.
- Driver:Dedicated gate-driver ICs enabling thermal separation between controller and power stage. Japanese home-theater manufacturers source these for compact multichannel receivers.
Integrated devices lead on scale; modules lead on momentum as automotive electrification reallocates thermal budgets.
Technology:
Modulation topology determines switching frequency, EMI signature, and fidelity performance.
- Analog:Continuous-time control loops with lower digital noise susceptibility. Legacy professional audio installations in the United States specify these where signal-chain purity outweighs efficiency priorities.
- Digital Signal Processing:Programmable coefficient banks enabling room correction and active crossover functions. South Korean television manufacturers integrate these for soundbar beam-steering applications.
- Pulse Width Modulation:Fixed-carrier switching with mature EMI suppression techniques. Dominates cost-optimized consumer electronics produced under China's dual-carbon efficiency frameworks.
- Hybrid:Combines analog front-end with digital feedback paths. Emerging in European automotive designs seeking to balance THD+N performance with GaN switching speeds.
Pulse Width Modification anchors volume; Digital Signal Processing climbs fastest as smart audio convergence accelerates.
End User:
Qualification intensity and margin structure vary sharply across customer categories.
- Consumer Electronics:High-volume, short-lifecycle products with minimal regulatory burden. Chinese appliance manufacturers drive procurement as MIIT efficiency thresholds harden.
- Automotive Audio:AEC-Q100 compliance and functional-safety documentation elongate design cycles. European OEMs under EU Green Deal mandates specify Class-D for cabin electronics thermal budget reallocation.
- Professional Audio:Tour-grade reliability requirements with voltage scalability demands. German and US live-sound equipment manufacturers prioritize standalone architectures.
- Home Theater:Multichannel density in constrained enclosures. Japanese and South Korean consumer electronics brands specify integrated modules with DSP convergence.
Consumer Electronics dominates shipment volume; Automotive Audio captures the steepest expansion trajectory as electrification restructures thermal budgets.
Application:
Use-case acoustics and installation constraints dictate channel count and shielding requirements.
- Television:Ultra-thin form factors demand sub-10mm amplifier modules. Chinese panel manufacturers integrate Class-D for soundbar and built-in audio under domestic efficiency regulations.
- Sound Systems:Portable and fixed installations spanning consumer to professional tiers. US and European brands specify GaN-enabled modules for battery-powered products.
- Musical Instruments:Modeling amplifiers and digital effects requiring low-latency signal paths. Japanese and German instrument manufacturers favor hybrid topologies.
- Home Automation:Distributed audio with voice-assistant integration. US smart-home ecosystem vendors specify DSP-enabled integrated devices for multi-room synchronization.
Television leads on unit scale; Home Automation gains share fastest as voice-interface penetration deepens residential installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is redistributing module assembly capacity toward economies with streamlined environmental compliance and concentrated electronics manufacturing ecosystems. Producers exploit cost-of-compliance gaps between REACH-heavy European markets and Asia-Pacific manufacturing zones.
China
Domestic EV brands compress audio subsystem design cycles from 18 months to 10 months, forcing concurrent engineering demands on semiconductor vendors. MIIT dual-carbon targets bind appliance manufacturers to efficiency thresholds that accelerate Class-D adoption in white goods. The Yangtze River Delta cluster around Shanghai and Suzhou concentrates gallium-nitride foundry investments and module packaging facilities.
Germany
Automotive tier-1s specify AEC-Q100-compliant modules for premium EV audio configurations under EU Green Deal efficiency mandates. KBA vehicle-type approval processes enforce CISPR 25 emissions compliance that elongates qualification cycles. Bavaria anchors power semiconductor design activity through Infineon Technologies AG's vertical manufacturing footprint.
United States
EPA fuel-economy rules push OEMs toward switch-mode amplification to reallocate thermal budgets toward cabin electronics. The Southeast manufacturing corridor attracts module assembly investments serving domestic automotive demand. Texas Instruments sustains broad catalog coverage from Dallas-Fort Worth operations spanning integrated and standalone architectures.
Japan
METI energy-efficiency standards for consumer electronics drive integrated Class-D adoption in compact multichannel home-theater receivers. Home-automation ecosystem vendors specify DSP-enabled devices for multi-room audio synchronization. The Kansai region around Osaka hosts precision analog-digital hybrid topology development for musical instrument applications.
South Korea
Television manufacturers integrate DSP-based Class-D for soundbar beam-steering under national broadcast equipment efficiency guidelines. The Seoul Capital Area concentrates fabless audio IC design houses serving Samsung and LG display divisions. Busan-Ulsan harbors module packaging capacity for export-oriented consumer electronics production.
Digital Class-D Amplifier Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue GaN-enabled premium configurations and functional-safety documentation services. The vendor base stratifies between integrated device specialists, automotive-grade module suppliers, and discrete driver IC catalog houses. Three archetypes dominate: European power semiconductor vertically integrated players, US broad-catalog analog vendors, and East Asian foundry-dependent fabless designers. Capacity expansion and AEC-Q100 qualification acceleration represent the dominant competitive moves.
Among European vertically integrated producers, Infineon Technologies AG and STMicroelectronics exemplify the automotive-grade module archetype through captive power semiconductor fabrication. Texas Instruments represents the broad-catalog strategy spanning integrated and standalone architectures across consumer and industrial tiers. These three anchors collectively demonstrate how process expertise and qualification documentation now outweigh discrete component sourcing as margin determinants.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Analog Devices Inc. |
| NXP Semiconductors |
| ON Semiconductor |
| ROHM Semiconductors |
| Texas Instruments |
| STMicroelectronics |
| Renesas Electronics |
| Qualcomm Technologies Inc. |
| Others |
Pricing and Supply Chain Analysis
Silicon wafer spot indices cascade through Class-D amplifier supply chains into three distinct pricing tiers: automotive-grade modules command premium positioning through AEC-Q100 qualification costs, consumer integrated devices compete on scale economies, and professional standalone architectures price around voltage scalability and thermal separation features.
Pricing Analysis
Distributor margins of 15-25 percent separate catalog pricing from direct-to-OEM contract rates, with automotive tier-1s negotiating volume-based discounts that compress channel economics. Price differentiation hinges on AEC-Q100 certification tier and gallium-nitride process node, with GaN-enabled modules carrying material premiums over silicon alternatives. Cost compression in consumer integrated segments intensifies as Chinese white-goods manufacturers consolidate procurement volumes. Appliance OEMs exhibit highest price sensitivity, while German automotive tier-1s prioritize qualification documentation over unit cost.
Supply Chain Analysis
Ocean freight rate volatility from East Asian ports to European automotive hubs adds 3-8 percent landed cost variation for module assemblies. Taiwan, South Korea, and China concentrate BCD and HV-CMOS foundry capacity, while Germany and the United States anchor automotive-grade packaging and test operations. Raw material dependencies span 200mm silicon wafers, gallium-nitride substrates, and halogen-free laminate substrates. Single-source vulnerability concentrates around Taiwan's gallium-nitride foundry investments. Distribution runs through authorized distributors for small-lot professional audio, direct contracts for automotive volumes, and contract manufacturers for consumer electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in digital Class-D amplification rests on GaN process cost-down curves and the shift toward premium automotive modules that capture efficiency-mandate premiums.
For Market Incumbents: Deepen captive gallium-nitride foundry relationships to defend process expertise margins against fabless entrants. Accelerate AEC-Q100 qualification pipelines for next-generation integrated modules before Chinese EV brands compress design cycles further. Capacity addition in India's PLI-subsidized electronics corridors hedges against East Asian foundry concentration risk. For New Entrants and Emerging Players: Mid-tier Indian automotive audio integrators represent an underserved buyer archetype with limited incumbent penetration. White-space targets include DSP-enabled home automation modules for US smart-home ecosystems and GaN driver ICs for Japanese compact home-theater receivers. A design-in partnership model with Yangtze River Delta contract manufacturers accelerates market access without captive fab investment. For Investors and Strategic Acquirers: Asymmetric upside sits with GaN-compatible power semiconductor specialists possessing automotive qualification documentation. Long-term viability favors vertically integrated European producers with in-house BCD capacity over fabless designers exposed to foundry allocation risk. The signal to watch is AEC-Q100 revision publication timing, which typically triggers qualification investment cycles and M&A activity among module suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Process Node Transition | Enables higher-frequency switching with reduced thermal footprint for premium automotive modules. |
| AEC-Q100 Qualification Acceleration | Opens adjacent industrial and medical audio markets requiring documented reliability standards. |
| India PLI Manufacturing Footprint | Captures domestic automotive and appliance demand while hedging East Asian supply concentration. |
| Direct-to-Tier Procurement Contracts | Bypasses distributor channels for high-volume driver IC agreements with compressed margins. |
| Concurrent Engineering Partnerships | Aligns semiconductor vendor support with Chinese EV brands' compressed 10-month design cycles. |
Research Methodology
Direct dialogue with automotive tier-1 procurement directors, semiconductor foundry planning executives, audio subsystem design engineers, and contract manufacturing program managers grounded qualitative insights. Secondary validation drew from EPA fuel-economy rulemakings, EU Green Deal implementation documents, MIIT efficiency standard publications, and AEC-Q100 revision drafts. SEC 10-K disclosures from power semiconductor suppliers, customs trade data for amplifier module flows, and IHS Markit vehicle production databases supplied quantitative anchors. Bottom-up bill-of-materials modeling and top-down OEM electronics budget allocation analysis were cross-referenced for triangulation.
Bottom-up segmentation modeling tracked integrated, module, standalone, and driver product architectures across consumer electronics, automotive audio, professional audio, and home theater end-use categories. Top-down validation referenced OEM thermal budget reallocation trends under electrification and efficiency mandate compliance costs. Analytical frameworks incorporated modulation topology adoption curves, GaN device cost trajectories, and regional regulatory divergence across the projection horizon. CAGRs were derived from segment-level volume build-ups and value-per-unit trends, with automotive audio content-per-vehicle assumptions and consumer electronics replacement cycle patterns as key forecast inputs.
Underlying measurement precision varies by segment; automotive audio carries tighter precision due to visible OEM platform commitments and AEC-Q100 qualification tracking, while professional audio exhibits higher uncertainty around touring equipment replacement timing. Forecasts reflect documented assumptions regarding gallium-nitride cost curves, foundry capacity expansion schedules, and regulatory mandate enforcement intensity. A model refresh is warranted upon material change in EU Green Deal implementation timelines or MIIT dual-carbon target revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Power Inductors Market
Electronic Components
Capacitive Stylus Pen Market
Electronic Components
Aluminum Electrolytic Capacitor Market
Electronic Components
Global Microfluidic Components Market
Electronic Components
Speaker Cone Material Market
Electronic Components
Switch Diode Market
Electronic Components
Structural Electronics Market
Electronic Components
RAID Controller Card Market
Electronic Components
Europe Radiation-Hardened Electronics Market
Electronic Components
Global DC Motor Control Devices Market
Electronic Components
Fixed Capacitor Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
Global Flexible Electronics and Circuit Market
Electronic Components
AC Adapter Market
Electronic Components
Operational Amplifier Market
Electronic Components
2D Electronics Market