
 China MCU Market | 2026-2036
China MCU Market Size, Share, and Industry Trends Forecast 2026-2036
China MCU Market Insights
Modular reference-design bundling is expanding as the dominant product-configuration pattern, with vendors packaging MCUs alongside pre-certified RF modules and power-management ICs to shorten customer development cycles. GigaDevice Semiconductor leverages its NOR flash-MCU integration to control cost-sensitive consumer segments. NXP Semiconductors anchors premium automotive-grade supply through its ASIL-certified portfolio. STMicroelectronics dominates industrial automation with its STM32 ecosystem extending into edge-AI inference subsystems.
A microcontroller unit integrates a processor core, volatile and non-volatile memory, and programmable peripherals onto a single die, typically fabricated at 40nm to 90nm nodes for mainstream applications, executing real-time control tasks in embedded systems. The 32-bit product category leads value generation as automotive ECUs and industrial motor controllers demand higher clock speeds and expanded memory addressing. Automotive application segments absorb the fastest volume growth, driven by domain-controller architectures and battery-management systems. OEM end users concentrate procurement leverage, with tier-one device manufacturers competing on firmware customization depth and certification support.
MIIT enforces GB/T standards for information-technology equipment, while SAMR administers quality-certification rules that constrain import pathways for non-compliant MCU suppliers. The country's dual carbon goals from MEE impose energy-efficiency benchmarks on industrial end-use equipment, redirecting demand toward low-power process nodes. Stakeholders must monitor how SMIC capacity allocation across mature nodes affects domestic supply security for 40nm and above geometries.
Market Dynamics
MIIT localization mandates and GB standards compliance requirements are compressing import pathways while redirecting procurement toward domestic-certified suppliers, fundamentally restructuring competitive access in automotive and industrial electronics supply chains.
Growth Catalysts
- Automotive domain-controller architectures:Battery-management systems and zonal ECU designs in domestic EV platforms are multiplying MCU content per vehicle. Tier-one suppliers are scaling 32-bit shipments to meet ASIL-grade functional-safety requirements.
- Dual carbon goals from MEE:Energy-efficiency benchmarks on industrial motor drives and HVAC equipment are redirecting demand toward sub-100nm low-power process nodes with integrated power-management subsystems.
- Yangtze River Delta cluster concentration:Shanghai-Jiangsu-Zhejiang manufacturing corridors are aggregating packaging, testing, and firmware-development capabilities, shortening NPI cycles for domestic OEMs.
Market Restraints
- Mature-node foundry allocation constraints:SMIC capacity prioritization for 28nm and below geometries is tightening supply security for 40nm-90nm MCU geometries serving mainstream automotive and industrial applications.
- SAMR quality-certification timelines:Extended CCC and CQC approval pathways for imported MCUs are creating inventory-positioning disadvantages for non-domestic suppliers without in-country testing facilities.
- Silicon carbide power-module substitution:Discrete intelligent power devices in simple motor-control applications are displacing MCU-plus-driver configurations in sub-500W consumer appliances.
Strategic Opportunities
- Edge-AI inference subsystems:Industrial automation OEMs are integrating neural-network accelerators alongside real-time control cores, opening premium pricing tiers for heterogeneous MCU-plus-NPU architectures.
- Modular reference-design bundling:Pre-certified RF modules and power-management ICs packaged with MCUs are shortening customer development cycles and locking in socket positions across consumer IoT device categories.
- GB/T 9254-2021 electromagnetic-compatibility mandates:Stricter EMI testing requirements for information-technology equipment are disqualifying uncertified competitors and creating certification-barrier advantages for compliant domestic vendors.
Industry Challenges
- Firmware customization depth:Automotive OEMs are demanding ASIL-D certified software stacks with traceable toolchains, stretching engineering resources at tier-one device manufacturers.
- Legacy system integration friction:Industrial retrofit projects require CAN-FD and LIN protocol backward compatibility with 1990s-era 8-bit architectures, complicating code migration and peripheral driver validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China MCU Market |
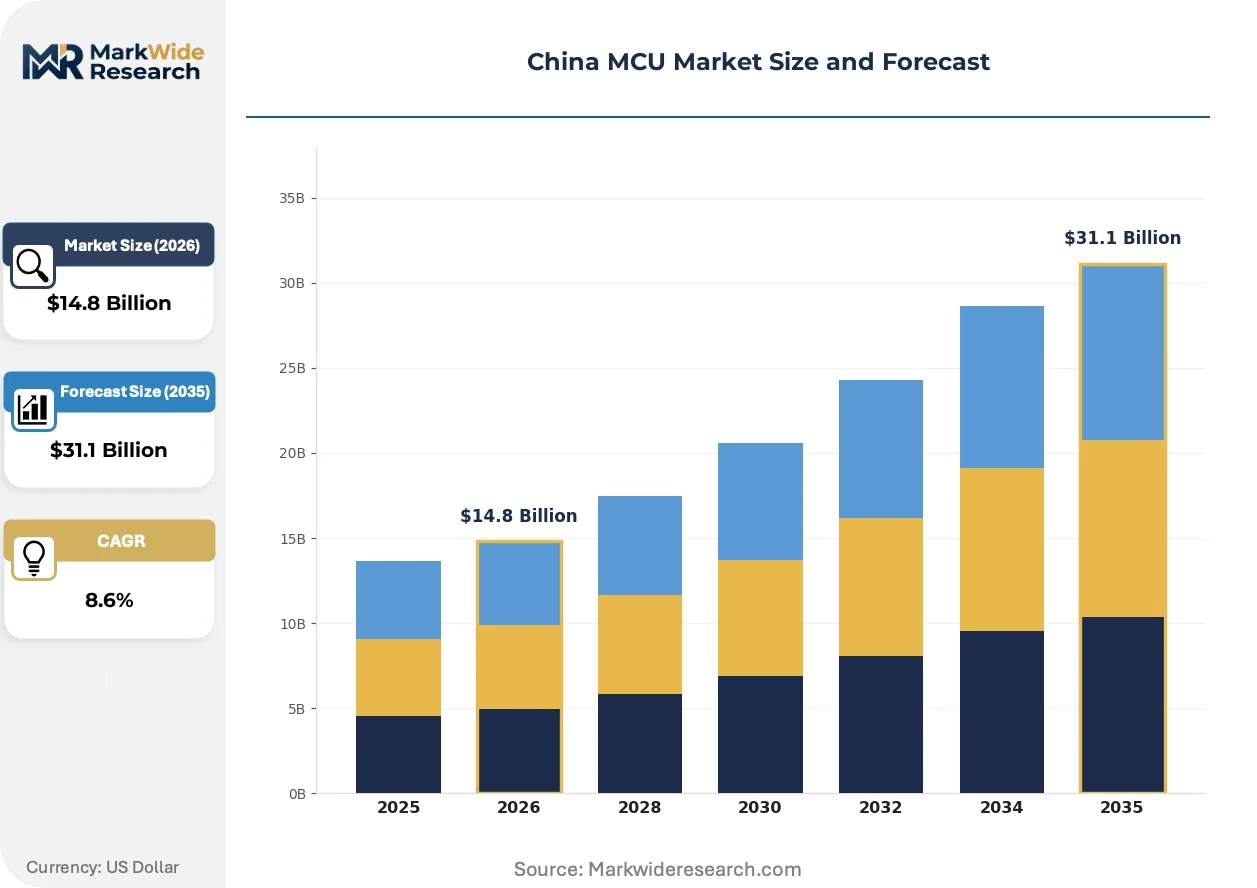
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 8-bit, 16-bit, 32-bit, 64-bit Application: Consumer Electronics, Automotive, Industrial Automation, Telecommunications Technology: Microcontrollers, Digital Signal Processors, Programmable Logic Controllers, System-on-Chip End User: OEMs, Device Manufacturers, System Integrators, Research Institutions |
| Companies Covered | STMicroelectronics, Infineon Technologies, NXP Semiconductors, Microchip Technology, Renesas Electronics, GigaDevice Semiconductor, Espressif Systems, Sinowealth, SMIC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China MCU Market Trends and Innovations
Real-time control architectures are converging with machine-learning inference at the edge, compressing hardware footprints while elevating software complexity requirements across automotive and factory-automation deployments.
RISC-V open-instruction-set architectures are consolidating proprietary ISA fragmentation in cost-sensitive consumer and IoT segments. Domestic fabless designers are migrating mid-range 32-bit portfolios away from ARM licensing fees. The shift is consolidating supplier margins and accelerating in-house core development at GigaDevice and other mainland vendors.
MIIT GB standards for functional safety and information-security certification are tightening procurement criteria for automotive ECUs and industrial controllers. SAMR enforcement of GB/T 34590 (functional safety) and GB/T 25000 (security) is disqualifying uncertified imports. Premium automotive-grade supply is responding with dedicated China-specific certification engineering teams and localized test facilities.
Buyers are compressing supplier qualification cycles through pre-certified subsystem procurement. Tier-one automotive OEMs are shifting from discrete component sourcing to domain-controller reference designs bundling MCUs, power stages, and RF connectivity. The pattern is most visible in Yangtze River Delta EV supply chains, where NPI timelines have compressed from 18 months to 9 months.
China MCU Market Segmentation
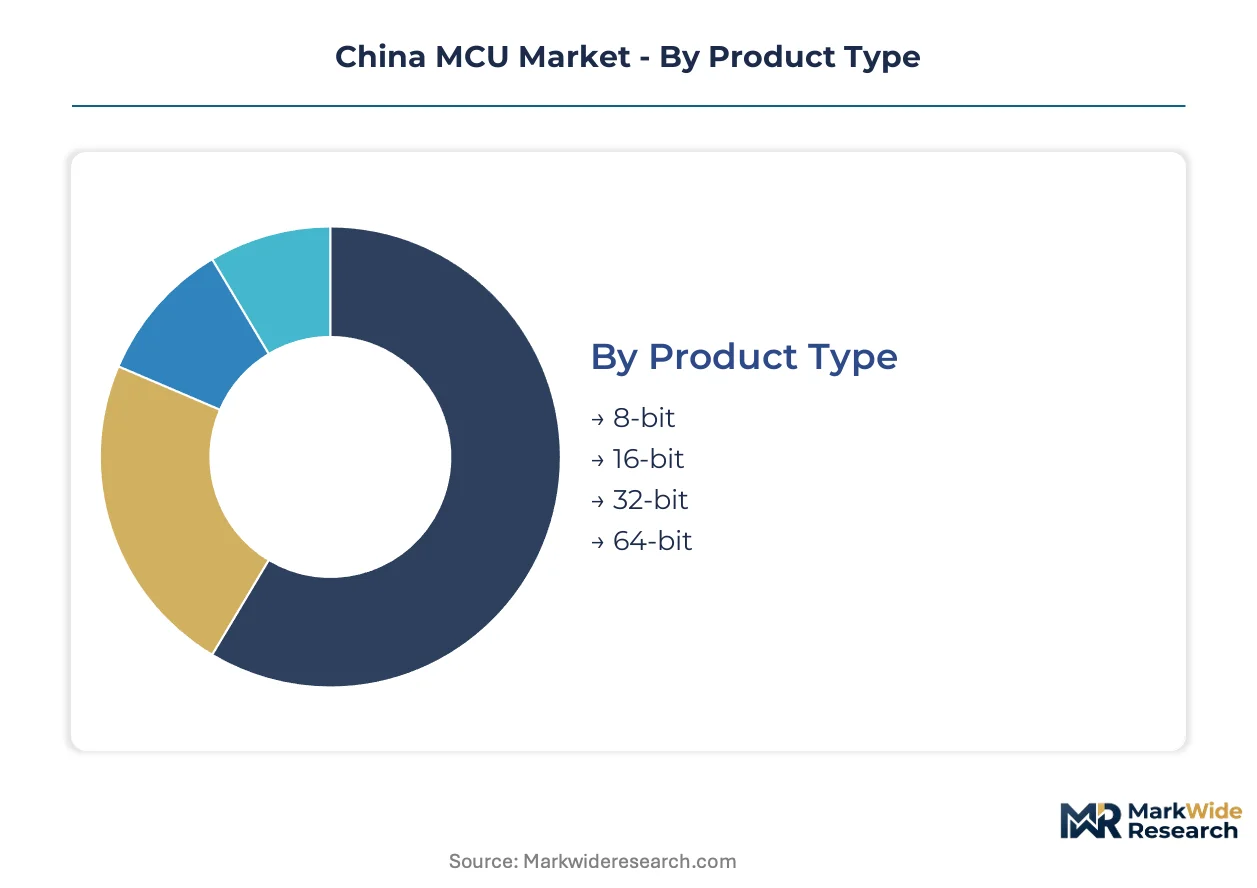
China's MCU segmentation reveals how capital intensity, certification requirements, and localization mandates fragment procurement patterns across automotive, industrial, and consumer supply chains. Each dimension carries distinct margin structures and competitive barriers that reshape supplier positioning.
Product Type:
32-bit architectures demand the heaviest upfront investment in ASIL-certified design teams and multi-layer verification flows, while 8-bit portfolios recover tooling costs through high-volume consumer shipments.
- 8-bit:Legacy cores with limited memory addressing dominate simple appliance controls and basic sensor interfaces. Cost-sensitive consumer electronics manufacturers in Guangdong province favor these devices for sub-dollar bill-of-materials targets, though MIIT efficiency mandates are compressing their addressable market in motor-drive applications.
- 16-bit:Mid-range architectures balance peripheral integration with modest clock speeds for industrial motor controllers and automotive body electronics. Demand concentrates in Jiangsu province manufacturing corridors where tier-one suppliers require CAN-FD compatibility without the cost overhead of full 32-bit implementations.
- 32-bit:ARM Cortex-M and RISC-V cores with expanded memory buses anchor domain controllers, battery-management systems, and edge-AI inference subsystems. Shanghai-based EV OEMs are scaling procurement for zonal ECU architectures, with MIIT GB/T 34590 functional-safety certification now mandatory for automotive sockets.
- 64-bit:High-performance application processors with integrated neural-network accelerators serve advanced driver-assistance systems and industrial vision platforms. These devices require 12nm-16nm finFET fabrication that SMIC cannot yet supply domestically, creating import dependency for premium automotive-grade silicon.
32-bit devices absorb the bulk of installed capacity; 64-bit architectures are expanding most quickly in premium automotive sockets.
Application:
Automotive procurement operates at the highest margin tier due to ASIL-D certification requirements, while consumer electronics segments compete on die-size optimization and flash-MCU integration.
- Consumer Electronics:White goods, wearable devices, and smart home controllers require ultra-low-power sleep modes and integrated touch-sensing peripherals. Zhejiang province appliance OEMs are consolidating socket positions around reference designs bundling MCUs with pre-certified RF modules to compress NPI cycles.
- Automotive:Domain controllers, battery-management systems, and zonal ECUs multiply MCU content per vehicle while elevating functional-safety requirements. Yangtze River Delta EV supply chains are absorbing the steepest volume expansion as domestic OEMs localize tier-one component sourcing under MIIT procurement directives.
- Industrial Automation:Programmable logic controllers, servo drives, and robotic motion controllers demand real-time deterministic response with integrated industrial Ethernet. MEE dual carbon goals are redirecting demand toward sub-100nm geometries with active power-management subsystems in motor-drive applications.
- Telecommunications:Baseband processing, power-amplifier control, and network timing equipment require extended temperature ranges and radiation tolerance for infrastructure deployments. 5G small-cell rollouts in eastern coastal provinces are stabilizing demand for industrial-grade 32-bit portfolios.
Automotive applications command the highest average selling prices; industrial automation is climbing the fastest as retrofit cycles accelerate under energy-efficiency mandates.
Technology:
System-on-Chip integration demands the most complex verification flows and longest design cycles, while discrete microcontroller architectures offer faster time-to-revenue for fabless competitors.
- Microcontrollers:Standalone processors with integrated flash, SRAM, and programmable peripherals fabricated at 40nm-90nm nodes. These devices dominate cost-sensitive consumer and industrial sockets where firmware customization depth determines competitive positioning.
- Digital Signal Processors:Specialized architectures with hardware multiply-accumulate units and circular addressing modes for real-time signal processing. Motor-control and power-inverter applications in Jiangsu province manufacturing clusters favor these devices for sensorless field-oriented control algorithms.
- Programmable Logic Controllers:Industrial control platforms with deterministic I/O scanning and ladder-logic execution engines. Heavy industry retrofit projects in northern provinces are sustaining demand despite longer replacement cycles compared to consumer electronics.
- System-on-Chip:Heterogeneous integration of application processors, neural-network accelerators, and connectivity subsystems on single die. Edge-AI inference requirements in smart factory deployments are driving premium pricing for these complex devices.
Microcontrollers absorb the bulk of wafer starts; System-on-Chip architectures are expanding most quickly in edge-AI industrial deployments.
End User:
OEMs wield the strongest procurement leverage through volume consolidation and qualification-driven supplier lock-in, while research institutions represent the smallest but most strategically significant demand segment for next-generation architecture validation.
- OEMs:Automotive and industrial equipment manufacturers with direct component specification authority and long-term supply agreements. These buyers are compressing supplier qualification cycles through pre-certified subsystem procurement in Yangtze River Delta EV supply chains.
- Device Manufacturers:Tier-one component suppliers and contract electronics manufacturers assembling finished goods for brand owners. SAMR CCC certification timelines are forcing these intermediaries to maintain larger safety stocks of domestically certified MCU inventory.
- System Integrators:Industrial automation and building-control specialists configuring customized solutions from discrete hardware and firmware modules. These buyers prioritize reference-design availability and technical support depth over unit cost minimization.
- Research Institutions:Universities and national laboratories evaluating emerging RISC-V architectures and advanced packaging technologies. MIIT funding for domestic semiconductor capability building is expanding procurement budgets at these organizations.
OEMs absorb the bulk of high-volume procurement; system integrators are expanding most quickly as industrial retrofit activity accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate MCU demand through integrated circuit design parks and bonded logistics zones that shorten procurement cycles for automotive tier-one suppliers.
Yangtze River Delta
Shanghai-based EV OEMs multiply MCU content per vehicle through zonal ECU architectures and battery-management systems. MIIT localization mandates redirect procurement toward domestic-certified suppliers with in-country test facilities. The Jiangsu-Zhejiang manufacturing corridor aggregates packaging, testing, and firmware development capabilities that compress NPI cycles from 18 months to 9 months.
Pearl River Delta
Guangdong province appliance manufacturers favor 8-bit devices for sub-dollar bill-of-materials targets in white goods and smart home controllers. SAMR CCC certification timelines force tier-one assemblers to maintain larger safety stocks of domestically certified inventory. Shenzhen hardware accelerators incubate reference-design bundling patterns that lock in socket positions across consumer IoT categories.
Beijing-Tianjin-Hebei
Industrial automation OEMs in the northern corridor integrate edge-AI inference subsystems alongside real-time control cores for factory retrofit projects. MEE dual carbon goals impose energy-efficiency benchmarks that redirect demand toward sub-100nm low-power process nodes. Beijing's Zhongguancun software corridor concentrates firmware customization engineering for ASIL-certified automotive stacks.
Sichuan-Chongqing
Western China manufacturing bases absorb capacity expansion for automotive-grade MCU testing and validation services. GB/T 9254-2021 electromagnetic-compatibility mandates disqualify uncertified competitors from information-technology equipment procurement. Chongqing's automotive industrial park hosts domestic OEMs localizing tier-one component sourcing under state-directed supply chain restructuring.
Shandong Peninsula
Heavy industry motor-drive applications in Jinan and Qingdao sustain demand for 16-bit architectures with CAN-FD protocol compatibility. BIS-equivalent quality-certification requirements for industrial equipment constrain import pathways for non-compliant suppliers. Weihai and Yantai port zones facilitate bonded warehousing for imported die that undergoes domestic packaging and final test.
China MCU Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification-tiered market segments. The vendor base stratifies around three structural archetypes: integrated device manufacturers with captive fabrication, fabless designers leveraging foundry partnerships, and modular subsystem bundlers combining MCUs with pre-certified RF and power-management components. Competitive intensity concentrates on certification engineering depth, reference-design availability, and NPI cycle compression through localized technical support.
Within the fabless tier, GigaDevice Semiconductor exemplifies domestic players leveraging NOR flash-MCU integration for cost-sensitive consumer sockets, while NXP Semiconductors anchors premium automotive-grade supply through ASIL-certified portfolio positioning. STMicroelectronics occupies a position spanning industrial automation with ecosystem extensions into edge-AI inference subsystems. These three companies represent the dominant competitive archetypes: domestic cost optimizers, international safety-certification leaders, and ecosystem-platform providers.
| Leading Market Players |
|---|
| STMicroelectronics |
| Infineon Technologies |
| NXP Semiconductors |
| Microchip Technology |
| Renesas Electronics |
| GigaDevice Semiconductor |
| Espressif Systems |
| Sinowealth |
| SMIC |
| Others |
Pricing and Supply Chain Analysis
Captive foundry integration at SMIC and Hua Hong anchors domestic MCU supply positions while compressing margin structures for fabless competitors dependent on external wafer allocation. This integration choice concentrates pricing power among integrated device manufacturers with in-country test facilities, while tier-one automotive OEMs leverage volume consolidation to extract firmware customization at compressed unit economics.
Pricing Analysis
Lead-time-driven pricing stratification rewards suppliers with SAMR-certified inventory and in-country testing facilities, commanding premiums for sub-12-week delivery windows against spot-market discounts for non-compliant imports. Three-tier pricing structure across ASIL-D automotive, industrial-grade, and consumer-economy levels separates certification-engineering investments from die-size optimization plays. Cost compression in 8-bit consumer sockets intensifies as Guangdong appliance OEMs consolidate procurement around reference-design bundles. Device manufacturers with SAMR CCC pre-certification exhibit lowest price sensitivity; cost-optimized consumer electronics assemblers in Zhejiang province demonstrate highest elasticity.
Supply Chain Analysis
Regional distribution centers in Shanghai bonded logistics zones and Suzhou industrial parks compress final-test-to-delivery cycles for Yangtze River Delta automotive tier-one suppliers. Foundry supply concentrates in Taiwan, South Korea, and mainland China, with mature-node 40nm-90nm capacity at SMIC and Hua Hong feeding domestic MCU designers. Silicon wafer, photoresist, and specialty gas inputs draw from Japanese and Korean chemical suppliers, exposing procurement to logistics chokepoints through Shanghai and Busan port corridors. Distribution runs through hub-and-spoke patterns radiating from Yangtze River Delta packaging houses to provincial device manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China MCU market sits in an architecture-transition phase as RISC-V open-instruction-set cores displace ARM licensing dependencies across mid-range 32-bit portfolios. This technology substitution is compressing proprietary ISA margins while elevating firmware customization depth as the primary competitive moat.
For Market Incumbents: Deepen captive test-facility investments in Yangtze River Delta special economic zones to defend socket positions against SAMR certification timeline compression. Prioritize ASIL-D software stack development with traceable toolchains to offset RISC-V margin erosion from emerging domestic fabless competitors. Lock in tier-one automotive OEMs through pre-certified domain-controller reference designs that bundle MCUs with power stages and RF modules.
For New Entrants and Emerging Players: Edge-AI inference subsystems with heterogeneous MCU-plus-NPU architectures offer the most penetrable white-space target for industrial automation retrofit projects under MEE dual carbon mandates. Target Sichuan-Chongqing automotive industrial parks where domestic OEMs are localizing tier-one sourcing under state-directed supply chain restructuring. Lead with modular reference-design bundling to compress NPI cycles and establish socket positions before incumbents can respond.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified semiconductor conglomerates seeking GB/T certification engineering teams and localized test infrastructure. Long-term viability over the next decade hinges on RISC-V core development capabilities and MIIT-funded domestic semiconductor capability building. Watch SMIC capacity allocation announcements for 40nm-90nm mature nodes as the critical inflection signal for domestic supply security.
| Strategic Initiative | Industry Significance |
|---|---|
| GB/T 34590 Functional Safety Certification | MIIT mandates now require ASIL-D stacks for automotive ECU procurement eligibility. |
| RISC-V Core Architecture Migration | Domestic fabless designers are eliminating ARM licensing fees across mid-range portfolios. |
| Modular Reference-Design Bundling | Pre-certified RF and power-management IC packaging shortens customer NPI cycles substantially. |
| Yangtze River Delta Test Facility Expansion | Localized SAMR CCC validation compresses lead times against import certification disadvantages. |
| Edge-AI Inference Subsystem Integration | Industrial automation OEMs demand neural-network accelerators alongside real-time control cores. |
Research Methodology
MIIT policy filings, SAMR certification registries, and SMIC capacity disclosure statements formed the secondary backbone for supply-side validation. Primary interviews with automotive tier-one procurement managers, industrial automation firmware engineering directors, and fabless semiconductor R&D heads combined with customs trade data and GB standards documentation to triangulate demand patterns. Bottom-up and top-down approaches cross-validated segmentation outputs across product type, application, technology, and end-user dimensions.
Bottom-up modeling aggregated unit economics across 32-bit automotive, industrial, and consumer segments, while top-down analysis calibrated aggregate market expansion against MIIT localization mandate timelines. Segmentation dimensions spanned bit-width architecture, application vertical, integration technology, and end-user procurement authority across the projection horizon. CAGRs derived from historical capacity utilization trends and forward-looking foundry expansion announcements, with automotive domain-controller content-per-vehicle and industrial edge-AI adoption curves serving as primary demand drivers.
Several conditions sit outside the modeled scope, including potential SMIC advanced-node sanctions expansion, abrupt ARM licensing renegotiations, and unannounced MIIT information-security certification revisions. Forecasts reflect documented assumptions around foundry yield improvements and SAMR approval timeline stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Japan CEP Market
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market
Semiconductor Devices
Global Power MOSFET Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
China Semiconductor Device Market
Semiconductor Devices
Finfet Technology Market
Semiconductor Devices
Japan MLCC Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
Field-Effect Rectifier Diodes Market
Semiconductor Devices
Analog and Mixed Signal Device Market
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Polymer Core Solder Ball Market
Semiconductor Devices
Dual Voltage Comparator Market
Semiconductor Devices
Digital Transistor Market
Semiconductor Devices
T-Con Board Market
Semiconductor Devices
Semiconductor Tubular Heaters Market