
 Global Small Signal Transistor Market | 2026-2036
Global Small Signal Transistor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Small Signal Transistor Market Foresight
The capital-intensity divergence between foundry-dependent and IDM players is unwinding as process-node costs escalate. NXP Semiconductors leverages its mixed-signal expertise to sustain leadership in automotive-qualified small signal devices. Toshiba anchors its position through captive fabrication of discrete bipolar junction transistors for industrial applications.
Small signal transistors are low-power semiconductor devices engineered to process electrical signals below one watt, typically fabricated on silicon substrates using epitaxial growth or ion implantation to achieve precise doping profiles for high-frequency switching and linear amplification. Bipolar junction transistors retain dominance in cost-sensitive analog circuits where saturation voltage and current gain stability matter, while heterojunction transistors command premium positioning in RF front-ends for 5G infrastructure due to superior electron mobility. Silicon carbide technology segments remain nascent in small signal applications but attract R&D allocation from power-electronics suppliers seeking thermal performance differentiation.
FDA oversight of medical device electronics, REACH substance restrictions in Europe, and China's GB/T semiconductor standards collectively elevate compliance burdens for component suppliers seeking multi-region market access. The EU AI Act's hardware traceability requirements will extend documentation obligations to transistor-level supply chains. Stakeholders must monitor divergence between regional semiconductor self-sufficiency policies and their impact on cross-border component qualification pathways.
Market Dynamics
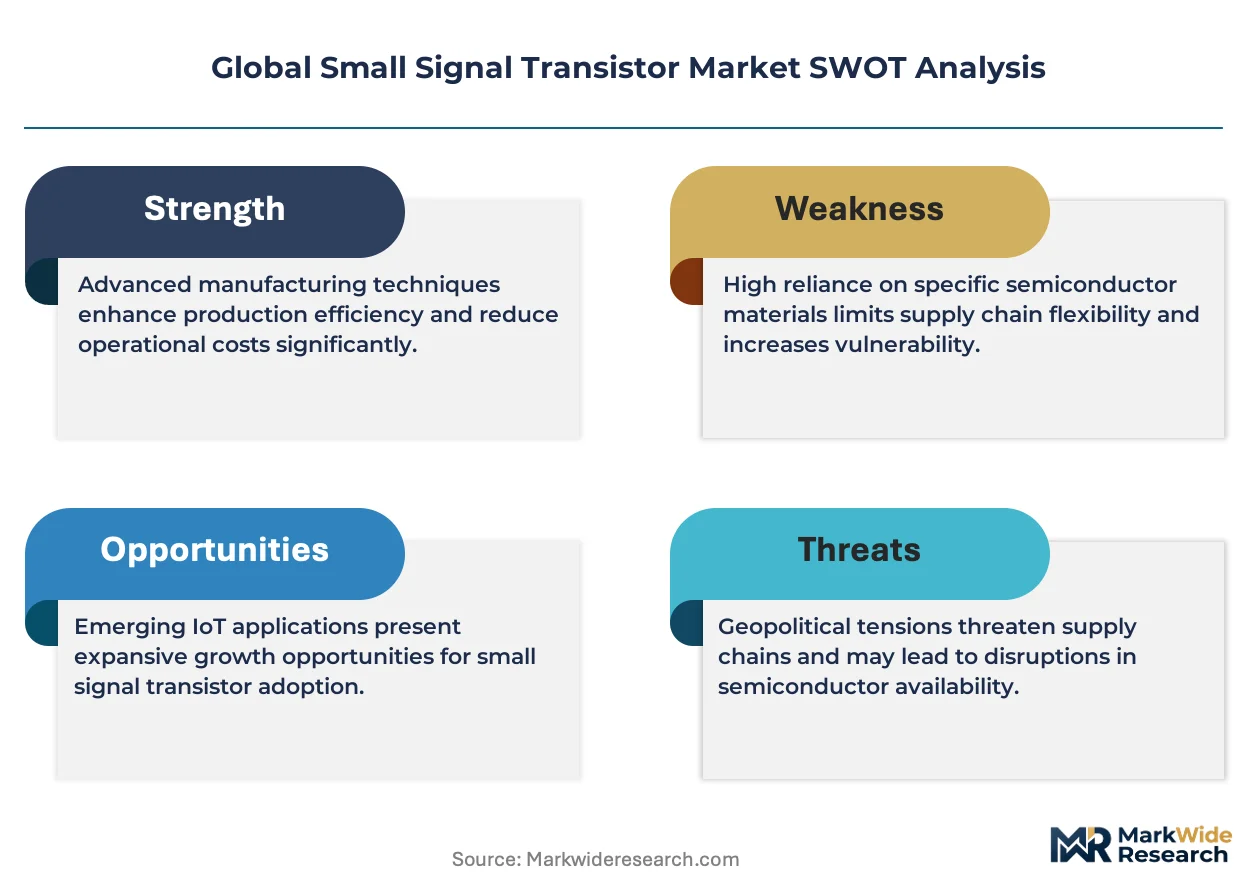
Process-node cost escalation is forcing capital-structure convergence between foundry-dependent and integrated device manufacturers, compressing legacy cost advantages in small signal transistor fabrication.
Growth Catalysts
- 5G Infrastructure Deployment:RF front-end modules for base stations and smartphones require heterojunction transistors with superior electron mobility. Base station manufacturers in South Korea and Taiwan drive procurement volumes.
- EU AI Act Hardware Traceability:Documentation obligations extending to transistor-level supply chains create qualification barriers that favor established suppliers with compliance infrastructure already deployed across European medical and automotive electronics.
- Wearable Device Miniaturization:Smartwatch and hearable manufacturers specify sub-millimeter package outlines. Silicon-on-insulator processes enable the power efficiency thresholds demanded by battery-constrained form factors.
Market Restraints
- Epitaxial Wafer Supply Concentration:High-resistivity silicon substrate production concentrates among Japanese and German suppliers, exposing buyers to allocation risk during semiconductor demand cycles.
- REACH Substance Restrictions:ECHA candidate list expansions threaten lead-free solder alternatives and specialized dopant chemistries used in precision doping profiles, forcing reformulation timelines.
- Silicon Carbide Substitution Threat:Power electronics suppliers developing SiC small-signal variants threaten thermal performance differentiation in high-temperature industrial applications.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor assembly and testing attract small signal transistor packaging investment to serve domestic smartphone and appliance production.
- Automotive Functional Safety:ISO 26262 certification requirements for advanced driver-assistance systems create premium positioning for automotive-qualified bipolar junction transistors with documented failure rates.
- Medical Device Wireless Connectivity:FDA-cleared implantable devices with Bluetooth Low Energy links specify ultra-low-noise amplification stages, opening high-margin niches for specialized RF transistors.
Industry Challenges
- Analog Design Talent Scarcity:Bipolar transistor circuit design expertise concentrates among aging engineer cohorts in Japan and Europe, constraining new product development velocity.
- Multi-Region Certification Burden:Simultaneous FDA, EMA medical device, and China NMPA pathways require parallel documentation streams, extending time-to-revenue for new transistor qualifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Small Signal Transistor Market |
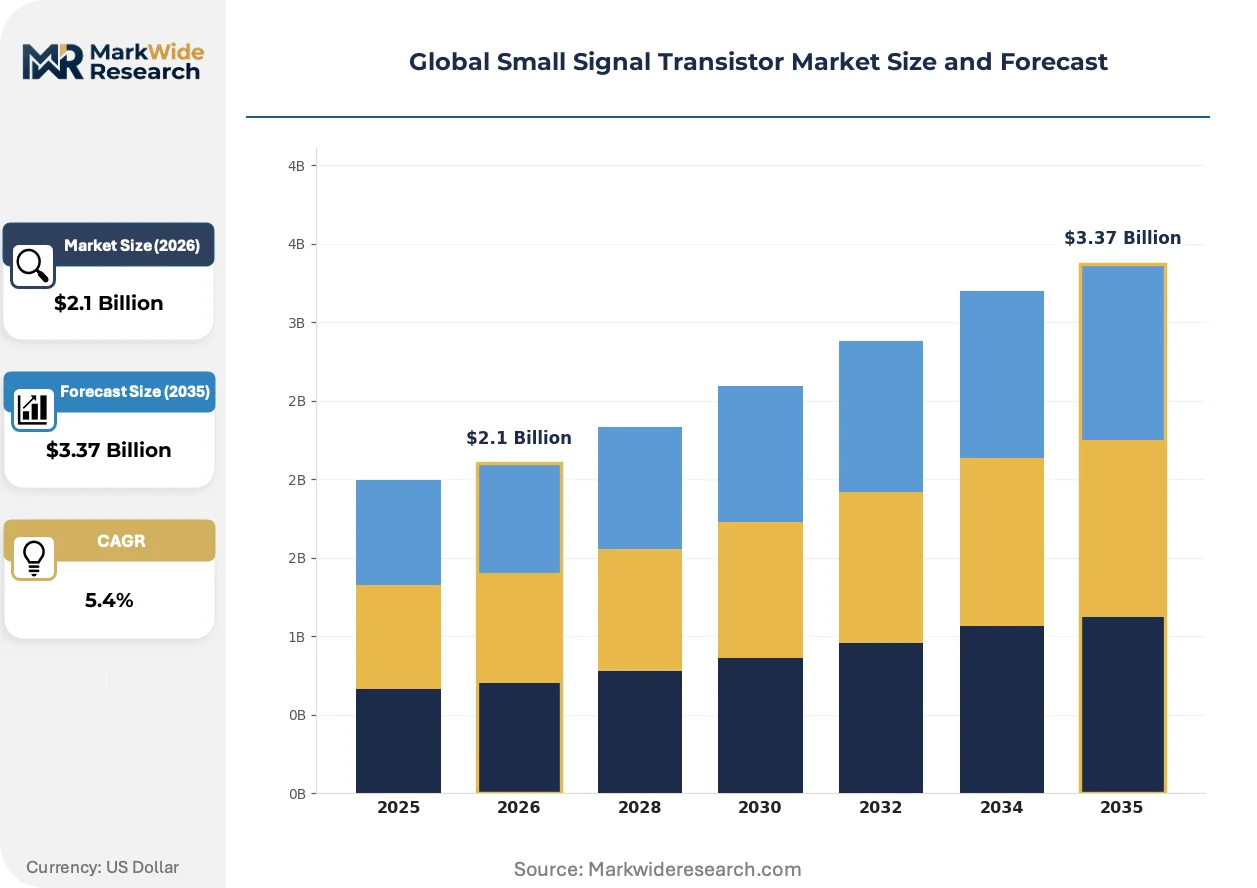
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bipolar Junction Transistor, Field Effect Transistor, Heterojunction Transistor, Insulated Gate Transistor, Junction Field Effect Transistor Technology: Silicon, Silicon Carbide, Gallium Arsenide, Germanium, Indium Phosphide Application: Signal Amplification, Switching, Oscillation, Modulation, Voltage Regulation End User: Consumer Electronics Manufacturers, Telecommunications Providers, Industrial Automation Firms, Aerospace Engineers, Instrumentation Developers |
| Companies Covered | NXP Semiconductors N.V., Toshiba Corporation, Infineon Technologies AG, ROHM Semiconductor, Vishay Intertechnology Inc., STMicroelectronics N.V., ON Semiconductor Corporation, Renesas Electronics Corporation, Texas Instruments Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Small Signal Transistor Market Shifts & Advancements
Materials science advances and regulatory traceability mandates are reconfiguring competitive positioning across discrete semiconductor supply chains.
Gallium arsenide heterojunction bipolar transistors is displacing silicon germanium in millimeter-wave 5G infrastructure. Base station original equipment manufacturers in South Korea and Taiwan specify GaAs HBTs for 28 GHz and 39 GHz bands. The technology is displacing incumbent SiGe solutions in high-frequency small-signal amplification, compressing addressable margins for legacy silicon suppliers.
REACH authorization requirements for cadmium and lead compounds are forcing reformulation of termination finishes and die-attach materials. ECHA sunset dates for restricted substances compress qualification timelines for medical and industrial equipment manufacturers. European automotive electronics suppliers accelerate alternative metallurgy validation to maintain CE marking compliance.
Consolidated component distributors are unbundling technical application support from transactional fulfillment. Original design engineers in North America and Europe now source small signal transistors through manufacturer-direct digital channels for prototype quantities. This pattern concentrates most visible in medical device startups seeking rapid iteration cycles bypassing traditional franchise distributor minimum order quantities.
Global Small Signal Transistor Market Segmentation
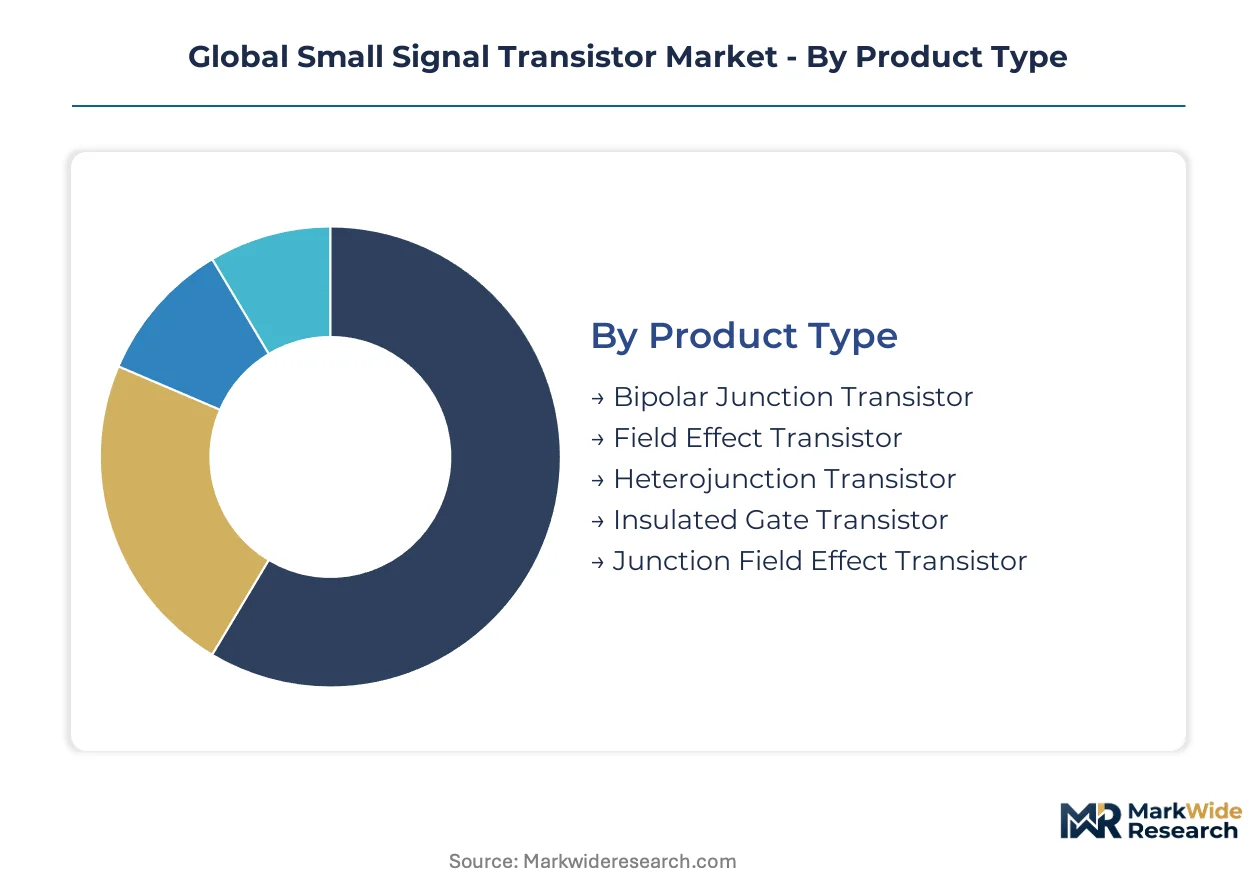
Small signal transistor procurement patterns diverge sharply across technical specifications and end-use requirements. Device physics, substrate material costs, and application-specific certification burdens fragment supplier strategies across each segmentation dimension.
Product Type:
Heterojunction and insulated gate architectures face the strongest substitution pressure from compound semiconductor alternatives in RF and power-sensitive designs.
- Bipolar Junction Transistor:Silicon-based three-layer structures deliver stable current gain and low saturation voltage for analog circuits. Industrial automation firms in Germany and Japan specify these for motor control interfaces where precision matters more than switching speed.
- Field Effect Transistor:Voltage-controlled channels enable ultra-high input impedance with minimal gate current draw. Wearable device manufacturers in South Korea drive procurement for battery-powered sensor front-ends requiring nanoamp quiescent consumption.
- Heterojunction Transistor:Bandgap engineering at emitter-base junctions yields superior electron mobility for millimeter-wave operation.
- Insulated Gate Transistor:MOS-gated structures merge high input impedance with bipolar conduction efficiency.
- Junction Field Effect Transistor:Depletion-mode operation provides normally-on functionality without gate bias.
Bipolar junction transistors retain volume leadership; heterojunction transistors hold the steepest expansion curve.
Technology:
Cost tier stratification separates mature silicon processes from premium compound semiconductor substrates with specialized epitaxial requirements.
- Silicon:Dominant substrate leverages 60 years of process refinement and foundry infrastructure. CMOS-compatible fabrication enables integration with digital logic for mixed-signal consumer electronics manufactured across Taiwan and mainland China.
- Gallium Arsenide:Direct bandgap and high electron mobility suit optoelectronic and RF applications beyond silicon frequency limits. Base station OEMs in South Korea specify GaAs for 28 GHz beamforming modules.
- Silicon Carbide:Wide bandgap delivers thermal resilience for high-temperature industrial environments.
- Germanium:Narrow bandgap enables low-voltage operation for specialized analog sensing.
- Indium Phosphide:Lattice-matched to long-wavelength optoelectronic compounds.
Silicon dominates unit shipments; GaAs substrates command the highest revenue per wafer.
Application:
Margin structure varies with performance verification burden—medical-grade amplification commands premium pricing over commodity switching.
- Signal Amplification:Low-noise front-ends for sensor interfaces and RF reception. FDA-cleared implantable devices with Bluetooth Low Energy links specify ultra-low-noise stages manufactured to ISO 13485 medical device quality systems.
- Switching:Binary state control for digital logic level translation and power management. Smartphone PMIC designers in Taiwan prioritize Ron-Qg tradeoffs for battery efficiency.
- Oscillation:Feedback-loop configurations for clock generation and frequency synthesis.
- Modulation:Amplitude and phase control for communications encoding.
- Voltage Regulation:Pass element operation in linear and switching regulators.
Switching applications drive the highest unit volumes; signal amplification captures the steepest margin premiums.
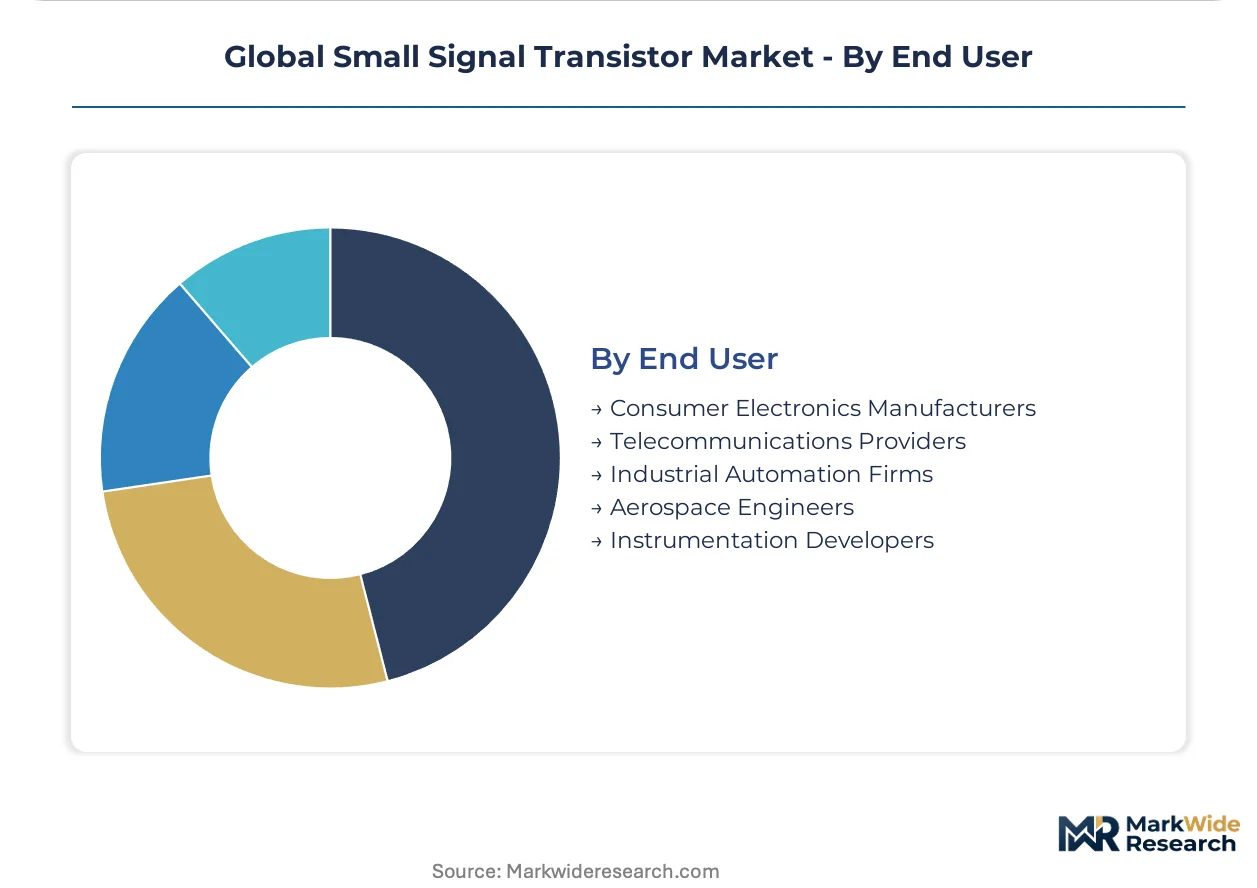
End User:
Customer type determines qualification pathway complexity—automotive and medical sectors impose documentation burdens absent from consumer electronics procurement.
- Consumer Electronics Manufacturers:Smartphone and wearable OEMs specify sub-millimeter packages with aggressive cost targets. Assembly operations in Vietnam and India source through consolidated distributors with regional inventory positioning.
- Telecommunications Providers:5G infrastructure deployment drives heterojunction transistor procurement for base station RF chains. South Korean network equipment vendors qualify suppliers to extended temperature ranges.
- Industrial Automation Firms:Programmable logic controllers and motor drives require extended operating temperature ratings.
- Aerospace Engineers:Mil-spec screening and radiation tolerance certification apply to satellite and avionics applications.
- Instrumentation Developers:Test and measurement equipment demands precision matching and low drift characteristics.
Consumer electronics manufacturers absorb the highest transistor unit volumes; telecommunications providers are expanding procurement most quickly for 5G infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in small signal transistors concentrate procurement leverage among East Asian fabrication clusters. China, Japan, South Korea, and Taiwan collectively dominate wafer output. Germany and the United States anchor Western demand through automotive and industrial automation consumption.
China
Domestic smartphone assembly and 5G base station deployment drive heterojunction transistor procurement volumes. MIIT's GB/T semiconductor standards mandate hazardous substance documentation for cross-border shipments. Shenzhen and Shanghai manufacturing corridors host captive packaging operations serving consumer electronics OEMs.
Japan
Industrial automation firms in Osaka and Nagoya specify bipolar junction transistors for precision motor control interfaces. METI's export control revisions on advanced semiconductor equipment affect foundry equipment sourcing. Tokyo and Yokohama clusters concentrate epitaxial wafer production for high-resistivity silicon substrates.
South Korea
Samsung and SK Hynix ecosystem demand pulls RF transistor volumes for smartphone RF front-end modules. MFDS medical device regulations extend to component-level traceability for implantable electronics. Suwon and Pyeongtaek semiconductor corridors anchor heterojunction transistor qualification programs.
Taiwan
TSMC-adjacent fabless designers source small signal devices for mixed-signal consumer SoC integration. The National Science and Technology Council's chip industry incentives attract packaging investment to Taichung and Tainan. Hsinchu Science Park hosts discrete device specialists serving foundry customers.
Germany
Automotive Tier-1 suppliers in Stuttgart and Munich procure ISO 26262-qualified bipolar transistors for ADAS signal conditioning. KBA type-approval requirements cascade to component-level failure rate documentation. Bavaria's industrial automation corridor sustains demand for extended-temperature discrete devices.
Global Small Signal Transistor Market Competitive Landscape
Concentration sits with diversified semiconductor conglomerates possessing captive fabrication and automotive qualification infrastructure. IDM players retain cost advantages in legacy bipolar processes while foundry-dependent fabless designers compete on RF integration speed. Three archetypes dominate: European automotive-qualified specialists, Japanese industrial discrete manufacturers, and American analog broadliners. Competitive moves center on backward integration into epitaxial wafer supply and multi-region certification infrastructure deployment.
Within the automotive-qualified tier, NXP Semiconductors N.V. and Infineon Technologies AG exemplify mixed-signal integration strategies. Toshiba Corporation and ROHM Semiconductor represent Japanese industrial discrete specialists with captive bipolar fabrication. Texas Instruments Incorporated anchors the American analog broadliner archetype with distributor-integrated fulfillment models.
| Leading Market Players |
|---|
| NXP Semiconductors N.V. |
| Toshiba Corporation |
| Infineon Technologies AG |
| ROHM Semiconductor |
| Vishay Intertechnology Inc. |
| STMicroelectronics N.V. |
| ON Semiconductor Corporation |
| Renesas Electronics Corporation |
| Texas Instruments Incorporated |
| Others |
Supply & Pricing Matrix
Epitaxial wafer fabrication scale economies in Japan and Germany anchor cost floors for high-resistivity silicon substrates, concentrating pricing power among substrate specialists while compressing margins for downstream packaging operations in Vietnam and India. Foundry utilization rates at Taiwan Semiconductor Manufacturing Company and Samsung Foundry directly transmit to small signal transistor die pricing, with automotive-qualified bipolar junction transistors commanding sustained premiums over commodity consumer-grade equivalents.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with ISO 26262-certified automotive-grade devices separated from industrial-extended-temperature tiers and mass-market consumer electronics specifications. Price differentiation rests on certification grade and volume scale, with medical-grade amplification stages capturing the widest spreads. Cost compression in consumer-grade field effect transistors is intensifying because smartphone original design manufacturers in South Korea and Taiwan consolidate procurement through direct manufacturer channels. Automotive Tier-1 suppliers in Germany exhibit the lowest price sensitivity due to failure-rate documentation requirements and multi-year qualification lock-ins.
Supply Chain Analysis
Inventory buffers for high-resistivity silicon substrates have compressed to six-to-eight week levels, exposing small signal transistor assemblers to allocation volatility during semiconductor demand cycles. Geographic supply concentration centers on Japan, South Korea, and Taiwan for epitaxial wafer production, with packaging and test operations migrating to Vietnam and India under India's PLI scheme incentives. Raw material dependencies draw from germanium tetrachloride precursors, gold wire bonding materials, and lead-free solder alternatives threatened by REACH authorization timelines. Single-source vulnerability concentrates in Tokyo and Yokohama clusters for substrate supply. Distribution runs through consolidated component distributors for volume procurement, with manufacturer-direct digital channels capturing prototype and low-volume medical device segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent small signal transistor suppliers face sustained substitution pressure from gallium arsenide heterojunction bipolar transistors displacing silicon germanium in millimeter-wave 5G infrastructure, requiring defensive positioning around automotive and medical qualification moats.
For Market Incumbents: Shield automotive-qualified product lines through captive epitaxial wafer supply and accelerated ISO 26262 documentation refresh cycles. Backward integration into high-resistivity silicon substrate production in Japan or Germany reduces allocation risk exposure. Prioritize R&D allocation toward silicon-on-insulator processes for wearable power efficiency thresholds to defend against compound semiconductor encroachment in RF front-ends.
For New Entrants and Emerging Players: Differentiate on India-based packaging and test operations serving domestic smartphone and appliance production under PLI scheme incentives. Target medical device wireless connectivity niches requiring FDA-cleared ultra-low-noise amplification stages, where qualification barriers limit incumbent response speed. Pursue direct-to-startup digital channels bypassing consolidated distributor minimum order quantities for rapid iteration cycles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automotive-qualified specialists with captive fabrication and multi-region certification infrastructure deployed across European medical and automotive electronics. Long-term viability hinges on sustained heterojunction transistor demand from 5G infrastructure buildout in South Korea and Taiwan. Monitor gallium arsenide heterojunction bipolar transistor penetration rates in base station original equipment manufacturer specifications as the critical inflection signal for silicon germanium displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxial Wafer Supply | Captive substrate production in Japan reduces allocation exposure to Tokyo and Yokohama suppliers. |
| ISO 26262 Certification Acceleration | Automotive functional safety documentation meets KBA type-approval requirements for Stuttgart Tier-1 procurement. |
| India Packaging Footprint Expansion | PLI scheme incentives attract assembly and test investment to serve domestic smartphone manufacturers. |
| Direct Digital Channel Deployment | Manufacturer-direct prototype fulfillment bypasses consolidated distributor minimum order quantities for medical startups. |
| Silicon-on-Insulator Process Development | Power efficiency thresholds address battery-constrained wearable specifications from South Korean OEMs. |
Research Methodology
The analysis maps bipolar junction transistor, field effect transistor, heterojunction transistor, and insulated gate transistor sub-sectors, each validated through semiconductor fabrication engineers, automotive Tier-1 procurement managers, medical device quality systems directors, and RF front-end design leads. Primary interview data triangulates against secondary sources including MIIT GB/T semiconductor filings, ECHA REACH candidate list expansions, SEC 10-K disclosures from diversified semiconductor conglomerates, and customs trade data for epitaxial wafer imports. Bottom-up unit shipment estimates by package type and application converge with top-down wafer consumption models from foundry utilization disclosures.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models technology substitution dynamics, end-use segmentation by certification burden, and regional production cluster migration patterns. CAGRs derive from installed base replacement cycles, 5G infrastructure deployment trajectories, and automotive electronics content expansion. Forecast inputs incorporate REACH substance restriction timelines, FDA medical device electronics oversight evolution, and China's GB standards harmonization progress.
The analysis sits within stated boundaries; outcomes outside sustained East Asian manufacturing cluster dominance or accelerated compound semiconductor substitution would require recalibration. Forecasts reflect documented assumptions regarding regulatory compliance burden trajectories and foundry capacity expansion schedules. Silicon carbide small-signal variant development velocity and EU AI Act hardware traceability implementation pace represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Americas Microcontroller (MCU) Market
Semiconductor Devices
Silicon-Based Anode Market
Semiconductor Devices
Micro Thermoelectric Modules Market
Semiconductor Devices
Finfet Technology Market
Semiconductor Devices
Semiconductor in Phones Market
Semiconductor Devices
Global Through Silicon via (TSV) Technology Market
Semiconductor Devices
Solar Cell Paste Market
Semiconductor Devices
Field Effect Transistor Market
Semiconductor Devices
Global Vacuum Capacitors Market
Semiconductor Devices
Global Trench Gate Power MOSFET Market
Semiconductor Devices
CZ Silicon Wafer Market
Semiconductor Devices
Advanced IC Substrates Market
Semiconductor Devices
Flip Chip Technology Market
Semiconductor Devices
Field-Effect Rectifier Diodes Market
Semiconductor Devices
Europe Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Gaming GPU Market