
 Leap Engine Market | 2026-2036
Leap Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Leap Engine Market Foresight
Modular engine configuration is hardening as the dominant procurement pattern, allowing airlines to swap core modules without full powerplant replacement. CFM International leverages its Safran-GE partnership to sustain dual-source manufacturing scale across European and North American facilities. Pratt & Whitney anchors its competitive stance through geared turbofan architecture, while MTU Aero Engines specializes in high-pressure compressor modules for multiple Leap variants.
A Leap engine denotes a high-bypass turbofan powerplant incorporating advanced aerodynamic blade designs, ceramic matrix composite hot-section components, and dual-annular combustor architecture achieving fifteen-to-one bypass ratios. Its primary commercial purpose centers on reducing specific fuel consumption and nitrogen oxide emissions for narrow-body aircraft platforms. The integrated product type captures the largest installed base as airlines favor factory-sealed powerplants with warranty-backed lifecycle management, while modular configurations represent the fastest-growing segment by enabling incremental upgrade paths without full capital replacement. Cloud-based deployment models for engine health monitoring are displacing legacy on-premise analytics stacks as carriers prioritize real-time fleet diagnostics.
The FAA enforces Part 33 airworthiness standards that dictate thrust rating verification and endurance testing protocols for all Leap variants entering US-registered service. EASA's Certification Memoranda on engine emissions and the ICAO Carbon Offsetting and Reduction Scheme for International Aviation collectively shape product development roadmaps and market access timelines. Stakeholders must monitor evolving noise certification stringency at airport-level regulators and assess how sustainable aviation fuel compatibility requirements will alter aftermarket service architectures.
Market Dynamics
Modular engine architectures are compressing replacement cycles as airlines seek to isolate maintenance costs within swappable core modules rather than absorbing full powerplant overhauls.
Growth Catalysts
- ICAO CORSIA compliance deadlines:International carriers face mandatory carbon offsetting obligations that favor Leap's fifteen-to-one bypass ratio and reduced NOx output.
- Ceramic matrix composite adoption:Hot-section components tolerate higher operating temperatures, extending time-on-wing and reducing shop visit frequency.
- Narrow-body fleet densification:Low-cost carriers in India and Vietnam are expanding single-aisle aircraft commitments that specify Leap powerplants.
Market Restraints
- Titanium and nickel superalloy volatility:Aerospace-grade material costs fluctuate with mining output from Russian and Chinese suppliers, squeezing module margins.
- EASA Certification Memoranda friction:Evolving emissions testing protocols extend type certificate amendment timelines by eight to fourteen months.
- Geared turbofan substitution:Pratt & Whitney's competing architecture captures share among carriers prioritizing noise reduction over fuel efficiency.
Strategic Opportunities
- Sustainable aviation fuel compatibility:EASA and FAA pathways for percent-blend certification create aftermarket service expansion around fuel system retrofits.
- Cloud-based health monitoring:Real-time vibration and exhaust gas temperature analytics enable predictive module swaps before hard failures.
- Indian MRO infrastructure buildout:Bangalore and Hyderabad facilities lack OEM-authorized Leap overhaul capacity, creating third-party service entry points.
Industry Challenges
- Specialized technician scarcity:Composite blade repair and CMC component inspection require certifications that training pipelines have not scaled to match fleet growth.
- FAA Part 33 endurance testing bottlenecks:Thrust rating verification for derivative variants queues at limited agency test facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leap Engine Market |
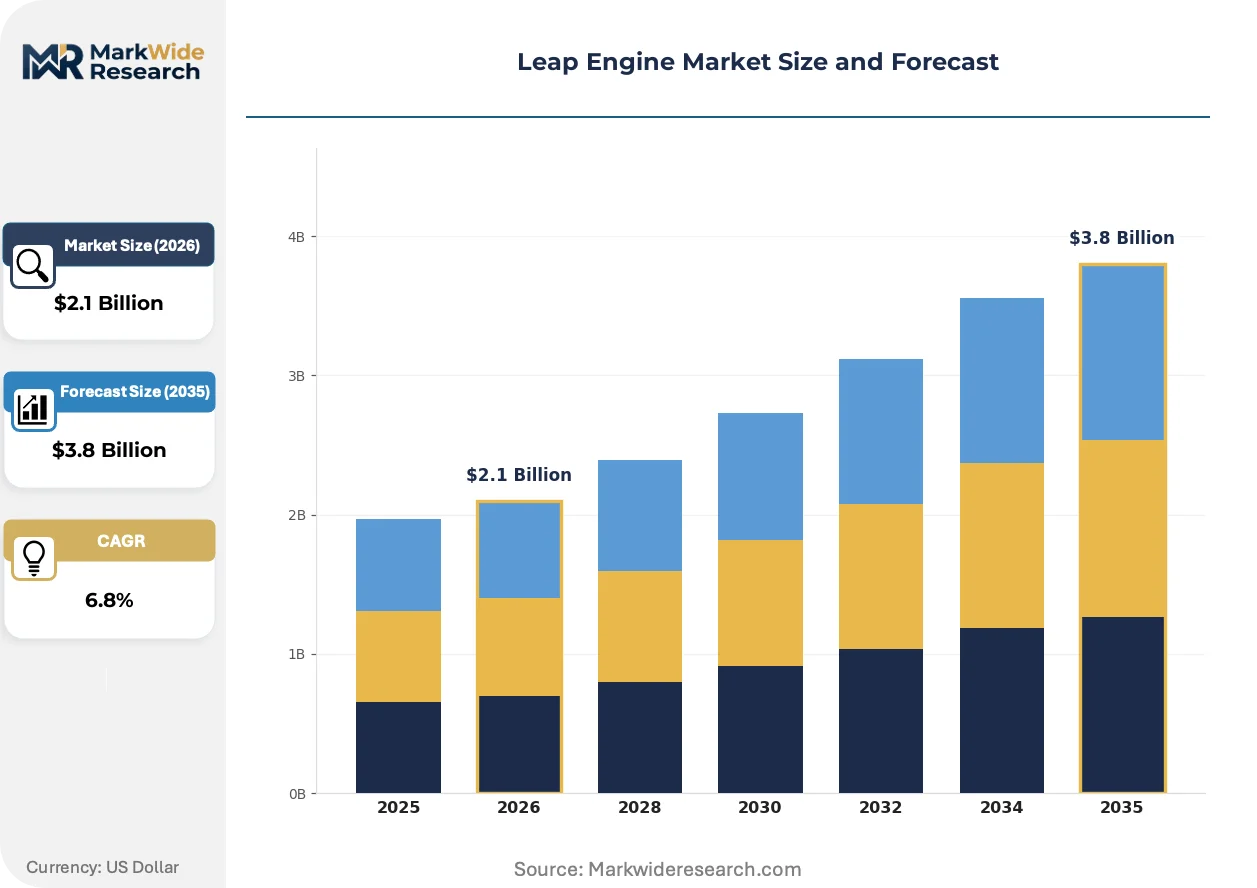
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Integrated, Modular, Cloud-Based Deployment Model: On-Premise, Public Cloud, Private Cloud, Hybrid Cloud End User: Enterprises, SMEs, Government Agencies, Educational Institutions Service Type: Consulting, Support, Maintenance, Training |
| Companies Covered | Pratt & Whitney, MTU Aero Engines, CFM International, IHI Corporation, Honeywell, General Electric, Rolls-Royce, Kawasaki Heavy Industries, Safran Aircraft Engines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leap Engine Market Shifts & Advancements
Digital thread integration across design, manufacturing, and aftermarket service is collapsing information latency that previously separated OEM engineering from operator maintenance decisions.
Additive manufacturing is integrating titanium aluminide low-pressure turbine blades that reduce component weight by twenty-two percent against conventional castings. Engine overhaul shops in the United States and France are qualifying these parts for replacement use. The technology is integrating repair workflows that previously required full module scrapping.
EPA aircraft engine emission standards are tightening particulate matter thresholds for engines certificated after 2028. Manufacturers must redesign combustor architectures to achieve smoke number compliance without sacrificing thermal efficiency. Narrow-body platforms serving US domestic routes face the steepest redesign urgency.
Airlines are unbundling power-by-the-hour contracts into discrete module-level service agreements. Lessors and independent MROs in Singapore and Ireland now compete directly with OEM-affiliated networks for high-pressure compressor overhauls. The shift concentrates pricing pressure on shop visit labor rates rather than bundled spare part markups.
Leap Engine Market Segmentation
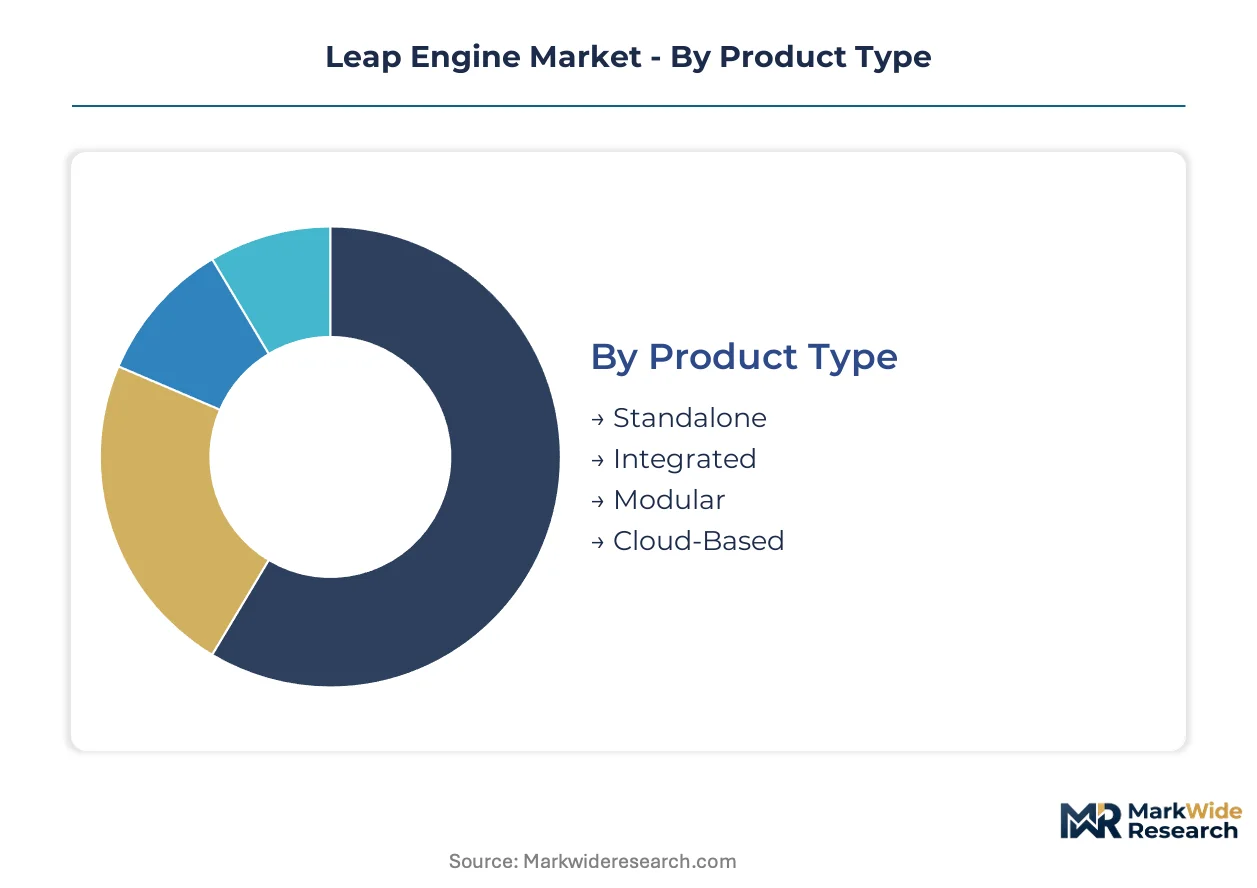
Leap engine procurement patterns diverge sharply between airlines seeking capital-light operational flexibility and those prioritizing lifecycle cost certainty. Segmentation reveals how module-level service unbundling and cloud-native health monitoring are redrawing traditional OEM-operator boundaries.
Product Type:
Volume concentrates in factory-sealed configurations with warranty-backed lifecycle management, while premium margins attach to architectures enabling incremental upgrade paths.
- Integrated:Factory-sealed powerplants with comprehensive warranty coverage dominate narrow-body fleet commitments from full-service carriers. Airlines in the United States anchor procurement volumes as they prioritize predictable maintenance budgeting over modular flexibility.
- Modular:Swappable core architectures isolate maintenance costs within replaceable modules rather than absorbing full powerplant overhauls. Low-cost carriers in India and Vietnam are expanding adoption fastest, driven by fleet densification strategies that demand operational agility.
- Standalone:Discrete powerplant units without bundled service agreements appeal to lessors and asset managers seeking residual value control.
- Cloud-Based:Virtualized engine health monitoring layers overlaying physical hardware enable real-time diagnostics without on-premise infrastructure.
Mature deployment sits with Integrated configurations. Newer deployment is concentrated in Modular architectures.
Deployment Model:
Legacy on-premise analytics stacks face displacement as carriers prioritize real-time fleet diagnostics accessible from distributed maintenance stations.
- Public Cloud:Multi-tenant infrastructure delivers vibration and exhaust gas temperature analytics without carrier-managed server capacity. Airlines with geographically dispersed fleets across Southeast Asia and the Middle East are migrating fastest to reduce IT capital burden.
- Hybrid Cloud:Sensitive operational data remains on-premise while anonymized trend analysis flows to OEM engineering centers. European carriers subject to GDPR data residency requirements favor this architecture for predictive maintenance workflows.
- Private Cloud:Single-tenant dedicated infrastructure serves carriers with stringent cybersecurity mandates or sovereign data requirements.
- On-Premise:Legacy server installations at carrier headquarters or major maintenance bases persist where connectivity reliability remains problematic.
Established infrastructure concentrates in On-Premise installations. Fastest expansion is occurring in Hybrid Cloud deployments.
End User:
Procurement scale and service sophistication separate large fleet operators from emerging market entrants and institutional non-commercial adopters.
- Enterprises:Major airline groups and leasing companies with 100+ aircraft fleets negotiate enterprise-level power-by-the-hour agreements. United States-based network carriers command volume pricing leverage through multi-engine commitments spanning single-aisle platforms.
- SMEs:Regional carriers and charter operators with 10-50 aircraft rely on third-party MRO networks rather than OEM-direct service relationships. Operators in Vietnam and Indonesia represent the fastest-expanding SME segment as narrow-body fleet commitments accelerate.
- Government Agencies:Military and state aviation authorities procure modified Leap variants for transport and tanker applications with specialized mission requirements.
- Educational Institutions:Aerospace engineering programs and technical training centers acquire decommissioned powerplants for instructional purposes.
Volume leadership rests with Enterprises. Fastest adoption velocity is appearing among SMEs.
Service Type:
Traditional bundled maintenance contracts fragment into discrete, separately priced service components as independent MROs compete for module-level work.
- Maintenance:Scheduled and unscheduled module overhauls, hot-section inspections, and life-limited part replacement constitute the largest revenue pool. Third-party MRO facilities in Singapore and Ireland now compete directly with OEM-affiliated networks for high-pressure compressor overhauls.
- Consulting:Fleet transition planning, reliability engineering, and regulatory compliance advisory support growing demand from carriers navigating EASA and FAA certification pathway changes.
- Support:Technical documentation access, troubleshooting hotlines, and AOG response coordination.
- Training:Composite blade repair certification and CMC component inspection programs address specialized technician scarcity.
Revenue concentration remains with Maintenance. Consulting services are climbing the fastest as regulatory complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in France and the United States where CFM International operates dual-source facilities, while consumption spreads across carrier hubs in India, Vietnam, and the Middle East as narrow-body fleet commitments accelerate. Regulatory divergence between FAA Part 33 standards and EASA emissions protocols shapes certification timelines across jurisdictions.
United States
Full-service carriers anchor procurement volumes through multi-engine commitments on single-aisle platforms. The FAA enforces Part 33 airworthiness standards that dictate thrust rating verification and endurance testing protocols for all Leap variants entering US-registered service. Seattle and Dallas-Fort Worth maintenance clusters lack sufficient OEM-authorized overhaul capacity, creating bottlenecks for high-pressure compressor module work.
France
Safran Aircraft Engines drives production scale through Villaroche and Gennevilliers facilities supplying core modules across the Leap family. EASA Certification Memoranda on engine emissions extend type certificate amendment timelines by eight to fourteen months. Toulouse and Nantes aerospace clusters concentrate ceramic matrix composite manufacturing for hot-section components.
India
Low-cost carriers in India expand single-aisle aircraft commitments that specify Leap powerplants for fleet densification strategies. The country's national aviation regulator aligns with ICAO CORSIA compliance deadlines mandating carbon offsetting obligations. Bangalore and Hyderabad MRO facilities lack OEM-authorized Leap overhaul capacity, creating third-party service entry points for independent providers.
Vietnam
Rapid narrow-body fleet growth among Vietnamese carriers drives demand for modular engine configurations enabling operational agility. The Ministry of Transport implements emissions testing protocols aligned with EASA frameworks for new engine certifications. Ho Chi Minh City and Hanoi maintenance stations remain dependent on Singapore-based overhaul networks for high-pressure compressor module work.
Germany
MTU Aero Engines anchors European supply chains through Munich-based high-pressure compressor module specialization across multiple Leap variants. The KBA enforces noise certification stringency at airport-level regulators affecting engine program market access. Hamburg and Munich industrial clusters concentrate additive manufacturing qualification for titanium aluminide low-pressure turbine blade repairs.
Leap Engine Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Leap engine supply chain. The market structure consolidates around three dominant archetypes: dual-source joint ventures controlling core architecture, national champion suppliers capturing module-level niches, and diversified industrial conglomerates with aerospace divisions. Strategic moves concentrate on manufacturing scale expansion and technology licensing arrangements rather than horizontal consolidation.
Within the joint venture tier, CFM International represents the dual-source manufacturing archetype through its Safran-GE partnership spanning European and North American facilities. Pratt & Whitney occupies a position exemplifying geared turbofan competitive alternatives, while MTU Aero Engines sits within the module-specialist tier anchoring high-pressure compressor supply for multiple Leap variants.
| Leading Market Players |
|---|
| Pratt & Whitney |
| MTU Aero Engines |
| CFM International |
| IHI Corporation |
| Honeywell |
| General Electric |
| Rolls-Royce |
| Kawasaki Heavy Industries |
| Safran Aircraft Engines |
| Others |
Supply & Pricing Matrix
Airline procurement consolidation around modular engine configurations forces suppliers to unbundle traditional power-by-the-hour contracts into discrete module-level agreements, compressing margins on shop visit labor rates while elevating pricing power for ceramic matrix composite components with limited qualified sources.
Pricing Analysis
Margin tightening in maintenance services reflects airlines unbundling bundled contracts into separately priced module overhauls. Pricing stratifies across premium OEM-authorized, standard independent MRO, and economy third-party repair tiers based on certification level and warranty backing. Cost-down pressure on high-pressure compressor modules accelerates because independent MROs in Singapore and Ireland now compete directly with OEM networks. Low-cost carriers in India and Vietnam exhibit highest price sensitivity, while United States full-service carriers prioritize lifecycle cost certainty over unit pricing.
Supply Chain Analysis
FAA Part 33 and EASA certification requirements gate entry for hot-section component suppliers, limiting qualified sources for ceramic matrix composite parts. Manufacturing concentrates in France, the United States, and Germany where Safran, GE, and MTU Aero Engines anchor dual-source production. The supply chain draws from Russian and Chinese mining output for titanium and nickel superalloys, exposing margins to commodity volatility. Distribution runs through OEM-affiliated networks and independent MRO facilities competing for high-pressure compressor module work.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modular engine architecture adoption consolidates procurement leverage among airlines with dense narrow-body fleets, squeezing smaller service providers unable to achieve scale in CMC component repair or additive manufacturing qualification.
For Market Incumbents: Anticipate Pratt & Whitney geared turbofan substitution threats by deepening captive supply of high-pressure compressor modules through Munich and Villaroche facility expansion. Secure additive manufacturing qualification for titanium aluminide turbine blade repairs before independent MROs achieve FAA certification for these components. For New Entrants and Emerging Players: Enter via third-party MRO authorization gaps in Bangalore and Hyderabad where OEM-authorized Leap overhaul capacity remains insufficient. Target Indian low-cost carrier module swap demand through cloud-based health monitoring integration that predicts failures before hard shop visits become necessary. For Investors and Strategic Acquirers: The window for entry favors module-specialist suppliers with ceramic matrix composite repair certifications and established relationships with CFM International's dual-source network. Watch EASA Certification Memoranda amendment timelines as inflection indicators for aftermarket service expansion opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Matrix Composite Repair Qualification | FAA-authorized CMC hot-section repair capability locks in high-margin aftermarket revenue streams. |
| Additive Manufacturing Certification | Titanium aluminide turbine blade repair qualification displaces conventional casting supply chains. |
| Cloud-Based Health Monitoring Deployment | Real-time vibration analytics enable predictive module swaps before costly hard failures occur. |
| Indian MRO Infrastructure Buildout | Bangalore and Hyderabad facility authorization captures low-cost carrier fleet densification demand. |
| Sustainable Aviation Fuel Compatibility Retrofit | Percent-blend certification pathways create aftermarket service expansion around fuel system upgrades. |
Research Methodology
Independent corroboration across engine program executives, MRO operations directors, airline fleet planners, and regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from FAA type certificate databases, EASA Certification Memoranda, ICAO CORSIA implementation documents, and customs records tracking aerospace-grade titanium and nickel superalloy trade flows. Bottom-up triangulation across module-level procurement volumes and top-down reconciliation against airframe delivery schedules anchor the analytical framework.
Historical reference periods spanning engine entry-into-service dates through current fleet accumulation rates anchor the projection horizon. The analytical framework models segmentation across product type, deployment model, end user category, and service type throughout the forecast period. CAGRs derive from fitted growth curves applied to module swap frequency trends and cloud-native health monitoring adoption velocities. Forecast inputs incorporate ceramic matrix composite time-on-wing extension assumptions and narrow-body fleet densification patterns across India and Vietnam.
Revisions become necessary when FAA Part 33 endurance testing bottlenecks extend type certificate amendment timelines or when sustainable aviation fuel compatibility mandates alter aftermarket service architectures. Forecasts reflect assumptions regarding EASA emissions protocol stability and mining output from Russian and Chinese suppliers. A model refresh is warranted upon material change in ICAO CORSIA compliance deadline enforcement or ceramic matrix composite manufacturing yield rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Hairpin Stator Market
Semiconductor Devices
Gan and Sic Power Semiconductor Market
Semiconductor Devices
Global Semiconductor Lead Frame Market
Semiconductor Devices
Global Small Signal Transistor Market
Semiconductor Devices
Single Electron Transistor Market
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
Field Programmable Gate Array (FPGA) Market
Semiconductor Devices
Plastic Transistors Market
Semiconductor Devices
Ram BOP Market
Semiconductor Devices
Japan Power Transistor Market
Semiconductor Devices
APAC Semiconductor Device for Industrial Applications Market
Semiconductor Devices
Analog and Mixed Signal Device Market
Semiconductor Devices
Data Processing Unit Market
Semiconductor Devices
Laneth-16 Market
Semiconductor Devices
Thin Film Transistors (TFT) Market
Semiconductor Devices
Japan CEP Market