
 Large-Size PV Silicon Wafer Market | 2026-2036
Large-Size PV Silicon Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
Large-Size PV Silicon Wafer Market Insights
M-grade wafer specifications is unwinding legacy supply commitments as buyers demand higher minority carrier lifetime thresholds. LONGi Green Energy Technology Co., Ltd. leverages integrated ingot-to-module production to lock in polysilicon offtake. TCL Zhonghuan Renewable Energy Technology Co. Ltd. anchors the 210mm format ecosystem through open-platform licensing to cell makers. JA Solar Holdings Co., Ltd. dominates Southeast Asian tolling arrangements that circumvent trade barriers.
Large-size PV silicon wafers are monocrystalline or polycrystalline semiconductor substrates, typically 182mm or 210mm in diagonal dimension, sliced from single-crystal or cast silicon ingots using diamond wire sawing to thicknesses ranging from 120 to 180 microns. These wafers serve as the foundational light-absorbing layer in photovoltaic cells, where photon energy converts to electrical current through the photovoltaic effect. Monocrystalline wafers command premium positioning in utility-scale applications where efficiency-per-watt drives project returns, while bifacial configurations capture incremental margin pools from albedo-sensitive installations. Thickness segmentation below 150 microns is accelerating as diamond wire and kerf-loss reduction techniques mature, though handling yield limits penetration in automated cell lines.
China's MIIT sets minimum efficiency thresholds and wafer dimension standards that de facto govern global supply specifications. The EU Green Deal and its attendant CSRD disclosure requirements are pressuring European developers to document embodied carbon in wafer sourcing, reshaping supplier qualification protocols. India's BIS certification mandate for imported solar cells and modules is forcing wafer vendors to pre-qualify local cell partners or establish domestic slicing operations. Stakeholders must track how the EU AI Act's supply-chain traceability provisions, when extended to critical raw materials, will interact with existing F-Gas Regulation boundaries on manufacturing process emissions.
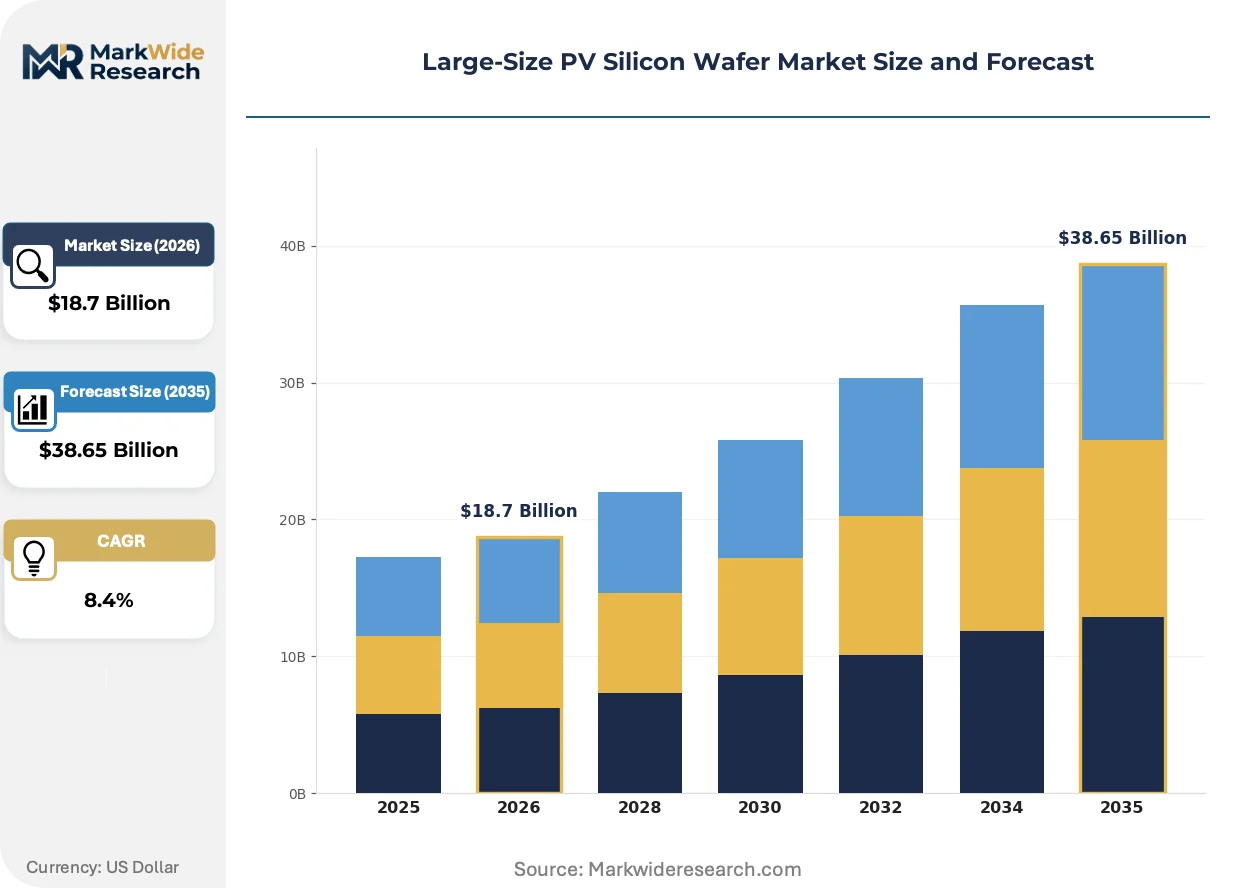
Market Dynamics
China's MIIT efficiency mandates and the EU Green Deal's embodied carbon disclosure rules are compressing wafer specification windows while fragmenting procurement geography, forcing manufacturers to maintain parallel product lines for diverging compliance regimes.
Growth Catalysts
- N-type cell migration:China's polysilicon-to-cell pipeline is retooling for higher minority carrier lifetime wafers, pulling 210mm format demand through utility-scale project pipelines.
- EU CSRD disclosure pressure:European developers now document supply-chain carbon intensity, creating qualification premiums for low-embodied-carbon wafer sources.
- India's BIS mandate:The certification requirement for imported cells is accelerating domestic slicing joint ventures and captive capacity builds.
Market Restraints
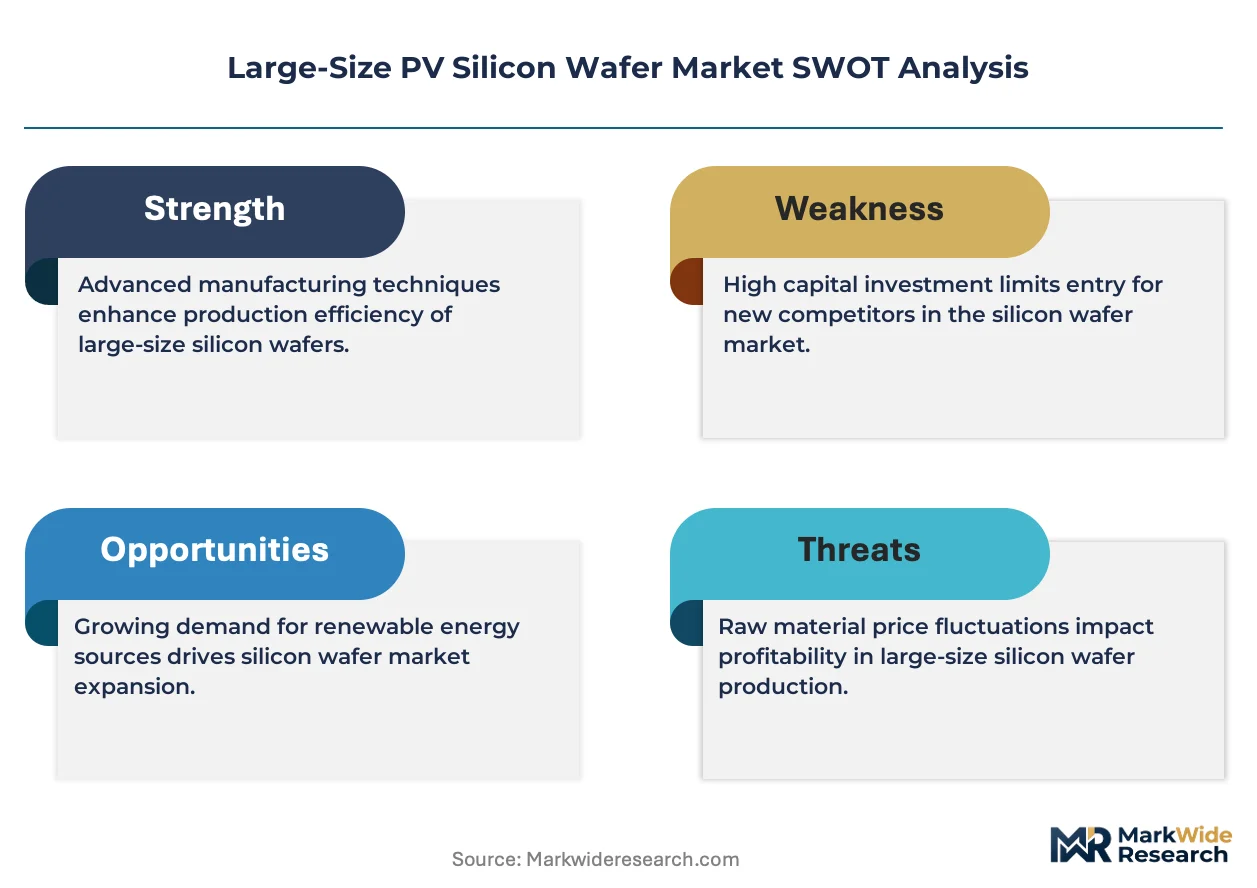
- Polysilicon cost volatility:Metallurgical-grade silicon feedstock and energy-intensive purification expose margins to electricity price spikes in Xinjiang and Inner Mongolia.
- Handling yield limits:Automated cell lines face breakage rates above threshold when processing sub-150 micron thicknesses, capping kerf-loss reduction programs.
- Trade barrier fragmentation:US anti-dumping duties and India's BIS rules force tolling arrangements through Southeast Asian intermediaries, elongating working capital cycles.
Strategic Opportunities
- US captive wafer builds:The IRA domestic content bonus is pulling slicing investments toward Arizona and Texas to serve utility-scale developers.
- Bifacial albedo capture:Desert and snow-field installations are specifying higher-transparency wafer architectures for rear-side energy harvest.
- Open-platform 210mm licensing:Format ecosystem control through royalty-free technical standards is displacing proprietary 182mm lock-in.
Industry Challenges
- Diamond wire sawing expertise scarcity:Thin-wafer processing requires technicians trained on kerf-loss optimization and surface damage engineering.
- Dual certification timelines:Simultaneous BIS, IEC, and UL qualification for India, Europe, and US markets stretches product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large-Size PV Silicon Wafer Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Bifacial, Thin Film Thickness: 180 Microns, 200 Microns, 300 Microns, 120 Microns Application: Utility-Scale, Residential, Commercial, Industrial End User: OEMs, Solar Installers, Distributors, Research Institutions |
| Companies Covered | LONGi Green Energy Technology Co., Ltd., TCL Zhonghuan Renewable Energy Technology Co. Ltd., GCL-Poly Energy Holdings Limited, JinkoSolar Holding Co., Ltd., JA Solar Holdings Co., Ltd., Risen Energy Co., Ltd., Trina Solar Co., Ltd., Shin-Etsu Chemical Co., Ltd., SUMCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large-Size PV Silicon Wafer Market Trends and Innovations
Wafer manufacturing is bifurcating between thickness-reduction programs chasing polysilicon savings and format-standardization battles determining cell line capital allocation.
Tandem cell architectures are supplanting single-junction PERC designs in premium utility bids. LONGi and Tongwei are piloting perovskite-silicon stacks requiring ultra-flat wafer surfaces below 130 microns. These structures enable module efficiencies above 26 percent, compressing LCOE calculations for Middle Eastern and Australian project finance.
The EU F-Gas Regulation is tightening process emissions boundaries for SF6 and NF3 used in ingot doping. Wafer vendors serving European developers must now document fluorinated gas containment protocols in CSRD supply-chain disclosures. Germany's KBA and France's environmental agency are cross-referencing these filings against actual facility audits.
Direct long-term offtake contracts are displacing spot-market wafer purchases among top-ten module assemblers. Buyers in India's Gujarat and Rajasthan solar parks are locking three-year supply agreements with fixed-thickness specifications. This concentration of procurement volume is squeezing merchant wafer traders in Jiangsu and Zhejiang.
Large-Size PV Silicon Wafer Market Segmentation
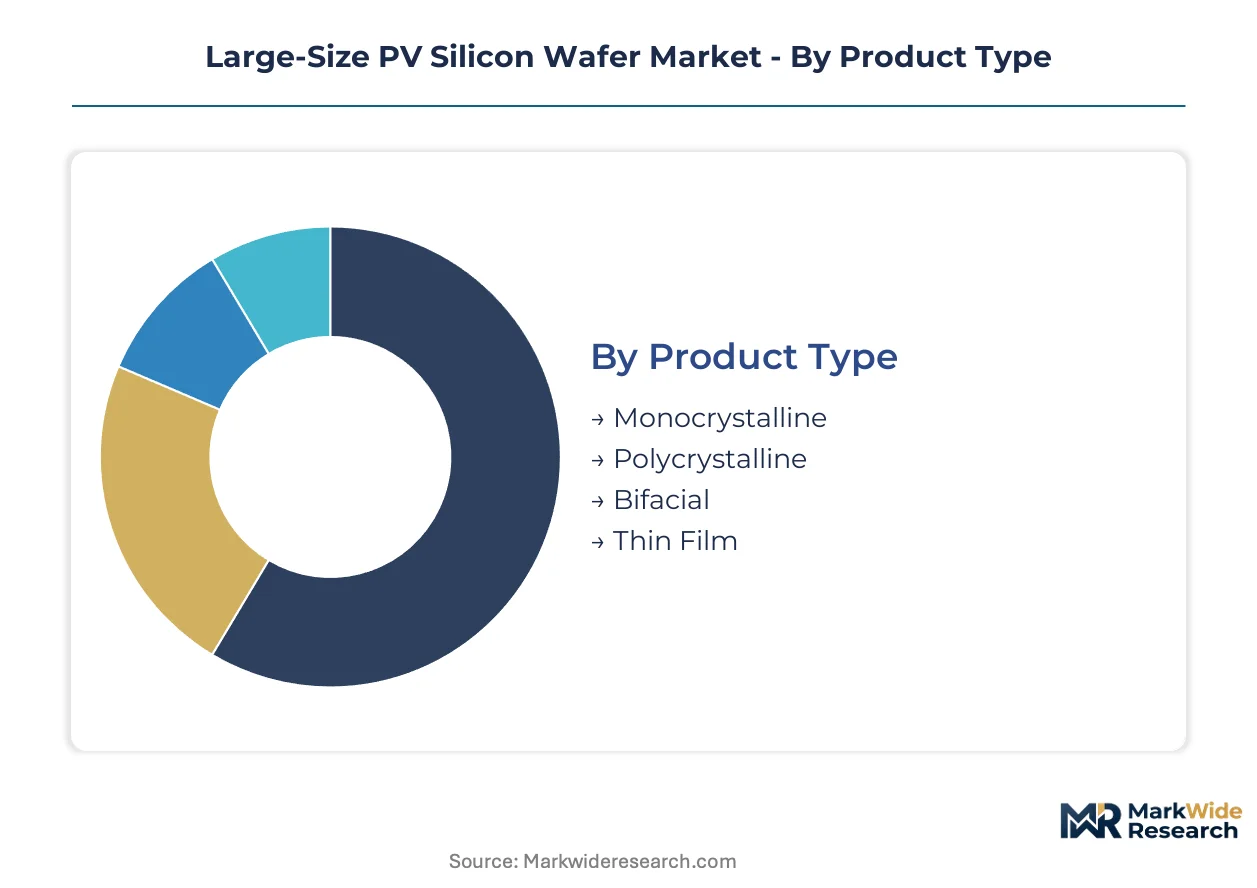
Wafer specification choices cascade through cell efficiency, module power ratings, and ultimately project IRR calculations. Segment boundaries are hardening as China's MIIT efficiency mandates and EU embodied carbon rules force product-line bifurcation.
Product Type:
Margin pools concentrate in monocrystalline premium tiers serving Middle Eastern and Australian utility bids where LCOE compression justifies efficiency premiums.
- Monocrystalline:Single-crystal ingots sliced via diamond wire sawing deliver superior minority carrier lifetime for N-type cell architectures. Utility-scale developers in Saudi Arabia and Australia specify these wafers for bifacial module configurations where albedo capture amplifies project returns.
- Bifacial:Higher-transparency wafer substrates enable rear-side photon absorption in desert and snow-field installations. China's Jiangsu and Zhejiang manufacturing clusters are retooling output mix toward bifacial-compatible specifications as European developers document rear-side yield gains in CSRD disclosures.
- Polycrystalline:Cast silicon ingots offer cost positioning for price-sensitive distributed generation segments in India and Southeast Asia.
- Thin Film:Cadmium telluride and CIGS alternatives occupy niche building-integrated applications where flexibility outweighs efficiency metrics.
Monocrystalline holds installed capacity. Bifacial is rotating up the share rankings.
Thickness:
Cost tier stratification tracks polysilicon savings potential against handling yield breakage thresholds in automated cell lines.
- 120 Microns:Kerf-loss reduction programs target maximum polysilicon conservation for integrated manufacturers with captive ingot supply. LONGi and Tongwei pilot lines in Xi'an and Hefei are stress-testing sub-130 micron substrates for perovskite-silicon tandem stacks requiring ultra-flat surfaces.
- 180 Microns:Legacy specification maintains broad compatibility with PERC cell lines across Southeast Asian tolling arrangements. Indian BIS certification timelines favor this thickness for initial qualification batches as domestic slicing joint ventures ramp in Gujarat.
- 200 Microns:Conservative specification persists in residential rooftop segments where installer handling variability elevates breakage risk.
- 300 Microns:Specialty thickness serves research institutions and pilot production lines testing next-generation cell architectures.
180 microns dominates current procurement volume. 120 microns is climbing the fastest as diamond wire expertise diffuses.
Application:
Volume concentration tracks utility-scale project pipelines where single-purchase orders absorb gigawatt-scale wafer output.
- Utility-Scale:Solar farms above 100MW specify 210mm format wafers for high-wattage module assembly. Developers in Texas and Arizona are locking three-year offtake agreements with fixed-thickness specifications to secure IRA domestic content bonus eligibility.
- Residential:Distributed rooftop installations in Germany and Italy favor standardized 182mm formats where module weight limits constrain handling logistics.
- Commercial:C&I segments in India's Rajasthan and Gujarat solar parks balance efficiency requirements against capital expenditure constraints.
- Industrial:Self-consumption installations at manufacturing facilities prioritize payback period over maximum efficiency metrics.
Utility-scale commands procurement volume concentration. Residential is gaining share fastest as EU rooftop mandates accelerate.
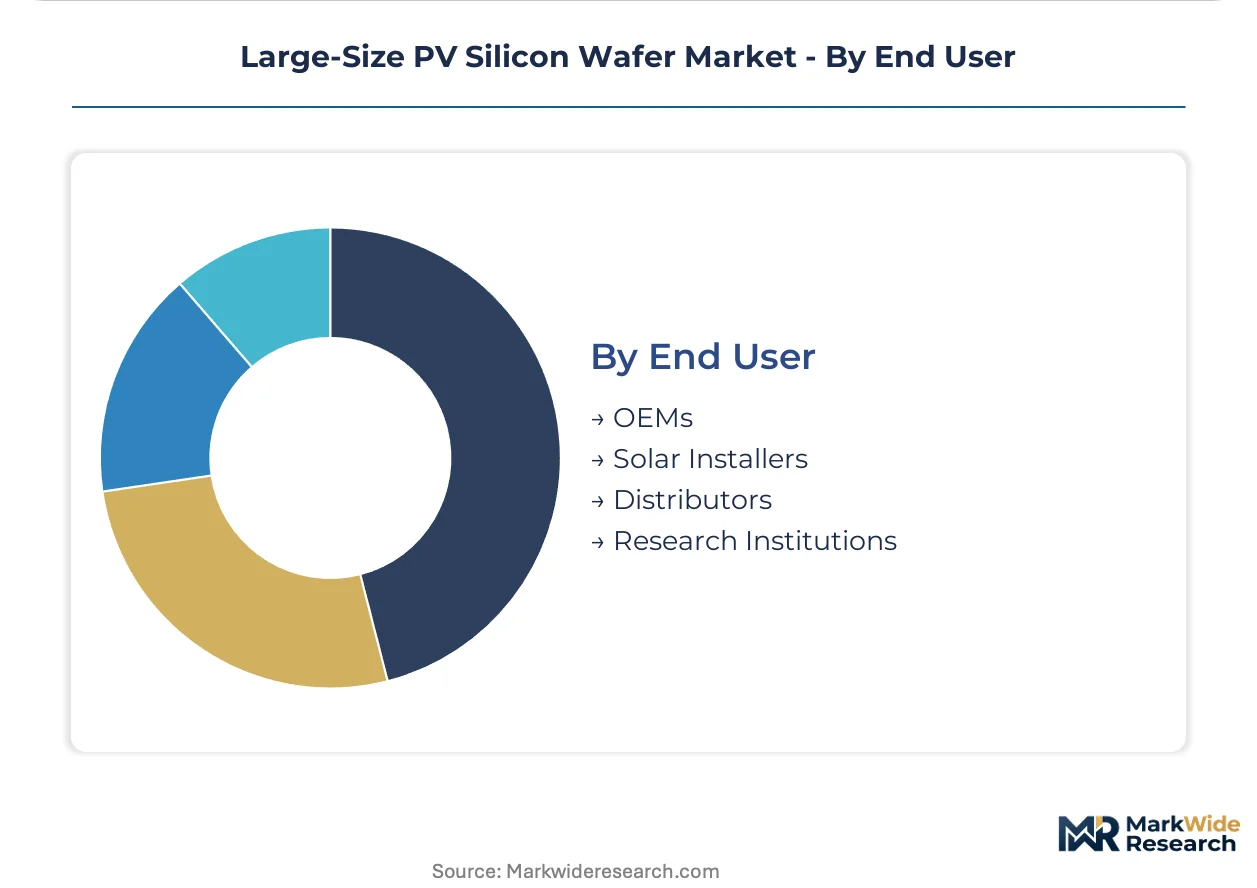
End User:
Customer type determines contract structure, with OEMs extracting volume discounts and research institutions paying specification premiums.
- OEMs:Vertically integrated module assemblers in China and Southeast Asia negotiate direct long-term offtake contracts bypassing merchant traders. These buyers specify exact minority carrier lifetime thresholds and thickness tolerances in binding supply agreements.
- Solar Installers:EPC contractors in the US Southwest and Indian states aggregate project demand into quarterly procurement batches with flexible specification windows.
- Distributors:Merchant traders in Jiangsu and Zhejiang face margin compression as direct OEM contracts displace spot-market volume.
- Research Institutions:National laboratories and university consortia purchase small-batch ultra-thin wafers for tandem cell and passivation layer experiments.
OEMs hold procurement leverage. Solar installers are expanding fastest as US and Indian project pipelines deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer slicing capacity clusters in eastern China while demand disperses across utility-scale project pipelines in North America, Europe, and South Asia. Regulatory fragmentation around carbon disclosure and domestic content is forcing manufacturers to replicate production footprints across multiple jurisdictions.
China
Jiangsu and Zhejiang provinces host the dominant ingot-growing and wafer-slicing complexes serving global module assemblers. MIIT efficiency mandates and dual carbon goals are accelerating N-type cell migration, pulling 210mm format adoption through domestic utility pipelines. Xi'an and Hefei pilot lines stress-test sub-130 micron substrates for tandem cell architectures.
United States
Texas and Arizona project developers are locking three-year offtake agreements to secure IRA domestic content bonus eligibility. FERC interconnection queues and state renewable portfolio standards are absorbing gigawatt-scale wafer volumes. Arizona slicing investments are ramping to serve captive module assembly operations.
Germany
CSRD disclosure requirements and the EU Green Deal are pressuring developers to document embodied carbon in wafer sourcing. KBA facility audits cross-reference fluorinated gas containment protocols against supply-chain filings. Bavarian and North Rhine-Westphalian solar parks are specifying low-carbon wafer qualifications in tender documents.
India
BIS certification mandates for imported cells are accelerating domestic slicing joint ventures in Gujarat and Rajasthan. PLI scheme incentives are pulling captive wafer capacity builds to serve state solar parks. Telangana and Karnataka are emerging as alternative manufacturing locations as land and power costs rise in western states.
Saudi Arabia
Vision 2030 utility-scale tenders are specifying bifacial module configurations for desert albedo capture. SFDA and national procurement standards are aligning with IEC certification timelines. NEOM and the Eastern Province are anchoring gigawatt-scale project pipelines that absorb premium-format wafer output.
Large-Size PV Silicon Wafer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Vertically integrated polysilicon-to-module operators compete against specialized wafer slicers on margin capture and capital efficiency. Three archetypes dominate: integrated energy conglomerates with captive polysilicon supply, open-platform format licensors, and tolling specialists routing through Southeast Asian trade corridors. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms lock in offtake ahead of format standardization battles.
Among Chinese integrated operators, LONGi Green Energy Technology Co., Ltd. and TCL Zhonghuan Renewable Energy Technology Co. Ltd. exemplify divergent strategic postures—one representing closed-loop margin capture, the other open-ecosystem format control. JA Solar Holdings Co., Ltd. occupies a position within the tolling-specialist archetype, routing supply through Southeast Asian intermediaries to circumvent trade barriers. These three anchors illustrate how geography, integration depth, and platform strategy segment competitive positioning.
| Leading Market Players |
|---|
| LONGi Green Energy Technology Co., Ltd. |
| TCL Zhonghuan Renewable Energy Technology Co. Ltd. |
| GCL-Poly Energy Holdings Limited |
| JinkoSolar Holding Co., Ltd. |
| JA Solar Holdings Co., Ltd. |
| Risen Energy Co., Ltd. |
| Trina Solar Co., Ltd. |
| Shin-Etsu Chemical Co., Ltd. |
| SUMCO Corporation |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization rates above 85 percent in Jiangsu and Zhejiang ingot-growing facilities compress marginal cost curves and harden price floors for merchant wafer traders. China's MIIT efficiency mandates and the EU CSRD disclosure requirements create parallel specification tracks that fragment pricing power across compliance tiers.
Pricing Analysis
China's MIIT dictates the pricing tier structure through minimum efficiency thresholds that separate premium N-type monocrystalline wafers from legacy PERC-compatible specifications. Price differentiation rests on minority carrier lifetime certification grades and volume-scale contract terms, with integrated manufacturers capturing margin pools that merchant traders cannot access. Cost compression in standard-grade 180-micron wafers is intensifying because polysilicon feedstock volatility in Xinjiang feeds through to spot-market quotations. Utility-scale developers in Texas and Arizona demonstrate lowest price sensitivity through multi-year offtake locks, while Indian distributors in Gujarat face acute margin pressure from BIS certification timelines.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane elongate inbound logistics cycles for European module assemblers sourcing from Jiangsu. Geographic supply concentration centers on China, Vietnam, and Malaysia, where tolling arrangements circumvent US anti-dumping duty exposure. Raw material dependencies draw from metallurgical-grade silicon in Yunnan, diamond wire consumables from Japanese suppliers, and high-purity quartz crucibles for ingot growth. Single-source vulnerability in polysilicon purification equipment creates chokepoint risk. Distribution runs through vertically integrated OEM direct contracts that displace merchant traders in Zhejiang.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The large-size PV silicon wafer market is approaching a platform-economics inflection as TCL Zhonghuan's open-platform 210mm licensing displaces proprietary format lock-in and reshapes ecosystem control.
For Market Incumbents: Fortify ingot-to-module integration through captive polysilicon offtake agreements that insulate margin pools from Xinjiang electricity price spikes. Accelerate minority carrier lifetime certification investments to meet EU CSRD disclosure thresholds before competitor qualification. The threat of tolling specialists routing through Southeast Asian intermediaries demands channel control through direct long-term contracts with Texas and Arizona utility developers. For New Entrants and Emerging Players: After-sales technical service for automated cell line integration represents a service-layer gap where incumbents under-serve mid-scale Indian slicing joint ventures. Target domestic qualification partnerships in Gujarat and Rajasthan solar parks where BIS certification mandates create penetrable white space. A go-to-market angle anchored in diamond wire sawing expertise transfer contracts bypasses capital-intensive ingot-growing barriers. For Investors and Strategic Acquirers: Specialized wafer slicers with tolling-specialist positioning and Southeast Asian facility footprints offer acquisition exposure to trade-barrier arbitrage economics. Long-term viability hinges on format standardization outcomes between 182mm and 210mm ecosystems. The signal to watch is IRA domestic content bonus eligibility determinations for Arizona and Texas slicing investments, which would recalibrate capital allocation toward North American captive capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Arizona slicing investments secure IRA domestic content bonus eligibility for utility developers. |
| Technology Licensing | Open-platform 210mm royalty-free standards displace proprietary format lock-in across cell makers. |
| Long-term Supply Agreement | Three-year offtake locks with fixed-thickness specifications compress working capital cycles. |
| Backward Integration | Captive polysilicon supply insulates margin pools from Xinjiang electricity price volatility. |
| Green Certification Program | CSRD-compliant embodied carbon documentation qualifies suppliers for European tender premiums. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wafer procurement managers at module assemblers, plant directors at Jiangsu slicing facilities, EPC contractors in Texas and Indian solar parks, and diamond wire equipment specialists. Secondary validation drew from MIIT efficiency mandate filings, EU CSRD disclosure protocols, BIS certification timelines, SEC 10-K filings of listed solar manufacturers, and customs data tracking polysilicon trade flows. Bottom-up capacity utilization models and top-down utility-scale project pipeline assessments were triangulated against format adoption curves.
Across the analysis window, the quantitative framework modeled volume and value outputs through segmentation across wafer format, thickness tier, cell architecture compatibility, and regional regulatory cluster. CAGRs were derived from installed capacity buildout trajectories and project finance absorption rates. Industry-specific forecast inputs incorporated FERC interconnection queue progressions and PLI scheme incentive disbursement schedules in India.
Forecasts assume regulatory continuity in China's MIIT mandates, EU CSRD disclosure requirements, and US IRA domestic content provisions; material policy shifts would require re-modeling. Technology inflection risks from perovskite-silicon tandem commercialization and trade barrier recalibrations represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Asia-Pacific Semiconductor Device Market
Semiconductor Devices
Global Gan Semiconductor Device Market
Semiconductor Devices
Finfet Technology Market
Semiconductor Devices
Field-Effect Rectifier Diodes Market
Semiconductor Devices
IT & Telecom Discrete Semiconductor Market
Semiconductor Devices
Americas Semiconductor Diode Market
Semiconductor Devices
Field Programmable Gate Array (FPGA) Market
Semiconductor Devices
Global Vacuum Capacitors Market
Semiconductor Devices
Micro Thermoelectric Modules Market
Semiconductor Devices
North America Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Semiconductor Device in Aerospace and Defense Industry Market
Semiconductor Devices
Varactor Diode Market
Semiconductor Devices
Thin Wafer Market
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
Semiconductor Tubular Heaters Market
Semiconductor Devices
Europe Semiconductor Device Market