
 Japan Semiconductor Diode Market | 2026-2036
Japan Semiconductor Diode Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Semiconductor Diode Market Insights
Automotive electronics is pivoting toward wide-bandgap diode architectures as Japanese OEMs electrify platforms. Rohm Semiconductor anchors silicon carbide vertical integration from ingot to module. Toshiba Electronic Devices leverages decades of rectifier expertise to sustain industrial market share. Renesas Electronics Corporation competes through automotive-grade qualification depth and tier-one supply chain proximity.
Japan semiconductor diodes are two-terminal nonlinear electronic components fabricated from silicon, silicon carbide, or gallium nitride that permit current flow in one direction while blocking reverse bias up to specified breakdown voltages, serving essential functions in power conversion, signal conditioning, and circuit protection across industrial and consumer systems. Schottky diodes lead volume in consumer and computing applications where low forward voltage drop determines efficiency, while silicon carbide rectifiers command premium positioning in automotive traction inverters due to thermal performance and switching speed advantages. Gallium nitride technology occupies an emerging niche in telecommunications infrastructure where millimeter-wave frequencies demand minimal junction capacitance.
METI's semiconductor and digital industry strategy shapes capital allocation toward domestic wafer fabrication and advanced packaging capacity. JIS standards and PMDA-adjacent quality frameworks govern automotive and medical device diode specifications, creating compliance barriers for non-certified suppliers. Stakeholders must monitor substrate supply security and METI subsidy disbursement timing to calibrate capacity expansion decisions against competitor positioning in Kyushu and Hiroshima manufacturing corridors.
Market Dynamics
Wide-bandgap substrate qualification is compressing legacy silicon rectifier margins while METI subsidy disbursements accelerate domestic SiC ingot capacity buildout across Kyushu manufacturing corridors.
Growth Catalysts
- EV Powertrain Electrification:Japanese OEMs are mandating silicon carbide traction inverters for next-generation platforms, pulling premium diode demand into automotive qualification pipelines.
- METI Semiconductor Resilience Framework:Domestic wafer fabrication subsidies are redirecting procurement toward local supply chains, reducing import dependency for critical substrate materials.
- Kyushu Silicon Island Cluster:Concentrated foundry and packaging infrastructure in Fukuoka and Kumamoto prefectures is lowering logistics costs for integrated device manufacturers.
Market Restraints
- Substrate Supply Concentration:Six-inch SiC wafer supply remains captive to limited US and European ingot growers, constraining Japanese module makers.
- Energy-Intensive Epitaxy:Chemical vapor deposition processes for SiC epi-layer growth consume disproportionate electricity, amplifying cost volatility amid regional power pricing fluctuations.
- JIS Certification Friction:Automotive-grade diode qualification under JIS standards imposes eighteen-month validation timelines that exclude non-domestic suppliers from tier-one procurement.
Strategic Opportunities
- Industrial Motor Drive Retrofit:Aging manufacturing infrastructure across Shikoku and Tohoku regions presents addressable demand for silicon carbide rectifier upgrades in variable frequency drives.
- Telecom Infrastructure Buildout:Millimeter-wave base station deployment for 5G-Advanced networks is creating niche demand for gallium nitride Schottky diodes with minimal junction capacitance.
- PMDA-Adjacent Medical Device Certification:Diagnostic imaging equipment manufacturers are specifying automotive-grade diodes for MRI power supplies, opening cross-sector qualification pathways.
Industry Challenges
- Compound Semiconductor Process Engineering Talent:Epitaxial growth and defect characterization expertise for SiC and GaN materials remains concentrated among retiring specialists at national research institutes.
- Legacy Rectifier Integration Complexity:Industrial customers maintaining thirty-year equipment lifecycles face technical friction when substituting wide-bandgap devices for silicon rectifiers in existing circuit topologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Semiconductor Diode Market |
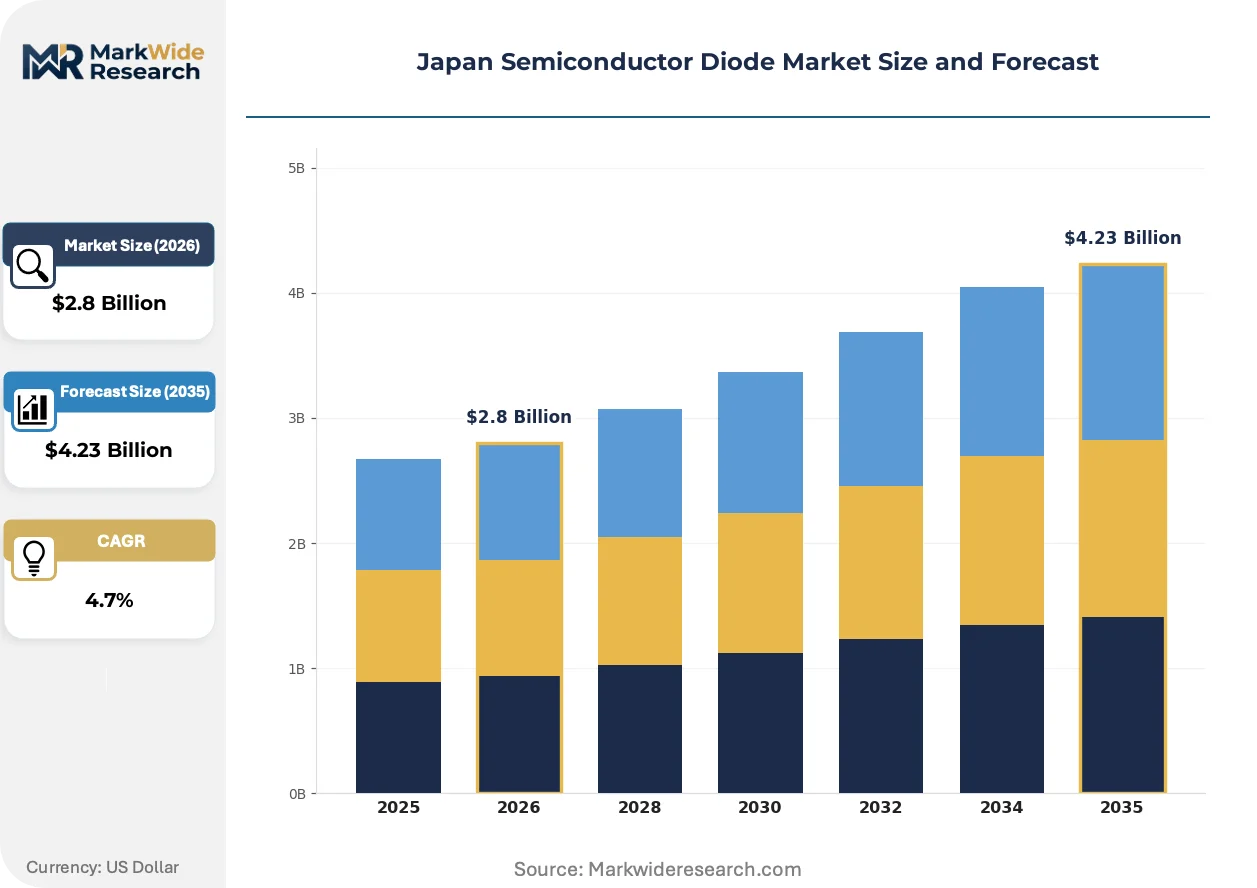
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zener Diodes, Schottky Diodes, Rectifier Diodes, Signal Diodes End User: Automotive Electronics, Consumer Electronics, Telecommunications, Industrial Applications Packaging Type: Surface Mount, Through Hole, Chip On Board, Dual In-Line Package Technology: Silicon, Gallium Nitride, Silicon Carbide, Organic |
| Companies Covered | Renesas Electronics Corporation, Rohm Semiconductor, Toshiba Electronic Devices, Hitachi Power Semiconductor Device Ltd, Fuji Electric, Sony Semiconductor Solutions, Seiko Instruments, Central Semiconductor Corporation, Diodes Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Semiconductor Diode Market Trends and Innovations
Material science breakthroughs and procurement model evolution are compressing product lifecycles while regulatory pressure accelerates qualification standard harmonization across automotive and industrial segments.
Silicon carbide MOSFET body diode integration is eliminating discrete rectifier requirements in high-frequency power conversion architectures. Automotive inverter designers at tier-one suppliers are adopting co-packaged solutions to reduce component count and thermal interface resistance. This integration is compressing addressable market volume for standalone discrete diodes in premium EV platforms.
METI's semiconductor and digital industry strategy is mandating domestic substrate fabrication capacity targets by fiscal year-end. Industrial consequence includes accelerated capital allocation toward Hiroshima and Kyushu wafer facilities with government matching funds. Automotive-grade diode suppliers are responding by pre-qualifying local epitaxy sources to secure JIS certification continuity.
Long-term supply agreements with foundry partners are displacing spot-market purchasing for critical SiC components. Tier-one automotive electronics buyers are locking three-to-five-year wafer allocations to secure substrate access amid ingot supply constraints. This behavioral shift is most visible among Tokyo-Osaka corridor module manufacturers supplying electrified powertrain platforms.
Japan Semiconductor Diode Market Segmentation
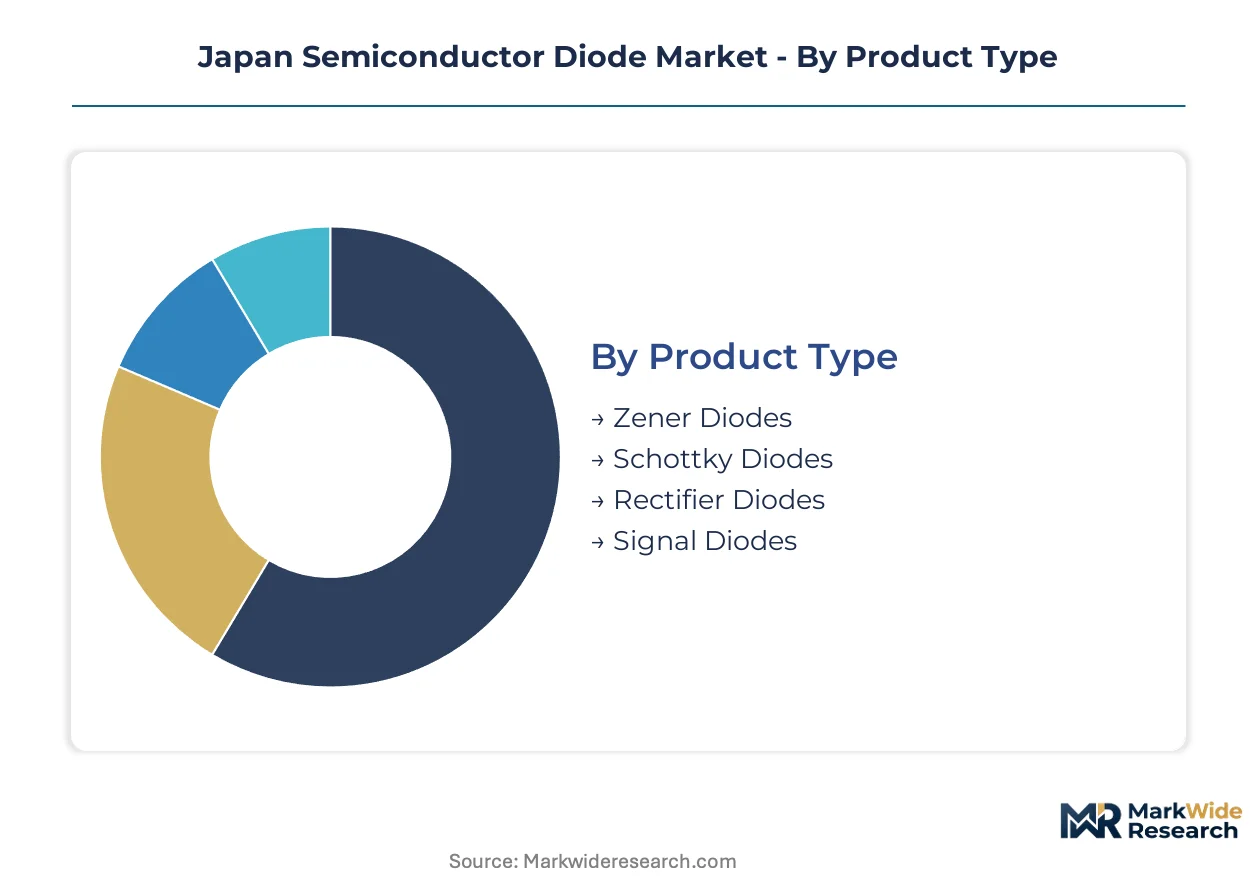
Japan's semiconductor diode market segments reflect divergent upgrade cycles across power electronics, signal conditioning, and protection applications. Component selection hinges on thermal performance thresholds, JIS certification requirements, and integration complexity within Kyushu and Tokyo-Osaka manufacturing corridors.
Product Type:
Replacement cycles vary dramatically by rectifier architecture, with silicon carbide platforms demanding complete system redesigns versus drop-in silicon upgrades.
- Zener Diodes:Voltage reference and surge protection devices exploiting controlled reverse breakdown characteristics. Automotive ECU manufacturers in Aichi Prefecture specify AEC-Q101 qualified variants for load dump protection, though qualification timelines extend component lifecycles.
- Schottky Diodes:Metal-semiconductor junction devices delivering sub-0.5V forward voltage drops. Consumer computing OEMs in the Tokyo corridor prioritize these for DC-DC converter efficiency, pulling volume from standard rectifier inventories.
- Rectifier Diodes:High-current silicon p-n junction devices dominating industrial motor drive retrofits across Shikoku manufacturing belts.
- Signal Diodes:Small-switching devices for RF and logic isolation in telecommunications infrastructure buildouts.
Volume placements concentrate in Schottky Diodes; the faster expansion belongs to Zener Diodes.
End User:
Customer procurement patterns split between JIS-mandated automotive qualification pipelines and price-sensitive consumer electronics spot purchasing.
- Automotive Electronics:Traction inverter and onboard charger applications specifying AEC-Q101 and JIS D 0203 environmental stress compliance. Tier-one suppliers in Hiroshima Prefecture lock three-to-five-year wafer allocations for SiC rectifier supply security.
- Industrial Applications:Variable frequency drives and welding equipment demanding high-temperature operation. Aging infrastructure across Tohoku regions creates retrofit demand for wide-bandgap replacements.
- Consumer Electronics:Computing and mobile device power management prioritizing cost-optimized surface-mount Schottky solutions.
- Telecommunications:5G-Advanced base station deployment requiring minimal junction capacitance for millimeter-wave signal chains.
Revenue concentration sits with Automotive Electronics; Industrial Applications are climbing the fastest amid electrification mandates.
Packaging Type:
Mounting technology selection tracks thermal dissipation requirements and automated assembly line compatibility across Japanese contract manufacturers.
- Surface Mount:Leadless chip carriers and small-outline packages dominating high-density consumer PCB assemblies. Osaka-area EMS providers favor these for pick-and-place throughput optimization.
- Through Hole:Axial and radial leaded packages persisting in industrial power supplies requiring manual rework accessibility. Legacy equipment maintenance across Kyushu steel mills sustains demand.
- Chip On Board:Bare die attach for miniaturized medical imaging and optical sensor modules.
- Dual In-Line Package:Through-hole configurations for prototype and low-volume industrial control systems.
Unit shipments favor Surface Mount; Through Hole retains margin strength in aftermarket industrial channels.
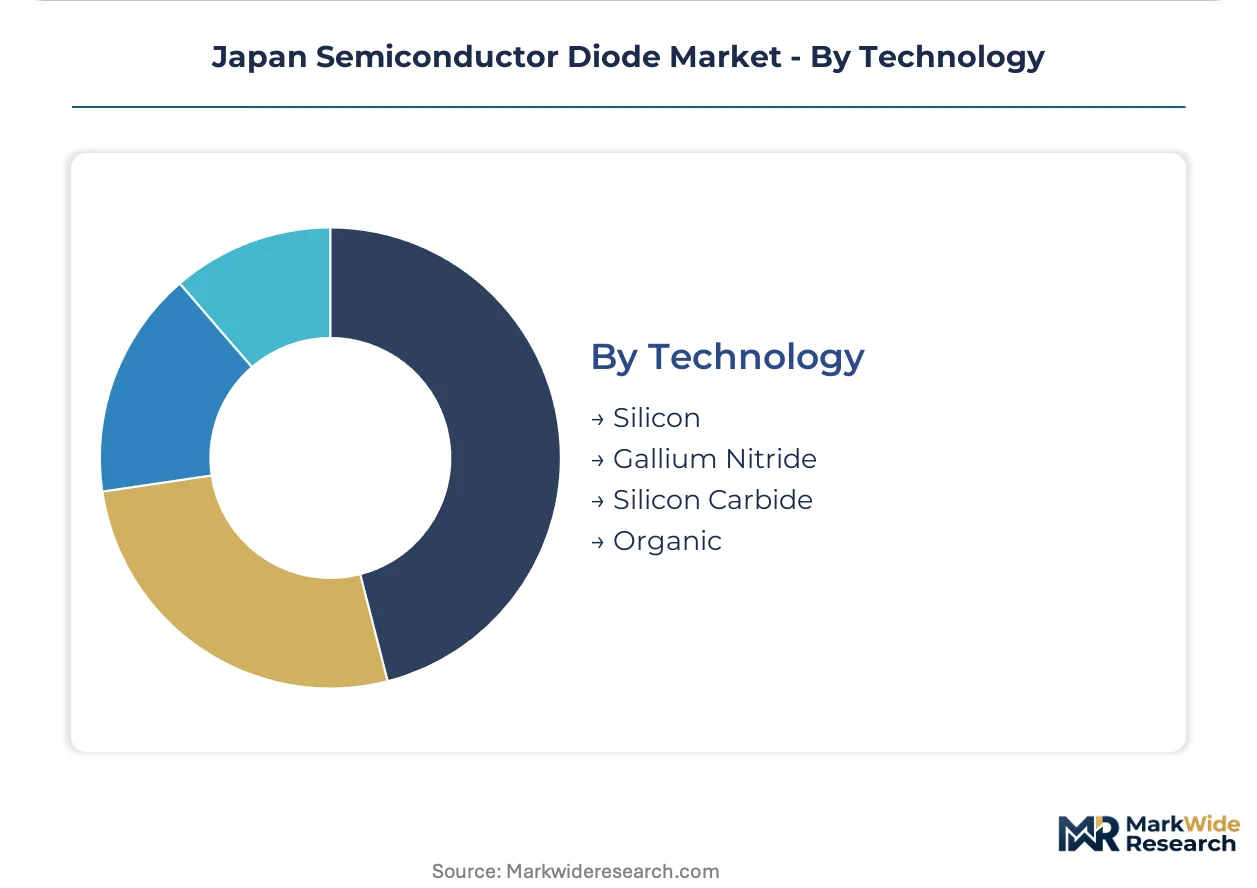
Technology:
Material platform transitions accelerate where METI subsidies offset capital intensity for domestic substrate fabrication.
- Silicon Carbide:Wide-bandgap crystals enabling 1200V+ blocking voltages with minimal switching losses. EV powertrain electrification at Japanese OEMs pulls six-inch wafer demand toward Kyushu epitaxy facilities.
- Silicon:Mature p-n junction technology commanding cost-optimized rectifier markets. Industrial motor drive retrofits across Shikoku and Tohoku regions sustain volume despite margin compression.
- Gallium Nitride:Heterostructure devices for sub-100V high-frequency conversion. Telecommunications infrastructure buildouts for 5G-Advanced networks exploit minimal gate charge characteristics.
- Organic:Polymer-based flexible diodes for emerging wearable and bio-integrated sensor applications.
Silicon retains volume dominance; Silicon Carbide shows the steepest expansion trajectory as METI resilience policies redirect procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kyushu's special economic zone status for semiconductor fabrication concentrates domestic diode production capacity through METI-matched capital subsidies. Regional procurement patterns track government resilience mandates and automotive OEM electrification timelines.
Kanto/Tokyo
Tokyo-based tier-one automotive electronics buyers lock long-term wafer allocations for SiC rectifier supply security. METI's semiconductor strategy directs subsidy disbursements toward domestic substrate fabrication targets. The Tokyo-Osaka corridor hosts concentrated module manufacturing for EV powertrain platforms.
Kansai/Osaka
Osaka-area EMS providers optimize pick-and-place throughput with surface-mount Schottky diode volumes for consumer computing OEMs. JIS certification requirements under METI industrial standards govern component qualification pipelines. The region's packaging infrastructure serves high-density PCB assembly demand.
Kyushu
Fukuoka and Kumamoto prefectures anchor silicon carbide epitaxy facility buildouts under METI resilience policies. Six-inch wafer supply constraints from US and European ingot growers limit Japanese module maker expansion. The silicon island cluster lowers logistics costs for integrated device manufacturers through co-located foundry capacity.
Chubu/Nagoya
Aichi Prefecture automotive ECU manufacturers specify AEC-Q101 qualified Zener diodes for load dump protection. JIS D 0203 environmental stress compliance extends component qualification timelines. The region's OEM supply chain proximity accelerates tier-one procurement decisions for traction inverter applications.
Tohoku
Aging industrial infrastructure across Tohoku regions creates retrofit demand for wide-bandgap rectifier upgrades in variable frequency drives. Regional power pricing fluctuations amplify cost volatility for energy-intensive SiC epitaxy processes. Steel mill maintenance requirements sustain through-hole package demand for legacy equipment.
Japan Semiconductor Diode Market Competitive Landscape
Top-tier vendors anchor automotive-grade qualification pipelines, while mid-tier specialists occupy industrial and consumer price-sensitive segments. The vendor structure concentrates around compound semiconductor substrate control and JIS certification depth. Three archetypes dominate: integrated device manufacturers with captive SiC ingot supply, fabless designers leveraging foundry partnerships, and discrete component specialists maintaining legacy rectifier portfolios. Capacity expansion and strategic partnerships constitute the dominant competitive moves as substrate access constraints intensify.
Among Japan-based integrated manufacturers, Renesas Electronics Corporation, Rohm Semiconductor, and Toshiba Electronic Devices occupy positions reflecting divergent vertical integration strategies. Renesas exemplifies the automotive-grade qualification depth archetype through tier-one supply chain proximity. Rohm anchors silicon carbide vertical integration from substrate to module. Toshiba leverages decades of rectifier expertise to sustain industrial market share. Each represents a distinct pathway for securing substrate access amid METI-directed domestic capacity buildouts.
| Leading Market Players |
|---|
| Renesas Electronics Corporation |
| Rohm Semiconductor |
| Toshiba Electronic Devices |
| Hitachi Power Semiconductor Device Ltd |
| Fuji Electric |
| Sony Semiconductor Solutions |
| Seiko Instruments |
| Central Semiconductor Corporation |
| Diodes Incorporated |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers anchored by METI-matched capital subsidies command pricing discipline through captive six-inch SiC wafer allocations, while family-owned mid-caps in the Tokyo-Osaka corridor absorb margin compression from spot-market substrate volatility. This ownership-financing bifurcation stratifies procurement power between automotive tier-one suppliers locking long-term offtake and industrial buyers exposed to energy-intensive epitaxy cost fluctuations.
Pricing Analysis
Premium pricing attaches to sub-twelve-week lead-time commitments for AEC-Q101 qualified SiC rectifiers, while spot inventory of standard silicon Schottky devices trades at discounted clearing levels. Three-tier pricing structure across automotive-grade certified, industrial-standard, and consumer-economy levels differentiates by JIS D 0203 compliance depth and thermal performance grade. Cost compression in the industrial tier is intensifying because legacy equipment retrofit demand concentrates price-sensitive procurement committees across Shikoku and Tohoku regions. Consumer electronics OEMs exhibit highest price sensitivity, whereas Hiroshima-based traction inverter suppliers accept premium positioning for supply security.
Supply Chain Analysis
Freight cost differentials between Kyushu domestic epitaxy facilities and US-European ingot sources amplify total landed cost variance for six-inch SiC substrates. Geographic supply concentration centers on Japan's Kyushu cluster, South Korea's power semiconductor foundries, and US substrate growers in North Carolina and New York. Raw material dependencies include high-purity silicon carbide powder, nickel-based ohmic contact metallization, and ceramic substrate carriers. Single-source vulnerability from limited qualified ingot growers constrains Japanese module makers. Distribution runs through tier-one automotive electronics buyers locking direct wafer allocations, bypassing traditional component distributors for critical SiC devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where JIS D 0203 environmental stress qualification creates an eighteen-month barrier-to-entry moat protecting domestic incumbents from non-certified foreign suppliers.
For Market Incumbents: Deploy backward integration into six-inch SiC epitaxy capacity in Kyushu manufacturing corridors to secure substrate access against US and European ingot supply concentration. Deepen AEC-Q101 certification pipelines to defend automotive tier-one positioning from emerging Chinese power semiconductor entrants. Channel control through direct wafer allocation agreements with Fukuoka foundry partners reinforces procurement leverage. For New Entrants and Emerging Players: Industrial maintenance contractors across Tohoku steel mills represent an underserved buyer archetype requiring through-hole package compatibility for thirty-year equipment lifecycles. Penetrate the Shikoku variable frequency drive retrofit segment by qualifying silicon carbide rectifiers for drop-in replacement of legacy silicon devices. Go-to-market leverage rests on local service partnerships with regional electrical distributors maintaining legacy equipment spare parts inventories. For Investors and Strategic Acquirers: Distressed-cycle entries favor compound semiconductor process engineering specialists with METI subsidy access in Hiroshima and Kumamoto prefectures amid energy cost volatility and substrate supply constraints. Long-term viability across the projection horizon hinges on captive epitaxy capability and JIS certification depth rather than pure scale. Monitor METI subsidy disbursement timing and six-inch wafer spot price trends as inflection indicators for capacity expansion decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic SiC Epitaxy Capacity Buildout | METI-matched funds in Kyushu reduce import dependency for critical substrate materials. |
| JIS Certification Pipeline Investment | Eighteen-month qualification timelines exclude non-domestic competitors from tier-one automotive procurement. |
| Long-term Wafer Allocation Agreements | Three-to-five-year supply locks secure substrate access amid limited US-European ingot sources. |
| Industrial Retrofit Application Engineering | Legacy equipment compatibility opens Tohoku and Shikoku maintenance markets for wide-bandgap upgrades. |
| Automotive Tier-One Supply Chain Proximity | Hiroshima and Aichi Prefecture OEM adjacency accelerates traction inverter platform design-ins. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with power semiconductor procurement managers at tier-one automotive suppliers, epitaxy facility operations directors in Kyushu, industrial equipment maintenance heads across Tohoku, and METI industrial strategy officials. Secondary validation drew from Japan Electronics and Information Technology Industries Association reports, METI subsidy disbursement disclosures, JIS standard publication records, and customs import data for six-inch SiC wafer flows. Bottom-up component demand modeling and top-down semiconductor market sizing were triangulated to converge volume estimates.
Data-stream reconciliation across the analysis window combined historical production capacity tracking with forward-looking OEM platform electrification timelines. Segmentation dimensions modeled include rectifier architecture, end-use application, packaging format, material technology platform, and regional manufacturing cluster. CAGRs were derived from fitted growth curves anchored to OEM powertrain rollout schedules and METI policy implementation phases. Industry-specific forecast inputs incorporated SiC substrate supply constraints and JIS certification pipeline throughput rates.
Revisions become necessary when METI subsidy disbursement schedules shift, six-inch SiC wafer supply concentration intensifies, or automotive OEM electrification timelines accelerate beyond current platform commitments. Forecasts reflect documented assumptions regarding substrate import dependency and domestic epitaxy yield ramp rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Thin Film Transistors (TFT) Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
Temperature-Controlled Semiconductor Market
Semiconductor Devices
Dual Voltage Comparator Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
Middle East Distribution Panel Market
Semiconductor Devices
CMP Pads Market
Semiconductor Devices
COF (Chip-On-Film) Market
Semiconductor Devices
Super Junction Mosfet Market
Semiconductor Devices
Global Semiconductor Lead Frame Market
Semiconductor Devices
Topcon Solar Cell Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Solar Cell Paste Market
Semiconductor Devices
Semiconductor Memory IP Market
Semiconductor Devices
China MLCC Market
Semiconductor Devices
T-Con Board Market