
 Japan CEP Market | 2026-2036
Japan CEP Market Size, Share, and Industry Trends Forecast 2026-2036
Japan CEP Market Foresight
Modular parcel bundling is realigning buyer choice across Japan's CEP landscape, as shippers unbundle express and standard tiers to match delivery urgency with cost sensitivity. Yamato Holdings Co. Ltd leverages its TA-Q-BIN network density to sustain premium same-day coverage across metropolitan corridors. Sagawa Express Co. Ltd anchors regional freight consolidation through its intermodal hub strategy. Nippon Express Co. Ltd dominates international CEP flows with integrated customs brokerage and air cargo linkages.
Courier, express, and parcel (CEP) services encompass time-definite collection, sorting, line-haul transport, and last-mile distribution of documents and packages up to approximately 30 kilograms, operating through hub-and-spoke networks with standardized tracking protocols. Parcel Delivery commands the largest revenue pool due to persistent B2C e-commerce volumes, while Same-Day Delivery registers the fastest structural ascent as convenience retailers and meal-kit platforms tighten fulfillment windows. Automated Sorting technology concentrates capital investment, though Route Optimization software captures disproportionate margin improvement by reducing fuel expenditure and driver overtime.
METI's carbon-neutral logistics roadmap and Japan's revised Trucking Business Act enforce fleet efficiency standards and driver hour limits, compelling operators to accelerate automation or exit unprofitable rural routes. PMDA guidelines for pharmaceutical cold-chain shipments and JIS standards for package handling further segment compliance requirements across temperature-controlled and general freight categories. Stakeholders must weigh regulatory compliance costs against automation dividends when configuring network density for aging rural demographics versus concentrated urban demand.
Market Dynamics
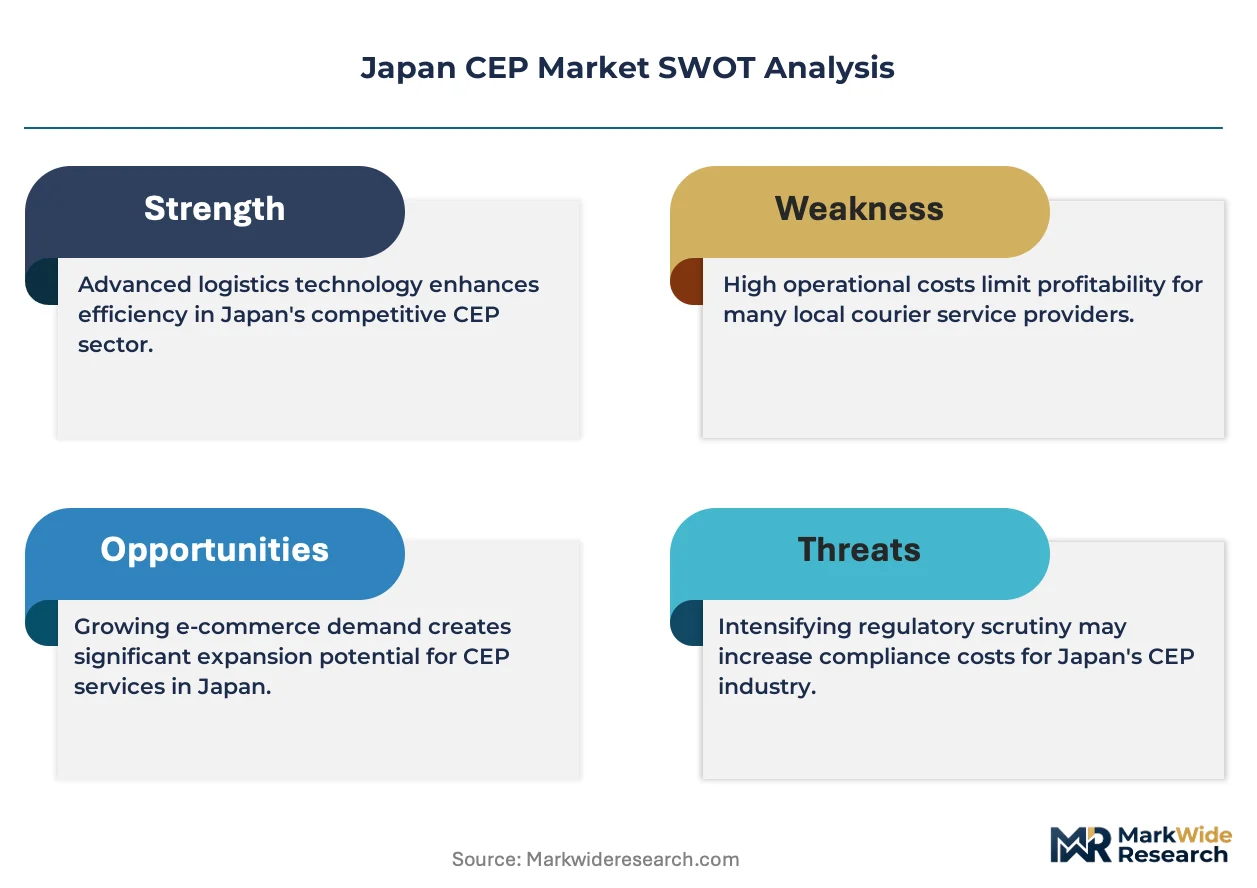
Japan's CEP sector faces a structural squeeze between METI's carbon-neutral logistics mandates and the 2024 Work Style Reform Act's driver hour limits, forcing operators to automate sorting and route optimization or abandon marginal rural corridors entirely.
Growth Catalysts
- Last-mile automation:Automated sorting systems reduce parcel handling time in Tokyo-Osaka corridors. Capital deployment concentrates in Kanto distribution centers.
- Meal-kit fulfillment:Refrigerated same-day delivery networks expand as convenience retailers tighten fulfillment windows. Cold-chain infrastructure draws fresh investment.
- METI efficiency mandates:Fleet electrification subsidies accelerate replacement of diesel vehicles in metropolitan last-mile operations. Operators capture operational cost savings.
Market Restraints
- Driver supply contraction:Japan's 2024 Work Style Reform Act caps weekly driving hours. Rural route profitability collapses under fixed cost allocation.
- Land scarcity:Tokyo-Osaka industrial real estate prices constrain hub expansion. Sorting facility footprints hit zoning limits.
- Intermodal fragmentation:Rail freight coordination gaps between JR Freight and private operators delay line-haul consolidation. Modal shift targets remain unmet.
Strategic Opportunities
- Kyushu corridor development:Fukuoka's semiconductor logistics cluster generates pharmaceutical and electronics express demand. Cold-chain infrastructure remains underbuilt.
- Pharmaceutical cold-chain:PMDA guidelines for temperature-controlled biologics shipments create compliance-premium pricing. Specialized fleet differentiation rewards early certification.
- Autonomous last-mile:Sidewalk delivery robots and drone corridors receive METI sandbox approvals. Regulatory clarity enables pilot-to-scale transitions in designated zones.
Industry Challenges
- Legacy system integration:Decades-old warehouse management systems resist API connectivity with new route optimization platforms. Middleware development consumes IT budgets.
- Skills mismatch:Maintenance technicians for automated sorting equipment remain scarce. Technical training pipelines lag hardware deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan CEP Market |
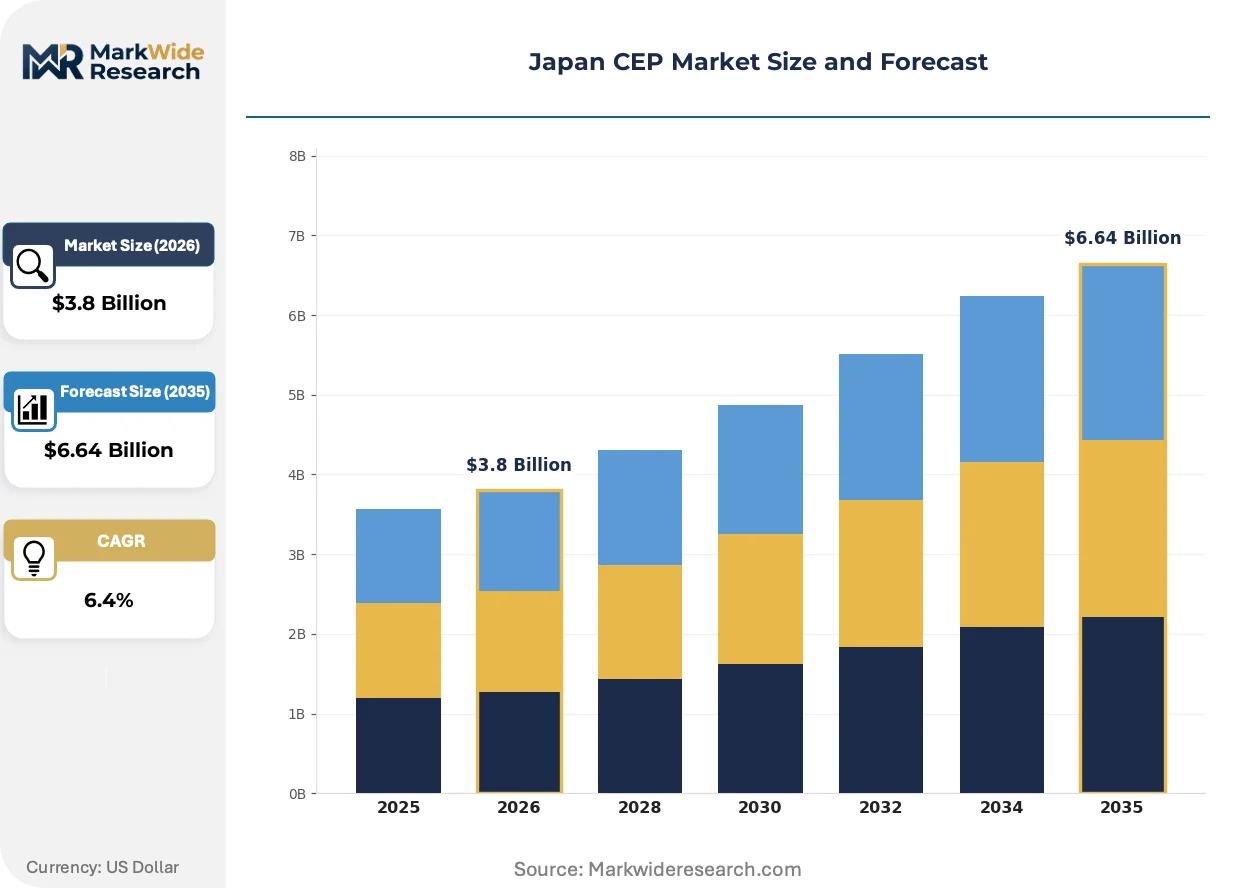
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Parcel Delivery, Freight Transport, Same-Day Delivery, Last-Mile Delivery Distribution Channel: Online Platforms, Retail Outlets, Mobile Apps, Direct Sales Customer Type: Businesses, Individuals, E-Commerce, Government Technology: Mobile Tracking, Route Optimization, Automated Sorting, Drones |
| Companies Covered | Japan Post Co. Ltd, Yamato Holdings Co. Ltd, Sagawa Express Co. Ltd, FedEx Corporation, DHL, Nippon Express Co. Ltd, Seino Transportation Co. Ltd, United Parcel Service, TNT Express, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan CEP Market Shifts & Advancements
Japan's CEP landscape is compressing delivery windows while fragmentating fulfillment origins. Three forces dominate: distributed micro-fulfillment, regulatory carbon accounting, and buyer demand for granular service tiering.
Micro-fulfillment centers are decentralizing parcel origin points across Tokyo's 23 wards and Osaka's central districts. Convenience store chains retrofit backrooms into same-day dispatch nodes. Urban delivery radii shrink from 50 kilometers to sub-10 kilometer zones, compressing line-haul requirements and amplifying hyperlocal fleet density.
METI's carbon-neutral logistics roadmap mandates Scope 3 emissions disclosure from 2025. Fleet operators must document fuel consumption per parcel-kilometer. Large e-commerce merchants now screen logistics providers on carbon intensity metrics, privileging electrified fleets in Tokyo Bay and Osaka Bay corridors where charging infrastructure concentrates.
Service unbundling reshapes buyer expectations across B2C and B2B segments. Shippers increasingly select delivery speed, time-window precision, and carbon offset as separate line items rather than bundled tiers. Subscription retailers in Kanto demand Sunday evening slots; pharmaceutical distributors prioritize temperature audit trails over speed. Procurement flexibility now separates retained contracts from spot-market relationships.
Japan CEP Market Segmentation
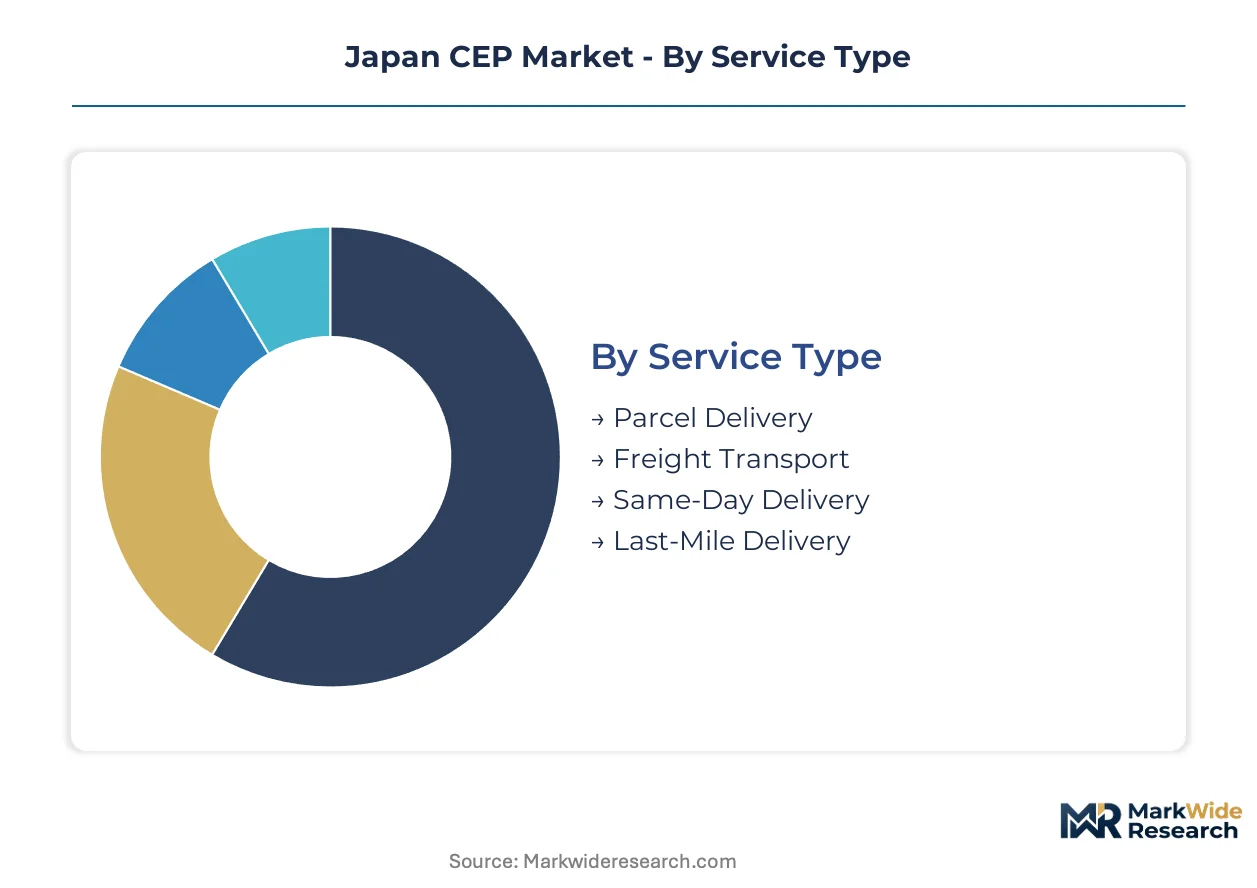
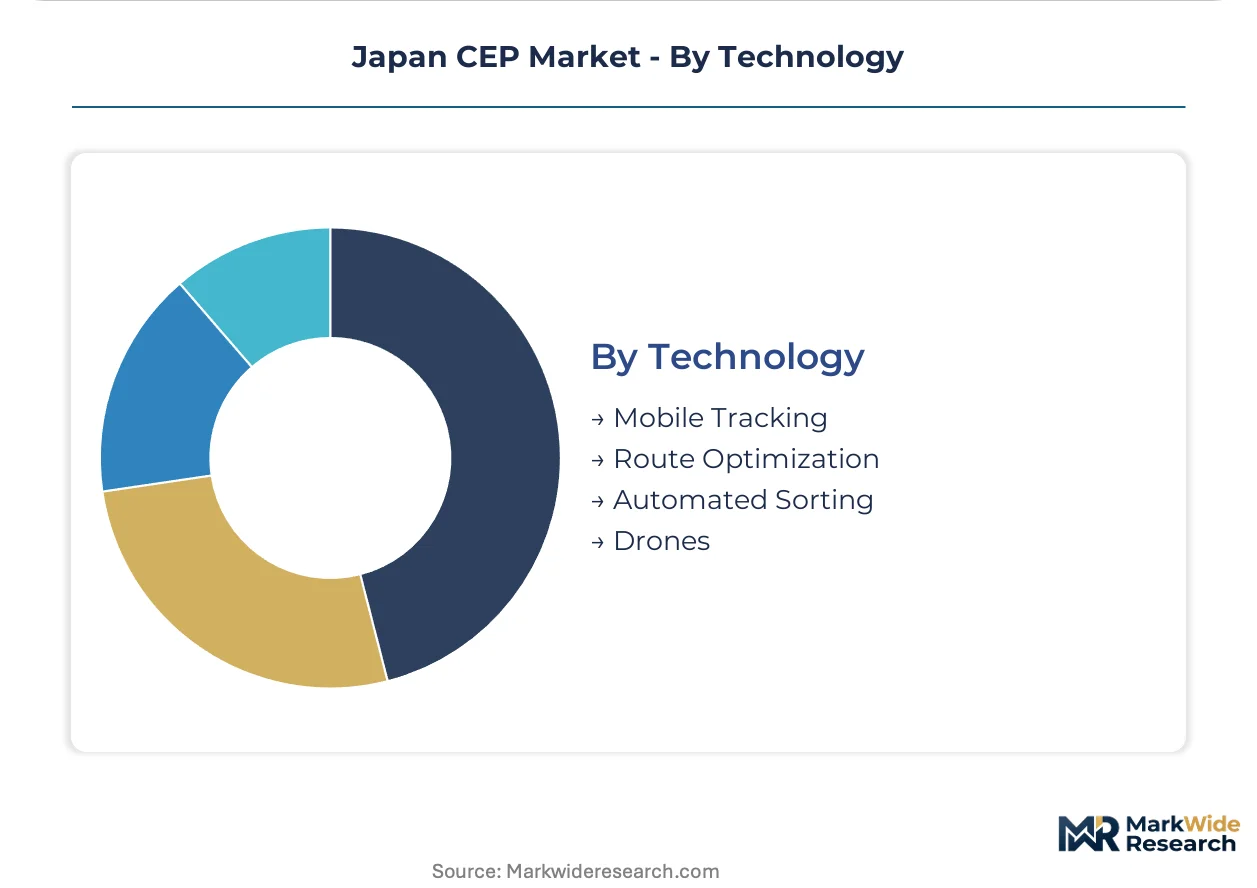
Segmentation in Japan's CEP market reflects divergent buyer priorities across delivery urgency, digital engagement, and regulatory compliance. Service tier selection now hinges on cost sensitivity versus fulfillment speed, while technology adoption separates automated metropolitan operations from labor-dependent rural networks.
Service Type:
Buyers choose service tiers based on delivery window requirements and per-shipment cost tolerance.
- Parcel Delivery:Standardized hub-and-spoke distribution handles non-urgent B2C e-commerce volumes across Kanto and Kansai corridors. Tokyo-Osaka line-haul density sustains unit economics despite METI's carbon accounting mandates.
- Same-Day Delivery:Refrigerated and ambient express networks serve meal-kit platforms and convenience retailers tightening fulfillment windows. Cold-chain infrastructure investments concentrate in Fukuoka and Sapporo where pharmaceutical demand intersects with urban density.
- Freight Transport:Consolidated palletized shipments move through intermodal hubs for B2B manufacturing supply chains.
- Last-Mile Delivery:Hyperlocal fleet deployment completes final distribution within 10-kilometer radii of micro-fulfillment nodes.
Parcel Delivery leads on scale; Same-Day Delivery leads on momentum.
Distribution Channel:
Channel selection tracks customer digital maturity and shipment frequency patterns.
- Online Platforms:Web-based booking portals aggregate volume from SME shippers seeking rate transparency. Kanto-based e-commerce merchants drive transaction density through API-integrated logistics marketplaces.
- Mobile Apps:Smartphone interfaces capture individual consumers and small retailers requiring on-demand pickup scheduling. Real-time tracking features and push notifications reduce customer service inquiries for Tokyo metropolitan operators.
- Retail Outlets:Convenience store counters serve as physical access points for cash-based transactions and returns processing.
- Direct Sales:Dedicated account teams secure enterprise contracts with pharmaceutical distributors and electronics manufacturers requiring SLA customization.
Online Platforms lead on scale; Mobile Apps lead on momentum.
Customer Type:
Customer classification determines network configuration and compliance burden allocation.
- E-Commerce:Online retailers generate parcel volume with extreme seasonality and delivery-window precision demands. Sunday evening slots and carbon-offset options now feature in procurement negotiations with Kanto-based fulfillment platforms.
- Businesses:Corporate accounts require integrated warehousing and customs brokerage for cross-border shipments. Nippon Express anchors this segment through air cargo linkages and pharmaceutical cold-chain certification.
- Individuals:Consumer senders prioritize convenience over cost, driving adoption of convenience store drop-off networks.
- Government:Public sector contracts mandate domestic supplier preferences and emissions disclosure under METI procurement guidelines.
E-Commerce leads on scale; Businesses lead on momentum.
Technology:
Technology deployment separates capital-intensive metropolitan operations from labor-dependent regional networks.
- Automated Sorting:Robotic parcel handling systems reduce processing time in Tokyo-Osaka distribution centers. Capital deployment concentrates in Kanto facilities where land scarcity drives vertical integration of sorting operations.
- Route Optimization:Algorithmic dispatch software reduces fuel expenditure and driver overtime in last-mile operations. METI's Work Style Reform Act hour limits amplify returns on dynamic routing investments.
- Mobile Tracking:GPS-enabled shipment visibility meets PMDA audit requirements for pharmaceutical cold-chain documentation.
- Drones:Autonomous aerial delivery receives METI sandbox approvals for pilot programs in designated rural zones.
Automated Sorting leads on scale; Route Optimization leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's courier, express, and parcel sector traces its modern density to Yamato Transport's 1976 launch of the TA-Q-BIN service, which established the hub-and-spoke model now replicated nationwide. Metropolitan corridors in Kanto and Kansai remain the operational core, though regulatory pressure and demographic shifts are redistributing investment toward secondary nodes.
Kanto/Tokyo
Tokyo's 23 wards generate the highest parcel density per square kilometer in Japan, driven by e-commerce fulfillment platforms and meal-kit subscription services. METI's carbon-neutral logistics roadmap mandates fleet electrification in the capital region by 2027. Automated sorting facilities concentrate in Koshigaya and Chiba Prefecture, where land scarcity has forced vertical warehouse construction.
Kansai/Osaka
Osaka anchors western Japan's CEP volume through semiconductor logistics clusters and pharmaceutical distribution networks. The 2024 Work Style Reform Act's driver hour limits hit Kansai's cross-regional line-haul routes particularly hard. Sakai City's port zone hosts expanding cold-chain infrastructure serving biologics manufacturers in Kyoto and Nara.
Kyushu
Fukuoka's semiconductor fabrication plants generate specialized express demand for temperature-controlled electronics components. PMDA guidelines for pharmaceutical shipments create compliance-premium opportunities in this corridor. Kitakyushu's logistics zone remains underbuilt relative to inbound manufacturing investment, creating facility scarcity.
Chubu/Nagoya
Nagoya's automotive supply chain sustains consolidated freight volumes for just-in-time manufacturing networks. JIS standards for package handling enforce uniform pallet dimensions across Toyota's supplier base. Hamamatsu and Shizuoka Prefecture function as intermodal transfer points between Tokyo-Osaka line-haul and regional distribution.
Hokkaido
Sapporo's isolation drives premium pricing for time-definite delivery services to northern agricultural and seafood exporters. METI subsidies for rural route automation offset profitability challenges from sparse population density. Asahikawa and Hakodate serve as secondary sorting nodes with limited same-day coverage.
Japan CEP Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service tier differentiation, with same-day refrigerated delivery commanding structural price premiums over standard parcel ground. The market exhibits consolidated metropolitan density alongside fragmented rural coverage, where smaller operators retain niche route knowledge. Three archetypes dominate: integrated express networks with owned sorting infrastructure, intermodal freight consolidators leveraging rail partnerships, and international forwarders with customs brokerage integration. Competitive moves center on automated sorting capital deployment and strategic partnerships with convenience retail chains for micro-fulfillment node access.
Within the integrated domestic network tier, Yamato Holdings Co. Ltd and Sagawa Express Co. Ltd occupy positions shaped by decades of hub-and-spoke investment in Kanto and Kansai corridors. Nippon Express Co. Ltd exemplifies the international-forwarder archetype, anchoring cross-border CEP flows through air cargo linkages. These three entities collectively represent the structural spectrum from last-mile density to customs-integrated global reach, with each archetype facing distinct pressure from METI efficiency mandates and the Work Style Reform Act's operational constraints.
| Leading Market Players |
|---|
| Japan Post Co. Ltd |
| Yamato Holdings Co. Ltd |
| Sagawa Express Co. Ltd |
| FedEx Corporation |
| DHL |
| Nippon Express Co. Ltd |
| Seino Transportation Co. Ltd |
| United Parcel Service |
| TNT Express |
| Others |
Supply & Pricing Matrix
Diesel fuel expenditure cascades through Japan's CEP pricing architecture, compressing margins in rural line-haul operations while METI electrification subsidies subsidize metropolitan fleet renewal. This cost asymmetry stratifies service tiers, with same-day premiums widening against standard parcel rates as operators recover capital deployment in Kanto's automated corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates buyer choice, with certification grade for pharmaceutical cold-chain and volume scale for e-commerce subscriptions driving differentiation. Pricing pressure stems from METI's carbon accounting mandates forcing fleet investment, while cost compression in rural standard parcel tiers reflects driver hour limits under the Work Style Reform Act. SME e-commerce merchants exhibit highest price sensitivity; pharmaceutical distributors prioritize temperature audit trails over per-shipment cost.
Supply Chain Analysis
METI procurement guidelines mandating domestic supplier preferences and emissions disclosure reshape sourcing decisions across fleet and facility procurement. Vehicle manufacturing draws from Japan, South Korea, and Germany; sorting equipment and telematics systems source from China, Taiwan, and the United States. Single-source vulnerability concentrates in semiconductor components for route optimization hardware. Distribution runs through hub-and-spoke networks anchored by Kanto and Kansai sorting facilities, with last-mile radii contracting around micro-fulfillment nodes in Tokyo's 23 wards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's CEP market represents a late-cycle quality story where premium same-day and pharmaceutical cold-chain specifications capture disproportionate margin expansion. Buyer procurement now weights carbon intensity metrics and temperature compliance above pure cost minimization.
For Market Incumbents: To counter driver supply contraction under the 2024 Work Style Reform Act, accelerate automated sorting deployment in Koshigaya and Chiba Prefecture distribution centers. Secure backward integration into charging infrastructure through METI subsidy programs. Prioritize PMDA cold-chain certification investment to defend pharmaceutical contract retention against specialized entrants. For New Entrants and Emerging Players: Convenience store chains represent the most accessible channel partner type for micro-fulfillment node deployment in underserved Kyushu corridors. Target Fukuoka's semiconductor logistics cluster where cold-chain infrastructure remains underbuilt relative to inbound manufacturing investment. Pursue METI sandbox approvals for autonomous last-mile pilots as a regulatory-first go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where rural route profitability collapses under fixed cost allocation and aging demographics. Long-term viability favors operators with automated metropolitan density and pharmaceutical compliance certification. The signal to watch is METI fleet electrification subsidy renewal rates as an inflection indicator for capital deployment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sorting Deployment | Reduces parcel handling time in Tokyo-Osaka corridors where labor scarcity intensifies. |
| Cold-Chain Infrastructure Expansion | Captures pharmaceutical compliance-premium pricing under PMDA temperature-control guidelines. |
| Micro-Fulfillment Network Densification | Compresses last-mile radii to sub-10 kilometer zones for meal-kit and convenience retail fulfillment. |
| Fleet Electrification Partnership | Secures METI subsidy capture and carbon-intensity screening preference from large e-commerce merchants. |
| Route Optimization Platform Integration | Reduces fuel expenditure and driver overtime amid Work Style Reform Act hour limits. |
Research Methodology
Multiple input streams — executive interviews with logistics operations directors, fleet procurement managers, and pharmaceutical supply chain leads; secondary validation through METI regulatory filings, JR Freight modal data, and customs trade statistics; plus bottom-up and top-down triangulation — were reconciled to construct market estimates. Primary fieldwork captured operator perspectives on automation deployment timelines and regulatory compliance costs. Secondary sources included PMDA pharmaceutical distribution guidelines, JIS packaging standards documentation, and e-commerce merchant procurement survey data.
Historical volume trajectories were cross-referenced against panel input from distribution center operators and convenience retail logistics heads to anchor projection assumptions across the analysis window. Segmentation modeling incorporated service tier urgency, distribution channel digital maturity, customer type compliance burden, and technology deployment intensity. CAGRs derived from trend extrapolation moderated by regulatory enforcement timelines and capital investment cycle visibility. Forecast inputs included METI electrification subsidy allocation trajectories and Work Style Reform Act enforcement phase-ins.
Revisions become necessary when METI carbon-neutral logistics mandate enforcement intensifies, PMDA cold-chain guideline scope expands, or autonomous delivery sandbox approvals accelerate beyond pilot parameters. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Silicon Carbide Semiconductor Devices Market
Semiconductor Devices
DNA Chip Market
Semiconductor Devices
Global Bipolar Power Transistor Market
Semiconductor Devices
North America Silicon Carbide Wafers Market
Semiconductor Devices
Polymer Core Solder Ball Market
Semiconductor Devices
Japan Semiconductor Device Market
Semiconductor Devices
Americas Microcontroller (MCU) Market
Semiconductor Devices
Thick Film Devices Market
Semiconductor Devices
Americas Power Transistor Market
Semiconductor Devices
Amorphous-Semiconductor Devices Market
Semiconductor Devices
Coated Silicon Wafer Market
Semiconductor Devices
Silicon on Insulator Market
Semiconductor Devices
Global Trench Gate Power MOSFET Market
Semiconductor Devices
Hybrid Microcircuits Market
Semiconductor Devices
Transistor Arrays Market
Semiconductor Devices
Temperature-Controlled Semiconductor Market