
 Europe Ultra-Low-Power Microcontroller Market | 2026-2036
Europe Ultra-Low-Power Microcontroller Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ultra-Low-Power Microcontroller Market Foresight
Germany is fragmenting its ultra-low-power microcontroller supply base across multiple foundry partnerships and fabless design houses. Infineon Technologies AG leverages its Dresden manufacturing complex to sustain captive production of automotive-grade MCUs with sub-microamp sleep currents. NXP Semiconductors anchors its Eindhoven design centers with deep expertise in secure connectivity protocols for industrial gateways. STMicroelectronics competes through its Grenoble R&D campus, specializing in energy harvesting integration for distributed sensor networks.
Ultra-low-power microcontrollers are 16-bit and 32-bit embedded processors engineered to operate below one milliwatt in active mode and sub-microamp levels during sleep, fabricated on specialized low-leakage process nodes for extended battery life in untethered applications. Their primary purpose is deterministic control of wearable devices, IoT endpoints, and automotive body electronics where energy budgets are constrained by limited power sources. The 32-bit Microcontrollers segment leads value generation as edge AI inference and wireless protocol stacks demand higher arithmetic throughput. Energy Harvesting technology represents the fastest-growing architecture category, enabling perpetual operation from ambient thermal, vibrational, or photovoltaic sources without battery replacement cycles.
EMA medical device directives and CE marking requirements under the EU MDR shape validation timelines for healthcare-grade MCUs, while REACH chemical restrictions and RoHS substance limits constrain die-attach materials and molding compounds used in European-bound packages. The EU AI Act introduces conformity assessment obligations for MCUs deployed in safety-critical autonomous systems, tightening traceability across semiconductor supply chains. Stakeholders must monitor how ECHA substance-of-very-high-concern listings will restrict gallium arsenide and fluorinated polymer availability in advanced packaging processes.
Market Dynamics
REACH substance restrictions and RoHS material bans are forcing European MCU suppliers to requalify die-attach compounds and molding resins, compressing design cycles while elevating qualification costs for healthcare and automotive certifications.
Growth Catalysts
- EU MDR compliance mandates:CE marking requirements for medical devices are accelerating design-in of healthcare-grade MCUs with traceable supply chains across German and French diagnostic equipment manufacturers.
- Energy harvesting integration:Ambient power capture from thermal gradients and photovoltaic cells is eliminating battery replacement cycles in Dutch agricultural sensor networks and Nordic industrial monitoring.
- Germany:Automotive OEMs in Bavaria and Baden-Württemberg are specifying sub-microamp sleep currents for body electronics modules, anchoring continental demand for automotive-grade ultra-low-power architectures.
Market Restraints
- Advanced packaging material scarcity:ECHA listings of substances-of-very-high-concern are restricting gallium arsenide and fluorinated polymer availability, elevating costs for high-reliability European-bound packages.
- Foundry concentration risk:Leading-edge low-leakage process nodes depend on a concentrated Asian foundry base, exposing European fabless designers to geopolitical supply disruptions and allocation constraints.
- Silicon carbide controller substitution:Power management ICs with integrated MCU cores are displacing discrete ultra-low-power units in high-voltage industrial motor control applications.
Strategic Opportunities
- Poland and Czechia:Industrial automation clusters in Central Europe remain underpenetrated for battery-operated wireless sensor nodes, offering first-mover advantages for localized distribution partnerships.
- EU AI Act conformity assessment:Safety-critical autonomous system mandates are creating certified-MCU demand for traceable edge inference in French and German automotive programs.
- Secure element convergence:Integration of hardware security modules with ultra-low-power cores is opening payment-token and identity-authentication sockets previously served by discrete secure MCUs.
Industry Challenges
- Mixed-signal verification expertise:European semiconductor employers face acute shortages of engineers proficient in sub-threshold analog design and radio-frequency co-simulation for energy-harvesting architectures.
- EMA validation timelines:Medical device directive compliance cycles extend 18-24 months for healthcare-grade MCUs, compressing product refresh windows against faster-moving consumer IoT segments.
- Legacy industrial protocol integration:Fieldbus and industrial Ethernet stacks require certified software stacks that strain code memory budgets on sub-64KB flash devices, forcing difficult performance-cost tradeoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ultra-Low-Power Microcontroller Market |
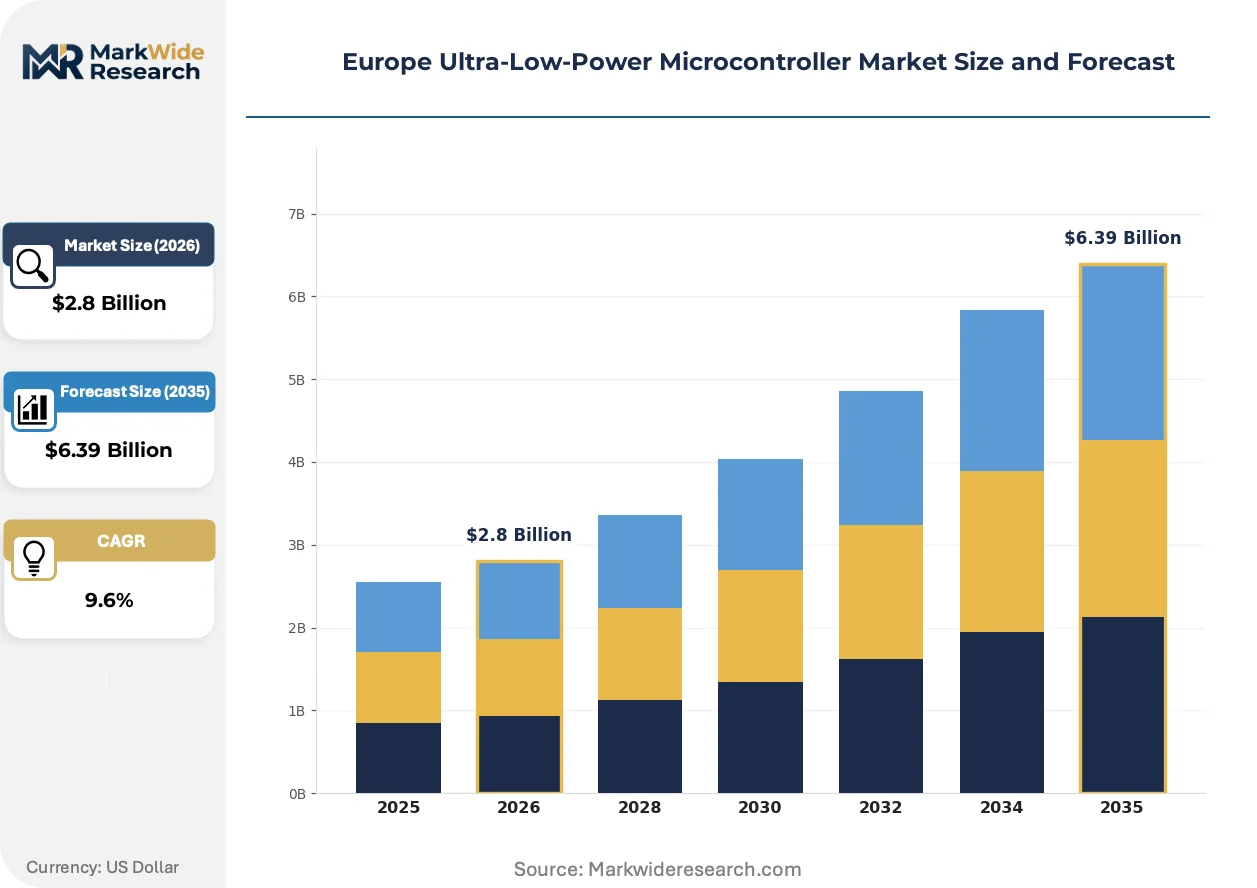
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.39 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 16-bit Microcontrollers, 32-bit Microcontrollers, Analog Microcontrollers, Digital Microcontrollers End User: Consumer Electronics, Industrial Automation, Healthcare Devices, Smart Home Applications Technology: Embedded Connectivity, Energy Harvesting, Digital Signal Processing, Real-Time Processing Application: Wearable Devices, IoT Solutions, Home Appliances, Automotive Systems |
| Companies Covered | Infineon Technologies AG, NXP Semiconductors, STMicroelectronics, Microchip Technology Inc., Texas Instruments Incorporated, Analog Devices, Inc., Renesas Electronics Corporation, Silicon Laboratories, Ambiq Micro, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ultra-Low-Power Microcontroller Market Shifts & Advancements
Digital twin methodologies are virtualizing hardware verification workflows, compressing development cycles while regulatory pressure intensifies around material traceability and AI-enabled safety systems.
Sub-threshold digital design is virtualizing traditional voltage scaling approaches by operating logic gates below transistor threshold voltages. German automotive suppliers are adopting these techniques for always-on body electronics. This architecture is virtualizing the power-performance tradeoff that previously forced discrete PMIC-MCU partitioning.
REACH chemical restrictions are tightening purity standards for semiconductor molding compounds and die-attach materials. ECHA substance-of-very-high-concern listings now cover critical packaging chemistries. Medical device and automotive segments are responding with dual-sourcing strategies and accelerated qualification of alternative material sets.
Buyers are consolidating procurement around vertically integrated suppliers offering combined silicon, wireless stacks, and security certification. Industrial automation OEMs in Germany and France are displacing multi-vendor sourcing with single-source platform contracts. This concentration is most visible in Bavaria, where automotive tier-ones are bundling MCU, transceiver, and antenna tuning under unified supplier accountability.
Europe Ultra-Low-Power Microcontroller Market Segmentation
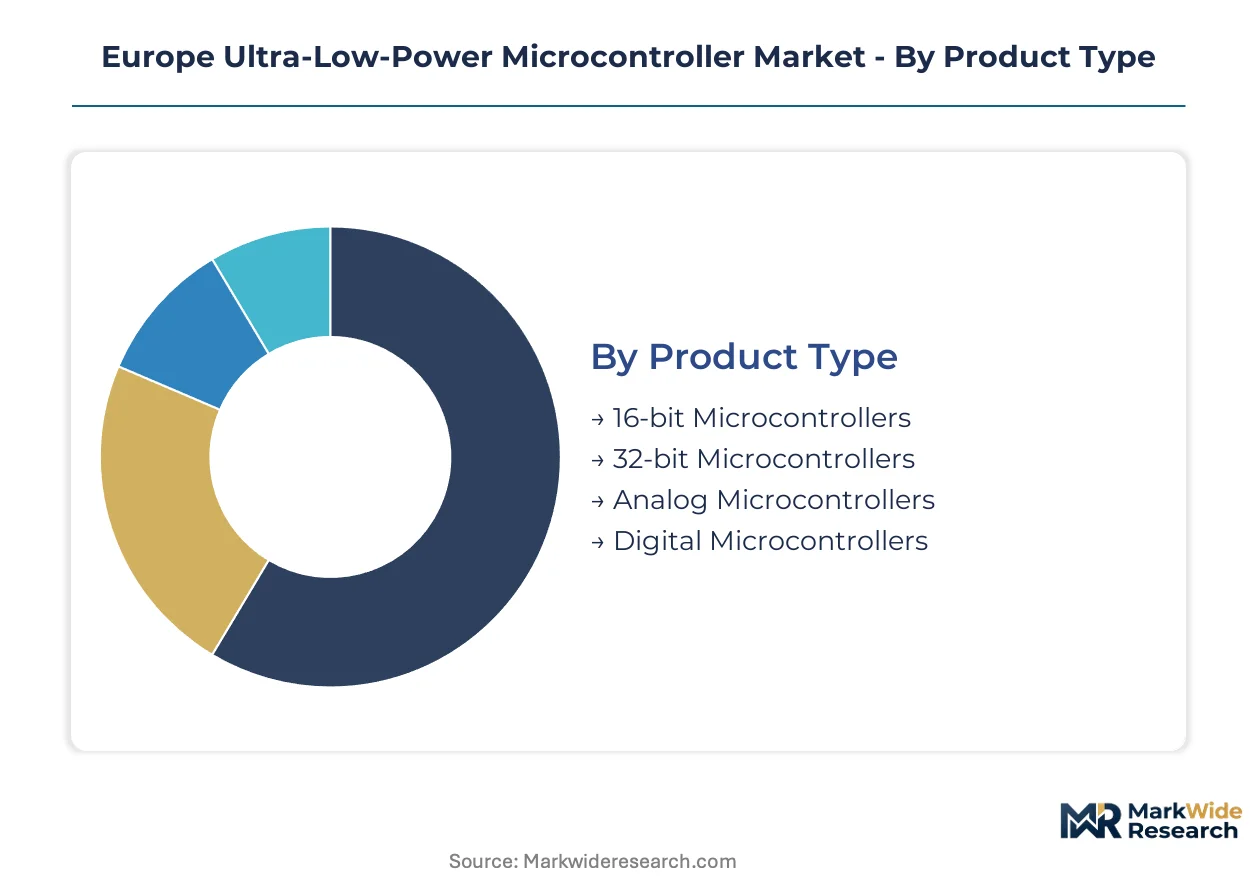
Ultra-low-power microcontroller procurement cycles vary dramatically across segments, with consumer wearables demanding 12-18 month refresh rates while automotive platforms lock specifications for 5-7 years. Understanding these divergent rhythms shapes inventory strategy and R&D prioritization for European suppliers competing across multiple verticals simultaneously.
Product Type:
Cycle times stretch from rapid consumer turnover in 16-bit devices to decade-long automotive qualification windows for advanced 32-bit architectures with functional safety certification.
- 32-bit Microcontrollers:These architectures integrate ARM Cortex-M series cores with sub-microamp sleep states and hardware-accelerated cryptography for edge AI inference. Bavarian automotive tier-ones are specifying these for body electronics modules where deterministic response meets stringent energy budgets. EU AI Act traceability requirements are accelerating design-in of certified 32-bit platforms with documented supply chain provenance.
- 16-bit Microcontrollers:Simpler instruction sets and smaller die footprints deliver cost-optimized control for disposable medical sensors and single-purpose industrial monitors. French diagnostic equipment manufacturers favor these for battery-operated glucose meters where code memory requirements stay below 64KB and unit economics dominate technical sophistication.
- Analog Microcontrollers:Mixed-signal integration combines precision ADCs with digital control cores for sensor interface applications in Dutch agricultural monitoring networks.
- Digital Microcontrollers:Pure digital architectures optimize logic density for protocol conversion gateways in Polish industrial automation clusters.
32-bit Microcontrollers dominate installed base value. 16-bit Microcontrollers is where expansion concentrates in cost-sensitive healthcare and consumer tiers.
End User:
Customer concentration patterns split between fragmented consumer procurement and consolidated industrial contracts with multi-year volume commitments.
- Industrial Automation:Battery-operated wireless sensor nodes for predictive maintenance command premium pricing when bundled with certified software stacks and decade-long supply guarantees. German machinery OEMs in Baden-Württemberg are consolidating procurement around single-source platform contracts that combine MCU, wireless transceiver, and antenna tuning under unified supplier accountability.
- Healthcare Devices:EMA medical device directives and EU MDR CE marking requirements impose 18-24 month validation timelines that compress product refresh windows against faster-moving consumer segments. Diagnostic equipment manufacturers in France and Germany demand traceable supply chains with documented REACH compliance for all packaging materials.
- Consumer Electronics:Wearable and hearable devices in Nordic markets drive volume but squeeze margins through annual specification churn and aggressive cost targets.
- Smart Home Applications:Energy management controllers and security sensors in Netherlands and Belgium residential construction favor interoperable wireless protocols over proprietary architectures.
Industrial Automation commands the highest unit margins and longest contract durations. Healthcare Devices is climbing the fastest as EU MDR compliance mandates accelerate certified-MCU procurement.
Technology:
Architecture differentiation centers on power source independence versus connectivity integration, with divergent investment requirements for analog design expertise.
- Energy Harvesting:Ambient power capture from thermal gradients, piezoelectric vibration, and indoor photovoltaic cells eliminates battery replacement cycles entirely. Dutch agricultural sensor networks and Nordic industrial monitoring deployments are adopting these architectures for perpetual operation in remote locations where maintenance access is prohibitively expensive.
- Embedded Connectivity:Integrated radio cores for Bluetooth Low Energy, Thread, and proprietary sub-GHz protocols reduce bill-of-materials complexity for wireless endpoints. German smart building contractors favor pre-certified wireless MCU modules to accelerate commissioning timelines and reduce RF regulatory testing burdens.
- Digital Signal Processing:Hardware multiply-accumulate units accelerate sensor fusion algorithms for industrial vibration analysis in Czech manufacturing plants.
- Real-Time Processing:Deterministic interrupt latency guarantees meet automotive functional safety requirements for Bavarian powertrain control modules.
Embedded Connectivity dominates current shipment volumes. Energy Harvesting is gaining share fastest as perpetual operation eliminates battery logistics costs in distributed deployments.
Application:
End-use requirements fragment across extreme miniaturization pressures in wearables versus electromagnetic compatibility demands in automotive environments.
- Wearable Devices:Sub-milliwatt active power consumption and sub-microamp sleep states enable multi-day operation from coin cell batteries in fitness trackers and medical patches. French and German consumer health brands are driving integration of biometric sensing front-ends with ultra-low-power processing cores to reduce PCB area in wrist-worn form factors.
- Automotive Systems:Body electronics modules for door control, seat adjustment, and climate interfaces require automotive-grade temperature ranges and AEC-Q100 qualification. Bavarian and Baden-Württemberg OEMs specify sub-microamp sleep currents to preserve vehicle battery charge during extended parking periods.
- IoT Solutions:Distributed environmental and asset tracking sensors in Polish logistics networks prioritize wireless range over processing throughput.
- Home Appliances:Motor control and user interface modules in Italian white goods manufacturing favor proven 8-bit migration paths to minimize firmware redevelopment costs.
Automotive Systems anchors the highest reliability premiums and longest design-in cycles. Wearable Devices is expanding most quickly as health monitoring integration accelerates across European consumer markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European ultra-low-power microcontroller supply chains concentrate manufacturing and design expertise across a concentrated corridor stretching from Dresden to Grenoble. Foundry partnerships and captive production facilities anchor continental capacity, while regulatory compliance requirements fragment procurement patterns across national markets.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify sub-microamp sleep currents for body electronics modules, driving specification-setting authority for continental design-in volumes. KBA vehicle-type approval requirements and EU AI Act conformity assessments tighten traceability obligations for safety-critical autonomous systems. The Dresden manufacturing complex sustains captive production of automotive-grade MCUs with extended temperature ranges.
France
Diagnostic equipment manufacturers in Île-de-France and Auvergne-Rhône-Alpes demand healthcare-grade MCUs with documented REACH compliance for all packaging materials. EMA medical device directives and EU MDR CE marking requirements impose 18-24 month validation timelines that compress product refresh windows. The Grenoble R&D campus anchors energy harvesting integration expertise for distributed sensor networks.
Netherlands
Dutch agricultural sensor networks and smart building contractors drive adoption of energy harvesting architectures and pre-certified wireless MCU modules. REACH substance restrictions constrain die-attach compounds and molding resins, elevating qualification costs for high-reliability packages. Eindhoven design centers anchor secure connectivity protocol expertise for industrial gateways.
Poland
Industrial automation clusters in Polish manufacturing plants remain underpenetrated for battery-operated wireless sensor nodes, offering first-mover advantages for localized distribution partnerships. RoHS material bans force requalification of alternative material sets for European-bound semiconductor packages. Logistics networks in Polish distribution hubs prioritize wireless range over processing throughput for environmental and asset tracking sensors.
Czechia
Czech manufacturing plants deploy digital signal processing architectures for industrial vibration analysis and predictive maintenance applications. ECHA substance-of-very-high-concern listings restrict gallium arsenide availability, elevating costs for advanced packaging processes. Industrial automation OEMs consolidate procurement around single-source platform contracts combining MCU, wireless transceiver, and antenna tuning.
Europe Ultra-Low-Power Microcontroller Market Competitive Landscape
Vertically integrated semiconductor conglomerates and specialized fabless design houses split the market across divergent capital intensity models. Captive foundry operations anchor supply security for automotive-grade volumes, while fabless competitors access leading-edge low-leakage process nodes through concentrated Asian foundry partnerships. Two strategic archetypes dominate: diversified semiconductor conglomerates with in-house fabrication, and connectivity-focused specialists leveraging external manufacturing. Competitive moves concentrate on secure element convergence and energy harvesting integration.
Among diversified European semiconductor conglomerates, Infineon Technologies AG, NXP Semiconductors, and STMicroelectronics exemplify the vertically integrated archetype with captive manufacturing and design center networks spanning the continent. These entities occupy positions shaped by regional regulatory compliance requirements, with each representing distinct geographic concentrations of automotive, industrial, and healthcare design-in expertise.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| NXP Semiconductors |
| STMicroelectronics |
| Microchip Technology Inc. |
| Texas Instruments Incorporated |
| Analog Devices, Inc. |
| Renesas Electronics Corporation |
| Silicon Laboratories |
| Ambiq Micro, Inc. |
| Others |
Supply & Pricing Matrix
The Rotterdam-Antwerp semiconductor logistics corridor anchors continental distribution costs, compressing margins for fabless designers while amplifying pricing power for vertically integrated suppliers with captive European fabrication. REACH compliance burdens and foundry concentration in East Asia feed downstream price differentiation across certification tiers and supply security guarantees.
Pricing Analysis
REACH and RoHS substance restrictions dictate the pricing tier structure across automotive, healthcare, and industrial segments. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 certified automotive-grade units with full traceability from industrial-tier devices with basic CE marking and cost-optimized consumer variants. Cost compression in the economy tier is intensifying because foundry allocation constraints force smaller fabless designers to accept spot-market wafer pricing. Industrial automation OEMs in Germany exhibit the lowest price sensitivity due to decade-long supply guarantees, while Nordic consumer wearable brands drive the hardest unit-cost negotiations.
Supply Chain Analysis
Foundry concentration risk between Taiwan and South Korea dominates supply-side vulnerability for European ultra-low-power microcontroller procurement. Leading-edge low-leakage process nodes draw from Taiwanese foundry complexes, while South Korean memory-integrated logic suppliers anchor embedded flash architectures. Silicon carbide substrates and gallium arsenide packaging materials face ECHA substance-of-very-high-concern restrictions, elevating single-source vulnerability for high-reliability medical and automotive packages. Distribution runs through authorized distributors with regional inventory hubs in Germany and the Netherlands, supplemented by direct OEM contracts for high-volume automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around REACH compliance and EU MDR certification creates formidable defensive moats for established suppliers, as 18-24 month requalification timelines deter customer switching.
For Market Incumbents: Entrench market position through backward integration into specialized low-leakage process development at Dresden and Grenoble R&D campuses, while locking in decade-long supply agreements with Bavarian automotive tier-ones. Secure element convergence represents a critical threat from connectivity-focused specialists; counter by accelerating hardware security module integration with ultra-low-power cores. Certification investment in EU AI Act conformity assessment capabilities anchors pricing power in safety-critical autonomous systems. For New Entrants and Emerging Players: Mid-market industrial automation clusters in Poland and Czechia represent the most penetrable entry point, as German and French OEMs consolidate procurement around incumbent platforms. Battery-operated wireless sensor nodes for predictive maintenance in Central European manufacturing plants offer first-mover advantages before single-source platform contracts solidify. A go-to-market angle through pre-certified wireless MCU modules with integrated antenna tuning reduces RF regulatory barriers for smart building contractors in the Netherlands. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant semiconductor divisions possessing legacy foundry relationships or secure element IP. Long-term viability hinges on regulatory compliance capabilities rather than pure cost optimization, favoring targets with established EMA and KBA qualification track records. Watch for inflection in ECHA substance-of-very-high-concern listing announcements affecting gallium arsenide and fluorinated polymer availability, which would accelerate consolidation around suppliers with qualified alternative material sets.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Convergence | Hardware security module integration opens payment-token and identity-authentication sockets in French and German financial infrastructure. |
| Energy Harvesting Integration | Ambient power capture eliminates battery logistics costs for Dutch agricultural sensor networks and Nordic industrial monitoring deployments. |
| EU AI Act Certification | Conformity assessment obligations create certified-MCU demand for traceable edge inference in Bavarian automotive programs. |
| Central European Distribution Partnerships | Localized presence in Poland and Czechia secures first-mover positioning in underpenetrated industrial automation clusters. |
| Alternative Material Qualification | Dual-sourcing strategies for REACH-compliant die-attach compounds reduce ECHA restriction exposure in medical device packaging. |
Research Methodology
The analysis maps 32-bit automotive-grade architectures, 16-bit healthcare-optimized devices, energy harvesting integration platforms, and embedded connectivity modules, each validated through semiconductor procurement executives at German automotive tier-ones, French diagnostic equipment manufacturers, and Dutch agricultural sensor network operators. Primary fieldwork combined structured interviews with biomedical engineers specifying healthcare-grade MCUs and industrial automation plant engineers deploying battery-operated sensor nodes. Secondary validation drew from SEC 10-K filings of listed semiconductor suppliers, ECHA substance-of-very-high-concern registry updates, EU MDR CE marking databases, and KBA vehicle-type approval records. Bottom-up unit shipment estimates triangulated against top-down semiconductor wafer demand projections.
Assumptions around REACH substance restriction timelines and EU AI Act implementation phases were held fixed across base-case scenarios, while foundry capacity expansion trajectories and silicon carbide controller substitution rates were stress-tested in sensitivity analysis. Segmentation dimensions modeled include bit-width architecture, end-use vertical, power source technology, and geographic regulatory cluster. CAGRs were derived from fitted growth curves anchored to validated base-year estimates and forward-looking design-in pipeline data from European OEM procurement systems. Forecast inputs incorporated EMA medical device directive validation cycle durations and automotive platform lock-in periods.
Macroeconomic conditions sit as an overlay; deviation in eurozone industrial production indices and automotive capital expenditure cycles would shift the trajectory of ultra-low-power microcontroller demand. Forecasts reflect documented assumptions around regulatory implementation timelines and foundry capacity allocation priorities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Automotive Grade Emmc Market
Semiconductor Devices
Hairpin Stator Market
Semiconductor Devices
Japan MLCC Market
Semiconductor Devices
Middle East and Africa Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Topcon Solar Cell Market
Semiconductor Devices
Silicon Epitaxial Wafer Market
Semiconductor Devices
Coated Silicon Wafer Market
Semiconductor Devices
Global Probe Card Market
Semiconductor Devices
3D TSV Device Market
Semiconductor Devices
Digital Tunable Capacitors Market
Semiconductor Devices
Ferroelectric FET Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
Global Thermoelectric Modules Market
Semiconductor Devices
Leadframes Market
Semiconductor Devices
Leap Engine Market
Semiconductor Devices
Global Small Signal Transistor Market