
 Global 8 - Bit Microcontroller Market | 2026-2036
Global 8 - Bit Microcontroller Market Size, Share, and Industry Trends Forecast 2026-2036
Global 8 - Bit Microcontroller Market Foresight
Edge computing migration toward distributed sensor nodes is reshaping how OEMs architect low-power embedded systems. Microchip Technology leverages its vertically integrated fabrication footprint to dominate general-purpose 8-bit portfolios. STMicroelectronics anchors European automotive supply chains through AEC-Q100-qualified product lines. Texas Instruments competes on analog-digital integration density within single-chip 8-bit architectures.
An 8-bit microcontroller integrates an 8-bit central processing unit with onboard program memory, data RAM, and configurable peripherals such as timers, ADCs, and UART interfaces on a single silicon die. These devices execute control-oriented tasks in resource-constrained environments where die cost, power draw, and code footprint must stay minimal. Automotive grade and industrial control segments lead absolute revenue contribution due to extended temperature-range requirements and multi-year qualification cycles. Flash memory technology displaces legacy ROM and UV-EPROM architectures across new designs because field reprogrammability reduces inventory risk for OEMs. Home automation and smart metering applications represent the fastest-growing demand pools as utilities and building operators deploy cost-optimized sensing endpoints.
FDA device classification rules in the United States and EU MDR conformity requirements in Europe shape design documentation and traceability obligations for 8-bit controllers deployed in medical devices. China's GB standards and MIIT certification protocols govern electromagnetic compatibility testing for consumer electronics implementations. RoHS substance restrictions across both European and North American jurisdictions constrain leadframe plating chemistries and solder joint metallurgy. Stakeholders must monitor how automotive functional safety standards evolve to determine whether 8-bit architectures retain sufficient diagnostic coverage for next-generation body electronics or cede position to 32-bit alternatives.
Market Dynamics
Flash memory reprogrammability has become the dominant architectural force restructuring 8-bit microcontroller procurement, as OEMs eliminate mask-ROM inventory exposure and demand field-upgradable firmware across automotive body electronics and industrial sensor networks.
Growth Catalysts
- Automotive body module expansion:Tier-1 suppliers in Germany, Japan, and the United States are qualifying 8-bit controllers for door control units, seat modules, and climate interfaces where cost sensitivity exceeds processing demands.
- REACH substance compliance:European chemical registration requirements are accelerating lead-free plating transitions across Asian semiconductor packaging houses, creating specification pull-through for RoHS-aligned 8-bit product lines.
- Pearl River Delta concentration:China's electronics manufacturing cluster generates concentrated demand for cost-optimized 8-bit units in white goods controllers, smart meter subassemblies, and toy electronics.
Market Restraints
- Copper and gold input volatility:Bond wire and leadframe plating materials expose margins to London Metal Exchange price swings that contract manufacturers cannot fully pass through.
- Foundry concentration in Taiwan:Mature-node 8-bit fabrication relies on a narrow supplier base for 180nm and larger geometries, creating geographic supply risk.
- 32-bit ARM Cortex-M0 substitution:Sub-dollar 32-bit alternatives are eroding 8-bit sockets in applications requiring future firmware scalability or networking stacks.
Strategic Opportunities
- India smart metering deployment:State electricity boards under the Ministry of Power's RDSS scheme are tendering millions of prepaid meter units specifying indigenous 8-bit controller integration.
- Capacitive touch convergence:Merging touch-sensing peripherals with 8-bit cores eliminates discrete sensor ICs in appliance panels and automotive center stacks.
- EU F-Gas Regulation phase-down:Refrigeration compressor controllers must adapt to variable-speed drive algorithms, opening 8-bit sockets for cost-optimized motor control in retrofit markets.
Industry Challenges
- AEC-Q100 qualification timelines:Automotive-grade 8-bit products require 12-18 month validation cycles that compress product refresh rates against consumer electronics design velocities.
- Legacy 5V ecosystem integration:Industrial control installations running 5V logic levels demand voltage-tolerant 8-bit variants that conflict with modern 3.3V and 1.8V process shrinks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 8 - Bit Microcontroller Market |
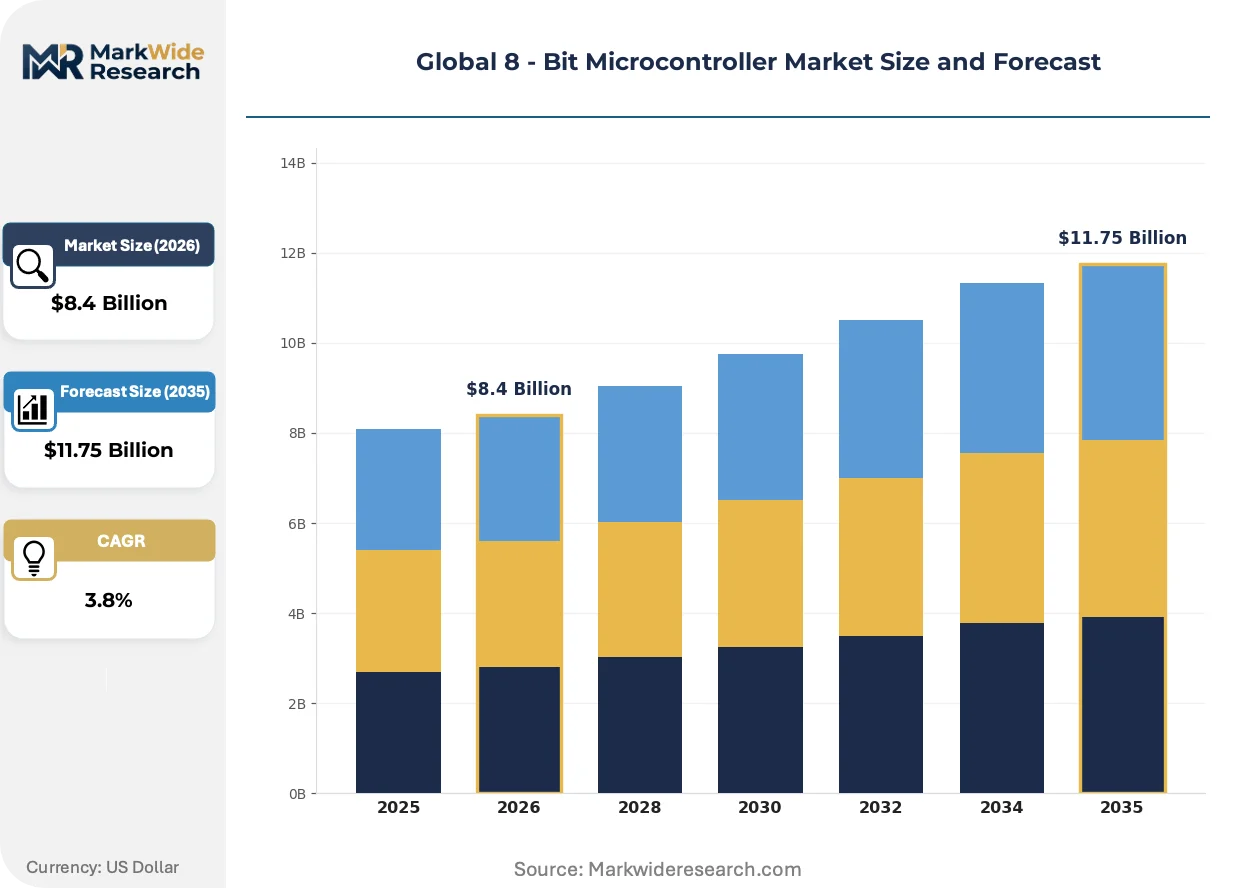
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $11.75 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Purpose, Automotive Grade, Consumer Electronics, Industrial Control, Medical Devices Technology: Flash Memory, ROM, EPROM, EEPROM, UV-EPROM Application: Home Automation, Wearable Devices, Smart Metering, Robotics, Electronic Toys, Security Systems End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, System Integrators, Embedded Systems Developers |
| Companies Covered | Microchip Technology, NXP Semiconductors, STMicroelectronics, Renesas Electronics, Infineon Technologies, Texas Instruments, Silicon Laboratories, Holtek Semiconductor, Analog Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 8 - Bit Microcontroller Market Shifts & Advancements
Peripheral integration density and analog precision are reshaping competitive differentiation as 8-bit architectures absorb functions previously requiring external discrete components.
Embedded non-volatile memory is migrating from one-time-programmable antifuse architectures toward multi-time-programmable Flash and emerging ferroelectric RAM alternatives. Appliance OEMs in South Korea and Mexico are adopting these reprogrammable options to consolidate regional firmware variants onto single hardware SKUs. This migration from fixed-mask ROM is compressing inventory carrying costs and enabling post-manufacturing security patch deployment.
The EU Medical Device Regulation's Class I software documentation requirements are forcing 8-bit controller suppliers serving diagnostic equipment to implement formalized design history files and traceability matrices. European notified bodies are rejecting legacy 8-bit implementations lacking structured risk management per ISO 14971. German and Italian ventilator and infusion pump manufacturers are responding by dual-sourcing AEC-Q100-qualified 8-bit lines that satisfy both automotive and medical reliability benchmarks.
Consolidated purchasing by Chinese white goods conglomerates is compressing supplier margins and accelerating specification standardization across air conditioner and washing machine controller boards. Haier, Midea, and Gree are centralizing 8-bit procurement decisions at headquarters level, displacing historically fragmented regional sourcing. This concentration is most visible in Guangdong province, where controller module vendors report 40% buyer base reduction over five years.
Global 8 - Bit Microcontroller Market Segmentation
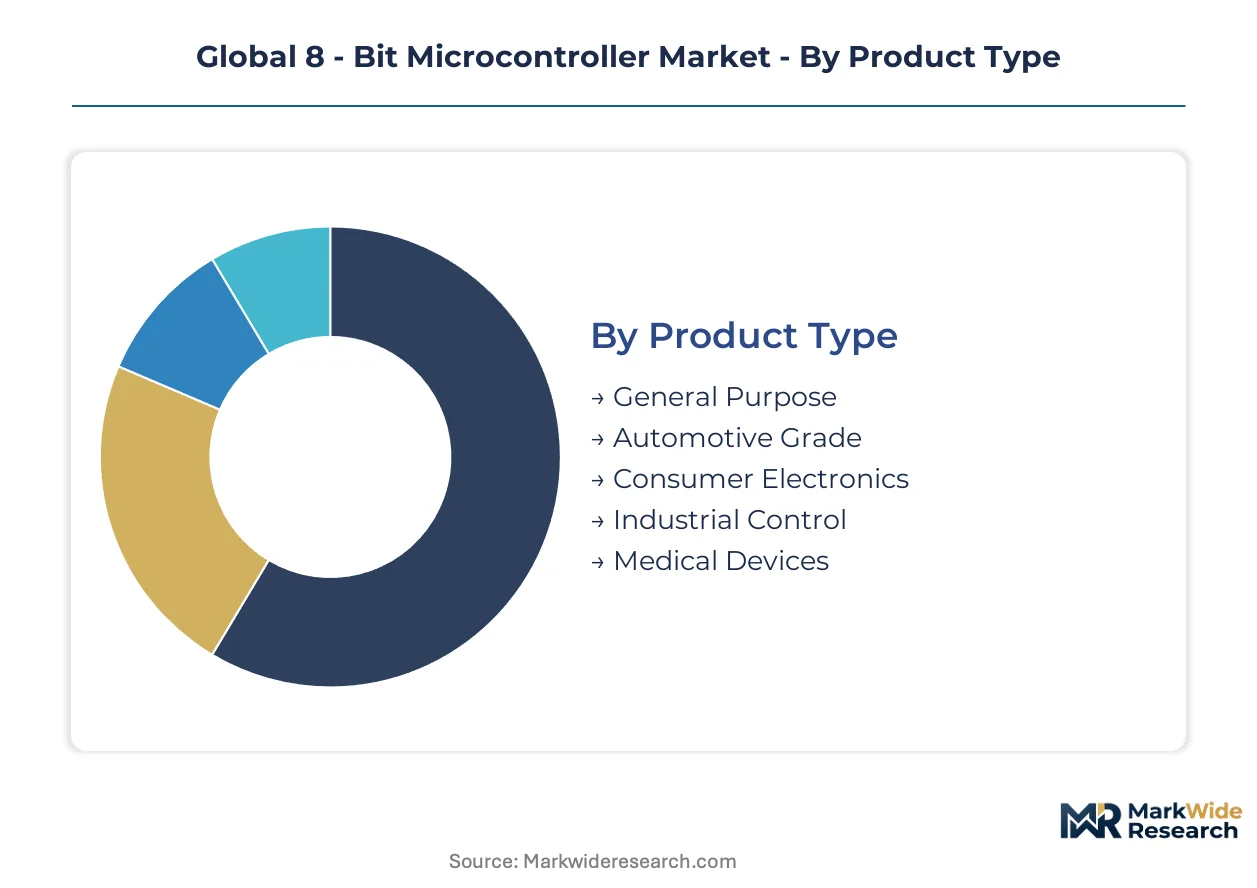
Architectural specialization across 8-bit microcontrollers determines qualification depth, peripheral integration, and margin structure. Segment boundaries increasingly blur as automotive-grade reliability benchmarks migrate into industrial and medical applications.
Product Type:
Mature segments dominate absolute volume while emerging categories capture specification premiums through extended temperature ranges and enhanced diagnostic coverage.
- General Purpose:These devices integrate standard 8-bit cores with configurable GPIO, timers, and basic analog peripherals for undemanding control tasks. Demand concentrates in China's Pearl River Delta for white goods controllers and toy electronics where die cost minimization overrides performance headroom.
- Automotive Grade:AEC-Q100-qualified devices operate across -40°C to 125°C with enhanced ESD protection and lockstep watchdog timers. German and Japanese Tier-1 suppliers specify these for door modules and climate interfaces where functional safety documentation is mandatory.
- Consumer Electronics:Cost-optimized variants with minimal peripheral counts serve disposable electronics and promotional devices with sub-12-month lifecycles.
- Industrial Control:5V-tolerant I/O and extended electromagnetic immunity characterize controllers deployed in motor drives and programmable logic relays.
- Medical Devices:ISO 14971-compliant design history files and FDA traceability matrices elevate these units above standard industrial grades for diagnostic equipment.
Automotive Grade handles the majority of throughput; Medical Devices is expanding most quickly on share as ventilator and infusion pump manufacturers dual-source qualified lines.
Technology:
Memory architecture selection directly determines field upgrade capability, inventory risk exposure, and security patch deployment flexibility across end-use applications.
- Flash Memory:Electrically erasable and reprogrammable without UV exposure, Flash dominates new designs by enabling firmware updates post-manufacturing. Appliance OEMs in South Korea and Mexico consolidate regional variants onto single hardware SKUs, compressing carrying costs.
- ROM:Mask-programmed read-only memory persists only in highest-volume, frozen-specification applications such as legacy automotive sensor interfaces where firmware stability exceeds flexibility requirements.
- EPROM:Erasable programmable read-only memory requiring UV exposure for reprogramming survives in isolated industrial retrofit markets with obsolete equipment maintenance obligations.
- EEPROM:Byte-addressable non-volatile storage supports calibration data logging and runtime parameter retention without full Flash sector erase cycles.
- UV-EPROM:Windowed ceramic packages for laboratory development environments have nearly disappeared from production designs.
Flash Memory commands the dominant technology position; EEPROM is climbing the fastest as sensor calibration and secure key storage requirements proliferate.
Application:
Application segmentation tracks the migration of intelligence toward distributed endpoints in building automation, utility infrastructure, and consumer accessories.
- Home Automation:Capacitive touch-enabled 8-bit cores eliminate discrete sensor ICs in smart switch panels and thermostat interfaces.
- Wearable Devices:Sub-milliwatt active modes and rapid wake-from-sleep transitions support fitness bands and health monitors with coin cell power budgets.
- Smart Metering:India's state electricity boards under the RDSS scheme tender millions of prepaid meter units specifying indigenous controller integration.
- Robotics:Low-latency interrupt response and deterministic timing support servo motor control in educational and hobbyist platforms.
- Electronic Toys:Price-sensitive applications in Guangdong manufacturing clusters prioritize die yield over peripheral richness.
- Security Systems:Tamper detection inputs and encrypted communication peripherals address access control and intrusion detection endpoints.
Smart Metering absorbs the largest project-based volumes; Home Automation is gaining share fastest as building operators deploy cost-optimized sensing endpoints.
End User:
End user categories reflect procurement authority concentration and technical specification ownership across the value chain.
- OEMs:Original equipment manufacturers in Germany, Japan, and the United States retain direct controller specification for differentiated product architectures.
- Tier-1 Suppliers:Automotive module vendors consolidate 8-bit sourcing decisions at headquarters level, reducing supplier base by 40% over five years.
- Aftermarket Providers:Replacement controller modules for legacy vehicle and industrial equipment sustain demand for pin-compatible legacy architectures.
- System Integrators:Turnkey solution providers in India's industrial automation sector bundle 8-bit controllers with sensors and actuators.
- Embedded Systems Developers:Independent design houses and consulting engineers influence early-stage architecture selection through reference design adoption.
Tier-1 Suppliers manage the highest procurement volumes; System Integrators are expanding most rapidly as developing economies industrialize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tier-1 automotive suppliers in Germany, Japan, and the United States concentrate procurement authority for AEC-Q100-qualified 8-bit controllers, while China's Pearl River Delta electronics cluster drives volume demand for cost-optimized general-purpose variants.
United States
NHTSA safety mandates and EPA emissions regulations propel 8-bit controller demand for automotive body electronics and powertrain sensors. The FDA's device classification rules shape design documentation for medical-grade implementations. Detroit's automotive corridor hosts Tier-1 suppliers qualifying controllers for door modules and climate interfaces.
Germany
REACH substance restrictions and RoHS directives accelerate lead-free plating transitions across supplier packaging operations. The KBA enforces automotive functional safety standards that determine 8-bit diagnostic coverage adequacy. Bavaria's industrial automation sector integrates 5V-tolerant controllers into legacy manufacturing equipment retrofits.
China
MIIT certification protocols govern electromagnetic compatibility testing for consumer electronics implementations, while GB standards constrain material selection. The dual carbon goals drive variable-speed compressor controller demand. Shenzhen and Dongguan in the Pearl River Delta manufacture white goods controllers and smart meter subassemblies at scale.
India
The Ministry of Power's RDSS scheme tenders millions of prepaid smart meters specifying indigenous 8-bit controller integration. BIS standards regulate electronic product safety and interoperability. Karnataka's electronics manufacturing cluster hosts system integrators bundling controllers with sensors for industrial automation deployments.
Japan
METI industrial policy supports domestic semiconductor supply chain resilience for mature-node fabrication. JIS standards define quality management systems for automotive component qualification. Nagoya's automotive supplier corridor maintains demand for AEC-Q100-qualified controllers in hybrid vehicle body electronics.
Global 8 - Bit Microcontroller Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Vertically integrated fabricators with captive foundry capacity dominate general-purpose portfolios, while fabless specialists anchor automotive-grade segments through AEC-Q100 qualification depth. Three archetypes structure rivalry: IDM-scale suppliers with backward integration into mature-node fabrication, automotive-focused specialists with extended temperature-range portfolios, and mixed-signal integrators combining analog precision with digital control. Competitive moves concentrate on foundry capacity reservation agreements and cross-licensing of touch-sensing peripheral IP.
Among IDM-scale suppliers with fabrication control, Microchip Technology exemplifies the vertically integrated archetype through its captive production footprint. STMicroelectronics anchors European automotive supply chains through qualification-intensive product lines. Texas Instruments occupies a position emphasizing analog-digital integration density within single-chip architectures.
| Leading Market Players |
|---|
| Microchip Technology |
| NXP Semiconductors |
| STMicroelectronics |
| Renesas Electronics |
| Infineon Technologies |
| Texas Instruments |
| Silicon Laboratories |
| Holtek Semiconductor |
| Analog Devices |
| Others |
Supply & Pricing Matrix
Taiwanese foundry concentration for 180nm and larger geometries concentrates margin capture upstream, forcing downstream module vendors into long-term capacity reservation agreements that compress their pricing flexibility against Chinese white goods conglomerates.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange copper and gold pricing dominate 8-bit microcontroller procurement between Asian packaging houses and European automotive Tier-1 suppliers. Three-tier pricing structure across automotive-grade, industrial, and consumer electronics levels reflects AEC-Q100 certification depth and temperature range tolerance. Cost compression in general-purpose tiers intensifies because Haier, Midea, and Gree centralize procurement decisions at headquarters level. Chinese white goods OEMs exhibit the highest price sensitivity, while German automotive Tier-1 suppliers prioritize qualification depth over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for 8-bit microcontroller vendors serving dual-region automotive programs. Mature-node fabrication concentrates in Taiwan, South Korea, and Japan, while packaging and testing operations draw from Malaysia and the Philippines. Bond wire and leadframe plating materials rest on copper and gold input streams vulnerable to commodity volatility. Distribution runs through authorized distributors serving industrial automation sectors and direct OEM contracts for high-volume automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across automotive, industrial, and consumer electronics demand pools creates niche specialization opportunities as edge computing migration toward distributed sensor nodes diversifies specification requirements.
For Market Incumbents: Harden AEC-Q100 qualification pipelines against 32-bit ARM Cortex-M0 substitution threats by extending diagnostic coverage in body control modules. Secure captive foundry capacity for 180nm geometries through reservation agreements with Taiwanese suppliers. Deepen backward integration into flash memory fabrication to control field-upgrade capability roadmaps.
For New Entrants and Emerging Players: India's state electricity board smart metering tenders under the RDSS scheme represent the most penetrable entry point for indigenous controller integration. Capacitive touch-enabled 8-bit cores in South Korean appliance panels offer a second white-space target. Partner with Shenzhen-based module vendors for rapid qualification into Guangdong white goods supply chains.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive semiconductor specialists holding AEC-Q100 portfolios but lacking flash memory integration. Five-to-ten year viability hinges on whether 8-bit architectures retain sufficient diagnostic coverage for next-generation body electronics or cede position to 32-bit alternatives. Monitor EU automotive functional safety standard evolution as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | Long-term agreements with Taiwanese mature-node fabs secure die supply for automotive programs. |
| Touch-Sensing Peripheral Integration | Eliminating discrete sensor ICs in appliance panels captures value from capacitive interface adoption. |
| Dual-Source Qualification | AEC-Q100 and ISO 14971 alignment opens automotive and medical device revenue pools simultaneously. |
| Regional Firmware Consolidation | Flash reprogrammability enables South Korean and Mexican OEMs to compress SKU proliferation. |
| India Smart Meter Localization | Indigenous controller integration aligns with Ministry of Power RDSS procurement mandates. |
Research Methodology
Cross-validation between primary interviews with automotive Tier-1 procurement officers, industrial automation system integrators, and white goods controller module vendors and secondary sources anchors the qualitative findings. Semiconductor customs data, AEC-Q100 qualification databases, SEC 10-K filings from IDM-scale suppliers, and India Ministry of Power tender documents provide quantitative grounding. Bottom-up unit shipment estimates triangulate against top-down value projections across the analysis window.
Calibration against historical flash memory adoption curves and automotive body electronics content per vehicle shapes the analytical framework. Segmentation dimensions include product type, memory technology, application vertical, and end-user procurement authority. CAGRs derive from regression analysis of shipment velocity against macroeconomic indicators. Foundry utilization rates and copper price volatility feed industry-specific forecast sensitivity.
Practitioners should monitor EU automotive functional safety standard evolution and 32-bit substitution rates in body electronics for early signals of architectural displacement. Forecasts reflect assumptions about mature-node fabrication capacity expansion and REACH compliance timeline adherence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Flip Chip Technology Market
Semiconductor Devices
IGBT Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Field Effect General Purpose Transistors Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
China Semiconductor Device Market
Semiconductor Devices
Multi-Chip Module (MCM) Market
Semiconductor Devices
Global Automotive Mosfets Market
Semiconductor Devices
Digital Transistor Market
Semiconductor Devices
Field Effect Transistor Market
Semiconductor Devices
Taiwan Discrete Semiconductor Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Advanced IC Substrates Market
Semiconductor Devices
ATX Motherboards Market
Semiconductor Devices
Global Probe Card Market