
 Heterojunction Solar Cell Market | 2026-2036
Heterojunction Solar Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Heterojunction Solar Cell Market Analytics
Module-level bundling of bifacial heterojunction panels with smart inverters and performance warranties is repositioning buyer choice toward integrated system contracts rather than component-only procurement. HuaSun leverages vertical integration into n-type silicon wafer production to control cost structures across the cell stack. Meyer Burger specializes in precision deposition equipment that sustains its technology leadership in amorphous silicon layer interfaces. REC Group anchors European demand through brand strength in distributed rooftop segments.
Heterojunction solar cells combine crystalline silicon wafers with ultra-thin amorphous silicon layers deposited at temperatures below 200°C, achieving conversion efficiencies exceeding 25% through superior surface passivation and reduced carrier recombination. Silicon Heterojunction products dominate current manufacturing volumes due to mature equipment supply chains and proven bankability for utility-scale projects. Tandem Cells represent the fastest-growing technology category as perovskite-silicon stacks push laboratory efficiencies toward 33%. Ground-Mounted Systems concentrate the largest installed capacity share, though Building-Integrated installations are gaining traction in premium commercial segments where aesthetic constraints override pure cost optimization.
China's MIIT sets national efficiency benchmarks through GB standards that force domestic manufacturers toward n-type cell architectures, while the EU Green Deal's carbon border adjustments reshape import competitiveness for Asian producers. India's PLI scheme and BIS certification requirements create localized manufacturing obligations that fragment supply chain geography. Japan's METI JIS standards maintain stringent quality protocols that filter market access for new entrants. Stakeholders must monitor regulatory divergence between efficiency mandates and domestic content rules when siting capital-intensive cell and module capacity.
Market Dynamics
Wafer-thinning below 100 micrometers is compressing silicon consumption per watt while China's MIIT efficiency mandates force migration toward n-type heterojunction architectures.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for domestic solar manufacturing are pulling utility-scale developers toward bifacial heterojunction procurement under localized content rules.
- Low-temperature processing:Sub-200°C deposition protocols reduce thermal budget and enable thinner wafer handling without carrier lifetime degradation.
- Japan's METI feed-in tariff revisions:Premium rates for high-efficiency modules accelerate residential and commercial adoption of heterojunction panels.
Market Restraints
- Silver paste dependency:Heterojunction cells require 2-3x silver loading versus PERC alternatives, exposing cost structures to London Metal Exchange price volatility.
- Equipment concentration:Precision chemical vapor deposition tools for amorphous silicon layers concentrate among Japanese and Swiss equipment vendors, creating supply chokepoints.
- Perovskite-silicon tandem threat:Laboratory demonstrations above 33% efficiency threaten to compress heterojunction's efficiency advantage window before cost parity matures.
Strategic Opportunities
- Building-integrated photovoltaics:Aesthetic-grade heterojunction glass-glass modules command premium positioning in commercial facades where crystalline silicon aesthetics fail.
- EU Green Deal carbon border adjustments:Embodied carbon accounting favors low-temperature manufacturing processes, advantaging heterojunction against high-thermal budget alternatives.
- Smart inverter bundling:Module-level power electronics integration creates system-level contracting opportunities beyond component sales.
Industry Challenges
- Amorphous silicon deposition expertise:The thin-film semiconductor skill base concentrates in legacy display panel industries, creating talent migration friction for cell manufacturers.
- GW-scale capex requirements:Cleanroom infrastructure and vacuum deposition equipment demand 18-24 month commissioning timelines, compressing capital deployment windows.
- BIS certification timelines:India's mandatory testing protocols for imported modules create 4-6 month market entry delays for new heterojunction product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heterojunction Solar Cell Market |
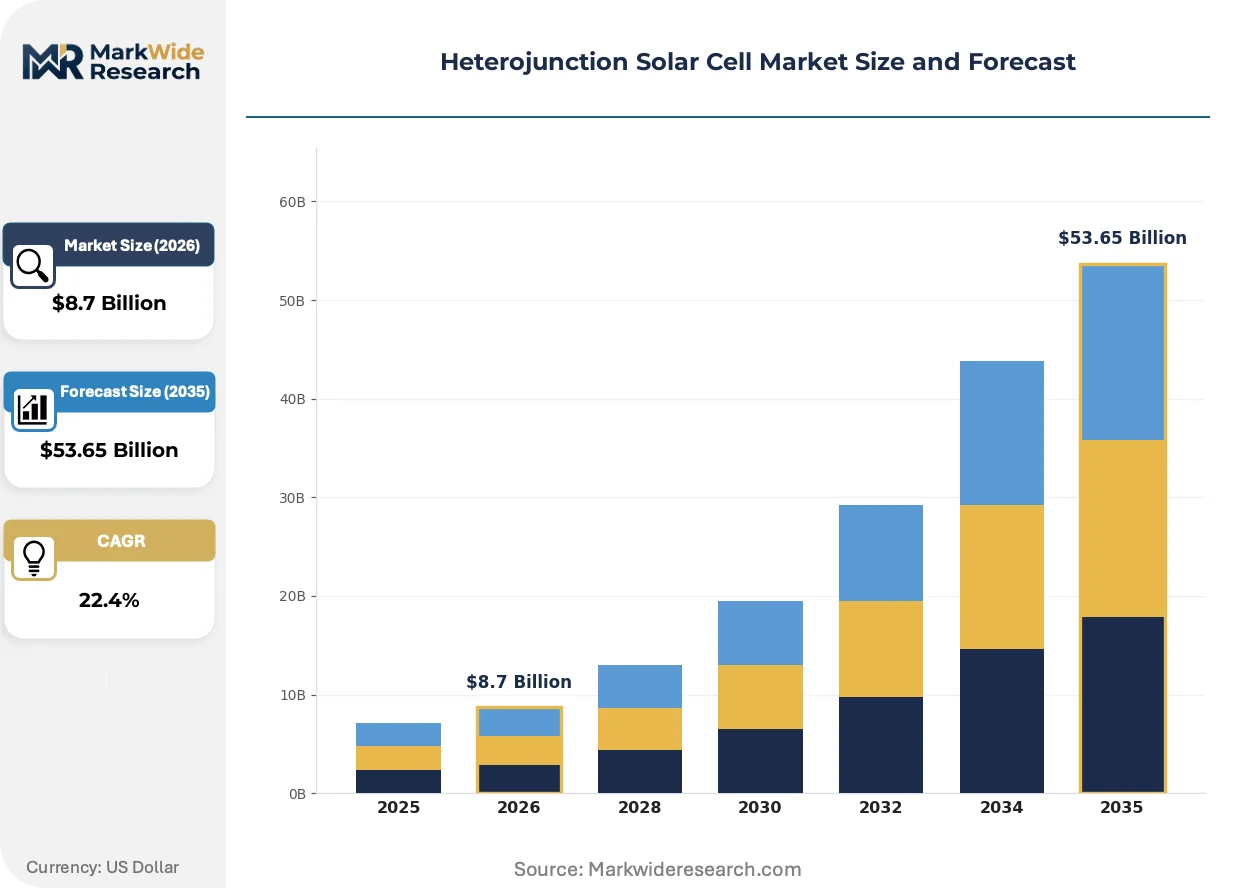
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Heterojunction, Tandem Cells, Bifacial Cells, Photovoltaic Modules End User: Residential, Commercial, Industrial, Utility Scale Technology: Thin-Film, Crystalline Silicon, Organic Photovoltaics, Dye-Sensitized Installation: Roof-Top Systems, Ground-Mounted Systems, Building-Integrated, Off-Grid Systems |
| Companies Covered | HuaSun, Jinergy, REC Group, GS-Solar, Akcome, Risen Energy, Canadian Solar, Meyer Burger, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heterojunction Solar Cell Market Evolving Landscape
Surface passivation engineering and tandem cell architectures are compressing the efficiency gap between laboratory demonstrations and mass production yields.
Silicon heterojunction technology is converging with perovskite top-cell deposition in tandem configurations. Research consortia in Germany and South Korea are scaling pilot lines for 30%-plus efficiency stacks. This convergence is forcing equipment suppliers to redesign deposition chambers for dual-material compatibility.
China's MIIT GB standards now mandate minimum efficiency thresholds that PERC architectures cannot satisfy, effectively banning legacy p-type production for new capacity additions. Domestic manufacturers are responding by converting idled PERC lines to heterojunction through equipment retrofit programs.
Utility-scale developers in India are consolidating procurement around integrated EPC contracts that bundle heterojunction modules with 25-year performance warranties and smart inverter packages. This consolidation is marginalizing component-only vendors and favoring vertically integrated manufacturers with in-house wafer supply.
Heterojunction Solar Cell Market Segmentation
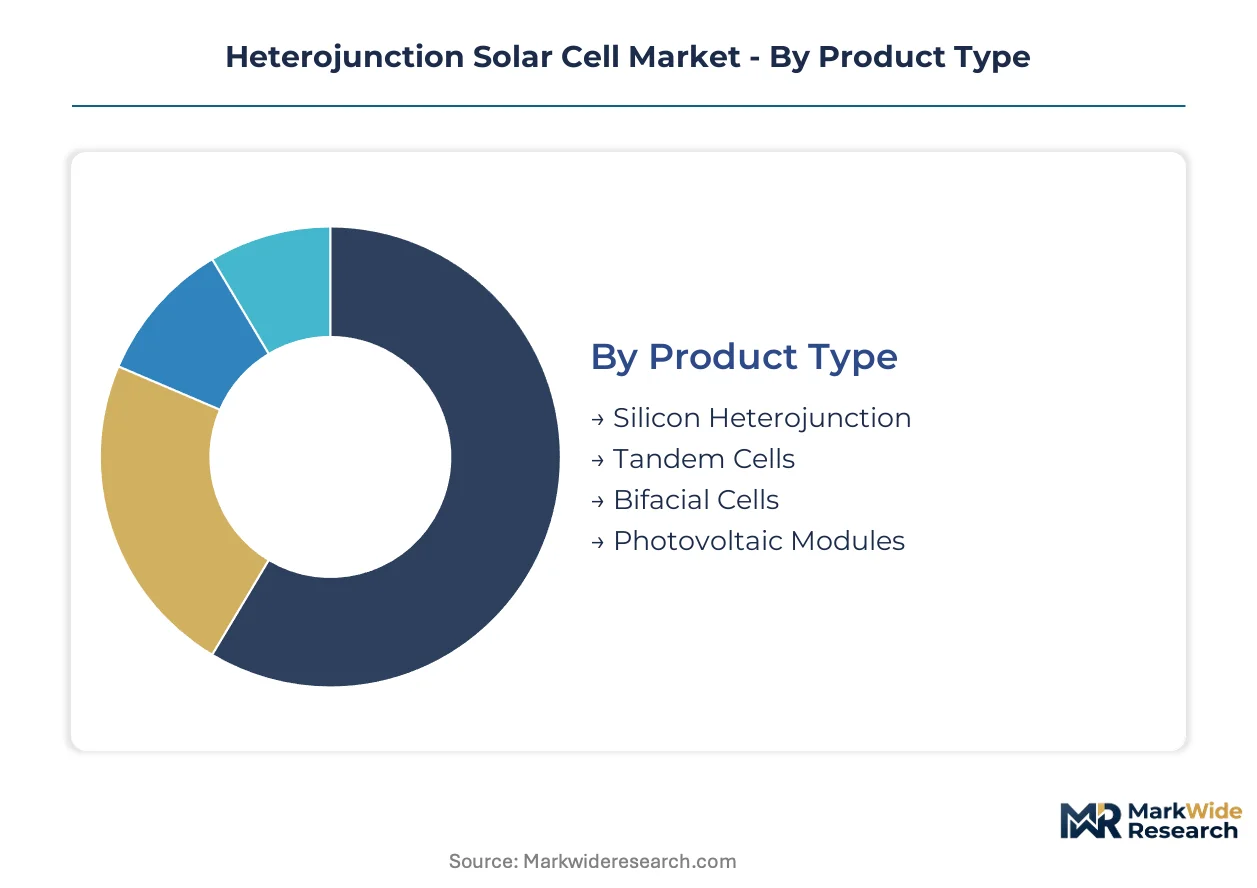
Heterojunction cell architectures fragment across multiple technical and commercial dimensions. Equipment specialization, end-use economics, and installation constraints each reshape procurement patterns and margin structures for manufacturers.
Product Type:
Equipment supply chains for amorphous silicon deposition concentrate among Japanese and Swiss vendors, concentrating manufacturing know-how in legacy thin-film hubs.
- Silicon Heterojunction:Combines crystalline silicon wafers with ultra-thin amorphous silicon layers deposited below 200°C. Utility-scale developers in India and China dominate procurement volumes under efficiency mandates from MIIT GB standards.
- Tandem Cells:Stacks perovskite top-cells atop silicon heterojunction bases. Research consortia in Germany and South Korea pilot 30%-plus efficiency configurations that threaten to compress conventional heterojunction's advantage window.
- Bifacial Cells:Captures reflected light from rear surfaces. Ground-mounted installations in desert climates drive adoption where albedo conditions maximize bifacial gain.
- Photovoltaic Modules:Packaged assemblies integrating cells with encapsulation and framing. Module-level power electronics bundling is repositioning procurement toward integrated system contracts.
Silicon Heterojunction absorbs the bulk of installed capacity; Tandem Cells are expanding most quickly.
End User:
Customer economics diverge sharply between subsidized residential feed-in tariffs and competitive utility-scale auctions.
- Residential:Premium efficiency modules command price tolerance where rooftop space constraints dominate economics. Japan's METI tariff revisions accelerate heterojunction adoption in high-cost urban markets.
- Commercial:Building owners balance aesthetic requirements against energy cost savings. Glass-glass heterojunction modules penetrate facade-integrated installations where crystalline silicon aesthetics fail.
- Industrial:C&I offtakers prioritize 25-year performance warranties and degradation guarantees. Procurement consolidates around EPC integrators with in-house module supply.
- Utility Scale:Competitive auctions in India and China force cost compression through wafer-thinning and silver paste reduction. Bifacial heterojunction configurations dominate new capacity additions.
Utility Scale commands the largest revenue pool; Residential delivers the steepest expansion trajectory.
Technology:
Material compatibility constraints shape equipment retrofit economics for manufacturers migrating from legacy architectures.
- Thin-Film:Amorphous silicon deposition expertise concentrates in former display panel manufacturing regions. Talent migration friction limits expansion speed for new cell manufacturers.
- Crystalline Silicon:N-type wafer supply anchors heterojunction cost structures. China's Yangtze River Delta cluster controls polysilicon purification and ingot pulling capacity.
- Organic Photovoltaics:Solution-processed alternatives remain confined to niche flexible applications. Efficiency gaps exclude organic architectures from mainstream heterojunction competition.
- Dye-Sensitized:Laboratory curiosity with limited manufacturing scale. No meaningful overlap with heterojunction equipment or supply chains.
Crystalline Silicon underpins virtually all heterojunction production; Thin-Film retains specialized relevance for tandem top-cell deposition.
Installation:
Mounting configuration determines module form factor, framing requirements, and balance-of-system economics.
- Roof-Top Systems:Weight constraints and wind loading drive demand for lightweight glass-glass modules. Residential and commercial segments in Japan and Germany concentrate procurement.
- Ground-Mounted Systems:Bifacial heterojunction modules maximize energy yield in utility-scale desert installations. Single-axis tracking compatibility favors standardized module dimensions.
- Building-Integrated:Aesthetic-grade transparency and color uniformity command premium positioning. Commercial facades in European urban cores override pure cost optimization.
- Off-Grid Systems:Remote industrial and rural electrification applications prioritize reliability over efficiency maximization. Limited overlap with heterojunction's cost structure.
Ground-Mounted Systems dominate capacity deployment; Building-Integrated is climbing the fastest on premium commercial demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands manufacturing capacity while India and Japan drive procurement through policy mechanisms. Production concentrates in the Yangtze River Delta where polysilicon purification and ingot pulling anchor supply chains. Consumption patterns diverge between subsidized residential feed-in tariffs and competitive utility-scale auctions.
China
MIIT GB standards mandate minimum efficiency thresholds that PERC architectures cannot satisfy, forcing migration toward n-type heterojunction. The Yangtze River Delta cluster hosts HuaSun and Meyer Burger gigawatt-scale production facilities. Wafer-thinning below 100 micrometers compresses silicon consumption per watt across domestic manufacturing lines.
India
Utility-scale developers consolidate procurement around integrated EPC contracts bundling bifacial heterojunction modules with 25-year warranties. The PLI scheme for domestic solar manufacturing creates localized content obligations that fragment supply chain geography. Gujarat and Rajasthan host ground-mounted installations where albedo conditions maximize bifacial gain.
Japan
METI renewable energy feed-in tariff revisions accelerate residential and commercial adoption of high-efficiency heterojunction panels. JIS standards maintain stringent quality protocols that filter market access for new entrants. The Kanto region around Tokyo concentrates premium rooftop installations where space constraints dominate economics.
Germany
Research consortia pilot perovskite-silicon tandem configurations pushing toward 30%-plus efficiency stacks. EU Green Deal carbon border adjustments reshape import competitiveness for Asian producers through embodied carbon accounting. Bavaria anchors equipment supply chains for precision chemical vapor deposition tools.
South Korea
Pilot lines for tandem cell architectures scale manufacturing readiness for next-generation stacks. MFDS regulatory frameworks overlap with industrial policy supporting clean energy technology transitions. The Seoul Capital Area concentrates R&D coordination between research institutes and equipment vendors.
Heterojunction Solar Cell Market Competitive Landscape
The competitive structure tilts toward vertically integrated wafer-to-module specialists and precision equipment vendors. Tiered differentiation separates premium efficiency players from scale-driven cost competitors. Two archetypes dominate: captive n-type silicon producers controlling stack economics, and deposition equipment specialists sustaining interface quality leadership. Capacity expansion and strategic partnerships constitute the dominant competitive moves as manufacturers retrofit idled PERC lines.
Among Chinese integrated manufacturers, HuaSun and Jinergy exemplify the captive wafer supply archetype. REC Group and Meyer Burger occupy positions on the premium-efficiency vector, with the latter representing Swiss precision equipment specialization. Panasonic Corporation anchors Japanese quality-tier positioning through residential market brand strength.
| Leading Market Players |
|---|
| HuaSun |
| Jinergy |
| REC Group |
| GS-Solar |
| Akcome |
| Risen Energy |
| Canadian Solar |
| Meyer Burger |
| Panasonic Corporation |
| Others |
Value Network & Pricing Analysis
Silver paste traverses from London Metal Exchange pricing volatility through module cost structures into bifacial heterojunction procurement decisions by India's utility-scale developers. Wafer-thinning below 100 micrometers compresses silicon consumption per watt while China's MIIT efficiency mandates force migration toward n-type architectures that command premium positioning.
Pricing Analysis
Margin tightening in standard-grade modules reflects silver loading multiples versus PERC alternatives and equipment concentration among Japanese and Swiss deposition tool vendors. Three-tier pricing structure across premium efficiency, standard utility-grade, and economy retrofit tiers separates Meyer Burger's precision equipment positioning from HuaSun's captive wafer cost control. Cost-down pressure accelerates because India's PLI scheme consolidates procurement around integrated EPC contracts bundling 25-year warranties. Utility-scale auctions demonstrate highest price sensitivity; residential segments under Japan's METI tariffs tolerate efficiency premiums.
Supply Chain Analysis
Freight cost differentials between polysilicon purification in China's Yangtze River Delta and module assembly in Gujarat reshape landed cost economics for Indian developers. Manufacturing gravity centers on China, Japan, and Germany for precision chemical vapor deposition equipment. Raw material dependencies span silver paste, high-purity n-type silicon wafers, and amorphous silicon precursor gases. Single-source vulnerability concentrates in Japanese and Swiss equipment vendors for amorphous silicon deposition chambers. Distribution runs through vertically integrated wafer-to-module specialists and EPC integrators with in-house supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heterojunction solar cell market occupies a technology-transition phase as n-type architectures displace legacy PERC production under efficiency mandates from China's MIIT GB standards.
For Market Incumbents: Anticipate perovskite-silicon tandem laboratory demonstrations above 33% efficiency compressing the heterojunction advantage window before cost parity matures. Retrofit idled PERC lines through equipment conversion programs to preserve capital deployment timelines. Deepen backward integration into n-type silicon wafer production to control stack economics against silver paste price volatility.
For New Entrants and Emerging Players: EPC contractors with bundled procurement mandates represent the most accessible channel for bypassing component-only vendor marginalization. Target India's distributed commercial rooftop segment where BIS certification timelines create incumbent vulnerability and aesthetic-grade glass-glass modules command premium positioning. Pursue technology licensing partnerships with German or South Korean research consortia piloting tandem cell architectures.
For Investors and Strategic Acquirers: METI feed-in tariff revision announcements are the leading indicator that premium efficiency module demand inflection is imminent in Japan's residential market. Position for five-to-ten year viability around deposition equipment specialists with amorphous silicon interface expertise rather than pure-play module assemblers. Monitor wafer-thinning process yields below 100 micrometers as the signal for manufacturing cost structure inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Thinning Process Scale-Up | Compresses silicon consumption per watt for Yangtze River Delta manufacturers under MIIT mandates. |
| Silver Paste Reduction R&D Partnership | Addresses London Metal Exchange price volatility exposure in heterojunction cell metallization. |
| Perovskite Tandem Pilot Line Investment | Positions German and South Korean consortia for 30%-plus efficiency stack commercialization. |
| Integrated EPC Contract Consolidation | Marginalizes component-only vendors in India's PLI-driven utility-scale procurement. |
| Carbon Border Adjustment Compliance Program | Secures EU Green Deal market access for low-temperature heterojunction manufacturing. |
Research Methodology
Independent corroboration across equipment vendor technical specifications, utility developer procurement databases, and national regulator filing repositories underwrites the qualitative findings. Primary interviews with cell manufacturing executives, EPC project developers, and grid interconnection planners combined with secondary validation from MIIT GB standard documents, METI tariff revision notices, and SEC filings from publicly traded solar manufacturers. Bottom-up capacity build-out tracking and top-down policy incentive modeling triangulate volume estimates.
Comparable-period anchoring to historical capacity addition data and efficiency improvement curves structures the projection methodology across the analysis window. Segmentation dimensions span cell architecture type, end-use application, installation configuration, and regional regulatory framework. CAGRs derive from equipment deployment timelines, wafer supply expansion schedules, and policy incentive phase-out trajectories. Forecast inputs incorporate silver price volatility bands and perovskite tandem technology readiness assessments.
Caveats apply where METI tariff revision timing, BIS certification protocol changes, or perovskite-silicon tandem pilot line yield breakthroughs could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Europe Wigig Market
Optoelectronics
Thermophotovoltaics Market
Optoelectronics
Taiwan Optoelectronics Market
Optoelectronics
Quantum Dots Market
Optoelectronics
Optoelectronic Transducers Market
Optoelectronics
Automotive Optoelectronics Market
Optoelectronics
Quantum Cascade Lasers Market
Optoelectronics
Light Projector Market
Optoelectronics
Laser Diode Market
Optoelectronics
Electro-Optical/Infrared (EO/IR) Systems Market
Optoelectronics
Optical Emission Spectroscopy Market
Optoelectronics
Japan Optoelectronics Market
Optoelectronics
Gaas Photodiode Market
Optoelectronics
Laser Projection Market
Optoelectronics
Global Optocoupler Market
Optoelectronics
Global Opto-Isolator Market