
 Pcie Switches Market | 2026-2036
Pcie Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Pcie Switches Market Analysis
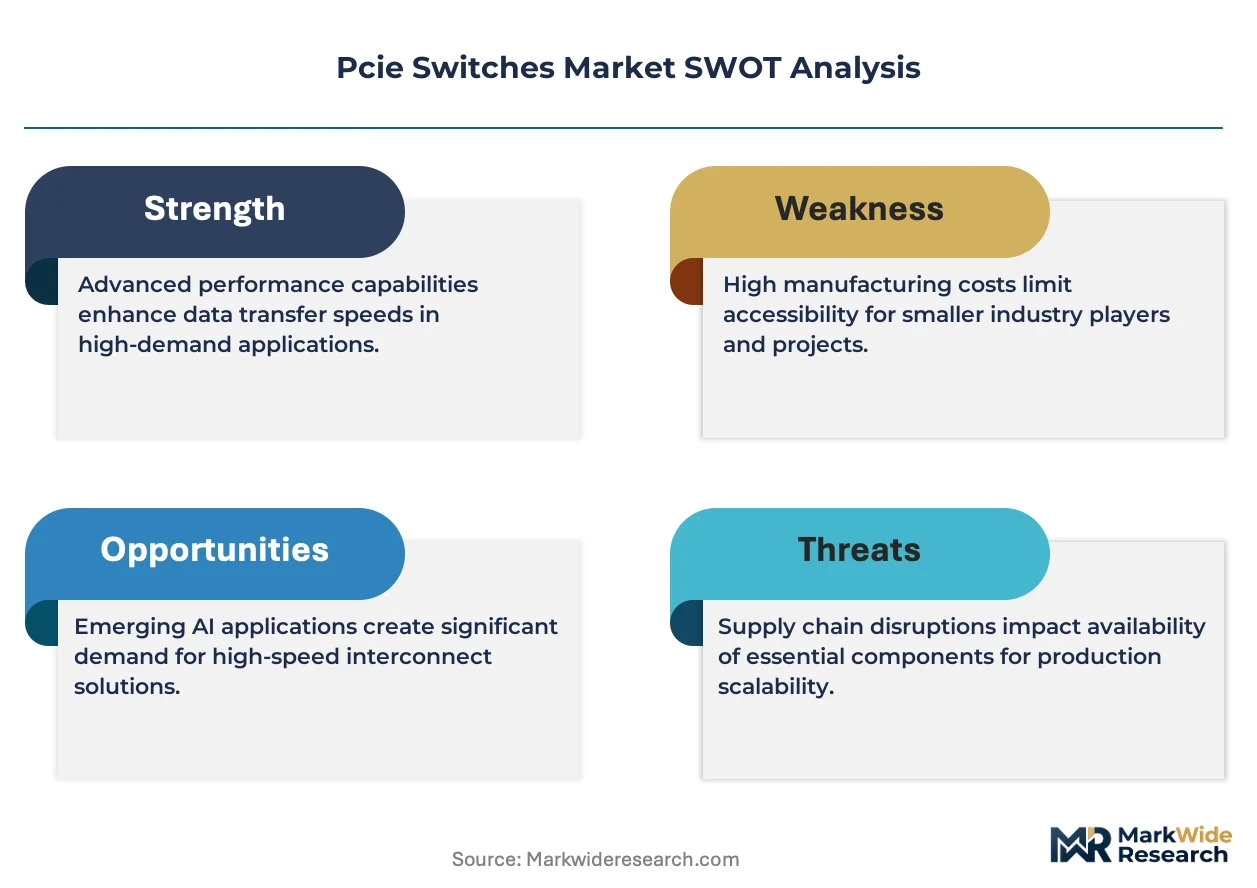
Silicon photonics engineering talent is rotating toward PCIe switch design teams as data center bandwidth requirements outpace electrical interconnect scaling. Broadcom Inc. leverages its custom ASIC relationships to sustain design wins at hyperscale cloud operators. Marvell Technology Inc. anchors its position through in-house production of high-speed SerDes IP. Renesas Electronics Corporation differentiates by competing aggressively in automotive PCIe bridge segments where functional safety certifications matter.
A PCIe switch is a high-speed packet-switching semiconductor that routes data between multiple endpoints over the PCI Express serial interconnect protocol, typically supporting lane configurations from x1 to x128 and data rates up to 64 GT/s in Gen6 implementations. Its primary purpose is to expand connectivity in compute-intensive environments where CPU-native PCIe lanes prove insufficient for attached GPUs, NVMe storage arrays, and network interface cards. Non-blocking architectures command premium positioning in data center deployments where deterministic latency shapes total cost of ownership calculations. Embedded switch variants are gaining share in edge computing appliances where space and thermal budgets constrain modular alternatives. Switch fabric components capture disproportionate margin pools relative to power management subsystems due to their direct impact on bandwidth scalability.
The FCC governs electromagnetic emissions from server equipment deployed in US commercial facilities, while the EU AI Act imposes transparency obligations on automated decision-making systems that rely on high-throughput interconnect hardware. REACH restricts hazardous substances in semiconductor packaging materials, directly affecting substrate and solder choices for PCIe switch vendors serving European OEMs. Stakeholders must monitor how NIST cybersecurity frameworks for critical infrastructure reshape procurement specifications for data center interconnect components.
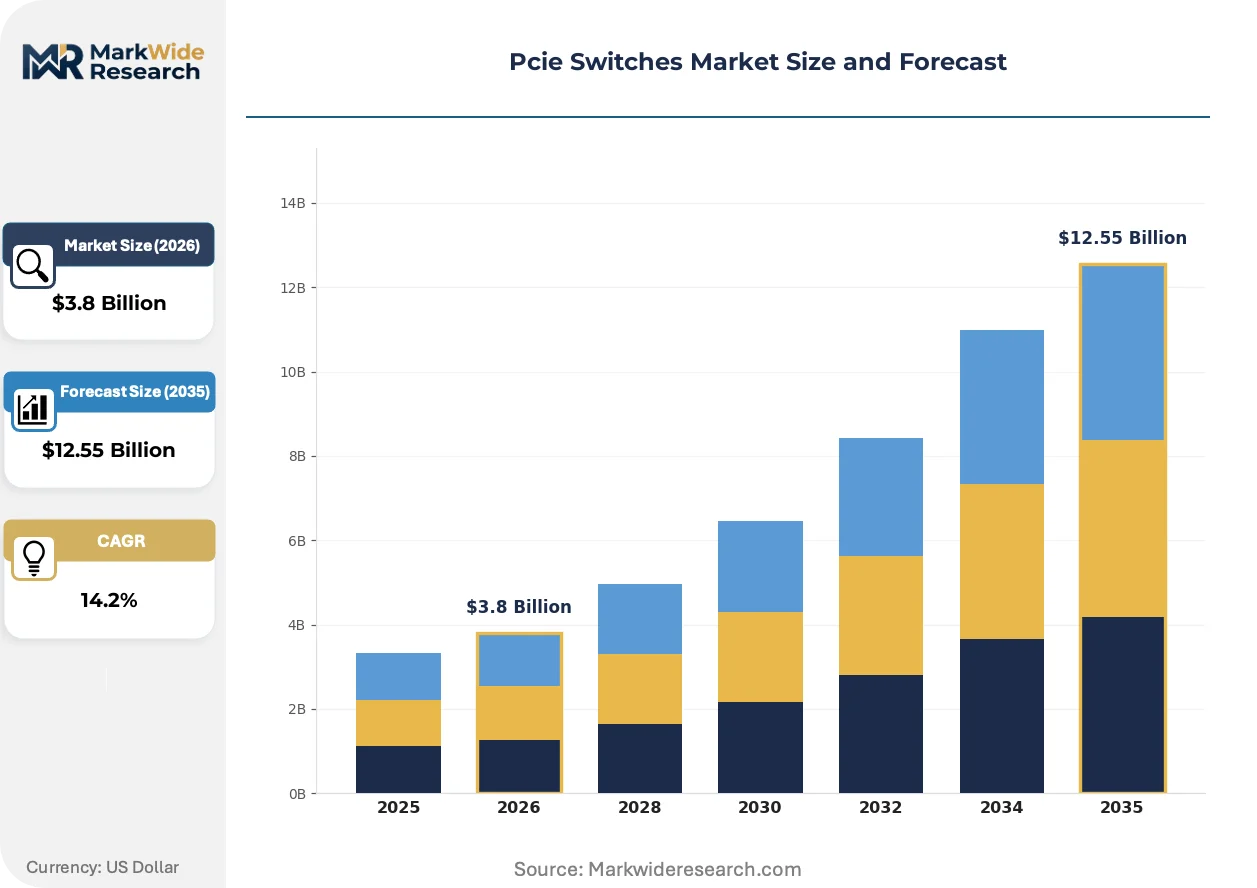
Market Dynamics
PCIe switch architectures are compressing design cycles as hyperscale cloud operators demand deterministic latency guarantees for AI training clusters. Taiwan's foundry concentration for advanced SerDes IP is constraining second-tier vendor access to leading-edge process nodes.
Growth Catalysts
- EU AI Act transparency mandates:Automated decision-making systems in European data centers now require certified interconnect hardware, accelerating procurement of compliant PCIe Gen5 and Gen6 switches.
- Silicon photonics convergence:Engineering teams are migrating optical interconnect expertise into electrical switch design, enabling 64 GT/s signal integrity at reduced power density.
- Edge computing appliance demand:Space-constrained industrial automation deployments in Germany and Japan are adopting embedded PCIe switch variants for localized GPU inference.
Market Restraints
- Advanced substrate cost volatility:Organic substrate and high-density laminate prices fluctuate with epoxy resin supply, squeezing gross margins on mid-range switch SKUs.
- Taiwan foundry concentration risk:Single geography dominance in 3nm and 2nm CoWoS packaging creates supply vulnerability for Gen6 retimer-integrated switches.
- Electrical interconnect physics ceiling:Copper trace attenuation at 64 GT/s limits reach without active retimers, adding bill-of-materials complexity.
Strategic Opportunities
- Automotive functional safety certification:PCIe bridge segments serving autonomous vehicle compute platforms require ISO 26262 ASIL-D compliance, opening premium pricing tiers.
- India data center buildout:Domestic cloud infrastructure investment under the PLI scheme creates demand for cost-optimized Gen4 switches with localization requirements.
- Direct liquid cooling integration:Thermal interface standardization for immersion-cooled servers enables switch vendors to capture cooling subsystem margin pools.
Industry Challenges
- High-speed SerDes talent scarcity:Mixed-signal design expertise for 112G PAM4 interfaces concentrates at established IP houses, constraining new vendor entry.
- Multi-generational interoperability testing:Backward compatibility validation across Gen3 through Gen6 lane configurations extends certification timelines for server OEM qualifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pcie Switches Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-blocking, Blocking, Embedded, Modular Application: Data Centers, Enterprise Servers, Cloud Computing, High-Performance Computing Component: Switch Fabric, Controller, Power Management, Thermal Management Deployment: On-premises, Cloud-based, Hybrid, Edge |
| Companies Covered | Broadcom Inc., Microchip Technology Inc., Intel Corporation, Texas Instruments Incorporated, NXP Semiconductors, Marvell Technology Inc., Renesas Electronics Corporation, ON Semiconductor, Diodes Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pcie Switches Market Emerging Trajectories
Compute fabric architectures are fragmenting into distinct performance tiers as AI training and inference workloads diverge in interconnect requirements. Switch vendors must now optimize for either bandwidth density or power efficiency rather than unified designs.
PCIe switch product lines are bifurcating into distinct data center and edge-optimized variants. Hyperscale operators in the United States are adopting monolithic retimer-integrated switches for AI clusters. This technology compression is eliminating modular chassis switch opportunities below 400W thermal envelopes.
REACH substance restrictions are forcing substrate material transitions in semiconductor packaging. European OEM procurement specifications now exclude legacy halogenated flame retardants. Server motherboard vendors serving Germany and France are accelerating qualification of alternative laminate systems ahead of 2025 compliance deadlines.
Hyperscale buyers are consolidating switch procurement through direct ASIC partnerships rather than merchant silicon. Cloud operators in North America are engaging Broadcom and Marvell for custom lane configurations. This disintermediation is compressing distributor margins and forcing component vendors to absorb inventory risk for long-tail SKUs.
Pcie Switches Market Segmentation
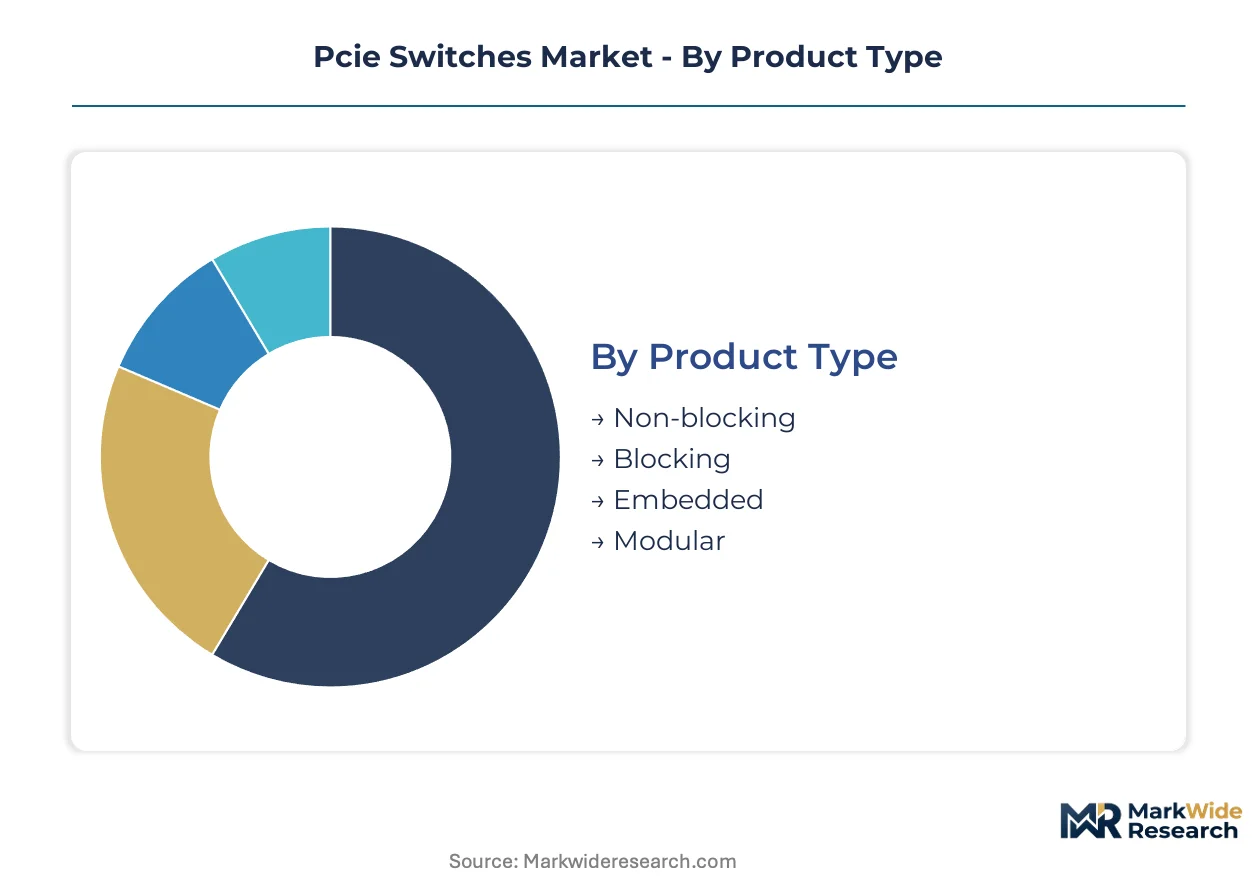
PCIe switch procurement channels diverge sharply between hyperscale direct ASIC partnerships and distributor-mediated enterprise sales. Understanding these channel dynamics reveals why certain segment combinations command premium positioning while others face margin compression from inventory risk absorption.
Product Type:
Non-blocking switches flow predominantly through direct vendor-OEM partnerships for data center qualification, while embedded variants reach industrial automation buyers via specialized distributors serving edge computing deployments.
- Non-blocking:Architectures guarantee deterministic latency across all port-to-port paths through independent crossbar matrices. Hyperscale cloud operators in the United States specify these for AI training clusters where tail latency directly impacts job completion economics.
- Embedded:Compact form factors integrate switch logic directly onto host boards with constrained thermal envelopes. German industrial automation OEMs are qualifying these for localized GPU inference in space-constrained factory floor installations.
- Blocking:Shared internal bandwidth architectures reduce die area and cost for cost-sensitive applications. These serve secondary expansion slots in enterprise servers where full bisection bandwidth remains unnecessary.
- Modular:Chassis-based designs with hot-swappable line cards target legacy enterprise data centers. Procurement is contracting as hyperscale operators disintermediate modular suppliers through custom ASIC programs.
Non-blocking architectures dominate installed base value. Embedded variants are where expansion concentrates most steeply.
Application:
Cost tier stratification separates million-unit cloud deployments from thousand-unit HPC installations, with certification requirements and volume scale determining pricing power across each tier.
- Data Centers:Hyperscale facilities deploy retimer-integrated switches at 400W+ thermal densities. Taiwan's foundry cluster supplies the advanced SerDes IP required for these deployments, constraining second-tier vendor participation.
- Cloud Computing:Public cloud operators negotiate custom lane configurations directly with switch ASIC designers. This procurement pattern eliminates distributor margins and shifts inventory risk to component vendors.
- Enterprise Servers:Mid-range configurations balance expansion capability against cost constraints. IT procurement teams prioritize backward compatibility validation across multiple server generations.
- High-Performance Computing:Research facilities and government laboratories specify ultra-low latency for tightly coupled simulation workloads. Volumes remain limited but pricing power is substantial due to technical qualification barriers.
Cloud Computing commands the steepest expansion trajectory. Enterprise Servers retain the largest installed base volume.
Component:
Margin concentration tracks technical differentiation, with fabric components capturing disproportionate returns relative to commodity power management subsystems.
- Switch Fabric:Crossbar and shared-memory architectures determine maximum throughput and latency characteristics. Design teams with silicon photonics expertise are migrating into fabric engineering as electrical interconnect scaling faces physics constraints.
- Controller:Firmware-programmable logic manages routing tables, error handling, and power state transitions. Automotive PCIe bridge applications require ISO 26262 ASIL-D certified controllers for autonomous vehicle compute platforms.
- Power Management:Voltage regulator modules and sequencing circuits ensure stable operation across dynamic load conditions. These subsystems face pricing pressure from established analog semiconductor suppliers.
- Thermal Management:Heat spreaders, thermal interface materials, and sensor networks maintain junction temperatures within specification. Direct liquid cooling integration is emerging as a differentiation vector for immersion-cooled server designs.
Switch Fabric components dominate margin pools. Controller ASICs are where automotive certification investments concentrate.
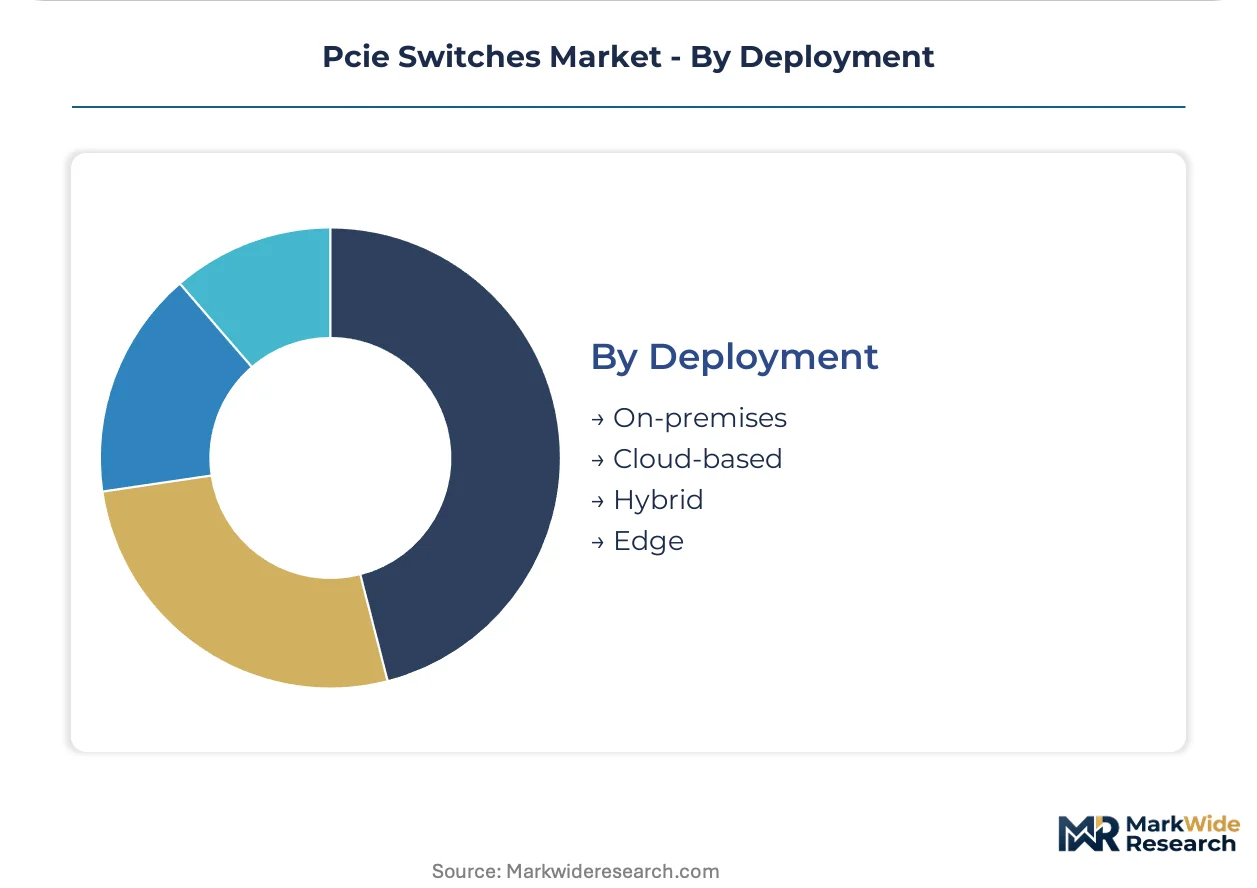
Deployment:
Customer type and infrastructure maturity determine procurement patterns, with cloud-native buyers favoring operational expenditure models against capital expenditure preferences in regulated industries.
- On-premises:Enterprise-owned infrastructure requires five-to-seven-year depreciation cycles and multi-generational interoperability. Compliance with the EU AI Act's transparency mandates is accelerating refresh timelines for European installations.
- Edge:Distributed compute nodes process inference workloads close to data sources. Japan's manufacturing sector is deploying these configurations for quality inspection and predictive maintenance applications.
- Hybrid:Workload portability between private and public environments demands consistent interconnect semantics. These deployments prioritize backward compatibility across Gen3 through Gen6 lane configurations.
- Cloud-based:Fully outsourced infrastructure shifts hardware procurement decisions to cloud operators. Hyperscale buyers consolidate purchasing power through direct ASIC partnerships rather than merchant silicon.
On-premises retains the largest installed base. Edge deployments are climbing the fastest among deployment modes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud operators in the United States deploy retimer-integrated switches at thermal densities exceeding 400W, while German industrial automation buyers favor embedded variants for space-constrained factory floors. This consumption-mix differential shapes procurement patterns across major markets.
United States
Cloud computing providers in Northern Virginia and Oregon data center corridors are expanding procurement of high-bandwidth interconnect hardware for AI training clusters. The FCC governs electromagnetic emissions from server equipment deployed in commercial facilities. Austin and San Jose engineering centers concentrate custom ASIC design partnerships with switch vendors.
Germany
Industrial automation OEMs in Bavaria are qualifying embedded PCIe switch variants for localized GPU inference on factory floors. Compliance with the EU AI Act's data-processing transparency rules is accelerating certification requirements for server infrastructure. Stuttgart and Munich host automotive PCIe bridge development targeting ISO 26262 ASIL-D functional safety standards.
Japan
Manufacturing sector buyers in the Chubu region are deploying edge computing configurations for quality inspection and predictive maintenance applications. METI industrial policy supports domestic semiconductor packaging capabilities for advanced interconnect components. Yokohama and Osaka house precision equipment vendors integrating switch logic into compact thermal envelopes.
Taiwan
Advanced packaging capabilities for PCIe Gen5 and Gen6 devices are scaling within the Hsinchu Science Park foundry cluster. The concentration of 3nm and 2nm CoWoS packaging creates supply leverage for retimer-integrated switch production. Tainan and Taichung facilities supply high-speed SerDes IP that constrains second-tier vendor access to leading-edge process nodes.
India
Domestic cloud infrastructure investment under the PLI scheme is creating demand for cost-optimized Gen4 switches with localization requirements. BIS certification timelines shape procurement decisions for data center interconnect components. Bengaluru and Hyderabad engineering centers are qualifying switch designs for tropical climate thermal specifications.
Pcie Switches Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in PCIe switch supply. The upper tier commands direct ASIC partnerships with hyperscale operators, while mid-tier players compete through distributor-mediated enterprise channels. Three archetypes dominate: custom silicon designers with captive foundry relationships, automotive-certified bridge specialists, and merchant silicon vendors absorbing inventory risk for long-tail SKUs. Competitive moves concentrate on backward integration into SerDes IP and strategic partnerships for advanced packaging access.
Within the integrated leader tier, Broadcom Inc. and Marvell Technology Inc. exemplify the custom ASIC partnership model with hyperscale cloud operators. Renesas Electronics Corporation occupies a distinct position representing the automotive functional safety certification archetype. These three anchors illustrate how vendor positioning diverges between bandwidth-density optimization for data centers and power-efficiency priorities for edge computing deployments.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Microchip Technology Inc. |
| Intel Corporation |
| Texas Instruments Incorporated |
| NXP Semiconductors |
| Marvell Technology Inc. |
| Renesas Electronics Corporation |
| ON Semiconductor |
| Diodes Incorporated |
| Others |
Supply Flow & Price Mechanics
Foundry-scale economies in Taiwan's Hsinchu Science Park concentrate advanced SerDes IP production, compressing cost floors for PCIe Gen6 switches while elevating pricing power for retimer-integrated designs serving hyperscale cloud operators.
Pricing Analysis
Long-term offtake contracts dominate hyperscale procurement, locking in volume commitments for custom lane configurations while spot purchasing persists for enterprise distributor channels. Price differentiation hinges on certification tier—ISO 26262 ASIL-D compliance commands substantial premiums in automotive PCIe bridges—and volume scale, with million-unit cloud deployments securing steep discounts unavailable to thousand-unit HPC installations. Cost compression in mid-range enterprise SKUs is intensifying because organic substrate price volatility squeezes gross margins. Enterprise IT procurement teams exhibit highest price sensitivity, prioritizing backward compatibility over performance premiums, whereas AI training cluster buyers prioritize deterministic latency with limited budget elasticity.
Supply Chain Analysis
Taiwan anchors wafer fabrication and CoWoS advanced packaging for Gen5 and Gen6 switches, while South Korea supplies high-bandwidth memory integration and the United States concentrates custom ASIC design partnerships. Raw material dependencies include epoxy resin systems for organic substrates, high-purity copper for trace layers, and rare earth elements for thermal interface materials. Single-source vulnerability concentrates in 3nm and 2nm foundry capacity at TSMC, constraining second-tier vendor access to leading-edge nodes. Distribution runs through direct vendor-OEM partnerships for hyperscale qualification, with distributor-mediated channels serving long-tail enterprise and industrial automation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as hyperscale AI infrastructure investment accelerates refresh timelines for server interconnect hardware, reversing the procurement freeze that characterized the prior downcycle.
For Market Incumbents: Secure captive foundry capacity through advance purchase agreements at Taiwan's leading-edge nodes, insulating against single-geography supply disruption that threatens Gen6 retimer-integrated switch availability. Deepen backward integration into high-speed SerDes IP to reduce dependency on external design houses. Defend automotive PCIe bridge margins through accelerated ISO 26262 ASIL-D certification timelines, creating qualification barriers against merchant silicon competitors.
For New Entrants and Emerging Players: Automotive functional safety certification fast-tracks offer the most penetrable entry vector, as established vendors underinvest in bridge segments serving autonomous vehicle compute platforms. Target India's PLI-supported data center buildout for cost-optimized Gen4 switch localization, where BIS certification requirements filter out uncompetitive imports. Pursue direct liquid cooling integration partnerships with immersion-cooled server designers as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automotive-certified bridge specialists with established functional safety credentials, as PCIe Gen6 transition concentrates bandwidth-density investment at hyperscale incumbents. Long-term viability across the projection horizon rests on backward compatibility capabilities spanning Gen3 through Gen6 lane configurations. Acquisition screening should prioritize vendors with in-house SerDes IP and advanced packaging partnerships. The signal to watch is hyperscale direct ASIC partnership announcements, which foreshadow merchant silicon margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Custom ASIC Partnership | Direct engagement with hyperscale cloud operators eliminates distributor margins and locks in multi-year volume commitments. |
| Automotive Certification Investment | ISO 26262 ASIL-D compliance opens premium pricing tiers in autonomous vehicle compute platforms. |
| Advanced Packaging Access | CoWoS capacity reservations at Taiwan foundries secure supply leverage for retimer-integrated Gen6 production. |
| Silicon Photonics Integration | Optical interconnect expertise migration enables 64 GT/s signal integrity at reduced power density. |
| Direct Liquid Cooling Standardization | Thermal interface partnerships with immersion-cooled server designers capture cooling subsystem margin pools. |
Methodological Framework
The analysis maps PCIe switch product architectures, application segments, and deployment modes, each validated through primary interviews with data center infrastructure architects, semiconductor procurement leads at server OEMs, and thermal design engineers at cloud operators. Secondary validation draws from SEC 10-K filings of switch vendors, hyperscaler capex disclosures, Taiwan foundry utilization reports, and EU regulatory filings under the AI Act. Bottom-up segment sizing triangulates against top-down market aggregation across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs, with segmentation modeling spanning non-blocking versus embedded versus modular form factors, data center versus cloud versus enterprise application tiers, and on-premises versus edge versus cloud-based deployment modes. CAGRs derive from installed base replacement cycles, generational transition velocity from Gen5 to Gen6, and AI training cluster expansion trajectories. Forecast inputs include foundry capacity allocation announcements, REACH substance restriction timelines, and PLI scheme disbursement patterns in India.
Underlying assumptions cover sustained hyperscale AI infrastructure investment, stable Taiwan foundry access, and REACH compliance deadlines, with deviation risk concentrated in geopolitical disruption to advanced packaging supply and faster-than-expected silicon photonics substitution for electrical interconnect. Recalibration cycles align with material shifts in hyperscale procurement patterns, foundry capacity announcements, and EU regulatory enforcement actions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Automotive Grade Emmc Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Hairpin Stator Market
Semiconductor Devices
APAC Semiconductor Device for Processing Applications Market
Semiconductor Devices
ATX Motherboards Market
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
Semiconductor in Phones Market
Semiconductor Devices
China Semiconductor Device Market
Semiconductor Devices
Silicon Epitaxial Wafer Market
Semiconductor Devices
AMD Motherboards Market
Semiconductor Devices
MBE Components Market
Semiconductor Devices
Global Transistor Market
Semiconductor Devices
Programmable Logic Device (PLD) Market
Semiconductor Devices
Middle East Distribution Panel Market
Semiconductor Devices
IT & Telecom Discrete Semiconductor Market