
 Tanzania Cashew Market | 2026-2036
Tanzania Cashew Market Size, Share, and Industry Trends Forecast 2026-2036
Tanzania Cashew Market Analytics
Snack manufacturers are unwinding decades of direct bulk purchasing from Indian and Vietnamese traders, redirecting orders toward Tanzanian processors with traceable supply chains. YYTZ leverages its integrated processing and export license to capture this rotation. Mtwara Cashew Processing Company anchors volume output through its coastal facility proximity to raw nut sourcing clusters. Azam Cashew Industries differentiates via retail-branded kernel packs distributed through East African supermarket channels.
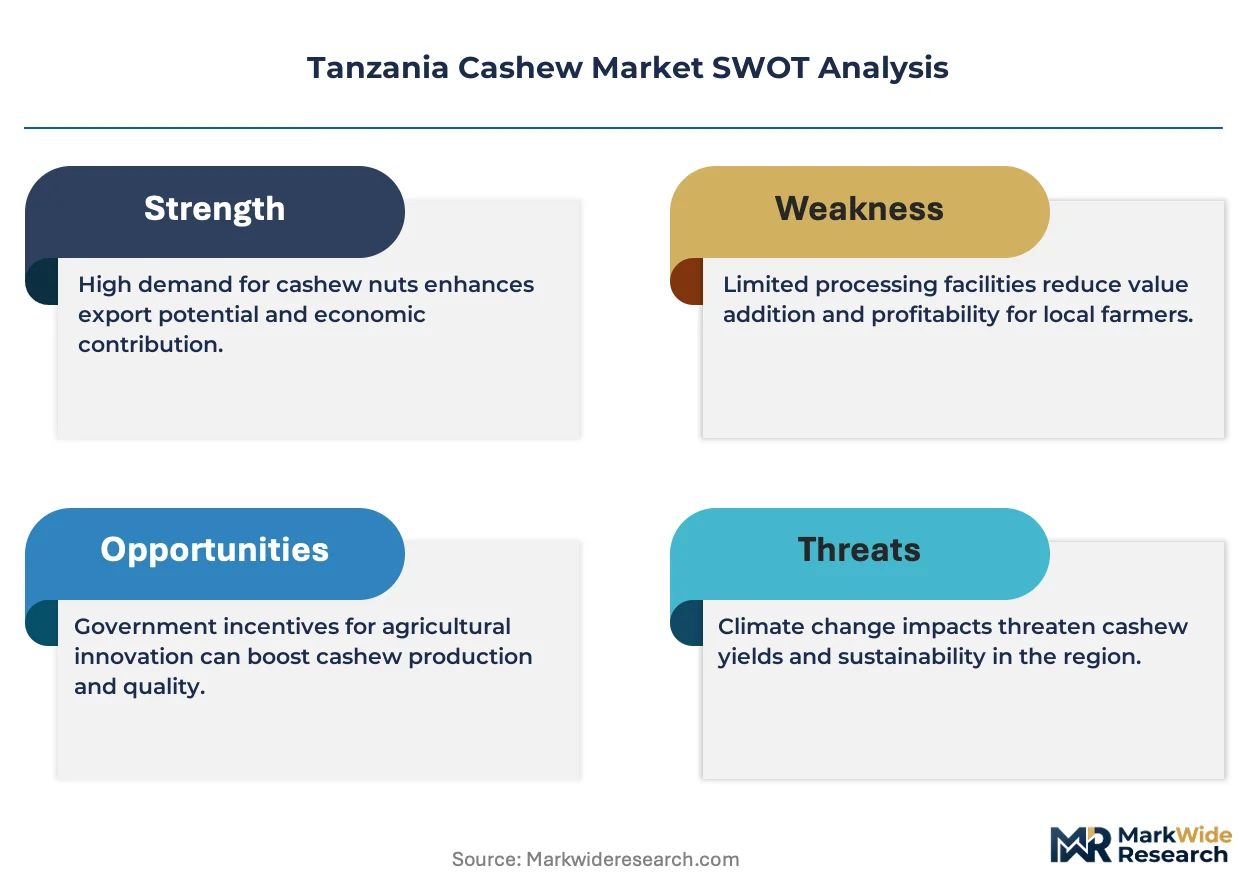
Tanzania cashew comprises the seed and kernel of Anacardium occidentale, typically yielding 22-25 percent kernel content after shelling and moisture reduction to below 5 percent. The crop serves confectionery, snack, and culinary oil applications across Asian, European, and African consumer markets. Raw cashew nuts still dominate export tonnage, though processed cashew kernels command higher unit margins and attract premium offtake from European snack manufacturers. Wet processing infrastructure remains limited relative to dry processing capacity, constraining value-added output expansion despite superior kernel quality recovery.
Tanzania's Cashew Nut Industry Act governs licensing, quality standards, and farmer minimum price floors, while the Tanzania Bureau of Standards enforces kernel grading and aflatoxin thresholds for export eligibility. The Agricultural Seeds Agency regulates planting material certification, directly influencing yield trajectories and farm-gate supply volumes. Stakeholders must monitor processing capacity utilization rates against raw nut export quota allocations, as policy shifts between promoting domestic value addition and preserving foreign exchange liquidity from raw sales reshape investment incentives.
Market Dynamics
Export levy reforms under Tanzania's Cashew Nut Industry Act are rebalancing farmer-processor pricing power, redirecting raw nut flows from bulk export toward domestic shelling facilities in Mtwara and Lindi corridors.
Growth Catalysts
- Snack manufacturer traceability mandates:European confectionery buyers now require farm-origin documentation, pulling orders toward Tanzanian processors with integrated supply chains.
- Cashew Nut Industry Act minimum price floors:Farmer income guarantees stabilize planting decisions and secure long-term raw nut availability for domestic processors.
- Wet processing quality premiums:Superior kernel recovery rates from steam-based shelling methods attract specialty foodservice contracts demanding whole-grade kernels.
Market Restraints
- Raw nut export quota volatility:Foreign exchange liquidity pressures periodically expand raw export allocations, starving domestic processors of feedstock.
- Dry processing capacity dominance:Fire-based shelling infrastructure locks in inferior kernel breakage rates, constraining premium segment participation.
- Indian and Vietnamese trader networks:Established bulk purchasing relationships in Asian spot markets undercut Tanzanian processor price competitiveness.
Strategic Opportunities
- Retail-branded kernel packs:East African supermarket channel expansion enables margin capture beyond commodity kernel sales.
- Culinary oil extraction:Cashew nut shell liquid processing into industrial resins and friction materials diversifies revenue streams.
- Agricultural Seeds Agency certified planting material:High-yielding clonal varieties promise farm-gate volume expansion for integrated processors.
Industry Challenges
- Moisture-controlled storage infrastructure:Aflatoxin compliance requires capital-intensive warehousing upgrades at processor and cooperative levels.
- Shelling mechanic skill scarcity:Wet processing precision demands trained operators absent in regions dominated by seasonal fire-processing labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tanzania Cashew Market |
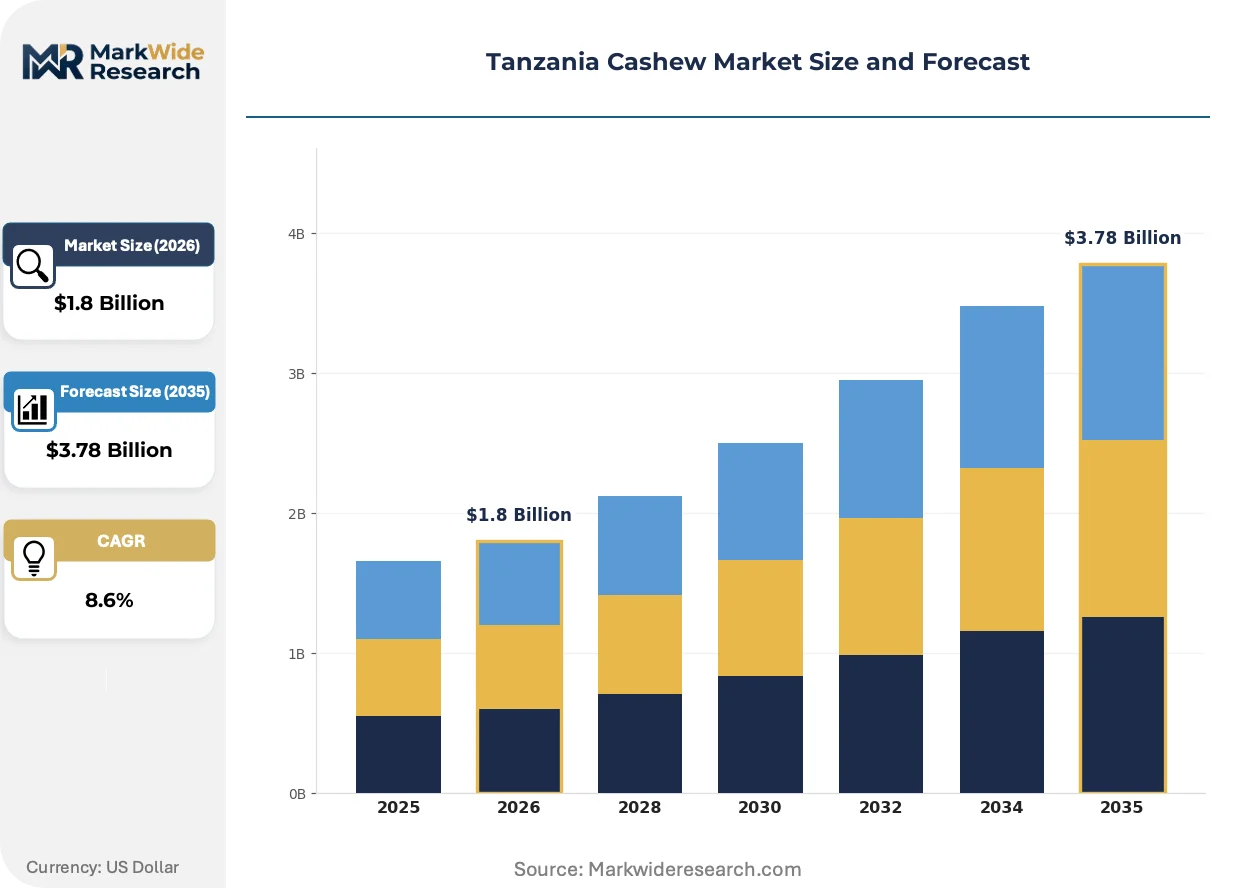
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Cashew Nuts, Processed Cashew Nuts, Cashew Kernel, Cashew Butter End User: Food Industry, Snack Manufacturers, Exporters, Food Service Distribution Channel: Direct Sales, Retail Outlets, Online Sales, Wholesale Processing Method: Dry Processing, Wet Processing, Roasting, Blanching |
| Companies Covered | Cashew Nut Authority of Tanzania, YYTZ, Ahar Group, Zatra, Mtwara Cashew Processing Company, Lindi Cashew Processors, Ruvuma Cashew Nuts Company, Trans Cashew Trading, Azam Cashew Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tanzania Cashew Market Evolving Landscape
Processing technology divergence and procurement model restructuring are compressing legacy trading margins while opening premium capture pathways for integrated operators.
Steam-based wet processing is fragmenting kernel quality hierarchies by enabling whole-grade recovery rates unattainable through conventional fire roasting. Specialty snack manufacturers in Northern Europe are accelerating adoption, locking in multi-year supply agreements with Tanzanian processors demonstrating traceable wet capacity. This quality stratification is fragmenting the commodity kernel market into distinct premium and standard tiers with diverging price formation mechanisms.
Tanzania Bureau of Standards aflatoxin threshold enforcement is tightening export eligibility criteria, disqualifying non-compliant batches from European foodservice channels. Processors must now maintain laboratory testing infrastructure or forfeit premium market access. Small-scale dry processors in peripheral growing districts face disproportionate compliance burdens, accelerating consolidation toward Mtwara and Lindi coastal facilities.
Direct contracting between processors and farmer cooperatives is displacing auction-based raw nut sales. This channel shift reduces price volatility exposure for planting decisions while securing predictable feedstock for shelling facilities. The cooperative-processor linkage model concentrates most visibly in Lindi District, where Agricultural Seeds Agency extension networks facilitate structured procurement relationships.
Tanzania Cashew Market Segmentation
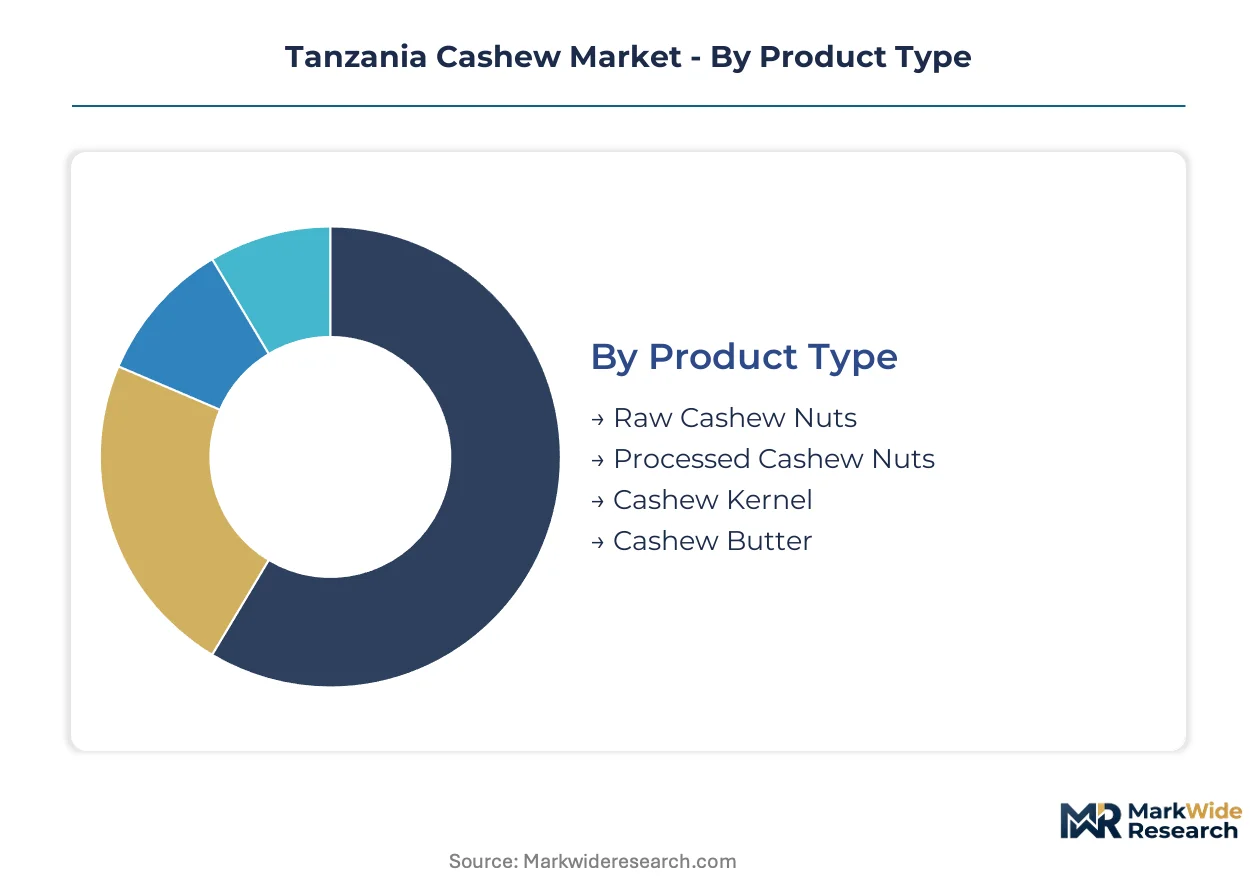
Segmentation in the Tanzania cashew market reveals how regulatory frameworks and processing capabilities fragment revenue capture across distinct value chain positions. Each dimension exposes different compliance burdens and margin structures that determine competitive positioning.
Product Type:
Tanzania Bureau of Standards enforces divergent aflatoxin thresholds and grading protocols across product categories, creating tiered export eligibility that shapes processor investment decisions.
- Raw Cashew Nuts:Unprocessed in-shell nuts with moisture content typically ranging 8-10 percent at harvest. Exporters dominate this segment through auction-based procurement in Mtwara and Lindi corridors, though Cashew Nut Industry Act levy reforms are redirecting volumes toward domestic shelling facilities.
- Processed Cashew Nuts:Shelled nuts with testa intact, requiring mechanical decortication and moisture reduction below 5 percent. European snack manufacturers concentrate procurement here, demanding Tanzania Bureau of Standards certification and farm-origin traceability documentation that only integrated processors can reliably supply.
- Cashew Kernel:Blanched or unblanched edible kernels graded by size and color. Commodity traders in Asian spot markets absorb standard grades while specialty foodservice contracts command premiums for whole-grade recovery.
- Cashew Butter:Ground paste formulation for confectionery and spread applications. Emerging demand from East African supermarket channels drives small-batch production, though scale constraints limit processor participation.
Raw Cashew Nuts handles the majority of throughput; Cashew Kernel is gaining share fastest as export levy incentives redirect feedstock toward domestic value addition.
End User:
Customer procurement models range from commodity spot purchasing to multi-year supply agreements with embedded compliance requirements, fragmenting pricing power across the demand base.
- Food Industry:Confectionery and bakery manufacturers requiring consistent kernel sizing and aflatoxin documentation. Tanzania Bureau of Standards enforcement has tightened eligibility, disqualifying small-scale dry processors from premium contracts.
- Snack Manufacturers:Roasted and flavored kernel packers with traceability mandates. Direct contracting with Mtwara and Lindi processors is displacing traditional Indian and Vietnamese trader intermediation.
- Exporters:Bulk commodity traders shipping raw nuts to Asian shelling centers. Foreign exchange liquidity pressures periodically expand their quota allocations under Cashew Nut Industry Act provisions.
- Food Service:Restaurants and institutional kitchens sourcing whole-grade kernels for culinary applications. Wet processing quality premiums attract this segment toward steam-based shelling output.
Food Industry commands the highest compliance investment; Snack Manufacturers are expanding most quickly as European traceability mandates accelerate.
Distribution Channel:
Channel selection determines working capital intensity and price discovery transparency, with coastal infrastructure proximity favoring certain modes over others.
- Direct Sales:Processor-to-manufacturer contracting without intermediary traders. Cooperative-processor linkages in Lindi District exemplify this channel's growth under Agricultural Seeds Agency extension facilitation.
- Retail Outlets:Branded kernel packs through East African supermarket networks. Azam Cashew Industries and similar integrated operators capture margin premiums unavailable in commodity sales.
- Online Sales:Digital platforms for specialty and gift-packaged kernels. Limited penetration due to logistics constraints in southern growing districts.
- Wholesale:Aggregated bulk sales to regional traders. Auction-based systems still dominate raw nut flows despite cooperative displacement trends.
Direct Sales carries the largest volume commitment; Retail Outlets show the steepest expansion trajectory as branded distribution deepens in urban East African markets.
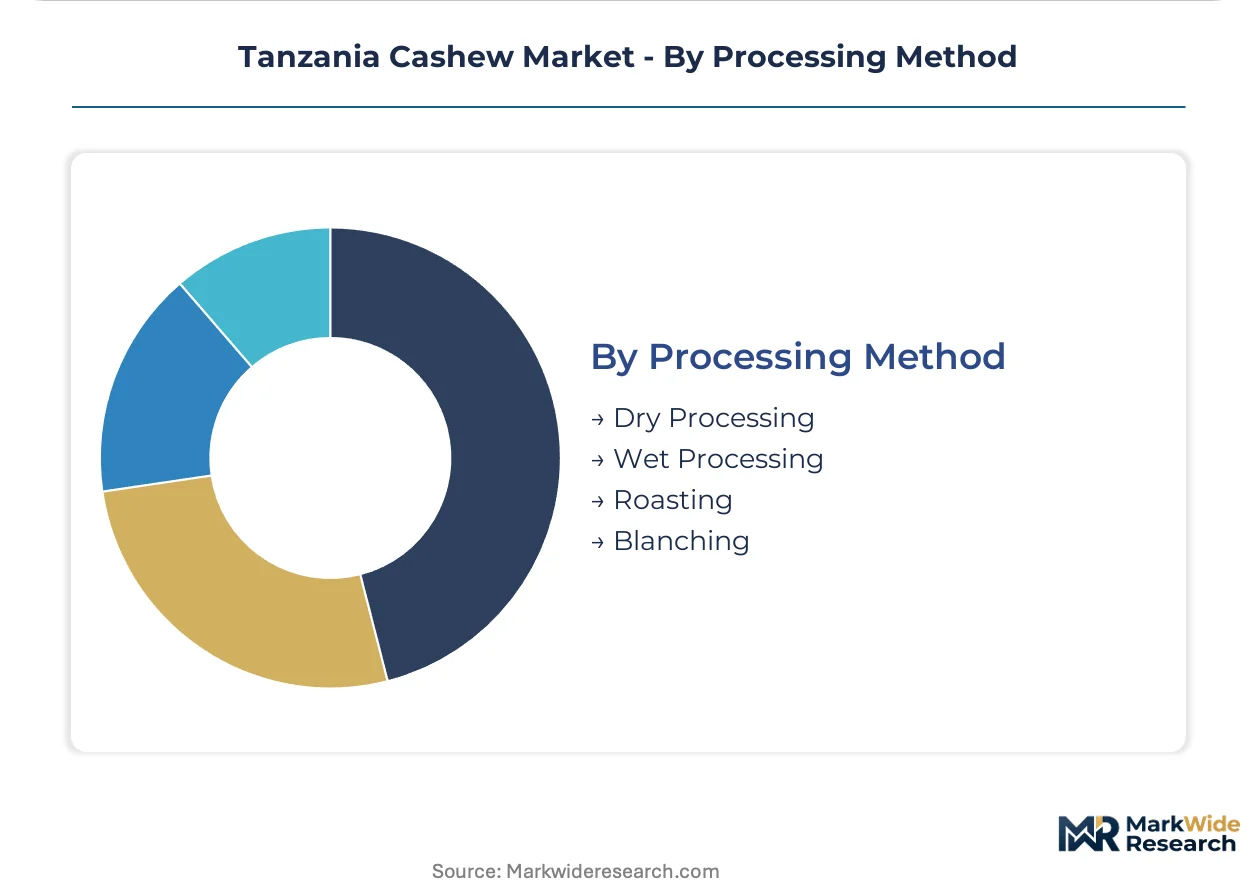
Processing Method:
Technology choice locks in kernel quality recovery rates and determines premium market access, with capital requirements creating structural barriers between methods.
- Dry Processing:Fire-based roasting and shelling with higher kernel breakage rates. Dominates installed capacity in peripheral growing districts but faces Tanzania Bureau of Standards aflatoxin compliance challenges.
- Wet Processing:Steam-based shelling enabling superior whole-grade recovery. Mtwara coastal facilities concentrate this capacity, attracting specialty foodservice contracts with quality premiums.
- Roasting:Thermal treatment for flavor development and shelf stability. Snack manufacturers specify roast profiles in direct supply agreements.
- Blanching:Testa removal through heat and abrasion. Required for confectionery-grade kernel output, adding processing cost that standard commodity channels rarely justify.
Dry Processing retains the widest installed base; Wet Processing is climbing the fastest as European buyers lock in traceable supply agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European snack manufacturers with traceability mandates concentrate procurement in Tanzania's southern processing belt, while Asian commodity traders anchor spot-market demand for raw nut exports. This buyer-archetype split shapes infrastructure investment patterns across the country's cashew-growing regions.
Mtwara Region
Coastal processing facilities serve European confectionery buyers requiring Tanzania Bureau of Standards certification and farm-origin documentation. The Cashew Nut Industry Act export levy reforms redirect raw nut flows from bulk export toward domestic shelling infrastructure. Mtwara Cashew Processing Company anchors volume output through facility proximity to raw nut sourcing clusters along the southern corridor.
Lindi Region
Direct contracting between processors and farmer cooperatives displaces auction-based sales, reducing price volatility for planting decisions. Agricultural Seeds Agency extension networks facilitate structured procurement relationships in Lindi District. Wet processing capacity concentrates here, attracting specialty foodservice contracts demanding whole-grade kernel recovery.
Ruvuma Region
Peripheral growing districts supply raw nuts to coastal processors, though limited wet processing infrastructure constrains premium segment participation. Dry processing dominance locks in inferior kernel breakage rates relative to steam-based methods. Ruvuma Cashew Nuts Company exemplifies the trader-processor hybrid model bridging farm-gate aggregation and export channels.
Pwani Region
Logistics corridors connecting southern growing belts to Dar es Salaam port infrastructure enable raw nut export quota fulfillment during foreign exchange liquidity pressures. Coastal warehousing investments address moisture-controlled storage requirements for aflatoxin compliance. Trans Cashew Trading operates procurement networks spanning Pwani access routes to Asian spot markets.
Tanzania Cashew Market Competitive Landscape
Player mix skews toward integrated processor-exporters with traceable supply chains and cooperative-linked procurement networks. Market structure fragments across dry processing specialists in peripheral districts and wet processing concentrators in coastal corridors. Strategic archetypes include auction-based bulk traders, cooperative-integrated processors, and retail-branded packagers. Competitive moves center on cooperative contracting displacement of auction systems and wet processing capacity expansion for European premium contracts.
Within the integrated processor tier, YYTZ leverages its processing and export license positioning, while Azam Cashew Industries exemplifies retail-branded distribution through East African supermarket channels. Mtwara Cashew Processing Company anchors volume-focused operations. These three represent distinct archetypes: traceability-integrated supply chain control, downstream brand margin capture, and coastal infrastructure scale concentration.
| Leading Market Players |
|---|
| Cashew Nut Authority of Tanzania |
| YYTZ |
| Ahar Group |
| Zatra |
| Mtwara Cashew Processing Company |
| Lindi Cashew Processors |
| Ruvuma Cashew Nuts Company |
| Trans Cashew Trading |
| Azam Cashew Industries |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day raw nut inventory cycles at Mtwara coastal processors compress farm-gate price discovery windows while amplifying bargaining power for integrated operators with moisture-controlled warehousing. This lead-time band concentrates margin capture among wet processing facilities that can bridge harvest seasonality against European snack manufacturer contract timelines.
Pricing Analysis
Fire-based dry processing versus steam-based wet processing creates a technology-generation pricing gap that separates commodity kernel traders from premium whole-grade suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks kernel breakage rates and Tanzania Bureau of Standards certification tiers, with European traceability mandates compressing margins in standard grades. Cost compression in dry-processed output is intensifying because Indian and Vietnamese trader networks undercut coastal processor offers in Asian spot markets. Exporters absorbing raw nuts for bulk shipment display highest price sensitivity, while specialty foodservice buyers lock in long-term premiums for wet-processed whole kernels.
Supply Chain Analysis
Strategic stockpile preferences among European confectionery buyers favor processors with six-month forward contracting capacity over just-in-time auction participants. Geographic supply concentrates in Tanzania's southern belt, with secondary dependencies on Vietnamese and Indian shelling capacity for overflow raw nut volumes. Raw material flows hinge on Agricultural Seeds Agency certified planting material, fire-processed feedstock from Ruvuma periphery districts, and imported steam-processing equipment. Single-source vulnerability sits with Dar es Salaam port logistics corridors during foreign exchange liquidity-driven export quota expansions. Distribution runs through cooperative-processor direct linkages in Lindi and auction-based wholesale channels in Mtwara.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tanzania's cashew sector tracks a cyclical recovery anchored to Cashew Nut Industry Act minimum price floor stabilization of farmer planting decisions after years of export quota volatility.
For Market Incumbents: Consolidate wet processing capacity in Mtwara and Lindi corridors to capture European traceability contract premiums before fire-based competitors achieve Tanzania Bureau of Standards laboratory compliance. Threat of Indian trader network price undercutting demands backward integration into cooperative procurement networks that lock in harvest-season feedstock. Priority lever rests on Agricultural Seeds Agency extension partnerships that secure certified high-yielding clonal variety distribution rights. For New Entrants and Emerging Players: Tanzania Bureau of Standards certification fast-track investment opens white-space penetration in cashew butter and retail-branded kernel packs for East African supermarket channels. Most penetrable segment sits in culinary oil extraction from cashew nut shell liquid for industrial resin applications, where incumbent processors lack dedicated refining infrastructure. Go-to-market angle centers on direct e-commerce platforms for gift-packaged specialty kernels bypassing wholesale auction systems. For Investors and Strategic Acquirers: Long-term, this sits as a value-add processing infrastructure play because export levy reforms structurally redirect raw nut flows from bulk export toward domestic shelling facilities over the projection horizon. Acquisition target archetype encompasses cooperative-integrated processors with existing Tanzania Bureau of Standards certification and underutilized wet capacity in Lindi District. Signal to watch is Cashew Nut Industry Act quota allocation announcements that reveal foreign exchange liquidity pressures starving domestic processors.| Strategic Initiative | Industry Significance |
|---|---|
| Wet Processing Capacity Expansion | Steam-based shelling enables whole-grade kernel recovery rates unattainable through fire roasting, attracting European premium contracts. |
| Cooperative Procurement Integration | Direct contracting with farmer cooperatives displaces auction volatility and secures predictable feedstock for shelling facilities. |
| Tanzania Bureau of Standards Certification Investment | Laboratory testing infrastructure unlocks European foodservice channel eligibility that dry processors forfeit. |
| Retail-Branded Kernel Pack Launch | East African supermarket distribution captures margin premiums unavailable in commodity kernel spot sales. |
| Cashew Nut Shell Liquid Refining Partnership | Industrial resin and friction material applications diversify revenue beyond edible kernel commodity cycles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Cashew Nut Industry Act regulatory filings, Tanzania Bureau of Standards export certification databases, and Agricultural Seeds Agency variety registration records. Primary interviews incorporated cashew processing plant managers, farmer cooperative procurement officers, European snack manufacturer sourcing leads, and Mtwara-Lindi logistics operators. Secondary validation drew from customs export data, Tanzania Revenue Authority levy collection statistics, and regional agricultural extension reports. Bottom-up volume modeling triangulated against top-down value estimates across the analysis window.
Segmentation dimensions modeled span product type, end user, distribution channel, and processing method, with kernel quality grade and geographic processing corridor as cross-cutting industry-specific variables. Volume and value outputs reflect iterative reconciliation of raw nut harvest estimates, shelling capacity utilization assumptions, and export quota allocation scenarios throughout the forecast period. CAGRs derived from trend extrapolation of farmer price floor responsiveness, European traceability mandate adoption curves, and wet processing infrastructure deployment timelines.
Underlying assumptions cover Cashew Nut Industry Act policy continuity, Tanzania Bureau of Standards aflatoxin threshold stability, and Agricultural Seeds Agency certified material distribution scaling, with deviation risk concentrated in foreign exchange liquidity-driven raw export quota volatility and Indian-Vietnamese trader network pricing aggression. Revision becomes warranted when export levy reform implementation crosses thresholds that structurally alter farmer-processor pricing power balance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Global Medicated Feed Market
Agriculture and Agri Products
Bamboos Market
Agriculture and Agri Products
Tissue Cultured Date Palm Market
Agriculture and Agri Products
Residential Organic Compost Market
Agriculture and Agri Products
E-Commerce of Agricultural Products Market
Agriculture and Agri Products
Lucerne Market
Agriculture and Agri Products
France Compound Feed Market
Agriculture and Agri Products
India Palm Oil Market
Agriculture and Agri Products
Ethiopia Agriculture Sector Market
Agriculture and Agri Products
North America Aloe Vera Market
Agriculture and Agri Products
Asia-Pacific Poultry Meat Market
Agriculture and Agri Products
Poultry Processing Product Market
Agriculture and Agri Products
South America Animal Protein Market
Agriculture and Agri Products
Inulin Market
Agriculture and Agri Products
Floriculture Market
Agriculture and Agri Products
Italy Alfalfa Market