
 Tractor Rental Market | 2026-2036
Tractor Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Tractor Rental Market Outlook
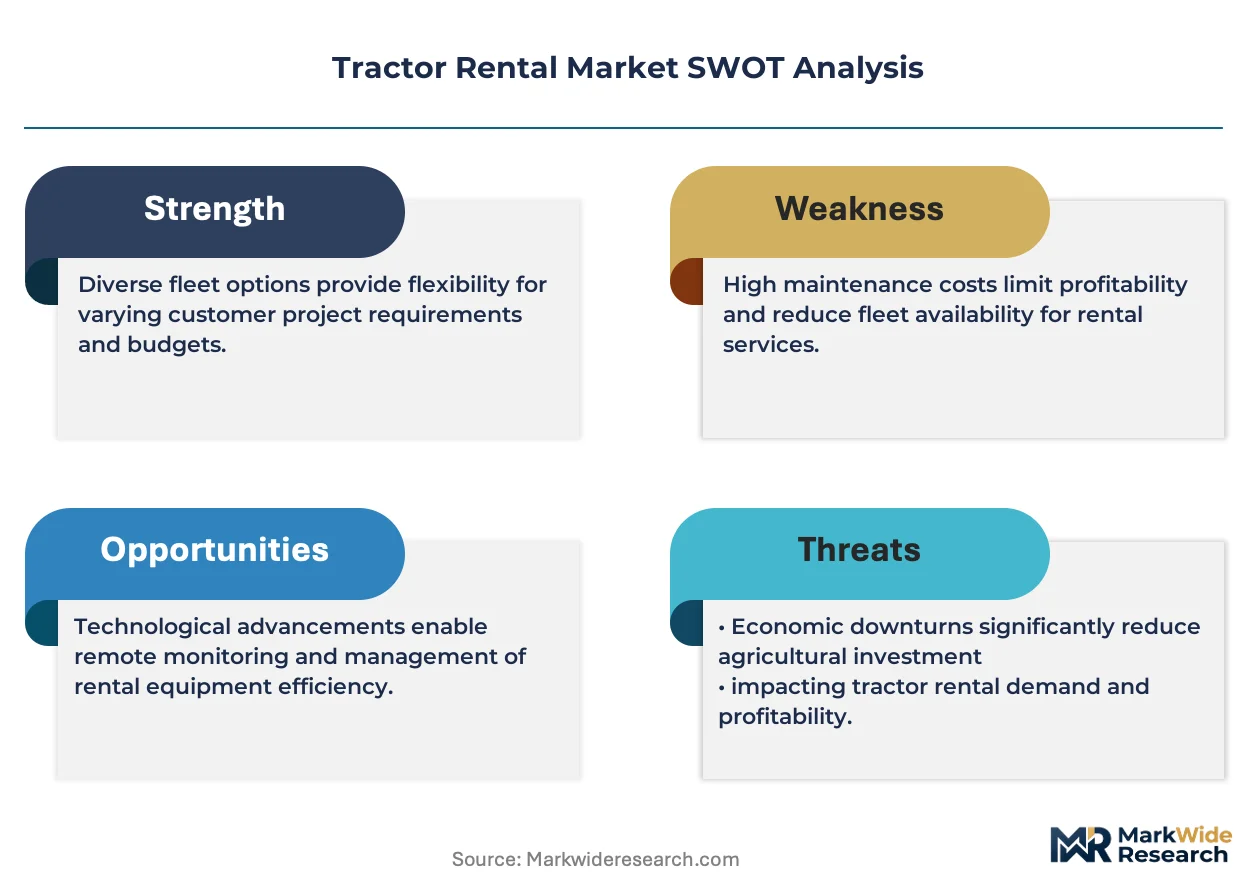
Asset-light operating lease structures is narrowing the capital barrier for mid-sized agricultural contractors seeking Tier 4 Final and Stage V compliant machinery. Deere & Company leverages its captive finance arm to bundle precision agriculture telemetry with rental contracts. CNH Industrial anchors its European rental network through Case IH and New Holland brand depots in France and Germany. Kubota Corporation specializes in compact tractor sub-50 horsepower segments for orchard and vineyard applications.
Tractor rental denotes the short-to-medium term provision of self-propelled agricultural or utility vehicles powered by diesel, electric, or hybrid drivetrains, typically rated by engine horsepower and hitch category, for soil preparation, material handling, or towing implements without transfer of ownership. The primary commercial purpose centers on converting fixed equipment costs into variable operating expenses while granting operators access to precision guidance, telematics, and emissions-compliant engines without residual value risk. Utility tractors occupy the largest margin pool due to cross-sector deployment across agriculture, construction, and municipal maintenance. Compact tractors represent the fastest-growing product type as hobby farms and landscaping contractors scale equipment access without dealership purchase commitments. Lease-to-own service structures concentrate in agricultural sector end users seeking pathway ownership after multi-season rental trials.
EPA Tier 4 Final and EU Stage V emissions frameworks from the respective environmental regulators mandate diesel particulate filter and selective catalytic reduction installation on rental tractors above 56 kilowatts, elevating fleet refresh costs and shortening holding periods for older inventory. OSHA agricultural safety directives and ISO 3600 rollover protective structure standards shape operator training requirements and liability exposure for rental fleet owners across state and national jurisdictions. Stakeholders must monitor electrification roadmaps from original equipment manufacturers and corresponding charging infrastructure buildouts to assess when battery-electric tractor rental economics displace diesel parity in specific horsepower bands.
Market Dynamics
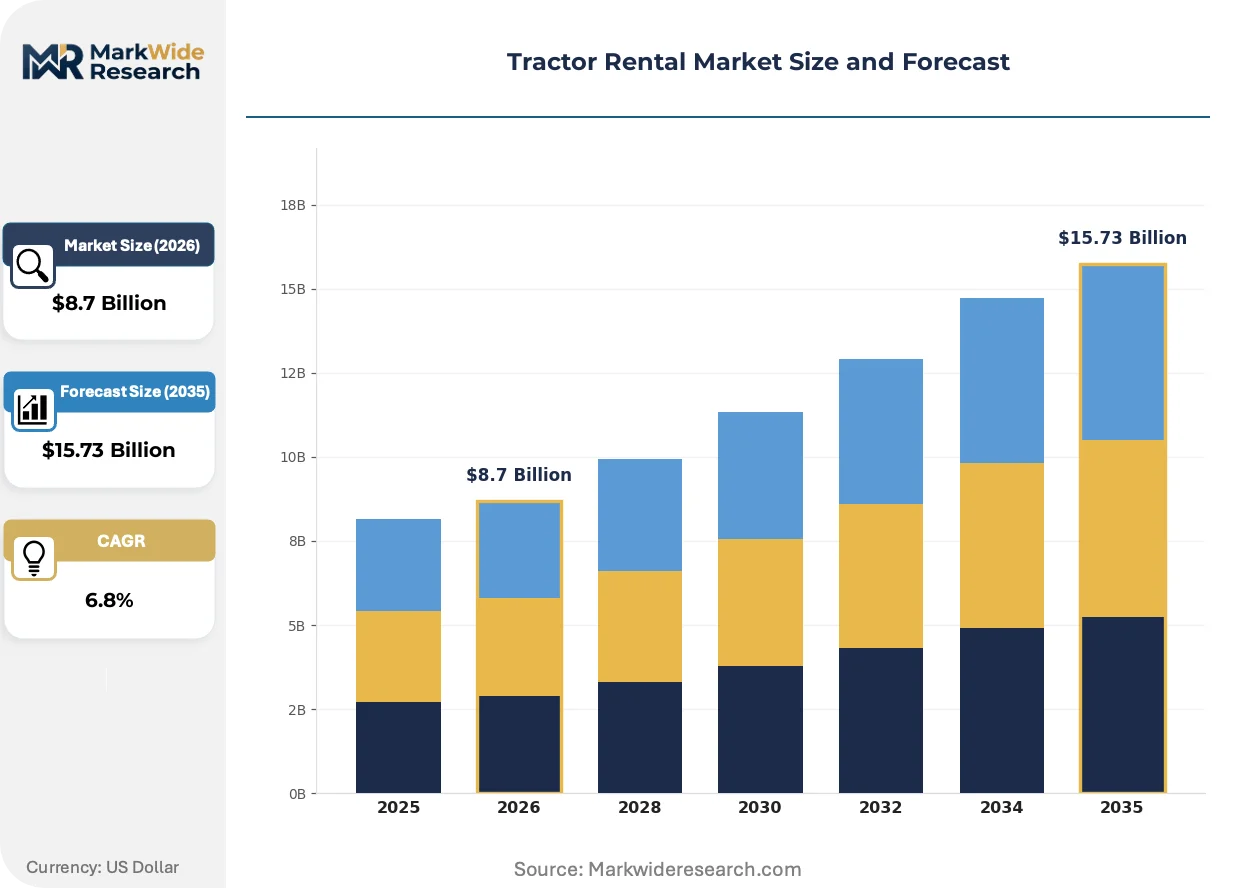
Asset-light operating models are compressing capital barriers for agricultural contractors seeking emissions-compliant machinery without residual value exposure, while EPA Tier 4 Final and EU Stage V mandates accelerate fleet refresh cycles across rental portfolios.
Growth Catalysts
- Emissions compliance mandates:EPA Tier 4 Final and EU Stage V regulations compel rental providers to modernize diesel inventories with particulate filter and selective catalytic reduction systems, creating replacement demand for older tractors.
- Midwest agricultural concentration:Row-crop farming and infrastructure project overlap in the Midwestern United States generates sustained equipment utilization rates that justify rental fleet expansion.
- Precision agriculture bundling:Telemetry and guidance system integration into rental contracts converts fixed technology investments into variable operating expenses for commercial operators.
Market Restraints
- Diesel engine cost escalation:Aftertreatment system requirements for Tier 4 Final and Stage V compliance inflate new equipment acquisition costs by fifteen to twenty-five percent, compressing rental provider margins.
- Charging infrastructure deficit:Battery-electric tractor viability remains constrained by rural electrical grid capacity and the absence of fast-charging networks at agricultural depots and job sites.
- Residual value uncertainty:Accelerated emissions standard transitions shorten economically viable holding periods for diesel assets, elevating fleet depreciation risk.
Strategic Opportunities
- Orchard and vineyard mechanization:Compact sub-50 horsepower tractor demand from specialty crop producers in France, Italy, and Spain remains underpenetrated by structured rental programs.
- Lease-to-own pathway structures:Multi-season rental trials with embedded purchase options address agricultural end users seeking equipment familiarity before ownership commitment.
- Municipal maintenance cross-deployment:Utility tractor versatility across construction, landscaping, and public works expands addressable rental demand beyond traditional agricultural seasonality.
Industry Challenges
- Telematics integration complexity:Retrofitting legacy rental fleets with ISO 11783-compatible precision agriculture systems requires specialized technical labor and extended downtime.
- Operator certification fragmentation:OSHA agricultural safety directives and state-level rollover protective structure training requirements create jurisdictional compliance overhead for multi-state rental operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tractor Rental Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Tractors, Utility Tractors, Orchard Tractors, Garden Tractors End User: Agricultural Sector, Construction Industry, Landscaping, Municipalities Deployment: On-Site Rental, Off-Site Rental, Short-Term Rental, Long-Term Rental Service Type: Standard Rental, Lease-to-Own, Maintenance Services, Delivery Services |
| Companies Covered | Deere & Company, CNH Industrial, AGCO Corporation, Kubota Corporation, Mahindra & Mahindra, Titan Machinery, The Papé Group, Farmease, Pacific AG Rentals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tractor Rental Market Strategic Shifts
Electrification roadmaps and precision agriculture convergence are restructuring equipment utilization economics, while regulatory emissions frameworks compress diesel asset lifecycles and procurement patterns shift toward outcome-based access models.
Autonomous guidance systems integrating RTK-GPS correction with implement control are rendering obsolete manual steering in broad-acre row-crop applications. Large-scale commercial farming operations in the United States and Brazil are adopting these systems through rental channels to avoid capital lock-in. The technology is rendering obsolete traditional hourly-rate rental structures in favor of per-acre performance contracts.
EU Stage V emissions frameworks mandate diesel particulate filter and selective catalytic reduction installation on all rental tractors above 56 kilowatts, elevating fleet refresh costs and shortening holding periods. Rental providers in Germany and France are responding by consolidating depot networks to achieve scale economies in maintenance and compliance documentation. Compact tractor segments below the power threshold are experiencing demand diversion as operators seek to circumvent aftertreatment complexity.
Outcome-based equipment access contracts are replacing traditional fixed-term leases in North American agricultural markets. Contractors now specify soil preparation or planting completion metrics rather than machine-hour commitments, transferring operational risk to rental providers. This shift concentrates most visibly in the Midwestern United States where precision agriculture telemetry enables performance verification.
Tractor Rental Market Segmentation
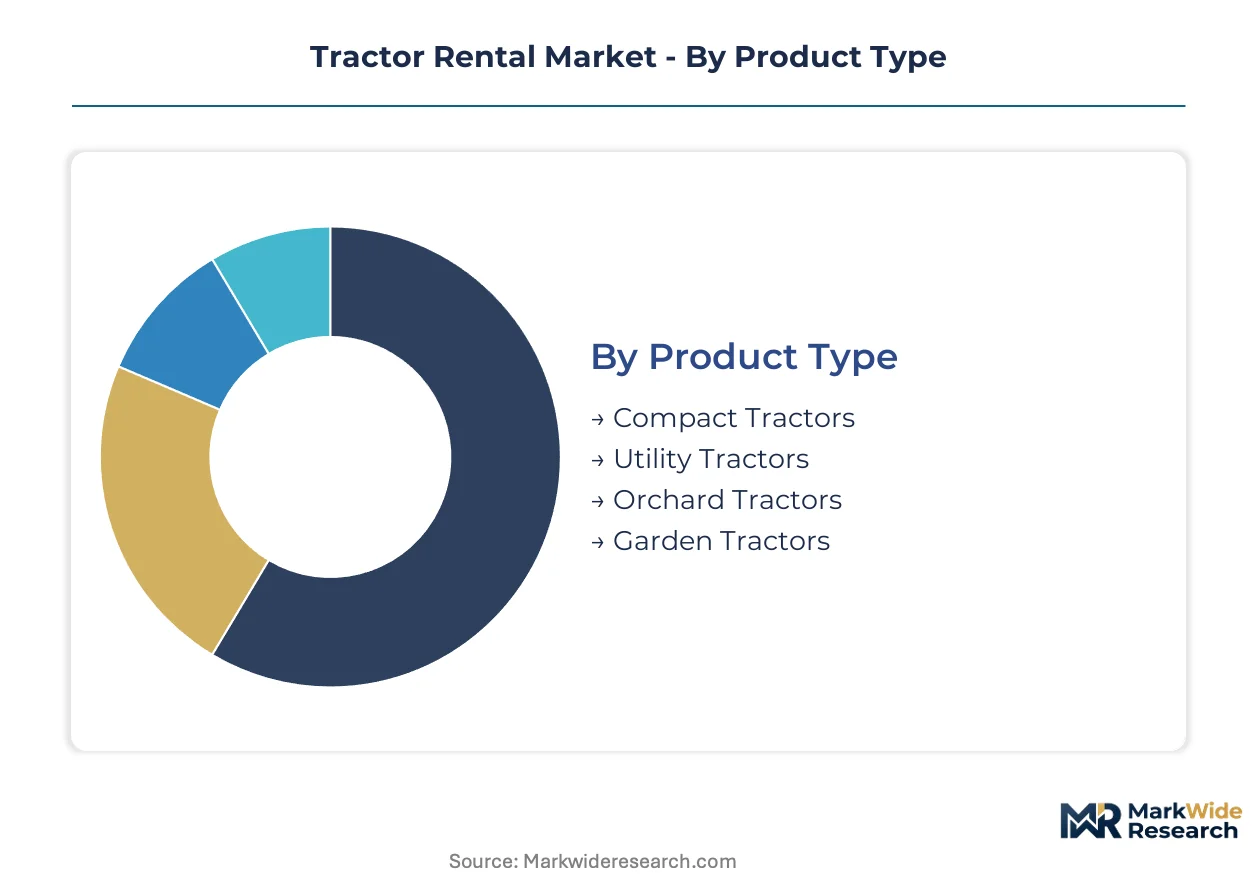
Tractor rental segmentation reveals how equipment specifications, user economics, and contract structures intersect. Understanding these dimensions clarifies where rental providers can extract premium returns versus where commoditization pressures dominate.
Product Type:
Use-case spectrum spans hobby-scale soil preparation through commercial broad-acre operations to specialized narrow-row crop systems.
- Utility Tractors:Multi-purpose machines typically rated 50-100 horsepower with three-point hitch and PTO capability for implement versatility. Midwestern United States row-crop contractors generate sustained utilization through cross-season deployment across tillage, planting, and grain handling operations. Rental providers capture margin premiums through precision agriculture telemetry bundling.
- Compact Tractors:Sub-50 horsepower units designed for maneuverability in confined spaces with hydrostatic transmission standard. Hobby farms and landscaping contractors in suburban fringe zones drive adoption as property maintenance complexity rises without justifying purchase capital. These units expand most quickly as asset-light operating models penetrate non-agricultural customer bases.
- Orchard Tractors:Narrow-profile designs with protective frames for tree and vine row navigation, predominantly diesel-powered with creep-speed gearing for harvest implement compatibility.
- Garden Tractors:Light-duty residential-grade equipment for lawn maintenance and light soil work, typically gasoline-powered with limited implement compatibility.
Established volume favors utility tractors; emerging adoption favors compact tractors.
End User:
Customer economics range from seasonal cash-flow constraints to capital-project budgeting cycles with divergent contract preferences.
- Agricultural Sector:Commercial farming operations, specialty crop producers, and agricultural contractors requiring seasonal equipment access without residual value exposure. Midwestern grain operations concentrate demand for high-horsepower utility fleets, while California Central Valley specialty crop growers drive orchard tractor requirements. Tier 4 Final compliance costs accelerate rental preference over ownership.
- Construction Industry:General contractors and earthmoving specialists deploying tractors for material handling, site preparation, and light grading tasks. Municipal infrastructure project timing in the United States generates demand spikes that rental structures accommodate more flexibly than ownership.
- Landscaping:Commercial grounds maintenance firms and residential estate managers seeking compact tractor access for seasonal property enhancement without dealership purchase commitments.
- Municipalities:Public works departments maintaining parks, road shoulders, and snow removal operations with budget cycles favoring operating expense treatment over capital appropriations.
Revenue concentration sits with agricultural sector; diversification opportunity concentrates in municipal accounts.
Deployment:
Logistics configuration determines fleet utilization rates and transport cost recovery mechanics across customer touchpoints.
- On-Site Rental:Equipment delivered to and operated at customer premises with provider retaining ownership and maintenance responsibility. Large-scale farming operations in Brazil and the United States prefer this structure for extended seasonal access with performance-based contract terms.
- Off-Site Rental:Customer pickup from provider depot locations requiring operator transport capability and insurance coverage transfer. European rental networks in France and Germany consolidate around this model to achieve maintenance scale economies.
- Short-Term Rental:Daily to weekly contract structures for peak season surge capacity or specialized implement testing.
- Long-Term Rental:Multi-month or seasonal agreements with embedded maintenance and telemetry service inclusion.
Margin stability favors long-term structures; volume elasticity concentrates in short-term deployment.
Service Type:
Contract architecture determines capital recovery timelines and customer relationship duration across the ownership spectrum.
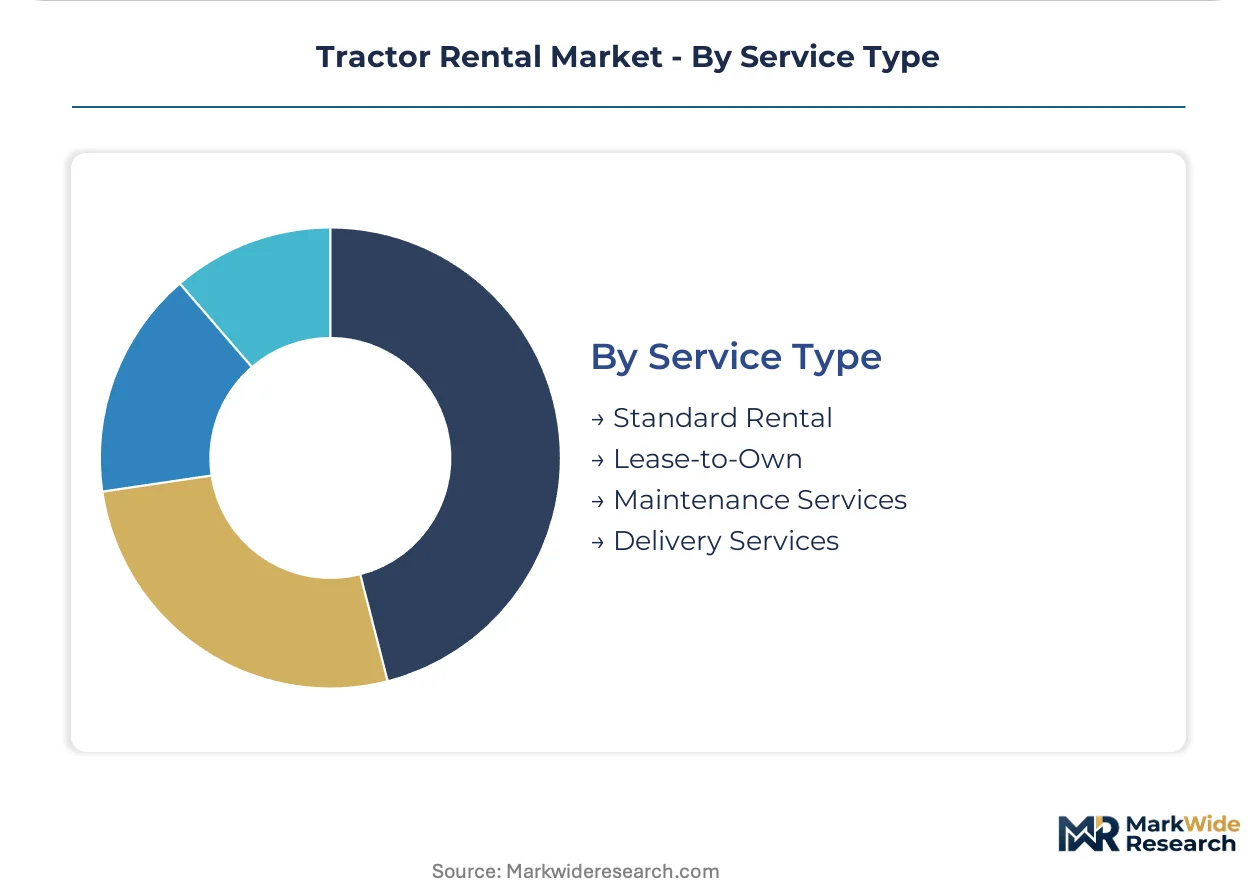
- Standard Rental:Fixed-term equipment access with hourly or daily rate structures, maintenance included, fuel typically excluded. This structure dominates commercial agricultural applications where utilization predictability supports rate card pricing.
- Lease-to-Own:Multi-season rental trials with embedded purchase options allowing equipment familiarity before ownership commitment. Agricultural end users in the United States increasingly prefer this pathway as emissions compliance complexity elevates purchase risk.
- Maintenance Services:Extended service contracts bundled with rental agreements or offered standalone for customer-owned fleets.
- Delivery Services:Transport logistics and operator training inclusion as contract add-ons or standalone offerings.
Retention economics favor lease-to-own structures; transaction velocity concentrates in standard rental.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where precision telemetry bundling commands rate premiums, while European markets compress margins through depot network consolidation and compliance documentation burdens.
United States
Midwestern row-crop operations in Iowa, Illinois, and Indiana generate sustained equipment utilization through overlapping agricultural and infrastructure cycles. EPA Tier 4 Final mandates accelerate fleet refresh timelines for rental providers serving grain belt contractors. Chicago and Minneapolis-St. Paul logistics clusters anchor equipment redistribution networks for seasonal demand surges.
Germany
Stage V compliance requirements elevate maintenance complexity for rental fleets serving Bavarian and Lower Saxony farming cooperatives. The country's federal motor transport authority enforces strict documentation protocols for commercial vehicle emissions testing. Stuttgart and Munich industrial corridors concentrate precision agriculture technology integration services for rental contract bundling.
Brazil
Mato Grosso and Goiás soybean belt expansion drives demand for high-horsepower utility tractors through operating lease structures. ANVISA agricultural machinery safety standards intersect with state-level environmental licensing for large-scale farming operations. São Paulo financial services cluster develops embedded credit products for multi-season rental-to-own pathways.
France
Specialty crop producers in Provence-Alpes-Côte d'Azur and Nouvelle-Aquitaine seek compact tractor access for vineyard mechanization without purchase capital commitment. EU Stage V regulations divert demand toward sub-56 kilowatt equipment categories exempt from aftertreatment requirements. Lyon and Bordeaux equipment depots consolidate maintenance scale economies across fragmented regional farming structures.
India
Maharashtra and Gujarat contract farming arrangements expand rental penetration among smallholder aggregators seeking mechanization without ownership risk. The Central Electricity Authority grid reliability standards constrain battery-electric tractor deployment in rural districts. Pune and Ahmedabad manufacturing corridors localize sub-50 horsepower production for cost-competitive rental fleet supply.
Tractor Rental Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the attachment and precision agriculture technology layers. The vendor base organizes around three archetypes: full-line original equipment manufacturers with captive finance arms, regional dealership networks with consolidated rental portfolios, and digital marketplace platforms connecting fragmented equipment supply with spot demand. Consolidation pressures intensify as emissions compliance costs favor scale economies in fleet management and maintenance documentation. Dominant competitive moves include backward integration into telematics development and geographic tuck-in acquisitions of independent rental operators.
Among manufacturer-anchored platforms, Deere & Company exemplifies the integrated finance-plus-telemetry archetype through its captive leasing structures. CNH Industrial occupies a position spanning multiple brand depots across European consolidation networks. Kubota Corporation represents specialization in compact equipment segments below regulatory power thresholds. These three anchors illustrate divergent strategic postures: full-system bundling, multi-brand geographic density, and sub-segment focus.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial |
| AGCO Corporation |
| Kubota Corporation |
| Mahindra & Mahindra |
| Titan Machinery |
| The Papé Group |
| Farmease |
| Pacific AG Rentals |
| Others |
Value Chain & Pricing Dynamics
Japanese and German diesel engine component suppliers anchor Tier 4 Final aftertreatment system production, concentrating margin capture upstream while rental providers downstream absorb fifteen to twenty-five percent equipment cost escalation. This supplier concentration shifts pricing power toward emissions-compliant subsystem manufacturers and away from fleet operators managing residual value risk on depreciating diesel assets.
Pricing Analysis
The configured-to-order premium for precision agriculture telemetry bundling runs fifteen to twenty percent above standard hourly-rate rental contracts. Three-tier pricing structure across premium telemetry-inclusive, standard maintenance-bundled, and economy bare-equipment levels captures divergent buyer sophistication. Price differentiation hinges on ISO 11783 compatibility certification and geographic delivery distance from depot clusters. Cost compression in the economy tier is intensifying because sub-56 kilowatt equipment demand diverts from aftertreatment complexity. Municipal maintenance departments exhibit highest price sensitivity due to budget-cycle constraints, while large-scale commercial farming operations in the Midwestern United States show lowest sensitivity given performance-based contract preference.
Supply Chain Analysis
Export-control regimes on precision GPS and RTK correction technology limit autonomous guidance system flows to certain agricultural markets. Manufacturing concentration rests on Japan for compact tractor powertrains, Germany for precision agriculture electronics, and the United States for high-horsepower utility platforms. Raw material dependencies include high-strength steel for rollover protective structures, rare earth elements for electric drivetrain motors, and semiconductor components for telematics modules. Single-source vulnerability concentrates in RTK-GPS base station networks and selective catalytic reduction catalyst substrates. Distribution runs through manufacturer-anchored depot networks in consolidated European markets and independent dealership channels in fragmented North American regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tractor rental market tracks a cyclical recovery pattern as agricultural capital expenditure cycles turn following commodity price stabilization and Midwestern grain belt expansion. Equipment replacement demand from Tier 4 Final compliance deadlines reinforces this cyclical upturn.
For Market Incumbents: Insulate fleet margin structures by backward integration into telematics development and captive maintenance service networks. Consolidate geographic tuck-in acquisitions of independent rental operators in the Midwestern United States to achieve scale economies in compliance documentation. Electrification roadmap uncertainty from original equipment manufacturers poses substitution threat requiring flexible fleet composition strategies. Certification investment in ISO 11783-compatible precision agriculture systems serves as defensive lever against technology obsolescence.
For New Entrants and Emerging Players: Establish a beachhead in orchard and vineyard mechanization segments across France, Italy, and Spain where structured rental programs remain underpenetrated. Target compact sub-50 horsepower equipment categories exempt from EU Stage V aftertreatment requirements as most penetrable white space. Municipal maintenance cross-deployment offers secondary expansion vector beyond agricultural seasonality constraints. Digital marketplace platforms connecting fragmented equipment supply with spot demand provide viable go-to-market angle against incumbent depot networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional dealership networks consolidating rental portfolios ahead of emissions compliance cost pressures. Long-term viability frames around five-to-ten year equipment utilization economics as battery-electric tractor rental models approach diesel parity in specific horsepower bands. Acquisition target archetype includes independent rental operators with established municipal maintenance relationships and precision agriculture telemetry integration capabilities. Signal to watch is original equipment manufacturer electrification roadmap acceleration coupled with rural electrical grid capacity expansion announcements.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Telemetry Bundling | Deere & Company leverages captive finance arm to convert fixed technology investments into variable operating expenses for commercial operators. |
| Depot Network Consolidation | CNH Industrial achieves maintenance scale economies across Case IH and New Holland brand locations in France and Germany. |
| Compact Segment Specialization | Kubota Corporation captures orchard and vineyard demand below EU Stage V regulatory power thresholds. |
| Lease-to-Own Pathway Development | Agricultural end users in the United States seek equipment familiarity before ownership commitment amid emissions compliance complexity. |
| Municipal Maintenance Cross-Deployment | Utility tractor versatility expands addressable rental demand beyond traditional agricultural seasonality constraints. |
Study Parameters
A spread of perspectives from fleet operations managers, agricultural contractors, precision agriculture technology specialists, and municipal procurement officers converged on the working assumptions underlying this analysis. Primary interviews with rental provider executives and end-user equipment managers combined with secondary validation against EPA regulatory filings, EU Stage V implementation documentation, and OEM electrification roadmaps. Customs data on agricultural machinery trade flows, SEC 10-K equipment revenue disclosures, and ISO standard development records provided triangulation anchors. Bottom-up equipment deployment estimates and top-down market sizing approaches were reconciled through iterative stakeholder feedback.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include product type tier, end-use sector, deployment logistics configuration, and contract architecture structure. Horsepower band analysis captured regulatory threshold effects on equipment category economics. CAGRs were derived through equipment replacement cycle analysis, fleet expansion patterns, and technology adoption curve integration. Industry-specific forecast inputs encompassed precision agriculture penetration rates and emissions compliance deadline clustering.
Sensitivities concentrate around electrification technology cost curves, rural electrical grid capacity buildout timelines, and commodity price volatility effects on agricultural capital expenditure cycles. Forecasts reflect documented assumptions on equipment holding periods, utilization rate trajectories, and telemetry bundling adoption slopes. Material shifts in battery-electric tractor total cost of ownership parity timing or federal emissions standard stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Irrigation Pumps Market
Farm Equipment and Irrigations
Irrigation Controllers Market
Farm Equipment and Irrigations
Australia Irrigation Automation Market
Farm Equipment and Irrigations
Farm Equipment Rental Market
Farm Equipment and Irrigations
Rain Barrels Market
Farm Equipment and Irrigations
Lawn Sprinkler Market
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Solar Powered Irrigation System Market
Farm Equipment and Irrigations
Smart Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Global Irrigation Machinery Market
Farm Equipment and Irrigations
Ride-On Mower Market
Farm Equipment and Irrigations
Sprinkler Irrigation Market
Farm Equipment and Irrigations
Brazil Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Fertigation Control System Market
Farm Equipment and Irrigations
Potato Planter Market
Farm Equipment and Irrigations
Greenhouse Irrigation Systems Market