
 Rain Barrels Market | 2026-2036
Rain Barrels Market Size, Share, and Industry Trends Forecast 2026-2036
Rain Barrels Market Analytics
Home improvement retail is reconfiguring shelf space and private-label priorities around rainwater harvesting as seasonal lawn-and-garden spending shifts toward conservation hardware. Fiskars Group leverages its established garden tool distribution network to anchor premium placement in big-box channels across North America. Graf Otto GmbH competes through specialized rotational molding expertise that sustains product differentiation in European markets. RTS Companies dominates the mid-tier plastic barrel segment by controlling direct-to-contractor fulfillment through wholesale distributors.
A rain barrel is a cylindrical or rectangular container, typically fabricated from high-density polyethylene, galvanized steel, or woven polypropylene, designed to capture and store rooftop runoff via gutter downspout connections for later irrigation or non-potable household use. Capacity ratings generally span 50 to 500 gallons, with wall thickness and UV stabilization determining service life in outdoor exposure. Plastic barrels lead unit volume due to low material cost and injection molding scalability, though metal variants command margin pools in architectural and decorative installations where aesthetic integration matters. Free-standing configurations represent the mature baseline, while in-ground systems are gaining specification in new residential developments where homeowners associations restrict visible hardware.
EPA stormwater regulations and municipal plumbing codes in the United States shape product standards by mandating overflow mechanisms and mosquito screening, while REACH compliance in Europe restricts certain plasticizers in rotational molding compounds. Australia's state-level water efficiency labeling schemes and California's Model Water Efficiency Landscape Ordinance create divergent certification pathways that manufacturers must navigate for market access. Stakeholders should monitor evolving rebate program eligibility criteria and building code amendments that could abruptly expand or contract addressable demand in key metropolitan zones.
Market Dynamics
EPA stormwater management guidelines and tiered municipal water pricing in drought-affected states are compressing payback periods for residential rainwater harvesting investments, redirecting homeowner capital toward certified collection systems.
Growth Catalysts
- California's Model Water Efficiency Landscape Ordinance:Mandates water-efficient irrigation in new developments, creating specification pull for high-capacity storage systems in suburban construction.
- Rotational molding process advancement:Enables complex geometries and integrated overflow chambers that reduce installation labor for landscaping contractors.
- Australian state-level rebate programs:Queensland and New South Wales subsidize certified barrel purchases, accelerating household adoption in peri-urban zones.
Market Restraints
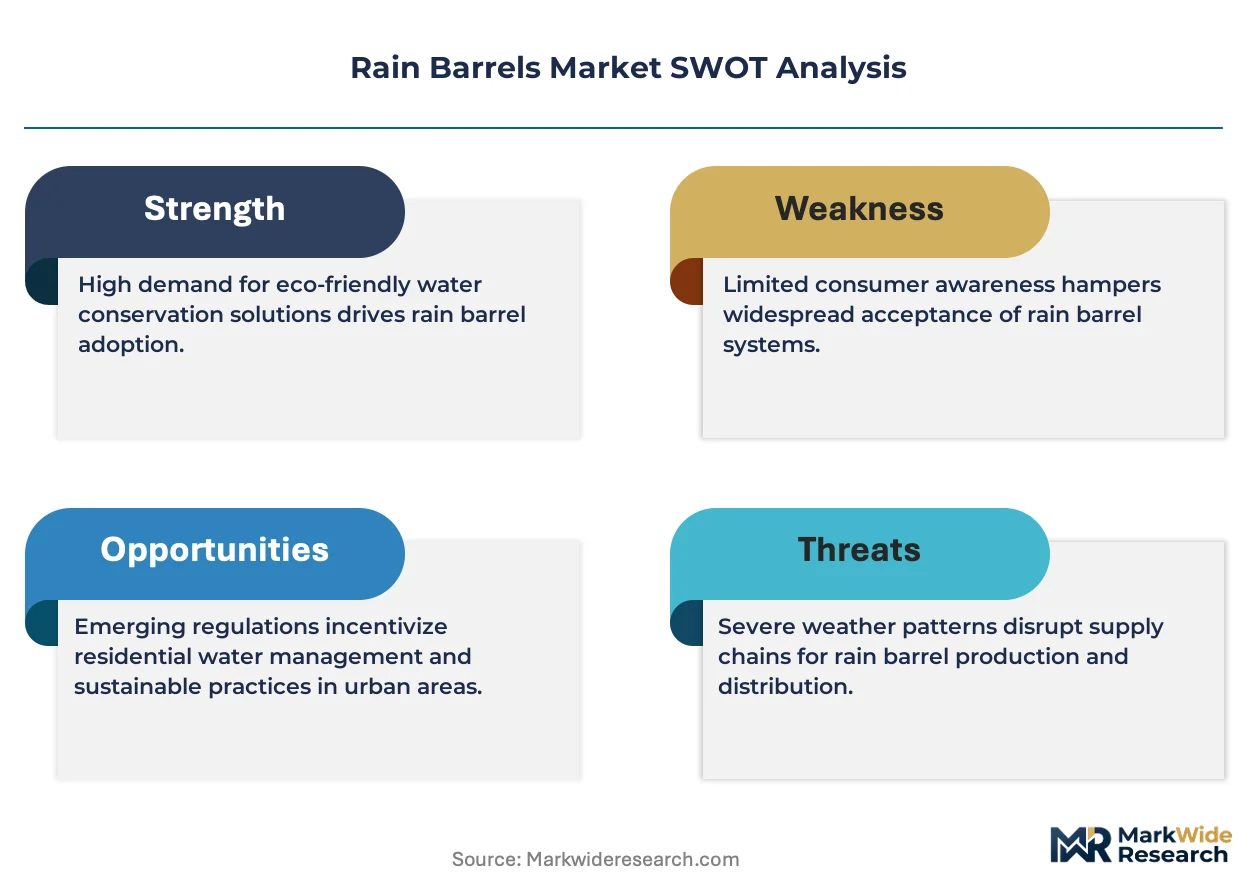
- HDPE resin price volatility:Feedstock cost swings compress margins for plastic barrel manufacturers dependent on petrochemical supply chains.
- Galvanized steel tariff exposure:Decorative metal variant producers face input cost pressure from trade policy uncertainty affecting architectural specification.
- Seasonal demand concentration:Spring landscaping season drives 60%+ of annual volume, forcing working capital intensity for distributors managing inventory turns.
Strategic Opportunities
- Texas Hill Country new development:Homeowners associations restricting visible hardware create specification opening for in-ground system integration.
- IoT sensor convergence with storage:Remote level monitoring and automated irrigation triggering command premium positioning in smart home ecosystems.
- EPA WaterSense certification expansion:Eligibility criteria broadening to include rainwater harvesting creates procurement preference in federal building projects.
Industry Challenges
- Mosquito screening compliance timelines:California plumbing code amendments require redesigned mesh specifications, forcing SKU transitions and inventory obsolescence.
- Rotational molding technician scarcity:Specialized thermoforming expertise shortages constrain capacity expansion for mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rain Barrels Market |
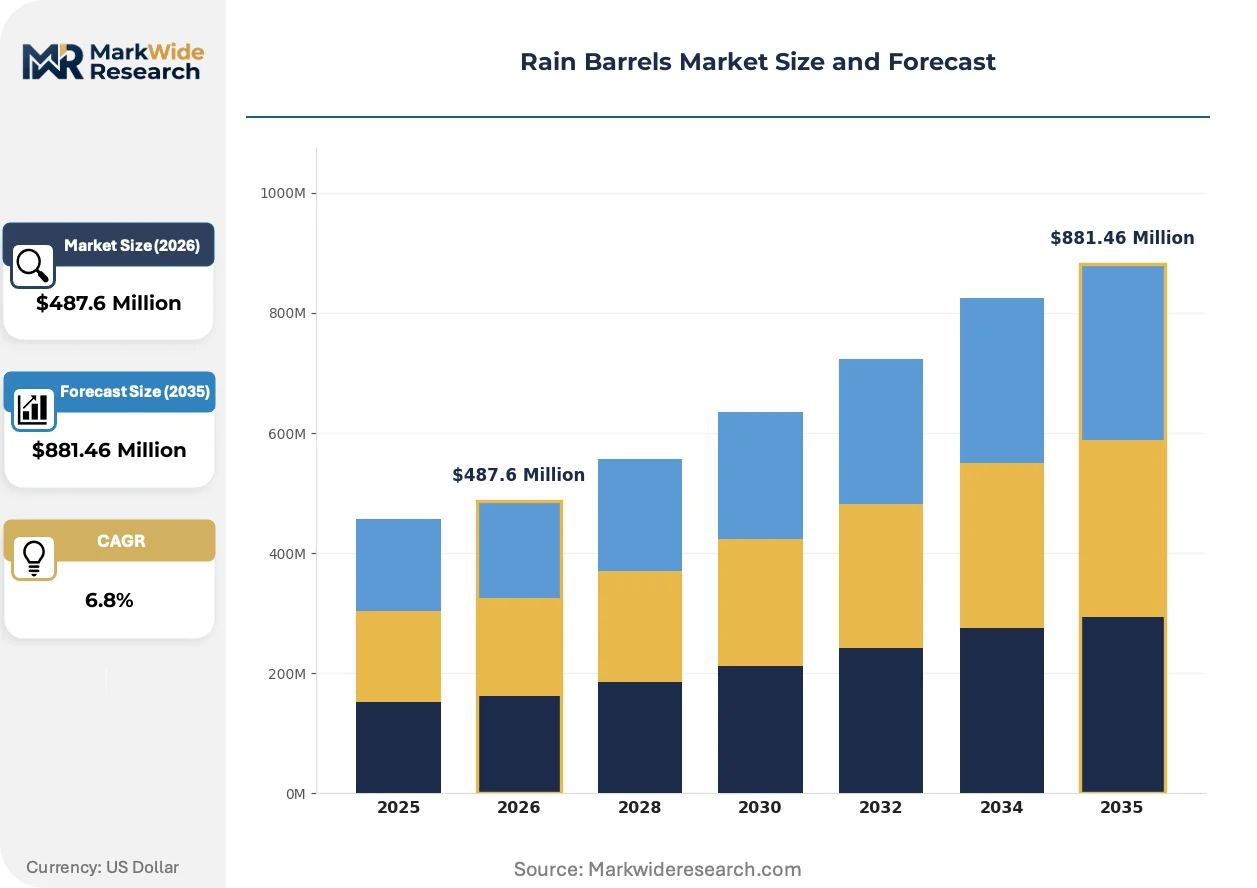
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Barrels, Metal Barrels, Fabric Barrels, Composite Barrels Installation Type: Wall-Mounted, Free-Standing, In-Ground, Decorative Capacity: 50 Gallons, 100 Gallons, 200 Gallons, 500 Gallons Distribution Channel: Online Retail, Home Improvement Stores, Garden Centers, Wholesale Distributors |
| Companies Covered | Algreen Products, Good Ideas, Fiskars Group, RTS Companies, EarthMinded, Graf Otto GmbH, Aquabarrel, Emsco, Gardener’s Supply Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rain Barrels Market Evolving Landscape
Product development is pivoting toward invisible infrastructure and connected monitoring as aesthetic restrictions and water accountability reshape residential specification priorities.
Integrated float sensors and cellular connectivity modules are digitizing rain barrel functionality for remote monitoring applications. Landscaping contractors in Arizona and Nevada are specifying these systems for estate properties managing multiple collection points. The technology is digitizing service models by enabling predictive maintenance alerts and automated irrigation scheduling that reduces on-site labor.
REACH restrictions on phthalate plasticizers in rotational molding compounds are forcing European manufacturers to reformulate HDPE compounds. The industrial consequence is shortened product development cycles as compounders validate alternative stabilizers for UV resistance. German and Dutch producers are responding by consolidating supplier relationships with certified polymer compounders to secure batch consistency.
Direct-to-contractor fulfillment platforms are compressing traditional wholesale distribution layers for commercial landscaping procurement. Big-box retailers are losing specification influence as RTS Companies and regional distributors build digital ordering portals with real-time inventory visibility. This channel shift is most pronounced in Texas and Florida where commercial contractor density supports dedicated fleet delivery economics.
Rain Barrels Market Segmentation
Rain barrel procurement patterns diverge sharply between cost-conscious homeowners seeking basic water storage and contractors specifying integrated systems for new developments. Material selection, installation constraints, and channel access create distinct competitive battlegrounds that manufacturers must navigate simultaneously.
Product Type:
The use-case spectrum spans utilitarian irrigation storage to architectural landscape integration, with material properties determining suitability for each application tier.
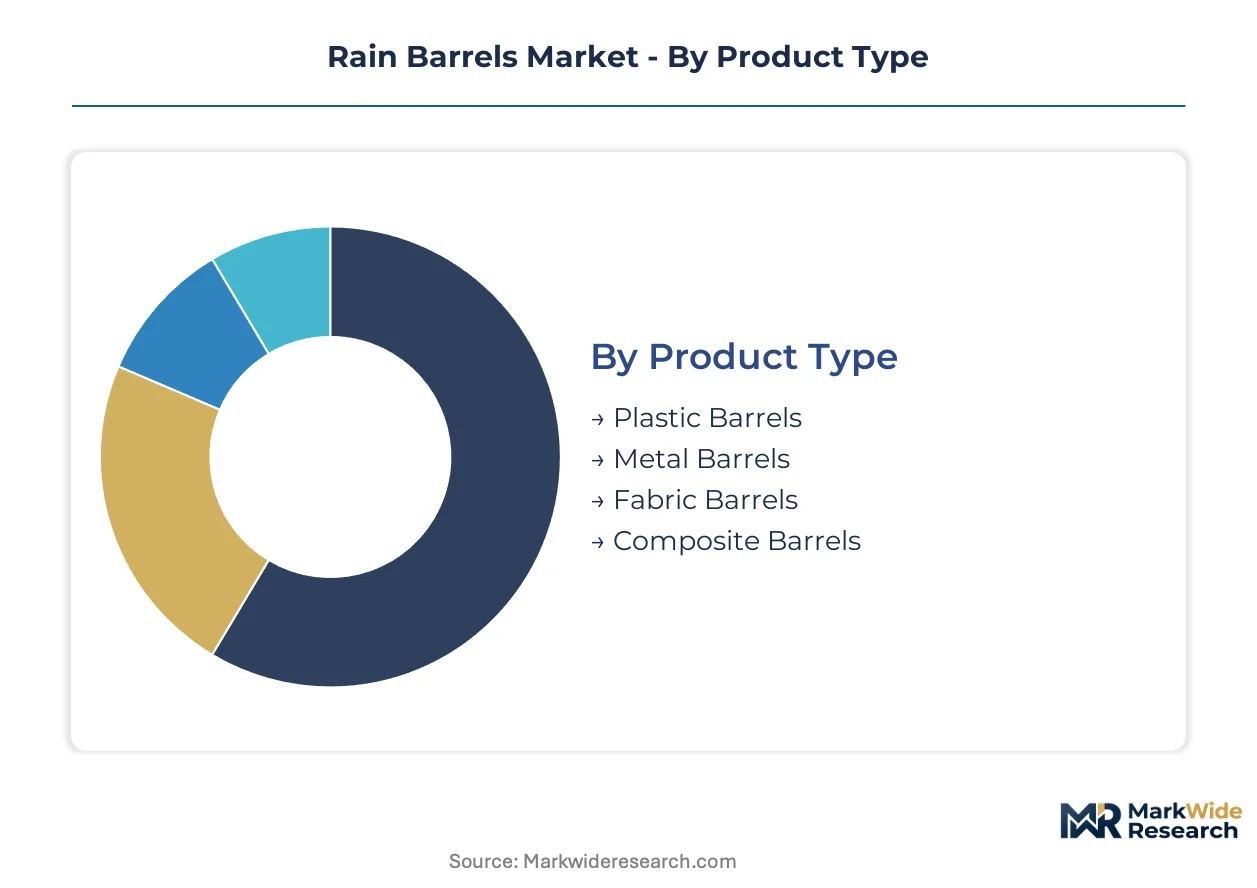
- Plastic Barrels:Fabricated from high-density polyethylene with UV stabilizers, these units dominate unit volume through injection molding scalability and sub-$100 price points. Demand concentrates in California and Texas suburban markets where municipal rebate programs subsidize certified polyethylene systems for residential retrofit.
- Metal Barrels:Galvanized steel or powder-coated aluminum variants command specification in architectural installations where aesthetic integration with exterior design matters. Australian estate properties and southwestern US custom home developments drive procurement, with EPA WaterSense certification becoming a threshold requirement for premium positioning.
- Fabric Barrels:Woven polypropylene collapsible designs address temporary or seasonal storage needs for renters and mobile homeowners.
- Composite Barrels:Hybrid constructions blending recycled plastics with wood fiber offer decorative textures without metal corrosion risks.
The dominant share belongs to Plastic Barrels, while Metal Barrels is closing the gap fastest.
Installation Type:
Site constraints and homeowners association governance create four distinct specification pathways with diverging margin profiles.
- Free-Standing:The baseline configuration requiring level ground placement and gravity-fed outlet hoses. Volume leadership stems from minimal installation complexity and compatibility with existing gutter downspouts across all climate zones.
- In-Ground:Buried polyethylene cisterns with integrated pumps address HOA aesthetic restrictions in Texas Hill Country and Nevada master-planned communities. Queensland's state-level rebate programs now include in-ground certification, accelerating specification in Australian peri-urban construction.
- Wall-Mounted:Bracket-attached designs maximize footprint efficiency for urban townhouses and narrow lot configurations.
- Decorative:Sculpted forms disguised as planters or architectural elements serve visible placement requirements without utility compromise.
Free-Standing retains volume leadership, though In-Ground is expanding most quickly in restricted-development zones.
Capacity:
Water stress severity and irrigation demand scale determine optimal storage sizing, with payback calculations varying by municipal tiered pricing structures.
- 50 Gallons:Entry-level capacity for townhouse balconies and small garden maintenance, typically sold through garden center impulse placement.
- 100 Gallons:The suburban household standard capturing roof runoff from 200-400 square foot collection surfaces, with California's Model Water Efficiency Landscape Ordinance creating specification pull in new development irrigation systems.
- 200 Gallons:Linked dual-barrel configurations for estate properties managing extended dry periods between rainfall events.
- 500 Gallons:Commercial-scale polyethylene cisterns serving landscaping contractors with centralized irrigation distribution across multiple zones.
The 100 Gallons segment anchors residential procurement, while 500 Gallons is gaining share fastest among commercial landscaping contractors.
Distribution Channel:
Channel selection reflects purchase urgency, installation complexity, and specification authority resting with homeowners versus contractors.
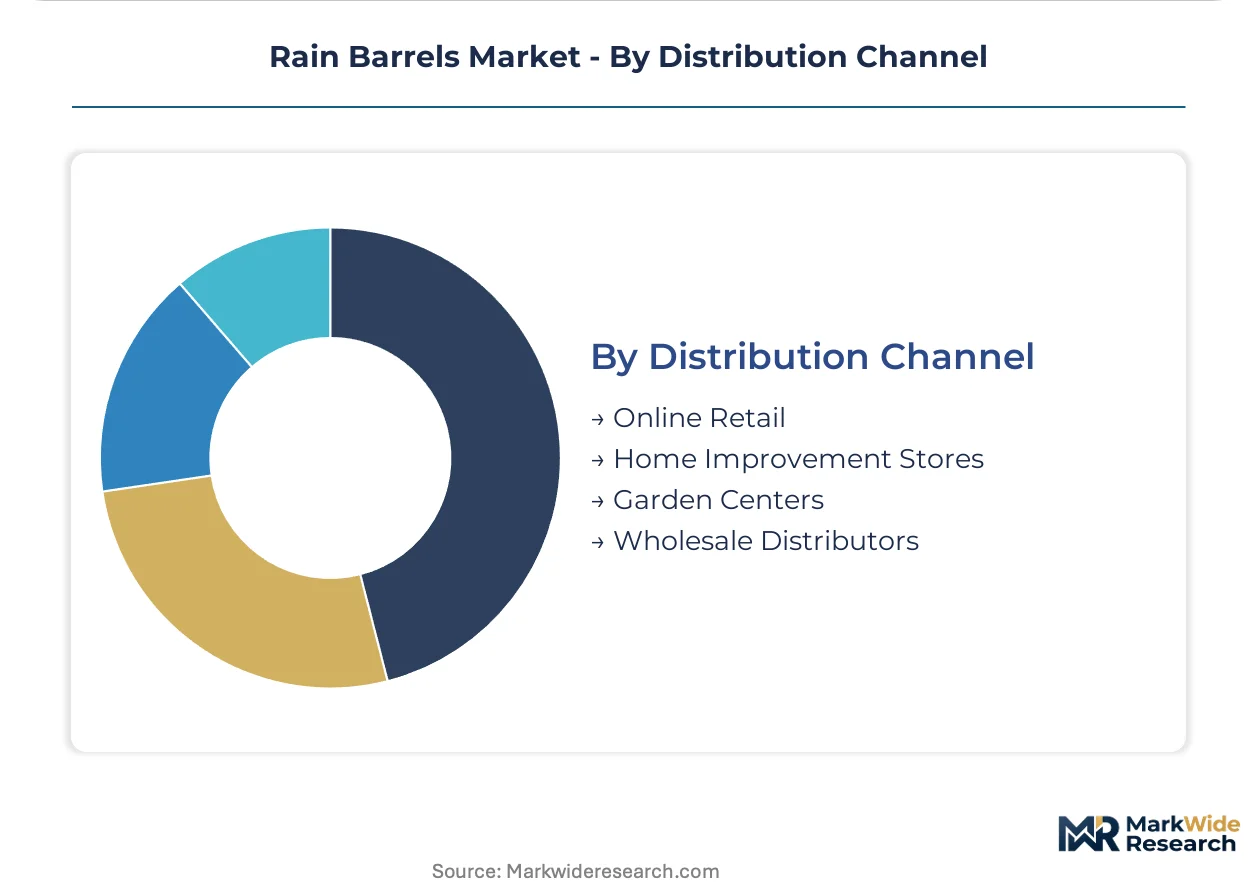
- Home Improvement Stores:Big-box retail placement drives spring season volume spikes through co-located gutter and irrigation aisle positioning. Fiskars Group leverages established garden tool relationships to secure premium end-cap placement in North American locations.
- Wholesale Distributors:Direct-to-contractor fulfillment with dedicated fleet delivery dominates commercial landscaping procurement in Texas and Florida, compressing traditional retail layers through real-time inventory portals.
- Online Retail:E-commerce captures research-intensive shoppers comparing EPA WaterSense certification status and customer installation reviews.
- Garden Centers:Seasonal nursery placement targets impulse purchases during spring planting season with staff-assisted sizing guidance.
Home Improvement Stores command the largest transaction volume, though Wholesale Distributors is climbing the fastest as contractor procurement digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Panama Canal's freshwater-dependent lock system anchors the Americas' water infrastructure calculus, while Australia's Murray-Darling Basin management shapes peri-urban conservation investment patterns across the Pacific.
United States
Residential contractors in drought-prone suburban zones are expanding procurement of high-capacity storage systems. EPA stormwater management guidelines and municipal rainwater harvesting rebates in California and Texas redirect homeowner spending toward certified collection equipment. The southwestern United States concentrates demand, where persistent water stress and tiered utility pricing amplify payback calculations for household-scale conservation investments.
Australia
State-level rebate programs in Queensland and New South Wales subsidize certified barrel purchases, accelerating household adoption in peri-urban zones. The country's water efficiency labeling schemes create divergent certification pathways that manufacturers must navigate for market access. Sydney and Melbourne metropolitan areas drive specification for in-ground systems in master-planned communities where homeowners associations restrict visible hardware.
Germany
REACH restrictions on phthalate plasticizers in rotational molding compounds force manufacturers to reformulate HDPE compounds. German producers respond by consolidating supplier relationships with certified polymer compounders to secure batch consistency. The North Rhine-Westphalia industrial cluster hosts specialized rotational molding expertise that sustains product differentiation in European markets.
Canada
Municipal stormwater management programs in Ontario and British Columbia create procurement preference for EPA WaterSense-equivalent certified systems. Health Canada's environmental health guidelines influence product standards for mosquito screening and overflow mechanisms. The Greater Toronto Area anchors distribution network expansion for big-box retail placement in North American locations.
Rain Barrels Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers: mass-market injection molders, specialized rotational molding houses, and integrated garden equipment conglomerates. The competitive terrain rewards distribution network depth over manufacturing scale, with contractor-facing fulfillment platforms compressing traditional wholesale layers. Strategic archetypes include the "garden tool anchor" leveraging established retail relationships, the "molding specialist" defending margin through process expertise, and the "direct-to-contractor platform" controlling last-mile logistics. Dominant competitive moves center on private-label consolidation with big-box retailers and backward integration into resin compounding to hedge feedstock volatility.
Among North American fabricators, Fiskars Group occupies a position exemplifying the garden tool anchor archetype, while RTS Companies represents the direct-to-contractor platform model. Graf Otto GmbH sits within the European molding specialist tier, anchoring regional differentiation through rotational process capabilities. These three entities collectively illustrate how supply-side positioning diverges across geographic markets and channel strategies.
| Leading Market Players |
|---|
| Algreen Products |
| Good Ideas |
| Fiskars Group |
| RTS Companies |
| EarthMinded |
| Graf Otto GmbH |
| Aquabarrel |
| Emsco |
| Gardener's Supply Company |
| Others |
Value Network & Pricing Analysis
HDPE resin compounding capacity concentrates in the US Gulf Coast petrochemical corridor and North Rhine-Westphalia industrial cluster, anchoring margin capture for rotational molding specialists while injection molders compete on throughput scale. This upstream geography directly shapes where pricing power accrues across the three-tier market structure.
Pricing Analysis
Volume-discount tiering separates architectural metal variants from commodity polyethylene barrels from collapsible fabric designs. Price differentiation rests on EPA WaterSense certification status and UV stabilization grade, with certified systems commanding placement in municipal rebate programs. Cost compression in the plastic barrel tier is intensifying because HDPE feedstock volatility transfers directly to contract manufacturers. Home improvement retail shoppers exhibit highest price sensitivity, while landscaping contractors prioritize installation labor reduction over unit cost.
Supply Chain Analysis
Supplier-financing facilities from wholesale distributors are extending payment terms to commercial landscaping contractors, compressing cash conversion cycles for mid-tier producers. Manufacturing draws from high-density polyethylene pellet supply in Texas, Louisiana, and Germany, with galvanized steel sheet dependency exposing decorative variant producers to tariff uncertainty. Single-source vulnerability sits with rotational molding technician scarcity constraining European capacity expansion. Distribution runs through direct-to-contractor fulfillment platforms in Texas and Florida, bypassing traditional retail layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from municipal-scale greywater recycling systems and smart irrigation controllers that bypass storage infrastructure entirely. Defense requires preemptive positioning around connected monitoring capabilities and in-ground installation expertise.
For Market Incumbents: Pre-empt greywater system displacement by embedding IoT level sensors and automated irrigation triggers into premium product lines. Backward integration into HDPE compounding hedges resin price volatility exposure. Secure rotational molding technician pipelines through apprenticeship partnerships with German technical institutes to defend European margin pools. For New Entrants and Emerging Players: Establish a beachhead in the Texas Hill Country in-ground system segment where HOA aesthetic restrictions create specification barriers for incumbent free-standing portfolios. Target commercial landscaping contractors in Florida through digital fulfillment platforms with real-time inventory visibility. Differentiate via integrated pump and overflow chamber packages that reduce on-site installation labor. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed garden equipment conglomerates seeking portfolio rationalization. The five-to-ten year viability window favors platforms with contractor-facing fulfillment infrastructure over retail-dependent brands. Monitor EPA WaterSense certification expansion into federal building procurement as the signal for demand inflection toward certified system manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Sensor Integration | Remote monitoring capabilities capture premium positioning in Arizona and Nevada estate property specifications. |
| Rotational Molding Capacity Expansion | European technician scarcity makes German and Dutch facility acquisitions strategically defensible. |
| Direct-to-Contractor Platform Buildout | Real-time inventory portals in Texas and Florida compress traditional wholesale distribution economics. |
| HDPE Compounding Backward Integration | Captive resin supply hedges margin compression from petrochemical feedstock volatility. |
| In-Ground System Certification | Queensland rebate program inclusion and Texas HOA restrictions create specification pull for buried cistern designs. |
Research Methodology
Cross-validation between landscaping contractor interviews and municipal procurement database analysis anchors the qualitative findings. Primary fieldwork engaged product managers at rotational molding houses, category buyers at big-box retailers, irrigation specialists at commercial landscaping firms, and compliance officers at state environmental agencies. Secondary sources included EPA stormwater guideline documents, California Model Water Efficiency Landscape Ordinance filings, Queensland rebate program eligibility criteria, and REACH regulatory updates from ECHA. Bottom-up unit economics modeling triangulated against top-down addressable market sizing across material type and installation configuration segments.
Calibration against historical adoption curves in California and Texas suburban markets shaped the projection framework. Segmentation dimensions modeled include material composition, installation type, capacity tier, and distribution channel structure across the analysis window. CAGRs derived from elasticity-adjusted demand curves responding to tiered municipal water pricing and rebate program expansion schedules. Industry-specific inputs incorporated HDPE resin price forecasting and rotational molding capacity utilization rates from European producer surveys.
Stress conditions across HDPE feedstock cost bands, tariff policy scenarios, and rebate program funding levels were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory continuity and contractor procurement digitization velocity. Macroeconomic contraction, abrupt building code amendments, or breakthroughs in alternative water conservation technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
United States Irrigation Valves Market
Farm Equipment and Irrigations
Global Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Drip Irrigation Systems Market
Farm Equipment and Irrigations
Asia-Pacific Irrigation Machinery Market
Farm Equipment and Irrigations
Greenhouse Irrigation Systems Market
Farm Equipment and Irrigations
South America Irrigation Machinery Market
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Africa Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Asia Pacific Irrigation Valves Market
Farm Equipment and Irrigations
Global Irrigation Automation Market
Farm Equipment and Irrigations
Lawn Sprinkler Market
Farm Equipment and Irrigations
Sprinkler Irrigation Market
Farm Equipment and Irrigations
Global Center Pivot Irrigation Systems Market
Farm Equipment and Irrigations
Brazil Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Irrigation Liner Market
Farm Equipment and Irrigations
North America Agricultural Tires Market