
 Global Precision Irrigation Market | 2026-2036
Global Precision Irrigation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Precision Irrigation Market Intelligence
Expanded manufacturing capacity in Israel and the United States is reshaping competitive positioning among system providers. Netafim leverages its deep expertise in drip irrigation technologies to maintain a strong market presence. Valmont Industries competes through its extensive portfolio of center pivot and linear move systems, targeting large-scale commercial farming operations. Trimble Inc. differentiates with its focus on integrated software and hardware solutions for farm management.
Precision irrigation involves the controlled and targeted delivery of water directly to the plant root zone, often guided by real-time data. These systems utilize components like emitters with specific flow rates, such as 2-4 liters per hour, to maximize water use efficiency and improve crop yields. Drip irrigation systems command a significant share due to their effectiveness in horticulture and orchards. Technology integration, particularly through IoT connectivity and soil moisture sensors, represents the fastest-growing segment as farmers seek automated control.
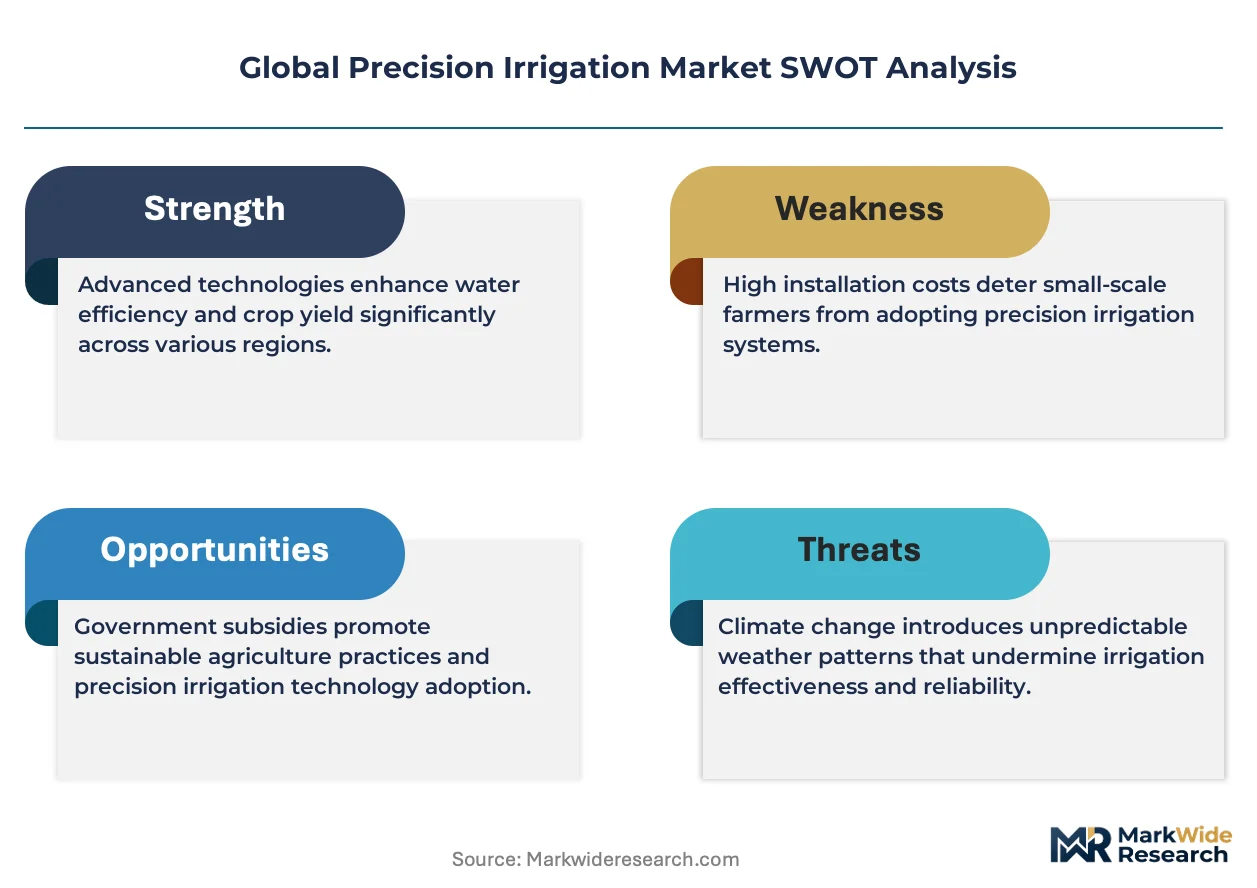
Water conservation mandates and agricultural subsidies in regions like the European Union under its Green Deal and in the United States via USDA programs are key demand drivers. Standards from organizations like ISO on water quality and system components influence product design and market access. The critical decision for commercial farmers now revolves around balancing the high initial capital investment against the long-term operational savings and yield improvements.
Market Dynamics
The fundamental market dynamic is the collision between intensifying water scarcity, driven by climate change and population growth, and the economic imperative for higher crop yields. This forces a structural shift away from traditional irrigation toward technology-enabled water management systems.
Growth Catalysts
- Government Mandates:India's Pradhan Mantri Krishi Sinchayee Yojana (PMKSY) provides subsidies and promotes micro-irrigation, directly stimulating system adoption to meet national food security and water conservation goals.
- Technology Integration:The fusion of IoT connectivity with soil moisture sensors enables real-time, automated water delivery, which is a primary driver for adoption in high-value horticulture where precise control is paramount.
- Yield & Quality Demands:In orchard and vineyard cultivation, the need for consistent fruit size, quality, and sugar content pushes growers toward drip irrigation systems that offer precise nutrient and water application.
Market Restraints
- High Initial Capital Outlay:The significant upfront cost of center pivot systems, advanced controllers, and sensor networks remains a primary barrier for small-to-medium-sized farms, particularly in developing economies.
- System Interoperability:A lack of standardization across hardware and software from different vendors creates integration challenges, locking farmers into specific ecosystems and complicating system expansion or upgrades.
- Knowledge and Training Gap:Effective use of precision irrigation requires agronomic and technical expertise that is often scarce, leading to underutilization of system capabilities or improper maintenance.
Strategic Opportunities
- Underpenetrated Geographies:Markets in Southeast Asia, such as Vietnam and Indonesia, present significant growth potential as they seek to improve water efficiency in rice and palm oil cultivation.
- Data-as-a-Service Models:Offering subscription-based analytical services that provide irrigation scheduling, yield forecasting, and pest management recommendations creates a recurring revenue stream beyond initial hardware sales.
- Retrofitting Existing Systems:Developing affordable upgrade kits with smart controllers and sensors for older, non-precision irrigation systems opens a large addressable market of established farms seeking efficiency gains.
Industry Challenges
- Data Security and Ownership:Securing sensitive farm-level data against cyber threats and clarifying data ownership between farmers, technology providers, and third-party consultants is a critical operational hurdle.
- Component Supply Chain Volatility:Reliance on a global supply chain for electronic components like semiconductors and sensors exposes manufacturers to disruptions, affecting production timelines and system costs.
- Integration with Legacy Farm Practices:Convincing farmers to shift from long-standing, experience-based watering practices to data-driven automated systems requires significant educational effort and demonstrated ROI.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Precision Irrigation Market |
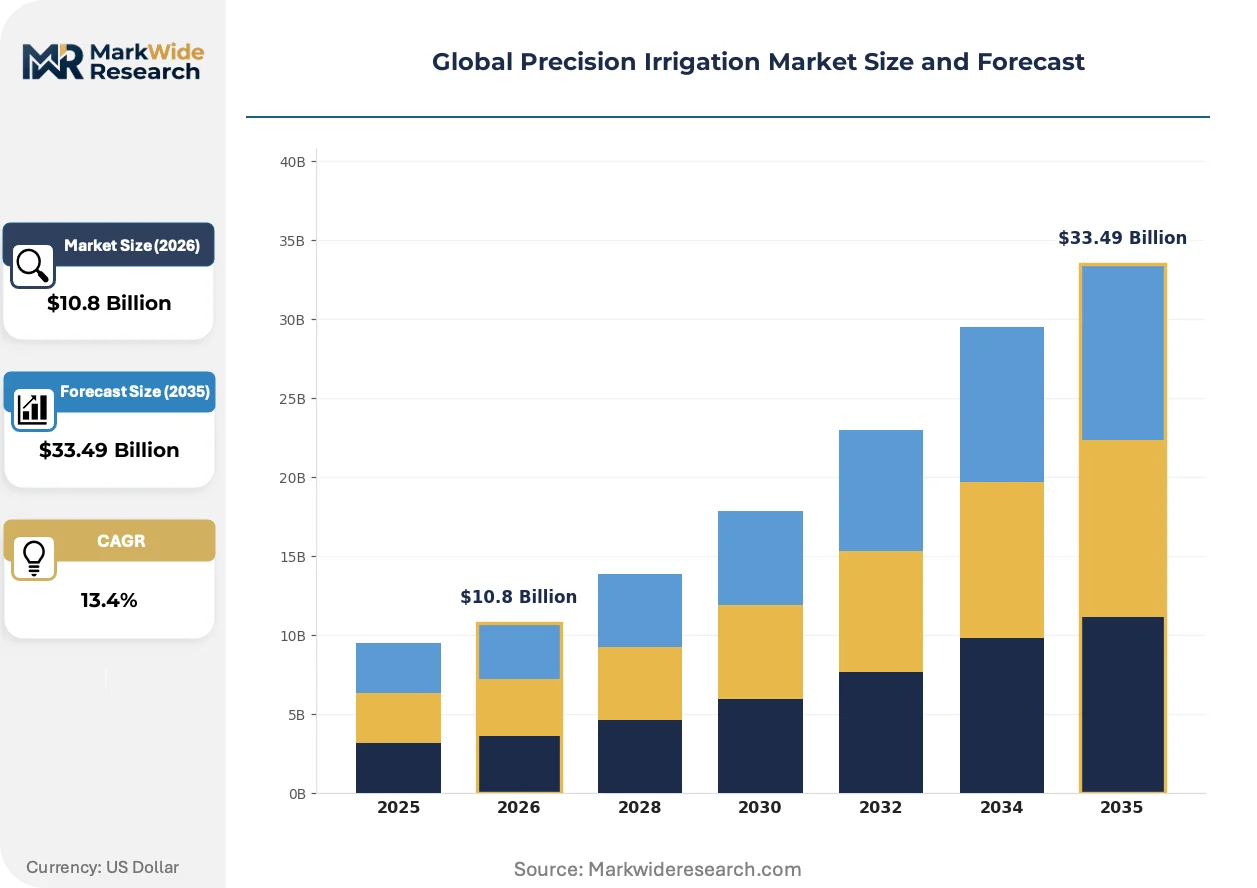
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $33.49 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip Irrigation, Sprinkler Systems, Surface Irrigation, Subsurface Irrigation, Center Pivot Irrigation Technology: Soil Moisture Sensors, Satellite Imaging, Weather Forecasting, Automated Controls, IoT Connectivity Application: Cereal Crops, Horticulture, Vegetable Farming, Greenhouse Cultivation, Orchards End User: Commercial Farmers, Agricultural Cooperatives, Research Institutions, Government Agencies |
| Companies Covered | Valmont Industries, Inc., Netafim, Hunter Industries, The Toro Company, Lindsay Corporation, Rain Bird Corporation, Rivulis, Reinke Manufacturing Co., Inc., Trimble Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Precision Irrigation Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from selling hardware components to delivering integrated, data-driven water management solutions. This transition elevates system intelligence and automation, making efficiency gains more accessible and quantifiable for farm operations.
Advanced sensor fusion combines data from soil moisture probes, drone-based thermal imaging, and satellite-based evapotranspiration maps. Large commercial farming operations in Australia and the United States are rapidly adopting these integrated platforms. This technology **is digitizing** irrigation management, replacing manual field checks with predictive, automated water application schedules tailored to specific crop zones.
Water conservation policies, such as the mandates within the EU Green Deal framework, are directly influencing system design and adoption. These regulations tie agricultural subsidies to verifiable water efficiency metrics, compelling farmers to invest in technology that can provide auditable data. Drip and micro-sprinkler segments are most impacted, as their inherent precision aligns with compliance requirements.
A notable shift in purchasing behavior involves the move from one-time capital expenditures to subscription-based service models. This trend disrupts the traditional equipment sales channel by introducing third-party providers who install, maintain, and operate systems for a recurring fee. This model is gaining traction in high-value agriculture like vineyards in France and nut orchards in California.
Global Precision Irrigation Market Segmentation
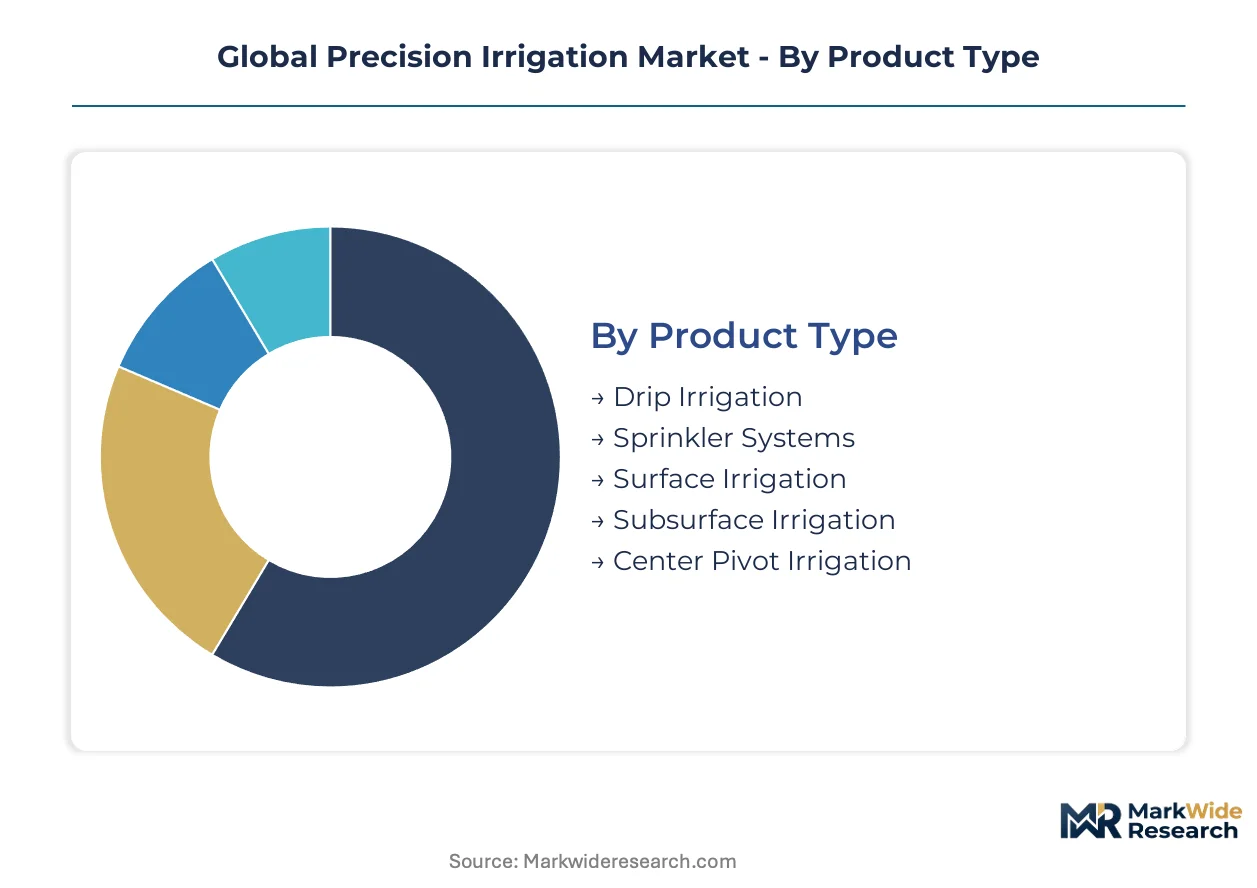
Understanding the Global Precision Irrigation Market through its constituent parts reveals distinct adoption patterns and value propositions. This segmentation highlights where innovation is most impactful, guiding stakeholders to identify specific growth vectors and address unique operational requirements.
Product Type:
The product type segmentation reflects varying investment cycles, from long-term infrastructure deployments to more frequent component upgrades. Systems with extensive physical infrastructure typically involve longer planning and installation phases, influencing their adoption rates.
- Drip Irrigation:This system delivers water directly to the plant root zone through emitters, maximizing water use efficiency. Demand concentrates in high-value horticulture and orchards, improving crop quality.
- Sprinkler Systems:Sprinkler systems distribute water over large areas, suitable for various field crops.
- Surface Irrigation:Surface irrigation involves water flowing over soil by gravity; lower cost, lower efficiency.
- Subsurface Irrigation:Subsurface irrigation applies water below soil, reducing evaporation and runoff for high efficiency.
- Center Pivot Irrigation:Center pivot irrigation systems rotate around a central point, watering circular areas efficiently. Valmont Industries targets large commercial farming operations despite high initial capital outlay.
Drip Irrigation anchors the volume base while Center Pivot Irrigation gains share at the steepest rate among large-scale commercial farms.
Technology:
The technology segment reveals different cost tiers, from foundational sensing hardware to complex, integrated software platforms. Investment decisions often hinge on balancing upfront capital expenditure with the long-term operational savings and data-driven insights provided by each technology.
- Soil Moisture Sensors:Soil moisture sensors measure volumetric water content in soil, providing real-time data for precise irrigation scheduling. Adoption expands in European horticulture, optimizing water delivery.
- Satellite Imaging:Satellite imaging provides aerial data on crop health and water stress, used by Australian farmers for zone-specific irrigation.
- Weather Forecasting:Weather forecasting integrates predictive data for proactive irrigation scheduling, optimizing resources.
- Automated Controls:Automated controls manage irrigation schedules and water delivery automatically.
- IoT Connectivity:IoT connectivity integrates sensors, controllers, and cloud platforms for remote monitoring and automated management. This technology represents the fastest-growing segment as farmers seek real-time data for efficiency.
Soil Moisture Sensors provide foundational data, while IoT Connectivity is on the steepest expansion trajectory due to demand for automation.
Application:
Application segmentation illustrates where the largest volumes of water and precision irrigation systems are deployed, reflecting diverse crop requirements and economic value. Different crops necessitate tailored irrigation strategies, influencing technology choices and system design.
- Cereal Crops:Cereal crops like wheat, rice, and corn are cultivated over vast areas. Efficiency gains in cereal irrigation are critical for global food security, especially in India with government micro-irrigation initiatives.
- Horticulture:Horticulture involves cultivating fruits, vegetables, and ornamental plants, where precision irrigation enhances yield quality. High-value horticulture in the European Union demands precise control for optimal growth.
- Vegetable Farming:Precision irrigation in vegetable farming supports consistent growth and quality.
- Greenhouse Cultivation:Greenhouse cultivation benefits from precision irrigation for optimal nutrient delivery and water recycling.
- Orchards:Orchards cultivate fruit trees like almonds, citrus, and apples, benefiting from targeted water delivery. Drip irrigation ensures consistent fruit size, quality, and sugar content, crucial for commercial success.
Cereal Crops represent a significant volume base, and Orchards are gaining share fastest due to quality demands.
End User:
The end-user segmentation differentiates adoption patterns based on organizational structure, scale of operations, and access to capital. Each customer type faces unique challenges and opportunities in integrating precision irrigation solutions into their agricultural practices.
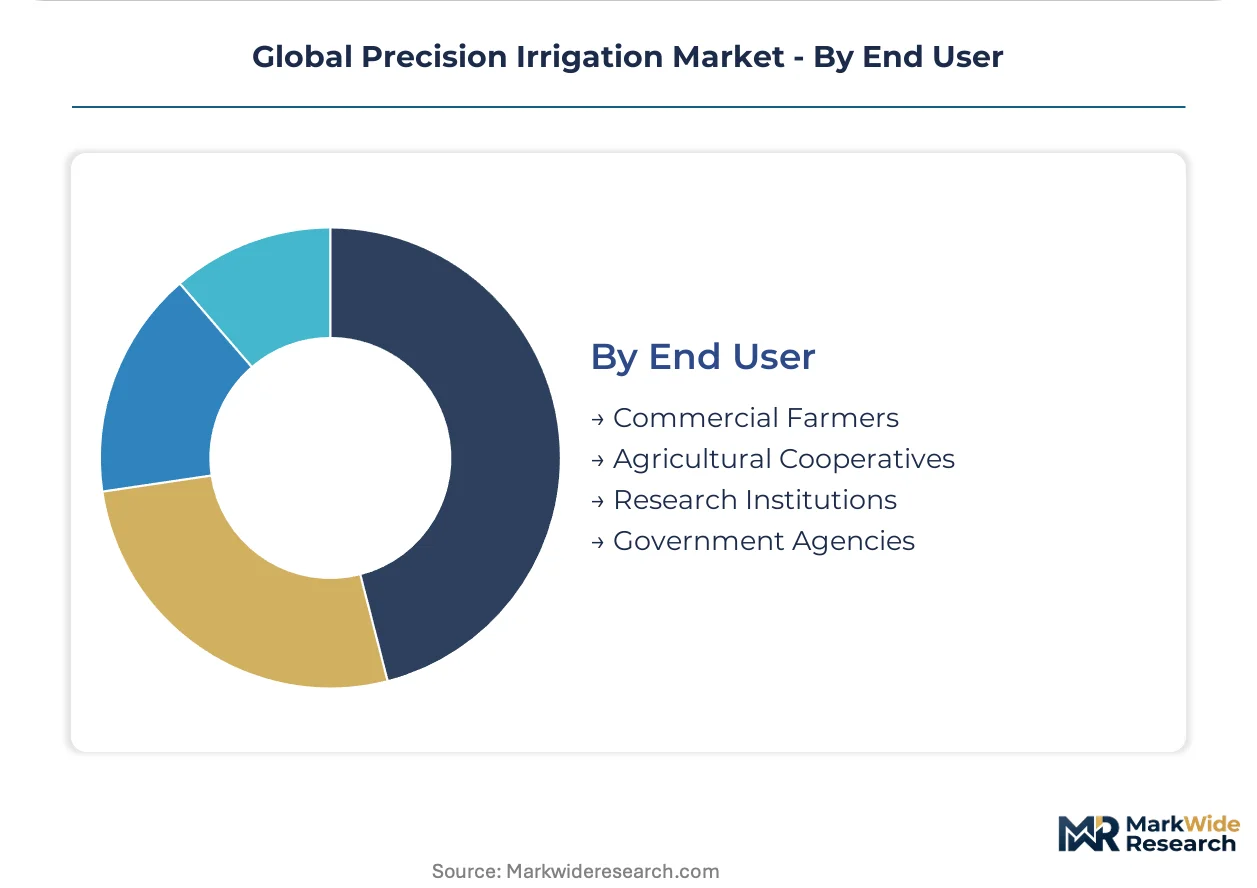
- Commercial Farmers:Commercial farmers prioritize efficiency, yield optimization, and long-term operational savings. They often possess capital for significant initial investments in advanced precision irrigation systems and data-driven solutions.
- Agricultural Cooperatives:Agricultural cooperatives pool resources for collective purchasing, shared infrastructure, and knowledge transfer among members. Cooperatives in the United States facilitate broader precision irrigation adoption for smaller farms.
- Research Institutions:Research institutions develop new irrigation technologies, optimize water use, and study crop responses.
- Government Agencies:Government agencies implement policies, provide subsidies, and promote efficient water use, influencing market demand.
Commercial Farmers constitute the largest user base, with Agricultural Cooperatives expanding most quickly by enabling wider access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Expanded manufacturing capacity in key regions drives global precision irrigation system availability. Production capabilities for advanced components are concentrated in specialized hubs. This geographic focus influences supply dynamics for smart irrigation technologies worldwide.
India
Demand for micro-irrigation systems in India stems from intensifying water scarcity and national food security goals. The Pradhan Mantri Krishi Sinchayee Yojana (PMKSY) actively promotes efficient water use through subsidies. In states like Maharashtra, government incentives stimulate widespread adoption among small and medium-sized farms.
United States
Commercial farmers in the United States prioritize yield optimization and long-term operational savings from precision irrigation. USDA programs offer financial assistance and incentives for water conservation practices across agricultural lands. California's Central Valley sees significant investment in drip and center pivot systems for high-value nut and fruit orchards.
Israel
Innovation in drip irrigation technologies and expanded manufacturing capacity are core demand drivers in Israel. The country's water management policies have fostered a robust domestic market for advanced systems. Companies in the Negev Desert region develop cutting-edge solutions for arid agricultural conditions.
Australia
Large-scale commercial farming operations in Australia require efficient water delivery due to persistent drought conditions. Australian government initiatives support the adoption of water-saving technologies in agriculture. The Murray-Darling Basin region utilizes satellite imaging and advanced platforms for zone-specific irrigation management.
France
High-value horticulture, particularly vineyards in France, drives demand for precise water and nutrient application. The European Union's Green Deal mandates influence system design and adoption for verifiable water efficiency metrics. The Bordeaux region exemplifies the shift towards subscription-based service models for advanced irrigation.
Global Precision Irrigation Market Key Industry Players
Full-service infrastructure providers and specialized technology integrators split the market for precision irrigation solutions. The competitive landscape features a blend of established equipment manufacturers with deep hardware expertise and agile software developers focusing on data-driven insights. Strategic archetypes include large-scale system providers and niche players offering advanced sensing and control components. Companies pursue expanded manufacturing capacity and strategic partnerships for technology integration as dominant competitive moves.
Within the large-scale system provider archetype, Valmont Industries, Inc. exemplifies an extensive portfolio of center pivot and linear move systems, primarily targeting expansive commercial farming operations. Netafim, a global leader in micro-irrigation, represents deep expertise in drip irrigation technologies, anchoring a significant market presence particularly in high-value horticulture and orchards. Trimble Inc. occupies a distinct position as a specialist in integrated software and hardware solutions for comprehensive farm management, highlighting the industry's shift towards data-driven offerings, automated control, and efficiency optimization.
| Leading Market Players |
|---|
| Valmont Industries, Inc. |
| Netafim |
| Hunter Industries |
| The Toro Company |
| Lindsay Corporation |
| Rain Bird Corporation |
| Rivulis |
| Reinke Manufacturing Co., Inc. |
| Trimble Inc. |
| Others |
Cost & Logistics Intelligence
Global shipping cost dynamics influence the final pricing of precision irrigation systems, particularly for specialized components sourced from concentrated manufacturing hubs. These cost fluctuations then impact price differentiation across various system configurations and end-user segments.
Pricing Analysis
EU Green Deal mandates dictate the pricing tier structure for advanced precision irrigation systems, especially those demonstrating verifiable water efficiency metrics. Project-based pricing dominates for large-scale installations, while subscription models gain traction for data-as-a-service offerings. Price differentiation stems from the level of IoT integration and specialized after-sales support. Pricing softness reflects the high initial capital outlay, which remains a primary barrier for small-to-medium-sized farms. Commercial farmers exhibit lower price sensitivity due to their focus on long-term yield improvements and operational savings.
Supply Chain Analysis
Component supply chain volatility, particularly for semiconductors and specialized polymers, poses a structural risk to precision irrigation system manufacturers. Geographic supply concentrates in Israel for drip technology, the United States for advanced software and center pivot systems, and China for electronic sensors. Specialized emitters and control valves draw from a limited number of global suppliers. Direct sales to large commercial operations and localized dealer networks represent the dominant downstream distribution models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision irrigation presents a significant service-attach opportunity, with data-as-a-service models for irrigation scheduling and yield forecasting expanding faster than hardware sales. This shift enables recurring revenue streams for technology providers.
For Market Incumbents:
Build proprietary data ecosystems by integrating advanced sensor fusion with existing hardware platforms. Expand manufacturing capacity in high-demand regions like India to leverage government subsidies and reduce logistics costs. Develop integrated software solutions for farm management to counter the threat from agile software developers. Invest in R&D for AI and machine learning to offer predictive analytics capabilities.
For New Entrants and Emerging Players:
Southeast Asian agricultural regions, particularly Vietnam and Indonesia, represent significant underpenetrated geographies for precision irrigation. Target small-to-medium-sized farms with affordable retrofitting kits for existing systems. Offer subscription-based analytical services tailored to local crop types and water availability. Form localized partnerships with agricultural cooperatives to facilitate broader adoption and provide necessary training.
For Investors and Strategic Acquirers:
Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core agricultural technology divisions. The long-term viability of this market is anchored in global food security and intensifying water scarcity. Acquisition target archetypes include specialized software providers for farm management and advanced sensor manufacturers. A signal to watch is increasing global regulatory pressure on agricultural water usage efficiency.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-powered irrigation controllers | These controllers enable hyper-localized water application, optimizing resource use for commercial farmers. |
| Strategic Partnership: With agricultural technology integrators | Partnerships broaden market reach and facilitate seamless system integration for diverse farm operations. |
| Geographic Expansion: Into underpenetrated markets like Vietnam | Expansion into new regions diversifies revenue streams and addresses growing food security needs. |
| Platform Integration: Combining sensor data with weather forecasting | Integrated platforms provide predictive irrigation schedules, enhancing crop yield and water conservation. |
| Acquisition of Specialist Firm: Targeting soil moisture sensor developers | Acquisitions secure critical component supply and enhance proprietary data collection capabilities. |
Research Approach
A standing panel of farm managers, irrigation system engineers, agricultural economists, and government policy advisors provided ongoing calibration for market dynamics. This primary research combined with secondary validation from USDA reports, EU Green Deal documents, FAO statistics, and company annual reports. Bottom-up and top-down triangulation ensured data consistency across various market segments.
Scenario-bracketing informed the quantitative modeling, developing a comprehensive analytical framework across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional water stress levels. Compound Annual Growth Rates were derived from historical data trends and projected adoption rates, incorporating inputs like crop commodity prices and government subsidy allocations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated technology firms would shift outcomes. Forecasts reflect assumptions regarding technological advancements and stable regulatory environments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Agricultural Sensors Market
Precision Agriculture
Connected Agriculture Software Market
Precision Agriculture
Europe Precision Farming Market
Precision Agriculture
Precision Farming Software Market
Precision Agriculture
Digital Agriculture Solutions Market
Precision Agriculture
United States Precision Farming Software Market
Precision Agriculture
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market
Precision Agriculture
Soil Moisture Meter Market
Precision Agriculture
Global Digital Farming Market
Precision Agriculture
Digital Agriculture Market
Precision Agriculture
Crop Nutrient Management Market
Precision Agriculture
Global Agriculture Sensors Market
Precision Agriculture
Global Digital Agriculture Platform Market
Precision Agriculture
Soil Moisture Sensor Market
Precision Agriculture
Precision Livestock Market
Precision Agriculture
Agricultural Mapping Services Market