
 China Agricultural Irrigation Machinery Market | 2026-2036
China Agricultural Irrigation Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
China Agricultural Irrigation Machinery Market Outlook
Buyer concentration among agricultural cooperatives and state-owned farms is expanding as smaller plot holders lease land to consolidated operators. Dayu Irrigation Group Co. Ltd anchors its position through deep manufacturing scale across Shandong province. Chinadrip Irrigation Equipment (Xiamen) Co., Ltd. leverages coastal logistics to dominate export-adjacent domestic sales. Orbia Group (Netafim) competes on precision emitter technology originally developed for arid-climate applications.
Agricultural irrigation machinery encompasses mechanized systems that deliver controlled water volumes to crops through pressurized networks, typically operating at 0.5–2.5 bar for drip lines and 2–5 bar for sprinkler assemblies depending on terrain and crop canopy requirements. These systems reduce labor intensity while improving water-use efficiency in water-stressed cultivation zones. Drip irrigation leads product type revenue due to government subsidy alignment with water conservation targets, while smart irrigation technology is expanding fastest as MIIT promotes IoT-enabled farm equipment under digital agriculture initiatives. Subsurface irrigation occupies a narrower premium niche serving high-value orchard operations with elevated installation costs but superior evaporation control.
MIIT equipment certification standards and MEE water efficiency labeling jointly determine market access for pump and controller assemblies sold in China. BIS-equivalent agricultural machinery safety protocols and provincial water quota enforcement from the Ministry of Water Resources shape replacement demand timing across irrigation districts. Stakeholders must monitor how county-level groundwater extraction permits interact with subsidy eligibility rules for efficient equipment upgrades.
Market Dynamics
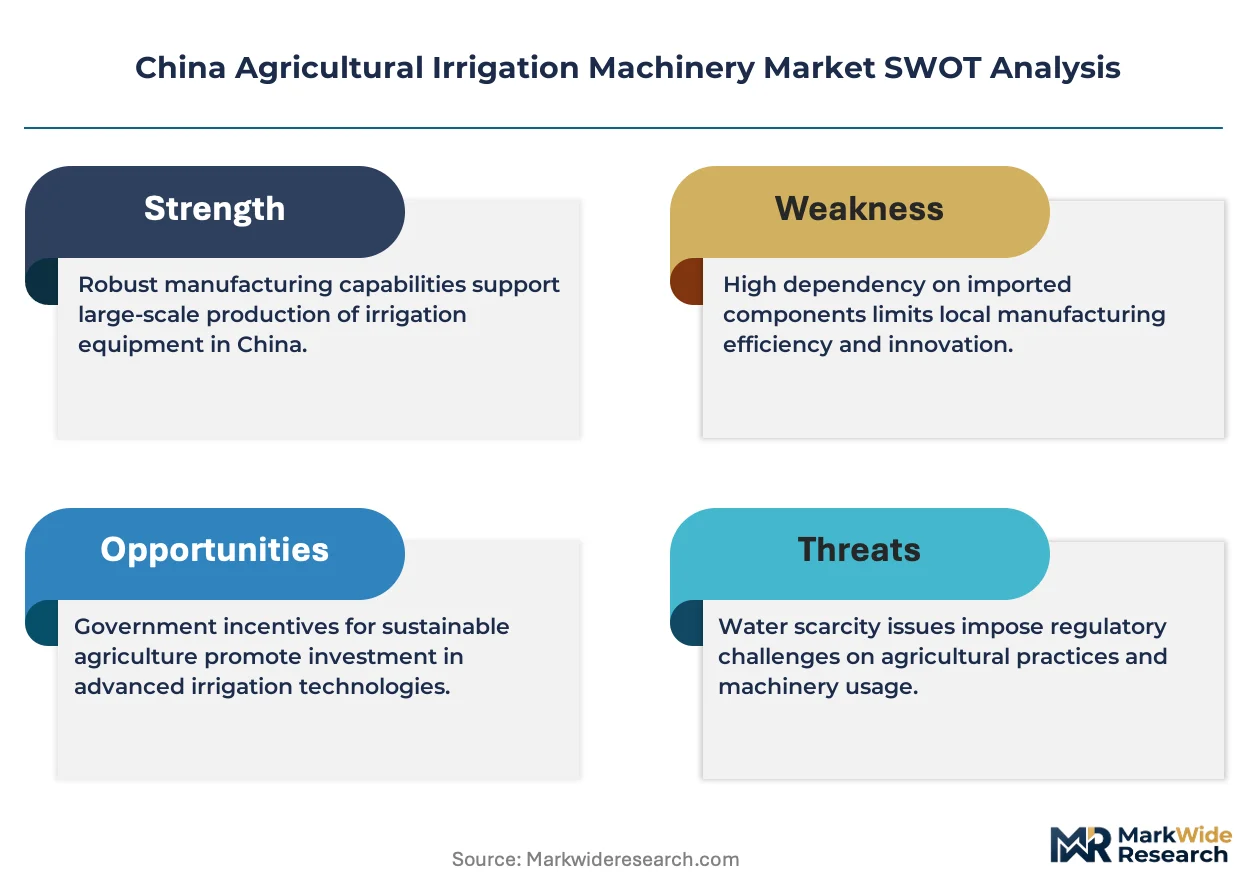
Groundwater conservation mandates from the Ministry of Water Resources are compressing equipment replacement cycles across the North China Plain, forcing cooperatives to retire inefficient flood-irrigation systems ahead of depreciation schedules.
Growth Catalysts
- Dual carbon targets:MEE pump efficiency mandates are accelerating solar-powered system installations on state farms in Heilongjiang and Xinjiang provinces.
- Land consolidation:Agricultural cooperatives leasing fragmented plots from smallholders are creating concentrated demand for mechanized drip networks at scale.
- Digital agriculture promotion:MIIT IoT certification pathways are subsidizing smart controller adoption in water-stressed cultivation zones.
Market Restraints
- Polymer resin volatility:Drip emitter and pipe production faces margin compression from petrochemical feedstock price swings.
- Installation labor scarcity:Subsurface system deployment requires specialized trenching crews concentrated in Shandong and Jiangsu provinces.
- Groundwater quota enforcement:County-level extraction permit reductions are freezing capital expenditure planning for orchard operators in Hebei.
Strategic Opportunities
- High-value orchard segment:Subsurface irrigation penetration remains below fifteen percent in Xinjiang's apple and grape operations.
- Service unbundling:Remote monitoring subscriptions are creating recurring revenue streams independent of hardware sales.
- Export-adjacent domestic channels:Coastal logistics hubs near Xiamen enable same-day fulfillment to Southeast Asian buyers.
Industry Challenges
- Field technician shortage:Pressure-compensating emitter troubleshooting requires training unavailable in county vocational programs.
- Legacy system integration:Smart controllers must interface with twenty-year-old diesel pumps lacking standardized electrical interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Agricultural Irrigation Machinery Market |
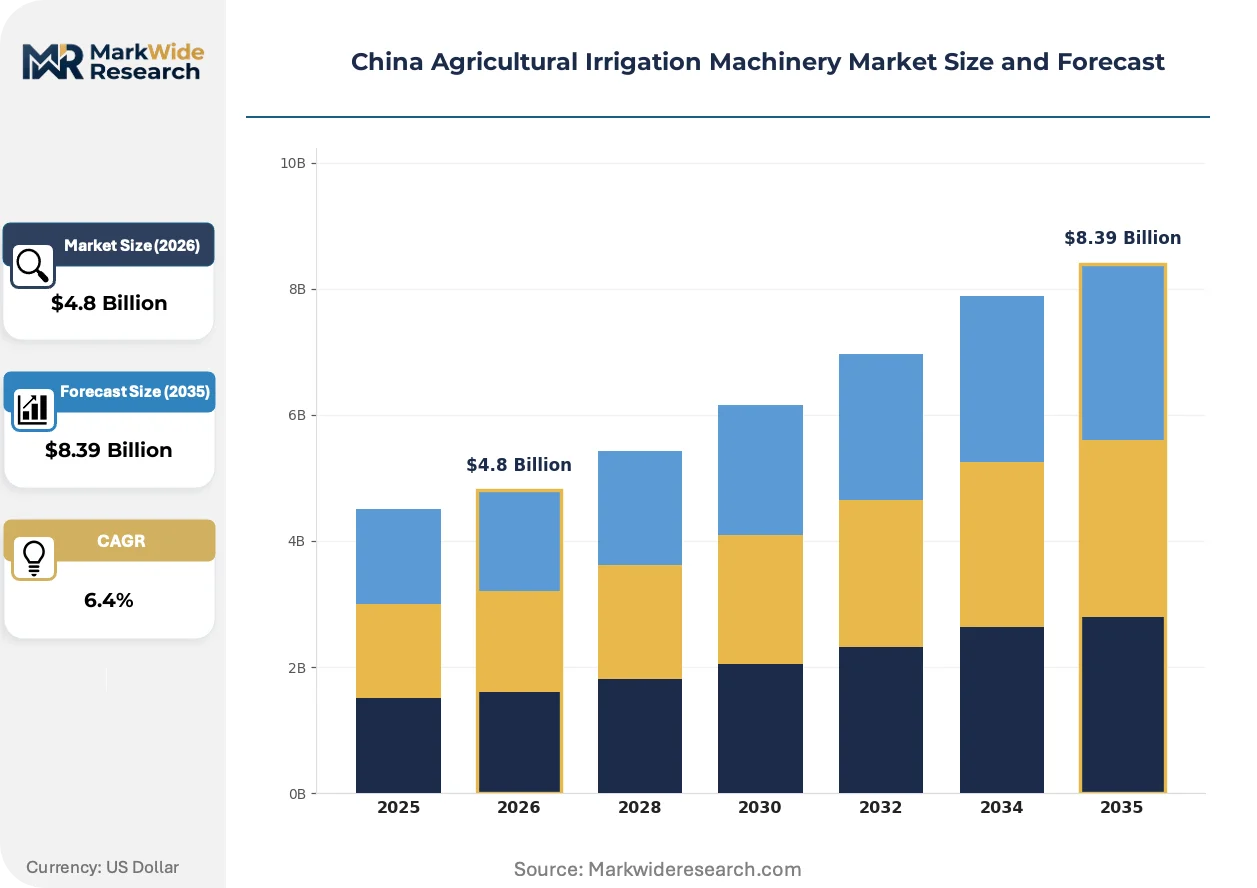
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip Irrigation, Sprinkler Systems, Center Pivot, Subsurface Irrigation End User: Farms, Greenhouses, Orchards, Agricultural Cooperatives Technology: Automated Systems, Smart Irrigation, Traditional Methods, Conical Pumps Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Agricultural Shows |
| Companies Covered | Chinadrip Irrigation Equipment (Xiamen) Co., Ltd., Dayu Irrigation Group Co. Ltd, Lindsay Corporation, The Toro Company, Rain Bird Co. Ltd., Orbia Group (Netafim), T-L Irrigation Co., Valmont Industries, Weichai Lovol Intelligent Agricultural Technology Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Agricultural Irrigation Machinery Market Strategic Shifts
Solar-diesel hybrid pump architectures are rewriting power-source economics for off-grid irrigation districts. Equipment vendors are racing to certify integrated energy-storage controllers under MIIT's evolving standards framework.
Variable-frequency drive technology is modularizing pump system design across the North China Plain. Agricultural cooperatives in Hebei and Shandong are retrofitting existing diesel installations with VFD-compatible electric motors at accelerated pace. This retrofit wave is modularizing the traditional bundled pump-controller market into separable component procurement.
MEE water efficiency labeling is tightening market access for uncertified pump assemblies sold in China. The regulation forces manufacturers to submit third-party test data on flow-rate performance curves. Low-efficiency centrifugal pump models are exiting distribution channels in Henan and Anhui provinces ahead of enforcement deadlines.
Cooperative procurement officers are consolidating annual equipment tenders into multi-year framework agreements with performance guarantees. Traditional county-level dealer networks are losing volume to direct manufacturer relationships. This consolidation is most visible in Heilongjiang's state farm system where thousand-hectare operators negotiate enterprise pricing.
China Agricultural Irrigation Machinery Market Segmentation
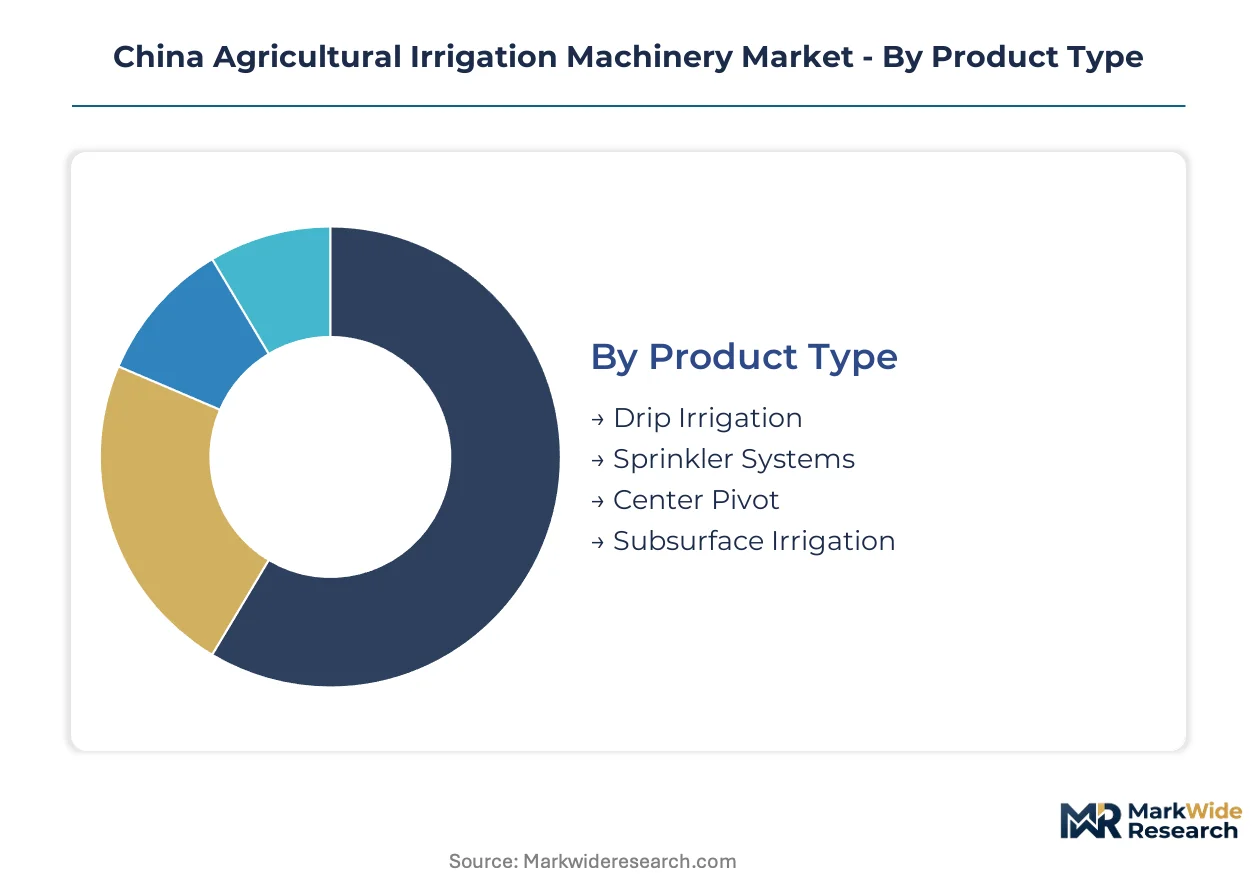
Equipment configuration varies sharply across cultivation scales and water access conditions in China. Understanding segment boundaries clarifies why state farms and cooperatives source through entirely different procurement channels despite operating identical crop types.
Product Type:
Buyers differentiate primarily by capital intensity tolerance and water scarcity exposure rather than crop category alone.
- Drip Irrigation:Pressurized networks operating at 0.5–2.5 bar deliver controlled water volumes directly to root zones through polymer emitters. Demand concentrates in Hebei and Shandong provinces where MEE water efficiency mandates are forcing cooperatives to replace flood-irrigation infrastructure ahead of depreciation schedules.
- Sprinkler Systems:Above-canopy distribution assemblies operating at 2–5 bar suit broad-acre grain operations with moderate terrain variation. North China Plain state farms in Henan are consolidating procurement into multi-year framework agreements for these systems as labor costs rise.
- Center Pivot:Self-propelled lateral boom configurations dominate Xinjiang's thousand-hectare cotton operations with flat topography and deep groundwater access.
- Subsurface Irrigation:Buried emitter lines at 20–40 centimeter depth serve premium orchard segments in Xinjiang's grape and apple belts where evaporation control justifies elevated installation costs.
Drip irrigation leads volumes today; subsurface irrigation is gaining share fastest in high-value cultivation zones.
End User:
Scale concentration determines equipment specification complexity and service bundling requirements.
- Farms:State-owned operations in Heilongjiang and Xinjiang drive mechanized irrigation coverage expansion through enterprise-scale tenders.
- Greenhouses:Controlled-environment vegetable producers in Shandong demand precision fertigation integration with climate control systems.
- Orchards:Apple and grape operators in Xinjiang face frozen capital expenditure planning where county-level groundwater quota enforcement has tightened extraction permits.
- Agricultural Cooperatives:Consolidated land-leasing entities across the North China Plain create concentrated demand for drip networks at scale, displacing fragmented smallholder procurement patterns.
Agricultural cooperatives are displacing individual farm procurement fastest; state farms retain the largest absolute equipment volumes.
Technology:
Regulatory certification pathways split procurement between subsidized upgrade programs and legacy replacement cycles.
- Automated Systems:Timer-based valve controllers with minimal sensor integration occupy a mid-tier position between manual operation and full IoT connectivity.
- Smart Irrigation:MIIT-certified IoT-enabled controllers with soil-moisture and weather-data integration are expanding most quickly in water-stressed districts where digital agriculture subsidies apply.
- Traditional Methods:Gravity-fed flood irrigation and manual valve operation persist in peripheral provinces where MEE efficiency labeling enforcement remains uneven.
- Conical Pumps:Specialized centrifugal configurations for high-sand-content groundwater dominate Xinjiang's deep-well extraction operations.
Traditional methods still account for the largest installed base; smart irrigation is climbing the fastest on new installation tenders.
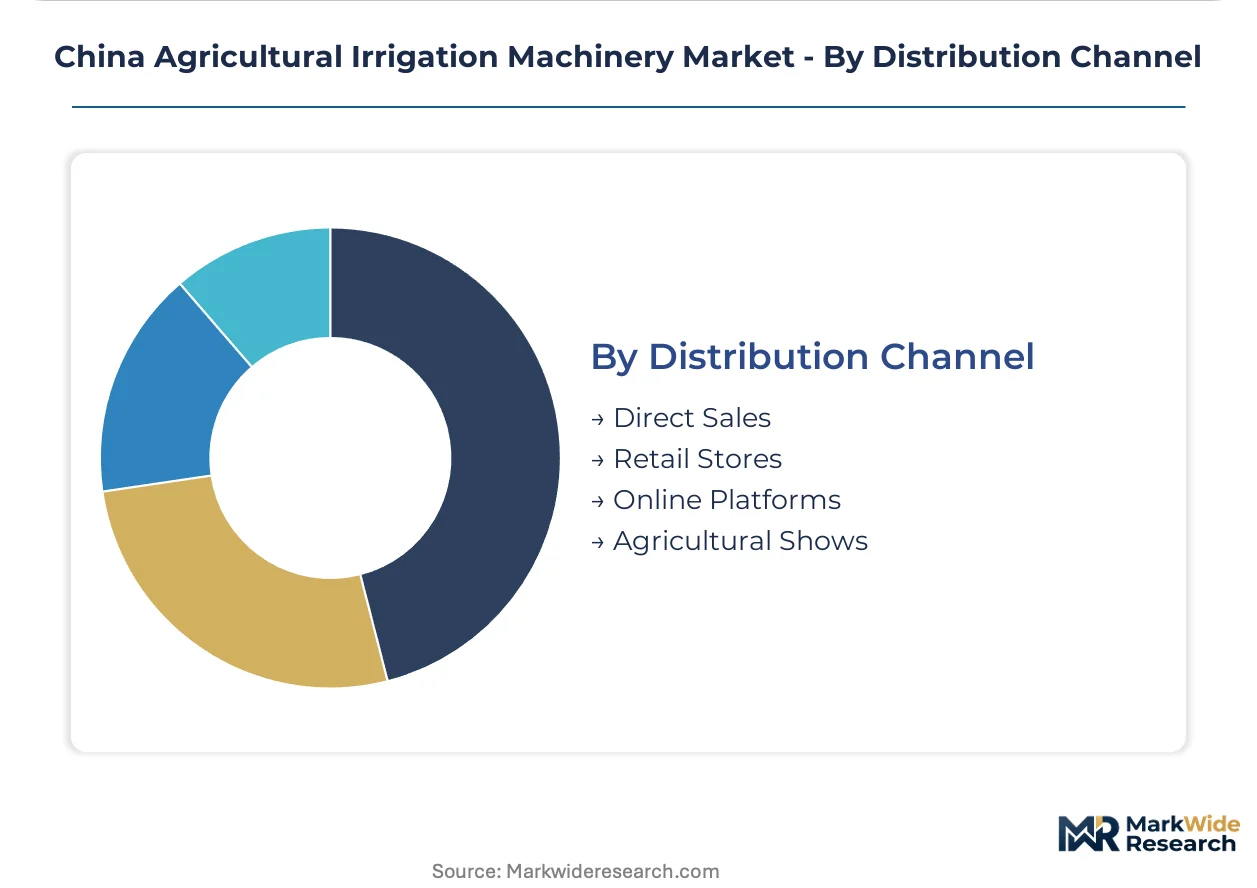
Distribution Channel:
Logistics configuration and technical service requirements separate procurement pathways by buyer scale.
- Direct Sales:Manufacturer relationships with Heilongjiang state farm systems bypass traditional county dealer networks through enterprise pricing negotiations.
- Retail Stores:Provincial agricultural machinery markets in Shandong serve smaller cooperatives requiring immediate parts availability.
- Online Platforms:E-commerce channels are gaining traction for standardized emitter and pipe components where specification is commoditized.
- Agricultural Shows:Seasonal exhibitions in Henan and Anhui provinces facilitate equipment demonstration and subsidy documentation for cooperative procurement officers.
Direct sales dominate value concentration; online platforms are expanding most quickly for consumable components.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision engineering tradition contrasts with China's state-directed consolidation when shaping irrigation machinery procurement. Both markets prioritize efficiency mandates, yet regulatory instruments differ sharply. This divergence creates distinct competitive entry barriers across major producing regions.
United States
Great Plains grain operations drive center-pivot system demand across Nebraska and Kansas. EPA water quality standards intersect with USDA conservation programs to subsidize precision emitter retrofits. Manufacturing clusters in Omaha and Fresno anchor domestic supply chains for large-diameter aluminum lateral systems.
Germany
Specialized horticulture producers in Bavaria and Baden-Württemberg specify high-pressure misting assemblies for greenhouse operations. REACH chemical compliance and EU Green Deal water efficiency directives constrain polymer emitter formulations. Stuttgart-area engineering firms dominate variable-frequency drive controller exports to Mediterranean buyers.
India
Micro-irrigation penetration accelerates in Maharashtra and Gujarat amid sugarcane and cotton water stress. BIS equipment certification and central government PM-KUSUM solar pump subsidies reshape distributor inventory priorities. Coimbatore's pump manufacturing belt is expanding capacity for surface-solar hybrid architectures.
Brazil
Cerrado soybean and sugarcane estates in Mato Grosso and São Paulo states drive mechanized sprinkler tender volumes. ANVISA agricultural chemical integration rules affect fertigation system specifications. Ribeirão Preto's equipment assembly corridor is consolidating around multi-year service contracts for thousand-hectare operators.
China Agricultural Irrigation Machinery Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. Market structure concentrates around three to five integrated manufacturers serving state farm systems, while fragmented regional assemblers occupy secondary cooperative segments. Strategic archetypes separate scale-driven full-line suppliers, precision technology licensors, and solar-hybrid system integrators. Dominant competitive moves include direct manufacturer bypass of county dealer networks and multi-year framework agreements with performance guarantees.
Within the precision technology tier, Orbia Group (Netafim) and Chinadrip Irrigation Equipment (Xiamen) Co., Ltd. exemplify contrasting geographic positioning strategies. Dayu Irrigation Group Co. Ltd represents the scale-driven domestic archetype with Shandong province manufacturing depth. Lindsay Corporation and Valmont Industries occupy positions among North American lateral-move and center-pivot system providers. These five entities collectively span the premium emitter, mechanized boom, and integrated controller segments without overlapping core competencies.
| Leading Market Players |
|---|
| Chinadrip Irrigation Equipment (Xiamen) Co., Ltd. |
| Dayu Irrigation Group Co. Ltd |
| Lindsay Corporation |
| The Toro Company |
| Rain Bird Co. Ltd. |
| Orbia Group (Netafim) |
| T-L Irrigation Co. |
| Valmont Industries |
| Weichai Lovol Intelligent Agricultural Technology Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Solar-diesel hybrid pump architectures are compressing cost economics across Shandong and Heilongjiang manufacturing clusters while concentrating procurement leverage among thousand-hectare state farm operators. This technology transition simultaneously erodes margin buffers for pure-play diesel pump assemblers and rewards integrated energy-storage controller vendors with pricing power in enterprise tenders.
Pricing Analysis
Capacity additions in Shandong province are reshaping price floors for polymer emitter assemblies as Dayu Irrigation Group scales manufacturing depth. Three-tier pricing structure across premium, standard, and economy levels separates MIIT-certified smart controllers from basic timer-based valves and uncertified legacy units. Cost compression in standard-tier drip networks is intensifying because agricultural cooperatives consolidate procurement into multi-year framework agreements. County-level dealers face the steepest price sensitivity as direct manufacturer relationships bypass traditional markups.
Supply Chain Analysis
Domestic-content mandates under MIIT equipment certification standards are reshaping sourcing patterns for pump motor windings and controller circuit boards. Manufacturing gravity centers on Shandong, Jiangsu, and Hebei provinces, with polymer resin feedstock drawing from petrochemical complexes in Ningbo and Dalian. Supply chain risk hinges on single-source vulnerability for high-efficiency permanent magnet motors sourced from concentrated electromechanical clusters. Distribution runs through direct manufacturer relationships with state farm systems alongside provincial agricultural machinery markets serving smaller cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on solar-hybrid system penetration displacing legacy diesel installations and premium-tier smart controller adoption accelerating under MIIT digital agriculture subsidies.
For Market Incumbents: Deploy multi-year performance-guarantee frameworks to lock in state farm procurement cycles before county-level groundwater quotas freeze capital expenditure planning. Deepen backward integration into polymer emitter manufacturing to offset petrochemical feedstock volatility threatening margin stability. Channel control through direct technical service teams counters emerging solar-hybrid system integrators poaching enterprise accounts in Xinjiang. For New Entrants and Emerging Players: Capture subsurface irrigation white space in Xinjiang's apple and grape belts where penetration remains below fifteen percent and installation labor scarcity blocks incumbent expansion. Target remote monitoring subscription revenue independent of hardware sales, anchoring recurring income streams before equipment commoditization accelerates. Pursue coastal logistics positioning near Xiamen to serve Southeast Asian export channels with same-day fulfillment capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among tier-two regional assemblers lacking MIIT certification pathways but holding established county-level dealer networks convertible to smart controller distribution. Long-term viability favors integrated manufacturers with captive solar-hybrid system development and direct state farm relationships spanning the analysis window. Watch county-level groundwater extraction permit issuance rates as the inflection signal for equipment replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Solar-Hybrid System Certification | MIIT energy-storage controller standards unlock subsidy eligibility for state farm tenders in Heilongjiang. |
| Backward Integration into Polymer Manufacturing | Captive emitter production hedges petrochemical feedstock volatility compressing margins across Shandong. |
| Remote Monitoring Platform Launch | Subscription revenue streams decouple growth from hardware sales cycles in saturated drip segments. |
| Direct State Farm Relationship Building | Enterprise pricing negotiations bypass county dealer networks losing volume to manufacturer channels. |
| Subsurface Irrigation Service Capability | Specialized trenching crews unlock premium orchard segments in Xinjiang with evaporation control demand. |
Study Parameters
Coverage spans Heilongjiang, Xinjiang, Shandong, Hebei, and Henan provinces, with primary inputs from each region's agricultural cooperative procurement officers, state farm equipment managers, MIIT certification consultants, polymer resin procurement leads, and county-level groundwater regulation administrators. Secondary validation draws from MIIT equipment certification databases, Ministry of Water Resources extraction permit filings, provincial agricultural machinery market trade data, and customs records for export-adjacent channels. Bottom-up equipment installation tallies triangulate against top-down subsidy disbursement tracking.
Granularity-level modeling disaggregates volume and value across product type, end user scale, technology tier, and distribution channel dimensions throughout the forecast period. CAGRs derive from equipment replacement cycle analysis intersecting regulatory enforcement timelines with subsidy eligibility windows. Industry-specific inputs include county-level groundwater quota implementation schedules and MIIT IoT certification pathway evolution for smart controller eligibility.
Regulatory enforcement delays, petrochemical feedstock price spikes, and county-level permit issuance freezes are the dominant revision risks to installation forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Irrigation Liner Market
Farm Equipment and Irrigations
Sprinkler Irrigation Market
Farm Equipment and Irrigations
Europe Irrigation Valves Market
Farm Equipment and Irrigations
Smart Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Golf Irrigation Market
Farm Equipment and Irrigations
Hose Reel Irrigation Machine Market
Farm Equipment and Irrigations
Drip Irrigation Market
Farm Equipment and Irrigations
Potato Planter Market
Farm Equipment and Irrigations
Global Irrigation Machinery Market
Farm Equipment and Irrigations
Global Fruit Picker Market
Farm Equipment and Irrigations
India Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Asia Pacific Irrigation Valves Market
Farm Equipment and Irrigations
Fertigation Control System Market
Farm Equipment and Irrigations
Global Center Pivot Irrigation Systems Market
Farm Equipment and Irrigations
Grass Trimmer Market
Farm Equipment and Irrigations
Soaker Hose Irrigation System Market