
 Global Center Pivot Irrigation Systems Market | 2026-2036
Global Center Pivot Irrigation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Center Pivot Irrigation Systems Market Analysis
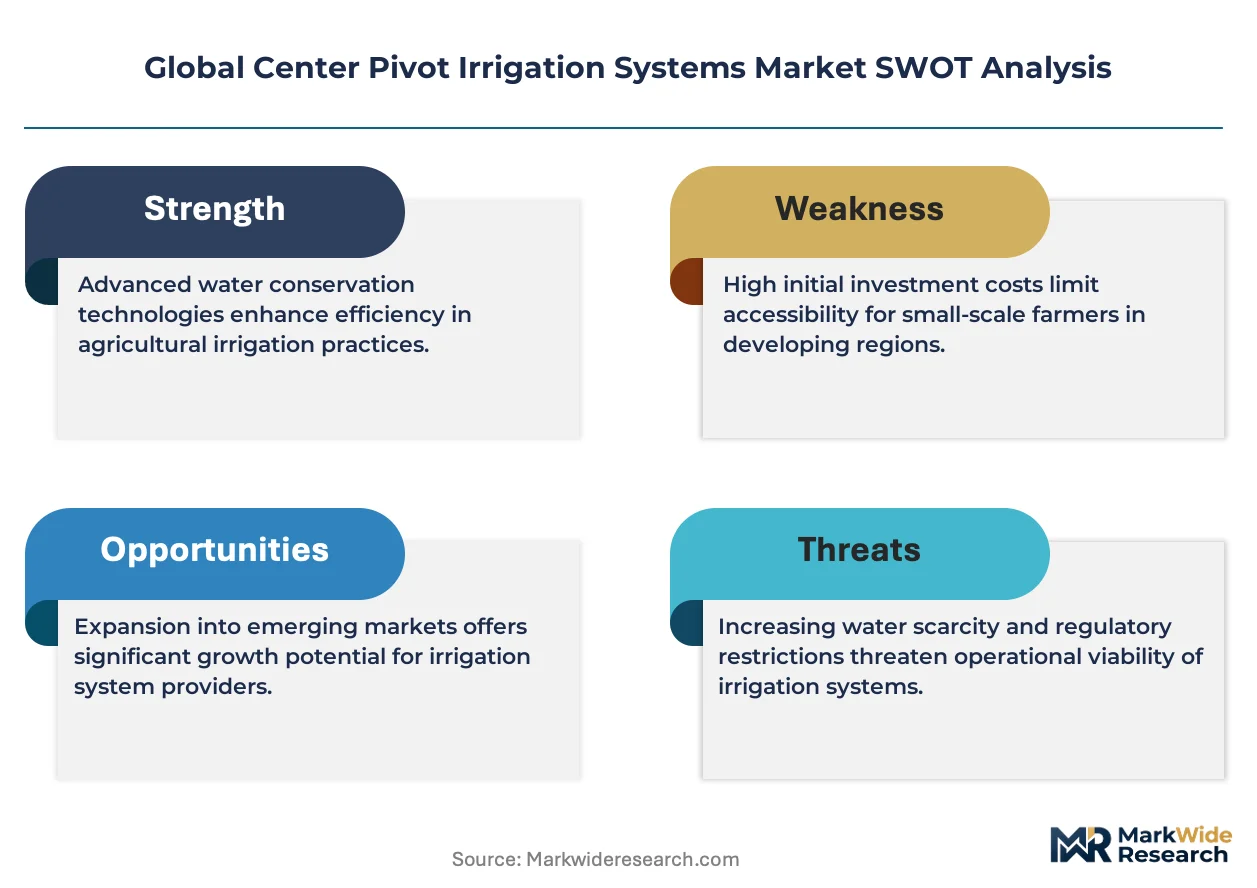
The EU Green Deal is restructuring capital allocation across mechanized irrigation supply chains, tightening emissions benchmarks for pump motors and steel fabrication inputs. Valmont Industries leverages its in-house tower manufacturing and galvanizing capacity to control component costs across North American and Australian deployments. Lindsay Corporation anchors its position through advanced remote monitoring platforms that integrate soil-moisture telemetry with pivot automation. Jain Irrigation Systems Ltd. competes on polyline and drip-component backward integration, extending its cost advantage in emerging markets.
Center pivot irrigation systems consist of modular steel truss towers mounted on wheeled bases, rotating around a central water-supply point to distribute pressurized flow through overhead sprinkler drops across circular or part-circle field patterns. Standard spans range from 130 to 200 feet with pipeline diameters of 6 to 8 inches, engineered to maintain uniform application depths across variable topography. Fixed pivots dominate installed base value due to their structural permanence and compatibility with large-field grain operations, while smart irrigation technology represents the fastest-expanding segment as variable-rate prescriptions and satellite-linked controls displace manual panel settings. Solar-powered systems occupy a narrower but growing niche where grid extension costs prohibit conventional electric motor drives.
The EPA enforces water-quality standards that restrict agricultural runoff from poorly managed irrigation, indirectly mandating precision application technologies that center-pivot systems deliver. ISO 8224 and IEC motor-efficiency classifications shape product design specifications for international market access, particularly in regions adopting harmonized equipment standards. China's MEE groundwater withdrawal permitting system and Australia's Murray-Darling Basin cap-and-trade frameworks are converging toward volume-monitored irrigation, a trajectory that rewards telemetry-integrated system architectures. Stakeholders must weigh capital deployment toward retrofit connectivity kits against full-system replacement cycles as regulatory telemetry mandates spread.
Market Dynamics
Telemetry-integrated pivot architectures are restructuring competitive advantage as water accounting mandates spread from Australia's Murray-Darling Basin to China's MEE permitting zones and the EU's F-Gas enforcement corridors.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant-phaseout timelines are accelerating pump-motor retrofits across Spain's Ebro Valley and Italy's Po Basin, converting flood-irrigated acreage to precision pivot coverage.
- Brazilian soybean frontier expansion:Mato Grosso and Goiás producers are mechanizing Cerrado savanna conversion at scale, with center-pivot systems displacing rain-fed dependency amid intensifying dry spells.
- Satellite-linked variable-rate control:Soil-moisture telemetry integration is compressing manual calibration cycles, enabling prescription irrigation that matches nozzle output to real-time crop-stress indices.
Market Restraints
- Galvanized steel input volatility:Tower fabrication costs swing with zinc price exposure, squeezing margin structures for system assemblers lacking captive galvanizing capacity.
- Groundwater extraction permitting:China's MEE volume-monitored withdrawal system and India's CEA state-level clearance requirements are extending sales-to-commissioning timelines by 8-14 months in stressed aquifer zones.
- Drip irrigation substitution:Polyline micro-irrigation is capturing high-value vegetable and orchard segments where water-use efficiency premiums outweigh pivot mechanization benefits.
Strategic Opportunities
- Sub-Saharan Africa mechanization gaps:Zambia's Copperbelt and Nigeria's Kaduna irrigation schemes present untapped demand for solar-powered pivot systems where grid extension costs exceed equipment capital outlay.
- US IRA clean-energy incentives:Tax credits for renewable-powered agricultural equipment are lowering effective cost barriers for electric-motor retrofits across Nebraska and Kansas corn-soy operations.
- Telematics-platform unbundling:Aftermarket connectivity kits are opening recurring-revenue streams from installed-base retrofit, decoupling hardware sales from software subscription attach rates.
Industry Challenges
- Electro-hydraulic technician scarcity:Pivot automation deployment outpaces vocational training pipeline for mechatronics specialists capable of field-calibrating variable-frequency drive systems.
- Legacy panel integration friction:1990s-era Zimmatic and Reinke installations lack standardized data protocols, forcing costly gateway hardware deployment to achieve telemetry interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Center Pivot Irrigation Systems Market |
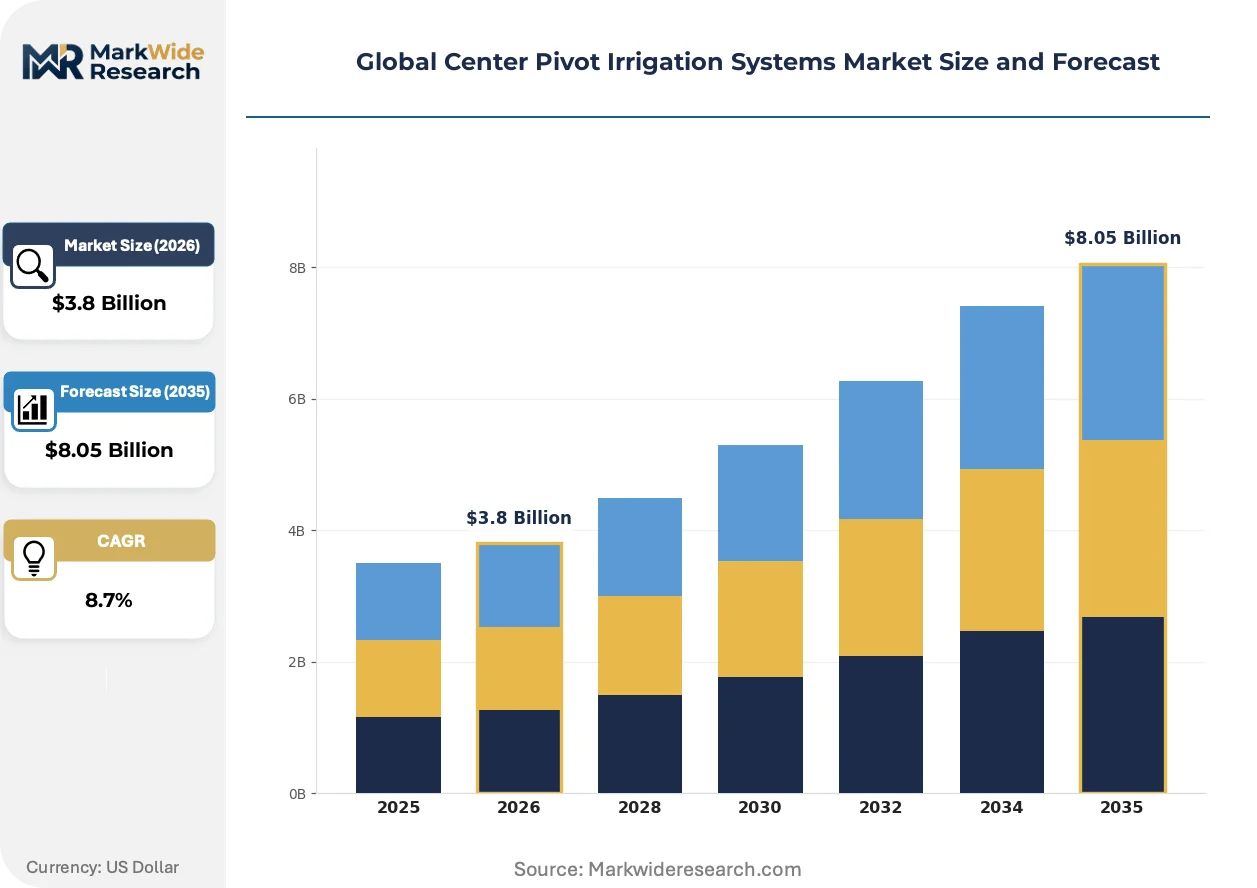
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Pivots, Portable Pivots, Subsurface Drip Systems, Lateral Move Systems Technology: Manual Control, Automatic Control, Smart Irrigation, Solar-Powered Systems End User: Agricultural Producers, Agricultural Cooperatives, Government Agencies, Research Institutions Distribution Channel: Direct Sales, Distributors, Online Retail, Third-Party Retail |
| Companies Covered | T-L Irrigation Company, Jain Irrigation Systems Ltd., Valmont Industries, Rivulis Irrigation, Pierce Corporation, Lindsay Corporation, Netafim, Alkhorayef Group, Reinke Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Center Pivot Irrigation Systems Market Emerging Trajectories
Control-layer digitization is compressing the gap between irrigation prescription and execution, embedding algorithmic decision-making directly into field hardware rather than farm-office software.
Low-energy precision application (LEPA) nozzle technology is expanding into Texas Panhandle and Oklahoma cotton operations where wind drift and evaporative loss erode conventional overhead efficiency. Mid-scale producers are retrofitting existing spans with bubble-mode delivery systems that deposit water directly into crop furrows. This hardware conversion is expanding into drought-stressed grain districts previously deemed uneconomical for mechanized irrigation.
Australia's Murray-Darling Basin cap-and-trade framework is enforcing volumetric accountability that exceeds ISO 8224 equipment standards, compelling manufacturers to embed flow-meter certification directly into span pipeline architecture. Basin water entitlements now trade as financial instruments, making telemetry audit trails a prerequisite for market participation. European regulators are studying this model for potential F-Gas-phaseout irrigation adaptation.
Service unbundling is fragmenting traditional equipment-sale economics across the US Great Plains. Nebraska and Kansas dealers are separating hardware delivery from annual calibration contracts, with remote diagnostics subscriptions displacing scheduled maintenance visits. This consumption-pattern shift concentrates margin capture in software-enabled retention rather than upfront equipment financing.
Global Center Pivot Irrigation Systems Market Segmentation
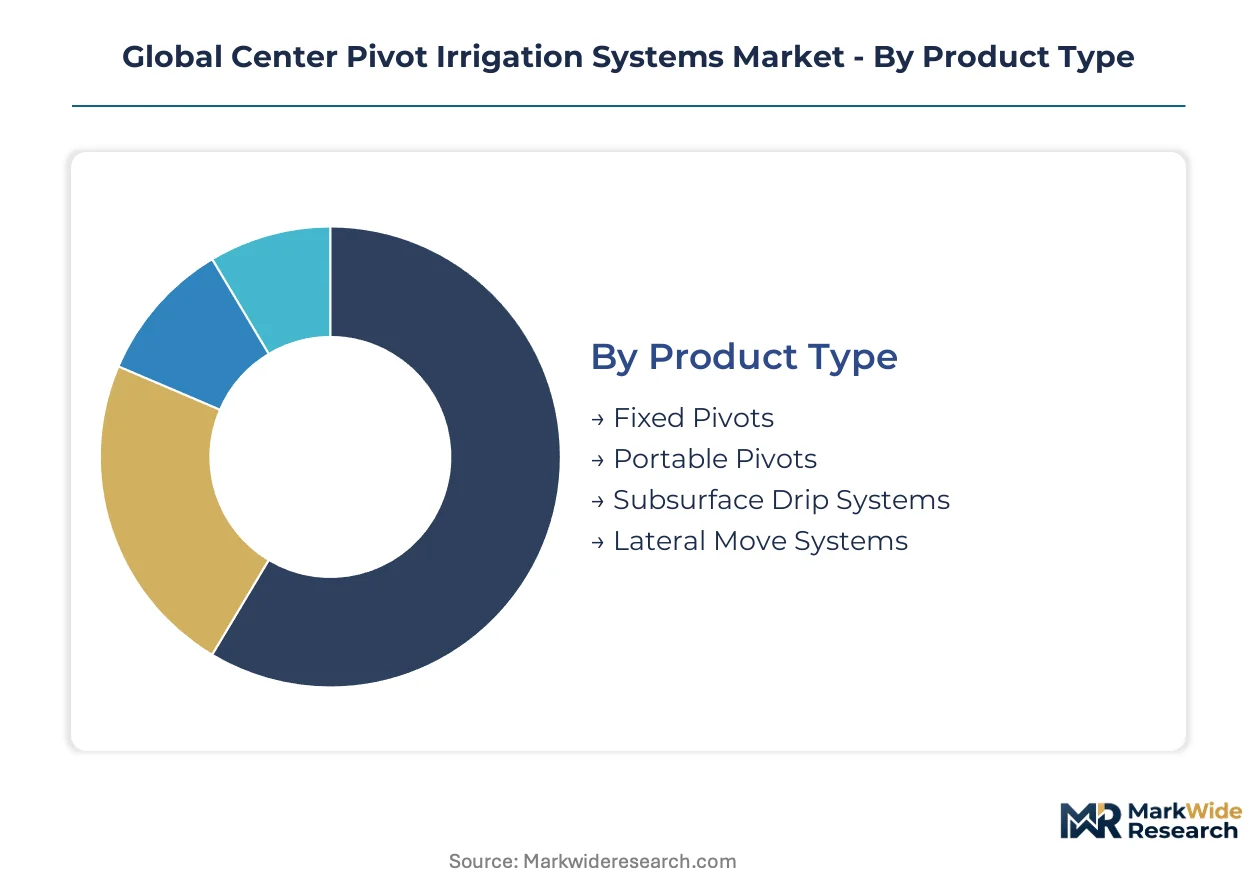
Center pivot irrigation systems fragment across product architectures, automation tiers, buyer types, and procurement channels. Each segmentation axis reveals distinct margin structures, installation complexity, and aftermarket attachment potential that shape vendor strategy.
Product Type:
Fixed pivots anchor the installed base as permanent infrastructure investments, while portable and specialty systems serve transitional or constrained deployment environments.
- Fixed Pivots:Modular steel truss towers mounted on permanent concrete pads deliver pressurized water through 6-8 inch diameter spans across 130-200 foot standard lengths. Nebraska and Kansas grain operations favor these systems for multi-decade depreciation schedules and compatibility with GPS-guided field equipment.
- Portable Pivots:Lightweight aluminum or hybrid truss designs mount on skid bases rather than fixed anchors, enabling seasonal relocation across leased acreage. Australian broadacre wheat producers deploy portable units where annual water allocation uncertainty discourages permanent infrastructure commitment.
- Subsurface Drip Systems:Buried polyline emitter networks deliver water directly to root zones beneath crop rows.
- Lateral Move Systems:Linear-tracking booms traverse rectangular fields where central-point pivot geometry creates unirrigated corners.
Volume placements concentrate in Fixed Pivots; the faster expansion belongs to Portable Pivots.
Technology:
Control sophistication separates price tiers and determines recurring revenue potential through software subscriptions and telemetry services.
- Manual Control:Mechanical timer panels and hydraulic sector valves require operator presence for speed and depth adjustments. Brazil's Mato Grosso soybean frontier still deploys manual systems where labor costs remain below automation premiums and grid connectivity is unreliable.
- Automatic Control:Programmable logic controllers execute preset schedules without continuous supervision. Spain's Ebro Valley corn operations adopted automatic panels during prior EU drought-response funding cycles.
- Smart Irrigation:Satellite-linked variable-rate systems integrate soil-moisture telemetry, weather APIs, and prescription algorithms for real-time nozzle adjustment.
- Solar-Powered Systems:Photovoltaic arrays drive DC motor pumps where grid extension costs exceed equipment capital outlay.
Smart Irrigation is climbing the fastest as water accounting mandates spread; Solar-Powered Systems occupy the narrowest commercial niche.
End User:
Buyer scale and procurement authority determine contract structure, financing terms, and service bundling requirements.
- Agricultural Producers:Individual farm operators purchasing 1-4 systems per deployment, typically financing through equipment lenders or manufacturer captive finance. Iowa and Illinois row-crop operations dominate this segment with corn-soy rotation irrigation requirements.
- Agricultural Cooperatives:Pooled procurement entities aggregating demand across 50-200 member farms for volume pricing and shared maintenance infrastructure. North Dakota wheat cooperatives coordinate seasonal pivot relocation across member properties.
- Government Agencies:Public irrigation scheme administrators in China's Henan and Shandong provinces deploy state-funded systems on reclaimed land.
- Research Institutions:University extension services and agronomy stations operating demonstration plots for cultivar stress trials.
Procurement volume clusters with Agricultural Producers; institutional buyers drive specification innovation through pilot programs.
Distribution Channel:
Channel selection reflects buyer technical sophistication, geographic density, and service dependency.
- Direct Sales:Manufacturer-employed territory managers handle specification, financing, and installation coordination for orders exceeding 10-system thresholds. Valmont and Lindsay deploy direct teams across the US Great Plains and Australian Murray-Darling Basin.
- Distributors:Independent dealer networks stock inventory, provide field service, and extend localized credit to mid-scale producers. Kansas and Oklahoma cotton districts rely on distributor technical support for LEPA nozzle retrofits.
- Online Retail:E-commerce platforms list replacement components, control panels, and sprinkler packages for self-installation.
- Third-Party Retail:Agricultural supply cooperatives and farm equipment consortia aggregate seasonal demand.
System placements flow predominantly through Distributors; Direct Sales capture the largest individual contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act's clean-energy tax credits are concentrating capital deployment across Nebraska and Kansas corn-soy belts, accelerating electric-motor retrofits and solar-powered pivot installations.
United States
Large-scale grain operations across the Great Plains are expanding mechanized irrigation coverage to sustain yields amid intensifying drought cycles. The EPA enforces water-quality standards that restrict agricultural runoff from poorly managed irrigation, indirectly mandating precision application technologies. Nebraska and Kansas host the densest concentration of fixed pivot installations, with dealers separating hardware delivery from annual calibration contracts.
Brazil
Expanding soybean frontiers in Mato Grosso and Goiás are converting rain-fed Cerrado savanna into irrigated cropland at accelerating rates. ANVISA regulates agricultural equipment safety standards while state-level water boards enforce extraction permits. The Mato Grosso soybean belt represents the fastest-growing demand cluster for portable pivot systems among leased-acreage operators.
China
State-funded irrigation schemes in Henan and Shandong provinces deploy systems on reclaimed land to secure domestic grain production. The MEE groundwater withdrawal permitting system enforces volume-monitored irrigation, extending sales-to-commissioning timelines by 8-14 months in stressed aquifer zones. The North China Plain concentrates government-procured fixed pivot installations for wheat and corn cultivation.
Australia
Broadacre wheat producers in the Murray-Darling Basin deploy portable units where annual water allocation uncertainty discourages permanent infrastructure commitment. The Basin's cap-and-trade framework enforces volumetric accountability that exceeds ISO 8224 equipment standards, compelling flow-meter certification embedded in span pipeline architecture. New South Wales and Victoria host telemetry-integrated system deployments tied to water entitlement trading.
Germany
Precision agriculture adoption across Brandenburg and Saxony-Anhalt is upgrading flood-irrigated acreage to pivot systems under EU F-Gas Regulation compliance timelines. The EU Green Deal tightens emissions benchmarks for pump motors and steel fabrication inputs, restructuring capital allocation across mechanized irrigation supply chains. Eastern German grain cooperatives aggregate demand for volume pricing and shared maintenance infrastructure.
Global Center Pivot Irrigation Systems Market Vendor Landscape
North American producers anchor one tier; European and Middle Eastern specialists hold differentiated positions in telemetry integration and regional fabrication. The vendor base concentrates around three strategic archetypes: vertically integrated tower manufacturers controlling galvanizing capacity, control-layer specialists monetizing software subscriptions, and polyline-integrated diversifiers leveraging backward component integration. Competitive moves center on captive galvanizing investments and telematics-platform unbundling for aftermarket retrofit revenue.
Among US-based manufacturers, Valmont Industries, Lindsay Corporation, and Reinke Manufacturing Company exemplify the integrated fabrication archetype, each occupying positions spanning tower production through field deployment. Jain Irrigation Systems Ltd. represents the diversified component model, extending cost positioning through captive polyline supply. T-L Irrigation Company anchors the hydraulic-drive specialization segment. These named entities illustrate how competitive positioning fragments across automation sophistication, geographic coverage density, and captive manufacturing depth rather than converging on uniform scale advantages.
| Leading Market Players |
|---|
| T-L Irrigation Company |
| Jain Irrigation Systems Ltd. |
| Valmont Industries |
| Rivulis Irrigation |
| Pierce Corporation |
| Lindsay Corporation |
| Netafim |
| Alkhorayef Group |
| Reinke Manufacturing Company |
| Others |
Supply Flow & Price Mechanics
Telemetry-integrated pivot architectures are compressing cost economics while concentrating supply among galvanizing-capable tower fabricators. Zinc price volatility and ISO 8224 certification requirements are reshaping procurement patterns across Nebraska grain cooperatives and Australian broadacre wheat producers.
Pricing Analysis
Short lead-time premiums apply to smart irrigation retrofits with embedded flow-meter certification, while spot inventory discounts move legacy manual panels. Three-tier pricing structure across premium telemetry-integrated, standard automatic control, and economy manual tiers reflects after-sales service bundling and ISO compliance grade. Pricing pressure stems from galvanized steel input swings squeezing margin structures for non-integrated assemblers. Agricultural cooperatives exhibit highest price sensitivity due to pooled procurement volumes, whereas government agencies in China's Henan province prioritize specification compliance over unit economics.
Supply Chain Analysis
ISO 8224 and IEC motor-efficiency classifications gate market access for span pipeline and drive system suppliers. Tower fabrication concentrates in the United States, Brazil, and China, with steel truss components drawing from captive galvanizing operations and regional zinc smelters. Supply chain risk centers on single-source vulnerability for variable-frequency drive controllers sourced from concentrated electronics manufacturing clusters. Distribution runs through independent dealer networks stocking inventory and extending localized credit across Kansas cotton districts and Mato Grosso soybean frontiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Galvanized steel capacity constraints prop pricing power for integrated tower manufacturers. Captive zinc coating operations represent the binding bottleneck sustaining margin structures.
For Market Incumbents: To counter telemetry-platform unbundling by aftermarket connectivity specialists, deepen backward integration into flow-meter certification hardware and anchor dealer networks with exclusive calibration service contracts. Prioritize captive galvanizing investments to insulate tower costs from zinc price swings. For New Entrants and Emerging Players: Launch via solar-powered pivot systems targeting Zambia's Copperbelt and Nigeria's Kaduna irrigation schemes where grid extension costs exceed equipment capital outlay. White-space concentrates in Sub-Saharan Africa mechanization gaps and US IRA-funded electric-motor retrofits across Nebraska corn-soy operations. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated fabrication conglomerates seeking telemetry capabilities. Long-term viability favors control-layer specialists with recurring software revenue streams. Watch for F-Gas Regulation enforcement acceleration in Spain's Ebro Valley as inflection indicator for European retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Unbundling | Aftermarket connectivity kits unlock recurring revenue from installed-base retrofits across 1990s-era Zimmatic and Reinke systems. |
| Captive Galvanizing Investment | In-house zinc coating capacity insulates Valmont and Lindsay from steel input volatility across North American deployments. |
| Solar-Powered System Launch | Photovoltaic drive systems penetrate Sub-Saharan Africa and Australian off-grid broadacre wheat operations. |
| Dealer Network Consolidation | Direct sales teams capture 10-system thresholds in Murray-Darling Basin while distributors handle LEPA nozzle retrofits. |
| ISO 8224 Certification Embedding | Flow-meter certification integrated into span pipeline architecture satisfies Australia's volumetric accountability mandates. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with irrigation scheme administrators, agricultural cooperative procurement officers, electro-hydraulic technicians, and OEM aftermarket service heads combined with EPA enforcement records, MEE groundwater permitting databases, and Murray-Darling Basin water entitlement trade data. Bottom-up system placement tallies triangulated against top-down agricultural machinery trade flows.
Data-stream reconciliation across equipment shipment records, water withdrawal permit issuances, and dealer inventory positions shaped the analytical framework. Segmentation dimensions span product architecture, automation tier, end-user scale, and procurement channel across the projection horizon. CAGRs derived from fitted growth curves incorporating drought cycle intensity indices, F-Gas Regulation phaseout timelines, and soybean frontier expansion rates in Brazil's Cerrado.
Regulatory enforcement delays, zinc price volatility spikes, and electro-hydraulic technician supply constraints are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding water accounting mandate diffusion and clean-energy incentive continuity. A model refresh is warranted upon material change in EU F-Gas Regulation irrigation adaptation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Weed Trimmer Market
Farm Equipment and Irrigations
Global Anal Irrigation Systems Market
Farm Equipment and Irrigations
Drip Irrigation Market
Farm Equipment and Irrigations
Zero Turn Mowers Market
Farm Equipment and Irrigations
Soaker Hose Irrigation System Market
Farm Equipment and Irrigations
Smart Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Africa Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Potato Planter Market
Farm Equipment and Irrigations
Solar Powered Irrigation System Market
Farm Equipment and Irrigations
North America Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Global Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Irrigation Controllers Market
Farm Equipment and Irrigations
South America Irrigation Machinery Market
Farm Equipment and Irrigations
Global Irrigation Automation Market
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Ride-On Mower Market