
 Europe Irrigation Valves Market | 2026-2036
Europe Irrigation Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Irrigation Valves Market Insights
CE marking under the EU Pressure Equipment Directive is redrawing competitive boundaries for irrigation valve suppliers seeking access to European agricultural markets. Hunter Industries leverages its R&D intensity in smart irrigation controllers to differentiate its valve offerings across Mediterranean markets. Toro Company anchors its position through backward integration into polymer compounding for durable valve housings. Rivulis Irrigation specializes in drip-compatible pressure-regulating valves that dominate greenhouse installations in the Netherlands and Belgium.
Europe irrigation valves are flow-control devices engineered to regulate water distribution across pressurized agricultural networks, typically constructed with brass or stainless steel bodies rated for sustained operating pressures and equipped with threaded or flanged connections for field integration. Ball valves deliver rapid shutoff capability with minimal pressure drop, making them the default choice for mainline isolation in large-scale Spanish and Italian farms, while smart irrigation technology commands premium positioning as remote telemetry and soil-moisture feedback loops displace manual gate valves in precision farming deployments. Stainless steel segments capture margin pools in saline-water and fertigation applications where PVC degradation accelerates replacement cycles.
REACH compliance and the EU F-Gas Regulation shape material selection and actuator design for electrically operated valves across member states, while ECHA substance restrictions on leaded brass alloys are forcing alloy reformulation in Italian and German manufacturing clusters. The EU Green Deal's water-efficiency targets channel public subsidy flows toward smart-controlled retrofits, tightening technical documentation requirements for market access. Stakeholders must monitor the trajectory of EU AI Act classifications as autonomous irrigation algorithms attract compliance scrutiny for decision-making transparency in automated water allocation systems.
Market Dynamics
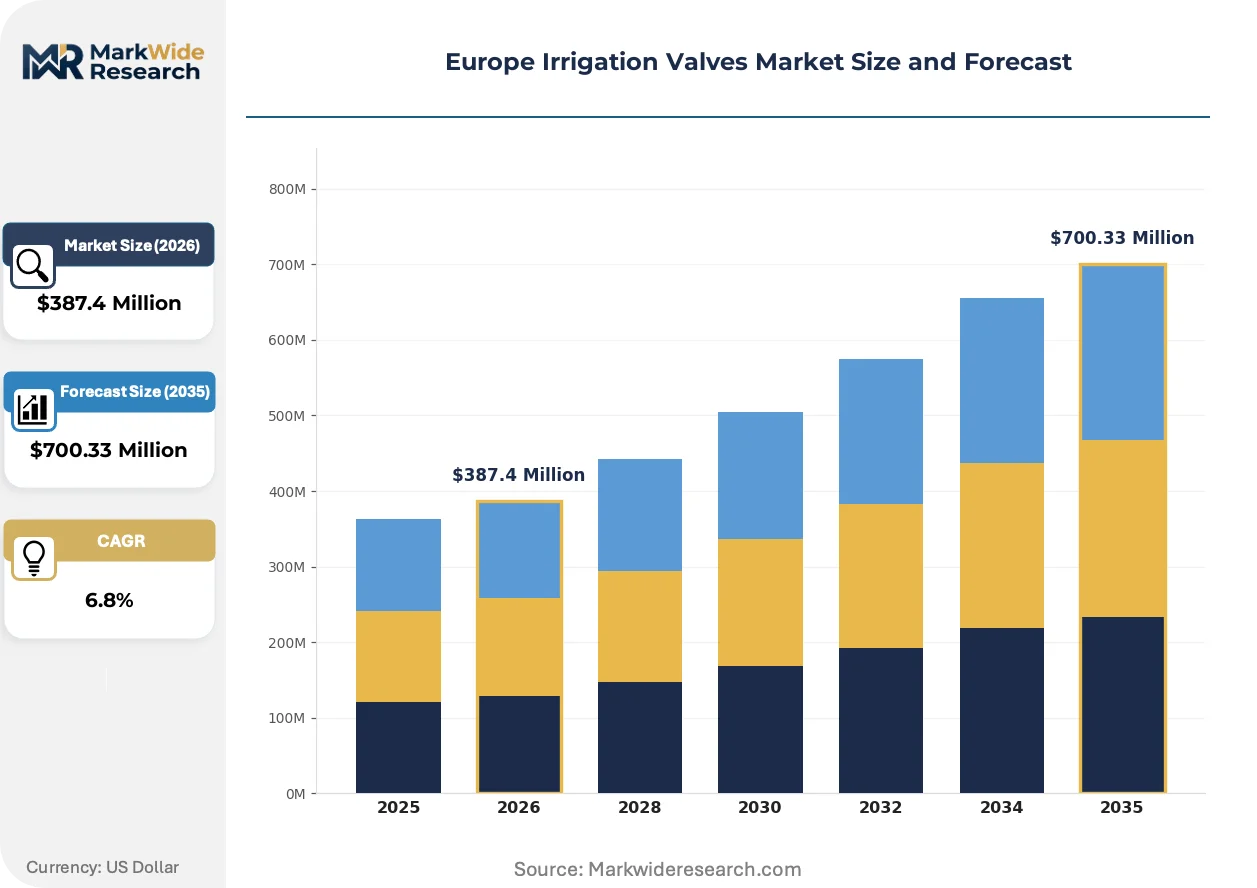
Smart irrigation controllers are compressing replacement cycles across European agricultural networks as farmers retrofit legacy gate valves with telemetry-enabled pressure-regulating systems. The EU Green Deal's water-efficiency mandates are accelerating this hardware refresh.
Growth Catalysts
- EU Green Deal subsidies:Public funding channels toward smart-controlled retrofits in Spain's arid cropping zones, tightening technical documentation requirements for market access.
- Precision agriculture adoption:Soil-moisture feedback loops and remote telemetry displace manual valve operation in Italy's Po Valley intensive fruit production.
- Saline-water infrastructure:Stainless steel valve segments capture margin pools in coastal fertigation applications where PVC degradation accelerates hardware replacement.
Market Restraints
- Alloy reformulation costs:ECHA substance restrictions on leaded brass alloys force Italian and German manufacturing clusters to retool foundry processes.
- CE marking complexity:The EU Pressure Equipment Directive redraws competitive boundaries for suppliers seeking access to European agricultural markets.
- Smart valve premium pricing:Electric actuators with integrated telemetry command hardware cost multiples versus conventional ball valves, limiting penetration among smaller Spanish and Greek farm holdings.
Strategic Opportunities
- Netherlands greenhouse expansion:Drip-compatible pressure-regulating valve demand concentrates in Dutch and Belgian controlled-environment agriculture installations.
- EU AI Act compliance services:Autonomous irrigation algorithms attract scrutiny for decision-making transparency, creating advisory revenue streams for valve-controller integration specialists.
- Fertigation convergence:Chemical injection compatibility is becoming a specification differentiator in French and Portuguese vineyard automation projects.
Industry Challenges
- REACH documentation timelines:Chemical substance registration requirements for polymer valve housings extend product launch cycles by 8-14 months.
- Legacy system integration:Retrofitting smart actuators onto existing PVC mainline infrastructure in older Italian irrigation cooperatives requires custom flange adapters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Irrigation Valves Market |
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $700.33 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gate Valves, Globe Valves, Check Valves, Ball Valves Material: Brass, PVC, Stainless Steel, Ductile Iron End User: Agriculture, Greenhouses, Golf Courses, Landscaping Technology: Manual, Automatic, Remote-Controlled, Smart Irrigation |
| Companies Covered | Raven Industries, Bermad CS Ltd, Hunter Industries, Rivulis Irrigation, Fluidra S.A., Toro Company, Dickey-John Corporation, TeeJet Technologies, Netafim USA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Irrigation Valves Market Trends and Innovations
Telemetry integration is redefining valve functionality from passive flow control to active network nodes. Three developments are restructuring competitive positioning across Mediterranean and North European agricultural markets.
Solenoid-actuated micro-valves are miniaturizing. These compact units enable zone-specific drip irrigation control in high-density greenhouse layouts. Dutch tomato and pepper producers are adopting them at accelerating rates. Component miniaturization is compressing the physical footprint of valve stations while expanding addressable precision-agriculture acreage.
REACH compliance is forcing material substitution across electrically operated valve portfolios. The regulation bans specific phthalate plasticizers and restricts heavy-metal content in brass alloys. Stainless steel actuator housings and bio-based polymer seals are gaining specification share in German and French municipal irrigation tenders.
Cooperative procurement consortia are consolidating valve purchasing across Spanish and Italian farmer associations. These aggregators negotiate volume-based service contracts directly with manufacturers, bypassing traditional agricultural distributor networks. The shift is most visible in Andalusian olive and citrus operations where irrigation modernization programs cluster demand geographically.
Europe Irrigation Valves Market Segmentation
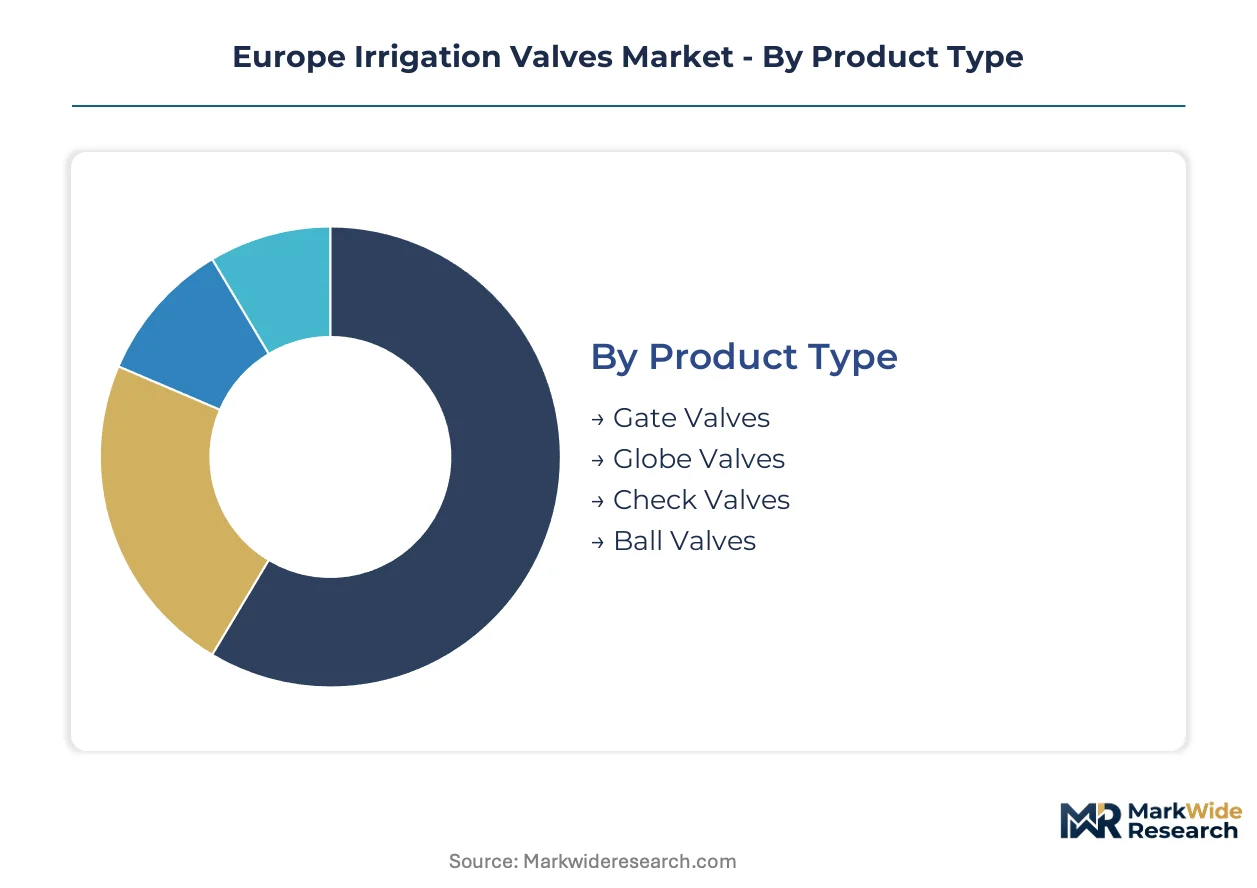
Valve specification in European agriculture diverges sharply by water chemistry, pressure regime, and automation maturity. Segment selection determines compliance burden, replacement cycle length, and subsidy eligibility under EU Green Deal frameworks.
Product Type:
CE marking under the EU Pressure Equipment Directive creates divergent certification costs across mechanical valve architectures.
- Ball Valves:Quarter-turn shutoff mechanisms with minimal pressure drop dominate mainline isolation in Spanish citrus groves and Italian olive operations. Rapid actuation suits high-frequency zone switching in pressurized networks.
- Gate Valves:Linear-motion closure devices provide full-bore flow with low friction loss, serving as legacy infrastructure standards in older Italian irrigation cooperatives. Manual operation limits precision-agriculture compatibility.
- Globe Valves:Throttling-optimized designs regulate flow in greenhouse fertigation skids across Dutch bell pepper installations.
- Check Valves:Spring-loaded or swing-type backflow prevention protects pump stations in Portuguese vineyard pressure-boosting arrays.
Established volume favors Ball Valves; emerging adoption favors Smart Irrigation convergence.
Material:
Cost tiers stratify sharply by corrosion resistance and regulatory compliance burden.
- Brass:Lead-free alloy reformulations under ECHA restrictions dominate residential and light-commercial landscaping across German municipal tenders. Foundry retooling costs compress margins for Italian manufacturers.
- Stainless Steel:Austenitic grades (304/316) withstand saline groundwater and aggressive fertigation chemistry in Spanish coastal agriculture and Greek island operations. Premium positioning captures replacement-driven demand where PVC fails.
- PVC:Thermoplastic construction dominates cost-sensitive surface irrigation in Polish and Romanian cereal production.
- Ductile Iron:High-pressure ratings suit transmission mains and pumping station headers in French large-scale cooperative networks.
Brass commands volume in established landscaping; Stainless Steel gains share fastest in coastal saline applications.
End User:
Application intensity dictates automation tier and pressure-regulation sophistication.
- Agriculture:Field-scale row crops and orchards in Spain's Ebro Valley drive demand for rugged manual and basic automatic valves. Water-efficiency mandates accelerate smart retrofit cycles in arid zones.
- Greenhouses:Dutch and Belgian controlled-environment vegetable production requires drip-compatible pressure-regulating micro-valves with chemical injection ports. Zone-specific control density exceeds field agriculture by an order of magnitude.
- Golf Courses:Turf irrigation in UK and Irish links demands weather-responsive remote control with frost protection interlocks.
- Landscaping:Municipal parks and commercial grounds in French and Italian urban centers specify aesthetic concealment and vandal-resistant actuation.
Agriculture anchors absolute volume; Greenhouses exhibit steepest technology premium expansion.
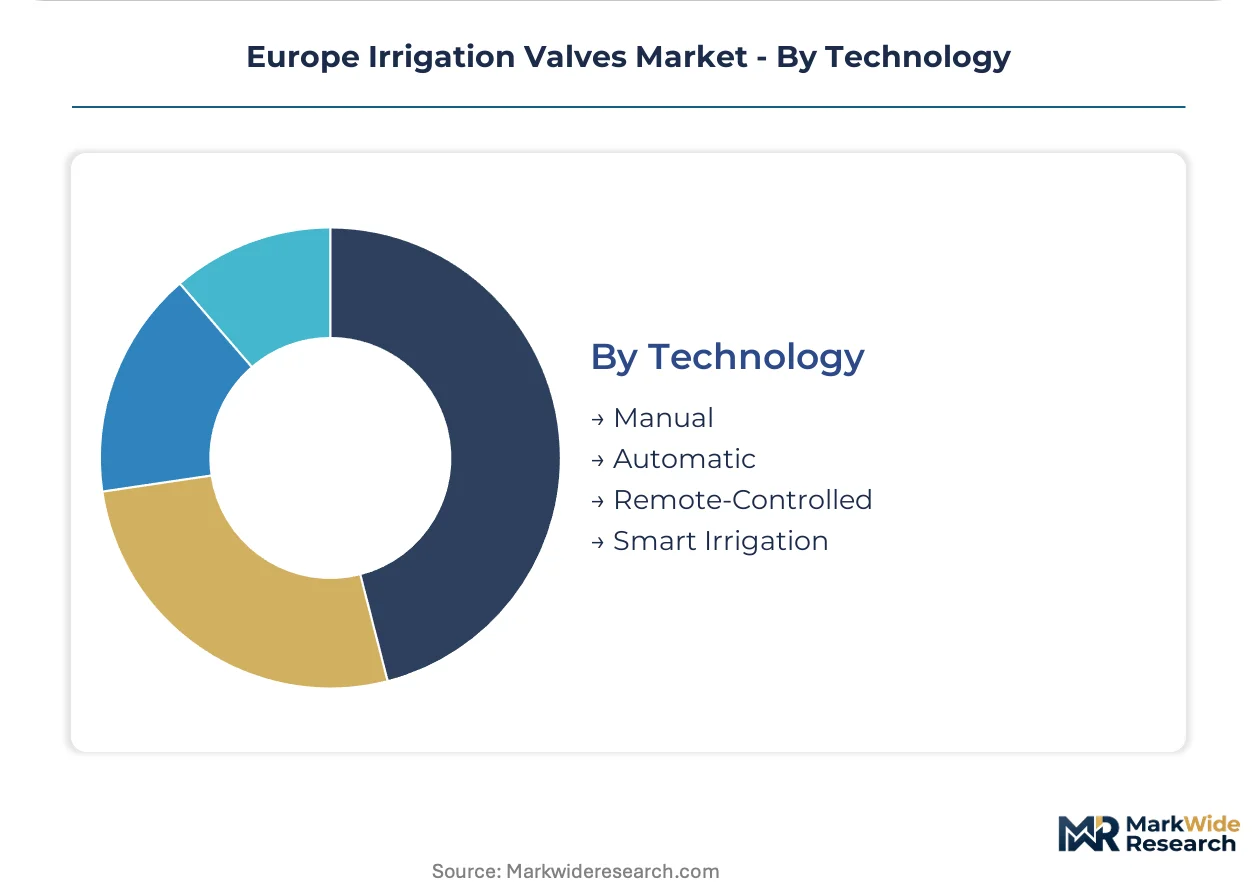
Technology:
Customer type—large cooperative versus smallholder—determines automation penetration and service contract structures.
- Smart Irrigation:Soil-moisture telemetry, weather API integration, and autonomous zone scheduling command hardware premiums in Italy's Po Valley intensive horticulture. EU Green Deal subsidies offset upfront costs for qualifying retrofits.
- Remote-Controlled:Radio or cellular actuation enables pump and valve operation without field presence, serving isolated Portuguese and Greek holdings with labor constraints.
- Automatic:Time-based or pressure-triggered actuation provides intermediate automation for mid-scale Spanish almond and pistachio operations.
- Manual:Handwheel or lever operation persists in smallholder parcels below subsidy thresholds and legacy systems without electrical infrastructure.
Manual technology retains installed-base dominance; Smart Irrigation climbs fastest where subsidy density and water stress coincide.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal subsidy flows are redistributing valve procurement across Mediterranean and North European agricultural belts. Water-efficiency mandates concentrate retrofit demand in arid cropping zones and intensive horticulture clusters.
Spain
Andalusian olive and citrus cooperatives are aggregating demand through procurement consortia that negotiate directly with manufacturers. The country's national agricultural modernization program channels public funding toward telemetry-enabled retrofits in the Ebro Valley. Seville-based irrigation districts report accelerating replacement cycles for legacy gate valves.
Italy
Intensive fruit and vegetable production in the Po Valley requires sophisticated pressure-regulating infrastructure with zone-specific control density. ECHA substance restrictions on leaded brass alloys are forcing foundry retooling in Emilia-Romagna manufacturing clusters. Bologna-area valve fabricators face compressed margins from alloy reformulation compliance costs.
Netherlands
Dutch greenhouse expansion is driving drip-compatible micro-valve demand across controlled-environment tomato and pepper operations. REACH compliance deadlines are accelerating material substitution in polymer actuator housings. Westland municipality clusters exhibit steepest technology premium expansion for chemical injection compatibility.
Germany
Municipal landscaping tenders in Bavaria and North Rhine-Westphalia specify lead-free brass alloys and aesthetic concealment requirements. The country's environmental regulator enforces strict documentation timelines for polymer valve housing registrations. Stuttgart-area manufacturers are pivoting toward stainless steel actuator designs.
France
Vineyard automation projects in Bordeaux and Champagne regions are specifying fertigation-compatible valve systems with chemical injection ports. The national agricultural subsidy framework prioritizes smart-controlled retrofits in water-stressed appellations. Lyon-based irrigation cooperatives are consolidating purchasing across Rhône Valley holdings.
Europe Irrigation Valves Market Competitive Landscape
Player mix skews toward diversified irrigation equipment manufacturers with captive controller technology. Mid-scale polymer specialists occupy secondary positions through greenhouse-focused micro-valve portfolios. Consolidation pressure concentrates among brass foundry operators facing ECHA alloy reformulation mandates. Dominant competitive moves include backward integration into polymer compounding and strategic partnerships for telemetry platform integration.
Within the diversified equipment tier, Hunter Industries and Toro Company exemplify manufacturers leveraging controller R&D intensity to differentiate valve offerings across Mediterranean markets. Rivulis Irrigation occupies a specialist position representing drip-compatible pressure-regulating architectures. Among Israel-based precision agriculture groups, Netafim USA anchors a position in fertigation-integrated system design.
| Leading Market Players |
|---|
| Raven Industries |
| Bermad CS Ltd |
| Hunter Industries |
| Rivulis Irrigation |
| Fluidra S.A. |
| Toro Company |
| Dickey-John Corporation |
| TeeJet Technologies |
| Netafim USA |
| Others |
Pricing and Supply Chain Analysis
Foundry scale economies in Italian and German manufacturing clusters compress unit costs for brass valve bodies while simultaneously concentrating pricing power among alloy-compliant producers. This dual dynamic elevates price floors for smaller Spanish and Greek fabricators lacking captive smelting capacity, reshaping competitive tiering across Mediterranean agricultural supply.
Pricing Analysis
Certification level creates the primary spread across European irrigation valve tiers, with CE-marked pressure equipment commanding hardware premiums over non-compliant imports. Three-tier pricing structure across premium, standard, and economy levels stratifies by automation integration, with smart-actuated systems capturing multiples over manual ball valves. Cost compression in brass alloy segments is intensifying because ECHA lead restrictions force foundry retooling. Smallholder cooperatives in Andalusia exhibit highest price sensitivity, while Dutch greenhouse operators show least elasticity due to subsidy offset mechanisms.
Supply Chain Analysis
Italy and Germany anchor precision brass casting and stainless steel machining for pressure-rated valve bodies serving EU agricultural networks. Raw material flows draw from Chilean copper concentrate, Turkish zinc ingot, and Ukrainian ferroalloy feeds. Single-source vulnerability concentrates in specialty polymer seals subject to REACH phthalate restrictions. Distribution runs through agricultural equipment consortia in Spain and Italy that aggregate cooperative purchasing, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe irrigation valves market sits in cyclical recovery phase as EU Green Deal subsidy waves trigger replacement cycles for legacy gate valve infrastructure across arid cropping zones.
For Market Incumbents: Compound technical documentation capabilities to tighten CE marking compliance moats against Asian import competition. Prioritize backward integration into lead-free brass alloy formulation to capture margin pools retreating from ECHA-restricted competitors. Channel R&D intensity toward AI Act-compliant telemetry algorithms before autonomous irrigation decision-making attracts regulatory scrutiny. For New Entrants and Emerging Players: Service-layer gaps in legacy system retrofit integration—specifically custom flange adapters for PVC mainline upgrades—offer white-space entry points. Target Italian irrigation cooperatives with aging infrastructure as the most penetrable segment. Lead with advisory revenue models for EU AI Act compliance rather than hardware-only positioning. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among smart-controller integration specialists with multi-year service contracts. Five-to-ten year viability favors acquisition targets possessing captive polymer compounding capabilities and greenhouse-focused micro-valve portfolios. Watch ECHA substance restriction expansion timelines as inflection signals for accelerated consolidation among brass foundry operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captures margin pools in REACH-compliant actuator housings for Dutch greenhouse suppliers. |
| CE Marking Pathway Investment | Unlocks access to Italy's Po Valley intensive horticulture procurement channels. |
| Smart Controller Platform Integration | Aligns valve offerings with EU Green Deal telemetry subsidy eligibility requirements. |
| Greenhouse Micro-Valve Portfolio Expansion | Addresses zone-specific control density demands in Belgian controlled-environment agriculture. |
| Long-term Service Contract Negotiation | Bypasses traditional distributor networks via Spanish cooperative procurement consortia. |
Research Methodology
Desk research of EU regulatory filings, customs trade databases, and agricultural subsidy disbursement records preceded structured interviews with irrigation cooperative procurement managers, valve foundry operations directors, greenhouse systems integrators, and ECHA compliance consultants. Primary fieldwork across Spanish Andalusian olive districts, Italian Emilia-Romagna manufacturing clusters, and Dutch Westland greenhouse municipalities validated secondary estimates. Bottom-up volume triangulation against top-down subsidy allocation models anchored market sizing.
Variance decomposition across product type, material grade, automation tier, and end-use intensity shaped the analytical framework over the projection horizon. CAGRs derived from replacement cycle acceleration curves in arid zones and penetration rate assumptions for smart-controlled retrofits. Modeled inputs incorporated EU Green Deal funding trajectory, ECHA substance restriction timelines, and cooperative procurement consolidation patterns.
Material uncertainties — subsidy disbursement delays, alloy supply disruptions, AI Act classification revisions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and farmer association aggregation behavior. Recalibration cycles align with material shifts in EU water-efficiency mandate implementation and REACH compliance deadline proximity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Ride-On Mower Market
Farm Equipment and Irrigations
Rain Barrels Market
Farm Equipment and Irrigations
Smart Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Australia Irrigation Automation Market
Farm Equipment and Irrigations
India Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Drip Irrigation Market
Farm Equipment and Irrigations
Potato Planter Market
Farm Equipment and Irrigations
Zero Turn Mowers Market
Farm Equipment and Irrigations
Brazil Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Sprinkler Irrigation Market
Farm Equipment and Irrigations
Africa Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Irrigation Liner Market
Farm Equipment and Irrigations
Asia-Pacific Irrigation Machinery Market
Farm Equipment and Irrigations
Grass Trimmer Market
Farm Equipment and Irrigations
Irrigation Pumps Market
Farm Equipment and Irrigations
Tractor Rental Market