
 Drip Irrigation Systems Market | 2026-2036
Drip Irrigation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Drip Irrigation Systems Market Analysis
Aftermarket service revenue is narrowing as equipment manufacturers bundle remote diagnostics with hardware sales. Netafim Limited leverages its digital farming platform to lock in recurring revenue streams beyond emitter replacement cycles. Jain Irrigation Systems Limited anchors its position through backward integration into polymer compounding for drip tape production. The Toro Company competes via precision agriculture partnerships that extend its reach into autonomous irrigation management.
Drip irrigation systems deliver water and nutrients directly to plant root zones through emitters operating at low pressure, typically 10–30 psi, with flow rates measured in gallons per hour rather than per minute. The technology minimizes evaporative losses and enables fertigation, the simultaneous application of soluble fertilizers through the same distribution network. Pressure compensating emitters command premium positioning due to their ability to maintain uniform discharge across elevation changes and long lateral runs. Subsurface drip installations represent the fastest-growing installation category as permanent buried lines reduce tillage interference and cut labor demands. Smart controllers within the solution segment attract software-like margins as growers adopt soil-moisture-based automation over timer-based scheduling.
The EPA's WaterSense program certifies efficient irrigation products for commercial and residential segments, while the USDA's Environmental Quality Incentives Program subsidizes agricultural conversions to micro-irrigation methods. India's PMKSY scheme and Israel's water pricing framework both accelerate farmer transitions from flood to drip systems through direct cost offsets. Stakeholders must monitor groundwater basin adjudication timelines and subsidy renewal cycles to anticipate demand inflection points in water-stressed growing regions.
Market Dynamics
Groundwater basin adjudication timelines in water-stressed agricultural regions are compressing farmer decision cycles and accelerating conversion from flood irrigation to precision delivery systems. The Sustainable Groundwater Management Act in California and comparable extraction limits across Israel, India, and Spain are forcing permanent shifts in irrigation infrastructure investment.
Growth Catalysts
- India's PMKSY scheme:Direct capital subsidies for micro-irrigation equipment cover 50-70% of system costs for smallholders in Maharashtra and Gujarat, accelerating conversions from flood methods.
- Fertigation convergence:The integration of soluble fertilizer delivery through drip networks enables simultaneous water-nutrient optimization, driving replacement demand among specialty crop growers.
- Subsurface drip expansion:Permanent buried lateral lines eliminate tillage interference and reduce seasonal labor demands, attracting large-scale row-crop operators in California's Central Valley.
Market Restraints
- Polymer price volatility:Ethylene and propylene feedstock fluctuations directly compress drip tape and emitter manufacturing margins, forcing producers to absorb cost spikes or risk farmer affordability thresholds.
- Emitter clogging susceptibility:Biological and chemical precipitation in hard-water regions degrades system performance and raises maintenance burdens, limiting adoption in untreated groundwater zones.
- Subsidy dependency cycles:Farmer purchasing decisions concentrate around government renewal timelines in India and Israel, creating demand discontinuities when program budgets face fiscal pressure.
Strategic Opportunities
- Saudi Arabia's Qatrah program:National water efficiency targets mandate 70% reduction in agricultural consumption by 2030, creating mandated demand for retrofit infrastructure across the Kingdom's wheat and date sectors.
- Soil-moisture automation:Smart controllers integrating sensor telemetry with valve actuation command software-like margins and recurring subscription revenue streams.
- Almond orchard retrofit wave:California's permanent crop base—over 1.6 million bearing acres—represents embedded flood infrastructure ripe for precision conversion as SGMA compliance deadlines approach.
Industry Challenges
- Agronomic technician scarcity:System design, hydraulic optimization, and sensor calibration require specialized field expertise that outstrips training pipeline capacity in emerging adoption regions.
- Legacy flood infrastructure lock-in:Existing canal networks, field grading, and surface irrigation equipment represent sunk capital that farmers must write off to justify drip conversion economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drip Irrigation Systems Market |
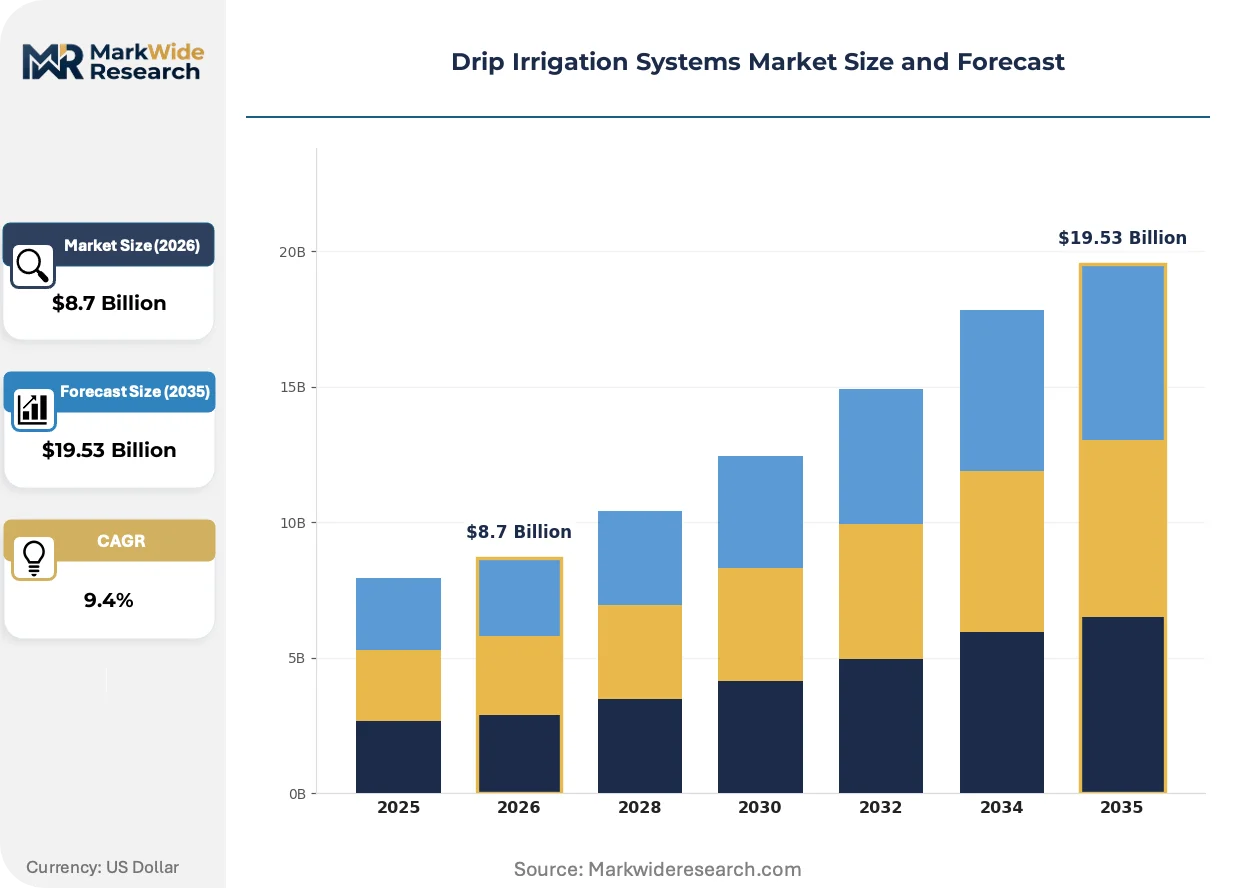
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Emitters, Drip Tapes, Pressure Compensating Emitters, Sprinkler Systems Installation Type: Surface Drip, Subsurface Drip, Portable Systems, Permanent Systems End User: Agricultural Producers, Greenhouses, Landscapers, Homeowners Solution: Autonomous Systems, Smart Controllers, Fertigation Systems, Monitoring Solutions |
| Companies Covered | Netafim Limited, The Toro Company, Jain Irrigation Systems Limited, Lindsay Corporation, Rain Bird Corporation, Hunter Industries, Rivulis Irrigation Limited, Irritec S.p.A, Valmont Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drip Irrigation Systems Market Emerging Trajectories
Digital farming platforms are virtualizing the traditional hardware-service boundary, compressing equipment margins while expanding recurring revenue capture through telemetry-based optimization. Three developments are restructuring competitive positioning and value distribution.
Pressure-compensating emitter technology is virtualizing the hydraulic design constraints that previously limited lateral run lengths and elevation tolerance. Specialty vegetable growers in Spain's Almería province and Mexico's Sinaloa corridor are adopting these emitters to enable uniform discharge across undulating terrain. The technology is virtualizing the engineering trade-offs between system complexity and water-use efficiency, allowing simplified mainline configurations without sacrificing distribution uniformity.
The EPA's WaterSense certification program for commercial irrigation products is tightening performance benchmarks for flow uniformity and pressure management. Manufacturers must now submit third-party test data to maintain eligibility for federal procurement and utility rebate programs. Agricultural equipment vendors serving the US nursery and greenhouse segment are redesigning product lines to meet these specifications ahead of anticipated expansion into open-field crop categories.
Service unbundling is fragmenting the traditional equipment-installation-maintenance bundle that dominated market entry. Israeli and Indian distributors are piloting subscription models where farmers pay per acre-inch delivered rather than purchasing capital equipment outright. This shift concentrates credit risk with distributors while accelerating adoption among liquidity-constrained smallholders in Gujarat and Karnataka.
Drip Irrigation Systems Market Segmentation
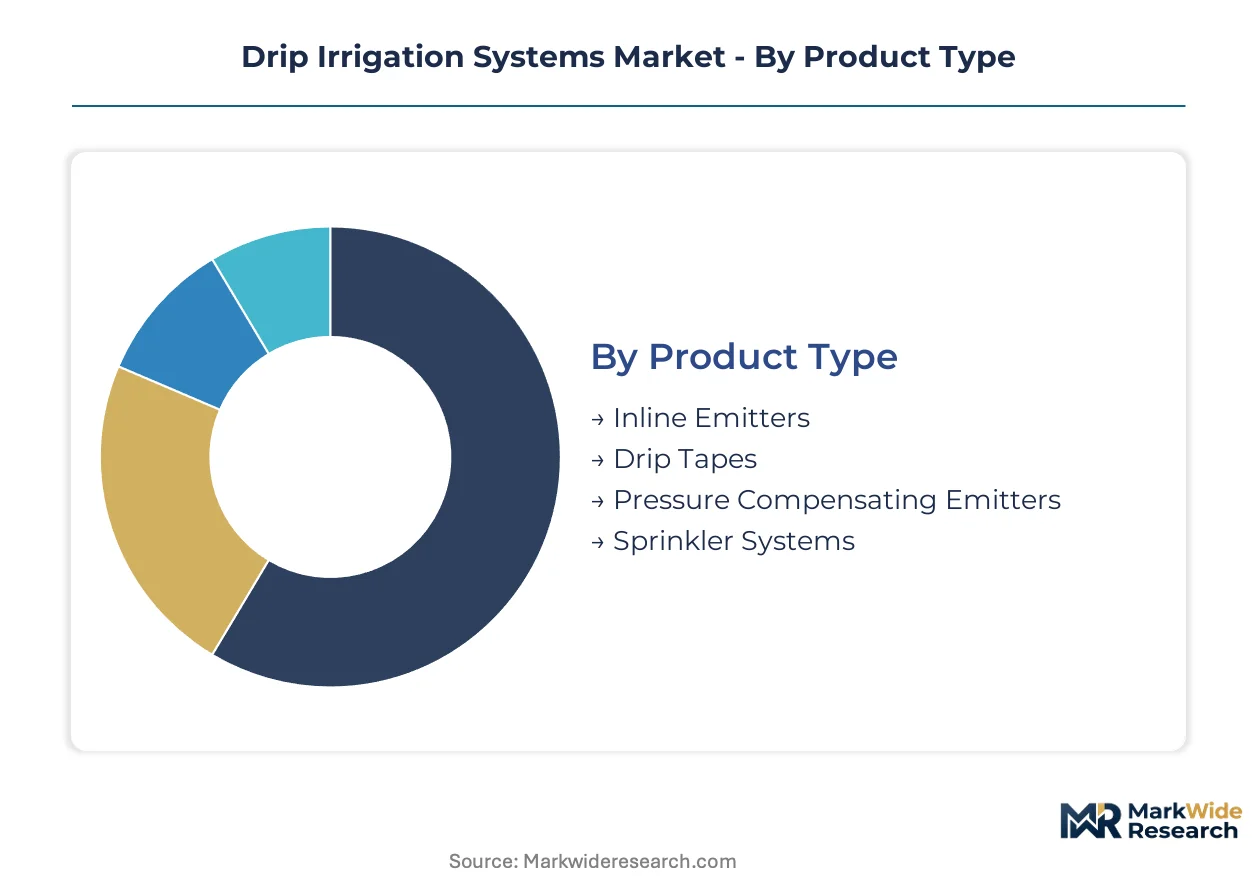
Segmentation in drip irrigation reveals how technology specialization, installation permanence, and automation intensity create distinct margin profiles across customer tiers. Equipment manufacturers calibrate product portfolios across these dimensions to capture value from subsurface retrofit cycles and precision agriculture upgrades.
Product Type:
Cost tier differentiation separates commodity emitters from precision-engineered pressure-compensating variants that command premium positioning in undulating terrain applications.
- Inline Emitters:Polyethylene-bodied emitters factory-integrated into lateral tubing deliver consistent flow rates at 10-15 psi operating pressure. Demand concentrates among vegetable growers in Spain's Almería province where standardized row configurations favor integrated manufacturing economies.
- Drip Tapes:Thin-walled, flat-profile tubing with laser-punched flow paths enables cost-effective deployment across high-acreage row crops. Adoption accelerates in India's Maharashtra state where PMKSY subsidies offset capital burdens for smallholder cotton and sugarcane operations.
- Pressure Compensating Emitters:Silicon membrane mechanisms maintain discharge uniformity across elevation changes exceeding 15 meters. Specialty nut and vineyard operators in California's Central Valley specify these for hillside orchards where hydraulic variation would otherwise degrade distribution.
- Sprinkler Systems:Micro-sprinkler variants bridge coverage gaps in tree canopy applications where drip alone underperforms. Citrus groves in Florida and São Paulo state deploy hybrid configurations combining subsurface drip with overhead supplemental coverage.
Inline emitters and drip tapes command the established base. The steepest expansion runs through pressure compensating emitters.
Installation Type:
Application permanence determines capital recovery timelines and tillage compatibility, with buried systems attracting large-scale operators seeking labor reduction.
- Surface Drip:Above-ground lateral placement enables seasonal deployment and crop rotation flexibility. Vegetable producers in Mexico's Sinaloa corridor favor surface configurations for annual crop cycles where annual repositioning accommodates field reconfiguration.
- Subsurface Drip:Permanent buried installation at 20-40 cm depth eliminates tillage interference and cuts seasonal labor demands. California almond growers retrofitting flood-irrigated orchards under SGMA compliance deadlines drive adoption acceleration.
- Portable Systems:Lightweight, movable configurations serve smallholder plots and demonstration applications. Subsistence farmers in Ethiopia's Rift Valley utilize portable drip kits distributed through NGO-led water efficiency programs.
- Permanent Systems:Fixed infrastructure with buried mains and laterals designed for 15-20 year operational life. Saudi Arabia's Qatrah program mandates permanent retrofit across wheat and date sectors to achieve 70% agricultural water reduction targets.
Surface drip retains volume leadership in annual cropping. Permanent systems are climbing the fastest as groundwater basin adjudication compresses farmer decision cycles.
End User:
Customer type segmentation maps purchasing authority, technical sophistication, and subsidy eligibility across distinct operational scales.
- Agricultural Producers:Commercial farming operations managing 100+ hectare holdings with dedicated irrigation management staff. Israeli cooperative farms (kibbutzim) deploy centralized fertigation systems integrating drip networks with precision nutrient delivery.
- Greenhouses:Controlled-environment operations requiring ultra-uniform moisture distribution for substrate-based cultivation. Dutch glasshouse tomato producers specify high-flow drip stakes paired with recirculating drainage systems.
- Landscapers:Commercial turf and ornamental contractors serving municipal parks, golf courses, and corporate campuses. EPA WaterSense certification requirements shape product selection for US federal procurement eligibility.
- Homeowners:Residential gardeners utilizing battery-timer kits and expandable micro-drip configurations. California's turf replacement rebate programs accelerate conversion from spray irrigation in drought-affected municipalities.
Agricultural producers anchor revenue concentration. Greenhouse applications gain share fastest as controlled-environment agriculture expands.
Solution:
Automation intensity stratifies pricing architecture, with sensor-integrated systems capturing recurring revenue streams beyond hardware margins.
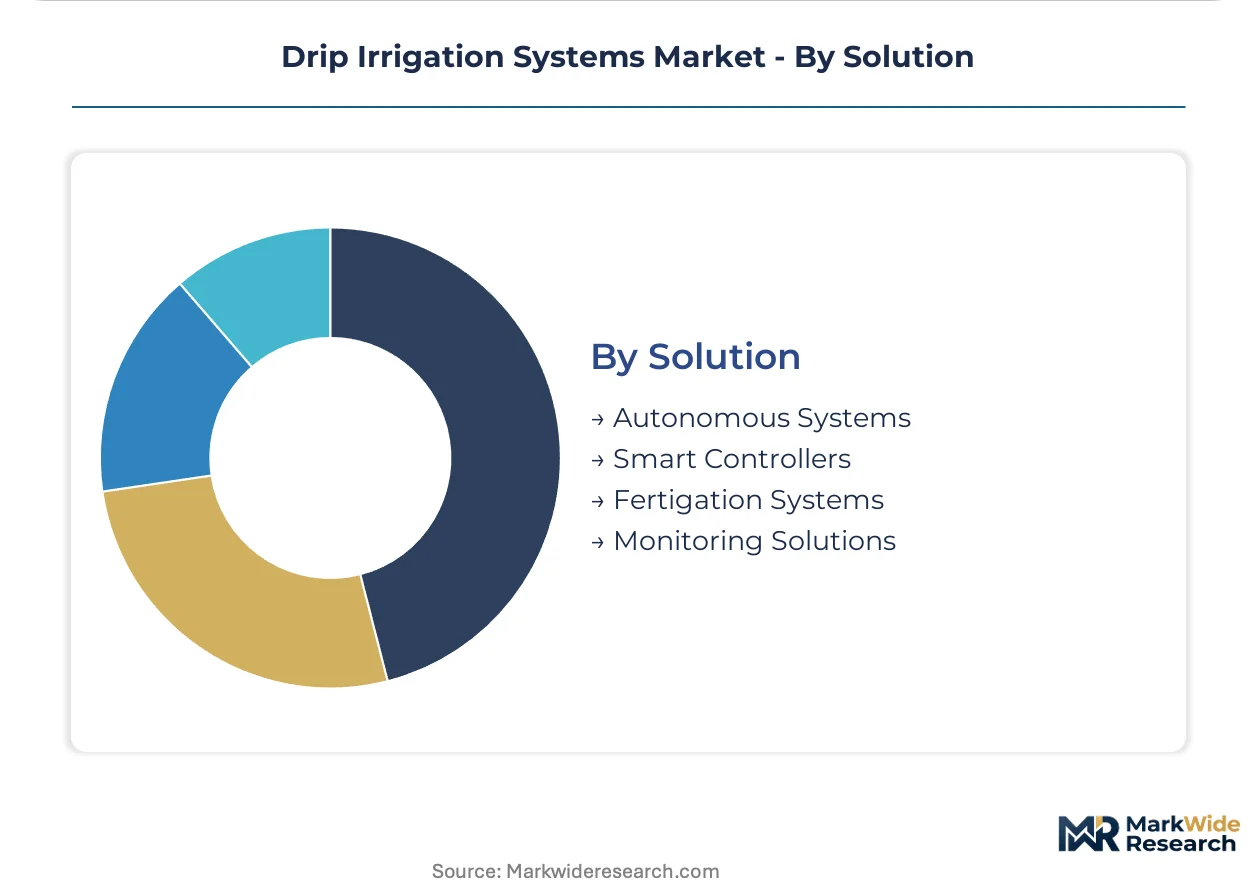
- Autonomous Systems:Fully automated configurations integrating soil moisture telemetry, weather data, and valve actuation without human intervention. Large-scale operators in Australia's Murray-Darling Basin deploy autonomous zones to comply with volumetric water allocation enforcement.
- Smart Controllers:Cloud-connected scheduling devices replacing mechanical timers with evapotranspiration-based algorithms. Software-like margins attract equipment manufacturers seeking recurring subscription revenue beyond emitter replacement cycles.
- Fertigation Systems:Injection equipment delivering soluble fertilizers through drip distribution networks. Specialty crop growers in Florida's phosphate-intensive vegetable belt specify acid-compatible materials for nutrient-acid combination delivery.
- Monitoring Solutions:Sensor arrays tracking soil moisture, salinity, and system pressure for diagnostic optimization. Indian distributor pilots in Gujarat deploy monitoring-as-a-service models charging per acre-inch delivered rather than capital equipment purchase.
Fertigation systems command the installed base. Autonomous systems are expanding most quickly as labor scarcity and water accounting precision intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian smallholders exhibit extreme price elasticity, clustering purchases around subsidy renewal windows, while Israeli cooperative farms absorb premium pricing for automation-ready systems with minimal volume sensitivity.
United States
California's almond and pistachio orchards drive retrofit demand as SGMA compliance deadlines force permanent infrastructure shifts away from flood irrigation. The EPA's WaterSense program certifies efficient products for federal procurement eligibility. Fresno and Kern counties concentrate installation activity where groundwater basin adjudication accelerates farmer decision cycles.
India
Maharashtra and Gujarat smallholders convert cotton and sugarcane acreage under PMKSY capital subsidies covering 50-70% of system costs. The Ministry of Agriculture's micro-irrigation fund directs deployment toward water-stressed districts. Jalgaon and Ahmednagar districts anchor manufacturing and distribution networks serving the Deccan Plateau.
Israel
Kibbutzim and moshavim deploy centralized fertigation systems integrating precision nutrient delivery with drip networks. The national water pricing framework penalizes flood irrigation while rewarding efficiency investments. The Jezreel Valley and Negev Desert host demonstration farms exporting technical expertise to arid-region adopters.
Spain
Almería province vegetable growers adopt pressure-compensating emitters to maintain uniformity across greenhouse benching and undulating terrain. EU Common Agricultural Policy cross-compliance requirements tighten water efficiency benchmarks. The Campo de Dalías and Poniente Almeriense clusters concentrate high-value protected cultivation.
Saudi Arabia
The Qatrah program mandates 70% agricultural water reduction by 2030, forcing wheat and date sector retrofits. The Ministry of Environment, Water and Agriculture administers infrastructure conversion timelines. Al-Qassim and Eastern Province date plantations anchor permanent subsurface drip deployment at scale.
Drip Irrigation Systems Market Vendor Landscape
Capability concentration sits with engineering-intensive specialists; scale advantage sits with diversified industrial conglomerates. The vendor base stratifies across three tiers: precision emitter designers, integrated polymer processors, and precision agriculture platform operators. Dominant competitive moves include backward integration into polymer compounding and strategic partnerships extending reach into autonomous irrigation management.
Within the precision agriculture tier, Netafim Limited and The Toro Company exemplify contrasting strategic positions. Netafim anchors engineering heritage in emitter design and digital farming platform development. The Toro occupies a position extending from turf equipment into precision agriculture partnerships. Jain Irrigation Systems Limited represents the integrated manufacturing archetype, with backward control over polymer supply chains for drip tape production. These three companies collectively illustrate how capability depth, platform breadth, and supply chain integration define competitive differentiation in water-stressed agricultural markets.
| Leading Market Players |
|---|
| Netafim Limited |
| The Toro Company |
| Jain Irrigation Systems Limited |
| Lindsay Corporation |
| Rain Bird Corporation |
| Hunter Industries |
| Rivulis Irrigation Limited |
| Irritec S.p.A |
| Valmont Industries |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese polymer compounding facilities is compressing emitter manufacturing margins and forcing tiered pricing strategies across export markets. This utilization dynamic concentrates bargaining power with large-scale agricultural buyers in India and California while squeezing mid-tier distributors in emerging adoption regions.
Pricing Analysis
Aftermarket service contracts and remote diagnostics subscriptions now drive lifetime value beyond hardware margins. Pricing stratifies across premium, standard, and economy tiers based on pressure-compensation capability and smart-controller integration. Cost compression in commodity drip tape is intensifying because Indian smallholders cluster purchases around PMKSY subsidy windows. Agricultural producers in Israel's kibbutzim exhibit minimal price sensitivity for automation-ready systems, while Maharashtra cotton growers face acute affordability constraints.
Supply Chain Analysis
Contract manufacturing concentration sits with Indian polymer processors in Jalgaon and Ahmedabad, plus Israeli precision-molding specialists serving European export markets. Raw material flows draw from Saudi ethylene crackers, South Korean specialty polymer suppliers, and Gujarat-based virgin resin distributors. Single-source vulnerability runs through silicon membrane suppliers for pressure-compensating emitters. Distribution runs through government-subsidized dealer networks in India, direct-to-farm technical sales in California, and cooperative procurement pools in Israel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across the drip irrigation landscape as groundwater adjudication creates geographic niches with divergent compliance timelines and subsidy eligibility. The shift from flood infrastructure to precision delivery generates specialized service gaps that regional players can exploit.
For Market Incumbents: Harden platform stickiness by bundling soil-moisture telemetry with emitter hardware to lock in recurring revenue streams. Deepen backward integration into polymer compounding to defend margin position against ethylene price volatility. Prioritize certification investment for EPA WaterSense eligibility ahead of anticipated expansion into open-field crop categories.
For New Entrants and Emerging Players: Establish a beachhead in Saudi Arabia's Qatrah-mandated retrofit segment where foreign expertise commands premium positioning. Target portable drip kit distribution through NGO-led programs in Ethiopia's Rift Valley where capital constraints exclude conventional equipment vendors. Deploy subscription pricing models charging per acre-inch delivered to bypass smallholder liquidity barriers in Gujarat.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among smart-controller manufacturers with telemetry integration capabilities. Long-term viability favors platform operators over pure hardware vendors as software margins displace commodity emitter economics. Monitor groundwater basin adjudication timelines in California's Central Valley as the critical signal for retrofit demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Jain Irrigation's captive resin supply anchors cost position against feedstock volatility. |
| Digital Farming Platform Development | Netafim's telemetry integration locks in subscription revenue beyond replacement cycles. |
| Pressure-Compensating Emitter Scale-Up | Specialty nut growers in California's hillside orchards specify premium hydraulic uniformity. |
| Subsurface Drip Retrofit Partnerships | Toro's precision agriculture alliances extend reach into autonomous irrigation management. |
| Subscription Service Model Pilot | Indian distributors in Gujarat charge per acre-inch delivered to accelerate smallholder adoption. |
Methodological Framework
A standing panel of irrigation district managers, agricultural cooperative technical officers, polymer procurement leads, and aftermarket service heads provided ongoing calibration across the study period. Primary interviews with equipment distributors in Maharashtra and California's Central Valley combined with secondary validation from USDA Environmental Quality Incentives Program disbursement records, Israeli Water Authority pricing frameworks, and Indian Ministry of Agriculture PMKSY deployment statistics. Bottom-up triangulation across emitter shipment volumes and top-down cross-check against agricultural water efficiency investment flows anchored value estimates.
Scenario bracketing around subsidy renewal cycles, groundwater adjudication timelines, and polymer price volatility bands shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, installation permanence, automation intensity, and end-user operational scale. CAGRs derived from hydraulic infrastructure replacement curves and farmer conversion elasticity in water-stressed regions. Industry-specific inputs incorporated SGMA compliance deadline phasing and Saudi Qatrah program infrastructure conversion mandates.
Macroeconomic conditions sit as an overlay; deviation in ethylene-propane spreads, Indian rupee exchange rates, or California agricultural credit availability would shift the trajectory. Forecasts reflect documented assumptions regarding subsidy continuity and regulatory enforcement intensity. Quarterly review of groundwater basin adjudication dockets, polymer futures curves, and micro-irrigation fund disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Europe Irrigation Valves Market
Farm Equipment and Irrigations
Global Center Pivot Irrigation Systems Market
Farm Equipment and Irrigations
Grass Trimmer Market
Farm Equipment and Irrigations
Global Fruit Picker Market
Farm Equipment and Irrigations
Global Irrigation Automation Market
Farm Equipment and Irrigations
Lawn Edge Trimmer Market
Farm Equipment and Irrigations
Irrigation Controllers Market
Farm Equipment and Irrigations
Lawn Sprinkler Market
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Solar Powered Irrigation System Market
Farm Equipment and Irrigations
Brazil Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Farm Equipment Rental Market
Farm Equipment and Irrigations
Smart Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
North America Agricultural Tires Market
Farm Equipment and Irrigations
Agricultural Solar Pumps Market
Farm Equipment and Irrigations
Drip Irrigation Market