
 Australia Irrigation Automation Market | 2026-2036
Australia Irrigation Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Irrigation Automation Market Outlook
Specialist irrigation dealerships across the Murray-Darling Basin is tilting toward bundled service contracts that pair hardware with remote monitoring. Netafim leverages its drip irrigation heritage to anchor premium system sales in Australian horticulture. Lindsay Corporation competes through its Zimmatic pivot brand, which dominates broadacre field coverage. Rain Bird Corporation differentiates via centralized control platforms that integrate flow metering with weather data feeds.
Australia irrigation automation encompasses electromechanical and software-driven systems that regulate water delivery through programmable valves, soil moisture sensors, and telemetry networks operating at pressures typically between 100 and 400 kPa. These systems serve commercial agriculture, turf management, and urban green infrastructure by reducing manual intervention, cutting energy costs, and enforcing volumetric entitlements. Drip irrigation and sensor-based systems capture expanding margin pools as water scarcity intensifies precision requirements across the sector. Central control systems retain structural importance in large-scale operations where multi-zone coordination justifies capital outlay, while sprinkler systems face gradual displacement in water-stressed catchments.
The Murray-Darling Basin Authority enforces sustainable diversion limits that directly shape farm-level automation investment cycles. Standards Australia maintains AS 4419 and related specifications for irrigation equipment performance and interoperability. The Bureau of Meteorology's water data services underpin most scheduling algorithms, making federal meteorological infrastructure a de facto market gatekeeper. Stakeholders must weigh capital replacement timelines against evolving telemetry standards and basin plan compliance thresholds.
Market Dynamics
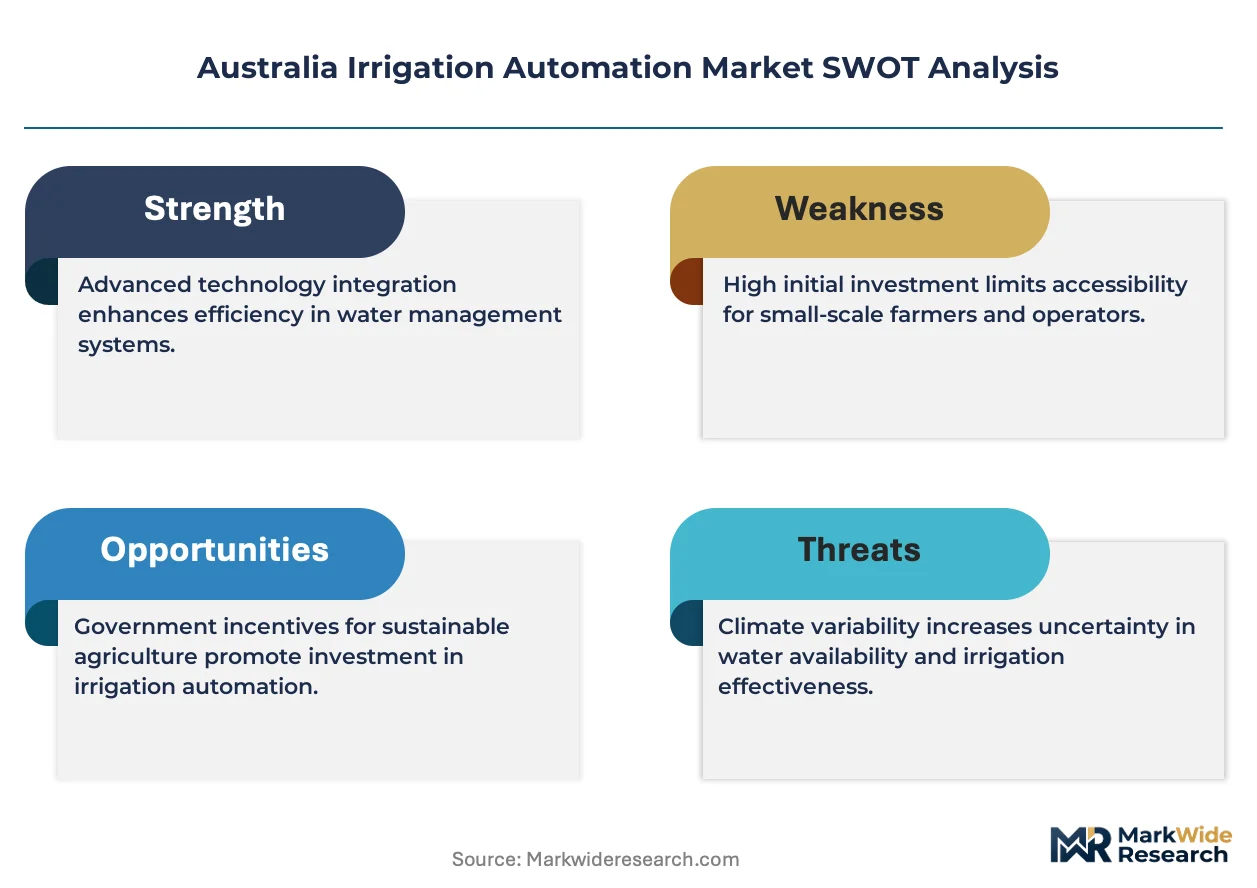
The Murray-Darling Basin Authority's sustainable diversion limits enforcement is compressing capital replacement timelines and forcing farm-level telemetry upgrades across Australia's irrigation belt.
Growth Catalysts
- Murray-Darling Basin Plan compliance deadlines:Water entitlement reforms tighten volumetric tracking requirements, accelerating sensor network deployment among broadacre operators.
- Horticulture belt expansion:Southern Queensland and northern New South Wales growers face intensifying water scarcity, driving precision irrigation hardware purchases.
- LoRaWAN telemetry protocols:Low-power wide-area networks reduce connectivity costs for remote monitoring, enabling smaller farms to justify automation investment.
Market Restraints
- Aluminum and polymer input volatility:Pivot and drip component manufacturers face margin compression from commodity price swings in irrigation hardware supply chains.
- Specialized dealer concentration:Technical installation and calibration expertise clusters in the Murray-Darling Basin, creating service access gaps for Western Australian and Tasmanian operators.
- Legacy gravity-fed system persistence:Flood irrigation infrastructure in older catchments slows electromechanical retrofit adoption despite water efficiency mandates.
Strategic Opportunities
- Tasmanian vegetable and dairy irrigation:Underpenetrated precision automation markets in the state's high-rainfall zones offer expansion potential as water security planning tightens.
- Solar-powered pumping integration:Hybrid renewable-automation systems align with Australian Renewable Energy Agency incentives and reduce off-grid operational costs.
- Urban green infrastructure mandates:Council water restrictions in Perth, Adelaide, and Melbourne drive smart controller demand for municipal parks and sports turf.
Industry Challenges
- Telemetry technician scarcity:Regional Australia faces acute shortages of field engineers capable of calibrating soil moisture sensors and troubleshooting valve actuators.
- AS 4419 interoperability gaps:Standards Australia equipment specifications lag emerging IoT protocols, creating integration friction between hardware generations.
- Capex payback uncertainty:Variable seasonal water allocations in the Murray-Darling Basin complicate automation ROI calculations for risk-averse grain growers.
Report Scope
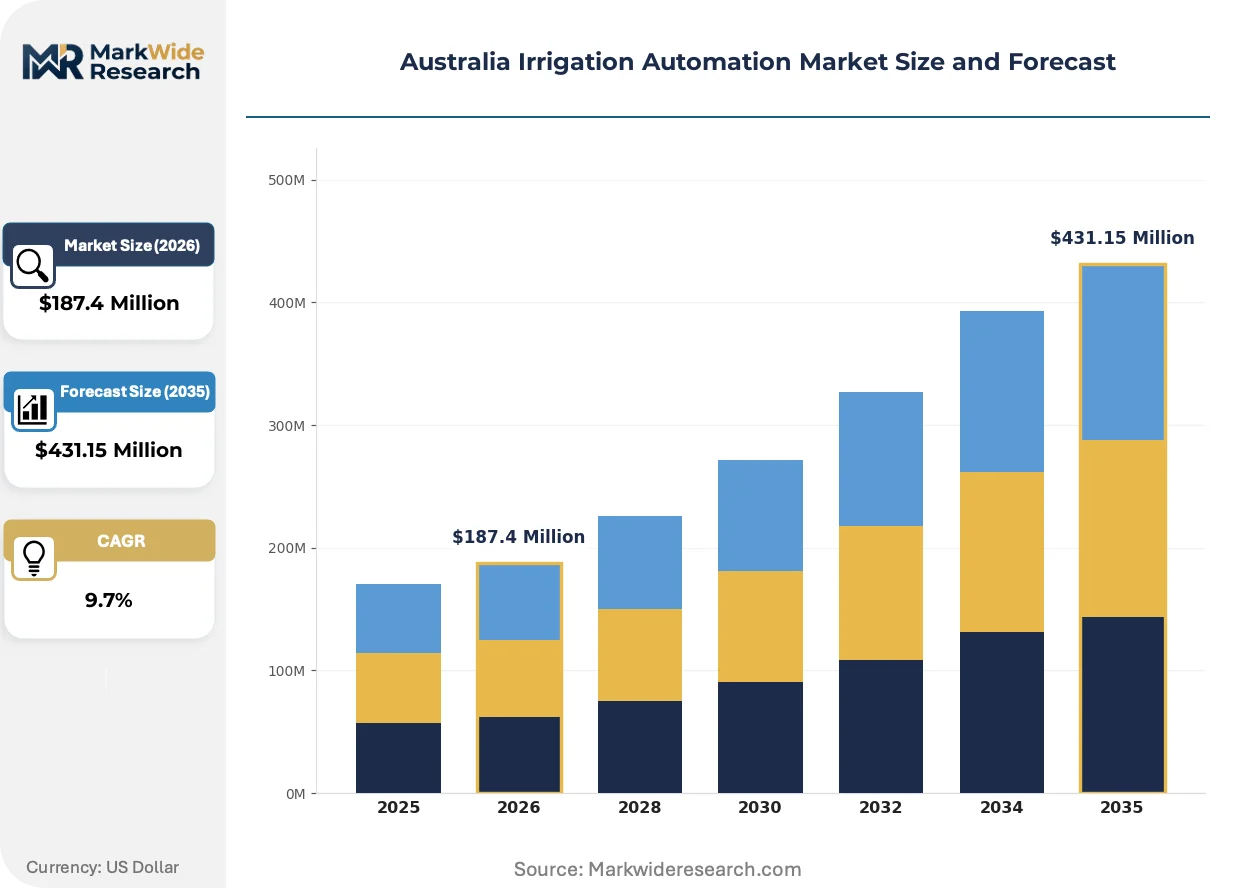
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Irrigation Automation Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Drip Irrigation, Sprinkler Systems, Sensor-Based Systems, Central Control Systems Application: Agricultural Fields, Greenhouses, Golf Courses, Public Parks End User: Farmers, Landscape Architects, Golf Course Managers, Urban Planners Solution: Software Solutions, Cloud-Based Monitoring, Automated Pumps, Flow Meters |
| Companies Covered | Antelco, Weathermatic, Orbit Irrigation, The Toro Company, Rain Bird Corporation, Netafim, Jain Irrigation Systems, Lindsay Corporation, Valmont Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Irrigation Automation Market Strategic Shifts
Sensor-to-cloud architectures are compressing decision latency in Australian irrigation, while regulatory telemetry mandates and shifting procurement models reshape how automation systems reach end-users.
Variable rate irrigation technology is migrating from broadacre cotton operations into horticulture and viticulture applications. Premium wine producers in the Barossa Valley and Margaret River are retrofitting drip systems with soil moisture mapping and canopy temperature sensors. This technology is migrating from large-scale pivot coverage to block-level precision, compressing water application variance and enabling deficit irrigation protocols that were previously uneconomical at smaller scales.
The Bureau of Meteorology's water data services integration into commercial scheduling algorithms has intensified under Murray-Darling Basin compliance frameworks. Farm management software platforms now embed real-time flow telemetry with entitlement tracking, creating audit-ready documentation chains. Cotton and rice producers in the northern basin face the steepest adaptation curves as diversion limit enforcement tightens, accelerating centralized control platform adoption.
Service bundling is displacing discrete hardware sales across the dealer network. Bundled contracts pairing Zimmatic or Valley pivot hardware with multi-season remote monitoring and maintenance are capturing preference share from transactional equipment purchases. This shift concentrates most visibly among corporate farming operations in the Murrumbidgee and Goulburn-Murray irrigation districts, where operational scale justifies long-term service relationships over capital ownership.
Australia Irrigation Automation Market Segmentation
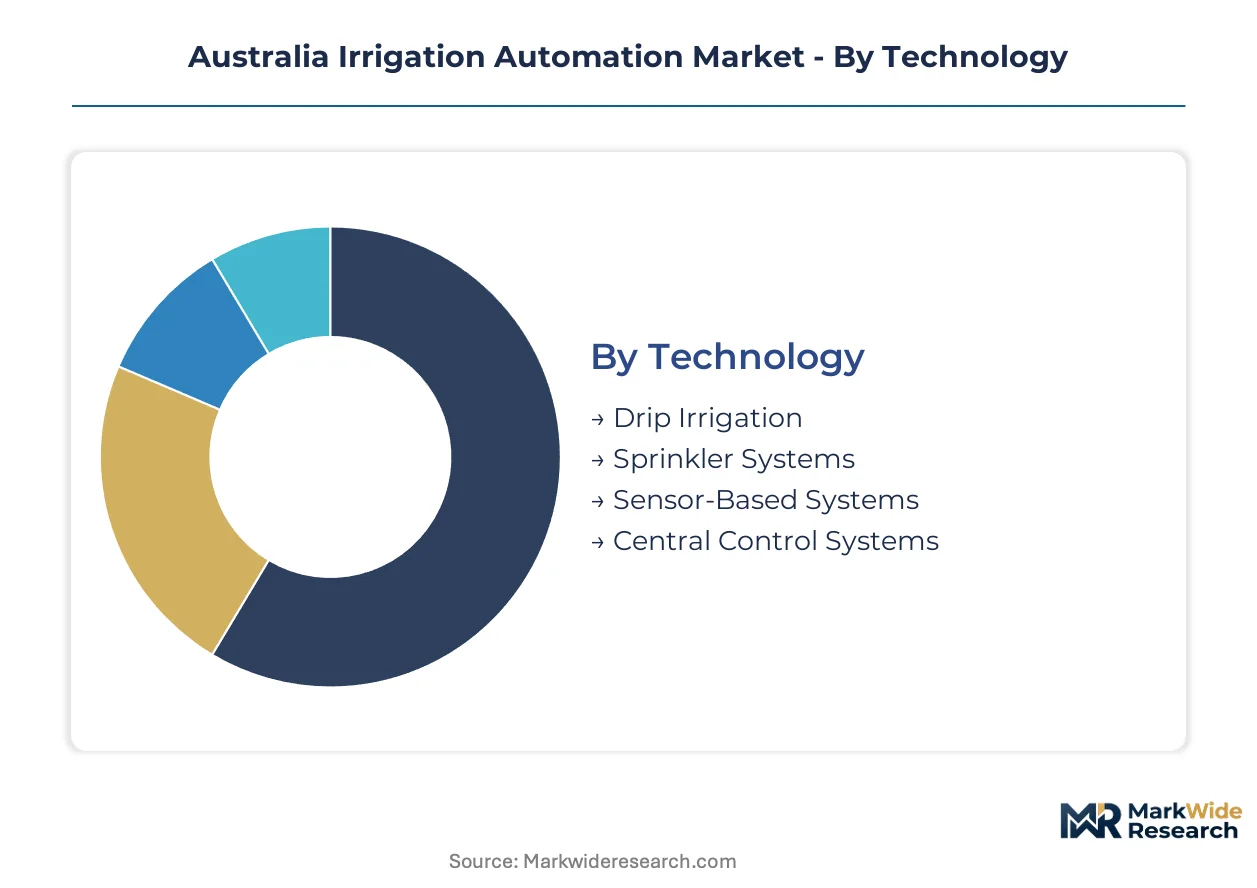
Technology choice in Australian irrigation automation hinges on water pressure specifications, crop water requirements, and Murray-Darling Basin compliance mandates. Application context determines whether precision drip, broadacre pivot, or centralized telemetry architectures deliver measurable efficiency gains against tightening volumetric entitlements.
Technology:
The use-case spectrum spans high-pressure broadacre coverage to low-pressure precision delivery, with connectivity infrastructure increasingly dictating system selection.
- Drip Irrigation:Pressure-compensating emitters operating at 100-150 kPa deliver targeted water volumes directly to root zones. Cotton producers in northern New South Wales and southern Queensland deploy subsurface drip to minimize evaporative losses under Basin Plan diversion limits.
- Sensor-Based Systems:Soil moisture probes, weather stations, and canopy sensors feed telemetry networks for real-time scheduling adjustments. Viticulture operations in the Barossa Valley and Margaret River drive adoption as deficit irrigation protocols tighten water application variance.
- Sprinkler Systems:Center-pivot and lateral-move configurations dominate grain belt coverage across Victoria and New South Wales.
- Central Control Systems:Multi-zone coordination platforms integrate valve actuation with flow metering for large-scale operations.
Established volume favors sprinkler systems; emerging adoption favors sensor-based systems.
Application:
Water scarcity intensity and regulatory exposure vary sharply across deployment contexts, shaping automation investment priorities.
- Agricultural Fields:Broadacre grain, cotton, and horticulture operations across the Murray-Darling Basin face the steepest compliance pressure. Entitlement tracking mandates accelerate telemetry deployment among corporate farming operations in the Murrumbidgee and Goulburn-Murray districts.
- Greenhouses:Controlled-environment agriculture in high-value vegetable production zones demands sub-millimeter precision in irrigation scheduling. Protected cropping expansion near Bundaberg and the Lockyer Valley drives demand for integrated climate-irrigation control platforms.
- Golf Courses:Turf quality standards and council water restrictions create dual pressure for automated scheduling.
- Public Parks:Municipal water restrictions in Perth, Adelaide, and Melbourne mandate smart controller deployment for sports grounds and urban green infrastructure.
Revenue concentration sits with agricultural fields; steepest expansion trajectory belongs to greenhouses.
End User:
Technical sophistication and capital access create distinct procurement patterns across user categories.
- Farmers:Broadacre operators and horticulture growers dominate hardware procurement, with corporate farming entities favoring bundled service contracts over discrete equipment purchases. Basin Plan compliance deadlines compress replacement timelines for telemetry-capable systems.
- Golf Course Managers:Turf quality maintenance under water restriction regimes drives smart controller adoption across metropolitan and regional courses.
- Landscape Architects:Urban green infrastructure projects specify automated irrigation for water-sensitive design compliance.
- Urban Planners:Council procurement mandates shape demand for centralized park and sports field management systems.
Procurement volume clusters with farmers; specification influence is concentrating with urban planners.
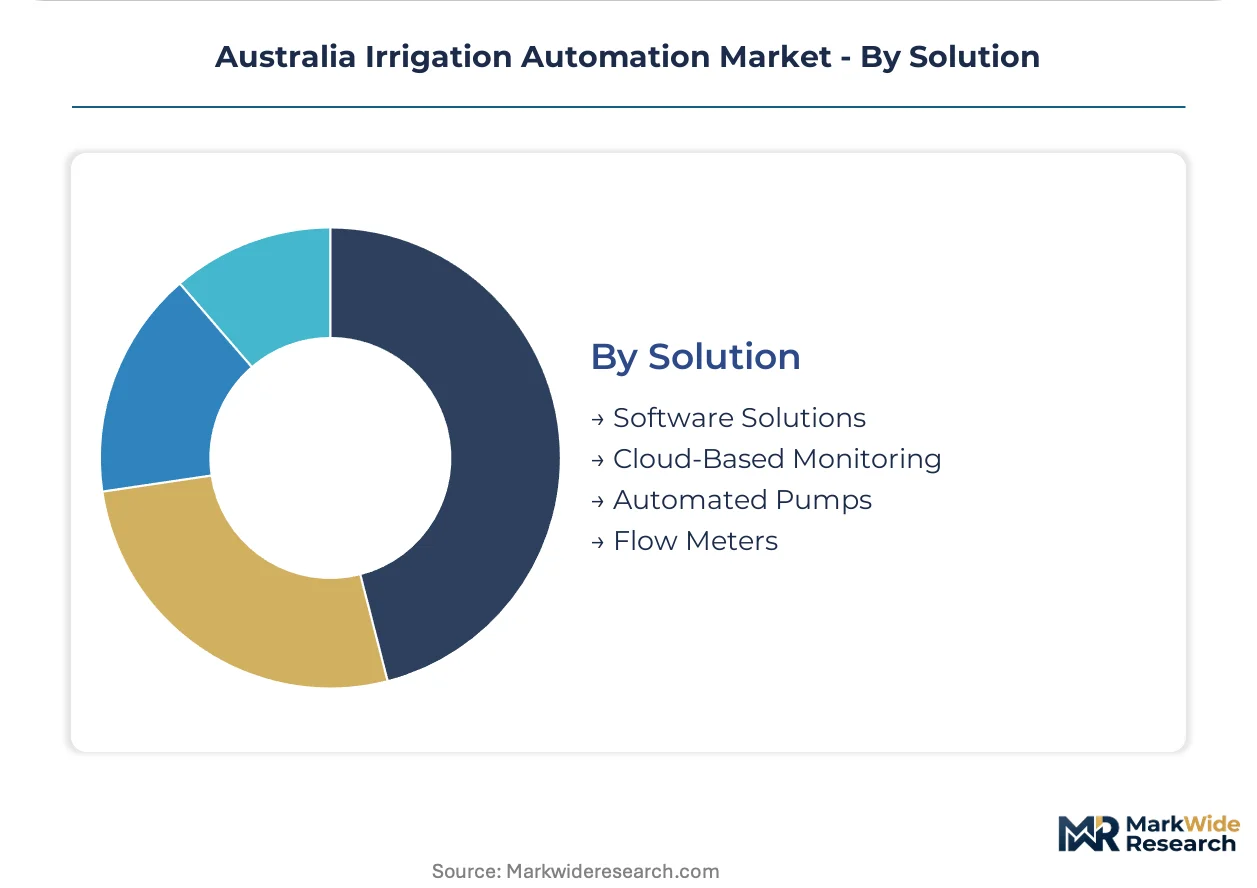
Solution:
Margin capture is shifting from hardware sales toward recurring software and monitoring revenue streams.
- Software Solutions:Farm management platforms embed Bureau of Meteorology data feeds with entitlement tracking for audit-ready compliance documentation. Cotton and rice producers in the northern basin face the steepest adaptation curves as diversion limit enforcement tightens.
- Cloud-Based Monitoring:LoRaWAN telemetry protocols reduce connectivity costs for remote sensor networks, enabling smaller farms to justify real-time monitoring investment previously viable only at corporate scale.
- Automated Pumps:Solar-powered pumping integration aligns with Australian Renewable Energy Agency incentives for off-grid operational cost reduction.
- Flow Meters:Volumetric measurement devices satisfy Basin Plan sustainable diversion limit reporting requirements.
Hardware legacy favors automated pumps; recurring revenue expansion favors cloud-based monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Murray-Darling Basin Plan's sustainable diversion limits are compressing capital replacement timelines and forcing telemetry upgrades across Australia's irrigation belt. State-level water security frameworks and federal renewable energy incentives are reshaping procurement patterns. Regional concentration clusters around the Murray-Darling Basin states, with Tasmania and Western Australia presenting expansion frontiers.
New South Wales
Broadacre grain farmers in the Murrumbidgee and Goulburn-Murray districts are expanding sensor-based system purchases under tightening volumetric tracking requirements. The state's Natural Resources Access Regulator enforces water take compliance through telemetry-mandated reporting. Corporate farming operations near Griffith and Deniliquin favor bundled service contracts pairing pivot hardware with multi-season remote monitoring.
Victoria
Horticulture belt expansion in the Sunraysia region drives precision irrigation hardware purchases as water scarcity intensifies. Victorian water corporations administer bulk entitlements that accelerate automation adoption for audit-ready documentation. Premium wine producers in the Yarra Valley and Mornington Peninsula retrofit drip systems with soil moisture mapping and canopy temperature sensors.
Queensland
Cotton and rice producers in the northern basin face steep adaptation curves as diversion limit enforcement tightens. The state's Department of Resources oversees water planning that mandates flow metering integration with farm management software. Irrigated cotton operations near St George and Dirranbandi deploy subsurface drip to minimize evaporative losses under Basin Plan limits.
South Australia
Municipal water restrictions in Adelaide drive smart controller demand for municipal parks and sports turf under urban green infrastructure mandates. The South Australian Water Corporation's pricing signals accelerate residential and commercial automation adoption. Precision viticulture in the Barossa Valley and McLaren Vale compresses water application variance through deficit irrigation protocols.
Tasmania
Underpenetrated precision automation markets in high-rainfall vegetable and dairy zones offer expansion potential as water security planning tightens. The state's Irrigation Development Board coordinates infrastructure investment that enables sensor network deployment. Protected cropping expansion near Devonport and the Tamar Valley drives demand for integrated climate-irrigation control platforms.
Australia Irrigation Automation Market Competitive Environment
On the supply side, the industry is moderately concentrated around specialist irrigation dealerships that cluster technical expertise in the Murray-Darling Basin. Three strategic archetypes dominate: drip irrigation heritage specialists, pivot hardware manufacturers, and centralized control platform providers. Competitive moves concentrate on bundled service contract expansion and solar-powered pumping integration to capture renewable energy incentives.
Within the heritage specialist tier, Netafim anchors premium system sales in Australian horticulture through its drip irrigation lineage. Lindsay Corporation exemplifies the pivot hardware archetype, with its Zimmatic brand dominating broadacre field coverage. Rain Bird Corporation occupies a position in centralized control platforms that integrate flow metering with weather data feeds.
| Leading Market Players |
|---|
| Antelco |
| Weathermatic |
| Orbit Irrigation |
| The Toro Company |
| Rain Bird Corporation |
| Netafim |
| Jain Irrigation Systems |
| Lindsay Corporation |
| Valmont Industries |
| Others |
Value Chain & Pricing Dynamics
Road-rail intermodal corridors connecting Adelaide and Melbourne to the Murray-Darling Basin irrigation districts transmit aluminum and polymer cost volatility directly into hardware pricing tiers, compressing margins for pivot and drip component manufacturers while amplifying price differentiation between bundled service contracts and transactional equipment sales.
Pricing Analysis
Certification level under AS 4419 equipment specifications creates the primary spread between premium telemetry-integrated systems and basic electromechanical hardware. Three-tier pricing structure across premium, standard, and economy levels segments the market, with premium tiers capturing recurring software revenue through remote monitoring subscriptions. Cost compression in standard-tier pivot hardware is intensifying because aluminum input volatility squeezes manufacturer margins. Corporate farming operations in the Murrumbidgee and Goulburn-Murray districts exhibit lowest price sensitivity due to compliance-driven replacement cycles, while smaller broadacre grain growers in Victoria face acute budget constraints.
Supply Chain Analysis
Tariff exposure between China and Australia dominates supply chain risk calculations for electromechanical valve actuators and polymer emitter components. Manufacturing concentrates in China, Israel, and the United States for precision irrigation hardware. Component sourcing draws from Australian aluminum smelters, Chinese polymer resin producers, and Taiwanese semiconductor foundries for sensor telemetry chips. Single-source vulnerability persists for pressure-compensating drip emitters. Distribution runs through specialist irrigation dealerships clustered in the Murray-Darling Basin, with technical installation expertise creating captive channel relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemetry technician scarcity across regional Australia constrains automation deployment velocity, creating a bottleneck where hardware availability outpaces field calibration capacity and compressing returns on dealer network expansion investments.
For Market Incumbents: Entrench service bundling advantages by extending multi-season remote monitoring contracts into Tasmania and Western Australia, where technical expertise gaps threaten emerging competitors. Deepen backward integration into solar-powered pumping systems to capture Australian Renewable Energy Agency incentives and defend margin position against aluminum price volatility. Lock in exclusive distribution partnerships with the Natural Resources Access Regulator's preferred telemetry vendors. For New Entrants and Emerging Players: Build out cloud-based monitoring platforms targeting Tasmanian vegetable and dairy operations, the most penetrable geography given underdeveloped dealer infrastructure. Pursue LoRaWAN protocol specialization to reduce connectivity cost barriers for smaller farms previously excluded from corporate-scale automation. Position through council procurement channels for urban green infrastructure mandates in Perth, Adelaide, and Melbourne. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-centric platforms with recurring revenue streams over hardware-dependent manufacturers facing commodity input volatility. Long-term viability rests on farm management software providers embedding Bureau of Meteorology data feeds with entitlement tracking for audit-ready compliance documentation. Target acquisition candidates with established AS 4419 certification and existing Murray-Darling Basin dealer relationships. Watch telemetry technician training pipeline expansion as inflection indicator for market penetration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Solar-Powered Pumping Integration | Captures Australian Renewable Energy Agency incentives while reducing off-grid operational costs for remote broadacre operations. |
| LoRaWAN Protocol Deployment | Enables smaller farms to justify real-time monitoring investment previously viable only at corporate scale across the analysis window. |
| AS 4419 Certification Investment | Resolves interoperability gaps with emerging IoT protocols and secures preferred vendor status under Murray-Darling Basin compliance frameworks. |
| Tasmanian Dealer Network Expansion | Addresses acute telemetry technician scarcity and captures protected cropping growth near Devonport and the Tamar Valley. |
| Bundled Service Contract Extension | Displaces transactional hardware sales and concentrates preference share among corporate farming operations in high-compliance districts. |
Study Parameters
Initial hypotheses were tested against primary input from irrigation dealership principals, farm management software developers, telemetry field engineers, and Murray-Darling Basin water entitlement administrators, and refined through secondary validation against Bureau of Meteorology water data service documentation, Standards Australia AS 4419 specifications, Natural Resources Access Regulator compliance bulletins, and Australian Bureau of Agricultural and Resource Economics trade flow data. Bottom-up equipment shipment tracking and top-down water entitlement allocation modeling were triangulated to establish market sizing boundaries.
Demand-supply-balance framing anchored the forecast framework, with segmentation dimensions spanning technology type, application context, and end-user procurement sophistication across the projection horizon. CAGRs were derived from equipment replacement cycle compression under Basin Plan deadlines and telemetry adoption diffusion curves. Industry-specific forecast inputs incorporated Bureau of Meteorology data integration intensity and LoRaWAN network coverage expansion trajectories.
Stress conditions across aluminum and polymer input price bands, seasonal water allocation variability, and telemetry technician availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding compliance deadline enforcement rigor and renewable energy incentive continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Greenhouse Irrigation Systems Market
Farm Equipment and Irrigations
Ride-On Mower Market
Farm Equipment and Irrigations
Soaker Hose Irrigation System Market
Farm Equipment and Irrigations
Global Fruit Picker Market
Farm Equipment and Irrigations
Agricultural Solar Pumps Market
Farm Equipment and Irrigations
Zero Turn Mowers Market
Farm Equipment and Irrigations
United States Irrigation Valves Market
Farm Equipment and Irrigations
South America Irrigation Machinery Market
Farm Equipment and Irrigations
Irrigation Pumps Market
Farm Equipment and Irrigations
Rain Barrels Market
Farm Equipment and Irrigations
India Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
North America Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Brazil Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Irrigation Controllers Market
Farm Equipment and Irrigations
Africa Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Hose Reel Irrigation Machine Market