
 Global Fruit Picker Market | 2026-2036
Global Fruit Picker Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fruit Picker Market Foresight
Seasonal agricultural labor availability is rotating toward chronic shortage across major fruit-producing belts, forcing orchard operators toward mechanized alternatives. HARVEST CROO leverages its robotic strawberry harvesting architecture to sustain deployment momentum in Florida and California growing regions. Abundant Robotics anchors its competitive position through computer-vision-guided apple harvesting systems that operate with minimal human oversight. FFRobotics differentiates via multi-fruit robotic platforms capable of handling delicate varieties across European orchard estates.
A fruit picker constitutes a specialized harvesting implement—spanning handheld manual tools, hydraulically actuated tree shakers, pneumatic limb-agitating systems, and autonomous robotic end-effectors—engineered to detach mature fruit from stems or branches without flesh bruising or structural damage to the tree. The equipment serves commercial agriculture by reducing per-unit harvest labor hours and minimizing post-harvest spoilage from improper handling. Robotic fruit pickers command the fastest expansion trajectory within the product type dimension, though manual and hydraulic variants still dominate unit volume in developing orchard economies. Berry collection and apple harvesting represent the most technically demanding application categories, where precision requirements sustain premium pricing tiers across both equipment and service models.
The EU Machinery Directive and CE marking requirements govern equipment safety standards for pneumatic and electric picker sales across European orchard markets, while the FDA's emerging agricultural automation guidance shapes food-contact material specifications and traceability protocols in the United States. China's GB standards and SAMR enforcement create parallel certification pathways for imported harvesting equipment entering domestic fruit production zones. Stakeholders must monitor evolving national labor migration policies alongside machinery safety harmonization efforts, as regulatory fragmentation threatens to outpace equipment standardization timelines.
Market Dynamics
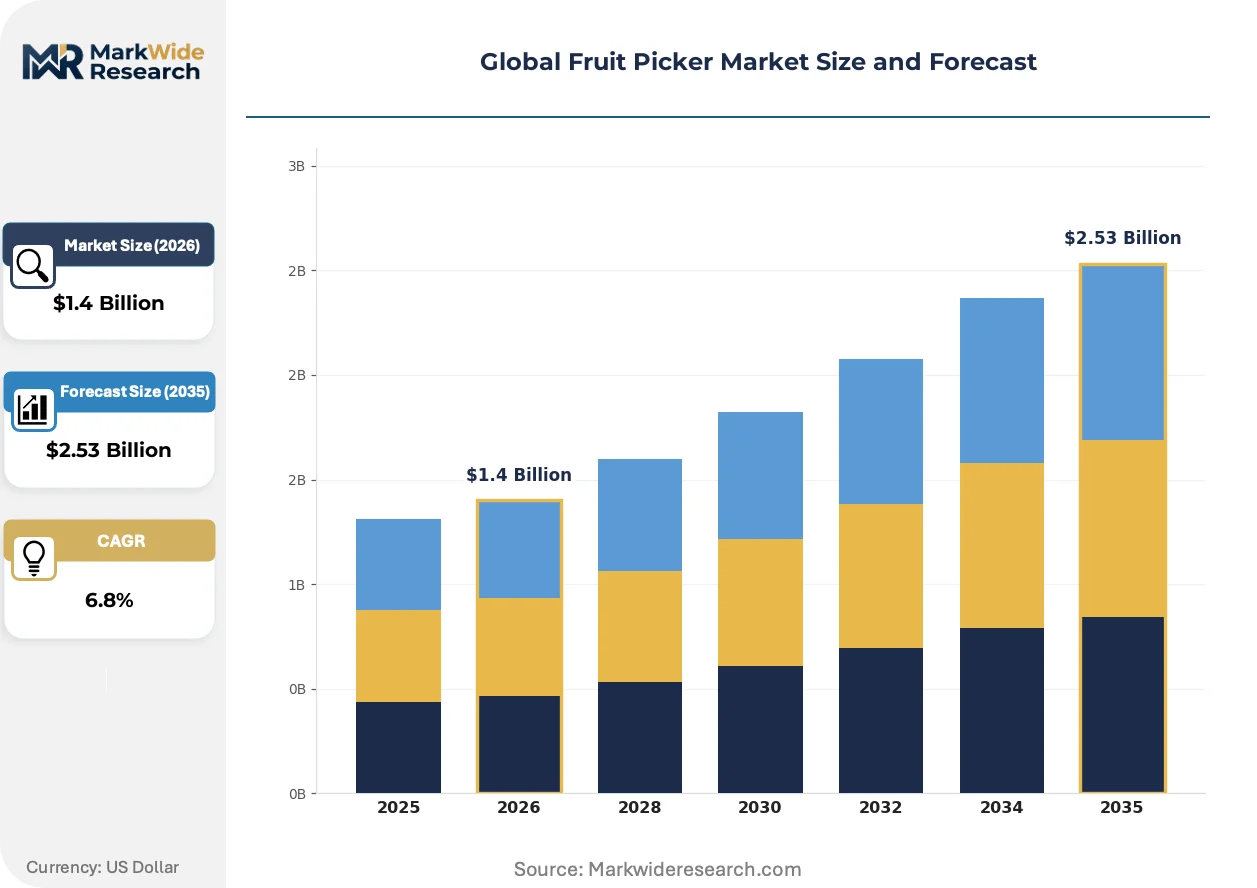
Seasonal labor shortages across California, Florida, and Spain are compressing orchard operators' harvest windows and forcing accelerated capital deployment into robotic and pneumatic systems. The EU Machinery Directive's safety certification requirements and emerging FDA guidance on agricultural automation are simultaneously reshaping equipment procurement criteria and compliance timelines.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for pneumatic and electric pickers are standardizing safety protocols across European orchard markets, creating procurement clarity for large-scale operators in Italy and Spain.
- Computer-vision-guided harvesting:Autonomous robotic end-effectors with real-time ripeness detection are reducing per-unit labor hours in apple and berry operations across Washington State and California growing regions.
- Orchard consolidation in China:Large-scale fruit production zones in Shandong and Shaanxi provinces are aggregating demand for mechanized harvesting equipment as smallholder plots transfer to commercial operators.
Market Restraints
- Steel and aluminum input volatility:Hydraulic picker manufacturers face margin compression from commodity price swings in structural alloys and precision-machined components sourced from East Asian foundries.
- Technical limitation in soft-fruit handling:Robotic grippers struggle with bruise-free strawberry and raspberry detachment at commercial throughput rates, constraining deployment in premium berry segments.
- Regulatory friction from China's GB standards:SAMR enforcement of domestic certification pathways creates parallel compliance burdens for European and North American equipment exporters entering Chinese production zones.
Strategic Opportunities
- Underpenetrated stone-fruit applications:Peach and plum harvesting in Argentina and Chile remains dominated by manual labor, presenting first-mover openings for pneumatic shaker systems adapted to orchard topography.
- Technology convergence of LiDAR and hyperspectral imaging:Integrated sensing architectures enable real-time ripeness mapping and selective harvesting across variable tree canopies in Italian and Greek olive and citrus operations.
- India's PLI scheme for agricultural mechanization:Production-linked incentives for domestic equipment manufacturing are attracting joint-venture investment for picker assembly in Maharashtra and Karnataka fruit belts.
Industry Challenges
- Mechatronics talent scarcity:Orchard automation specialists with combined robotics and agricultural domain expertise command premium compensation in California's Central Valley and Spain's Valencia region.
- CE marking timeline compression:EU Machinery Directive conformity assessment for novel robotic architectures extends equipment launch cycles by 8-14 months, delaying revenue recognition for European deployments.
- Legacy hydraulic fleet integration:Retrofitting pneumatic and robotic systems with existing tractor-hydraulic interfaces requires custom engineering for Spanish and Italian orchard operators with mixed-vintage equipment bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fruit Picker Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Fruit Pickers, Hydraulic Fruit Pickers, Pneumatic Fruit Pickers, Electric Fruit Pickers, Robotic Fruit Pickers Application: Apple Harvesting, Citrus Gathering, Berry Collection, Mango Picking, Olive Harvesting End User: Small-Scale Farmers, Large-Scale Growers, Agricultural Cooperatives, Horticulturalists, Pick-Your-Own Operations Distribution Channel: Direct Sales, Agricultural Equipment Dealers, Online Marketplaces, Rental Services, Wholesale Suppliers |
| Companies Covered | HARVEST CROO, Abundant Robotics, Agrobot, Corona Tools, Flexrake, FFRobotics, OCTINION, Ohuhu, Dogtooth Technologies Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fruit Picker Market Shifts & Advancements
Autonomous harvesting architectures are displacing conventional mechanical systems through sensor fusion and adaptive gripping technologies. Regulatory divergence across the EU, United States, and China is fragmenting certification pathways while procurement models rotate toward equipment-as-a-service structures.
Soft-robotic end-effectors with pneumatically actuated fingers are displacing rigid mechanical grippers in delicate-fruit operations. Large-scale berry growers in California and Florida are deploying these systems at commercial scale. The technology is displacing seasonal hand-picking crews while reducing post-harvest spoilage rates in premium strawberry segments.
REACH substance restrictions and emerging FDA agricultural automation guidance are tightening material specifications for food-contact picker components. Equipment manufacturers must reformulate polymer formulations and lubricant chemistries to maintain market access. Pneumatic picker suppliers serving European and North American markets face accelerated R&D cycles to satisfy dual-jurisdiction compliance.
Harvest contracting is consolidating around outcome-based agreements where operators pay per successfully picked unit rather than equipment lease or purchase. This model is disrupting traditional distributor relationships and OEM direct-sales channels in Spain and Italy. Large orchard estates in Andalusia and Sicily are driving the shift, compressing vendor cash conversion cycles while transferring yield-risk exposure to equipment providers.
Global Fruit Picker Market Segmentation
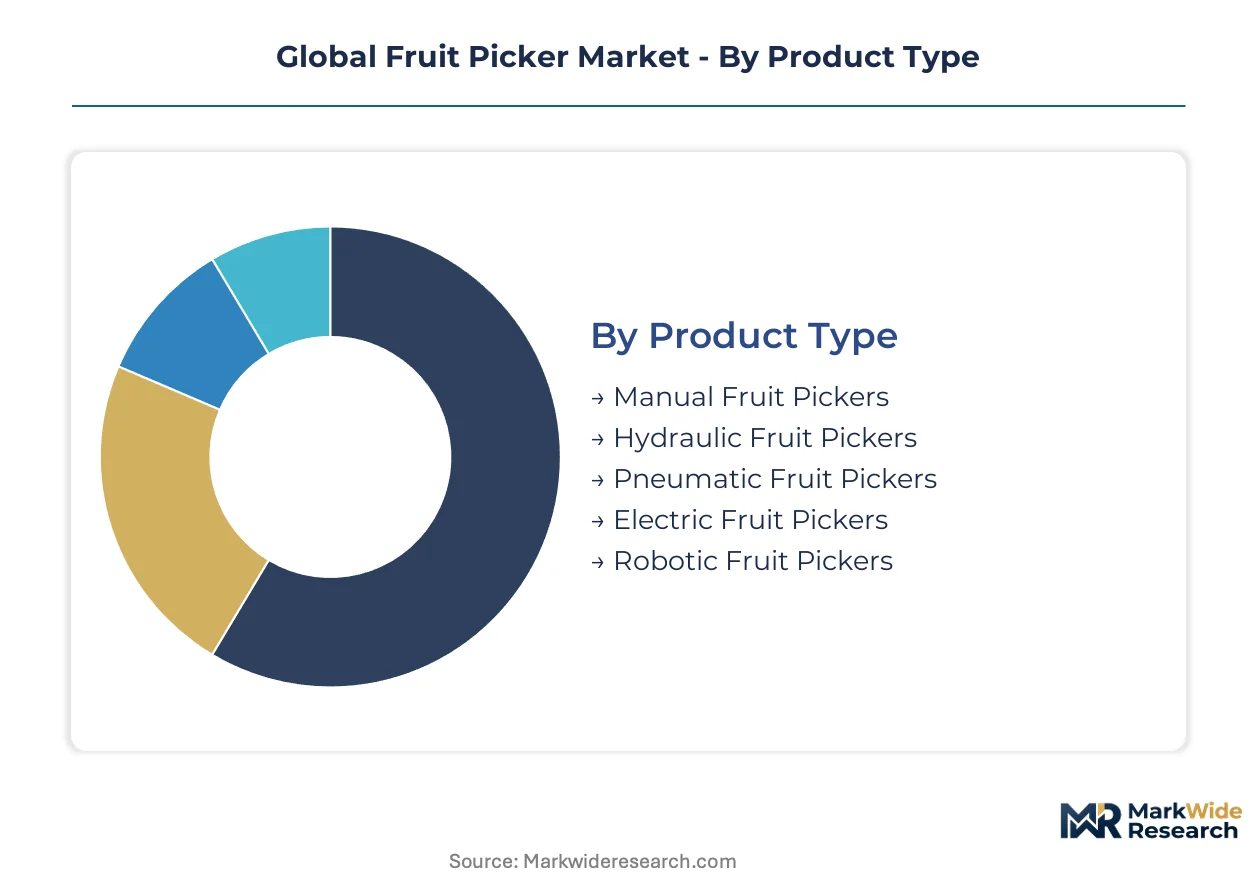
Equipment substitution dynamics vary sharply across picker categories, with labor cost trajectories and orchard consolidation patterns determining which segments face imminent displacement versus sustained relevance. Understanding these cross-currents clarifies where capital deployment and R&D investment will concentrate.
Product Type:
Substitution pressure intensifies most acutely where seasonal labor costs have crossed mechanization thresholds, forcing rapid platform transitions in premium fruit belts.
- Robotic Fruit Pickers:Autonomous end-effectors with computer-vision-guided gripping architectures operate in Washington State apple orchards and California berry fields with minimal human oversight. Large-scale growers in Spain's Valencia region are accelerating procurement as seasonal labor pools contract.
- Pneumatic Fruit Pickers:Compressed-air limb-agitating systems detach mature fruit through controlled vibration cycles, dominating olive harvesting across Italian and Greek estates. CE marking requirements under the EU Machinery Directive are standardizing safety protocols for European deployments.
- Manual Fruit Pickers:Handheld cutting and reaching tools retain dominance in smallholder operations across India and Southeast Asia where capital constraints persist.
- Hydraulic Fruit Pickers:Tractor-mounted shaker systems serve legacy orchard fleets in Argentina and Chile with established hydraulic infrastructure.
- Electric Fruit Pickers:Battery-powered handheld units bridge manual and pneumatic functionality for mid-scale operations in China's Shandong province.
Manual fruit pickers retain volume leadership; robotic fruit pickers hold the steepest expansion curve.
Application:
Margin structures diverge sharply across crop categories, with bruise-sensitive varieties commanding premium equipment specifications and service pricing.
- Berry Collection:Strawberry and raspberry harvesting demands soft-robotic grippers with pressure-feedback controls to prevent flesh damage during detachment. Florida and California growers deploy these systems at commercial scale despite throughput constraints.
- Apple Harvesting:Computer-vision systems with real-time ripeness detection navigate variable tree canopies in Washington State and Himachal Pradesh orchards. Abundant Robotics anchors deployment momentum through minimal-oversight architectures.
- Citrus Gathering:Pneumatic shaker systems adapted to irregular canopy structures serve orange and lemon operations across Spain and Italy.
- Olive Harvesting:Trunk-mounted vibrators with catch-frame integration dominate Mediterranean basin operations where terrain precludes ground-based collection.
- Mango Picking:Manual pole-and-basket methods persist in India and Mexico where orchard topography and stem-attachment biology resist mechanization.
Apple harvesting commands the highest equipment price points; berry collection is expanding most quickly.
End User:
Procurement scale and financing access create distinct equipment tiers, with cooperative structures aggregating demand for advanced systems.
- Large-Scale Growers:Corporate orchard operators in California's Central Valley and Spain's Andalusia region deploy robotic platforms through outcome-based contracting models. Capital availability supports rapid technology refresh cycles.
- Agricultural Cooperatives:Pooled procurement structures in Italy's Emilia-Romagna and France's Provence aggregate demand for pneumatic harvesting systems. Shared equipment utilization improves amortization across seasonal windows.
- Small-Scale Farmers:Manual and electric handheld tools dominate procurement in India's Maharashtra belt and Vietnam's Mekong Delta.
- Horticulturalists:Specialty nursery operators in the Netherlands and Belgium prioritize precision reach tools for specimen maintenance.
- Pick-Your-Own Operations:U-pick farms in Germany's Baden-Württemberg and New York's Hudson Valley emphasize customer-accessible collection equipment.
Large-scale growers anchor premium segment demand; agricultural cooperatives are gaining share fastest through pooled procurement.
Distribution Channel:
Channel selection reflects equipment complexity and operator technical sophistication, with advanced platforms requiring direct vendor relationships.
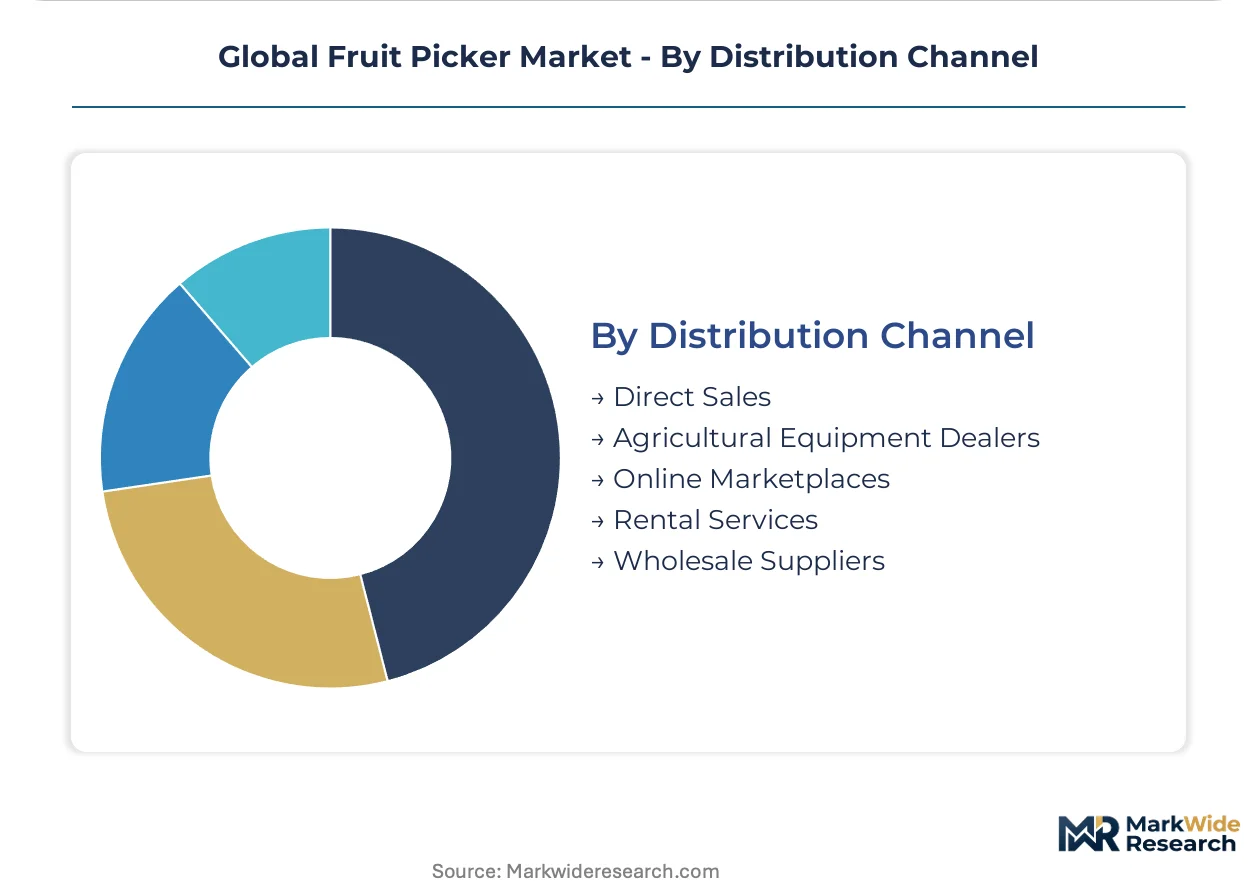
- Direct Sales:Robotic system manufacturers maintain captive sales forces for California and Florida large-grower accounts. Technical commissioning and training requirements justify bypassing dealer networks.
- Agricultural Equipment Dealers:John Deere and Kubota dealer networks distribute hydraulic and pneumatic pickers across Midwestern US and European markets. Established service infrastructure supports maintenance-intensive platforms.
- Rental Services:Seasonal equipment leasing gains traction among Italian and Spanish cooperatives with compressed harvest windows.
- Online Marketplaces:Alibaba and Amazon channels serve manual and electric picker demand in China's domestic market and Southeast Asia.
- Wholesale Suppliers:Bulk procurement aggregators supply replacement parts and consumables for legacy fleet maintenance.
Agricultural equipment dealers retain volume leadership; direct sales channels are climbing the fastest as robotic deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: developed orchard belts deploy autonomous robotic platforms while emerging fruit economies retain manual and semi-mechanized methods. Equipment specifications and procurement financing models reflect these structural divides.
United States
California's Central Valley and Washington State's Yakima Valley anchor robotic deployment for apple and berry harvesting. FDA's emerging agricultural automation guidance shapes food-contact material specifications for equipment entering domestic production zones. Large-scale growers in Florida's Plant City region accelerate procurement of pneumatic systems as seasonal labor pools contract.
China
Shandong and Shaanxi provinces drive mechanization demand as orchard consolidation transfers smallholder plots to commercial operators. SAMR enforcement of GB standards creates parallel certification pathways for imported harvesting equipment. Yangtze River Delta equipment manufacturers are scaling domestic production of electric handheld pickers for mid-scale operations.
Spain
Andalusia's olive and citrus estates deploy pneumatic shaker systems under EU Machinery Directive CE marking requirements. Valencia region growers accelerate robotic procurement as North African seasonal labor availability tightens. Catalan agricultural cooperatives aggregate demand through shared equipment utilization models.
Italy
Emilia-Romagna's fruit cooperatives pool procurement for pneumatic harvesting systems across compressed seasonal windows. REACH substance restrictions tighten polymer specifications for food-contact picker components. Sicilian large orchard estates drive outcome-based contracting shifts, compressing vendor cash conversion cycles.
India
Maharashtra and Karnataka fruit belts attract joint-venture investment under PLI scheme incentives for domestic equipment manufacturing. Smallholder operations in Himachal Pradesh retain manual pole-and-basket methods for mango harvesting. BIS certification requirements shape import pathways for European pneumatic system suppliers.
Global Fruit Picker Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper layer commanding premium positioning through captive technology architectures. The middle tier fragments across regional equipment fabricators and component suppliers serving legacy hydraulic fleets. Three archetypes dominate: vision-guided robotics developers, pneumatic system specialists, and diversified agricultural equipment conglomerates with harvesting attachments. Competitive moves concentrate on strategic partnerships for sensor fusion integration and geographic licensing arrangements for CE-marked platform variants.
Among robotics-focused developers, HARVEST CROO and Abundant Robotics exemplify the autonomous harvesting archetype with computer-vision-guided architectures. FFRobotics occupies a position within the multi-fruit platform specialist tier, representing European orchard estate focus. These three entities anchor the premium equipment segment where outcome-based contracting models are displacing traditional direct sales channels.
| Leading Market Players |
|---|
| HARVEST CROO |
| Abundant Robotics |
| Agrobot |
| Corona Tools |
| Flexrake |
| FFRobotics |
| OCTINION |
| Ohuhu |
| Dogtooth Technologies Limited |
| Others |
Supply & Pricing Matrix
EU Machinery Directive CE marking requirements gate both supplier qualification and price differentiation across European orchard markets, compressing equipment launch timelines while creating tiered compliance premiums that separate certified robotic platforms from uncertified alternatives.
Pricing Analysis
Long-term offtake contracts dominate procurement between California large-scale growers and robotic system vendors, though outcome-based per-unit agreements are displacing traditional leases in Spain and Italy. Price differentiation rests on CE certification tier and after-sales service bundling, with fully certified architectures commanding substantial premiums over provisional-marked alternatives. Pricing pressure stems from steel and aluminum input volatility transmitted through East Asian foundry networks. Smallholder cooperatives exhibit highest price sensitivity, while corporate orchard operators prioritize throughput reliability over capital efficiency.
Supply Chain Analysis
China and Germany anchor precision-machined component fabrication for pneumatic and robotic picker assemblies, with Italian and Spanish firms contributing specialized polymer formulations for food-contact grippers. Raw material dependencies center on high-grade aluminum alloys, servo motors, and LiDAR sensors. Single-source vulnerability concentrates in computer-vision processing chipsets sourced from Taiwanese foundries. Distribution runs through agricultural equipment dealer networks for hydraulic and pneumatic platforms, while direct vendor relationships dominate robotic system deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computer-vision-guided harvesting architectures are disrupting century-old manual labor dependencies, with FDA agricultural automation guidance and EU Machinery Directive compliance timelines compressing vendor differentiation windows.
For Market Incumbents: Secure CE marking pre-certification for next-generation robotic architectures to outpace 8-14 month conformity assessment delays threatening European revenue recognition. Deepen backward integration into precision-machined component production to offset East Asian foundry price volatility eroding hydraulic picker margins.
For New Entrants and Emerging Players: FDA agricultural automation guidance fast-tracks market entry for food-contact material specialists capable of satisfying dual-jurisdiction compliance. Target stone-fruit harvesting in Argentina and Chile where pneumatic shaker penetration remains minimal and manual labor costs are crossing mechanization thresholds. Pursue cooperative procurement aggregation models in Italy's Emilia-Romagna to bypass capital-intensive direct sales infrastructure.
For Investors and Strategic Acquirers: FDA agricultural automation guidance reshapes the acquisition landscape toward food-contact material compliance capabilities as a standalone valuation pillar. Five-to-ten year viability favors vertically integrated robotics developers with captive computer-vision architectures rather than pneumatic system assemblers facing commodity input exposure. Monitor CE marking timeline compression as the inflection signal indicating which vendors can sustain European deployment momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pre-Certification | Compresses equipment launch cycles by 8-14 months for European orchard deployments. |
| Outcome-Based Contracting | Transfers yield-risk exposure to vendors while accelerating adoption in Andalusia and Sicily. |
| Backward Integration into Components | Insulates margin structures from East Asian aluminum and steel price volatility. |
| Soft-Robotic End-Effector Development | Enables bruise-free strawberry harvesting at commercial throughput rates in Florida. |
| Cooperative Procurement Aggregation | Improves equipment amortization across Italian and Spanish shared-utilization models. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with orchard operations managers, agricultural cooperative procurement leads, robotic systems engineers, and pneumatic equipment distributors; and secondary validation through EU Machinery Directive filings, FDA guidance documents, SAMR GB standard registrations, customs trade data for harvesting equipment, and SEC filings from diversified agricultural equipment manufacturers. Bottom-up equipment deployment counts triangulated against top-down orchard consolidation metrics.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation across product type, application crop category, end-user scale tier, and distribution channel structure. CAGRs were derived from fitted growth curves incorporating labor shortage severity indices, orchard consolidation rates, and regulatory compliance timeline assumptions. Industry-specific inputs included seasonal labor availability forecasts for California's Central Valley and CE marking assessment duration distributions.
Decision-makers should treat outputs as directional under base assumptions of sustained labor shortage trajectories and stable regulatory harmonization timelines; material deviation in seasonal migration policies or machinery safety standard fragmentation would warrant model refresh. Recalibration cycles align with material shifts in EU Machinery Directive enforcement patterns and FDA guidance finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Smart Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Irrigation Controllers Market
Farm Equipment and Irrigations
Sprinkler Irrigation Market
Farm Equipment and Irrigations
Global Mechanized Irrigation Systems Market
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Global Irrigation Automation Market
Farm Equipment and Irrigations
Watering Cans Market
Farm Equipment and Irrigations
Tractor Rental Market
Farm Equipment and Irrigations
Drip Irrigation Market
Farm Equipment and Irrigations
Africa Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Asia Pacific Irrigation Valves Market
Farm Equipment and Irrigations
Irrigation Liner Market
Farm Equipment and Irrigations
Fertigation Control System Market
Farm Equipment and Irrigations
Ride-On Mower Market
Farm Equipment and Irrigations
Agriculture Logistics Market
Farm Equipment and Irrigations
Agricultural Solar Pumps Market