
 Global Spinal Motion Preservation Device Market | 2026-2036
Global Spinal Motion Preservation Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spinal Motion Preservation Device Market Intelligence
The substitution of traditional titanium alloys with advanced biocompatible polymers like PEEK is realigning the cost structure and performance characteristics of dynamic stabilization systems. Medtronic plc leverages its extensive distribution network to introduce next-generation polymer-based devices. Globus Medical differentiates through rapid innovation in expandable cage technology and robotic-assisted surgical platforms. Zimmer Biomet Holdings sustains its market position through a strong portfolio of both fusion and non-fusion spinal solutions.
Spinal motion preservation devices are implants designed to stabilize the spine while maintaining natural movement, offering an alternative to spinal fusion. These devices, including artificial discs and dynamic stabilizers, are engineered to bear physiological loads while permitting controlled flexion, extension, and rotation within specific vertebral segments. Artificial disc replacement products for treating degenerative disc disease represent the largest segment by revenue. Dynamic stabilization systems are showing significant growth, particularly for addressing spinal stenosis in younger, more active patients.
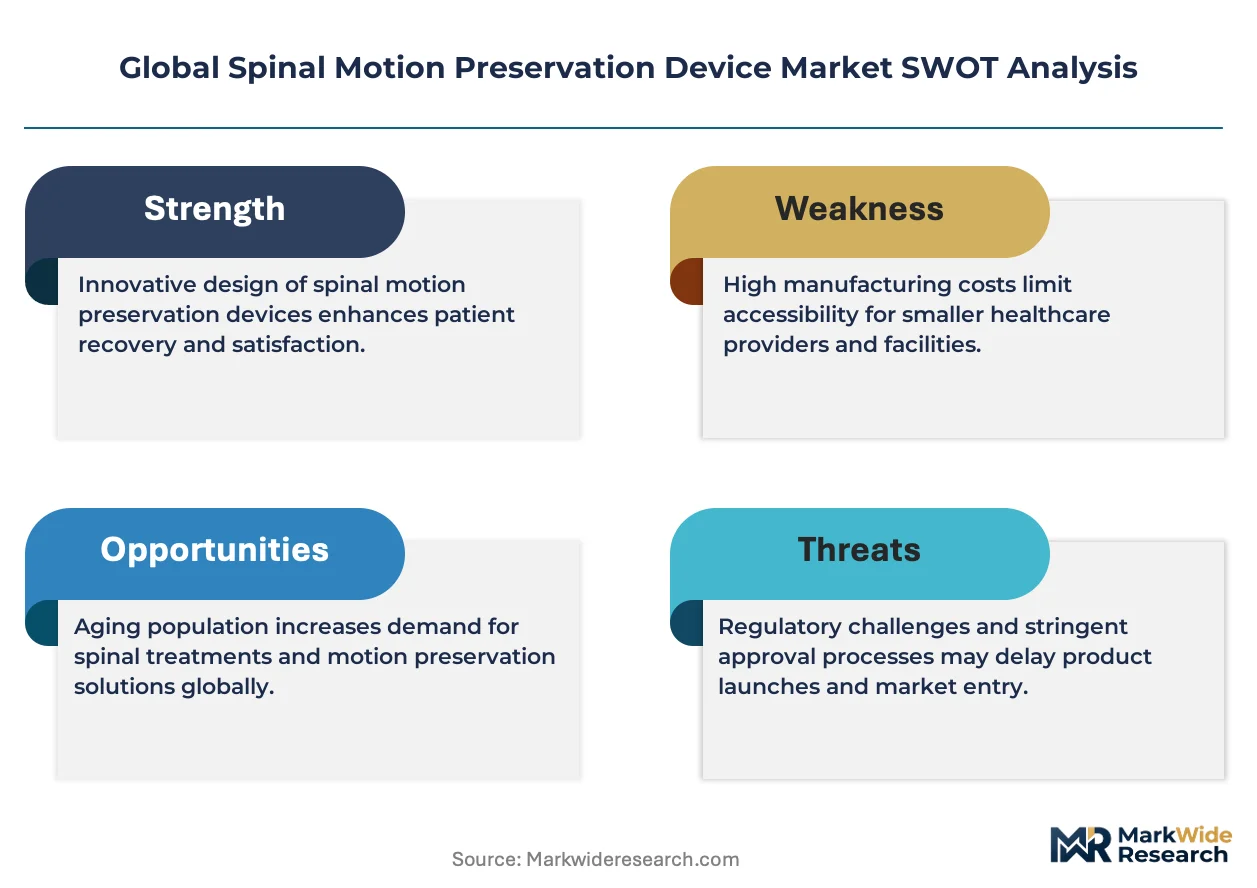
Market access hinges on stringent pre-market approval pathways set by regulators such as the US Food and Drug Administration (FDA) and China's National Medical Products Administration (NMPA). The European Union's Medical Device Regulation (MDR) imposes stricter clinical evidence and post-market surveillance requirements, influencing device design and lifecycle management. Future competitive advantage will be determined by a manufacturer's ability to generate and present long-term clinical data demonstrating superior patient outcomes and device durability.
Market Dynamics
The market's central force is the divergence between rapid material science advancements and the slow pace of generating long-term clinical data demanded by regulators like the FDA and EU authorities. This gap creates tension between innovation cycles and market access timelines, influencing strategic investment and product lifecycle management.
Growth Catalysts
- Advanced Materials:The substitution of titanium with polymers like PEEK creates lighter, more flexible dynamic stabilization systems with improved radiolucency for imaging.
- Demographic Shifts:An aging, active population in Germany and the United States seeks less invasive surgical options that preserve mobility over traditional spinal fusion.
- Reimbursement Policies:Favorable coverage for artificial disc replacement in specialized orthopedic centers expands patient access and procedural volume.
Market Restraints
- Regulatory Scrutiny:Strict pre-market approval pathways from the FDA and the EU's MDR require extensive, multi-year clinical trials, delaying market entry for new devices.
- Surgeon Training:A steep learning curve for implanting these devices limits adoption to surgeons who have completed specialized fellowship training.
- Alternative Procedures:Spinal fusion remains the gold standard for many indications, with a long history of use and established reimbursement, creating a strong substitution threat.
Strategic Opportunities
- Geographic Expansion:Markets in South Korea and Australia present opportunities as healthcare spending rises and regulatory pathways for innovative devices become more defined.
- Technology Integration:Incorporating smart sensors into implants to monitor micromotion and load offers a path toward data-driven, personalized post-operative care.
- Expanded Indications:Clinical trials validating devices for adjacent segment disease after a prior fusion can open a significant new patient population.
Industry Challenges
- Clinical Data Generation:The high cost and long timelines of producing multi-center, long-term follow-up studies demonstrating superiority over fusion remain a primary operational hurdle.
- Payer Acceptance:Convincing payers of the long-term cost-effectiveness of premium-priced devices requires substantial health economic outcome data versus fusion.
- Device Interoperability:A lack of standardization between manufacturers' systems creates complexity for hospitals managing instrumentation and implant inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spinal Motion Preservation Device Market |
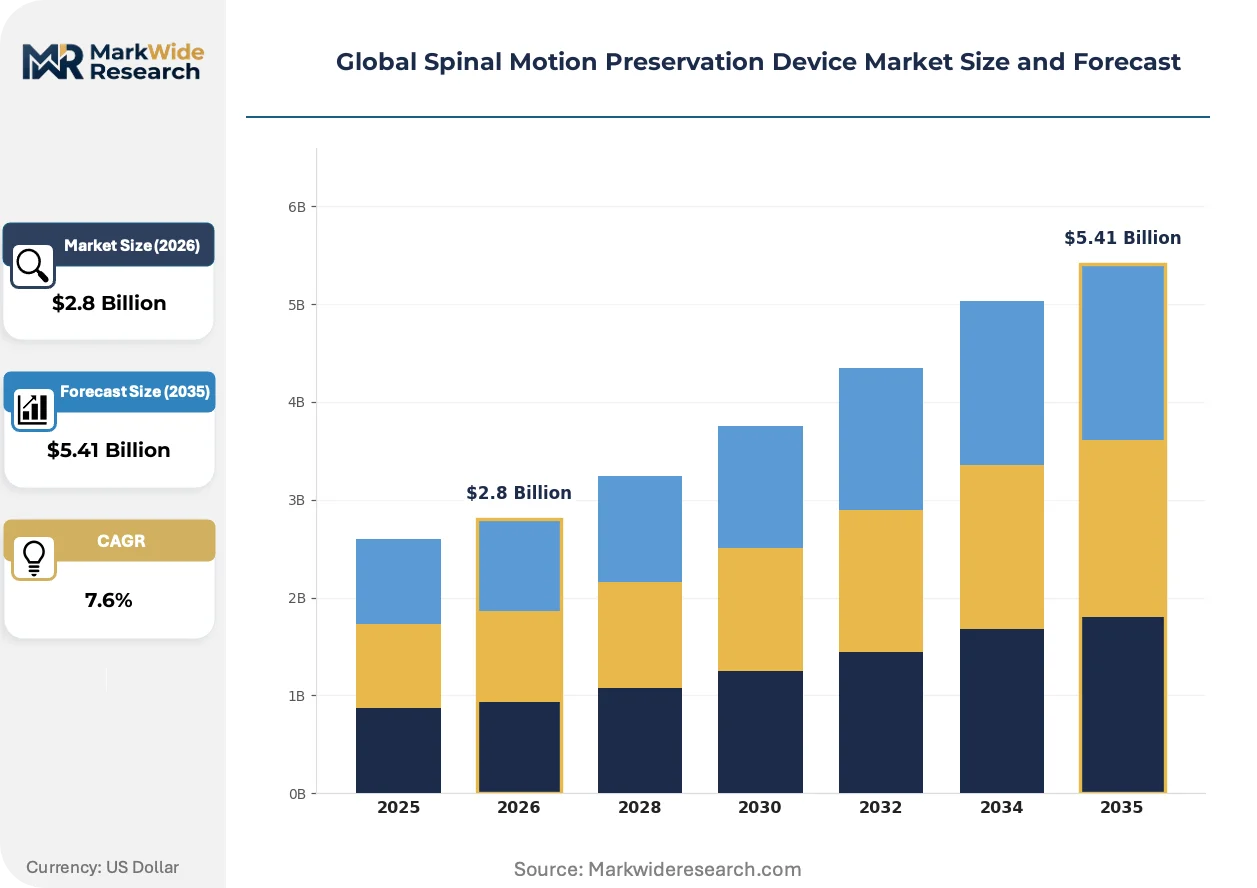
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Disc, Dynamic Stabilization System, Nucleus Replacement, Facet Replacement Technology: Mechanical, Polymer-Based, Titanium Alloy, Ceramics Application: Degenerative Disc Disease, Herniated Disc, Spinal Stenosis, Spondylolisthesis End User: Orthopedic Clinics, Specialized Hospitals, Rehabilitation Centers, Ambulatory Surgical Centers |
| Companies Covered | Medtronic plc, Zimmer Biomet Holdings, Stryker Corporation, Globus Medical, NuVasive, Johnson & Johnson (DePuy Synthes), Orthofix Medical Inc., Centinel Spine, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spinal Motion Preservation Device Market Strategic Shifts & Innovations
The evolution of implantable materials and integration of digital technologies are altering device capabilities. These shifts occur within a tightening global regulatory framework prioritizing demonstrable long-term patient outcomes over incremental design changes.
Additive manufacturing enables porous PEEK and titanium-hybrid implants. Surgeons adopt these advanced constructs to promote better osseointegration and long-term stability in younger, active patients. Tailoring implant porosity on a patient-specific basis is electrifying the development of next-generation dynamic stabilization systems.
The European Union's Medical Device Regulation (MDR) mandates more rigorous clinical evidence and continuous post-market surveillance. This regulatory shift compels manufacturers to invest heavily in collecting long-term outcome data. Artificial disc replacement devices face the most impact, as their benefit relies on proven long-term durability.
A clear procedural migration is moving spine cases from hospitals to ambulatory surgical centers (ASCs). This transition is propelled by payer incentives for cost-effective care and patient demand for minimally invasive surgery. The trend is most advanced in the United States, influencing device design toward systems optimized for outpatient efficiency.
Global Spinal Motion Preservation Device Market Segmentation
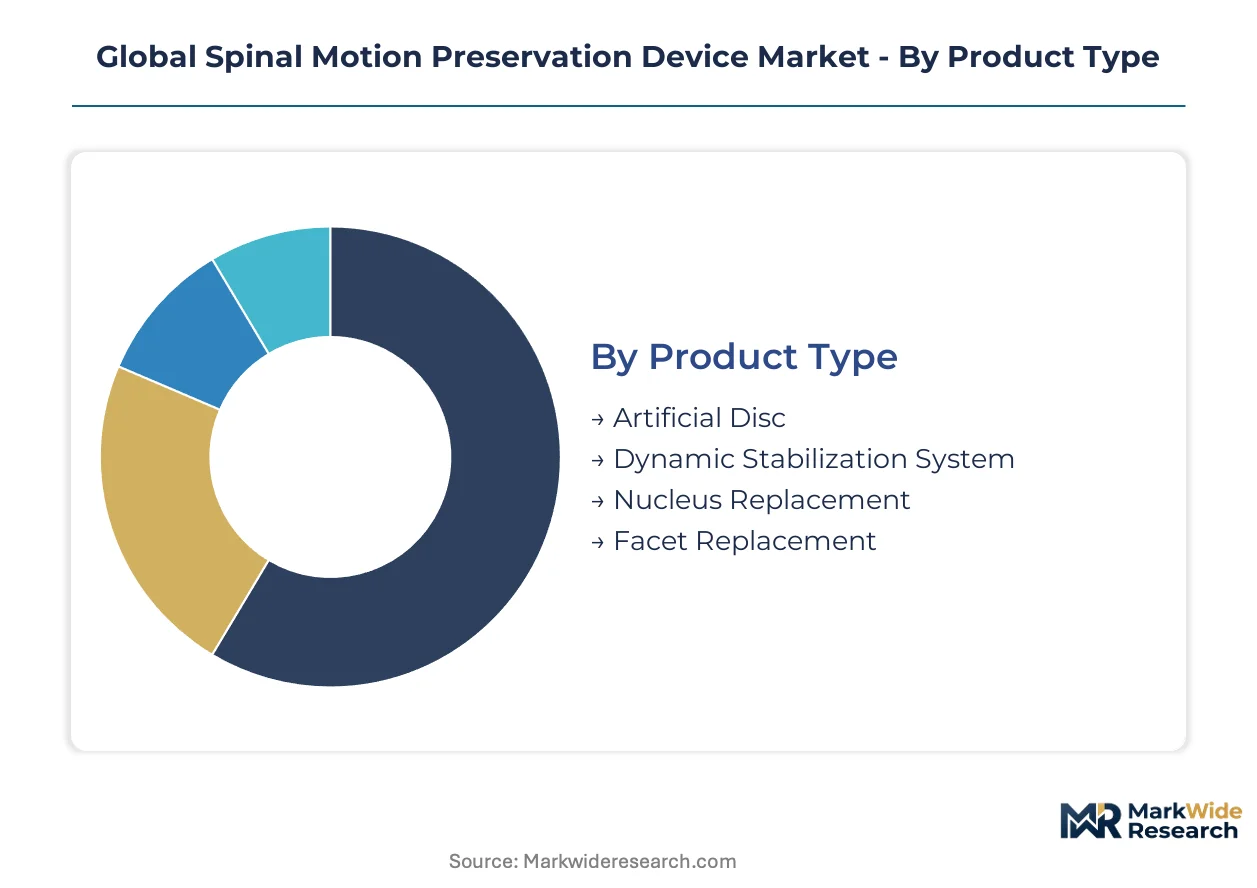
The segmentation of the global spinal motion preservation device market reveals distinct product characteristics, technological advancements, and end-user preferences. Understanding these categories is crucial for manufacturers to align product development with clinical needs and for healthcare providers to optimize patient selection and procedural settings.
Product Type:
Product types within spinal motion preservation devices face distinct regulatory hurdles, with artificial discs often requiring more extensive pre-market approval pathways from bodies like the US FDA and EU MDR.
- Artificial Disc:These devices replace a damaged intervertebral disc, aiming to restore physiological motion and reduce pain. Demand is concentrating in specialized orthopedic centers due to favorable reimbursement policies for degenerative disc disease.
- Dynamic Stabilization System:Designed to stabilize specific spinal segments while allowing controlled movement, these systems offer an alternative to rigid fusion. Demand is growing among younger, more active patients with spinal stenosis in regions like the United States and Germany.
- Nucleus Replacement:This segment involves implants that specifically replace the nucleus pulposus, preserving the annulus fibrosus and overall disc structure.
- Facet Replacement:Devices in this category address degeneration of the spinal facet joints, providing stability and restoring articular function.
Leading the category by volume: Artificial Disc. Growing fastest: Dynamic Stabilization System.
Technology:
Material science advancements are redefining performance and cost structures across different technology platforms within spinal motion preservation.
- Polymer-Based:This technology leverages advanced polymers such as PEEK, offering advantages like radiolucency for imaging and improved biomechanical flexibility. Demand is shifting towards these lighter, more flexible implants for minimally invasive procedures in ambulatory surgical centers.
- Titanium Alloy:Traditional titanium alloy devices provide high strength and proven biocompatibility, forming the backbone of many established spinal implants. Demand remains strong in conventional spinal surgeries and fusion procedures where long-term rigidity is desired.
- Mechanical:This segment includes devices that rely on various mechanical designs and linkages to facilitate controlled motion and spinal stabilization.
- Ceramics:Ceramic materials are explored for specific components due to their hardness, wear resistance, and inertness, particularly in articulating surfaces.
New polymer-based technologies are gaining share fastest, while titanium alloy devices maintain a significant volume.
Application:
Patient demographics and specific spinal pathologies drive demand for distinct application types in the spinal motion preservation market.
- Degenerative Disc Disease:This application segment targets patients suffering from chronic pain and instability due to intervertebral disc degeneration. Demand is concentrated in aging populations across the United States and Germany seeking mobility-preserving alternatives to fusion.
- Spinal Stenosis:Devices for spinal stenosis aim to alleviate nerve compression caused by the narrowing of the spinal canal, often through dynamic stabilization. Demand is increasing among younger, active patients treated in specialized orthopedic centers.
- Herniated Disc:This application focuses on treating conditions where the intervertebral disc material protrudes, causing nerve irritation and pain.
- Spondylolisthesis:Devices for spondylolisthesis address the forward slippage of one vertebra over another, aiming to restore spinal alignment and stability.
Degenerative Disc Disease applications account for the largest revenue, with spinal stenosis treatments expanding most quickly.
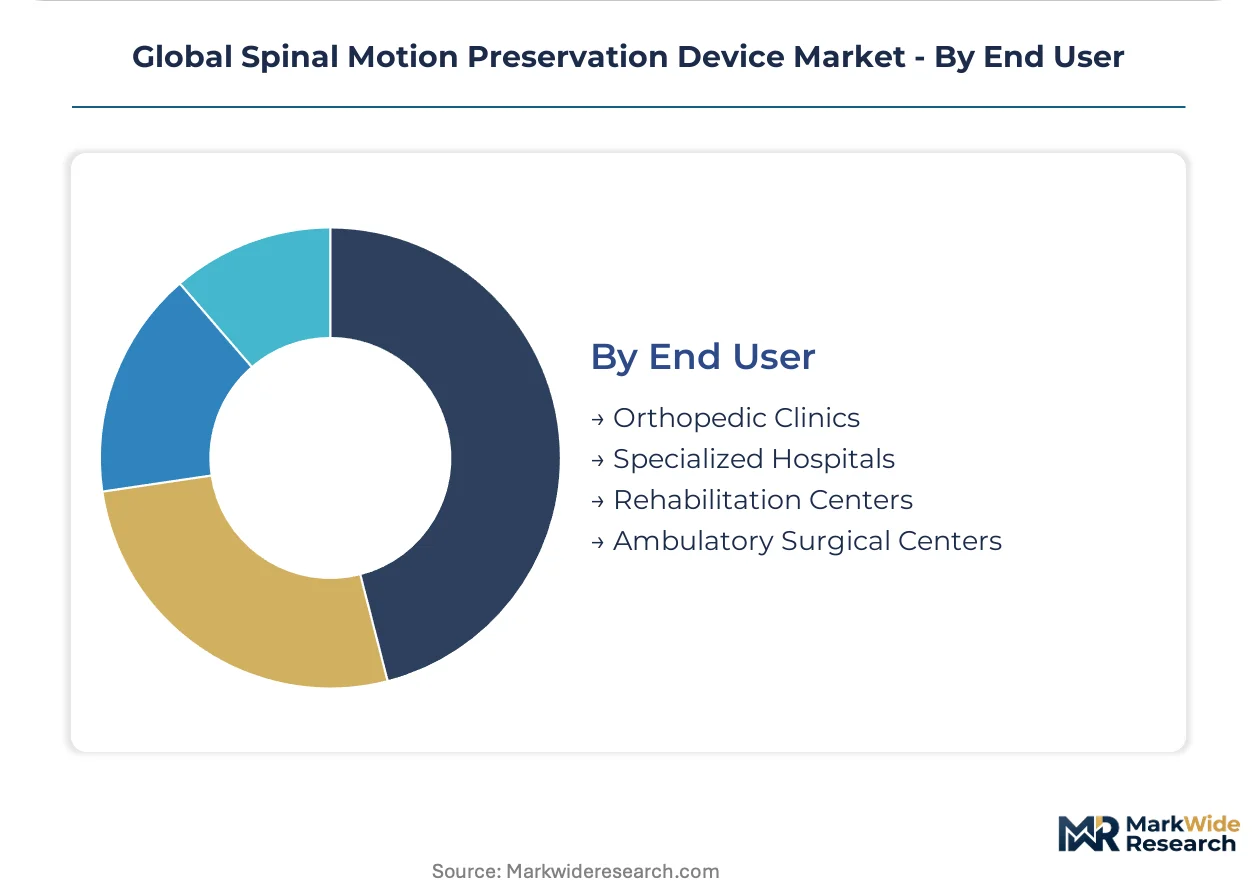
End User:
The care setting for spinal procedures is undergoing a significant procedural migration, influencing end-user demand for motion preservation devices.
- Specialized Hospitals:These facilities offer comprehensive surgical capabilities, advanced imaging, and post-operative care for complex spinal conditions. Demand originates from high-acuity cases and the initial adoption of innovative spinal technologies requiring extensive support.
- Ambulatory Surgical Centers:ASCs specialize in outpatient, minimally invasive procedures, driven by payer incentives for cost-effective care and patient preference for shorter stays. Demand for optimized devices is particularly strong in the United States, influencing product design for efficiency.
- Orthopedic Clinics:These clinics primarily handle initial patient consultations, non-surgical management, and long-term post-operative follow-up for spinal conditions.
- Rehabilitation Centers:Rehabilitation centers provide crucial post-surgical physical therapy and functional restoration programs, supporting patient recovery after spinal motion preservation procedures.
Specialized hospitals continue to lead procedural volume, while ambulatory surgical centers exhibit the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for spinal motion preservation devices concentrates in specific geographies, driven by an aging population and favorable reimbursement. Specialized orthopedic centers in developed economies lead in adoption and procedural volume. This regional focus shapes market access strategies and product development.
United States
An aging, active population in the United States drives demand for mobility-preserving spinal solutions. Favorable reimbursement policies for artificial disc replacement expand patient access. The US Food and Drug Administration (FDA) sets stringent pre-market approval pathways. Major metropolitan areas like New York and Los Angeles host numerous specialized orthopedic centers.
Germany
Germany exhibits strong demand for spinal motion preservation devices from its aging, active population. The European Union's Medical Device Regulation (MDR) dictates rigorous clinical evidence requirements. Favorable national health insurance policies support advanced medical technologies. Innovation clusters in Munich and Berlin contribute to polymer-based implant development.
South Korea
South Korea presents opportunities due to rising healthcare spending and emphasis on patient outcomes. The Ministry of Food and Drug Safety (MFDS) streamlines regulatory pathways for innovative devices. National health insurance coverage is expanding for advanced spinal procedures. Medical technology parks near Seoul actively develop polymer-based solutions.
Australia
Australia's healthcare system supports advanced spinal motion preservation device adoption. The Therapeutic Goods Administration (TGA) provides clear regulatory guidance for market entry. Public and private health insurance schemes often cover innovative surgical interventions. Major medical centers in Sydney and Melbourne participate in clinical trials for new implants.
China
China's vast patient population and healthcare modernization drive demand for advanced spinal treatments. The National Medical Products Administration (NMPA) regulates medical device approvals. Government policies encourage domestic innovation and local production of high-tech medical devices. Manufacturing centers in Shanghai and Shenzhen are significant for implant production.
Global Spinal Motion Preservation Device Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the global spinal motion preservation device market. The market structure favors large, diversified medical device companies alongside specialized innovators. Strategic archetypes include established players leveraging extensive distribution and agile firms focusing on rapid technological advancements. Companies pursue portfolio diversification and strategic partnerships to maintain competitive advantage.
Within the established medical device archetype, Medtronic plc leverages its extensive distribution network for next-generation polymer-based devices. Globus Medical occupies a position of rapid innovation, particularly in expandable cage technology and robotic-assisted surgical platforms. Zimmer Biomet Holdings anchors a strong market presence through its comprehensive portfolio of both fusion and non-fusion spinal solutions. These large entities exemplify the strategic imperative to offer broad solutions across various spinal pathologies.
| Leading Market Players |
|---|
| Medtronic plc |
| Zimmer Biomet Holdings |
| Stryker Corporation |
| Globus Medical |
| NuVasive |
| Johnson & Johnson (DePuy Synthes) |
| Orthofix Medical Inc. |
| Centinel Spine |
| B. Braun Melsungen AG |
| Others |
Cost & Logistics Intelligence
Ambulatory surgical centers and specialized orthopedic centers increasingly influence pricing models, emphasizing value-based outcomes and cost-effectiveness for spinal motion preservation devices. This buyer concentration drives demand for optimized device designs and efficient supply.
Pricing Analysis
Volume-driven segments like artificial disc replacement face margin pressure, while dynamic stabilization systems command premium pricing for specialized indications. Pricing stratifies across premium, standard, and economy tiers based on clinical data validity and device durability. Payer incentives for cost-effective care intensify downward pricing pressure in outpatient settings. Specialized hospitals for complex cases exhibit less price sensitivity than ambulatory surgical centers.
Supply Chain Analysis
PEEK polymer supply for advanced devices primarily draws from specialized chemical manufacturers in Germany and the United States, while titanium alloy production centers in the US and China. Raw material dependencies include medical-grade polymers and specialized metal alloys. Regulatory restrictions on new material approvals pose a structural supply chain risk. Distribution runs through extensive direct sales forces and specialized orthopedic distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global spinal motion preservation device market represents a consolidation play, as stringent regulatory scrutiny and escalating clinical trial costs increasingly force smaller, undercapitalized players out. Larger entities with robust portfolios can leverage economies of scale.
For Market Incumbents:
To counter the threat of prolonged regulatory approval timelines, incumbents must deepen investment in long-term clinical data generation for existing and next-generation devices. Portfolio diversification into both fusion and non-fusion solutions strengthens market presence against emerging technologies. Leveraging extensive distribution networks can accelerate market penetration for polymer-based innovations.
For New Entrants and Emerging Players:
Capture white space by focusing on niche applications like adjacent segment disease or specific geographies like South Korea and Australia. Dynamic stabilization systems for younger, active patients offer a penetrable segment due to demand for mobility preservation. Go-to-market strategies should emphasize polymer-based material advantages and integrated digital health solutions.
For Investors and Strategic Acquirers:
The window for entry favors strategic acquirers seeking specialized innovators in advanced materials or digital integration. Long-term viability hinges on companies demonstrating superior patient outcomes and device durability over extended periods. Accelerated regulatory approvals for next-generation devices serve as a critical inflection indicator for investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in PEEK Polymer R&D | Enhances device flexibility and radiolucency, displacing traditional titanium alloys in specific indications. |
| Secure FDA/MDR Pre-Market Approvals | Ensures market access for innovative spinal motion preservation devices, validating clinical safety and efficacy. |
| Expand into Ambulatory Surgical Centers | Aligns with payer incentives for cost-effective care, optimizing device design for outpatient efficiency. |
| Develop Integrated Smart Sensor Implants | Enables data-driven post-operative monitoring, offering personalized care and improving patient outcomes. |
| Conduct Multi-Center Clinical Trials | Generates long-term evidence of device durability, crucial for payer acceptance and regulatory compliance. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for market sizing and trend identification. Primary research involved in-depth interviews with orthopedic surgeons, hospital procurement managers, medical device engineers, and regulatory specialists. This approach ensured robust bottom-up and top-down triangulation of market data.
Market granularity was modeled across product type, technology, application, end user, and key geographic regions. The analytical framework projected market dynamics across the projection horizon, with CAGRs derived from historical growth trends and anticipated shifts in patient demographics. Key forecast inputs included aging population trends and evolving reimbursement policy landscapes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory shifts and clinical trial outcomes. These projections reflect assumptions regarding material science breakthroughs and evolving payer acceptance. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Oxygen Sensors Market
Medical Devices
Global Cardiopulmonary Resuscitation Device Market
Medical Devices
Global MRI Safe Cardiac Resynchronization Therapy Device Market
Medical Devices
Neurosurgical Products Market
Medical Devices
Tourniquet Systems Market
Medical Devices
Medical Device Coating Market
Medical Devices
Minimally Invasive Spine Technologies Market
Medical Devices
Canada Digital X-Ray Devices Market
Medical Devices
Global Digital Dentistry Devices Market
Medical Devices
Partial Ossicular Replacement Prosthesis Market
Medical Devices
MRI Safe Neurostimulation Systems Market
Medical Devices
Global Spirometers Market
Medical Devices
Electric Breast Pumps Market
Medical Devices
Ultrasound Skin Tightening Devices Market
Medical Devices
Transcutaneous Oximetry Systems Market
Medical Devices
Digital BTE Market