
 Tourniquet Systems Market | 2026-2036
Tourniquet Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Tourniquet Systems Market Outlook
Preventive maintenance contracts for pneumatic tourniquet systems is hardening into a standard revenue layer alongside equipment sales. Stryker Corporation leverages its installed base in orthopedic surgery suites to attach multi-year service agreements. Zimmer Biomet Holdings Inc anchors its position through direct hospital supply chain relationships that bundle calibration and replacement schedules.
A tourniquet system is a pressure-controlled medical device that temporarily occludes arterial blood flow to a limb, typically employing pneumatic cuffs with microprocessor-regulated inflation between 50 and 600 mmHg for surgical hemostasis or emergency hemorrhage control. Pneumatic tourniquets dominate hospital procurement due to precise pressure modulation and integrated safety timers, while automated tourniquets represent the fastest-expanding category as algorithms reduce operator error in high-stress environments. Emergency services channel demand skews toward portable, battery-powered configurations with rapid-deployment cuffs, whereas military end users prioritize ruggedized units with extended operational temperature ranges.
The FDA's 510(k) pathway and the EU Medical Device Regulation (MDR) impose divergent clinical evidence requirements that fragment product development roadmaps for multinational manufacturers. ISO 13485 quality management certification functions as a baseline market access filter, with notified body audits intensifying scrutiny of software-controlled inflation algorithms. Stakeholders must monitor evolving battlefield trauma protocols from NATO medical directorates and civilian Stop the Bleed campaign expansions, as these dual demand streams reshape product specification priorities without converging on unified standards.
Market Dynamics
The tourniquet systems market is experiencing a fundamental reorientation as dual-use procurement—military battlefield trauma protocols and civilian Stop the Bleed campaigns—forces manufacturers to engineer single platforms satisfying divergent performance specifications without product line bifurcation.
Growth Catalysts
- Bundeswehr Modernization:Germany's military procurement programs are expanding inventory requirements for battlefield trauma kits, creating sustained demand for ruggedized pneumatic systems with extended temperature tolerances.
- FDA 510(k) Pathway Tightening:Updated Class II device guidance for pneumatic tourniquets is elevating validation barriers, advantaging incumbent manufacturers with established quality management systems and clinical evidence portfolios.
- Orthopedic Surgery Volume:Rising procedural counts in ambulatory surgery centers are driving replacement cycles for legacy tourniquet systems, particularly microprocessor-regulated units with integrated safety timers.
Market Restraints
- Silicone Cuff Material Volatility:Specialized elastomer supply chains concentrated in Southeast Asia expose manufacturers to input cost swings and logistics disruptions.
- EU MDR Clinical Evidence Burden:Divergent requirements from FDA 510(k) pathways force parallel development tracks, extending time-to-market and inflating regulatory compliance expenditures for multinational firms.
- Mechanical Tourniquet Substitution:Windlass-style combat application tourniquets retain cost advantages in mass-casualty stockpiling scenarios, limiting premium pneumatic system penetration in price-sensitive procurement channels.
Strategic Opportunities
- India Emergency Response Infrastructure:Underpenetrated civilian trauma care networks present white space for portable battery-powered configurations aligned with national highway accident reduction mandates.
- AI-Enabled Pressure Algorithms:Convergence of machine learning with pneumatic inflation control enables real-time tissue perfusion monitoring, differentiating next-generation systems in high-stress military and emergency medicine environments.
- Direct Hospital Supply Contracts:Bypassing traditional distributor networks through calibration-bundled service agreements captures recurring revenue streams and locks out competing vendors from installed bases.
Industry Challenges
- Software Validation Expertise Scarcity:ISO 13485-compliant firmware development for inflation algorithms requires specialized talent pools concentrated in medical device hubs, constraining R&D velocity for mid-tier manufacturers.
- Legacy System Integration Friction:Replacement of analog tourniquet systems in established surgical suites demands costly operating room workflow reconfiguration and staff retraining programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tourniquet Systems Market |
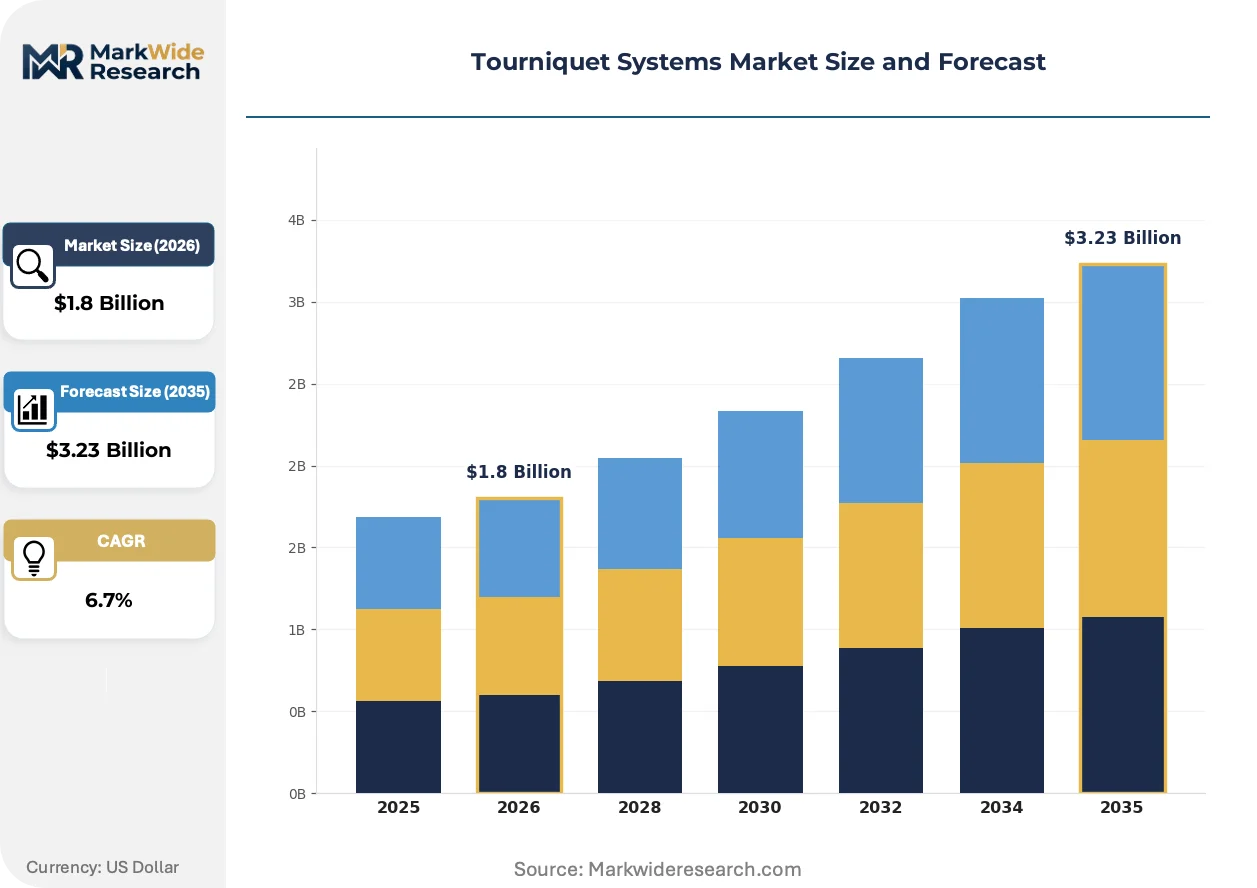
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastic Tourniquets, Pneumatic Tourniquets, Automated Tourniquets, Magnetic Tourniquets End User: Hospitals, Clinics, Emergency Services, Military Application: Trauma Care, Surgical Procedures, Blood Management, Sports Medicine Distribution Channel: Direct Sales, Online Retail, Medical Distributors, Hospital Supply Chains |
| Companies Covered | Delfi Medical Innovations Inc, Zimmer Biomet Holdings Inc, Stryker Corporation, Hammarplast Medical AB, AneticAid Ltd, VBM Medizintechnik GmbH, Ulrich Medical, OHK Medical Devices, Dessillons & Dutrillaux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tourniquet Systems Market Strategic Shifts
Algorithmic automation is overtaking manual pressure regulation as the defining technical frontier, compressing operator error margins while simultaneously elevating hardware complexity and software validation burdens across the value chain.
Automated tourniquet systems with closed-loop pressure modulation is overtaking conventional pneumatic units in emergency medicine procurement. Military medical directorates and civilian air ambulance operators are accelerating adoption of these systems for hemorrhage control scenarios where operator cognitive load peaks. This shift is overtaking the historical dominance of manual inflation devices, forcing established manufacturers to reallocate R&D resources toward embedded sensor integration and real-time feedback architectures.
EU Medical Device Regulation (MDR) post-market surveillance requirements are intensifying clinical follow-up obligations for software-controlled tourniquet systems. Manufacturers must now maintain systematic procedures for capturing and evaluating field performance data, particularly for inflation algorithm failures. Class IIa device reclassification pressures are concentrating compliance investments among firms with established notified body relationships, disadvantaging newer market entrants lacking legacy technical documentation.
After-sales service unbundling is fragmenting traditional equipment-only purchasing models in hospital procurement. Surgical suites now separately negotiate calibration contracts, replacement cuff schedules, and software update subscriptions, eroding the integrated pricing power of original equipment manufacturers. This behavioral shift is most pronounced in German and Austrian hospital networks, where centralized purchasing cooperatives actively disaggregate lifecycle costs across multi-year vendor agreements.
Tourniquet Systems Market Segmentation
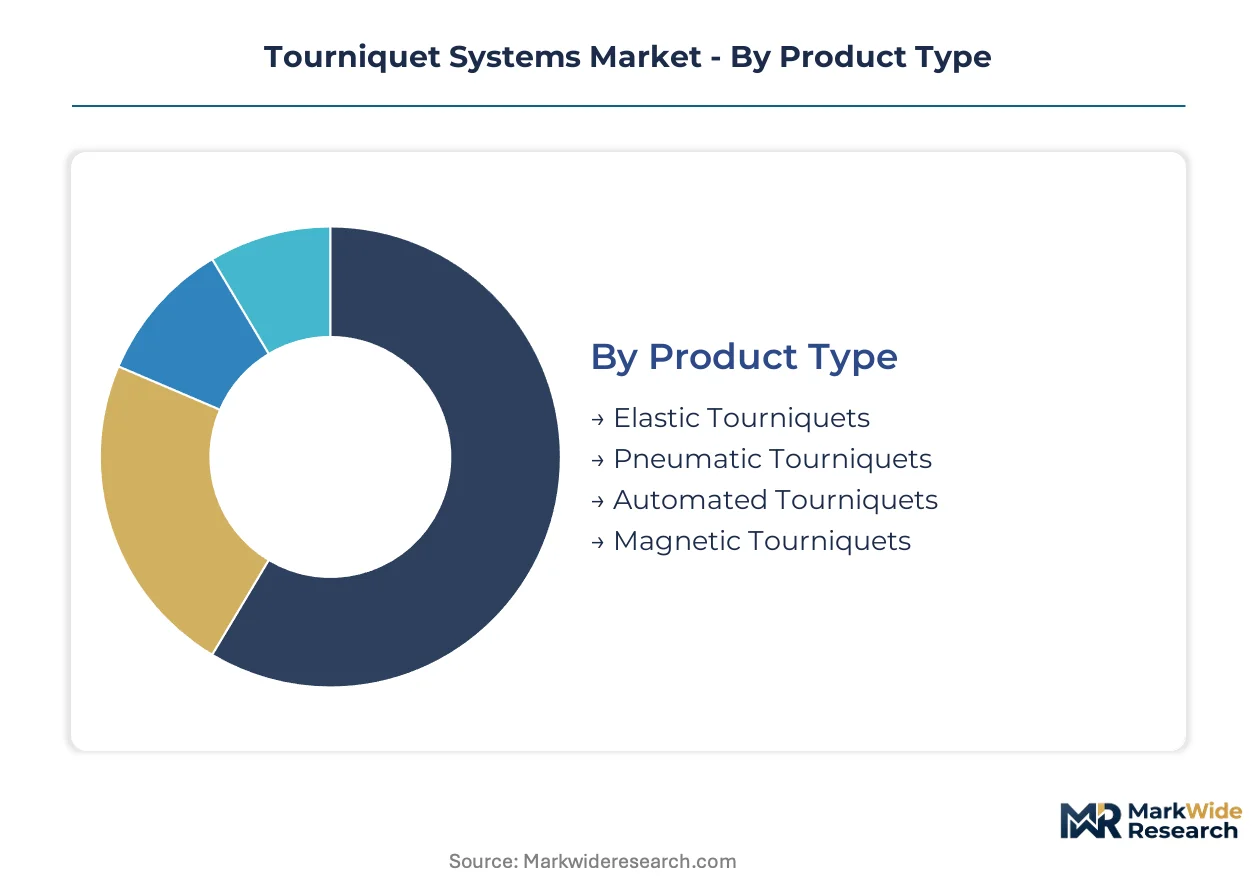
Tourniquet system procurement patterns diverge sharply across clinical environments, with surgical suites favoring precision-regulated pneumatic platforms while battlefield and emergency contexts drive demand for ruggedized automated alternatives. Segmentation clarity enables manufacturers to align R&D resource allocation with replacement-cycle timing and regulatory pathway requirements.
Product Type:
Replacement cycles for legacy pneumatic systems are shortening as microprocessor-controlled alternatives demonstrate superior pressure accuracy and integrated safety protocols.
- Pneumatic Tourniquets:Microprocessor-regulated inflation between 50 and 600 mmHg dominates orthopedic surgery suites through precise pressure modulation and programmable safety timers. German hospital procurement cooperatives are consolidating specifications around ISO 13485-certified units with embedded calibration tracking.
- Automated Tourniquets:Closed-loop algorithms with real-time tissue perfusion monitoring are displacing manual inflation in military trauma kits and air ambulance configurations. NATO medical directorates are embedding these systems in next-generation battlefield trauma protocols.
- Elastic Tourniquets:Low-cost mechanical bands retain position in mass-casualty stockpiling and resource-constrained emergency departments.
- Magnetic Tourniquets:Emerging magnetic compression technology targets specialized vascular surgery applications requiring rapid release capabilities.
Volume placements concentrate in Pneumatic Tourniquets; the faster expansion belongs to Automated Tourniquets.
End User:
Customer procurement sophistication varies dramatically across institutional types, with direct hospital contracts commanding premium pricing while military tenders emphasize total lifecycle cost.
- Hospitals:Ambulatory surgery centers are accelerating replacement of analog systems with microprocessor-regulated platforms featuring integrated electronic health record connectivity. Stryker and Zimmer Biomet leverage installed base relationships to attach multi-year calibration service agreements.
- Military:Bundeswehr modernization programs and NATO battlefield trauma kit upgrades are driving dual-use specifications requiring extended temperature tolerance and electromagnetic interference hardening.
- Emergency Services:Fire departments and municipal ambulance authorities prioritize portable battery-powered configurations with rapid-deployment cuff mechanisms.
- Clinics:Outpatient orthopedic practices favor cost-optimized pneumatic units with simplified operator interfaces.
Revenue concentration sits with Hospitals; Military procurement is climbing the fastest.
Application:
Clinical evidence requirements diverge substantially across use cases, with surgical applications demanding FDA 510(k) clearance while trauma protocols follow NATO medical directorate specifications.
- Surgical Procedures:Orthopedic limb surgery represents the dominant revenue pool, with pressure precision and timer reliability determining procurement decisions in German and Austrian hospital networks.
- Trauma Care:Civilian Stop the Bleed campaign expansions and military battlefield protocols are converging on automated systems with algorithmic hemorrhage control. FDA Class II device guidance tightening is elevating validation barriers for new market entrants.
- Blood Management:Phlebotomy and donation center applications favor single-use disposable cuff configurations with standardized pressure profiles.
- Sports Medicine:Athletic training facilities and professional sports organizations are adopting portable tourniquet systems for on-field injury management.
Procedure volume anchors Surgical Procedures; Trauma Care is gaining share fastest.
Distribution Channel:
Channel strategy determines margin capture and customer lock-in effectiveness, with direct sales enabling service bundling while distributor relationships provide geographic coverage.
- Direct Sales:Original equipment manufacturers are bypassing traditional distributors to negotiate calibration-bundled multi-year agreements directly with German hospital purchasing cooperatives.
- Hospital Supply Chains:Centralized procurement in Austrian and German networks is disaggregating equipment, service, and consumable purchasing decisions across separate vendor negotiations.
- Medical Distributors:Regional distributors retain relevance in mid-tier hospital and clinic segments where procurement sophistication lags centralized purchasing cooperatives.
- Online Retail:E-commerce channels are penetrating emergency services and clinic segments with standardized product configurations and transparent pricing.
Contract value concentrates in Direct Sales; Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and the United States while procurement demand spreads across NATO member states and emerging trauma care networks. Supply chain proximity to medical device clusters shapes regional competitive positioning more than raw material access.
Germany
Bundeswehr modernization programs and civilian emergency response upgrades drive dual-use purchasing of pneumatic tourniquet systems. The EU Medical Device Regulation (MDR) imposes stringent post-market surveillance obligations on manufacturers operating in this market. Tuttlingen in Baden-Württemberg anchors precision medical device fabrication, with regional suppliers integrating ISO 13485-certified calibration services into equipment contracts.
United States
FDA Class II device guidance tightening elevates validation barriers for pneumatic tourniquet manufacturers seeking 510(k) clearance. Military procurement through Defense Logistics Agency channels prioritizes ruggedized automated systems for battlefield trauma kits. Minneapolis-St. Paul and Warsaw, Indiana host orthopedic surgery device clusters where Stryker and Zimmer Biomet maintain installed base relationships.
United Kingdom
NHS procurement frameworks emphasize total lifecycle cost in tourniquet system acquisitions for ambulatory surgery centers. The Medicines and Healthcare products Regulatory Agency (MHRA) enforces UKCA marking requirements post-Brexit, creating parallel conformity assessment tracks. Cambridge and Oxford medical technology corridors concentrate R&D activity for algorithmic pressure control systems.
France
ANSM oversight of Class IIa medical devices aligns with EU MDR implementation timelines for software-controlled tourniquet systems. Civilian Stop the Bleed campaign expansion drives municipal emergency services procurement of portable battery-powered configurations. Lyon and Paris-Saclay clusters specialize in sensor integration for real-time tissue perfusion monitoring.
India
National highway accident reduction mandates accelerate emergency response infrastructure investment in underpenetrated trauma care networks. CDSCO medical device registration requirements are tightening for imported pneumatic systems, favoring local assembly partnerships. Ahmedabad and Hyderabad medical device manufacturing zones attract contract production for standardized cuff configurations.
Tourniquet Systems Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the tourniquet systems value chain, with integrated manufacturers controlling cuff fabrication while specialized software firms supply inflation algorithms. The market exhibits tiered consolidation around orthopedic surgery suite incumbents and emerging automated system specialists. Three archetypes dominate: diversified orthopedic device conglomerates with installed base leverage; mid-scale pneumatic specialists with regional hospital supply chain relationships; and automated system innovators targeting military and air ambulance procurement channels. Competitive intensity centers on multi-year service agreement attachment rates and calibration-bundled contract structures.
Among North American-based conglomerates, Stryker Corporation and Zimmer Biomet Holdings Inc exemplify the installed-base archetype, leveraging direct hospital relationships to lock in recurring calibration revenue. European specialists including VBM Medizintechnik GmbH and Ulrich Medical occupy positions within the precision pneumatic tier, serving German and Austrian hospital purchasing cooperatives with ISO 13485-certified platforms. These entities represent contrasting strategic postures: scale-driven service bundling versus regional regulatory compliance specialization.
| Leading Market Players |
|---|
| Delfi Medical Innovations Inc |
| Zimmer Biomet Holdings Inc |
| Stryker Corporation |
| Hammarplast Medical AB |
| AneticAid Ltd |
| VBM Medizintechnik GmbH |
| Ulrich Medical |
| OHK Medical Devices |
| Dessillons & Dutrillaux |
| Others |
Value Chain & Pricing Dynamics
Bundeswehr modernization specifications for extended temperature tolerance and electromagnetic interference hardening are forcing specialty elastomer suppliers to retool production lines, compressing margins for pneumatic cuff manufacturers unable to pass through input costs.
Pricing Analysis
Margin tightening in the pneumatic tourniquet tier reflects ISO 13485 certification premiums and multi-year calibration bundling. Three-tier pricing structure across premium microprocessor-regulated, standard pneumatic, and economy mechanical levels separates Stryker and Zimmer Biomet's service-integrated contracts from regional specialists. Price differentiation hinges on FDA 510(k) clearance tier and after-sales service attachment. Cost-down pressure on mid-tier manufacturers accelerates because German hospital purchasing cooperatives disaggregate lifecycle costs across separate vendor negotiations. Military procurement channels exhibit lowest price sensitivity; outpatient orthopedic clinics face highest budget constraints.
Supply Chain Analysis
Specialized silicone elastomer supply rests on concentrated producers in Germany, Malaysia, and Thailand. Microprocessor-controlled inflation systems draw from semiconductor fabrication clusters in Taiwan and South Korea. Precision pneumatic valve assemblies source from Swiss and German medical device component specialists. Single-source vulnerability concentrates in Southeast Asian elastomer feedstock for cuff fabrication. Distribution runs through direct hospital supply contracts in German-speaking Europe, regional medical distributors in mid-tier segments, and Defense Logistics Agency channels for military procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as manufacturers pursue captive supply of ISO 13485-certified calibration services to lock hospital installed bases.
For Market Incumbents: Anticipate FDA 510(k) pathway tightening by accelerating clinical evidence portfolios for algorithmic inflation systems. Acquire regional pneumatic specialists in Tuttlingen to consolidate precision fabrication capabilities and deny mid-tier competitors supply chain access.
For New Entrants and Emerging Players: Enter via India's underpenetrated emergency response infrastructure, where CDSCO registration barriers favor local assembly partnerships over direct import. Target portable battery-powered configurations for municipal ambulance authorities with simplified operator interfaces and transparent online pricing.
For Investors and Strategic Acquirers: The window for entry favors automated tourniquet innovators with embedded sensor integration and NATO medical directorate relationships. Watch for EU MDR post-market surveillance obligations triggering consolidation among software-validation-constrained mid-tier manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Updated Class II device guidance elevates validation barriers for pneumatic inflation algorithms. |
| CE Marking Pathway | EU MDR post-market surveillance requirements intensify clinical follow-up obligations for software-controlled systems. |
| Hospital System Partnership | Direct contracts with German purchasing cooperatives enable calibration-bundled multi-year revenue locks. |
| Software Companion Development | AI-enabled pressure algorithms differentiate next-generation systems in military trauma protocols. |
| Reimbursement Strategy | Alignment with civilian Stop the Bleed campaign expansions shapes product specification priorities. |
Study Parameters
Independent corroboration across hospital purchasing committee interviews, biomedical engineer consultations, and GPO contracts manager surveys underwrites the qualitative findings. Primary fieldwork engaged orthopedic surgery suite directors, military medical procurement officers, and emergency services equipment coordinators across German, US, and Indian markets. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, and hospital procurement database extracts. Bottom-up unit economics triangulated against top-down macroeconomic anchors.
Comparable-period anchoring to replacement cycle timing in orthopedic surgery suites and military inventory refresh programs structured the forecast window across the analysis window. Segmentation dimensions modeled include product type tier, end-user institutional category, clinical application, and regional regulatory cluster. CAGRs derived from surgical procedure volume trajectories, NATO trauma kit modernization schedules, and emergency response infrastructure investment pipelines. Algorithmic adoption curves and elastomer input cost volatility informed scenario weighting.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR reclassification pressures and silicone supply chain disruptions. Forecasts reflect assumptions on regulatory pathway timelines and procurement budget continuity. A small set of triggers—FDA guidance enforcement intensity, Bundeswehr contract awards, and CDSCO localization mandates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Surgical Monitors Market
Medical Devices
Scoliosis Traction Chairs Market
Medical Devices
Pharmaceutical Filtration Devices Market
Medical Devices
Mexico Electrocardiograph (ECG) Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
Global Body Composition Analyzers Market
Medical Devices
Collateral Ligament Stabilizer System Market
Medical Devices
Respiratory Devices Market
Medical Devices
Gutta Percha Obturator Market
Medical Devices
Cervical Retractors Market
Medical Devices
Blood Collection Devices Market
Medical Devices
Cryosurgery Devices Market
Medical Devices
Aortic Cannula Systems Market
Medical Devices
Band Ligators Market
Medical Devices
Stethoscope Hygiene Devices Market
Medical Devices
Osteosynthesis Devices Market