
 Neurosurgical Products Market | 2026-2036
Neurosurgical Products Market Size, Share, and Industry Trends Forecast 2026-2036
Neurosurgical Products Market Outlook
Hospital procurement of neurosurgical platforms is fragmenting as ambulatory surgery centers and specialty clinics gain direct purchasing power. Medtronic plc leverages its integrated navigation and robotics portfolio to sustain channel control across tier-one hospitals. Stryker Corporation competes through specialized cranial and spinal instrument lines that anchor its presence in academic medical centers. Johnson & Johnson Services, Inc. differentiates via its broad neurovascular and electrophysiology reach, occupying multiple points along the patient care pathway.
Neurosurgical products encompass instruments, implants, and capital equipment engineered for procedures involving the brain, spinal cord, and peripheral nerves, typically manufactured from titanium alloys, cobalt-chrome, or biocompatible polymers with tolerances measured in micrometers. Their primary purpose is to enable precise tissue manipulation, visualization, and therapeutic delivery while minimizing iatrogenic injury in confined anatomical spaces. Surgical instruments remain the mature revenue base with compressed margins, while surgical robots capture expanding capital budgets as hospitals prioritize minimally invasive techniques that reduce length of stay. Neurostimulation devices represent the fastest-growing product category, with deep brain and spinal cord applications drawing disproportionate R&D investment from device manufacturers seeking indication expansion.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines and clinical evidence requirements for neurosurgical device manufacturers seeking market access. The EPA and OSHA additionally govern sterilization process emissions and operating room occupational exposure limits that affect instrument reprocessing economics. Stakeholders must monitor how reimbursement policy for robotic-assisted procedures evolves relative to conventional surgery, as this will determine capital deployment speed across hospital systems and ambulatory settings.
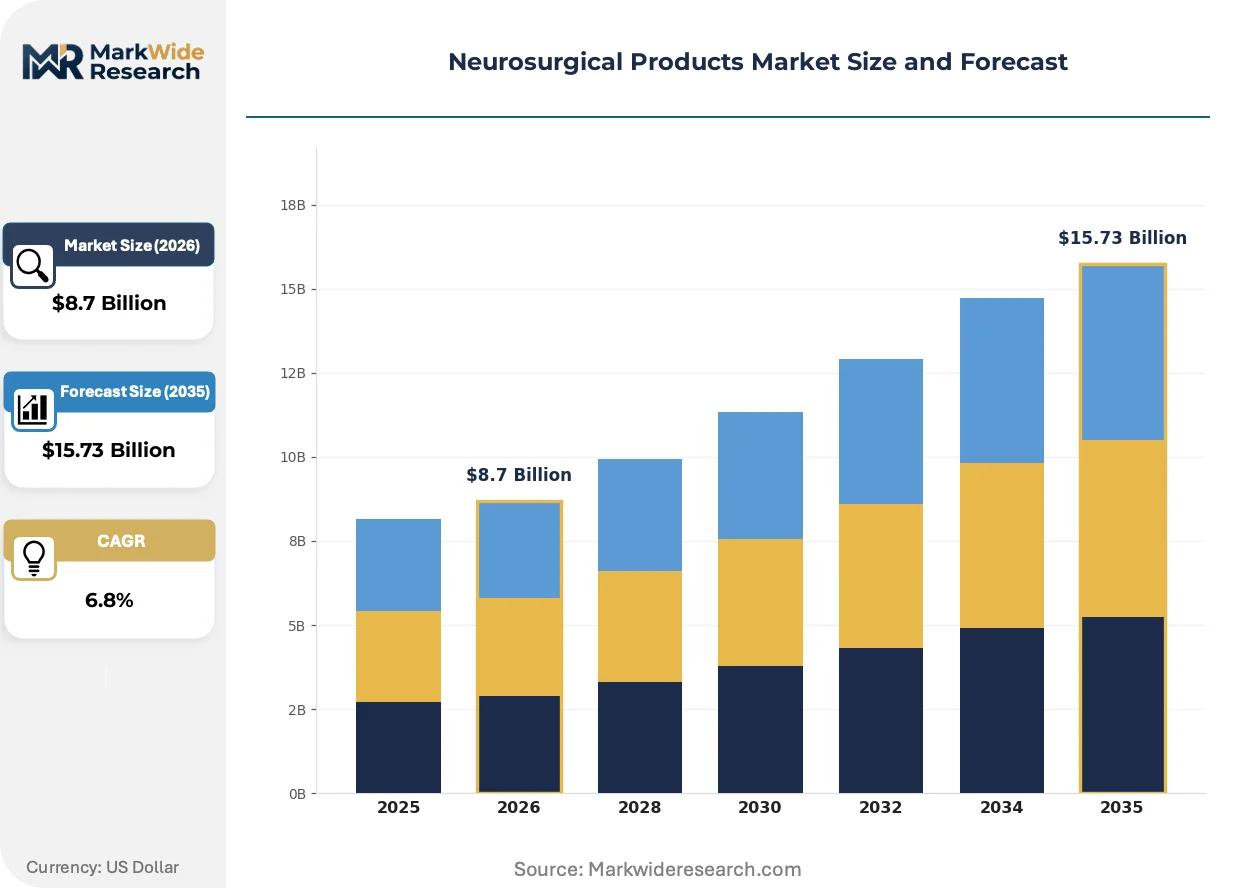
Market Dynamics
Robotic-assisted neurosurgical platforms are compressing procedure times and redefining capital allocation priorities across hospital systems, forcing traditional instrument manufacturers to defend instrument attach rates against integrated system vendors.
Growth Catalysts
- FDA 510(k) pathway refinement:Streamlined premarket notification for Class II neurostimulation devices accelerates commercialization timelines for deep brain stimulation systems targeting movement disorders.
- Ambulatory surgery center expansion:Freestanding neurological procedure facilities in Texas and Florida are procuring compact navigation systems previously confined to academic medical centers.
- Titanium alloy biocompatibility advances:Micrometer-tolerance machining of cobalt-chrome spinal implants enables longer fatigue life in dynamic stabilization constructs.
Market Restraints
- Capital intensity concentration:Single-source dependency on German and Japanese precision optics suppliers creates procurement vulnerability for stereotactic navigation hardware.
- EU MDR technical documentation burden:Expanded clinical evidence requirements for neurovascular stent retrievers extend conformity assessment timelines by 18-24 months for mid-tier manufacturers.
- Polymer raw material volatility:Medical-grade PEEK resin prices fluctuate with aerospace demand cycles, compressing margins on interbody fusion cages.
Strategic Opportunities
- Peripheral nerve stimulation underpenetration:Chronic migraine and cluster headache indications in France and Spain remain below 15% addressable patient penetration.
- AI-enabled surgical planning convergence:Machine learning segmentation of preoperative MRI fused with intraoperative ultrasound creates differentiated workflow value.
- Direct-to-physician distribution:Specialized cranial instrument vendors bypass hospital supply chain committees through surgeon preference item programs.
Industry Challenges
- Robotics integration complexity:Legacy navigation systems require proprietary software bridges to communicate with third-party surgical arms, delaying OR deployment.
- Neurophysiology monitoring certification gaps:Intraoperative neuromonitoring technologist shortages in Midwestern US markets constrain case throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurosurgical Products Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
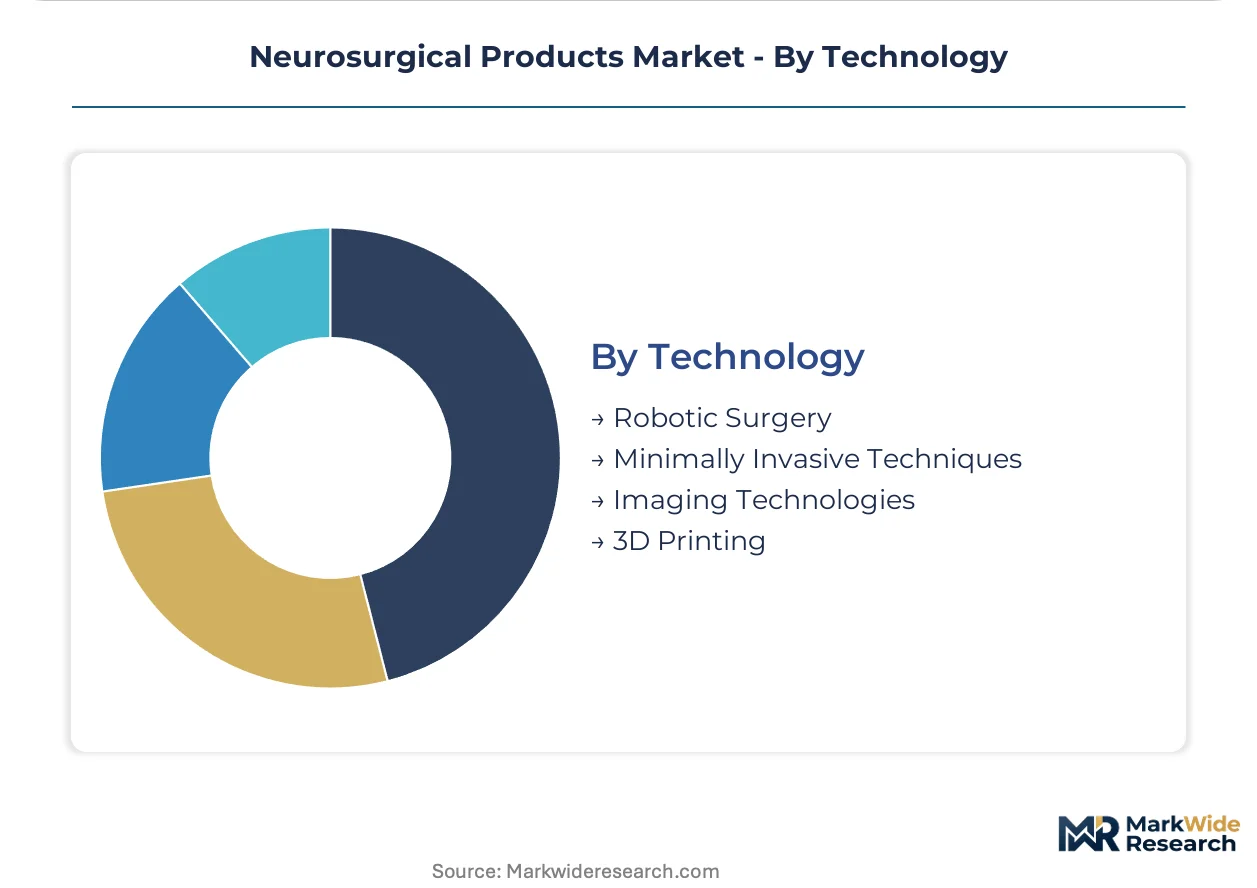
| Segmentation | Product Type: Surgical Instruments, Neurostimulation Devices, Navigation Systems, Surgical Robots Application: Brain Surgery, Spinal Surgery, Peripheral Nerve Surgery, Trauma Cases End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Research Institutions Technology: Robotic Surgery, Minimally Invasive Techniques, Imaging Technologies, 3D Printing |
| Companies Covered | Medtronic plc, Stryker Corporation, Integra LifeSciences Holdings Corporation, Johnson & Johnson Services, Inc., B. Braun Melsungen AG, KARL STORZ GmbH & Co. KG, Elekta AB, Penumbra, Inc., Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurosurgical Products Market Strategic Shifts
Digital surgical ecosystems are collapsing the boundaries between preoperative planning, intraoperative execution, and postoperative monitoring into continuous data loops that reshape vendor value propositions.
High-definition exoscopic visualization is collapsing the optical path between surgeon and operative field, eliminating the ergonomic constraints of traditional binocular microscopes. Academic medical centers in Germany and Japan are retrofitting existing cranial suites with 4K-3D exoscope towers at replacement cycles compressed to 4-5 years. This compression is collapsing the attach rate for disposable microscopic drapes and forcing instrument manufacturers to redesign retractor systems for exoscope working distances.
EU MDR Article 10 post-market surveillance requirements are mandating systematic implant registries for neurostimulation leads, compelling manufacturers to fund longitudinal outcome tracking infrastructure. The industrial consequence is a bifurcation between firms with existing health economics capabilities and those facing compliance-driven margin erosion. Spinal cord stimulation systems for chronic pain are experiencing the most acute documentation burden, with notified bodies demanding 5-year follow-up data for legacy device families.
Hospital value analysis committees are unbundling robotic-assisted procedure reimbursement from capital equipment procurement, forcing vendors to demonstrate standalone clinical utility independent of payer coverage decisions. Integrated delivery networks in California and New York are piloting per-procedure leasing models that transfer utilization risk to manufacturers. This behavioral shift is most visible in tier-one hospitals where neurosurgery service line margins face heightened scrutiny from system-level CFOs.
Neurosurgical Products Market Segmentation
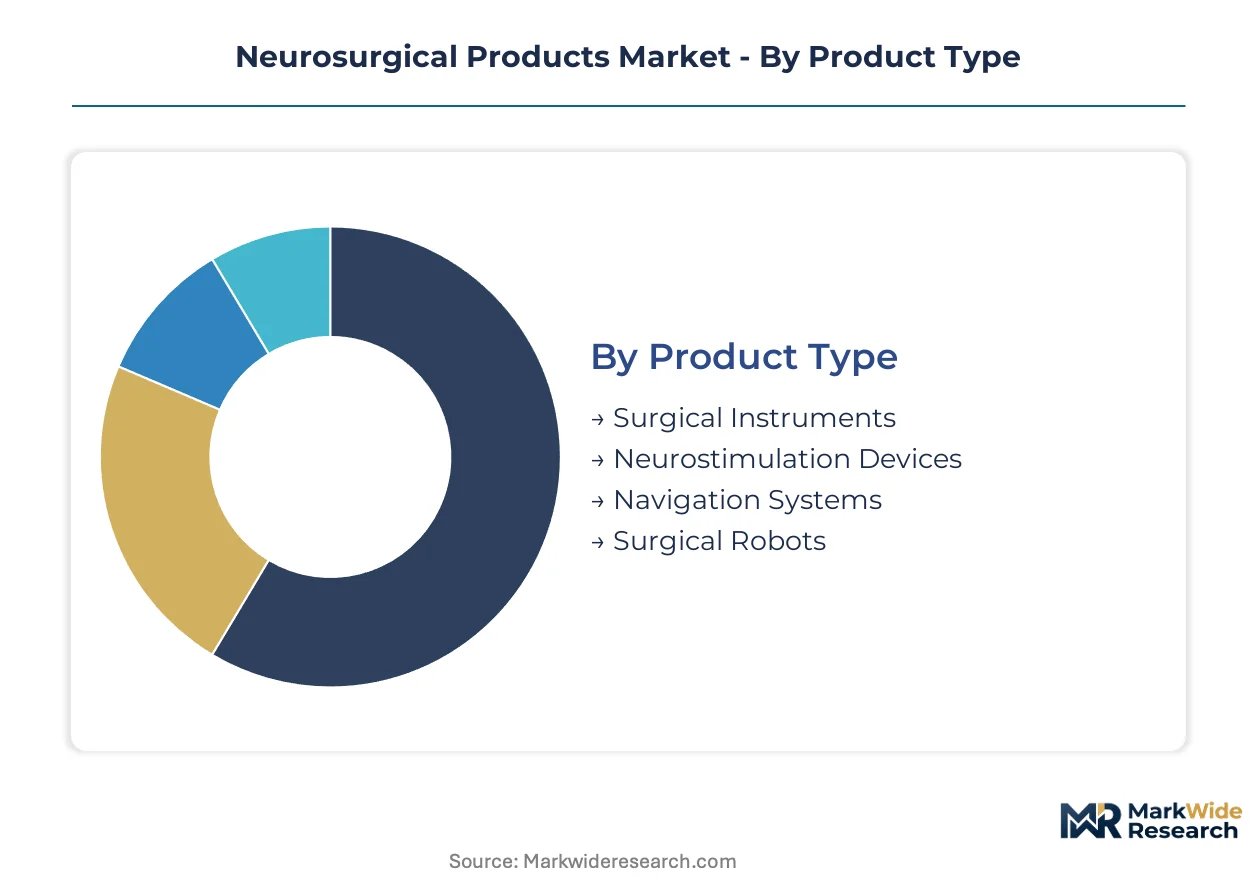
Neurosurgical products fragment across four intersecting dimensions that determine procurement behavior and margin structure. Product type separates capital-intensive platforms from consumable instruments, while application and end-user dynamics dictate regulatory pathways and reimbursement complexity. Technology tier increasingly governs hospital capital allocation priorities.
Product Type:
Mature instrument lines anchor hospital purchasing contracts, while emerging robotic platforms capture expanding capital budgets through minimally invasive value propositions.
- Surgical Instruments:Titanium alloy and cobalt-chrome cranial and spinal tools manufactured to micrometer tolerances enable precise tissue manipulation. Academic medical centers in Germany and Japan drive replacement cycles for high-speed drills and microdissection instruments as OR throughput demands intensify.
- Neurostimulation Devices:Implantable pulse generators and leads targeting deep brain and spinal cord applications deliver electrical modulation for movement disorders and chronic pain. FDA 510(k) pathway refinements for Class II devices are accelerating commercialization timelines for systems addressing Parkinson's disease and epilepsy.
- Navigation Systems:Optical and electromagnetic tracking platforms integrate preoperative imaging with intraoperative instrument localization. Stereotactic hardware procurement concentrates in tier-one hospitals expanding neurosurgical suites.
- Surgical Robots:Articulated arm platforms with haptic feedback enable submillimeter precision in confined anatomical spaces. Ambulatory surgery centers in Texas and Florida are piloting compact configurations previously confined to academic settings.
Surgical instruments handle the majority of throughput; surgical robots are expanding most quickly on share.
Application:
Procedure complexity spans from elective cranial interventions to emergent trauma stabilization, with reimbursement intensity varying across the spectrum.
- Brain Surgery:Craniotomy, tumor resection, and functional procedures demand navigation-integrated visualization and microinstrument precision. Deep brain stimulation for movement disorders is driving neurostimulation device attachment in tertiary hospitals.
- Spinal Surgery:Decompression, fusion, and dynamic stabilization procedures consume the highest implant volumes. PEEK interbody cages and pedicle screw systems face margin pressure from polymer raw material volatility tied to aerospace demand cycles.
- Peripheral Nerve Surgery:Nerve repair, grafting, and decompression procedures utilize specialized microsurgical instruments. Chronic migraine and cluster headache indications in France and Spain remain below 15% addressable penetration.
- Trauma Cases:Emergent craniotomy and spinal stabilization require rapid instrument availability and sterilization turnaround. Level I trauma centers prioritize instrument standardization across neurosurgery and orthopedic service lines.
Spinal surgery generates the highest implant revenue concentration; peripheral nerve surgery is gaining share fastest through indication expansion.
End User:
Procurement authority is fragmenting as ambulatory settings gain direct purchasing power outside traditional hospital supply chain committees.
- Hospitals:Integrated delivery networks in California and New York are unbundling robotic-assisted procedure reimbursement from capital equipment procurement. Value analysis committees now demand standalone clinical utility demonstrations independent of payer coverage decisions.
- Ambulatory Surgery Centers:Freestanding neurological procedure facilities are acquiring compact navigation systems and specialized instrument sets. Surgeon preference item programs enable direct-to-physician distribution bypassing traditional procurement channels.
- Specialty Clinics:Dedicated pain management and movement disorder centers focus on neurostimulation programming and device optimization. Post-implant follow-up services create recurring revenue attachment.
- Research Institutions:Academic medical centers drive early adoption of AI-enabled surgical planning and exoscopic visualization. EU MDR Article 10 post-market surveillance requirements are mandating systematic implant registries that leverage institutional data infrastructure.
Hospitals retain the dominant capital expenditure authority; ambulatory surgery centers are climbing the fastest on procurement volume.
Technology:
Digital convergence is collapsing boundaries between preoperative planning, intraoperative execution, and postoperative monitoring.
- Robotic Surgery:Haptic-enabled platforms with tremor filtration and motion scaling compress procedure times while reducing iatrogenic injury. Legacy navigation systems require proprietary software bridges to communicate with third-party surgical arms, delaying OR deployment.
- Minimally Invasive Techniques:Keyhole approaches through tubular retractors and endoscopic channels reduce length of stay and accelerate ambulatory eligibility. Reimbursement policy evolution relative to conventional open procedures determines capital deployment speed.
- Imaging Technologies:Intraoperative MRI, CT, and ultrasound fusion with navigation systems enable real-time anatomical verification. Machine learning segmentation of preoperative MRI combined with intraoperative ultrasound creates differentiated workflow value.
- 3D Printing:Patient-specific cranial implants and spinal interbody cages manufactured from titanium and PEEK enable anatomical customization. Medical-grade polymer feedstock costs fluctuate with industrial demand cycles, compressing margins on printed constructs.
Imaging technologies underpin the majority of navigation-integrated procedures; robotic surgery is gaining share fastest through capital budget prioritization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification requirements for Class II neurostimulation devices anchor the United States regulatory environment, while Germany, Japan, and the United States concentrate the bulk of navigation system procurement. Hospital procurement patterns vary substantially across these core markets.
United States
Integrated delivery networks in California and New York are unbundling robotic-assisted procedure reimbursement from capital equipment procurement. FDA 510(k) pathway refinements for Class II neurostimulation devices accelerate commercialization timelines for deep brain stimulation systems. Level I trauma centers in the Midwest prioritize instrument standardization across neurosurgery and orthopedic service lines.
Germany
Academic medical centers drive replacement cycles for high-speed drills and microdissection instruments as OR throughput demands intensify. EU MDR Article 10 post-market surveillance requirements mandate systematic implant registries for neurostimulation leads. The Baden-Württemberg and Bavaria clusters concentrate precision optics suppliers for stereotactic navigation hardware.
Japan
PMDA consultation procedures shape clinical evidence requirements for neurovascular device manufacturers seeking market access. METI industrial policy supports domestic production of medical-grade titanium alloys and cobalt-chrome alloys. The Kanto region around Tokyo anchors procurement of 4K-3D exoscope towers with compressed replacement cycles.
United Kingdom
NICE technology appraisals determine reimbursement eligibility for robotic-assisted neurosurgical procedures across NHS trusts. MHRA post-Brexit regulatory alignment with EU MDR extends conformity assessment timelines for mid-tier manufacturers. The Greater London and Southeast cluster concentrates private hospital investment in navigation-integrated visualization platforms.
India
CDSCO medical device rules classify neurostimulation systems as Class C devices requiring import license scrutiny and local clinical investigation. Government medical colleges in Maharashtra and Karnataka expand neurosurgical training programs with donated instrument sets. The Delhi-NCR corridor attracts distribution partnerships for compact navigation systems targeting tier-two hospital networks.
Neurosurgical Products Market Competitive Environment
Diversified conglomerates and specialized instrument houses split the market into distinct capability tiers. Consolidation pressure intensifies as robotic platform vendors capture capital budgets previously allocated to discrete instrument procurement. Three archetypes dominate: integrated navigation-robotics systems vendors, specialized cranial and spinal instrument manufacturers, and neurovascular-electrophysiology portfolio players. Competitive moves center on M&A for digital surgical planning capabilities and strategic partnerships for AI-enabled intraoperative imaging fusion.
Among diversified healthcare conglomerates, Medtronic plc and Johnson & Johnson Services, Inc. occupy positions spanning multiple points along the neurosurgical patient care pathway. Stryker Corporation exemplifies the specialized instrument house archetype with concentrated presence in academic medical centers. These three entities represent the scale-driven tier where channel control across tier-one hospitals determines competitive positioning.
| Leading Market Players |
|---|
| Medtronic plc |
| Stryker Corporation |
| Integra LifeSciences Holdings Corporation |
| Johnson & Johnson Services, Inc. |
| B. Braun Melsungen AG |
| KARL STORZ GmbH & Co. KG |
| Elekta AB |
| Penumbra, Inc. |
| Terumo Corporation |
| Others |
Value Chain & Pricing Dynamics
The Baden-Württemberg precision optics cluster anchors global stereotactic navigation hardware capacity, with micrometer-tolerance machining constraints translating directly into pricing power for German and Japanese suppliers serving tier-one hospital systems.
Pricing Analysis
Price spreads between German-manufactured navigation platforms and Asian-assembled alternatives span three certification tiers tied to FDA 510(k) pathway completion and EU MDR conformity depth. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center procurement from ambulatory surgery center budgets. Cost compression in spinal implant lines is intensifying because medical-grade PEEK resin tracks aerospace demand cycles. Ambulatory surgery centers exhibit highest price sensitivity; integrated delivery networks in California and New York demonstrate lowest sensitivity due to unbundled reimbursement pilots.
Supply Chain Analysis
Extended payment terms from tier-one hospital systems now stretch to 120 days, forcing mid-tier instrument manufacturers into supply-chain finance facilities to bridge working capital gaps. Component sourcing concentrates in Germany, Japan, and the United States for precision optics and micrometer-tolerance alloys. Manufacturing draws from titanium alloy feedstock, cobalt-chrome bar stock, and medical-grade polymer resin. Single-source vulnerability in German precision optics creates procurement risk for stereotactic hardware. Distribution runs through integrated delivery network value analysis committees and direct-to-physician surgeon preference programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neurosurgical product vendors increasingly monetize through recurring service layers—implant programming, device optimization, and longitudinal outcome tracking—that expand faster than capital equipment sales.
For Market Incumbents: Harden software companion capabilities around AI-enabled surgical planning to defend attach rates against robotic platform vendors capturing capital budgets. Deepen backward integration into titanium alloy feedstock to buffer PEEK resin volatility compressing spinal implant margins. Prioritize EU MDR Article 10 compliance infrastructure to maintain channel access as notified bodies demand extended follow-up data.
For New Entrants and Emerging Players: Build out peripheral nerve stimulation portfolios targeting chronic migraine and cluster headache indications in France and Spain where addressable penetration sits below fifteen percent. Compact navigation systems for ambulatory surgery centers in Texas and Florida offer the most penetrable entry point. Pursue direct-to-physician distribution through surgeon preference item programs bypassing hospital supply chain committees.
For Investors and Strategic Acquirers: Long-term, this sits as a health economics capability play because EU MDR post-market surveillance requirements and US reimbursement unbundling trends favor vendors with longitudinal outcome infrastructure. Target acquisition profiles center on AI-enabled surgical planning specialists and implant registry data platforms. Monitor FDA 510(k) pathway refinement announcements for deep brain stimulation systems as inflection indicators for neurostimulation device commercialization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined premarket notification accelerates Class II neurostimulation device commercialization timelines. |
| CE Marking Pathway | EU MDR conformity assessment completion secures access to German academic medical center procurement channels. |
| Hospital System Partnership | Integrated delivery network pilots unbundle robotic-assisted procedure reimbursement from capital equipment procurement. |
| Software Companion Development | Machine learning segmentation of preoperative MRI creates differentiated workflow value in navigation-integrated suites. |
| Reimbursement Strategy | Standalone clinical utility demonstration independent of payer coverage decisions determines ambulatory surgery center capital deployment. |
Study Parameters
Desk research of FDA 510(k) clearance databases, EU MDR notified body documentation, hospital procurement contract filings, and GPO pricing agreements preceded structured interviews with neurosurgical device product managers, hospital biomedical engineers, GPO contracts managers, and intraoperative neuromonitoring technologists. Secondary validation drew from SEC 10-K disclosures, CMS Medicare reimbursement data, and trade customs records. Bottom-up unit economics triangulated against top-down market sizing across product type, application, end user, and technology tier dimensions.
Assumptions around FDA premarket notification pathway stability, EU MDR implementation consistency, and reimbursement policy evolution for robotic-assisted procedures were held fixed across the projection horizon. Segmentation modeling spanned product type, application, end user, and technology tier with regional regulatory cluster overlays. CAGRs derived from regression analysis of historical procurement volumes against capital expenditure cycle indicators. Forecast inputs incorporated OR throughput demands, ambulatory surgery center expansion rates, and neurostimulation device indication pipeline depth.
Practitioners should monitor FDA 510(k) pathway refinement announcements, EU MDR notified body capacity constraints, and integrated delivery network reimbursement unbundling pilots for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Hydrocephalus Shunts Market
Medical Devices
Digital Orthodontics Market
Medical Devices
Global Medical Composite Market
Medical Devices
Global Canes and Crutches Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
MRI Motion Tracking Systems Market
Medical Devices
Global Pneumatic Tourniquets Market
Medical Devices
Waterproof Orthotics Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Implantable Port Devices Market
Medical Devices
Face Mask Device Market
Medical Devices
United States Diabetes Devices Market
Medical Devices
Global Keratometers Market
Medical Devices
Interventional Cardiology Devices Market
Medical Devices
Middle East and Africa Aligner Sheet Market