
 Spinal Stenosis Market | 2026-2036
Spinal Stenosis Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Stenosis Market Outlook
A widening capital-intensity gap between integrated device manufacturers and focused spine specialists is rotating competitive advantage toward firms with captive manufacturing and biologics pipelines. Medtronic leverages its neurosurgical portfolio breadth to sustain cross-selling momentum across implant and navigation platforms. Globus Medical anchors its position through vertically controlled manufacturing of expandable interbody devices. NuVasive differentiates via specialized lateral access technology and dedicated surgeon training infrastructure.
Spinal stenosis denotes the pathological narrowing of the spinal canal or neural foramina, typically arising from degenerative changes in ligamentum flavum hypertrophy, facet joint osteoarthritis, or disc bulging that compresses neural elements and produces neurogenic claudication or radiculopathy. Surgical instruments and spinal implants command the dominant revenue share, though robotic-assisted surgery represents the fastest-expanding technology segment as capital budgets shift toward systems enabling precision decompression and pedicle screw placement. Biologics occupy a concentrated margin pool, particularly osteobiologic adjuncts deployed in fusion procedures, while imaging equipment faces pressure from extended replacement cycles and leasing preferences among ambulatory surgical centers.
FDA 510(k) premarket notification requirements govern implantable spinal devices in the United States, with recent enforcement trends demanding more rigorous biomechanical testing data and post-market surveillance protocols. The EU Medical Device Regulation imposes stricter clinical evidence standards and notified body capacity constraints that delay CE marking timelines for European market entry. Stakeholders must monitor evolving CMS coverage determinations for minimally invasive decompression and interspinous spacer procedures, as reimbursement parity with open fusion will dictate capital allocation across product development and commercial channels.
Market Dynamics
Hospital procurement committees are consolidating vendor relationships around integrated spine platforms, compressing the number of approved suppliers per health system while elevating technical service and training commitments as decisive selection criteria.
Growth Catalysts
- CMS reimbursement parity:Medicare coverage determinations for minimally invasive decompression procedures are expanding eligible patient pools across ambulatory surgical centers and hospital outpatient departments.
- Biologics pipeline maturation:Osteobiologic adjuncts with enhanced osteoinductive properties are penetrating fusion procedures, capturing margin expansion opportunities within integrated delivery networks.
- Germany:The EU Medical Device Regulation's phased implementation timeline is accelerating notified body capacity investments, reducing CE marking delays for spinal implant manufacturers targeting European market entry.
Market Restraints
- Titanium alloy supply concentration:Raw material sourcing for interbody cages and pedicle screw systems depends on a limited supplier base concentrated in aerospace-adjacent foundries, exposing device manufacturers to input cost volatility.
- FDA 510(k) evidentiary demands:Recent enforcement trends require more rigorous biomechanical testing data and post-market surveillance protocols, extending product development timelines and regulatory compliance expenditures.
- Motion preservation substitution:Cervical and lumbar artificial disc replacement systems are capturing younger patient segments that previously defaulted to decompression and fusion protocols.
Strategic Opportunities
- Brazil:ANVISA regulatory harmonization initiatives are streamlining import pathways for spinal implants, creating first-mover advantages for manufacturers establishing localized distribution infrastructure.
- Robotic-navigation convergence:Integration of intraoperative imaging with autonomous pedicle screw placement is opening premium positioning opportunities for capital equipment vendors within academic medical centers.
- Direct-to-ASC distribution:Bypassing traditional hospital supply chain intermediaries through dedicated ambulatory surgical center sales channels is reducing customer acquisition costs and accelerating procedure volume capture.
Industry Challenges
- Surgeon training infrastructure:Minimally invasive lateral access and percutaneous screw placement techniques require specialized cadaveric lab investments and proctoring networks that strain commercial team bandwidth.
- Legacy EHR integration:Robotic surgery platforms must interface with heterogeneous hospital information systems, creating implementation friction and delayed go-live timelines within target accounts.
- Patent thickets in expandable interbody devices:Dense intellectual property landscapes around articulating cage geometries are complicating freedom-to-operate analyses and licensing negotiations for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Stenosis Market |
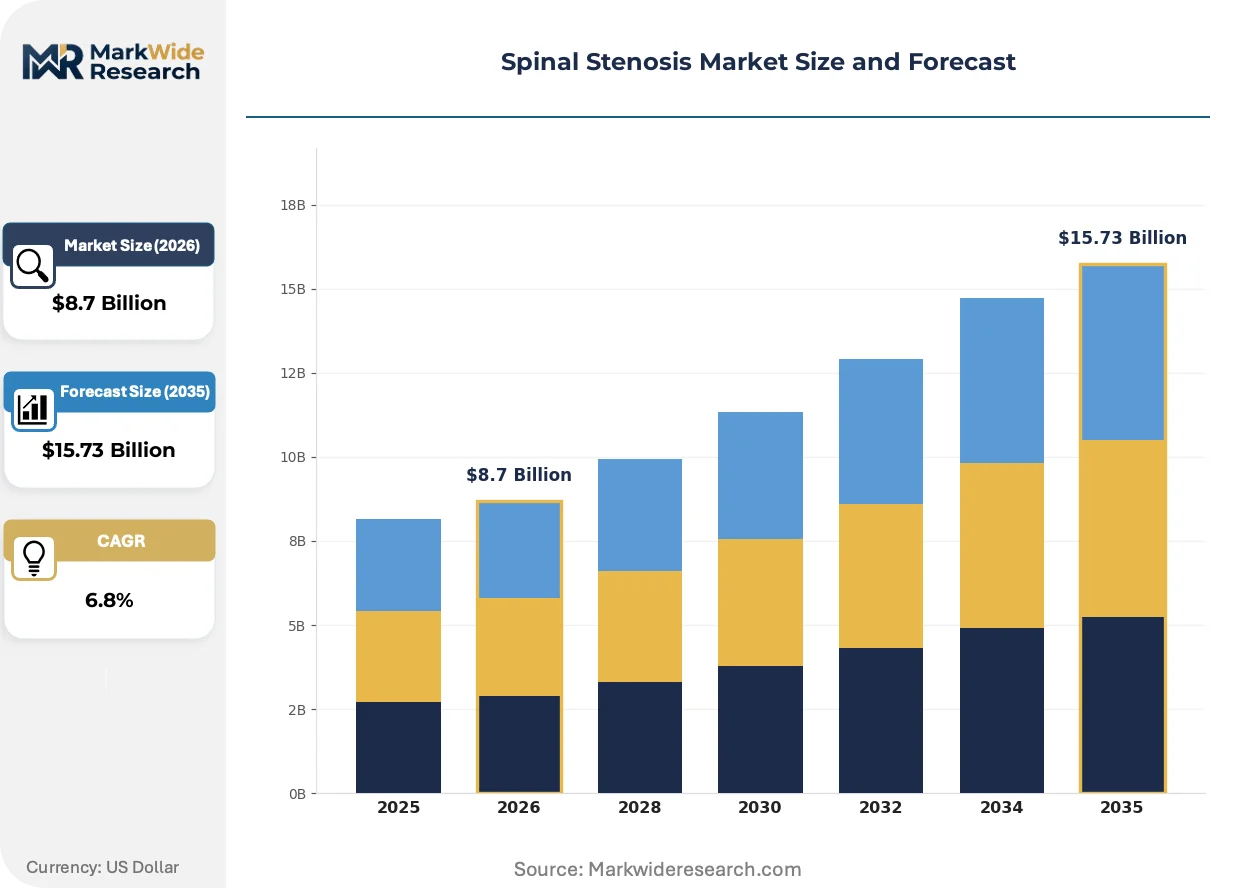
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Imaging Equipment, Spinal Implants, Biologics Application: Minimally Invasive Surgery, Open Surgery, Pain Management, Physical Therapy End User: Hospitals, Ambulatory Surgical Centers, Rehabilitation Clinics, Homecare Technology: Conventional Surgery, Robotic-Assisted Surgery, Endoscopic Techniques, Ultrasound Guidance |
| Companies Covered | DePuy Synthes, Globus Medical, Medtronic, Boston Scientific, Orthofix Medical, Stryker Corporation, NuVasive, Alphatec Holdings, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Stenosis Market Strategic Shifts
Active reshaping of the spinal stenosis market centers on three convergent forces: surgical modality migration, regulatory evidence escalation, and procurement centralization within consolidated health systems.
Robotic-assisted surgery platforms are bifurcating the capital equipment landscape. These systems enable sub-millimeter precision in pedicle screw trajectory planning and real-time navigation feedback. Academic medical centers and large integrated delivery networks are adopting them as standard-of-care anchors for spine service line marketing. The technology is compressing open procedure volumes while elevating capital budget competition between navigation, imaging, and implant vendors.
REACH substance restrictions and EU MDR clinical evidence requirements are elevating biocompatibility documentation burdens for implantable spinal devices. Manufacturers must now generate extended follow-up data on wear debris and adjacent segment degeneration. European market entry timelines for novel interbody materials have lengthened, prompting some firms to prioritize FDA 510(k) clearance pathways before CE marking investment.
Hospital value analysis committees are consolidating spine vendor panels from fifteen-plus suppliers to three to five preferred partners. Device manufacturers must now bundle implants, biologics, and capital equipment into single-source contracts to maintain access. This concentration is most visible within United States health systems pursuing Medicare ACO REACH or bundled payment participation, where supply cost accountability has shifted from surgeons to administrative procurement functions.
Spinal Stenosis Market Segmentation
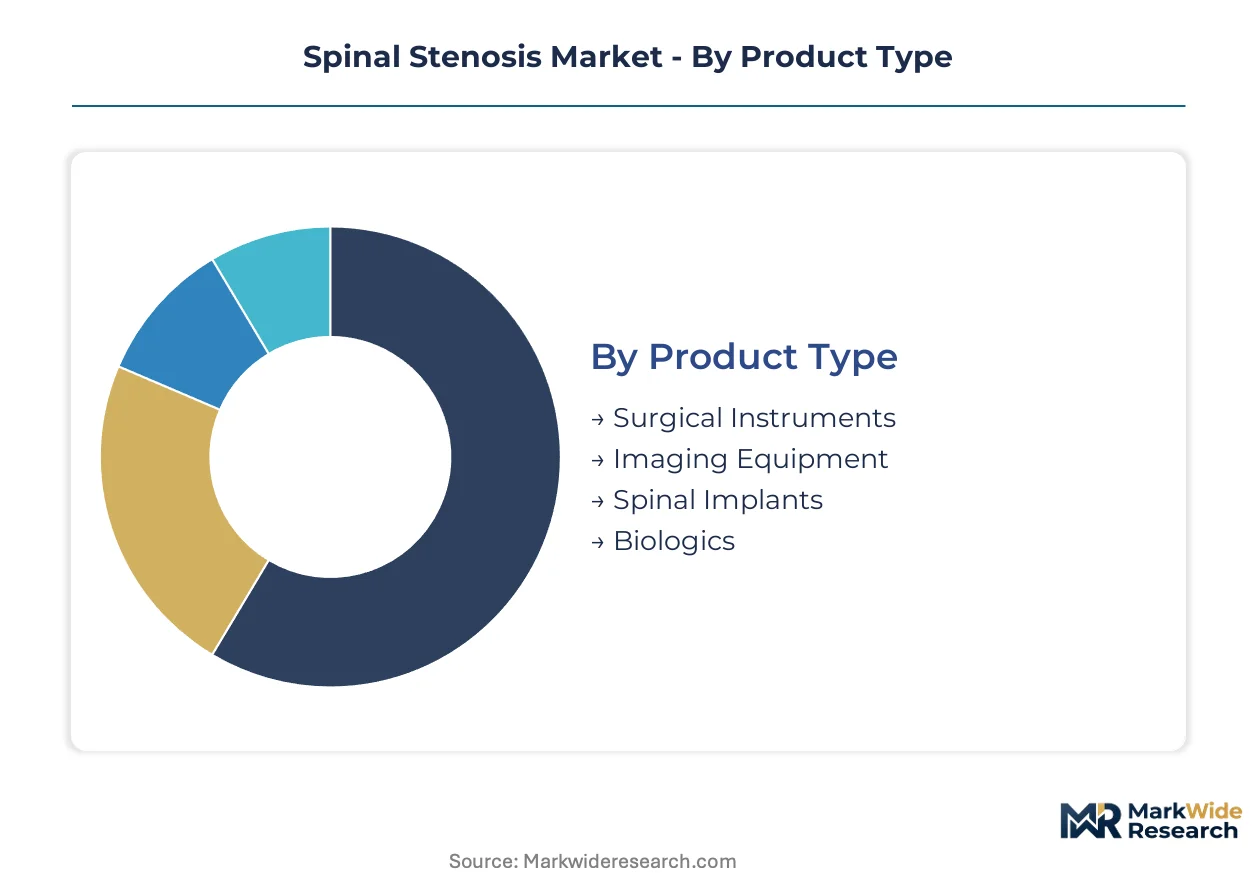
Spinal stenosis treatment modalities span invasive and conservative pathways, each governed by distinct regulatory frameworks and reimbursement structures. Device manufacturers must align product portfolios with the specific evidentiary requirements and procurement channels that characterize each segment category.
Product Type:
FDA 510(k) clearance pathways impose substantially different testing burdens across implantable versus non-implantable categories, with spinal implants facing the most rigorous biomechanical validation requirements.
- Spinal Implants:Interbody cages, pedicle screw systems, and interspinous spacers fabricated from titanium alloys or PEEK polymers constitute the revenue-dense core of this segment. Demand concentrates within United States hospital systems pursuing bundled payment contracts, where implant standardization reduces procurement complexity.
- Biologics:Osteobiologic adjuncts including demineralized bone matrix and synthetic bone graft substitutes carry concentrated margin profiles due to limited supplier bases and specialized cold-chain logistics. United States ambulatory surgical centers are expanding utilization as CMS reimbursement determinations clarify coverage for fusion procedures.
- Surgical Instruments:Rongeurs, Kerrison punches, and specialized retractors for posterior decompression.
- Imaging Equipment:Intraoperative fluoroscopy and navigation systems facing extended replacement cycles.
Established volume favors spinal implants; emerging adoption favors biologics.
Application:
Procedure selection depends on patient age, comorbidity burden, and anatomical severity, with minimally invasive techniques gaining preference among commercially insured populations.
- Minimally Invasive Surgery:Tubular retractor systems and percutaneous screw placement reduce paraspinal muscle disruption and accelerate recovery timelines. United States ambulatory surgical centers are capturing volume migration from inpatient settings as CMS extends reimbursement parity for decompression procedures.
- Open Surgery:Laminectomy and fusion procedures retain dominance for multilevel stenosis and spondylolisthesis cases. Hospital inpatient departments maintain volume concentration due to anesthesia requirements and overnight monitoring protocols.
- Pain Management:Epidural steroid injections and radiofrequency ablation for nonsurgical candidates.
- Physical Therapy:Conservative rehabilitation protocols for mild to moderate neurogenic claudication.
Clinical severity drives open surgery selection; commercial reimbursement tailwinds favor minimally invasive expansion.
End User:
Procurement authority is consolidating around value analysis committees that span multiple delivery sites, compressing vendor access points.
- Hospitals:Academic medical centers and community hospital systems command the dominant procedure volume, with spine service lines representing strategic priority investments. Integrated delivery networks in the United States are consolidating vendor panels to three to five preferred partners.
- Ambulatory Surgical Centers:Freestanding surgical facilities are expanding lumbar decompression capacity as CMS site-of-service differentials create margin incentives. United States metropolitan markets show the steepest facility buildout rates.
- Rehabilitation Clinics:Postoperative physical therapy and pain management services.
- Homecare:Remote monitoring and conservative symptom management.
Hospital systems anchor current revenue; ambulatory surgical centers represent the steepest expansion trajectory.
Technology:
Capital equipment acquisition cycles and training infrastructure requirements create divergent competitive dynamics across technological modalities.
- Robotic-Assisted Surgery:Navigation platforms enabling sub-millimeter pedicle screw trajectory precision are displacing conventional freehand techniques in United States academic medical centers. Capital budget competition between navigation, imaging, and implant vendors is elevating bundled contract requirements.
- Endoscopic Techniques:Visualized decompression through tubular working channels reduces tissue disruption versus microscopic approaches. United States specialty spine practices are adopting these systems to differentiate outpatient service offerings.
- Conventional Surgery:Microscopic and open techniques requiring lower capital investment.
- Ultrasound Guidance:Real-time imaging for injection-based interventions and percutaneous procedures.
Capital intensity favors conventional surgery penetration; precision outcomes and marketing differentiation favor robotic-assisted adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry separates the United States from Germany, where CMS reimbursement parity for ambulatory procedures accelerates volume migration while EU MDR compliance costs compress margins for European entrants.
United States
Aging demographics and commercial insurance frameworks drive procedure volume expansion across hospital outpatient departments and freestanding surgical centers. FDA 510(k) clearance pathways govern implantable device market entry, with recent enforcement trends demanding enhanced biomechanical testing documentation. Spine service lines in metropolitan hospital systems from Phoenix to Charlotte are consolidating vendor panels to capture bundled payment efficiencies.
Germany
Statutory health insurance reimbursement for minimally invasive decompression procedures supports adoption rates exceeding European averages. The EU Medical Device Regulation's phased implementation is accelerating notified body capacity investments, reducing CE marking delays for spinal implant manufacturers. Industrial clusters around Tuttlingen and the Lake Constance region concentrate precision surgical instrument fabrication and robotic platform assembly operations.
Japan
Super-aged population demographics sustain elevated spinal stenosis prevalence rates among patients over seventy-five. PMDA regulatory frameworks require local clinical trial data for novel interbody materials, extending market entry timelines for foreign manufacturers. Tokyo and Osaka academic medical centers anchor demand for navigation-enabled pedicle screw systems and integrated imaging platforms.
Brazil
Private health insurance expansion in São Paulo and Rio de Janeiro metropolitan areas creates addressable demand for premium implant technologies. ANVISA regulatory harmonization initiatives are streamlining import pathways for spinal implants, reducing registration timelines for established manufacturers. Localized distribution infrastructure investments in the Southeast region are capturing first-mover positioning advantages.
Australia
Public hospital procurement centralization under state-based health departments is compressing supplier access points for implant vendors. TGA regulatory requirements align with EU MDR evidence standards, elevating biocompatibility documentation burdens for market entrants. Sydney and Melbourne spine units are prioritizing robotic-assisted surgery platforms as service line differentiators in competitive private hospital markets.
Spinal Stenosis Market Competitive Environment
Concentration sits with integrated device manufacturers possessing captive manufacturing infrastructure and biologics pipelines. Hospital procurement committees are consolidating vendor relationships around single-source spine platforms, compressing approved supplier counts per health system from fifteen-plus to three to five preferred partners. Two strategic archetypes dominate: diversified medtech conglomerates leveraging cross-selling momentum across neurosurgical portfolios, and focused spine specialists anchoring positions through vertically controlled manufacturing. Dominant competitive moves include bundled contracting spanning implants, biologics, and capital equipment, alongside dedicated surgeon training infrastructure investments.
Among diversified conglomerates, Medtronic and Stryker Corporation represent integrated platform providers with breadth across implant, navigation, and robotic modalities. Globus Medical and NuVasive exemplify the spine-specialist archetype, with the former occupying a position anchored in vertically controlled manufacturing of expandable interbody devices and the latter differentiated through specialized lateral access technology. These four entities sit within the tier of vendors capable of meeting consolidated health system demands for technical service, training commitment, and supply cost accountability.
| Leading Market Players |
|---|
| DePuy Synthes |
| Globus Medical |
| Medtronic |
| Boston Scientific |
| Orthofix Medical |
| Stryker Corporation |
| NuVasive |
| Alphatec Holdings |
| Zimmer Biomet |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at aerospace-adjacent titanium foundries in the United States and Germany shapes both supply concentration and implant price floors, as spinal device manufacturers compete for alloy feedstock against aviation and defense contractors. Hospital procurement consolidation into three-to-five preferred vendor panels amplifies volume discount leverage while compressing margins for second-tier suppliers.
Pricing Analysis
Configured-to-order pricing for patient-specific interbody cages and navigation-enabled screw systems commands substantial premiums over standard catalog configurations. Three-tier pricing structure across premium robotic-integrated, standard navigation-assisted, and economy conventional instrument sets reflects FDA 510(k) certification tier and surgeon training bundling. Cost compression in the economy tier is intensifying because ambulatory surgical centers are standardizing around single-source contracts. Price sensitivity concentrates among independent specialty spine practices, while academic medical centers prioritize outcome metrics over unit cost.
Supply Chain Analysis
Strait of Malacca transit routes underpin cold-chain logistics for osteobiologic adjuncts sourced from United States and European processing facilities. Manufacturing concentration rests on titanium alloy forging in the United States, precision machining in Germany, and PEEK polymer extrusion in Switzerland. Raw material dependencies span aerospace-grade titanium, medical-grade PEEK, and demineralized bone matrix. Single-source vulnerability in titanium sponge processing elevates exposure to commodity price volatility. Distribution runs through hospital value analysis committees and GPO contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) evidentiary escalation and EU MDR compliance burdens are accelerating competitive separation between integrated platform vendors and capital-constrained specialists. Robotic-navigation convergence represents the decisive technological inflection reshaping procurement authority.
For Market Incumbents: Compound cross-selling momentum by bundling implants, biologics, and capital equipment into single-source contracts that satisfy consolidated health system procurement committees. Deepen backward integration into titanium alloy sourcing to insulate margin structures from aerospace demand cycles. Prioritize surgeon training infrastructure investments as a defensive moat against lateral access specialists. For New Entrants and Emerging Players: Differentiate on endoscopic visualization platforms for ambulatory surgical center outpatient decompression procedures. Target Brazil's private insurance expansion corridors and Australia's robotic-assisted surgery adoption wave as penetrable geographies. Pursue direct-to-ASC distribution models that bypass hospital supply chain intermediaries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among implant manufacturers with captive biologics pipelines and long-term GPO contract tenors. Five-to-ten year viability favors vertically controlled manufacturing archetypes over pure-play distribution models. Monitor CMS coverage determination timelines for minimally invasive decompression as the critical reimbursement inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Expedited clearance pathways compress time-to-revenue for novel interbody geometries. |
| CE Marking Pathway Investment | EU MDR compliance capabilities unlock European hospital system procurement access. |
| Hospital System Partnership | Bundled contracts with integrated delivery networks secure multi-year implant volume commitments. |
| Software Companion Development | Robotic navigation algorithms enhance pedicle screw placement precision and surgeon adoption. |
| Reimbursement Strategy | CMS coverage determination alignment maximizes ambulatory surgical center procedure economics. |
Study Parameters
A standing panel of spine surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration across the research process. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body capacity reports. Bottom-up implant volume modeling and top-down health system expenditure analysis were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, surgical modality, end-user facility category, and technology platform. CAGRs were derived from procedure volume elasticity to demographic aging patterns and reimbursement parity expansion. Forecast inputs incorporated titanium alloy price indices, robotic system placement rates, and biologics utilization trends.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement expansion or titanium supply stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory clearance timelines and hospital capital budget allocation. Practitioners should keep alternative scenarios live as EU MDR enforcement intensity and ambulatory surgical center buildout rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Orthopedic Repair Market
Orthopedics
Rotator Cuff Arthropathy Repair Market
Orthopedics
United States Orthopedic Braces and Support Market
Orthopedics
Cruciate Ligament Repair Procedures Market
Orthopedics
US Arthritis Market
Orthopedics
Skeletal Deformation Correction Market
Orthopedics
Orthopedic Pillow Market
Orthopedics
Hallux Rigidus Market
Orthopedics
Osteoarthritis Treatment Market
Orthopedics
Orthopedic Soft Tissue Repair Market
Orthopedics
Osteoporosis Treatment Market
Orthopedics
Bilateral Osteoarthritis Treatment Market
Orthopedics
Knee Hyaluronic Acid Injections Market
Orthopedics
Europe Extremity Reconstruction Market
Orthopedics
Orthopedics Market
Orthopedics
ACL Reconstruction Market