
 Global Spirometers Market | 2026-2036
Global Spirometers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spirometers Market Foresight
The gap between premium diagnostic-grade systems and commoditized home-use devices is realigning procurement patterns across healthcare networks. Koninklijke Philips N.V. leverages its imaging ecosystem to bundle spirometry with broader respiratory diagnostics, while SCHILLER anchors its position through cardiopulmonary integration platforms that reduce total equipment footprint. Vyaire Medical competes on disposable supply continuity, a channel control strategy that locks hospital systems into recurring revenue relationships.
A spirometer measures lung function parameters including forced vital capacity and forced expiratory volume through volume displacement or flow-sensing mechanisms, typically achieving accuracy within 3% of reading across ATS/ERS standards; its primary purpose is diagnosing obstructive and restrictive pulmonary disorders while tracking disease progression. Portable spirometers now dominate volume as point-of-care testing decentralizes from hospital pulmonary labs, while ultrasound technology segments command margin premiums due to superior hygiene profiles and reduced calibration overhead. Desktop systems retain installed-base dominance in research institutes where multi-parameter protocols require stationary precision.
FDA 510(k) premarket notification shapes device entry timelines for US manufacturers, while the EU MDR and ISO 26782:2022 calibration standards collectively determine which products access clinical reimbursement pathways. Japan's PMDA enforces JIS T 0601-1 electrical safety requirements that filter out lower-tier imports. Stakeholders must weigh regulatory capital intensity against the defensibility of certified product lines as software-as-medical-device frameworks expand compliance scope.
Market Dynamics
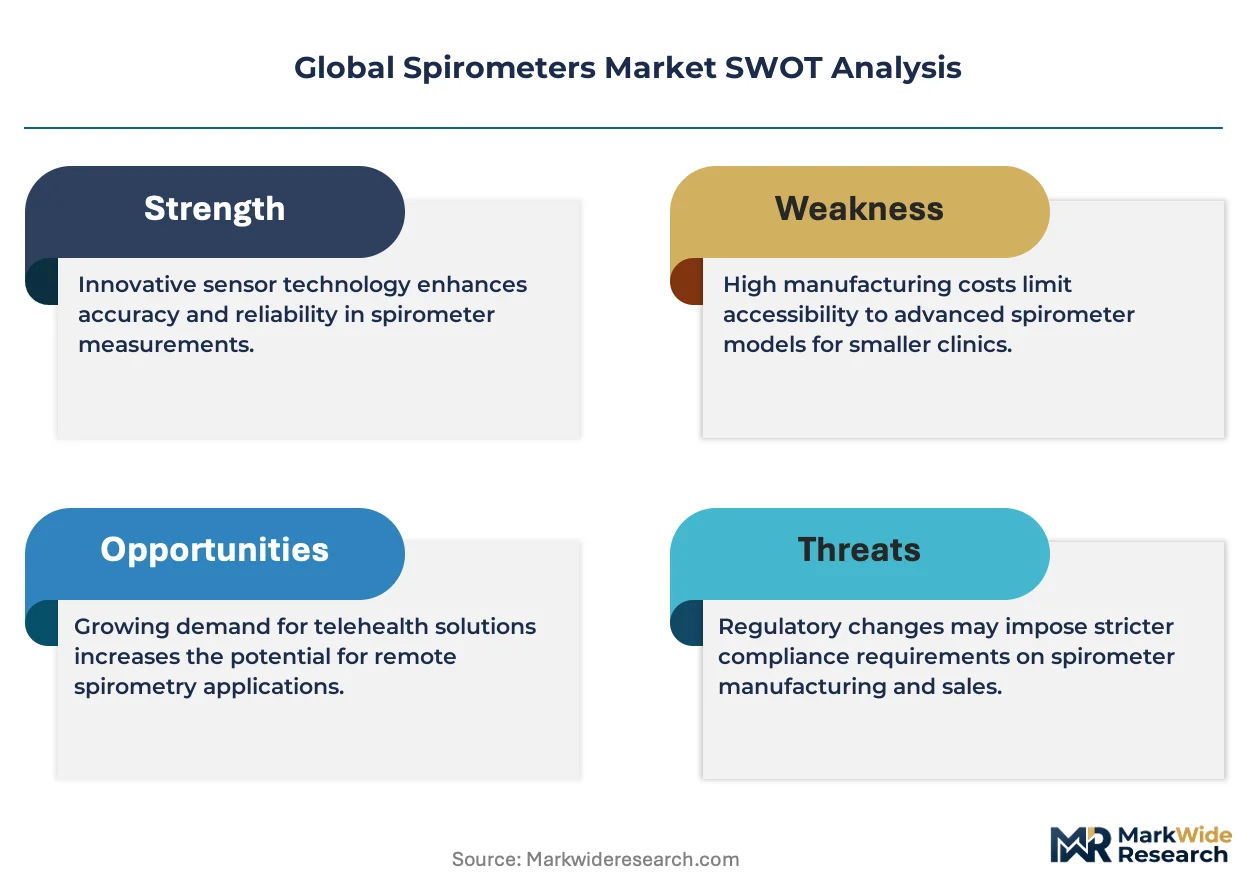
Software-as-medical-device frameworks are compressing hardware margins while expanding addressable use cases beyond traditional pulmonary labs into home monitoring and occupational health screening workflows.
Growth Catalysts
- EU MDR certification pathways:Streamlined conformity assessment for digital spirometry modules accelerates reimbursement eligibility across German, French, and Italian hospital networks.
- Ultrasonic flow sensors:Solid-state measurement eliminates moving parts, reducing calibration frequency from quarterly to annual cycles in high-throughput clinics.
- Japan's PMDA electrical safety standards:JIS T 0601-1 compliance requirements filter import competition, creating protected domestic volume for certified manufacturers.
Market Restraints
- MEMS pressure sensor supply:Taiwanese foundry concentration exposes manufacturers to wafer allocation volatility during semiconductor demand cycles.
- FDA 510(k) documentation burden:Predicate device matching requirements extend premarket timelines for novel flow-sensing architectures.
- Smartwatch SpO2 and respiratory rate monitoring:Consumer wearable ecosystems capture low-acuity screening volume that previously flowed to dedicated spirometry.
Strategic Opportunities
- Brazil's ANVISA telehealth expansion:Remote diagnostic authorization creates first-mover positioning for cloud-connected portable systems in Latin America's largest healthcare market.
- AI-interpreted waveform analysis:Machine learning pattern recognition converges with spirometry hardware to automate obstructive versus restrictive classification.
- Direct-to-employer occupational screening:Bypassing hospital procurement through corporate wellness contracts opens volume in mining, construction, and chemical processing sectors.
Industry Challenges
- ISO 26782:2022 calibration technician scarcity:Accredited service networks struggle to match deployment velocity of point-of-care devices.
- Legacy HL7 integration:Hospital information system compatibility gaps force custom middleware development for each electronic health record vendor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spirometers Market |
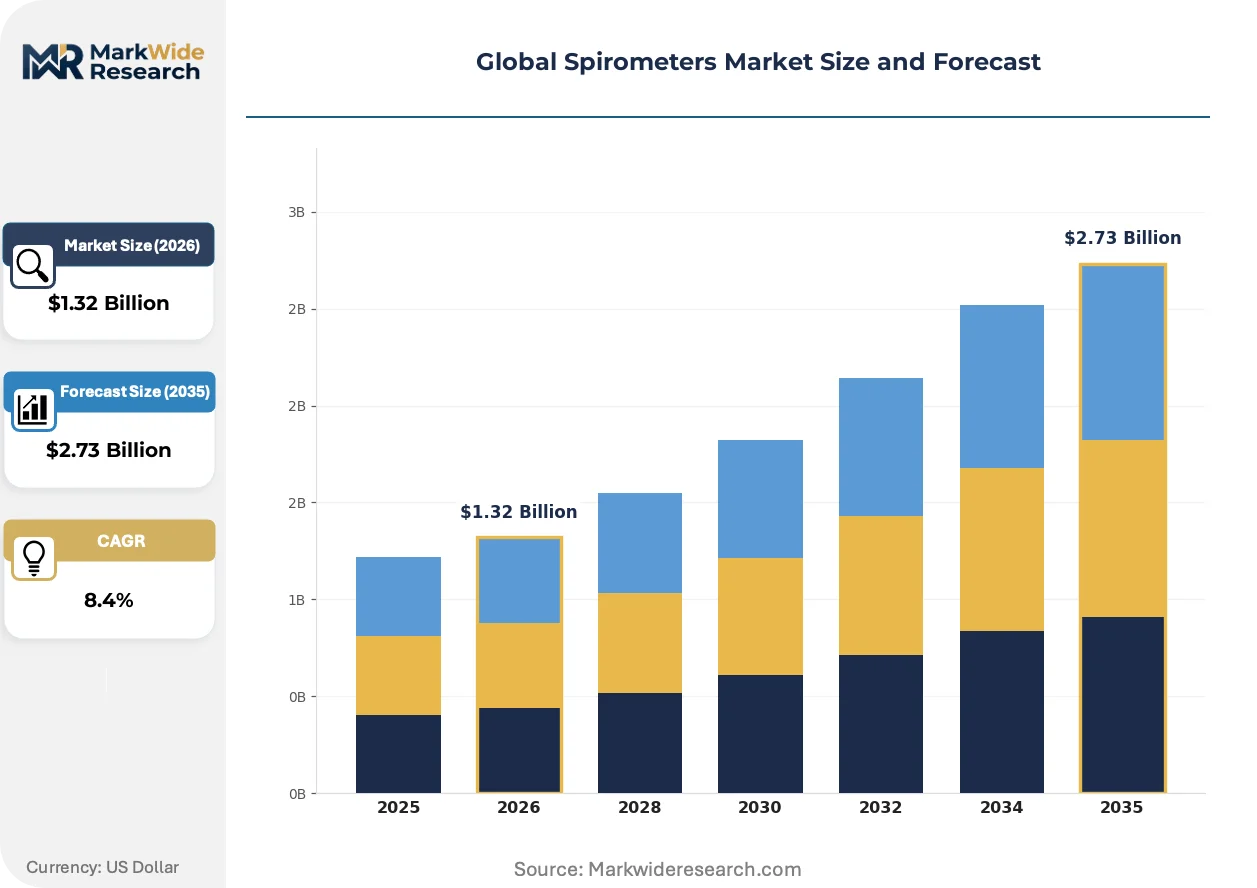
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.73 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Spirometers, Desktop Spirometers, Handheld Spirometers, Touch Screen Spirometers, Ultrasound Spirometers Technology: Ultrasonic, Pneumotachograph, Turbine, Fleisch, Hot Wire Anemometer Application: Chronic Obstructive Pulmonary Disorder, Asthma, Cystic Fibrosis, Pulmonary Fibrosis, Occupational Lung Disease End User: Hospitals, Diagnostic Centers, Research Institutes, Home Care Providers, Physiotherapy Clinics |
| Companies Covered | Koninklijke Philips N.V., SCHILLER, Vyaire Medical, MGC Diagnostics Corporation, COSMED srl, Nihon Kohden Corporation, Fukuda Sangyo Co. Ltd., Vitalograph, ndd Medizintechnik AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spirometers Market Shifts & Advancements
Spirometry hardware is dissolving into distributed sensor networks, with measurement accuracy migrating from standalone devices into multi-modal respiratory monitoring platforms that span clinical and non-clinical environments.
Ultrasonic time-of-flight flow measurement is unifying hygiene protocols with diagnostic precision. The technology eliminates turbine contamination risks that plague volume-displacement systems. German occupational health clinics and Japanese hospital networks are adopting these solid-state platforms at replacement-cycle velocity. This unification of sterility and accuracy is compressing the market for reusable mechanical sensors while expanding addressable settings into pharmaceutical trial sites and athletic performance labs.
REACH substance restrictions on mercury-containing pressure sensors are forcing redesigns of legacy calibration equipment across European manufacturing facilities. The regulation's industrial consequence is accelerated obsolescence of wet-spirometer reference standards that dominated quality control workflows. German and Swiss metrology laboratories are responding with dry-gas piston-based certification systems that satisfy both environmental compliance and ATS/ERS traceability requirements.
Hospital procurement departments are bundling spirometry with broader respiratory diagnostic suites rather than acquiring standalone devices. Pulmonary function test labs consolidate vendor relationships, replacing point-product negotiations with multi-year equipment service agreements. This concentration is most visible in US integrated delivery networks and NHS England trust procurement frameworks, where total-cost-of-ownership models now dominate capital allocation decisions.
Global Spirometers Market Segmentation
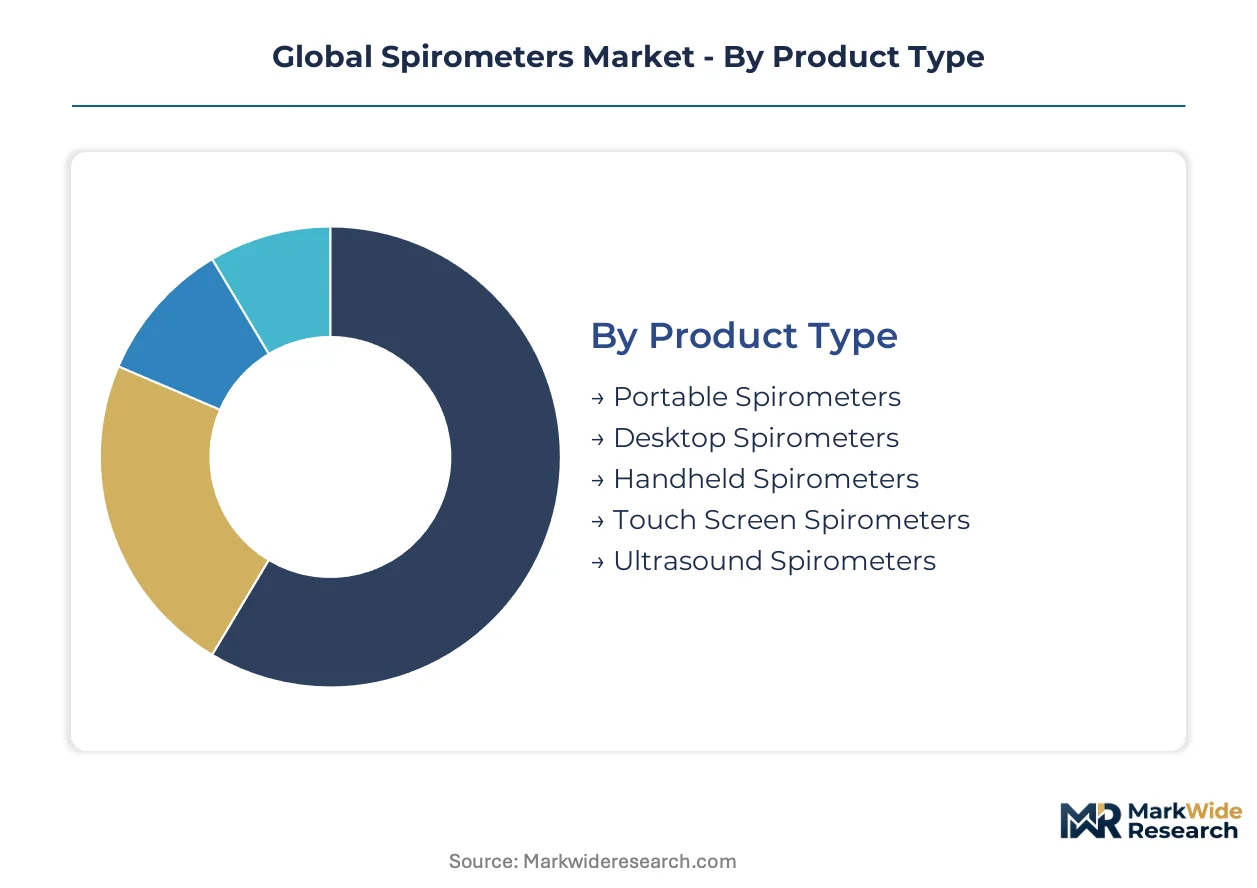
Segmentation in the spirometry market reveals how hardware specifications, measurement principles, and care settings fragment procurement decisions. Each dimension carries distinct regulatory pathways and margin profiles that reshape competitive positioning across clinical and non-clinical environments.
Product Type:
Customization-to-standardization tension runs deepest here, with portable systems pushing modularity against desktop platforms that anchor institutional precision.
- Portable Spirometers:Battery-powered units with Bluetooth telemetry dominate point-of-care decentralization. Demand concentrates in German occupational health clinics and US home care networks where remote monitoring reimbursement codes have activated procurement. Solid-state ultrasonic variants within this segment command margin premiums through reduced calibration overhead.
- Desktop Spirometers:Stationary systems with multi-parameter protocols serve research institutes and hospital pulmonary function labs. Japanese university hospitals and Swiss pharmaceutical trial sites sustain installed-base dominance through ATS/ERS traceability requirements that portable units struggle to match.
- Handheld Spirometers:Pocket-sized flow measurement for screening workflows in Brazilian mining operations and Indian construction sites.
- Touch Screen Spirometers:Integrated interfaces reducing technician training burden in French diagnostic centers and Italian respiratory clinics.
- Ultrasound Spirometers:Solid-state time-of-flight measurement eliminating turbine contamination risks in high-throughput Japanese hospital networks.
Leading the category by volume: Portable Spirometers. Expanding most quickly: Ultrasound Spirometers.
Technology:
Cost tier stratification separates premium solid-state architectures from mechanical systems facing obsolescence pressure through REACH substance restrictions.
- Ultrasonic:Time-of-flight flow measurement eliminates moving parts entirely. German and Swiss metrology laboratories drive replacement-cycle velocity as dry-gas piston certification systems displace mercury-containing wet-spirometer references. Annual calibration cycles versus quarterly maintenance reshape total-cost-of-ownership calculations.
- Pneumotachograph:Differential pressure measurement across a fixed resistance mesh remains the reference standard for ATS/ERS compliance. US hospital networks and NHS England trusts retain these systems where predicate device matching simplifies FDA 510(k) pathways.
- Turbine:Rotating vane mechanisms face hygiene protocol challenges in European clinical settings.
- Fleisch:Heated-wire anemometry retains niche positioning in research-grade respiratory physiology.
- Hot Wire Anemometer:Thermal dissipation measurement for specialized flow dynamics in athletic performance laboratories.
Volume leadership: Pneumotachograph systems. Steepest expansion trajectory: Ultrasonic technology.
Application:
Patient population severity and reimbursement intensity segment demand across obstructive, restrictive, and occupational disease categories.
- Chronic Obstructive Pulmonary Disorder:Forced expiratory volume tracking dominates Medicare and NHS reimbursement volumes. US integrated delivery networks and German statutory health insurance funds drive recurring testing protocols for disease progression monitoring. Home care providers expanding into remote respiratory monitoring target this population for continuous engagement.
- Asthma:Pediatric and adolescent screening concentrates in French school health programs and Japanese municipal health centers. Portable spirometry with cloud-connected interpretation supports decentralized diagnosis where specialist pulmonologist access remains limited.
- Cystic Fibrosis:Specialized pulmonary function protocols in research-intensive centers.
- Pulmonary Fibrosis:Restrictive pattern classification requiring diffusion capacity integration.
- Occupational Lung Disease:Mandated screening in German industrial sectors and emerging Brazilian ANVISA telehealth authorization.
Category leadership by procedure volume: Chronic Obstructive Pulmonary Disorder. Gaining share fastest: Occupational Lung Disease.
End User:
Customer type fragmentation separates capital-intensive institutional procurement from recurring-revenue service relationships and direct-to-consumer channels.
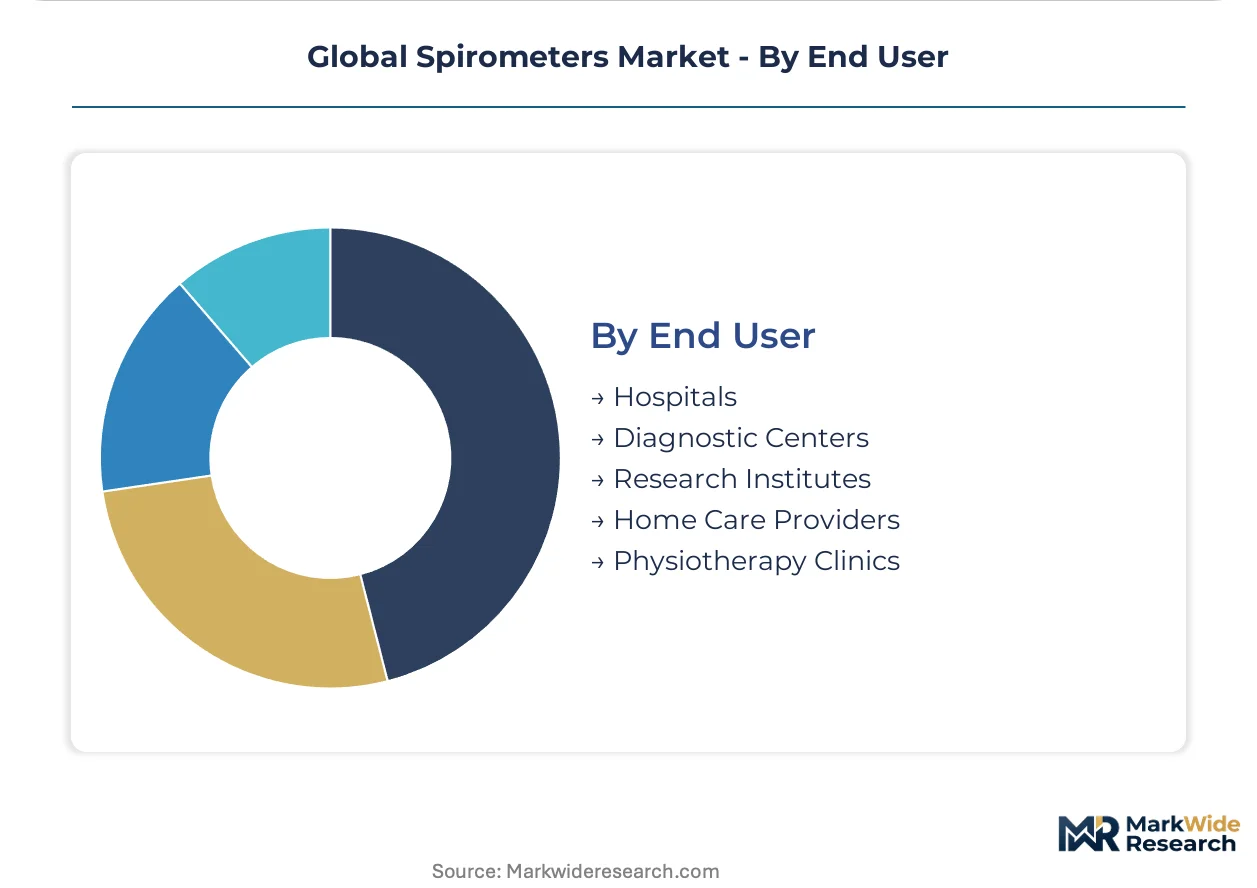
- Hospitals:Pulmonary function test labs consolidate vendor relationships through multi-year equipment service agreements. US integrated delivery networks and NHS England trusts bundle spirometry with broader respiratory diagnostic suites, replacing point-product negotiations with total-cost-of-ownership frameworks.
- Home Care Providers:Remote patient monitoring reimbursement activation drives portable device deployment. German disease management programs and US Medicare Advantage contracts sustain volume growth as decentralized testing becomes standard practice.
- Diagnostic Centers:High-throughput screening operations in Indian urban clusters and Mexican metropolitan areas.
- Research Institutes:Multi-parameter precision requirements in Swiss pharmaceutical trials and Japanese university hospitals.
- Physiotherapy Clinics:Rehabilitation-focused measurement in Australian and Canadian community care settings.
Volume concentration: Hospitals. Climbing the fastest: Home Care Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor in Germany concentrates occupational lung screening volume where mandated workplace health assessments sustain diagnostic equipment procurement.
United States
Medicare Advantage contracts and remote patient monitoring reimbursement codes activate portable spirometer deployment across home care networks. FDA 510(k) premarket notification requirements filter device entry timelines for novel flow-sensing architectures. The Greater Boston cluster anchors pulmonary function research where multi-parameter precision protocols sustain desktop system demand.
Germany
Statutory health insurance funds drive recurring testing protocols for chronic obstructive pulmonary disorder progression monitoring. EU MDR certification pathways streamline conformity assessment for digital spirometry modules across hospital networks. The Ruhr industrial corridor concentrates occupational health screening mandates that sustain clinical equipment procurement volume.
Japan
Municipal health centers deploy portable spirometry with cloud-connected interpretation for pediatric and adolescent asthma screening. PMDA enforces JIS T 0601-1 electrical safety requirements that filter lower-tier import competition. University hospitals in the Kanto region retain installed-base dominance through ATS/ERS traceability requirements.
Brazil
ANVISA telehealth expansion authorizes remote diagnostic deployment for cloud-connected portable systems in mining and construction sectors. Corporate wellness contracts bypass hospital procurement through direct-to-employer occupational screening agreements. São Paulo metropolitan diagnostic centers concentrate high-throughput screening operations.
Switzerland
Pharmaceutical trial sites sustain demand for research-grade respiratory physiology equipment with multi-parameter precision. REACH substance restrictions on mercury-containing pressure sensors accelerate obsolescence of wet-spirometer reference standards. Basel-area metrology laboratories deploy dry-gas piston-based certification systems.
Global Spirometers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across calibration certification and disposable supply continuity dimensions. The vendor base organizes around three strategic archetypes: imaging ecosystem bundlers, cardiopulmonary integration platforms, and disposable-anchored channel controllers. Consolidation pressures favor multi-year equipment service agreements over point-product negotiations. Dominant competitive moves include portfolio bundling with broader respiratory diagnostics and geographic positioning for protected domestic volume under national electrical safety standards.
Among imaging ecosystem bundlers, Koninklijke Philips N.V. represents the premium-tier vector where hardware margins compress against software-as-medical-device frameworks. SCHILLER exemplifies the cardiopulmonary integration platform archetype that reduces total equipment footprint across European hospital networks. Vyaire Medical occupies the disposable supply continuity position that locks hospital systems into recurring revenue relationships.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| SCHILLER |
| Vyaire Medical |
| MGC Diagnostics Corporation |
| COSMED srl |
| Nihon Kohden Corporation |
| Fukuda Sangyo Co. Ltd. |
| Vitalograph |
| ndd Medizintechnik AG |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists in European diagnostic equipment manufacturing anchor supply discipline through consolidated procurement networks, translating captive volume into tiered pricing power across German hospital systems and Japanese university hospitals. This ownership concentration compresses margin leakage while amplifying negotiating leverage against Taiwanese MEMS foundries and Swiss metrology laboratories.
Pricing Analysis
Outcome-based pricing anchors hospital procurement decisions, with total-cost-of-ownership models bundling hardware acquisition, calibration certification, and disposable supply continuity. Price differentiation rests on ATS/ERS traceability grade and EU MDR certification tier, with research-grade systems commanding premiums over screening-tier devices. Cost compression in portable segments intensifies as software-as-medical-device frameworks commoditize hardware. Home care providers exhibit highest price sensitivity; pharmaceutical trial sites demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese semiconductor foundries supplying MEMS pressure sensors for flow-sensing architectures. Component sourcing draws from Germany for precision pneumotachograph meshes, Switzerland for ultrasonic transducer assemblies, and Japan for heated-wire anemometry elements. Tariff exposure on Chinese-sourced electronic subassemblies threatens margin stability. Distribution runs through hospital GPO contracts in the United States, statutory health insurance procurement frameworks in Germany, and direct-to-employer occupational health channels in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 26782:2022-accredited calibration technician scarcity props pricing for certified service networks, constraining point-of-care device deployment velocity and sustaining premium-tier margin structures.
For Market Incumbents: Anticipate ultrasonic sensor commoditization by locking hospital systems into multi-year disposable supply agreements before solid-state calibration intervals become industry standard. Deepen backward integration into MEMS pressure sensor design to offset Taiwanese foundry allocation volatility. Prioritize FDA 510(k) predicate device matching investments to accelerate novel flow-sensing architecture timelines against emerging software-interpretation competitors. For New Entrants and Emerging Players: AI-interpreted waveform analysis offers a technology-first wedge into Brazilian occupational health screening, where ANVISA telehealth authorization remains underpenetrated by established cardiopulmonary platforms. Target direct-to-employer contracts in mining and construction sectors bypassing hospital procurement consolidation. Pursue cloud-connected portable systems with automated obstructive-restrictive classification as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor disposable-anchored channel controllers in German-speaking Europe, where EU MDR compliance costs filter marginal competitors. Long-term viability hinges on software-as-medical-device transition completion within a decade. Monitor JIS T 0601-1 electrical safety certification velocity as the inflection signal for protected Japanese domestic volume access.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerates market entry for novel ultrasonic flow-sensing architectures in US hospital networks. |
| CE Marking Under EU MDR | Unlocks reimbursement eligibility across German, French, and Italian statutory health insurance frameworks. |
| Hospital System Partnership | Consolidates vendor relationships through multi-year equipment service agreements replacing point-product negotiations. |
| Software Companion Development | Automates obstructive versus restrictive classification via machine learning pattern recognition integration. |
| Reimbursement Strategy | Activates remote patient monitoring codes for home care provider deployment across Medicare Advantage contracts. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR certification velocity, and Japanese PMDA electrical safety approvals anchored the trend analysis, supplemented by interviews with hospital biomedical engineers, GPO contracts managers, pulmonary function test lab directors, and occupational health clinic administrators. Secondary validation drew from FDA premarket notification databases, EU MDR conformity assessment records, CMS Medicare reimbursement code updates, and ISO 26782:2022 calibration network directories. Bottom-up device shipment tracking and top-down healthcare expenditure triangulation converged on segment-level estimates.
Input-output matrices mapped portable, desktop, and ultrasound spirometer unit economics against end-user procurement budgets across the projection horizon. Segmentation dimensions modeled include product type, flow-sensing technology, obstructive versus restrictive disease application, and care setting intensity. CAGRs emerged from logistic diffusion curves fitted to reimbursement code activation patterns and replacement-cycle velocity in German occupational health networks. Forecast inputs incorporated REACH substance restriction compliance costs and semiconductor foundry capacity utilization assumptions.
Several conditions sit outside the modeled scope, including unannounced regulatory pathway revisions, breakthrough wearable SpO2 technology displacement, and sovereign trade policy interventions affecting Taiwanese sensor supply. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Portable Ventilators Market
Medical Devices
Spain Artificial Organs and Bionic Implants Market
Medical Devices
Toe Fixation System Market
Medical Devices
Australia Clear Aligner Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
Australia Medtech Market
Medical Devices
Global Non Fusion Spinal Devices Market
Medical Devices
Wearable Insulin Pump Market
Medical Devices
Urine Collection Devices Market
Medical Devices
TMJ Implants Market
Medical Devices
Australia Insulin Delivery Devices Market
Medical Devices
Global Vessel Sealing Devices Market
Medical Devices
Global Casting Devices Market
Medical Devices
Mexico Spinal Surgery Devices Market
Medical Devices
Bioresorbable Coronary Scaffolds Market
Medical Devices
Anterior Cervical Plating Market