
 Electric Breast Pumps Market | 2026-2036
Electric Breast Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Breast Pumps Market Analysis
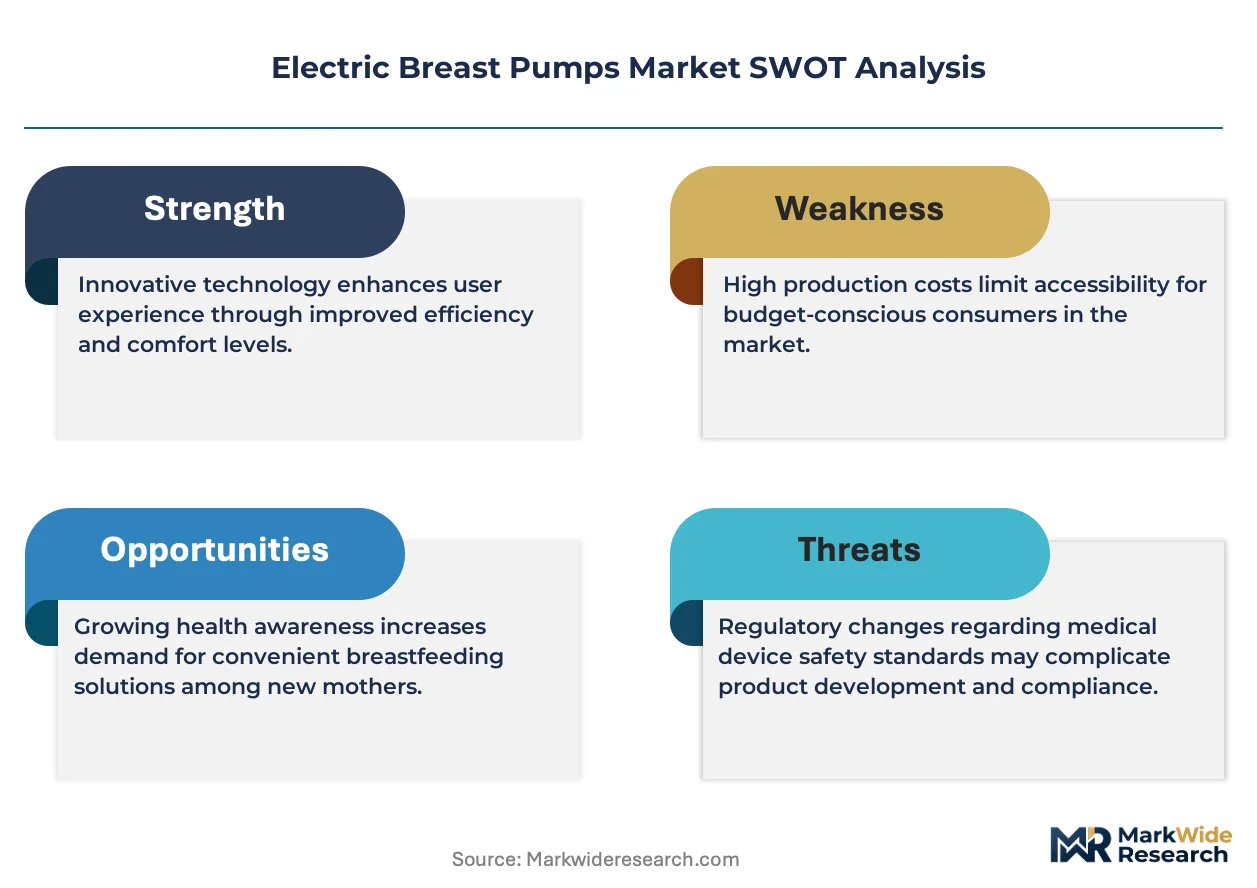
ISO 13485 certification is reorganizing competitive access in the electric breast pump sector, forcing smaller manufacturers to invest heavily in quality management systems or exit hospital supply chains entirely. Medela AG leverages its Swiss manufacturing base to sustain dual FDA and CE marking compliance across product lines. Philips Avent anchors its position through deep retail pharmacy partnerships in Western Europe, while Willow Innovations Inc. competes on proprietary wearable form factors that bypass traditional flange-based designs.
An electric breast pump is a motor-driven lactation device that generates cyclical negative pressure typically between 100 and 250 mmHg to express breast milk, incorporating either closed-system barriers to prevent contamination or open-system architectures for consumer-grade portability. Its primary commercial purpose spans personal use by mothers returning to workforce participation and clinical use in neonatal intensive care units requiring sterile collection protocols. Double electric configurations dominate unit economics in hospital settings where simultaneous bilateral expression halves staff supervision time, while wearable technology represents the fastest-growing margin pool as mothers prioritize mobility over suction strength. Smart technology integration with app-connected suction tracking is maturing fastest among direct-to-consumer channels, though closed system architecture retains pricing power in institutional procurement.
FDA 510(k) clearance pathways and the Affordable Care Act's mandatory breastfeeding equipment coverage shape product development priorities and reimbursement access across the United States market. ISO 80601-2-30 standards for physiological closed-loop controllers and IEC 60601-1 electrical safety requirements govern international market entry, with Health Canada and TGA maintaining mutual recognition agreements that streamline multi-jurisdiction launches. Stakeholders must monitor evolving state-level Medicaid expansion of wearable pump coverage, as reimbursement parity between hospital-grade rental units and personal purchase options will determine channel strategy and pricing architecture through the forecast horizon.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships around closed-system architectures, compressing supplier margins while elevating ISO 13485 certification from competitive advantage to minimum viable entry threshold.
Growth Catalysts
- Affordable Care Act mandates:Insurance reimbursement parity for breast pump equipment drives volume through durable medical equipment channels across United States commercial and Medicaid plans.
- Wearable form factor innovation:App-connected suction tracking and flange-free designs expand addressable demand among employed mothers requiring workplace mobility.
- Neonatal intensive care protocols:Simultaneous bilateral expression requirements in clinical settings standardize double electric configurations as institutional procurement default.
Market Restraints
- FDA 510(k) clearance timelines:Pre-market notification requirements extend product development cycles by 12-18 months for novel suction control algorithms.
- Silicone component concentration:Medical-grade elastomer supply chains cluster in Southeast Asian manufacturing zones, exposing producers to regional logistics volatility.
- Battery chemistry limitations:Lithium-ion cell energy density constraints restrict wearable unit operating duration below eight hours for hospital-grade suction profiles.
Strategic Opportunities
- State Medicaid wearable coverage expansion:Reimbursement parity legislation pending in California, New York, and Texas would unlock personal purchase channels for premium wearable units.
- ISO 80601-2-30 physiological closed-loop integration:Automated pressure modulation responding to milk flow feedback creates differentiation in direct-to-consumer premium tiers.
- Subscription-based consumable replenishment:Automated flange and tubing replacement programs bypass traditional retail pharmacy intermediaries.
Industry Challenges
- Biomedical engineering talent scarcity:Cross-functional expertise combining lactation physiology with pneumatic control systems concentrates in Swiss and German technical universities.
- Multi-jurisdiction certification synchronization:Health Canada, TGA, and Swissmedic mutual recognition agreements require simultaneous documentation updates across quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Breast Pumps Market |
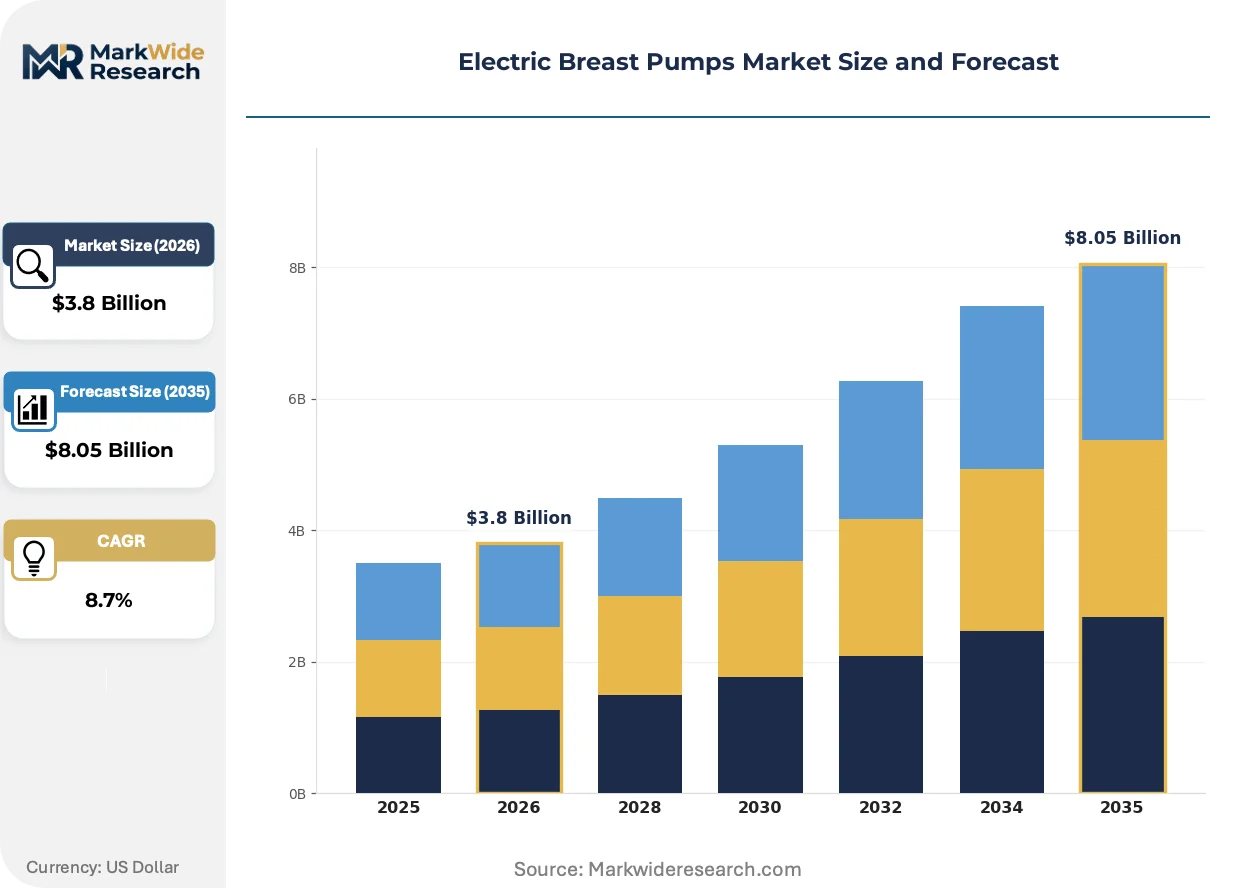
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Electric, Double Electric, Hospital-Grade, Wearable Technology: Closed System, Open System, Manual Mode, Smart Technology End User: Mothers, Hospitals, Lactation Consultants, Clinics Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | Medela AG, Philips Avent, Spectra Baby USA, Lansinoh Laboratories, Ardo Medical, Ameda Inc., Willow Innovations Inc., BabyBuddha, Elvie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Breast Pumps Market Emerging Trajectories
Smart connectivity and miniaturization are redefining performance benchmarks across personal and clinical segments, collapsing traditional distinctions between hospital-grade suction capability and consumer portability.
Wearable breast pump technology employing proprietary flange-free suction chambers is supplanting conventional double electric systems in employer-sponsored lactation benefit programs. Fortune 500 workplace wellness administrators are standardizing these units within three-year procurement cycles. The shift is compressing rental revenue models while expanding personal purchase margins through direct-to-consumer channels.
EU MDR technical documentation requirements for electrical medical devices are extending conformity assessment timelines for CE marking renewal. Manufacturers with legacy open-system designs face disproportionate clinical evidence burdens against closed-system competitors. German notified bodies are prioritizing review queues for devices with integrated contamination barriers, advantaging proactive quality system investments.
Direct employer contracting for lactation support benefits is displacing traditional insurance-mediated equipment distribution. Large self-insured employers in technology and financial services verticals are negotiating volume commitments with manufacturers for wearable unit deployment. This pattern concentrates most visibly in United States metropolitan corridors with dense corporate headquarters presence.
Electric Breast Pumps Market Segmentation
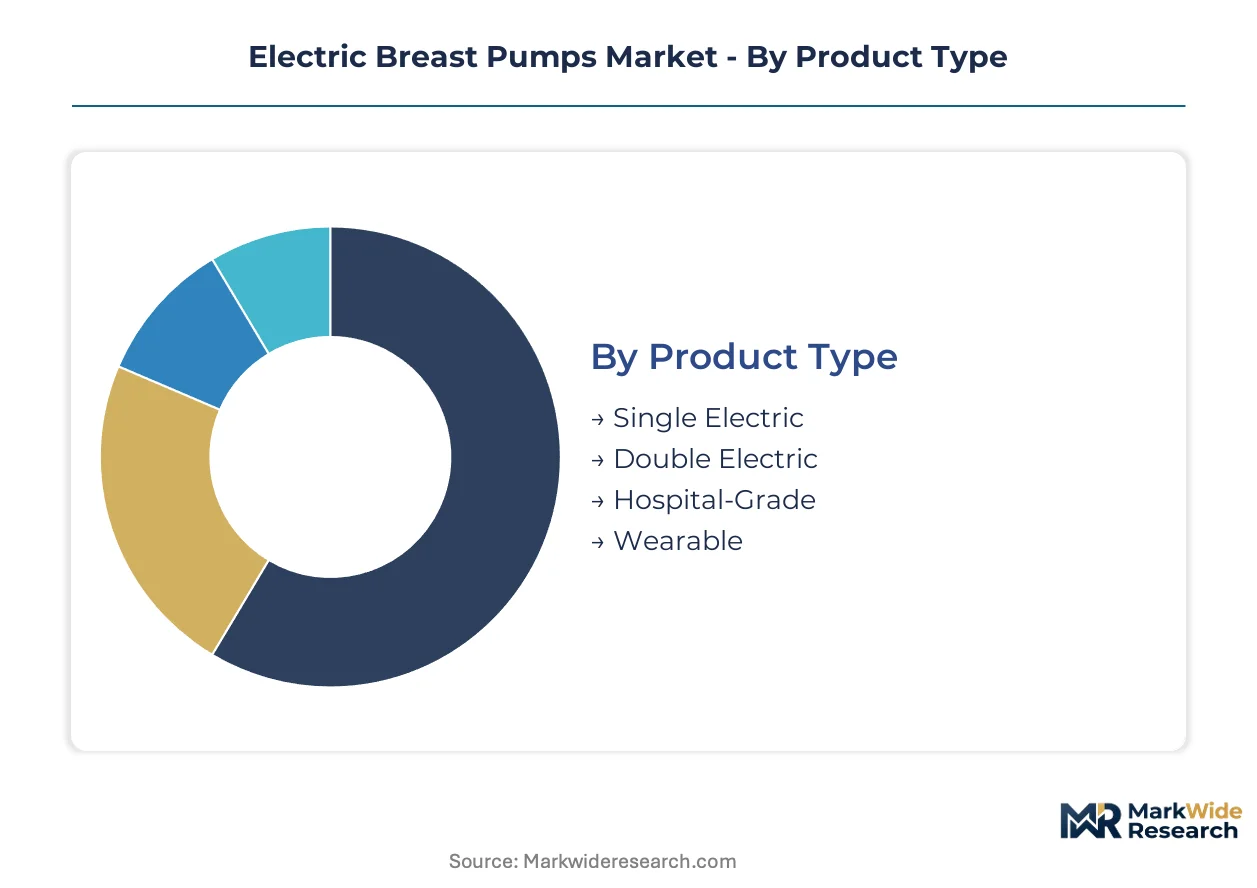
Segmentation in the electric breast pump market reveals how procurement priorities diverge between institutional buyers seeking closed-system reliability and consumers prioritizing workplace mobility. Understanding these fault lines enables manufacturers to align certification investments with channel-specific margin structures.
Product Type:
Premium margin pools concentrate in configurations that reduce supervision burden or enable ambulatory use.
- Double Electric:Simultaneous bilateral expression systems generate negative pressure through dual synchronized motors, cutting NICU staff supervision time by half. Hospital procurement departments in the United States standardize these units as default configurations under ACA-mandated equipment coverage.
- Wearable:Flange-free suction chambers integrate directly into nursing garments, eliminating external tubing. Fortune 500 employer wellness programs in technology and financial services verticals are consolidating three-year procurement cycles around these units.
- Single Electric:Unilateral motor systems serve price-sensitive personal purchase segments through retail pharmacy channels.
- Hospital-Grade:Heavy-duty rental units with enhanced suction durability dominate durable medical equipment channels for Medicaid-eligible mothers.
Double Electric holds installed capacity. Wearable is rotating up the share rankings.
Technology:
Certification burden intensity varies sharply across architecture types, with contamination barriers commanding pricing power in institutional segments.
- Closed System:Physical barriers between milk pathway and pump motor prevent bacterial contamination, satisfying ISO 13485 quality management requirements for hospital supply chain entry. FDA 510(k) clearance timelines extend 12-18 months for novel closed-loop pressure modulation algorithms.
- Smart Technology:App-connected suction tracking and flow-responsive pressure adjustment create differentiation in direct-to-consumer premium tiers. Bluetooth-enabled units are expanding fastest among employed mothers requiring workplace lactation support.
- Open System:Direct motor-milk contact designs sacrifice contamination protection for portability and cost reduction in consumer-grade segments.
- Manual Mode:Battery-independent hand-operated backup functionality addresses lithium-ion energy density constraints in wearable form factors.
Closed System dominates hospital procurement specifications. Smart Technology is climbing the fastest.
End User:
Volume concentration tracks reimbursement channel structure, with insurance-mandated equipment coverage creating distinct demand profiles.
- Hospitals:Neonatal intensive care units require sterile collection protocols and simultaneous bilateral expression capability, standardizing double electric closed-system configurations. Procurement departments are consolidating vendor relationships around ISO 13485-certified suppliers.
- Mothers:Personal use demand splits between ACA-mandated insurance coverage for rental units and direct purchase of wearable technology for workplace mobility.
- Lactation Consultants:Independent practitioners recommend specific pump configurations based on individual physiology, influencing downstream purchase decisions through consultative authority.
- Clinics:Outpatient lactation support facilities balance equipment durability against capital constraints, often selecting mid-tier double electric units.
Hospitals anchor institutional volume. Mothers are gaining share fastest through wearable adoption.
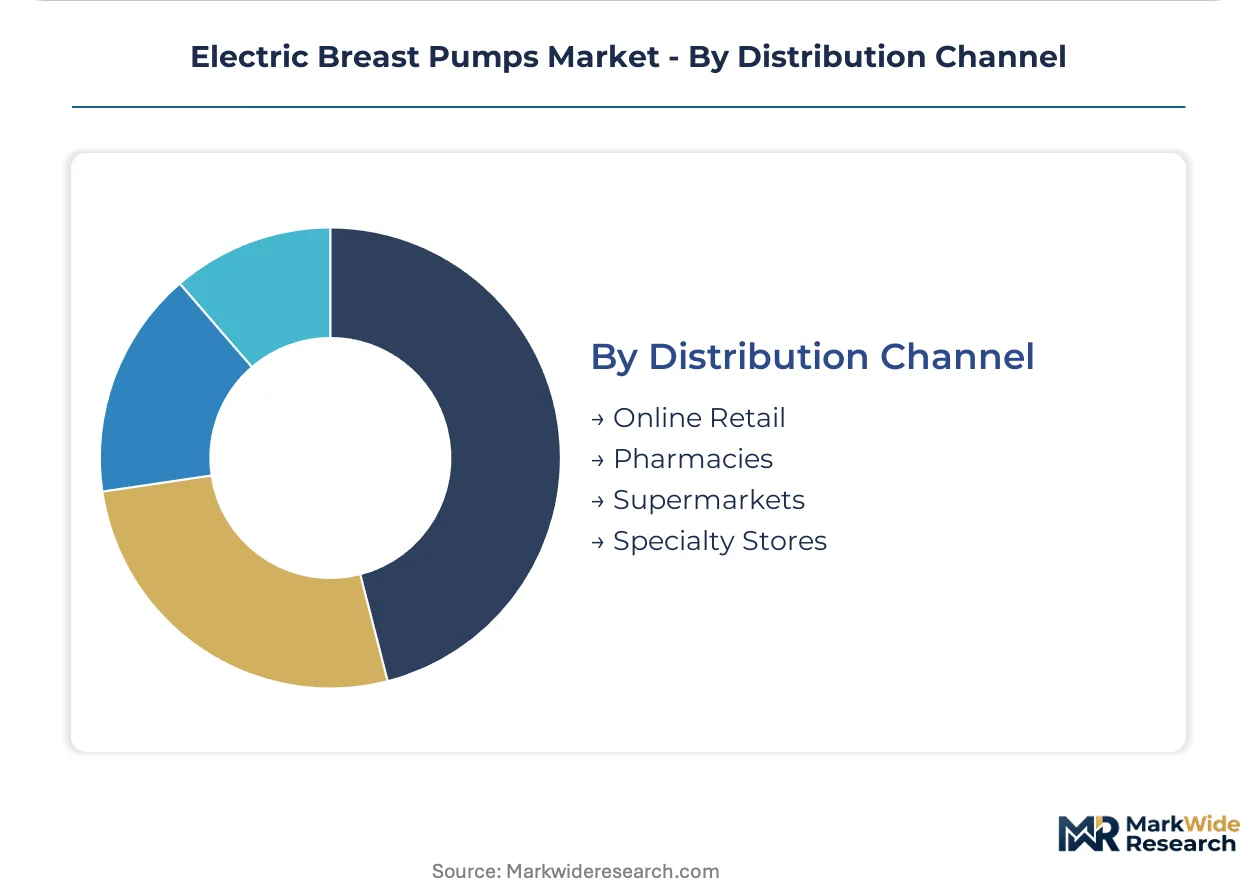
Distribution Channel:
Channel strategy determines pricing architecture, with direct employer contracting displacing traditional insurance-mediated distribution in premium segments.
- Online Retail:Direct-to-consumer platforms enable subscription-based consumable replenishment programs, bypassing traditional pharmacy intermediaries for flange and tubing replacement.
- Pharmacies:Retail pharmacy partnerships in Western Europe anchor mass-market penetration for single electric and entry-level double electric configurations.
- Specialty Stores:Maternity-focused retailers provide consultative selling environment for first-time mothers navigating product selection complexity.
- Supermarkets:Mass merchandisers capture impulse and convenience-driven purchases through limited SKU availability in consumables and accessories.
Online Retail holds transaction velocity leadership. Specialty Stores are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments and insurance reimbursement channels concentrate demand in specific national markets, with regulatory frameworks and workplace lactation policies shaping geographic expansion priorities for manufacturers.
United States
Employer-sponsored lactation benefits and ACA-mandated insurance coverage drive volume through durable medical equipment channels. FDA 510(k) clearance requirements and state-level Medicaid expansion debates in California, New York, and Texas shape market access. Corporate headquarters clusters in San Francisco Bay Area and Manhattan accelerate direct employer contracting for wearable pump deployment.
Germany
Neonatal intensive care unit standards and workplace breastfeeding protection laws under the Mutterschutzgesetz sustain institutional procurement. EU MDR technical documentation requirements and notified body prioritization for closed-system designs filter market entry. Medical device manufacturing concentrates in Baden-Württemberg around Stuttgart and Tuttlingen clusters.
United Kingdom
NHS procurement frameworks and midwife-led lactation support services standardize hospital-grade rental distribution. MHRA recognition of FDA and Health Canada approvals streamlines dual-market launches. London and Southeast England anchor retail pharmacy partnerships for consumer-grade segments.
China
Rising workforce participation among mothers and expansion of maternity care infrastructure drive personal purchase growth. NMPA Class II medical device registration requirements and GB standards compliance govern market entry. Manufacturing clusters in Guangdong Province around Shenzhen and Dongguan supply silicone components and pump motors.
Australia
Private health insurance rebate schemes and workplace lactation room mandates under Fair Work Act provisions support equipment uptake. TGA mutual recognition agreements with FDA and Health Canada reduce regulatory duplication. Sydney and Melbourne metropolitan areas concentrate lactation consultant practices influencing product recommendations.
Electric Breast Pumps Market Vendor Landscape
Player mix skews toward diversified medical device conglomerates and specialized maternal health innovators, with Swiss and German engineering heritage commanding premium positioning in institutional channels. Market structure exhibits tiered concentration: a narrow premium band anchored by ISO 13485-certified European manufacturers, a contested mid-market segment vulnerable to Asian cost competition, and an emerging direct-to-consumer tier bypassing traditional distribution. Strategic archetypes include engineering-driven closed-system specialists, retail pharmacy-anchored mass-market suppliers, and venture-backed wearable form factor disruptors. Dominant competitive moves center on M&A consolidation of component suppliers and strategic partnerships with Fortune 500 employer wellness programs.
Within the engineering-driven tier, Medela AG represents Swiss manufacturing heritage and dual FDA-CE marking compliance capabilities. Philips Avent anchors diversified medical device conglomerate positioning through deep retail pharmacy integration. Willow Innovations Inc. exemplifies venture-backed wearable disruption targeting employer direct contracting channels.
| Leading Market Players |
|---|
| Medela AG |
| Philips Avent |
| Spectra Baby USA |
| Lansinoh Laboratories |
| Ardo Medical |
| Ameda Inc. |
| Willow Innovations Inc. |
| BabyBuddha |
| Elvie |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Southeast Asian silicone component foundries shapes price floors across all pump tiers, with medical-grade elastomer contract structures indexed to petrochemical feedstock baskets. Hospital procurement consolidation around ISO 13485-certified suppliers compresses margins in institutional channels while wearable manufacturers extract premium pricing through direct-to-consumer subscription bundling.
Pricing Analysis
Cost-plus contracts with Japanese silicone suppliers carry quarterly price indexation tied to butadiene and silicone monomer benchmarks. Three-tier pricing structure across premium closed-system, standard double electric, and economy single electric levels tracks certification burden intensity. Pricing pressure stems from Fortune 500 employer wellness programs demanding volume discounts for wearable fleet deployments. Retail pharmacy channels exhibit highest price sensitivity, while NICU procurement committees prioritize contamination barrier reliability over unit cost.
Supply Chain Analysis
Inbound logistics costs from Shenzhen and Dongguan manufacturing clusters through Los Angeles and Rotterdam ports fluctuate with container availability on Asia-North America and Asia-Europe trade lanes. Component sourcing concentrates in China for silicone membranes and pump motors, Malaysia for medical-grade plastics, and Switzerland for precision pneumatic controllers. Supply chain risk centers on single-source dependency for FDA-validated silicone formulations. Distribution runs through durable medical equipment rental networks for hospital-grade units and direct-to-consumer platforms for wearable technology.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward hospital procurement departments consolidating vendor panels around closed-system architectures, with three-year contracting cycles squeezing supplier margins. This concentration demands differentiated strategic responses across incumbent, entrant, and investor archetypes.
For Market Incumbents: Consolidate component supplier relationships through backward integration into medical-grade silicone compounding or captive membrane production. Secure dual-source validation for FDA-cleared pump motor assemblies to preempt supply disruption. Defensive priority centers on ISO 13485 certification maintenance as entry barriers rise against open-system competitors.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for breakthrough suction control algorithms offer accelerated market access against legacy clearance timelines. White-space opportunity concentrates in state Medicaid wearable coverage expansion pending in California, Texas, and New York. Direct employer contracting bypasses traditional insurance channel gatekeepers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among wearable pump manufacturers with subscription-based consumable replenishment programs. Long-term viability favors targets with integrated app ecosystems and employer wellness program penetration. Signal to watch: reimbursement parity legislation advancing through state legislatures as inflection indicator for personal purchase channel expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Hospital procurement consolidation elevates quality management compliance from advantage to mandatory entry threshold. |
| Direct Employer Contracting | Fortune 500 wellness program partnerships bypass traditional insurance-mediated distribution for wearable fleet deployment. |
| Closed-Loop Pressure Algorithm Development | ISO 80601-2-30 physiological controller integration differentiates premium tiers in direct-to-consumer channels. |
| Subscription Consumable Programs | Automated flange and tubing replenishment captures recurring revenue and reduces customer acquisition costs. |
| Multi-Jurisdiction Regulatory Synchronization | Simultaneous FDA, Health Canada, and TGA submissions compress time-to-revenue across North American and Australasian markets. |
Methodological Framework
Desk research of FDA 510(k) clearance databases, hospital GPO contract repositories, and state Medicaid reimbursement filings preceded structured interviews with NICU clinical directors, durable medical equipment procurement managers, biomedical engineers, and lactation consultant practice owners. Secondary validation drew from ISO certification registries, ACA mandate implementation reports, and employer wellness program RFP documents. Bottom-up unit shipment estimates triangulated against top-down insurance claims data.
Variance decomposition across product type, technology architecture, end-user setting, and distribution channel segments shaped the analytical framework over the projection horizon. CAGRs derived from regression analysis of historical reimbursement expansion patterns and wearable adoption curves. Forecast inputs incorporated lithium-ion energy density improvement trajectories and EU MDR conformity assessment timeline projections.
Underlying assumptions cover continued ACA equipment coverage mandates, stable FDA clearance pathway durations, and silicone supply chain normalization, with deviation risk concentrated in state-level Medicaid policy reversals and battery chemistry breakthroughs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Guide Extension Catheter Market
Medical Devices
Cardiopulmonary Bypass System Market
Medical Devices
Global Vessel Sealing Devices Market
Medical Devices
Anorectal Manometry Systems Market
Medical Devices
ETCO2 Masks Market
Medical Devices
Personal-Use Facial and Skin Therapy Devices Market
Medical Devices
Global Stent Graft Balloon Catheter Market
Medical Devices
US Bathroom and Toilet Assist Devices Market
Medical Devices
South Africa Artificial Organs and Bionic Implants Market
Medical Devices
High Pressure Contrast Media Injectors Market
Medical Devices
Pulse Lavage Market
Medical Devices
Vaginal Specula Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Global Female Stress Urinary Incontinence Treatment Devices Market
Medical Devices
Urinary Flow Meters Market
Medical Devices
Venturi Mask Market