
 Ultrasound Skin Tightening Devices Market | 2026-2036
Ultrasound Skin Tightening Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasound Skin Tightening Devices Market Analytics
A shift from single-source component procurement to multi-source supply strategies is recalibrating how ultrasound skin tightening device manufacturers manage transducer arrays and cooling system costs. Ulthera Inc. leverages its proprietary micro-focused ultrasound platform to sustain premium positioning across North American dermatology networks. Alma Lasers Ltd. anchors its competitive stance through integrated software-hardware ecosystems that streamline treatment protocols for clinic operators. Beijing ADSS Development Co. Ltd. competes on manufacturing scale, offering modular device architectures that reduce capital outlay for emerging market buyers.
Ultrasound skin tightening devices generate controlled thermal coagulation points at depths of 1.5 mm to 4.5 mm within the dermis and superficial muscular aponeurotic system, triggering neocollagenesis without epidermal disruption. Their primary commercial purpose centers on delivering measurable tissue lifting outcomes for patients seeking alternatives to surgical intervention. Focused ultrasound systems occupy the dominant revenue position due to superior depth precision and established clinical validation, while combination devices integrating radiofrequency represent the fastest-expanding category as operators pursue dual-modality treatment efficiency. Dermatology centers command the highest per-site equipment spend among end-user channels, reflecting procedure volume concentration and reimbursement dynamics that favor physician-supervised settings over spa environments.
The US FDA regulates these devices under 510(k) premarket notification pathways for non-ablative dermatological applications, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa and IIb energy-based systems. China's NMPA implements GB standards for medical electrical equipment that manufacturers must satisfy for domestic market access, creating divergent testing protocols across major commercial jurisdictions. Stakeholders must monitor evolving notified body capacity constraints in Europe and shifting reimbursement classifications for aesthetic procedures in Asian markets to anticipate capital deployment timelines and geographic prioritization decisions.
Market Dynamics
Multi-source procurement strategies are recalibrating manufacturer relationships with transducer array and cooling system suppliers, compressing component lead times while elevating quality assurance overhead across ultrasound skin tightening device supply chains.
Growth Catalysts
- MFU technology maturation:Micro-focused ultrasound platforms now deliver consistent thermal coagulation at 4.5 mm depths, satisfying dermatology networks seeking surgical alternatives with measurable lifting outcomes.
- Seoul clinical cluster expansion:Medical spas and dermatology chains in South Korea are accelerating device procurement for non-invasive facial tightening protocols, establishing procedure volume benchmarks for Asian markets.
- 510(k) pathway clarity:The US FDA's established premarket notification framework for non-ablative energy-based devices provides regulatory certainty that accelerates capital deployment timelines for North American manufacturers.
Market Restraints
- Transducer array supply concentration:Precision piezoelectric component manufacturing clusters in East Asia create geographic vulnerability for device assemblers seeking dual-source qualification.
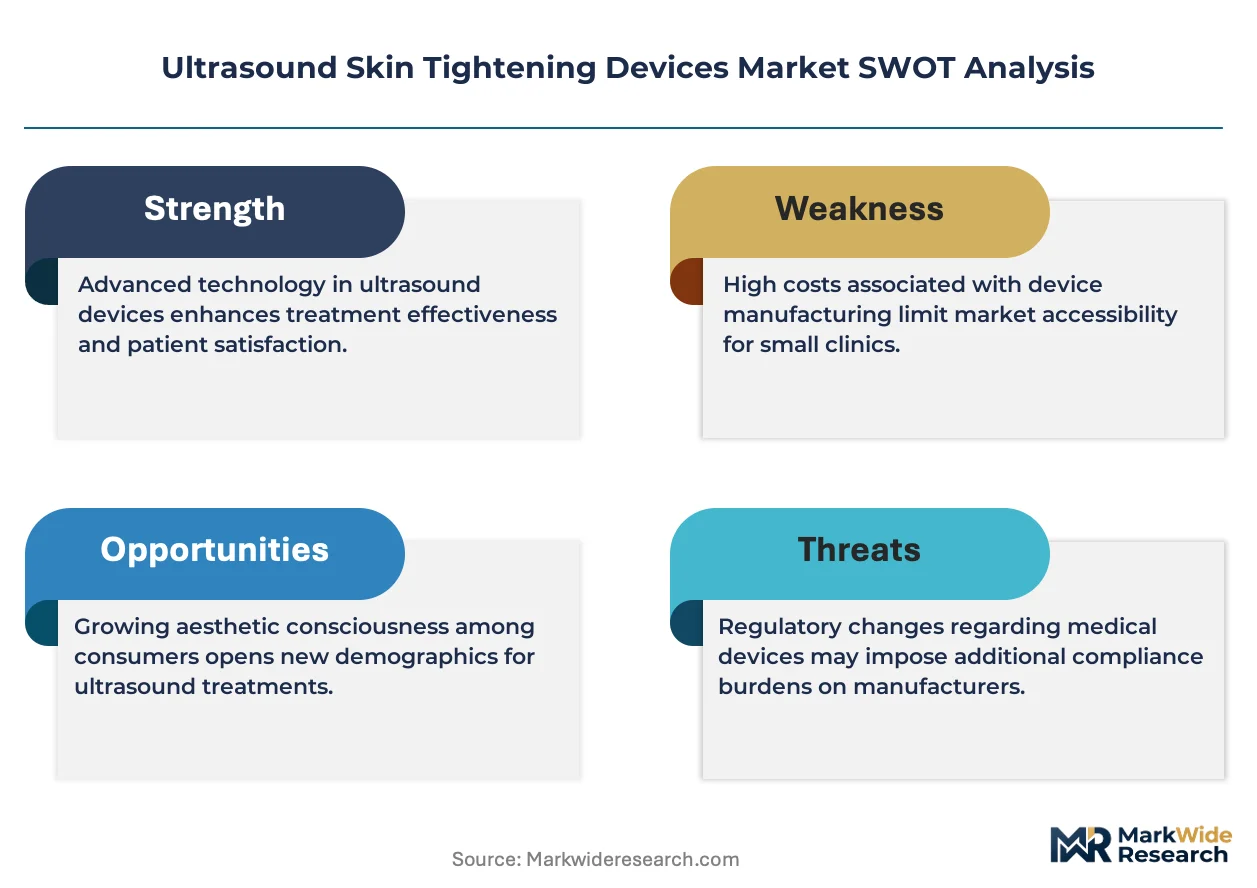
- EU MDR clinical evidence burdens:Stricter notified body requirements for Class IIb energy-based systems extend certification timelines and elevate documentation costs for European market entry.
- Radiofrequency substitution pressure:Combination devices integrating RF modalities compete for capital allocation within clinic budgets, fragmenting pure-play ultrasound demand.
Strategic Opportunities
- Brazil aesthetic market penetration:ANVISA regulatory pathways for Class II medical devices present underexploited entry points for manufacturers seeking Latin American expansion beyond saturated North American corridors.
- Dual-modality platform development:Convergence of focused ultrasound with fractional radiofrequency enables single-device treatment efficiency that commands premium positioning in high-volume dermatology centers.
- India PLI scheme alignment:Production-linked incentive frameworks for medical electronics manufacturing offer cost-offset mechanisms for regional assembly operations targeting price-sensitive emerging market segments.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in acoustic wave physics and thermal tissue modeling remains concentrated among legacy device manufacturers, constraining R&D scaling for mid-tier competitors.
- Legacy cooling system integration:Contact cooling module compatibility with next-generation transducer architectures requires substantial redesign cycles that delay product platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasound Skin Tightening Devices Market |
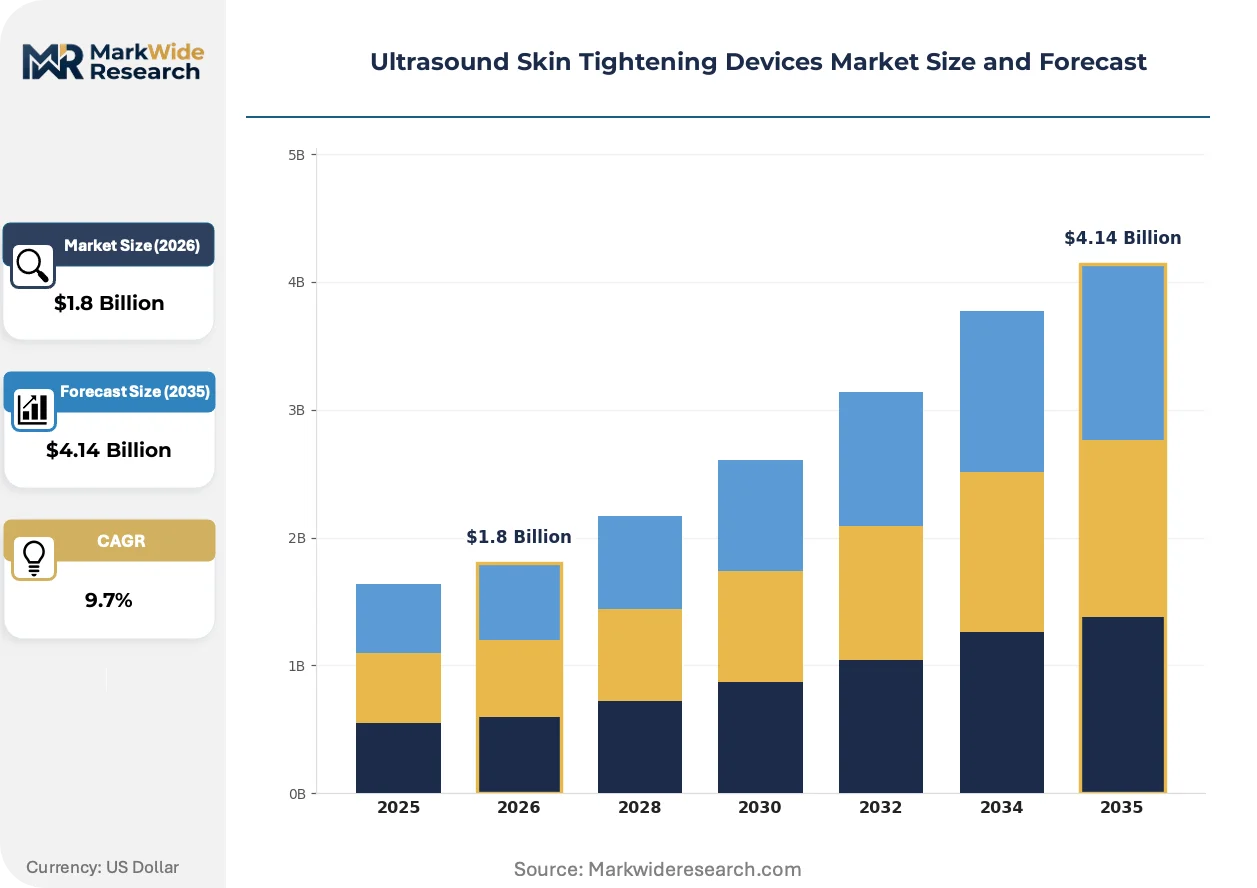
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Focused Ultrasound, Radiofrequency Devices, Combination Devices, Laser Systems End User: Clinics, Hospitals, Spas, Dermatology Centers Technology: Non-Invasive Techniques, Minimally Invasive Techniques, Micro-Needling, Thermal Therapy Application: Facial Tightening, Body Contouring, Wrinkle Reduction, Skin Rejuvenation |
| Companies Covered | Ulthera Inc., Merz Aesthetics, Lumenis Inc., Cynosure LLC, Alma Lasers Ltd., Beijing ADSS Development Co. Ltd., Daeyang Medical Co. Ltd., Guangzhou Beautylife Electronic Technology Co. Ltd., Lumasail Industrial Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasound Skin Tightening Devices Market Evolving Landscape
Real-time imaging guidance systems are compressing treatment variability and elevating outcome consistency across ultrasound skin tightening protocols, reshaping competitive differentiation toward software-hardware integration depth.
Micro-focused ultrasound with integrated visualization is electrifying precision delivery in facial tightening applications. Dermatology centers in California and New York are adopting these platforms at accelerated replacement cycles. The technology is electrifying premium positioning by collapsing the expertise gap between novice operators and experienced clinicians.
The EU Medical Device Regulation's expanded clinical evidence requirements for energy-based systems are elevating notified body backlogs and extending certification timelines. Manufacturers are responding by front-loading post-market surveillance infrastructure. Dermatology-focused device categories face the steepest compliance cost escalation as Class IIb reclassification sweeps broader product portfolios.
After-sales service unbundling is fragmenting traditional capital-plus-maintenance contracting models. Independent service organizations in Florida and Texas are capturing calibration and transducer replacement revenue streams previously captive to original equipment manufacturers. This shift concentrates in coastal metropolitan markets where clinic density supports third-party technician specialization.
Ultrasound Skin Tightening Devices Market Segmentation
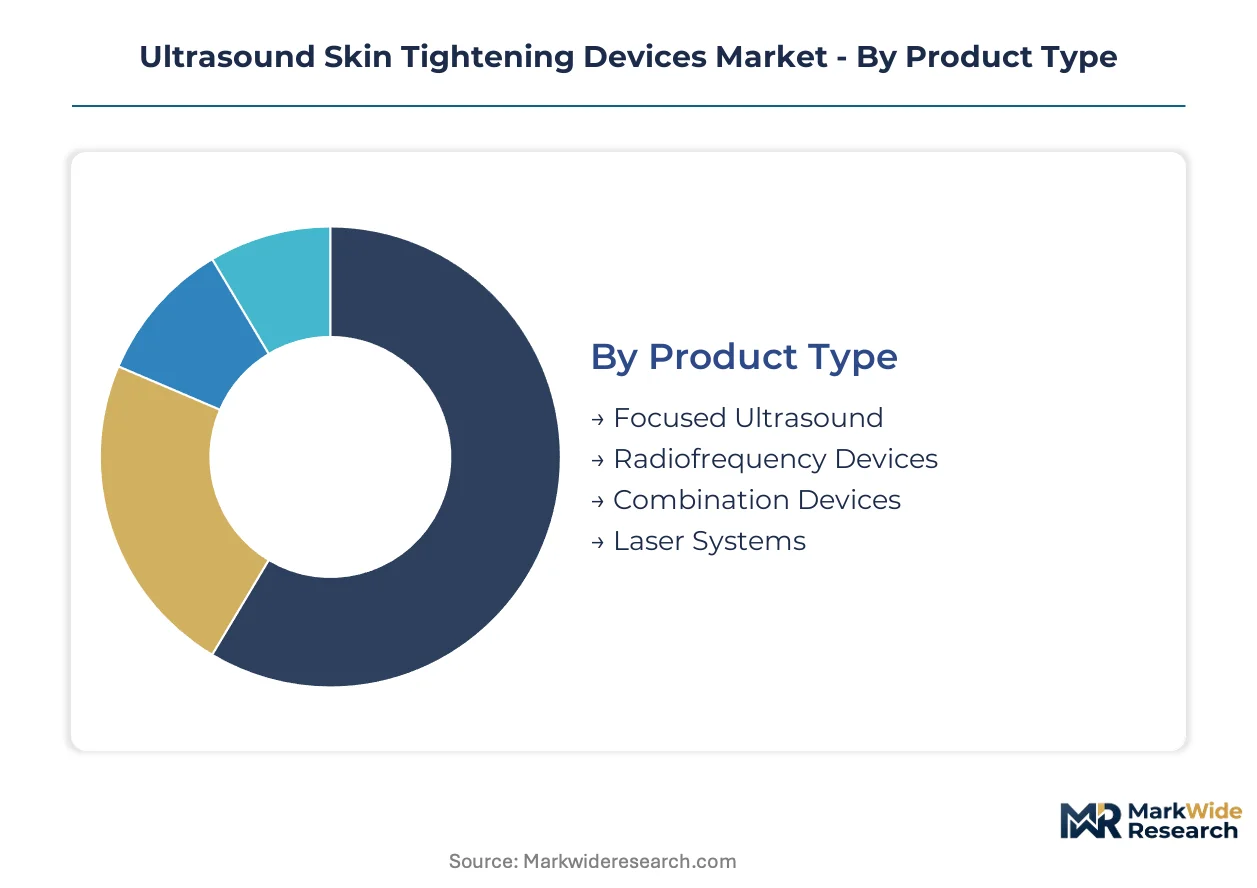
Segmentation in ultrasound skin tightening devices reveals how treatment depth, operator setting, and patient anatomy dictate hardware specifications and procurement priorities. Device manufacturers calibrate transducer arrays, cooling systems, and software protocols differently across each dimension, creating distinct competitive battlegrounds.
Product Type:
Standardized platforms dominate high-volume channels while customizable configurations capture premium positioning in specialized dermatology networks.
- Focused Ultrasound:Micro-focused acoustic energy platforms generate thermal coagulation points at 1.5 mm to 4.5 mm depths with millimeter precision. Demand concentrates in California and New York dermatology centers where surgical alternatives command premium pricing and outcome documentation requirements are strictest.
- Combination Devices:Integrated ultrasound-radiofrequency systems enable sequential or simultaneous energy delivery through single handpiece architectures. Seoul medical spas are accelerating procurement of these dual-modality platforms to compress treatment times and maximize hourly throughput per treatment room.
- Radiofrequency Devices:Monopolar and bipolar RF systems compete for capital allocation in price-sensitive clinic segments.
- Laser Systems:Non-ablative fractional lasers occupy adjacent budget categories with overlapping facial tightening indications.
Leading the category by volume: Focused Ultrasound. Growing fastest: Combination Devices.
End User:
Capital intensity and reimbursement dynamics separate institutional buyers from commercial operators across procurement patterns.
- Dermatology Centers:Physician-supervised facilities command the highest per-site equipment spend, driven by procedure volume concentration and liability frameworks that favor documented clinical outcomes. These buyers prioritize FDA-cleared platforms with established 510(k) predicates and comprehensive training protocols.
- Clinics:Multi-service aesthetic practices balance device versatility against capital efficiency, favoring modular platforms with swappable transducer cartridges. Procurement concentrates in Florida and Texas metropolitan corridors where clinic density supports aggressive equipment financing terms.
- Hospitals:Academic medical centers and outpatient surgery departments integrate skin tightening into broader cosmetic surgery portfolios.
- Spas:Non-medical wellness facilities face stricter scope-of-practice limitations on energy-based device operation.
Highest capital deployment per site: Dermatology Centers. Expanding most quickly: Clinics.
Technology:
Regulatory classification and operator credentialing requirements stratify adoption across technical complexity tiers.
- Non-Invasive Techniques:Surface-applied energy delivery without epidermal breach dominates commercial volume, anchored by established safety profiles and minimal downtime protocols. China's NMPA GB standard compliance and US FDA 510(k) pathways have created predictable market access frameworks that accelerate manufacturer scaling.
- Minimally Invasive Techniques:Subdermal energy delivery through micro-incision access points targets patients seeking amplified outcomes beyond surface-limited modalities. Adoption clusters in South Korean and Brazilian markets where procedural innovation spreads rapidly through demonstration-focused clinical training networks.
- Micro-Needling:Mechanical perforation combined with energy delivery occupies niche positioning between purely non-invasive and surgical alternatives.
- Thermal Therapy:Broad heating protocols without focused targeting face substitution pressure from precision ultrasound platforms.
Widest regulatory clearance: Non-Invasive Techniques. Steepest expansion trajectory: Minimally Invasive Techniques.
Application:
Anatomical treatment zone and outcome measurability shape device specification requirements and pricing power.
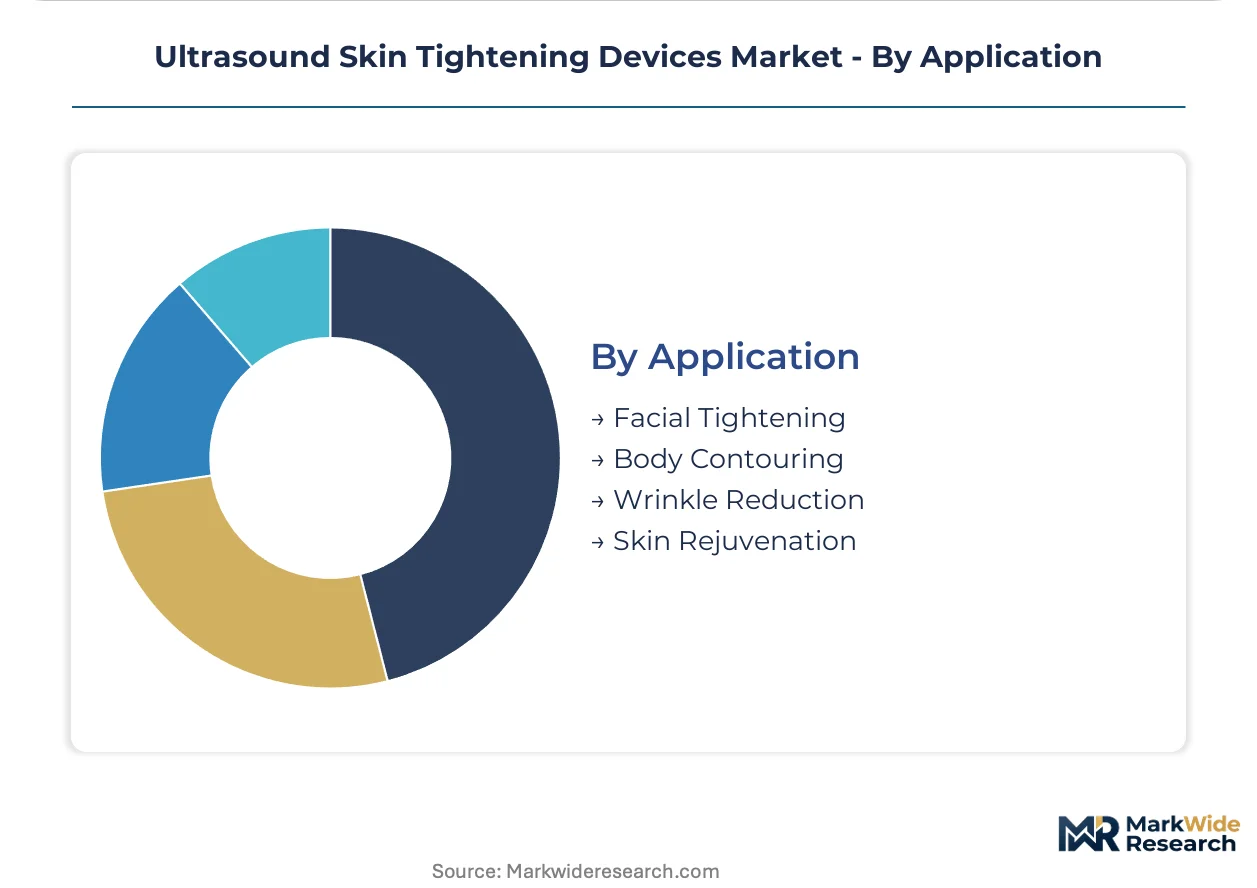
- Facial Tightening:Precision targeting of superficial muscular aponeurotic system layers at 3.0 mm to 4.5 mm depths represents the most clinically validated application with established lifting outcome metrics. Seoul and Los Angeles clinical clusters have generated procedure volume benchmarks that drive platform development roadmaps.
- Body Contouring:Larger treatment surface areas and deeper tissue penetration requirements demand higher-powered transducer arrays with enhanced cooling capacity. European adoption under EU MDR Class IIb frameworks is elevating clinical evidence requirements that favor manufacturers with robust post-market surveillance infrastructure.
- Wrinkle Reduction:Superficial dermal targeting at 1.5 mm depths competes with injectable alternatives.
- Skin Rejuvenation:Broad collagen remodeling indications face fragmentation across multiple energy modality categories.
Largest addressable population: Facial Tightening. Gaining share fastest: Body Contouring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision piezoelectric component manufacturing concentrates in East Asian industrial corridors, anchoring device assembly networks across multiple commercial jurisdictions. Divergent regulatory frameworks in the United States, European Union, China, South Korea, and Brazil shape capital deployment patterns and certification timelines for manufacturers seeking multi-market presence.
United States
Coastal metropolitan markets in California, New York, and Florida drive dermatology center procurement for physician-supervised facial tightening protocols. The FDA's 510(k) premarket notification pathway provides established regulatory certainty for non-ablative energy-based devices, though tightening clearance requirements elevate compliance documentation burdens. Los Angeles and New York clinical clusters generate procedure volume benchmarks that influence platform development roadmaps for North American manufacturers.
South Korea
Seoul's medical spa and dermatology chain expansion accelerates device procurement for non-invasive facial tightening applications, establishing Asian market volume benchmarks. The MFDS regulates energy-based aesthetic systems under medical device frameworks that align with international standards while maintaining domestic testing protocols. The Seoul Capital Area concentration of aesthetic clinics supports aggressive equipment financing terms and accelerated replacement cycles for visualization-integrated platforms.
China
Domestic manufacturing scale advantages position regional assemblers to serve price-sensitive emerging market segments through modular device architectures. The NMPA implements GB standards for medical electrical equipment that create divergent testing protocols from Western regulatory frameworks, extending market access timelines for foreign manufacturers. Yangtze River Delta and Pearl River Delta industrial zones concentrate precision component fabrication capacity that supplies transducer array requirements across the sector.
Germany
Notified body capacity constraints under the EU MDR extend certification timelines for Class IIb energy-based systems entering the European market. The country's aesthetic medicine networks prioritize platforms with comprehensive post-market surveillance infrastructure to satisfy expanded clinical evidence requirements. Bavaria and Baden-Württemberg host specialized biomedical engineering talent pools concentrated among legacy device manufacturers.
Brazil
ANVISA regulatory pathways for Class II medical devices present underexploited entry points for manufacturers seeking Latin American expansion beyond saturated North American corridors. São Paulo and Rio de Janeiro clinical training networks accelerate procedural innovation adoption through demonstration-focused education models. The country's aesthetic medicine market favors dual-modality platforms that maximize hourly throughput per treatment room.
Ultrasound Skin Tightening Devices Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to compress transducer array lead times and secure cooling system supply continuity. The vendor base stratifies across three tiers: legacy platforms with established 510(k) predicates, integrated software-hardware ecosystems, and scale-driven modular architectures. Competitive positioning hinges on regulatory clearance breadth, training protocol depth, and after-sales service infrastructure density. Technology licensing agreements and geographic distribution partnerships represent the dominant competitive moves as firms navigate divergent certification requirements across commercial jurisdictions.
Within the integrated ecosystem tier, Alma Lasers Ltd. and Ulthera Inc. exemplify contrasting approaches to software-hardware convergence for clinic operators. Beijing ADSS Development Co. Ltd. occupies a position among scale-driven fabricators targeting emerging market price sensitivity through modular capital outlay structures. These three anchors illustrate how competitive differentiation fragments across premium positioning, regulatory depth, and manufacturing scale vectors rather than concentrating around single capability advantages.
| Leading Market Players |
|---|
| Ulthera Inc. |
| Merz Aesthetics |
| Lumenis Inc. |
| Cynosure LLC |
| Alma Lasers Ltd. |
| Beijing ADSS Development Co. Ltd. |
| Daeyang Medical Co. Ltd. |
| Guangzhou Beautylife Electronic Technology Co. Ltd. |
| Lumasail Industrial Inc. |
| Others |
Value Network & Pricing Analysis
Precision piezoelectric ceramic costs cascade through ultrasound skin tightening device manufacturing, with transducer array fabrication in East Asian industrial zones feeding three-tier pricing structures that separate FDA-cleared premium platforms from modular economy configurations in emerging markets.
Pricing Analysis
Warranty and calibration service bundling separates premium dermatology center contracts from unbundled capital-plus-maintenance arrangements favored by high-volume clinic chains. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) predicate depth, visualization software integration, and after-sales infrastructure density. Price differentiation hinges on certification tier and geographic service coverage, with coastal metropolitan buyers showing lowest price sensitivity due to procedure volume concentration. Cost compression in economy-tier modular devices is intensifying because Chinese assemblers are capturing component sourcing efficiencies.
Supply Chain Analysis
India's PLI scheme for medical electronics manufacturing is reshaping sourcing calculus for regional assembly operations targeting price-sensitive segments. Transducer array fabrication concentrates in China, South Korea, and Japan, with cooling system components drawing from Taiwan and Germany. Raw material dependencies span precision piezoelectric ceramics, sapphire acoustic windows, and medical-grade aluminum housings. Single-source vulnerability in East Asian precision component clusters elevates qualification timelines for dual-source strategies. Distribution runs through authorized dealer networks in North America and direct manufacturer relationships in Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultrasound skin tightening devices are transitioning from standalone MFU platforms toward integrated visualization-guided systems, with real-time imaging software displacing legacy operator-dependent protocols across dermatology networks.
For Market Incumbents: Anchor premium positioning through proprietary software-hardware ecosystems that compress treatment variability and elevate outcome consistency. Deepen backward integration into transducer array fabrication to secure supply continuity against East Asian concentration risk. Prioritize post-market surveillance infrastructure investment to satisfy EU MDR expanded clinical evidence requirements for Class IIb reclassification.
For New Entrants and Emerging Players: ANVISA's streamlined Class II medical device pathways in Brazil open a window for Latin American market entry before saturation reaches North American levels. Target São Paulo and Rio de Janeiro clinical training networks with dual-modality platforms that maximize hourly throughput per treatment room. Pursue white-space capture in India's production-linked incentive-aligned regional assembly for price-sensitive emerging market segments.
For Investors and Strategic Acquirers: FDA 510(k) clearance backlogs extending beyond historical norms is the leading indicator that regulatory depth is becoming the primary scarcity factor in competitive positioning. Focus acquisition screening on mid-tier manufacturers with predicate device portfolios and notified body relationships in Europe. Watch for consolidation signals when transducer array supply concentration forces capital deployment into captive component fabrication.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Modality Platform Development | Convergence of MFU with fractional RF commands premium positioning in Seoul and Los Angeles dermatology centers. |
| Software Companion Development | Real-time imaging guidance elevates outcome consistency and collapses expertise gaps between novice and experienced operators. |
| CE Marking Pathway Investment | EU MDR Class IIb compliance extends certification timelines, favoring manufacturers with front-loaded clinical evidence infrastructure. |
| Hospital System Partnership | Academic medical center integration anchors physician-supervised credibility and procedure volume concentration. |
| Reimbursement Strategy | Documented clinical outcomes in SMAS-layer targeting support favorable classification dynamics in Asian aesthetic medicine markets. |
Research Methodology
Document review covered FDA 510(k) premarket notification databases, EU MDR technical documentation requirements, and MFDS domestic testing protocols, complemented by interviews with dermatology clinic operators, biomedical engineering directors at device manufacturers, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from customs trade data for precision piezoelectric component flows, SEC filings of publicly traded aesthetic device companies, and hospital procurement database records. Bottom-up segmentation modeling triangulated against top-down market sizing across product type, end user, technology, and application dimensions.
Historical procedure volume trajectories in Seoul, Los Angeles, and New York clinical clusters were cross-referenced against panel input from equipment financing specialists and distributor channel partners. The analytical framework modeled adoption patterns across the projection horizon by treatment depth specification, operator setting credentialing requirements, and patient anatomy segmentation. CAGRs were derived from installed base expansion rates and replacement cycle compression in visualization-integrated platforms. Forecast inputs incorporated regulatory clearance timeline assumptions and reimbursement classification shifts in Asian markets.
The model assumes a particular technology adoption path favoring integrated ultrasound-RF convergence; alternative pathways for standalone MFU platform refinement would alter the outlook for pure-play manufacturers. Forecasts reflect assumptions regarding notified body capacity normalization in Europe and PLI scheme continuity in India. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Contact Thermometer Market
Medical Devices
Minimally Invasive Deformity Correction System Market
Medical Devices
I.V. Fluid Warmer Market
Medical Devices
In Vitro and in Vivo Microelectrode Array Market
Medical Devices
Self-Destructing Syringe Market
Medical Devices
Intravenous Line Connectors Market
Medical Devices
Breast Pump Flange Market
Medical Devices
China Drug Delivery Devices Market
Medical Devices
Australia Artificial Organs and Bionic Implants Market
Medical Devices
China Aesthetic Devices Market
Medical Devices
Pulmonology Lasers Market
Medical Devices
Bone Allografts Market
Medical Devices
North America Wheelchair Market
Medical Devices
Nasal Atomizer Devices Market
Medical Devices
Cystic Fibrosis Devices Market
Medical Devices
Intravascular Temperature Management Systems Market