
 Extended Release Drugs Market | 2026-2036
Extended Release Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Extended Release Drugs Market Foresight
FDA New Drug Application requirements for bioequivalence and dissolution profile validation is redrawing competitive boundaries in extended release formulations. Pfizer leverages its manufacturing scale across multiple dosage forms to sustain leadership in matrix-based delivery. Janssen Pharmaceuticals anchors its position through R&D intensity in mental health applications. Teva Pharmaceuticals competes aggressively on cost structure in the generic extended release segment.
Extended release drugs employ polymeric matrices, semipermeable membranes, or ion-exchange resins to modulate active pharmaceutical ingredient release over hours to days, achieving therapeutic plasma concentrations with reduced dosing frequency. Matrix systems dominate current volume due to lower manufacturing complexity, while osmotic systems command premium positioning for narrow therapeutic index compounds. Pain management applications represent the largest therapy area by installed patient base, though diabetes formulations show the fastest volume trajectory as basal insulin analogs expand. Oral administration remains the primary route, yet transdermal patches capture disproportionate margin pools in chronic pain and hormonal therapy.
The FDA enforces dissolution testing standards under USP Chapter 711, while EMA's Quality Target Product Profile guidelines shape European development pathways, and Japan's PMDA mandates localized pharmacokinetic bridging studies for foreign sponsors. These frameworks elevate capital requirements for new entrants and privilege manufacturers with established regulatory dossier capabilities. Stakeholders must monitor emerging guidance on real-world evidence requirements for formulation switching and bioequivalence determination.
Market Dynamics
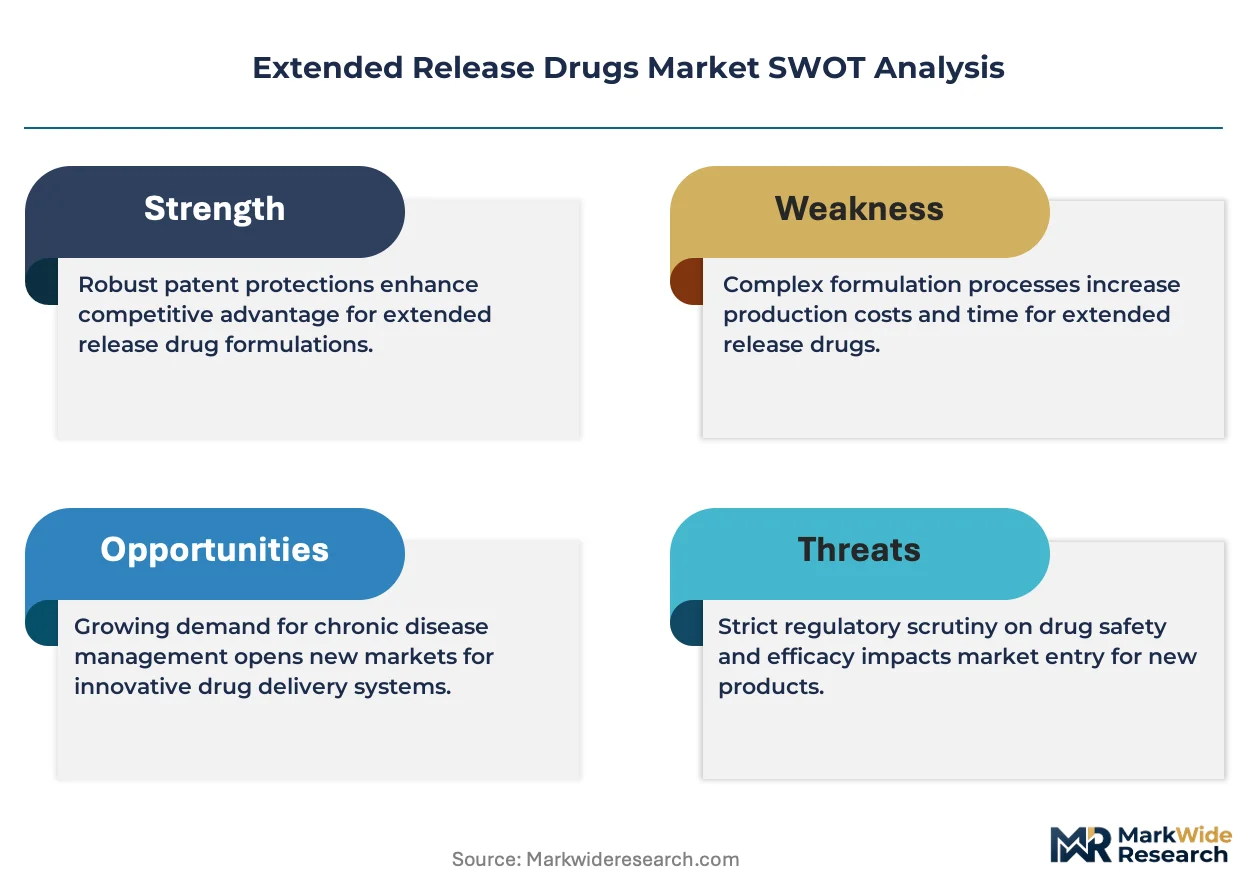
FDA's Quality by Design framework and EMA's Quality Target Product Profile guidelines are elevating capital barriers for new entrants while privileging manufacturers with established regulatory dossier capabilities and validated dissolution testing infrastructure.
Growth Catalysts
- Aging demographics in Germany, Japan, and Brazil:Expanding chronic disease patient pools intensify demand for once-daily formulations that improve medication adherence in long-term therapy management.
- Advances in osmotic pump technology:Precision-controlled release mechanisms enable narrow therapeutic index compounds to achieve stable plasma concentrations previously unattainable with conventional matrix systems.
- USP Chapter 711 dissolution testing standards:Harmonized analytical methods reduce regulatory friction for sponsors pursuing multi-jurisdiction approvals, accelerating time-to-market for validated formulations.
Market Restraints
- Specialized excipient supply concentration:High-purity hydroxypropyl methylcellulose and polyethylene oxide production clusters in limited manufacturing corridors, exposing formulators to input volatility.
- Bioequivalence validation complexity:FDA's stringent pharmacokinetic bridging study requirements for formulation modifications extend development timelines and inflate clinical program costs.
- Transdermal patch manufacturing scale limitations:Multi-layer lamination and precision coating capabilities remain concentrated among contract manufacturers with validated sterile production lines.
Strategic Opportunities
- Basal insulin analog expansion in diabetes:Extended-release injectable formulations capture volume trajectory as patient populations shift from prandial to long-acting glucose management protocols.
- PMDA localized pharmacokinetic bridging pathways:Streamlined approval routes for foreign sponsors with existing FDA or EMA dossiers reduce Japan market entry friction.
- Transdermal hormonal therapy channel development:Direct-to-specialist distribution models bypass traditional pharmacy networks, capturing margin pools in menopause and contraceptive applications.
Industry Challenges
- Formulation scientist talent scarcity:Cross-disciplinary expertise in polymer rheology, pharmacokinetic modeling, and regulatory science concentrates among experienced professionals nearing retirement.
- Legacy equipment integration with continuous manufacturing:Batch-to-continuous process transitions require substantial capital redeployment and validation protocol redevelopment.
- Real-world evidence requirements for formulation switching:Emerging FDA guidance on bioequivalence determination using observational data demands new analytical infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extended Release Drugs Market |
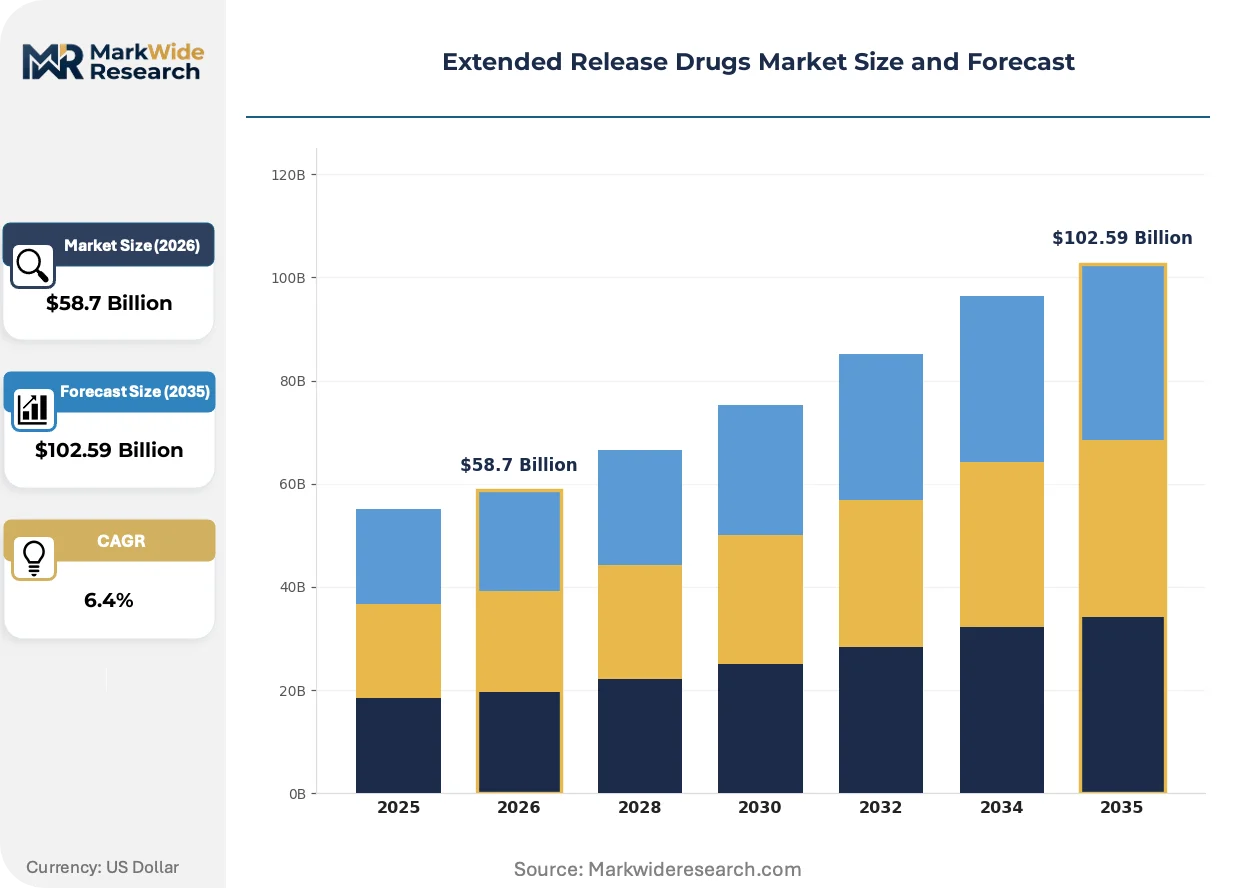
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $102.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Dosage Form: Tablets, Capsules, Solutions, Inhalers Therapy Area: Pain Management, Mental Health, Cardiovascular, Diabetes Route of Administration: Oral, Rectal, Transdermal, Inhalation Delivery Mechanism: Matrix Systems, Coated Systems, Osmotic Systems, Others |
| Companies Covered | Pfizer, Endo Pharmaceuticals, Janssen Pharmaceuticals, Mallinckrodt, Viatris, Teva Pharmaceuticals, AstraZeneca, Novartis, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extended Release Drugs Market Shifts & Advancements
Osmotic pump architectures are actively displacing conventional matrix systems in premium therapeutic categories, while regulatory convergence around quality-by-design principles and shifting procurement patterns in institutional channels reshape competitive positioning.
OROS (Osmotic Release Oral System) technology employs semipermeable membrane-controlled drug release through laser-drilled precision orifices, delivering zero-order kinetics independent of gastrointestinal pH and motility. Specialty clinics and hospital systems in the United States are adopting these formulations for narrow therapeutic index compounds at accelerating pace. This architecture is supplanting matrix-based delivery in pain management and cardiovascular applications where plasma concentration stability directly correlates with therapeutic outcomes and safety margins.
EMA's Quality Target Product Profile guidelines now mandate predefined critical quality attributes and design space establishment prior to clinical trial initiation, embedding risk assessment into early development phases. European sponsors must demonstrate multivariate understanding of formulation parameters affecting dissolution performance before regulatory submission acceptance. Small and mid-cap developers without established quality systems face disproportionate compliance burden, consolidating dossier preparation capabilities among experienced regulatory affairs consultancies and larger manufacturers.
Institutional procurement in United States hospitals is consolidating formulary decisions through pharmacy and therapeutics committees with centralized generic substitution authority. These committees increasingly mandate therapeutic equivalence documentation beyond minimum FDA requirements, pressuring manufacturers to invest in additional comparative pharmacokinetic studies. The behavioral shift is most visible in mental health applications where Janssen Pharmaceuticals and Teva Pharmaceuticals compete for preferred status through extended clinical data packages and adherence support program bundling.
Extended Release Drugs Market Segmentation
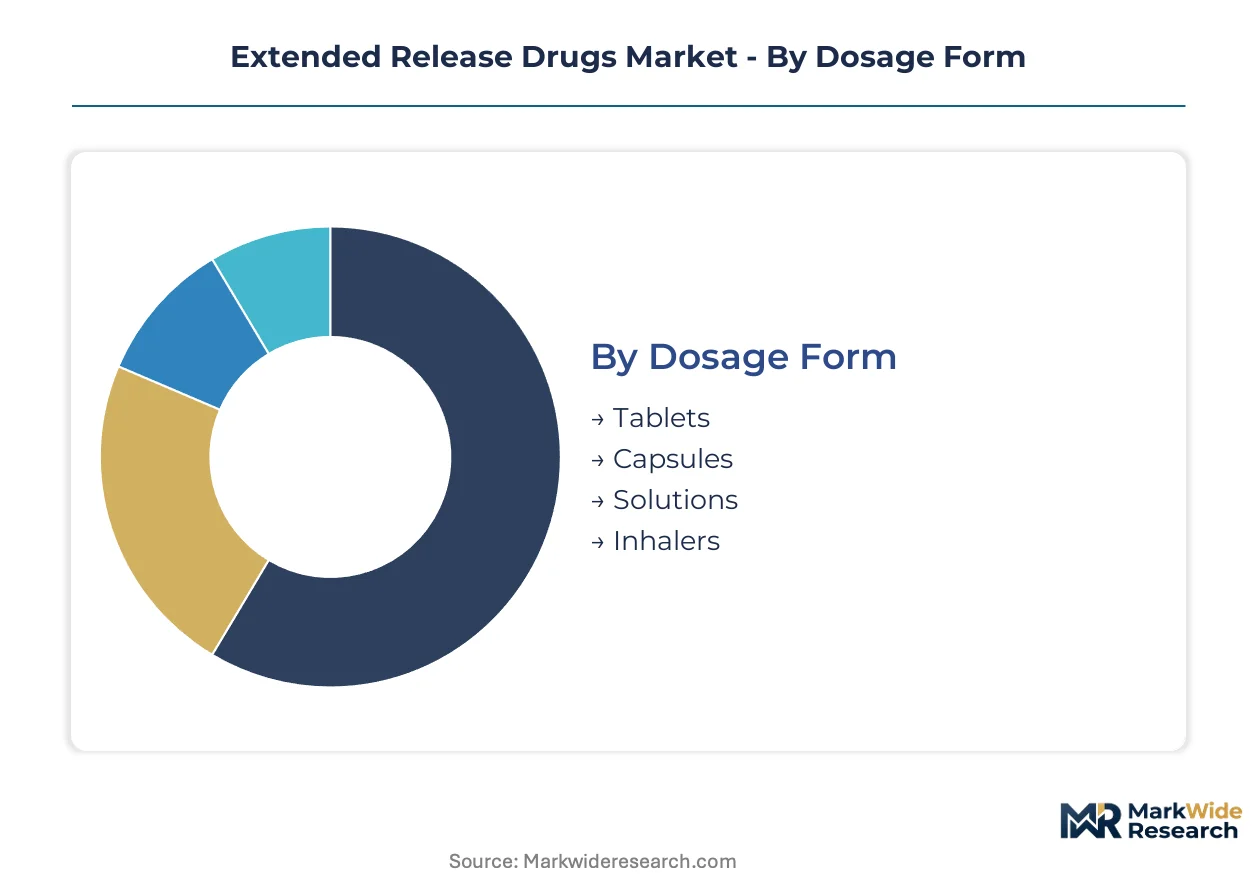
Extended release formulations command differentiated pricing and distribution strategies across dosage forms and therapy areas. Channel allocation reflects reimbursement complexity, with hospital systems driving volume in chronic disease categories while retail pharmacy networks dominate maintenance therapies.
Dosage Form:
Channel economics vary sharply across solid and liquid formulations, with institutional procurement favoring unit-dose packaging and retail channels prioritizing patient convenience features.
- Tablets:Matrix-compressed or osmotic-core architectures dominate hospital formularies due to manufacturing scale and stability profiles. United States specialty clinics drive adoption of laser-drilled osmotic tablets for narrow therapeutic index compounds where plasma concentration precision determines safety margins.
- Capsules:Pellet-filled or multiparticulate designs enable gastric pH-independent release kinetics. Germany's aging patient population concentrates demand for once-daily cardiovascular capsules that bypass food-effect variability through enteric coating technologies.
- Solutions:Liquid extended-release suspensions address pediatric and geriatric populations with swallowing difficulties. Brazil's public health system channels these through specialty pharmacy networks serving chronic pain management protocols.
- Inhalers:Dry-powder and metered-dose platforms with controlled-release excipients target respiratory maintenance therapy. Japan's PMDA regulatory pathway for inhaled generics creates concentrated development activity among established manufacturers.
By volume, tablets lead institutional procurement. By growth pace, inhalers are expanding most quickly as respiratory biologics migrate to extended-release formats.
Therapy Area:
Reimbursement intensity and patient adherence economics determine which therapeutic categories absorb formulation premium pricing.
- Pain Management:Opioid and non-opioid extended-release formulations face stringent FDA Risk Evaluation and Mitigation Strategy requirements. United States hospital systems mandate abuse-deterrent matrix technologies for formulary inclusion, concentrating volume among manufacturers with validated deterrent chemistries.
- Mental Health:Antipsychotic and antidepressant extended-release formulations reduce caregiver burden in long-term management. Germany's statutory health insurance funds prioritize once-daily antipsychotics through centralized tendering, compressing margins while expanding volume.
- Cardiovascular:Beta-blocker and calcium channel blocker extended-release formats stabilize hemodynamic control. Japan's aging demographic concentrates demand for amlodipine-based fixed-dose combinations through community pharmacy networks.
- Diabetes:Basal insulin analogs and GLP-1 receptor agonist extended-release injectables capture the steepest volume trajectory. Brazil's public procurement for diabetes management is shifting from prandial to long-acting glucose control protocols.
Pain management commands the largest installed patient base. Diabetes formulations are gaining share fastest as therapeutic protocols pivot toward long-acting regimens.
Route of Administration:
Patient compliance economics and manufacturing complexity create divergent margin structures across administration pathways.
- Oral:Gastrointestinal tract-dependent absorption dominates volume through established dissolution control technologies. United States Medicare Part D reimbursement patterns favor oral extended-release over immediate-release alternatives for chronic conditions.
- Transdermal:Multi-layer adhesive matrix systems capture premium pricing in hormonal and pain applications where first-pass hepatic metabolism must be avoided. Germany's dermatology clinics drive specialized patch development for menopause management.
- Rectal:Suppository and gel-based extended-release formats serve niche populations with compromised oral absorption. Brazil's oncology centers channel these through compounding pharmacies for palliative care protocols.
- Inhalation:Pulmonary deposition kinetics enable systemic delivery with reduced gastrointestinal exposure. Japan's respiratory specialist networks prioritize inhaled corticosteroid extended-release formats for asthma maintenance.
Oral administration generates the highest prescription volume. Transdermal delivery shows the strongest margin expansion as hormonal therapy channels develop direct-to-specialist distribution models.
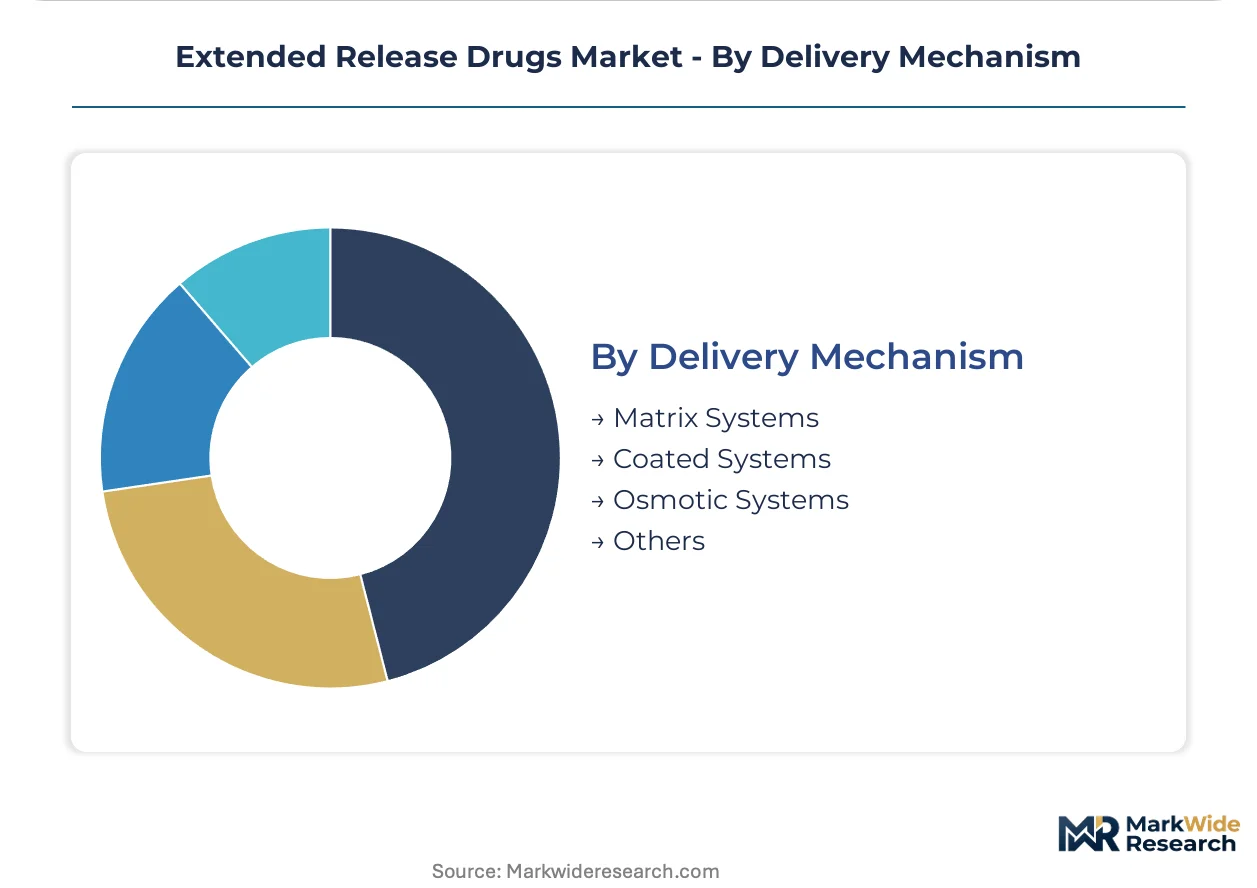
Delivery Mechanism:
Capital intensity and regulatory validation burden separate scalable matrix platforms from precision osmotic architectures.
- Matrix Systems:Hydrophilic polymer networks modulate drug diffusion through swelling and erosion kinetics. United States generic manufacturers concentrate volume here due to lower equipment requirements and established USP Chapter 711 dissolution validation protocols.
- Osmotic Systems:Semipermeable membrane-controlled release through precision-drilled orifices delivers zero-order kinetics independent of GI environment. Japan's PMDA recognizes these for narrow therapeutic index compounds where plasma concentration stability is paramount.
- Coated Systems:Enteric and sustained-release film coatings enable pH-triggered or time-dependent release profiles. Germany's contract manufacturing organizations specialize in aqueous coating technologies for European sponsors.
- Others:Ion-exchange resins and lipid-based formulations address specific solubility and stability challenges. Brazil's domestic manufacturers experiment with these for tropical climate storage requirements.
Matrix systems dominate current production volume. Osmotic architectures are climbing the fastest as precision-controlled release claims justify premium pricing in cardiovascular and mental health categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems and specialty clinics in the United States anchor institutional procurement volume for once-daily formulations. Germany's aging population drives statutory health insurance tendering for chronic disease management. Japan's PMDA regulatory pathways attract foreign sponsors with existing FDA dossiers.
United States
Specialty clinics and hospital pharmacy committees drive formulary consolidation for narrow therapeutic index compounds. FDA's Quality by Design framework elevates capital barriers for new entrants lacking validated dissolution testing infrastructure. Boston's contract research organizations cluster around bioequivalence study capabilities serving generic sponsors.
Germany
Statutory health insurance funds centralize tendering for once-daily antipsychotics and cardiovascular maintenance therapies. EMA's Quality Target Product Profile guidelines mandate predefined critical quality attributes before clinical trial acceptance. Baden-Württemberg's pharmaceutical manufacturing corridor hosts specialized aqueous coating technologies for European sponsors.
Japan
Aging demographics concentrate demand for amlodipine-based fixed-dose combinations through community pharmacy networks. PMDA mandates localized pharmacokinetic bridging studies for foreign sponsors while streamlining pathways for those with existing FDA or EMA dossiers. Osaka's respiratory specialist networks prioritize inhaled corticosteroid extended-release formats for asthma maintenance protocols.
Brazil
Public procurement shifts from prandial to long-acting glucose control protocols for diabetes management. ANVISA's regulatory framework channels liquid extended-release suspensions through specialty pharmacy networks serving pediatric and geriatric populations. São Paulo's oncology centers route rectal extended-release formats through compounding pharmacies for palliative care.
United Kingdom
NHS England's pharmacy and therapeutics committees mandate therapeutic equivalence documentation beyond minimum regulatory requirements. MHRA alignment with EMA guidelines embeds risk assessment into early development phases for domestic sponsors. London's regulatory affairs consultancies consolidate dossier preparation capabilities among experienced practitioners.
Extended Release Drugs Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with manufacturing scale across multiple dosage forms. The competitive structure concentrates around matrix-based delivery platforms and osmotic pump architectures. Strategic archetypes include R&D-intensive innovators, cost-optimized generic manufacturers, and specialty formulation developers. Dominant competitive moves encompass portfolio diversification into narrow therapeutic index compounds and geographic expansion through streamlined regulatory pathways.
Within the diversified pharmaceutical tier, Pfizer and Janssen Pharmaceuticals exemplify scale-driven positioning across matrix and osmotic delivery systems. Teva Pharmaceuticals occupies a position within the cost-optimized generic segment, competing on manufacturing efficiency and regulatory dossier breadth. These three anchors represent divergent strategic postures: R&D intensity, therapeutic specialization, and price-led volume capture.
| Leading Market Players |
|---|
| Pfizer |
| Endo Pharmaceuticals |
| Janssen Pharmaceuticals |
| Mallinckrodt |
| Viatris |
| Teva Pharmaceuticals |
| AstraZeneca |
| Novartis |
| Sanofi |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for high-purity hydroxypropyl methylcellulose translate directly into pricing power asymmetries between matrix-system manufacturers with captive excipient supply and those exposed to spot-market volatility. Contract-plus arrangements with pharmaceutical-grade polyethylene oxide suppliers index to raw-material pass-through clauses, embedding cost escalation risk into generic extended-release tablet pricing while osmotic-pump specialists with backward-integrated membrane production defend margin stability.
Pricing Analysis
Cost-plus contracts with hydroxypropyl methylcellulose and polyethylene oxide suppliers carry API-grade indexation clauses that transfer input volatility downstream. Pricing stratifies across osmotic-core premium tiers, matrix-compressed standard tiers, and liquid-suspension economy tiers differentiated by dissolution-profile precision and regulatory dossier depth. Price compression runs through generic matrix tablets as United States hospital formulary committees mandate therapeutic-equivalence documentation beyond minimum FDA requirements. Retail pharmacy networks exhibit highest price sensitivity for maintenance-therapy categories where substitution authority rests with payers, while specialty clinics absorb premiums for narrow-therapeutic-index compounds where plasma-concentration stability determines clinical outcomes.
Supply Chain Analysis
Seventy-five-day lead times for semipermeable membrane substrates concentrate supply risk among osmotic-system manufacturers without qualified secondary sources. High-purity excipient production clusters in the United States, Germany, and Japan, with hydroxypropyl methylcellulose drawing from wood-pulp supply chains and polyethylene oxide resting on petrochemical feedstock corridors. Single-source vulnerability for laser-drilled orifice equipment exposes precision-pump formulators to capacity constraints at validated contract manufacturers. Distribution runs through hospital pharmacy and therapeutics committees for institutional volume, direct-to-specialist channels for transdermal hormonal therapy, and retail pharmacy networks for maintenance-therapy oral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adherence-support program bundling expands faster than formulation hardware as United States payers shift reimbursement toward outcome-contingent contracts. Service-attach layers encompassing patient-monitoring platforms and dosing-optimization algorithms capture recurring revenue streams that compound lifetime value per prescription.
For Market Incumbents: Compound defensive positioning through captive production of hydroxypropyl methylcellulose and polyethylene oxide excipients to neutralize input-cost volatility threatening generic matrix-tablet margins. Expand dissolution-testing infrastructure capacity in Baden-Württemberg to capture EMA Quality Target Product Profile validation demand from mid-cap developers lacking established quality systems. Secure preferred formulary status through extended clinical-data packages that preempt institutional procurement committees' therapeutic-equivalence documentation requirements.
For New Entrants and Emerging Players: Post-market surveillance data integration represents a service-layer gap where incumbents under-serve, creating entry footholds for analytics-native platforms that aggregate real-world evidence for FDA bioequivalence-determination guidance compliance. Target Brazil's public-procurement shift toward long-acting glucose-control protocols, where ANVISA regulatory pathways for liquid extended-release suspensions remain less congested than oral-solid competition. Pursue direct-to-specialist distribution models for transdermal hormonal therapy that bypass traditional pharmacy network margin extraction.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates with underutilized aqueous-coating infrastructure in European manufacturing corridors. Long-term viability hinges on regulatory-dossier capability depth rather than single-product positioning, favoring platforms with validated dissolution-testing protocols across multiple jurisdictions. Monitor FDA guidance evolution on real-world-evidence requirements for formulation switching as the inflection signal determining analytical-infrastructure investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Expansion | Broadens FDA and EMA submission capabilities to capture multi-jurisdiction approval efficiency for osmotic-pump architectures. |
| Excipient Backward Integration | Captures hydroxypropyl methylcellulose production to neutralize supply-concentration risk in high-purity polymer inputs. |
| Continuous Manufacturing Transition | Reduces batch-variability costs while aligning with FDA Quality by Design framework expectations for process validation. |
| Real-World Evidence Infrastructure | Positions for emerging FDA bioequivalence-determination guidance using observational data from patient-monitoring platforms. |
| Direct-to-Specialist Channel Development | Bypasses retail pharmacy margin extraction in transdermal hormonal therapy through menopause and contraceptive clinic networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists. Secondary validation drew from FDA New Drug Application filings, EMA Quality Target Product Profile submissions, ClinicalTrials.gov protocol registries, and USP Chapter 711 dissolution standard databases. Bottom-up prescription-volume modeling across dosage forms and therapy areas triangulated against top-down pharmaceutical-market expenditure estimates from national health accounts.
Across the analysis window, value projections integrate treatment-line progression, dosage-form substitution elasticity, administration-route compliance economics, and regional regulatory-cluster approval timelines. Segmentation dimensions span matrix versus osmotic delivery mechanisms, oral versus transdermal versus injectable routes, and pain management versus mental health versus diabetes therapy areas. CAGRs derive from fitted growth curves calibrated to historical prescription-dispensing patterns and forward-looking protocol-shift assumptions in glucose-management and antipsychotic maintenance categories.
Underlying assumptions cover stable FDA bioequivalence-study requirements, EMA quality-attribute precedent continuity, and PMDA streamlined-pathway availability for foreign sponsors, with deviation risk concentrated in real-world-evidence guidance evolution and excipient-supply disruption scenarios. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pharmaceutical Grade Lactose Market
Pharmaceuticals
US Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
US Emergency Contraceptive Pills Market
Pharmaceuticals
Global Central Nervous System (CNS) Stimulant Drugs Market
Pharmaceuticals
Global Intravenous Solutions Market
Pharmaceuticals
Global Ovulation Inducing Drugs Market
Pharmaceuticals
North America Travel Vaccines Market
Pharmaceuticals
Sinus Therapeutic Drugs Market
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Asia-Pacific Aneurysmal Subarachnoid Hemorrhage Drugs Market
Pharmaceuticals
Unit Dose Manufacturing Market
Pharmaceuticals
Enbrel Market
Pharmaceuticals
Azathioprine API Market
Pharmaceuticals
APAC Pharmaceutical Warehousing Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Mexico Dimenhydrinate Market