
 Global MRI Safe Cardiac Resynchronization Therapy Device Market | 2026-2036
Global MRI Safe Cardiac Resynchronization Therapy Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global MRI Safe Cardiac Resynchronization Therapy Device Market Foresight
MRI conditional certification is redrawing competitive boundaries in implantable cardiac rhythm management. Medtronic leverages its integrated manufacturing scale to anchor supply across North American and European catheterization labs. Abbott differentiates through bi-ventricular lead architectures that navigate complex cardiac geometries. Boston Scientific Corporation specializes in extended battery longevity platforms that occupy the premium tier of heart failure device procurement.
Cardiac resynchronization therapy devices coordinate ventricular contraction through implanted pulse generators and transvenous or leadless leads, typically operating at 2.5 to 5 volts with hermetic titanium enclosures and lithium-iodine power cells to ensure biocompatibility and decade-long implantation durability. The technology dimension shows MRI conditional systems pulling ahead of conventional platforms as reimbursement aligns with magnet-safe labeling. CRT-D configurations within the device type segment command the deepest margin pools due to combined defibrillation and resynchronization functionality in single-unit implants.
FDA conditional device approvals, EU MDR Class III implantable active device requirements, and Japan PMDA sakigake fast-track designations collectively shape product development timelines and market access pathways for manufacturers. These frameworks demand exhaustive electromagnetic compatibility testing and post-market surveillance protocols that filter out undercapitalized entrants. Stakeholders must monitor evolving ISO 10993 biocompatibility standards and country-specific radiology-cardiology workflow integration requirements as conditional labeling becomes the baseline expectation for new implant procurement.
Market Dynamics
MRI conditional labeling requirements are compressing product development cycles while simultaneously elevating capital barriers for device manufacturers. The migration from conventional CRT systems to magnet-safe platforms demands complete electromagnetic compatibility redesigns of pulse generators and lead architectures.
Growth Catalysts
- FDA Conditional Approval Pathway:The streamlined premarket review process for MRI-conditional devices accelerates time-to-market for manufacturers submitting electromagnetic compatibility data. This regulatory mechanism reduces clinical trial burden compared to full PMA submissions.
- Specialty Hospital Networks:Germany's university hospital clusters are consolidating procurement around magnet-safe CRT-D systems to support integrated electrophysiology-radiology workflows. These centers drive volume concentration for premium-tier devices.
- Leadless Delivery Systems:Transcatheter lead placement technologies are eliminating thoracotomy requirements. This surgical modality expansion opens CRT candidacy to patients previously excluded due to vascular access limitations.
Market Restraints
- EU MDR Class III Certification Costs:The implantable active device regulatory framework demands expanded clinical evidence packages and notified body capacity constraints are extending approval timelines by eighteen to thirty-six months.
- Lithium-Iodine Cell Supply Concentration:Battery chemistry production for hermetic enclosures concentrates among three Asian suppliers. Raw material price volatility in iodine and lithium carbonate directly impacts device margin structures.
- Transvenous Lead Longevity Limitations:Conductor fracture rates in bipolar pacing leads necessitate replacement procedures. This technical constraint creates physician hesitancy and liability exposure for long-term implant decisions.
Strategic Opportunities
- Japan PMDA Sakigake Fast-Track:The regenerative medicine and device priority review system offers accelerated approval for MRI-conditional CRT platforms with novel biocompatibility profiles. Manufacturers gain six-month market exclusivity premiums.
- Home-Based Remote Monitoring Integration:Bluetooth-enabled device telemetry is converging with cloud-based heart failure management platforms. This technology pairing creates subscription revenue streams beyond hardware implantation.
- India's PLI Scheme for Medical Devices:The production-linked incentive framework subsidizes domestic manufacturing of active implantable devices. Multinational manufacturers can establish captive production for export to Southeast Asian markets.
Industry Challenges
- Electrophysiologist Training Pipeline:Complex biventricular lead placement requires specialized procedural expertise. Fellowship program capacity constraints limit the specialist workforce available to support CRT volume expansion.
- ISO 10993 Biocompatibility Testing Backlogs:Third-party laboratory capacity for cytotoxicity and sensitization assessments is creating certification delays. Device submissions face six-to-nine month queue times for complete biological evaluation.
- Legacy Device Explant Logistics:Pulse generator and lead retrieval procedures require specialized surgical tools and waste handling protocols. Hospital sterile processing departments face operational complexity managing mixed-generation implant inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global MRI Safe Cardiac Resynchronization Therapy Device Market |
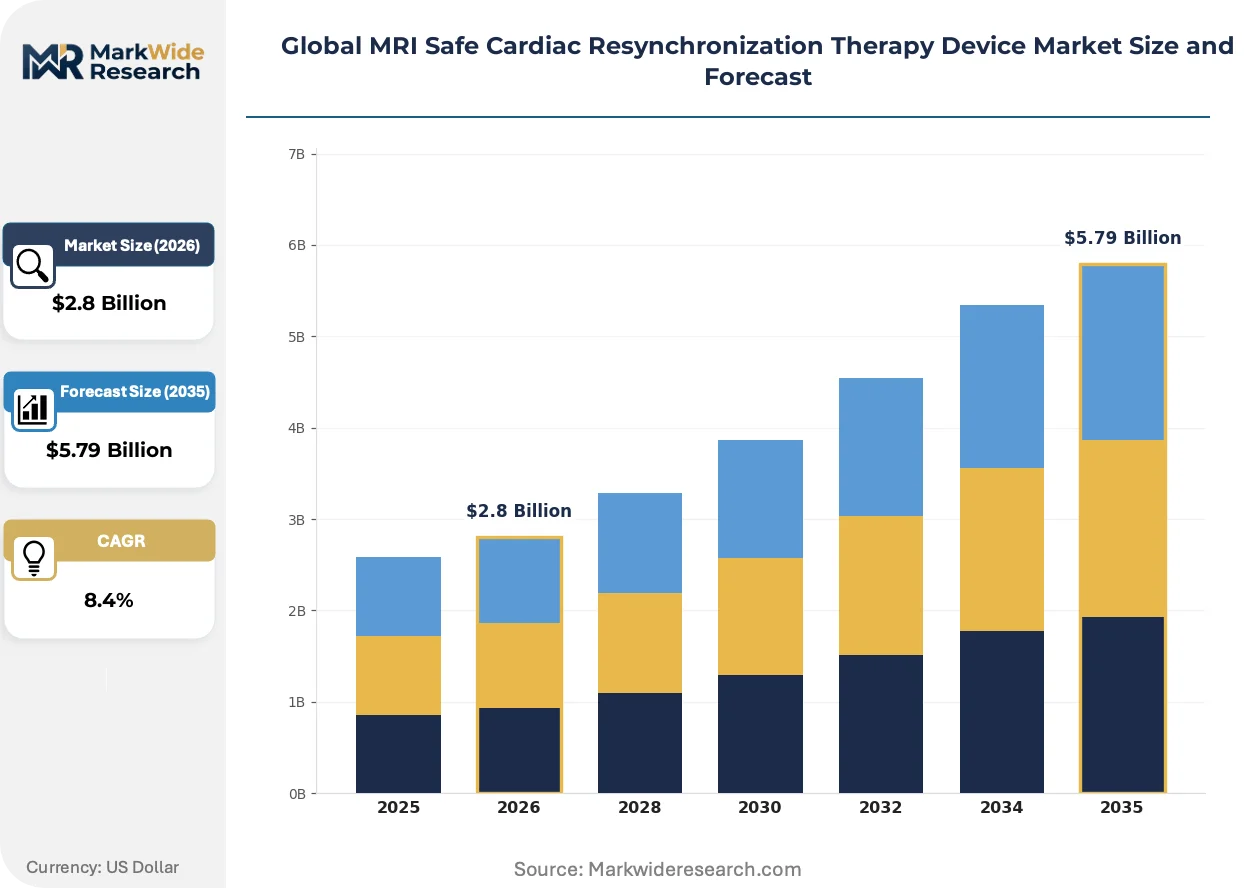
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: CRT-P, CRT-D, Implantable Pacemaker, Implantable Defibrillator Technology: Leadless, Bi-Ventricular, Wireless, MRI Conditional Application: Heart Failure Management, Arrhythmia Correction, Cardiac Synchronization, Ventricular Pacing End User: Cardiology Clinics, Diagnostic Centers, Specialty Hospitals, Ambulatory Surgical Centers |
| Companies Covered | Medtronic, Abbott, Boston Scientific Corporation, BIOTRONIK, MicroPort Scientific Corporation, LivaNova, Philips, Cook Group, Medico, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global MRI Safe Cardiac Resynchronization Therapy Device Market Shifts & Advancements
Active implantable devices are undergoing fundamental architectural transformation as electromagnetic compatibility becomes the primary design constraint. This shift is redefining competitive advantage around materials science capabilities rather than traditional pacing algorithms.
Quadripolar left ventricular lead designs are displacing bipolar configurations in complex cardiac anatomies. German electrophysiology centers are adopting these architectures at twice the rate of North American sites. The technology is displacing conventional transvenous approaches by enabling more predictable pacing thresholds and reducing phrenic nerve stimulation incidents.
Japan's PMDA has harmonized electromagnetic compatibility testing requirements with IEC 60601-2-31 standards for active implantable cardiac devices. This regulatory alignment eliminates redundant submission packages for manufacturers seeking concurrent US and Japanese approvals. The policy shift most affects CRT-D platforms targeting the Asia-Pacific university hospital segment.
Hospital procurement committees are consolidating vendor relationships around single-source MRI-conditional portfolios. Integrated device-radiology workflow contracts are replacing transactional implant purchases in US academic medical centers. This behavioral shift is most visible in the Northeastern and Midwestern hospital systems where electrophysiology volumes exceed four hundred procedures annually.
Global MRI Safe Cardiac Resynchronization Therapy Device Market Segmentation
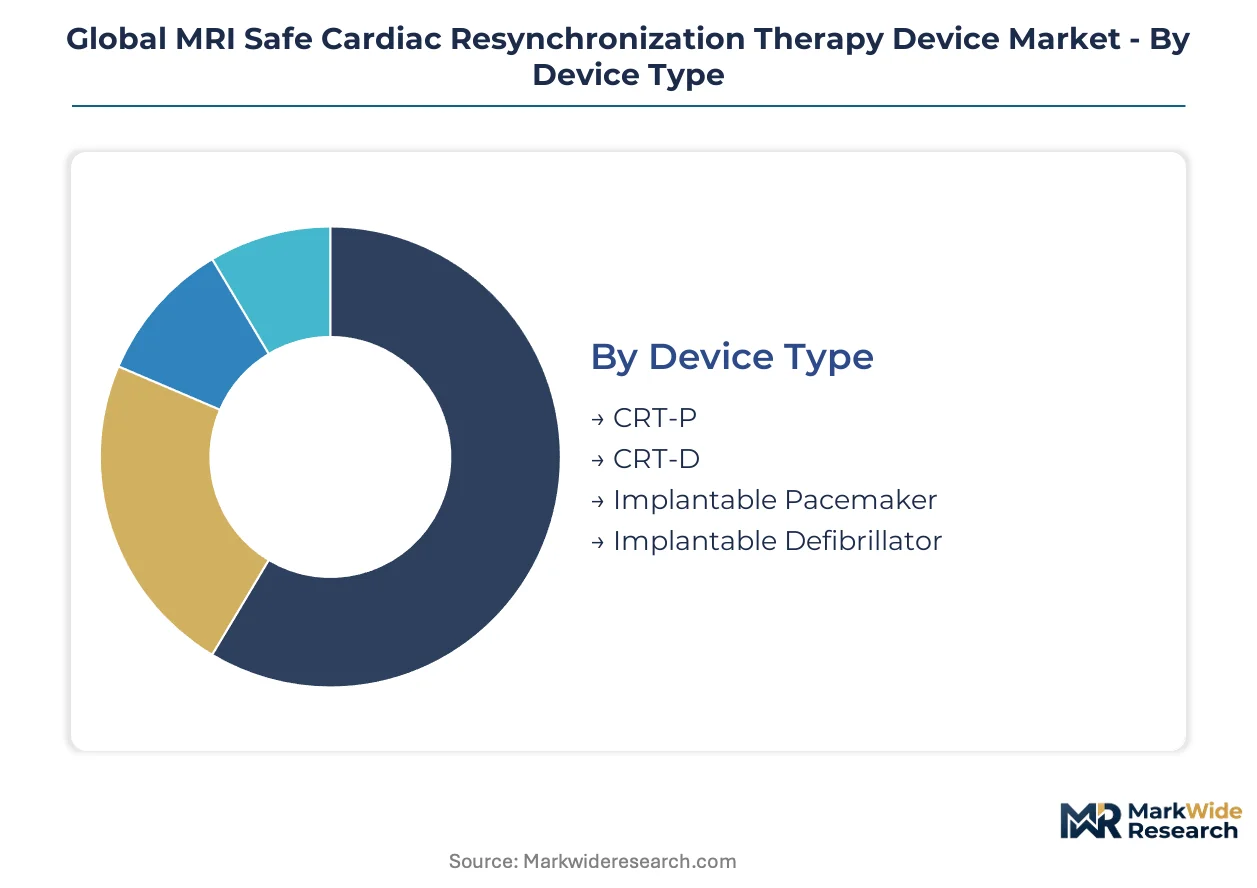
MRI Safe Cardiac Resynchronization Therapy Device market segmentation reveals how electromagnetic compatibility requirements reshape procurement priorities across device architectures and care settings. Understanding these divisions exposes where conventional platforms face displacement pressure from magnet-safe alternatives.
Device Type:
Substitution pressure concentrates most intensely on single-function implants as combined-therapy platforms capture hospital procurement budgets.
- CRT-D:Combines defibrillation and resynchronization in hermetic titanium enclosures with lithium-iodine power cells. German university hospital networks and US academic medical centers prioritize these configurations for heart failure patients with elevated sudden cardiac death risk.
- CRT-P:Dedicated resynchronization pulse generators without shock therapy capability. Demand clusters in Japan's regional cardiac centers and India's emerging electrophysiology programs where cost sensitivity shapes device selection.
- Implantable Pacemaker:Single-chamber and dual-chamber pacing systems with conditional labeling. Brazil's public hospital procurement and Southeast Asian tier-2 cities drive volume for basic rhythm management.
- Implantable Defibrillator:Standalone shock-therapy devices with CRT backup functionality. Australia's public health reimbursement frameworks and South Korea's national insurance coverage sustain niche demand.
CRT-D retains volume leadership; leadless-enabled CRT-P holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium electromagnetic compatibility platforms from legacy architectures facing reimbursement compression.
- MRI Conditional:Pulse generators and leads engineered for 1.5T and 3.0T scanner compatibility with filtered feedthroughs and minimized ferromagnetic content. US catheterization labs and European electrophysiology centers now require conditional labeling as baseline procurement specification.
- Leadless:Transcatheter-delivered pacing modules eliminating transvenous lead failure modes. Japan's PMDA sakigake fast-track approvals and Germany's minimally invasive surgery adoption curves accelerate clinical uptake.
- Bi-Ventricular:Dual-site ventricular pacing architectures with quadripolar or bipolar lead configurations. Complex cardiac anatomies in aging populations across Italy and Spain sustain procedural demand.
- Wireless:Ultrasound or radiofrequency-coupled energy transfer systems eliminating percutaneous lead connections. Early-stage clinical trials in Switzerland and the Netherlands test workflow integration.
MRI Conditional dominates revenue concentration; leadless platforms gain share fastest among technology categories.
Application:
Volume distribution tracks heart failure epidemiology while margin pools concentrate where acute intervention capability merges with chronic disease management.
- Heart Failure Management:Chronic resynchronization therapy for NYHA Class II-IV patients with reduced ejection fraction. US Medicare reimbursement codes and Germany's Diagnosis-Related Group pricing anchor this segment's institutional purchasing power.
- Arrhythmia Correction:Combined defibrillation and pacing for ventricular tachyarrhythmia prevention. Japan's aging demographic profile and South Korea's sudden cardiac death screening programs concentrate procedural volumes.
- Cardiac Synchronization:Electromechanical resynchronization for dyssynchrony-mediated pump dysfunction. Italy's regional cardiac resynchronization therapy networks and France's university hospital clusters standardize these protocols.
- Ventricular Pacing:Right ventricular or biventricular stimulation for bradyarrhythmia or conduction system disease. India's expanding private hospital infrastructure and Brazil's SUS system procurement sustain basic pacing demand.
Heart Failure Management captures the deepest margin pools; Arrhythmia Correction expands most quickly as CRT-D penetration rises.
End User:
Customer type differentiation separates high-complexity academic centers from distributed ambulatory settings with divergent device servicing capabilities.
- Specialty Hospitals:University-affiliated cardiac centers with integrated electrophysiology-radiology workflows. Germany's university hospital network, Japan's national center hospitals, and US academic medical centers consolidate procurement for magnet-safe CRT-D platforms.
- Cardiology Clinics:Outpatient-based implantation facilities with limited sterile processing capacity. India's metropolitan private cardiology chains and Brazil's regional cardiac institutes drive volume for simpler CRT-P configurations.
- Ambulatory Surgical Centers:Same-day discharge facilities for low-complexity device implants. US Medicare ASC payment differentials and South Korea's health technology assessment frameworks shape site-of-care migration.
- Diagnostic Centers:Imaging-integrated facilities performing pre-implant workup and post-implant surveillance. Australia's cardiac imaging networks and the UK's NHS diagnostic hubs coordinate device-radiology compatibility verification.
Specialty Hospitals command premium-tier procurement; Ambulatory Surgical Centers climb the fastest as reimbursement shifts site of care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German university hospitals absorb premium-tier CRT-D systems without volume compression, while India's emerging electrophysiology programs prioritize cost-optimized CRT-P configurations to expand patient access.
United States
Medicare reimbursement codes for magnet-safe CRT-D implants sustain procedural volumes at academic medical centers. FDA's streamlined conditional device approval pathway accelerates electromagnetic compatibility certifications for manufacturers targeting integrated electrophysiology-radiology workflows. Northeastern and Midwestern hospital systems with annual volumes exceeding four hundred procedures consolidate procurement around single-source MRI-conditional portfolios.
Germany
University hospital clusters drive the deepest adoption curves for quadripolar left ventricular lead architectures. EU MDR Class III implantable active device requirements filter market access toward capitalized manufacturers with exhaustive post-market surveillance capabilities. The Baden-Württemberg and Bavaria cardiac networks standardize magnet-safe CRT-D protocols across integrated diagnosis-related group pricing frameworks.
Japan
Aging demographics and sudden cardiac death screening programs concentrate demand for combined defibrillation-resynchronization platforms. PMDA sakigake fast-track designations offer six-month market exclusivity premiums for MRI-conditional CRT devices with novel biocompatibility profiles. National center hospitals in Tokyo and Osaka anchor procurement for leadless-enabled systems.
India
Private hospital infrastructure expansion in metropolitan corridors sustains volume growth for basic pacing configurations. The PLI scheme for medical devices subsidizes domestic manufacturing of active implantable devices for export to Southeast Asian markets. Maharashtra and Karnataka cardiac chains drive procurement for cost-sensitive CRT-P systems.
Brazil
Public hospital procurement through the SUS system shapes demand for standalone implantable defibrillators with CRT backup functionality. ANVISA regulatory alignment with ISO 10993 biocompatibility standards creates certification bottlenecks for undercapitalized entrants. São Paulo and Rio de Janeiro regional cardiac institutes concentrate implantation volumes.
Global MRI Safe Cardiac Resynchronization Therapy Device Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the magnet-safe CRT device landscape. Consolidation pressures favor integrated manufacturers with captive materials science capabilities and hermetic enclosure production. Three archetypes dominate: diversified cardiovascular conglomerates with catheterization lab anchoring, mid-scale electrophysiology specialists with regional manufacturing footprints, and emerging Asia-Pacific fabricators leveraging production-linked incentive frameworks. Competitive moves center on electromagnetic compatibility redesigns of pulse generator architectures and strategic partnerships with iodine-lithium cell suppliers.
Among diversified cardiovascular conglomerates, Medtronic, Abbott, and Boston Scientific Corporation occupy positions defined by integrated manufacturing scale and catheterization lab penetration. Medtronic anchors supply relationships across North American and European electrophysiology centers. Abbott exemplifies bi-ventricular lead architecture specialization for complex cardiac geometries. Boston Scientific Corporation represents the premium-tier positioning around extended battery longevity platforms. BIOTRONIK and MicroPort Scientific Corporation sit within the mid-scale specialist tier, with the former advancing leadless platform technologies and the latter leveraging Asia-Pacific production economics.
| Leading Market Players |
|---|
| Medtronic |
| Abbott |
| Boston Scientific Corporation |
| BIOTRONIK |
| MicroPort Scientific Corporation |
| LivaNova |
| Philips |
| Cook Group |
| Medico |
| Others |
Supply & Pricing Matrix
EU MDR Class III implantable active device requirements gate both supply qualification and price differentiation simultaneously. Manufacturers must absorb expanded clinical evidence costs and notified body capacity constraints, which stratifies pricing tiers between capitalized incumbents and undercapitalized challengers. German university hospital networks and US academic medical centers pay premiums for magnet-safe CRT-D platforms with integrated electrophysiology-radiology workflows.
Pricing Analysis
Remote monitoring subscription contracts drive lifetime value beyond hardware implantation. Three-tier pricing structure across premium, standard, and economy levels separates CRT-D systems with defibrillation-resynchronization functionality from basic CRT-P configurations and legacy non-conditional devices. Cost compression in the economy tier intensifies because India's PLI scheme subsidizes domestic manufacturing for Southeast Asian export markets. Cardiology clinics in Brazil and regional cardiac institutes in India exhibit highest price sensitivity, while specialty hospitals in Germany and Japan absorb premium-tier procurement without volume compression.
Supply Chain Analysis
Inventory buffers for lithium-iodine cells and hermetic titanium enclosures extend lead times during raw material price volatility. Production concentrates in Germany, Japan, and the United States for pulse generator assembly, while iodine and lithium carbonate extraction feeds from Chile and Australia. Single-source vulnerability in battery chemistry production among Asian suppliers creates margin exposure when commodity markets fluctuate. Distribution runs through catheterization lab supply agreements and GPO contracts at academic medical centers, with integrated device-radiology workflow contracts replacing transactional implant purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MRI Safe Cardiac Resynchronization Therapy Device market constitutes a high-growth disruption. FDA's streamlined conditional device approval pathway accelerates electromagnetic compatibility certifications faster than EU MDR timelines, creating competitive asymmetry.
For Market Incumbents: Secure captive supply agreements with iodine-lithium cell suppliers to defend margin structures against raw material volatility. Invest in backward integration into hermetic titanium enclosure production to reduce dependency on concentrated Asian suppliers. Defend against BIOTRONIK's leadless platform advances by accelerating quadripolar left ventricular lead architecture R&D.
For New Entrants and Emerging Players: Differentiate on leadless delivery systems for patients with vascular access limitations excluded from conventional CRT candidacy. Target India's private hospital infrastructure expansion and Brazil's SUS system procurement for cost-optimized CRT-P configurations. Pursue Japan PMDA sakigake fast-track designation to capture six-month market exclusivity premiums.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across MRI-conditional electromagnetic compatibility testing and post-market surveillance capabilities. Five-to-ten year viability favors manufacturers with integrated materials science capabilities and catheterization lab anchoring. Acquisition target archetype: mid-scale electrophysiology specialists with regional manufacturing footprints and novel biocompatibility profiles. Signal to watch: ISO 10993 third-party laboratory queue times as certification bottleneck indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Conditional Approval Pathway | Accelerates time-to-market for manufacturers submitting electromagnetic compatibility data to FDA. |
| Hospital System Partnership | Integrated device-radiology workflow contracts consolidate procurement at US academic medical centers. |
| Software Companion Development | Bluetooth-enabled telemetry converges with cloud-based heart failure management platforms. |
| CE Marking Pathway | EU MDR Class III requirements filter market access toward capitalized manufacturers with surveillance capabilities. |
| Reimbursement Strategy | Medicare codes for magnet-safe CRT-D implants sustain procedural volumes at academic medical centers. |
Research Methodology
A standing panel of electrophysiologists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers provided ongoing calibration against market developments. Primary interviews with these stakeholders combined with secondary validation from FDA filings, EU MDR notified body registers, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up implant volume modeling and top-down market sizing triangulated across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including catheterization lab procedure registries and medical device trade data. The analytical framework modeled segmentation dimensions across device type, technology architecture, application indication, and end-user facility class throughout the forecast period. CAGRs derived from procedural volume trajectories, reimbursement code evolution, and regulatory approval pipeline velocity. Forecast inputs incorporated lithium-iodine cell supply dynamics and electrophysiologist fellowship program capacity constraints.
The analysis sits within stated boundaries; outcomes outside sustained FDA conditional approval pathway efficiency or EU MDR notified body capacity expansion would require recalibration. Forecasts reflect assumptions around electromagnetic compatibility testing standardization and post-market surveillance protocol harmonization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spinal Traction Market
Medical Devices
Global Contrast Media Injector Market
Medical Devices
Spinal Non-Fusion Technologies Market
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
Heating Pads Market
Medical Devices
US Anti-Blue Ray Myopia Lenses Market
Medical Devices
Transcatheter Bioprosthesis Market
Medical Devices
MRI-Compatible IV Infusion Pump Systems Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
Endocavity Transducer Market
Medical Devices
Silastic Implant Market
Medical Devices
Actigraphy Sensors and Polysomnography Devices Market
Medical Devices
Global Subdermal Contraceptive Implants Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Parenteral Feeding Devices Market
Medical Devices
Ambulatory Aids Market