
 Sizing and Thickening Market | 2026-2036
Sizing and Thickening Market Size, Share, and Industry Trends Forecast 2026-2036
Sizing and Thickening Market Analytics
ISO 9001 quality management certification is reorganizing supplier qualification across the Sizing and Thickening Market, filtering out smaller producers lacking documented process controls. DuPont de Nemours leverages its synthetic polymer expertise to dominate high-performance textile sizing segments. Tate & Lyle sustains leadership in food-grade thickeners through backward integration into specialty starch cultivation. BASF competes on modified cellulose chemistry for paints and coatings applications.
Sizing and thickening agents encompass functional additives that alter viscosity, surface adhesion, or rheological behavior in liquid and semi-solid formulations, typically achieving target viscosities between 500 and 50,000 centipoise depending on polymer chain length and concentration. These agents serve primarily to stabilize emulsions, control flow properties, and improve substrate bonding across industrial processes. Thickening agents derived from natural sources command premium positioning in personal care and food applications where clean-label positioning drives procurement decisions. Synthetic sizing agents lead in textile manufacturing due to consistent batch performance and lower variability under high-speed weaving conditions. Additives for paints and coatings represent a mature margin pool where modified acrylics and polyurethane thickeners face substitution pressure from bio-based alternatives.
REACH registration requirements in Europe and FDA food additive regulations in the United States constrain market entry for unqualified suppliers while creating compliance-based differentiation for established manufacturers. BIS certification in India and the PLI scheme for textile manufacturing are redirecting regional supply chains toward domestic production of sizing chemicals. Stakeholders must monitor evolving GB standards in China and dual carbon goals from MEE that are reshaping synthetic polymer production quotas and feedstock sourcing requirements.
Market Dynamics
REACH registration deadlines and FDA food additive rulemaking are compressing supplier qualification timelines while concentrating procurement among ISO 9001-certified manufacturers with documented polymer traceability systems.
Growth Catalysts
- Clean-label food formulation:Consumer preference for recognizable ingredient lists drives food processors toward specialty starches and hydrocolloids from identifiable botanical sources.
- India PLI scheme for textiles:Production-linked incentives for domestic manufacturing accelerate local sourcing of sizing agents and reduce import dependence on synthetic polymer suppliers.
- High-speed weaving technology:Synthetic polymer sizing agents with consistent batch viscosity enable faster loom speeds and lower breakage rates in automated textile production.
Market Restraints
- Feedstock volatility:Petroleum-derived acrylates and ethylene-based polymers expose synthetic sizing producers to crude oil price swings and naphtha supply disruptions.
- Regional supply concentration:Modified cellulose production clusters in China face quota constraints under MEE dual carbon goals, limiting export availability.
- Natural source variability:Agricultural harvest conditions create lot-to-lot inconsistency in guar gum and tapioca starch thickening profiles.
Strategic Opportunities
- Bio-based paint additives:Modified polysaccharides and protein-based thickeners penetrate architectural coatings segments seeking VOC reduction without performance sacrifice.
- Personal care microbiome positioning:Fermentation-derived exopolysaccharides enable claims around skin-compatible rheology modifiers in premium skincare.
- EU Green Deal chemistry:ECHA safe-and-sustainable-by-design criteria reward suppliers with renewable feedstock certificates and biodegradability documentation.
Industry Challenges
- Cross-functional formulation expertise:Rheology modification across food, textile, and coatings applications demands chemists fluent in divergent regulatory frameworks and performance testing protocols.
- Multi-jurisdiction certification timelines:Simultaneous FDA GRAS petitions, EFSA novel food approvals, and BIS mark applications strain regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sizing and Thickening Market |
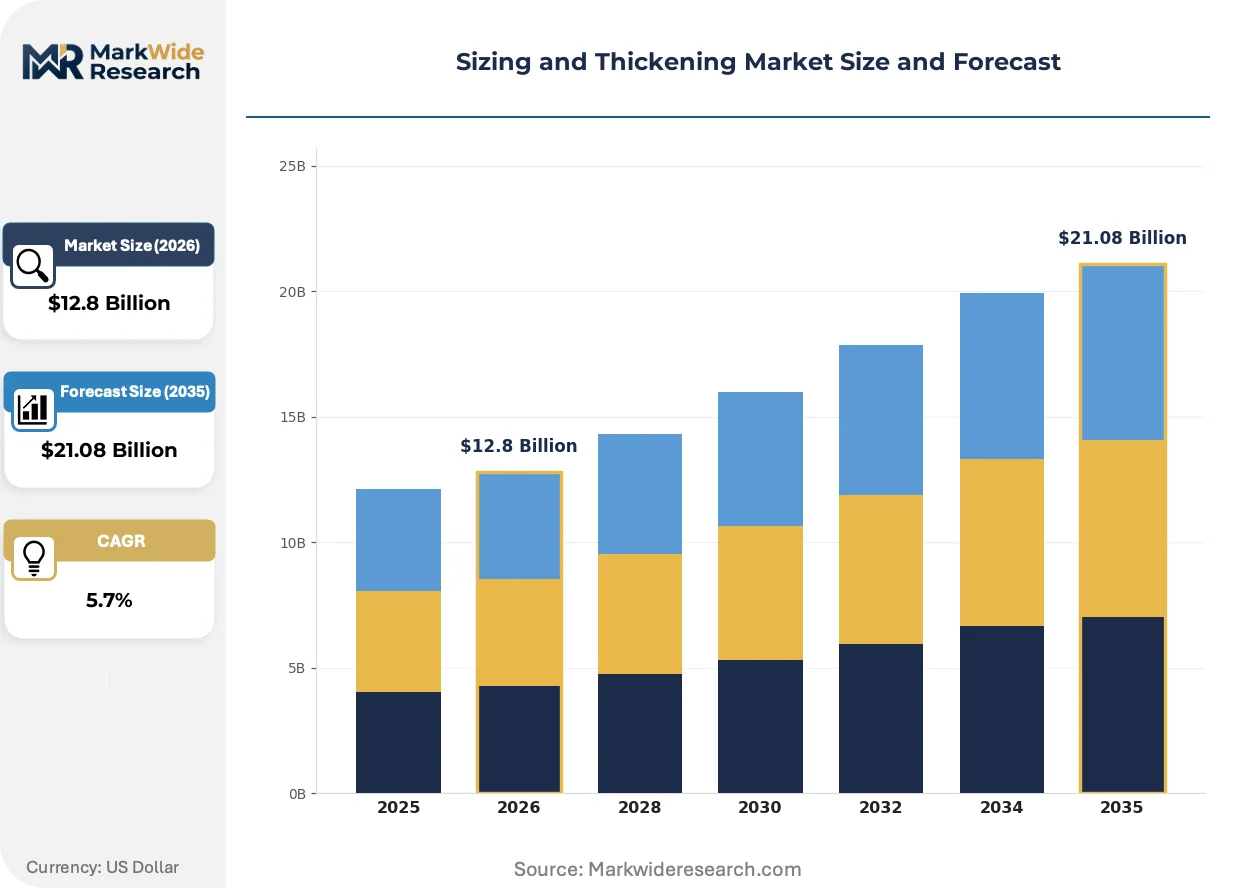
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sizing Agents, Thickening Agents, Additives, Emulsifiers Application: Textiles, Food & Beverage, Personal Care, Paints & Coatings End Use Industry: Textile Manufacturing, Food Processing, Cosmetic Industry, Construction Source: Synthetic, Natural, Modified, Others |
| Companies Covered | DuPont de Nemours, Tate & Lyle, Cargill, Dow, BASF, Ingredion Incorporated, CP Kelco, Akzo Nobel, Archer Daniels Midland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sizing and Thickening Market Evolving Landscape
Biotechnology-enabled production methods and regulatory pressure on petrochemical feedstocks are rewriting raw material sourcing strategies across viscosity-modifier categories.
Precision fermentation is displacing agricultural extraction for high-purity hydrocolloid production. Cultured microbial cellulose and fermentation-derived xanthan gum achieve tighter molecular weight distribution than plantation-sourced equivalents. Food and personal care formulators in North America and Western Europe are adopting these ingredients for label transparency and supply security.
REACH authorization requirements for microplastic-containing formulations force textile and coatings manufacturers to reformulate with biodegradable alternatives. ECHA substance evaluation timelines compress product development cycles. European paint producers accelerate testing of starch-based and protein-derived associative thickeners to maintain market access.
Direct material qualification between ingredient suppliers and end-brand technical teams is shortening traditional distributor channels. Technical service agreements now specify joint rheology mapping and accelerated stability protocols. This pattern concentrates in personal care and premium food segments where formulation differentiation determines shelf placement.
Sizing and Thickening Market Segmentation
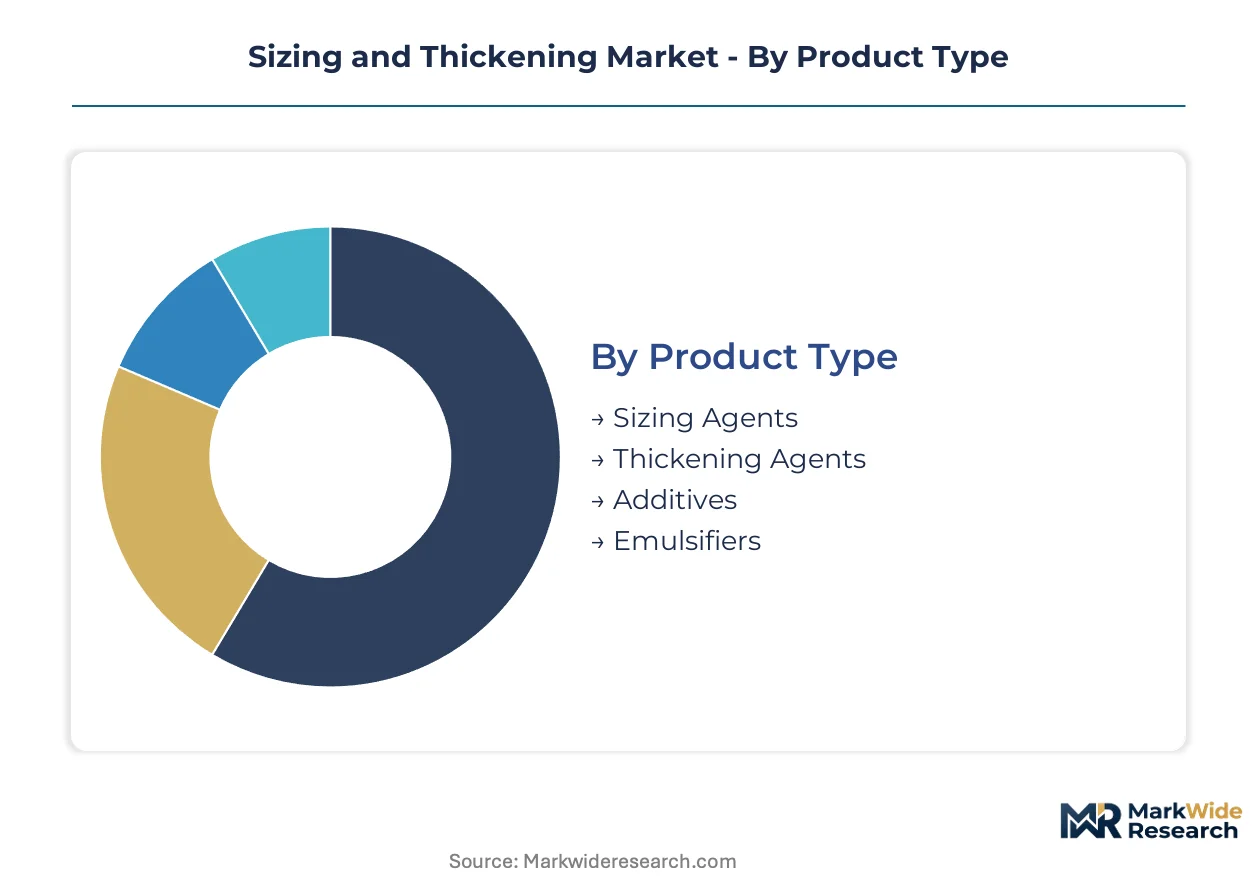
Sizing and thickening agents serve divergent performance requirements across viscosity ranges from 500 to 50,000 centipoise. Channel strategy varies sharply by segment: food-grade thickeners move through ingredient distributors with FSSAI documentation, while textile sizing agents sell direct to mill technical teams.
Product Type:
Distribution channels stratify by regulatory burden—food-contact thickeners flow through certified ingredient distributors, while industrial sizing agents move via direct mill relationships.
- Sizing Agents:Film-forming polymers including polyvinyl alcohol and modified starches that coat textile yarns to reduce abrasion during high-speed weaving. Demand concentrates in India where PLI scheme incentives for domestic textile manufacturing accelerate local sourcing of synthetic polymer grades. BIS certification requirements filter out unqualified import suppliers.
- Thickening Agents:Rheology modifiers spanning xanthan gum, guar derivatives, and cellulose ethers that build viscosity in aqueous systems. Food & beverage formulators in North America and Western Europe are shifting procurement toward fermentation-derived hydrocolloids for clean-label positioning.
- Additives:Functional modifiers including dispersants and stabilizers that augment base thickening performance in paint and coatings formulations.
- Emulsifiers:Surface-active agents that stabilize oil-water interfaces in personal care and food emulsions, often co-formulated with thickeners for texture control.
By volume, Thickening Agents leads. By growth pace, Sizing Agents is climbing the fastest.
Application:
Cost tier stratification separates commodity textile sizing from premium personal care rheology modifiers.
- Textiles:Warp sizing applications consume synthetic polymer grades—polyacrylates and polyesters—that withstand abrasive loom conditions. REACH authorization pressures on microplastic-containing formulations force European weavers to test biodegradable starch alternatives.
- Food & Beverage:Hydrocolloid thickeners from pectin, alginate, and modified starch sources build mouthfeel in dairy alternatives and convenience sauces. FDA GRAS petitions and EFSA novel food approvals create multi-year qualification timelines that concentrate procurement among established suppliers.
- Personal Care:Fermentation-derived exopolysaccharides enable microbiome-compatible claims in premium skincare, with technical service agreements specifying joint rheology mapping protocols.
- Paints & Coatings:Associative thickeners—hydrophobically modified ethoxylated urethanes and cellulosics—control sag and leveling in architectural formulations. ECHA substance evaluation timelines compress reformulation cycles as paint producers accelerate testing of starch-based alternatives.
Textiles holds the largest volume share. Personal Care is expanding most quickly.
End Use Industry:
Customer type determines contract structure—commodity textile mills negotiate annual volume agreements while cosmetic brands demand batch-level traceability.
- Textile Manufacturing:High-speed weaving operations prioritize synthetic sizing agents with consistent batch viscosity to minimize loom stoppages. India's PLI scheme redirects supply chains toward domestic producers.
- Food Processing:Clean-label formulation drives specialty starch and hydrocolloid procurement from identifiable botanical sources, with FSSAI compliance mandatory for India-market products.
- Cosmetic Industry:Premium skincare brands specify fermentation-derived thickeners with documented molecular weight distribution for microbiome positioning claims.
- Construction:Cement and mortar applications consume cellulose ether thickeners for water retention and workability, with modified grades commanding price premiums.
Textile Manufacturing dominates volume. Cosmetic Industry shows the steepest expansion trajectory.
Source:
Supply concentration varies by origin—petrochemical feedstocks cluster in integrated chemical complexes, while agricultural extraction disperses across growing regions.
- Synthetic:Petroleum-derived acrylates and ethylene-based polymers deliver consistent batch performance for high-speed textile weaving. MEE dual carbon goals in China constrain production quotas and feedstock sourcing for export-oriented suppliers.
- Natural:Guar gum from Indian subcontinent cultivation and tapioca starch from Southeast Asian processing face harvest variability that complicates formulation standardization.
- Modified:Chemically altered natural polymers—hydroxypropyl methylcellulose and carboxymethyl cellulose—bridge performance gaps between synthetic consistency and renewable sourcing.
- Others:Hybrid and emerging bio-based chemistries including cultured microbial cellulose from precision fermentation platforms.
Synthetic sources lead by volume. Modified grades are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust in Mumbai anchors India's import-export throughput for specialty chemicals, while the Rhine-Main-Danube waterway network underwrites Central European distribution of modified cellulose derivatives.
United States
Food processors in the Midwest and Southeast drive hydrocolloid consumption for clean-label dairy alternatives. FDA GRAS petitions and food additive rulemaking compress supplier qualification timelines. Chicago-area distribution hubs concentrate procurement of fermentation-derived thickeners for national CPG networks.
Germany
Paint and coatings manufacturers along the Rhine corridor demand biodegradable alternatives to petroleum-derived associative thickeners. ECHA substance evaluation under REACH authorization pressures microplastic-containing formulations. The BASF Ludwigshafen complex anchors modified cellulose production serving architectural coatings producers.
India
Textile mills in Surat and Tiruppur accelerate consumption of synthetic sizing agents under PLI scheme incentives for domestic manufacturing. BIS certification requirements filter unqualified import suppliers. Gujarat's chemical belt concentrates polyacrylate sizing production for high-speed weaving operations.
China
Modified cellulose producers face quota constraints under MEE dual carbon goals limiting export availability. GB standards compliance and feedstock sourcing requirements reshape synthetic polymer production. The Yangtze River Delta clustering of cellulose ether plants experiences capacity pressure from environmental inspections.
Brazil
Agricultural processors in São Paulo state consume tapioca starch thickeners for convenience food manufacturing. ANVISA food additive regulations align with Mercosur harmonization efforts. The Campinas industrial corridor hosts formulation R&D facilities serving Latin American CPG brands.
Sizing and Thickening Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory compliance capabilities, producing a tiered structure where scale-driven multinationals hold premium segments and regional processors capture commodity volumes. Three archetypes dominate: integrated chemical conglomerates with backward control into polymer feedstocks, ingredient specialists focused on single hydrocolloid categories, and diversified agricultural processors leveraging crop origination advantages. M&A activity concentrates on fermentation technology platforms and regional distribution assets, while capacity expansion targets India and Southeast Asia to capture PLI-driven textile demand.
Within the integrated chemical tier, DuPont de Nemours and BASF occupy positions exemplifying synthetic polymer expertise and modified cellulose chemistry respectively. Tate & Lyle represents the ingredient specialist archetype with stated emphasis on backward integration into specialty starch cultivation. These three entities anchor competitive positioning across high-performance textile sizing, food-grade thickeners, and paints and coatings applications.
| Leading Market Players |
|---|
| DuPont de Nemours |
| Tate & Lyle |
| Cargill |
| Dow |
| BASF |
| Ingredion Incorporated |
| CP Kelco |
| Akzo Nobel |
| Archer Daniels Midland |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day inventory cycles for guar gum and tapioca starch derivatives compress pricing power for natural-source suppliers while extending payment terms for synthetic polymer distributors. This lead-time band concentrates margin capture with backward-integrated starch processors and petroleum-linked acrylate producers who command volume-commitment pricing.
Pricing Analysis
Volume-discount tiering structures stratify procurement across annual offtake commitments exceeding five hundred metric tons. Food-grade hydrocolloids with FSSAI documentation and REACH-registered textile sizing agents command fifteen-to-twenty percent premiums over uncertified equivalents. Cost compression in synthetic polymer grades intensifies as Indian PLI scheme incentives expand domestic polyacrylate capacity. Commodity textile mills exhibit acute price sensitivity, while cosmetic brands purchasing fermentation-derived exopolysaccharides prioritize batch-level traceability over unit economics.
Supply Chain Analysis
The Jawaharlal Nehru Port Trust throughput chokepoint filters Indian import-export flows for specialty hydrocolloids and sizing chemicals. Manufacturing concentrates in China for modified cellulose, India for guar gum cultivation and processing, and Germany for precision fermentation platforms. Feedstock sourcing draws from petroleum-derived acrylates, ethylene-based polymers, and agricultural starches. Single-source vulnerability runs through Chinese cellulose ether plants facing MEE dual carbon quota constraints. Distribution runs through certified ingredient distributors for food-contact grades and direct mill relationships for textile applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service agreements and joint rheology mapping protocols expand recurring revenue attachment faster than base chemical sales. This service-attach opportunity deepens as formulation complexity rises across clean-label food and microbiome-positioned personal care segments.
For Market Incumbents: Consolidate backward integration into specialty starch cultivation and precision fermentation capacity to defend against bio-based substitute technologies. Expand BIS-certified production in Gujarat's chemical belt to capture PLI-driven textile demand before import-dependent competitors qualify. Lock in multi-year technical service contracts with premium cosmetic brands to reduce spot-market exposure. For New Entrants and Emerging Players: Lead with fermentation-derived hydrocolloids targeting North American clean-label food processors seeking supply security beyond Indian guar gum harvest variability. Penetrate the personal care microbiome positioning segment where established suppliers lack documented molecular weight distribution capabilities. Deploy direct technical sales teams to bypass traditional distributor markups in premium formulation accounts. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because REACH authorization timelines and FDA GRAS petition backlogs create durable moats for qualified suppliers. Target fermentation technology platforms with commercial-scale microbial cellulose production. Watch ECHA substance evaluation timelines as the inflection signal for biodegradable thickener substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Starch Cultivation | Tate & Lyle's captive supply chains reduce harvest variability exposure for food-grade thickeners. |
| Precision Fermentation Capacity Expansion | Cultured microbial cellulose achieves tighter molecular weight distribution than plantation-sourced equivalents. |
| BIS Certification Investment | Domestic Indian producers qualify for PLI scheme textile incentives filtering unqualified import suppliers. |
| Technical Service Agreement Expansion | Joint rheology mapping protocols shorten distributor channels in premium personal care segments. |
| Green Manufacturing Transition | ECHA safe-and-sustainable-by-design criteria reward renewable feedstock certificates in EU coatings. |
Research Methodology
A standing panel of textile mill technical directors, food formulation chemists, paint R&D managers, and hydrocolloid procurement leads provided ongoing calibration across primary interview cycles. Secondary validation drew from BIS certification registries, FSSAI food additive approvals, ECHA REACH authorization databases, and customs trade flow records. Bottom-up volume estimates from end-use consumption patterns triangulated against top-down polymer production capacity assessments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by product type, application, end-use industry, and source origin alongside grade-tier differentiation and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for PLI scheme implementation pacing and ECHA substance evaluation timelines. Forecast inputs incorporated MEE dual carbon quota constraints and FDA food additive rulemaking velocity.
The analysis sits within stated boundaries; outcomes outside sustained PLI scheme funding or accelerated REACH microplastic restrictions would require recalibration. Forecasts reflect documented assumptions around fermentation technology scale-up rates and agricultural harvest stability. Practitioners should keep alternative scenarios live as ECHA authorization timelines and Indian domestic manufacturing incentives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Dipentene (Limonene) Market
Specialty Chemicals
Nucleotides Market
Specialty Chemicals
AEA Salicylic Acid Market
Specialty Chemicals
Global Prepacked Chromatography Columns Market
Specialty Chemicals
Silicone Acrylate Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Eco-Friendly Plasticizers Market
Specialty Chemicals
North America Chromatography Resins Market
Specialty Chemicals
Diisononyl Adipate (DINA) Market
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
Phospholipid Market
Specialty Chemicals
Petroleum Jelly Market
Specialty Chemicals
Global Specialty Resins Market
Specialty Chemicals
Perms and Relaxants Market
Specialty Chemicals
Fatty Alcohol Alkoxylates Market
Specialty Chemicals
Ricinoleic Acid Market