
 Glucosinolates Market | 2026-2036
Glucosinolates Market Size, Share, and Industry Trends Forecast 2026-2036
Glucosinolates Market Analysis
Pharmaceutical and nutraceutical end-use demand is hardening as formulators replace synthetic bioactives with plant-derived alternatives. Xian Yuensun Biological anchors Chinese supply chains through captive extraction infrastructure. Kirkman Group differentiates via allergen-free certification protocols for pediatric and sensitive populations. Jarrow Formulas GmbH leverages European distribution density to place glucosinolate complexes in pharmacy and practitioner channels.
Glucosinolates are sulfur-containing glucosides stored in brassica family plants, released upon tissue disruption by the enzyme myrosinase to yield isothiocyanates and indoles with documented bioactivity. Industrial extraction employs cold-press or solvent methods followed by chromatographic standardization to achieve defined sulforaphane or glucoraphanin concentrations. Dietary supplement applications lead volume uptake as clinical studies on Nrf2 pathway activation drive practitioner recommendation. Broccoli-derived extracts command premium positioning due to sulforaphane concentration benchmarks, while kale and Brussels sprout sources occupy mid-tier functional food tiers. Agricultural applications in biopesticide development represent an emerging margin pool with lower current volume but higher regulatory barriers.
EFSA Novel Food classifications and FDA GRAS self-affirmation pathways shape market access timelines for new glucosinolate concentrates. REACH registration requirements in Europe enforce batch-level contaminant testing that elevates compliance costs for smaller extractors. Stakeholders must monitor evolving pharmacovigilance frameworks as glucosinolate isolates migrate from supplement aisles toward drug-adjacent positioning requiring clinical trial substantiation.
Market Dynamics
Clinical validation of Nrf2 pathway activation is compressing development timelines for glucosinolate-based supplements, forcing extractors to synchronize batch standardization with evolving pharmacovigilance frameworks before products migrate toward drug-adjacent positioning.
Growth Catalysts
- EFSA Novel Food pathway acceleration:Streamlined safety assessments for brassica-derived concentrates are shortening market access timelines for standardized sulforaphane formulations in European nutraceutical channels.
- Dietary supplement formulators:Practitioner-grade brands are replacing synthetic antioxidants with glucoraphanin complexes backed by peer-reviewed clinical data on cellular defense mechanisms.
- German pharmacy procurement:Apotheken networks are expanding shelf space for glucosinolate complexes as reimbursement-adjacent wellness products gain physician recommendation protocols.
Market Restraints
- REACH batch-level contaminant testing:ECHA enforcement of residual solvent and heavy metal thresholds elevates compliance costs disproportionately for smaller extraction operations without captive analytical laboratories.
- Brassica biomass concentration:Raw material sourcing clusters in Shaanxi and Gansu provinces create geographic vulnerability to climate-induced crop yield variability.
- Synthetic bioactive substitution:Pharmaceutical formulators retain N-acetylcysteine and other manufactured antioxidants in cost-sensitive therapeutic categories where plant-derived standardization premiums encounter resistance.
Strategic Opportunities
- Indian functional food expansion:FSSAI regulatory clarity on glucosinolate fortification in traditional dairy and beverage formats opens penetration pathways for extractors targeting Ayurveda-influenced wellness consumers.
- Biopesticide registration tailwinds:EPA biopesticide division fast-tracks brassica-derived nematicide formulations as agricultural operators seek alternatives to synthetic soil fumigants facing cancellation pressure.
- Chromatography-AI convergence:Machine learning-driven metabolite fingerprinting is compressing standardization cycles for complex glucosinolate profiles in multi-source extracts.
Industry Challenges
- Myrosinase stability engineering:Formulators face execution gaps in preserving enzyme activity through shelf-stable delivery formats, limiting bioavailability claims in ambient-storage supplement products.
- GRAS self-affirmation documentation:FDA notification preparation for novel glucosinolate concentrates demands toxicological study investments that strain mid-tier extractor R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucosinolates Market |
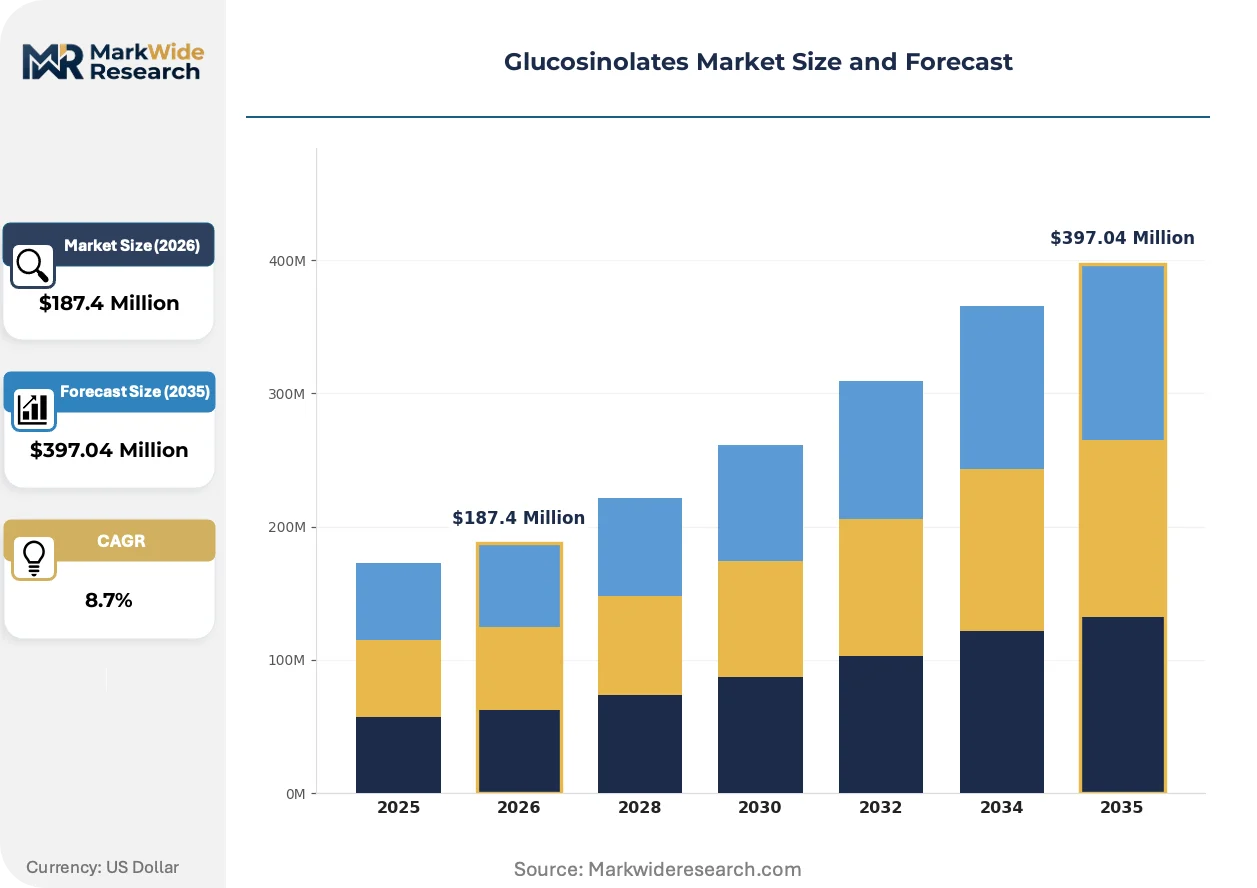
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broccoli, Kale, Brussels Sprouts, Cabbage Application: Food Additive, Dietary Supplement, Pharmaceutical, Agricultural End User: Food Industry, Healthcare Providers, Agricultural Sector, Nutraceuticals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Xian Yuensun Biological Co., Ltd, Kirkman Group, Jarrow Formulas GmbH, Brightol, Wincobel, Nutra Canada, Seagate Products, Interherb Ltd., Native Extracts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucosinolates Market Emerging Trajectories
Enzymatic stabilization technologies and regulatory pathway optimization are compressing the gap between raw extract production and clinically substantiated finished formulations, reshaping competitive advantage toward integrated quality verification systems.
Myrosinase encapsulation via lipid-based delivery matrices is rewriting shelf-stability economics for sulforaphane-activated supplements. Pediatric and geriatric formulators are adopting these systems fastest, with practitioner-channel brands leading pharmacy placement. The technology is compressing spoilage rates and enabling ambient-distribution claims previously restricted to cold-chain logistics.
REACH registration expansion under ECHA's 2023 substance evaluation work program is tightening residual pesticide specifications for botanical imports. European extractors with in-house GC-MS capabilities are capturing contract manufacturing share from importers dependent on third-party testing. Broccoli seed extract categories face the steepest compliance recalibration timelines.
Practitioner-channel consolidation is displacing mass-market retail as the primary volume pathway for premium glucosinolate complexes. Functional medicine clinics and integrative pharmacy networks are replacing health food store distribution in Germany and France. This channel rotation is most visible in urban clusters where physician dispensing laws create prescription-adjacent purchase environments.
Glucosinolates Market Segmentation
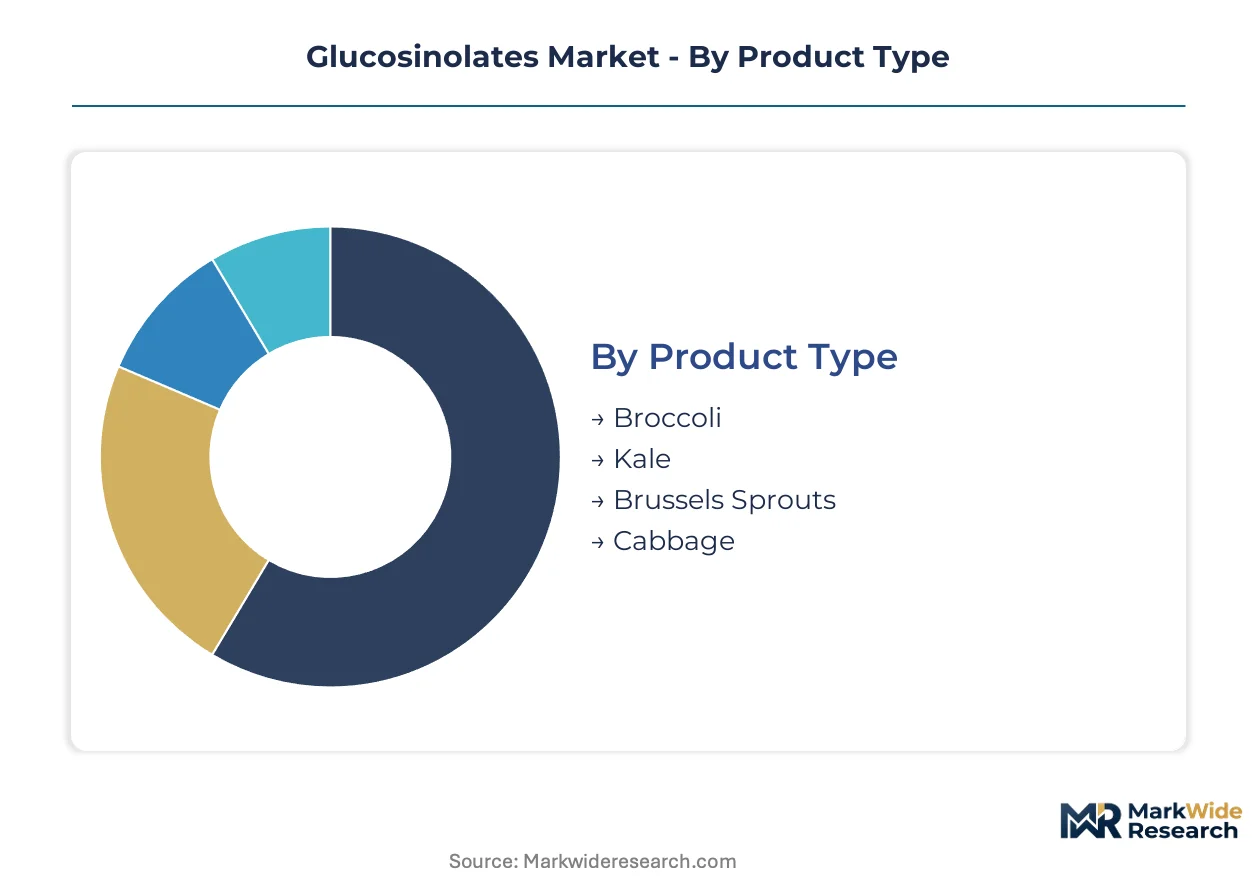
Glucosinolate sourcing and formulation requirements diverge sharply across extraction matrices and end-use specifications. Segmentation reveals how brassica origin determines bioactive yield, regulatory pathway, and pricing tier in finished goods markets.
Product Type:
Buyers in this category differentiate primarily by sulforaphane concentration benchmarks and standardization costs.
- Broccoli:Seed and sprout extracts yield the highest glucoraphanin-to-sulforaphane conversion rates upon myrosinase activation. German nutraceutical formulators pay premiums for certified seed extracts meeting EFSA Novel Food purity thresholds.
- Kale:Leaf-derived concentrates carry lower sulforaphane titers but broader glucosinolate diversity profiles. Functional food manufacturers in France incorporate kale extracts into ambient-stable beverage formats where milder flavor notes prove advantageous.
- Brussels Sprouts:Mid-tier positioning for bulk glucosinolate sourcing with established supply chains in Belgian and Dutch agricultural zones.
- Cabbage:Cost-optimized feedstock for agricultural biopesticide applications with lower standardization requirements.
Volume sits with Broccoli; growth tilts toward Kale.
Application:
Margin capture in this category tracks regulatory complexity and clinical substantiation depth.
- Dietary Supplement:Practitioner-grade brands demand batch-certified glucoraphanin complexes with Nrf2 pathway activation documentation. Jarrow Formulas GmbH and Kirkman Group compete on allergen-free certification and pediatric formulation protocols.
- Pharmaceutical:Drug-adjacent positioning requires IND-enabling toxicology packages and GMP manufacturing compliance. Clinical trial substantiation for oncology support indications drives multi-year development timelines.
- Food Additive:Fortification applications in dairy and plant-based beverages face FSSAI and FDA GRAS pathway variability.
- Agricultural:Biopesticide registrations through EPA fast-track channels exploit brassica nematicide properties as synthetic fumigant alternatives face cancellation.
Revenue concentrates in Dietary Supplement; steepest expansion trajectory belongs to Pharmaceutical.
End User:
Procurement sophistication in this category separates specification-driven buyers from commodity-accepting segments.
- Nutraceuticals:Contract manufacturers enforce chromatographic fingerprinting and residual solvent testing exceeding baseline regulatory minimums. REACH-registered suppliers capture share from importers lacking captive analytical laboratories.
- Healthcare Providers:Functional medicine clinics and integrative pharmacy networks in Germany drive practitioner-channel consolidation with prescription-adjacent dispensing protocols.
- Food Industry:Clean-label positioning demands non-GMO and organic certification chains with traceability to Shaanxi and Gansu cultivation zones.
- Agricultural Sector:Formulators of soil amendments and crop protection products prioritize cost-per-hectare efficacy over bioactive standardization.
Supply tilts toward Nutraceuticals; pricing power accumulates with Healthcare Providers.
Distribution Channel:
Channel selection in this category determines margin retention and brand positioning latitude.
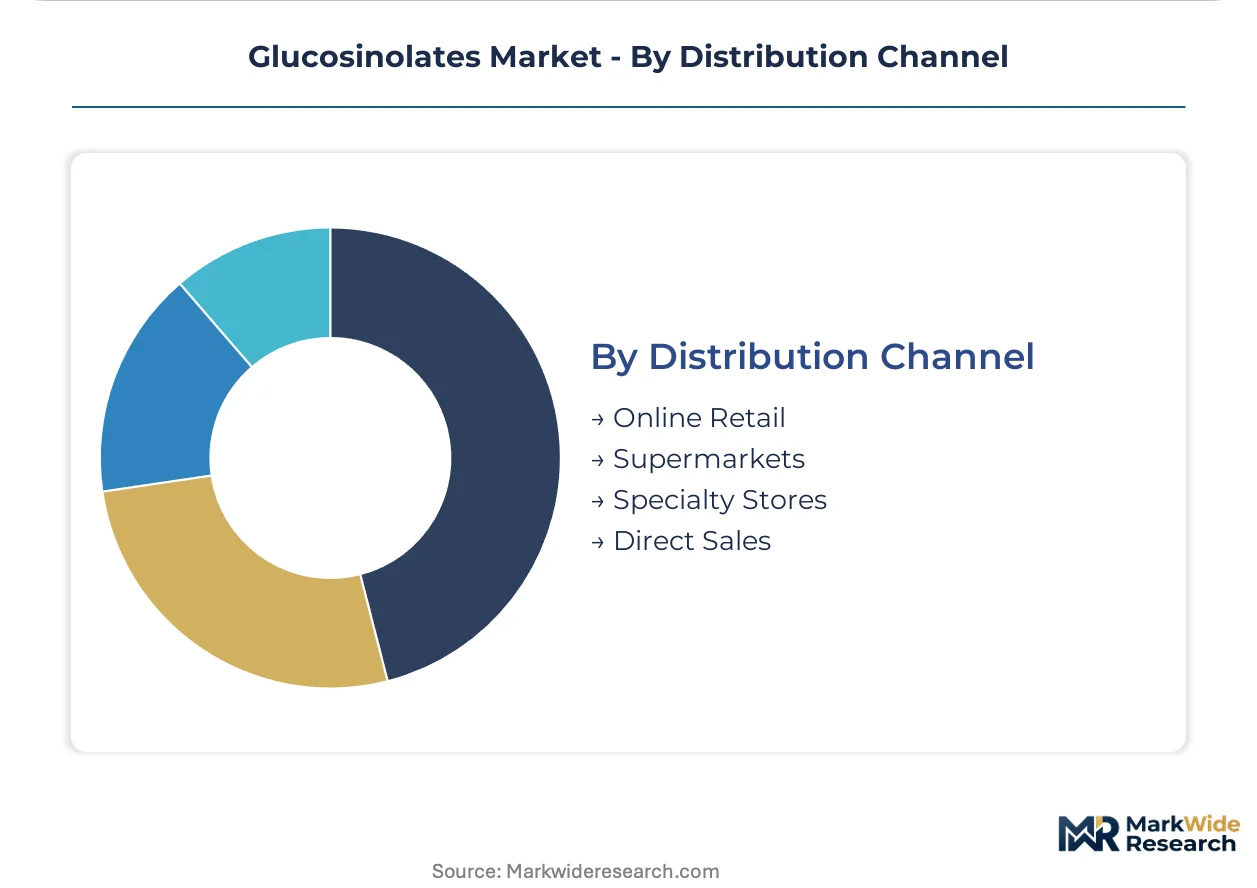
- Direct Sales:Practitioner-only distribution through functional medicine clinics enables premium pricing and clinical education investment. German Apotheken networks expand shelf space for reimbursement-adjacent wellness protocols.
- Specialty Stores:Health food retailers face displacement as pharmacy and clinic channels capture premium glucosinolate complex volumes.
- Online Retail:Direct-to-consumer subscription models compress customer acquisition costs for standardized supplement lines with repeat purchase economics.
- Supermarkets:Mass-market placement limited to basic glucosinolate-fortified functional foods with lower bioactive concentration claims.
Volume accumulates in Direct Sales; channel expansion concentrates in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shaanxi Free Trade Zone incentives have concentrated glucosinolate extraction infrastructure in China's northwest corridor, drawing contract manufacturers from coastal provinces seeking lower processing costs and streamlined customs procedures for botanical exports.
Germany
Apotheken networks in Berlin and Munich are expanding practitioner-channel distribution for glucoraphanin complexes as physician dispensing laws create prescription-adjacent purchase environments. EFSA Novel Food classifications enforce batch-level purity documentation that favors REACH-registered domestic extractors over importers. The Baden-Württemberg cluster around Stuttgart hosts chromatographic standardization facilities serving Central European nutraceutical formulators.
United States
Functional medicine clinics in California and Texas are driving direct-to-practitioner procurement of sulforaphane-activated supplements with Nrf2 pathway documentation. EPA biopesticide division fast-tracks brassica-derived nematicide registrations as agricultural operators in Iowa and Nebraska seek alternatives to synthetic soil fumigants. FDA GRAS self-affirmation pathways for novel glucosinolate concentrates remain concentrated among extractors with captive toxicological study capabilities.
France
Nutraceutical formulators in Lyon and Paris are incorporating kale-derived glucosinolate concentrates into ambient-stable beverage formats where milder flavor profiles prove advantageous over broccoli extracts. ANSM pharmacovigilance frameworks are tightening documentation requirements for supplement-adjacent wellness claims. The Provence-Alpes-Côte d'Azur region hosts organic certification bodies tracing supply chains to Shaanxi cultivation zones.
India
FSSAI regulatory clarity on glucosinolate fortification in traditional dairy and beverage formats is opening penetration pathways for extractors targeting Ayurveda-influenced wellness consumers in Maharashtra and Karnataka. CDSCO is evaluating pharmacovigilance frameworks for botanical isolates migrating toward drug-adjacent positioning. Contract manufacturers in Hyderabad are upgrading chromatographic capabilities to meet European import specifications.
Australia
TGA complementary medicine regulations are compressing market access timelines for standardized sulforaphane formulations through streamlined safety assessment pathways. Native extractors in New South Wales and Victoria are developing multi-source glucosinolate profiles for export to Southeast Asian functional food markets. Sydney-based analytical laboratories are capturing contract testing share from European importers seeking batch certification for REACH compliance.
Glucosinolates Market Vendor Landscape
Top-tier vendors anchor premium practitioner-channel positioning, while mid-tier extractors compete on standardization speed and regulatory documentation breadth. The vendor base stratifies across three functional tiers: integrated extraction-to-formulation operators, specialized analytical-standardization houses, and commodity biomass processors. Strategic archetypes include REACH-registered European distributors with captive laboratory infrastructure, Chinese integrated extractors controlling upstream cultivation zones, and allergen-free certification specialists serving pediatric populations. Dominant competitive moves center on backward integration into Shaanxi and Gansu biomass sourcing and machine learning-driven metabolite fingerprinting for batch consistency.
Among Asia-Pacific integrated extractors, Xian Yuensun Biological Co., Ltd anchors the upstream-controlled archetype through northwest China cultivation infrastructure. Kirkman Group and Jarrow Formulas GmbH occupy differentiated positions within practitioner-channel distribution: the former exemplifies allergen-free certification protocols for sensitive populations, while the latter represents European pharmacy network density for standardized supplement placement. These three entities illustrate how competitive advantage is concentrating around regulatory documentation depth and channel-specific formulation expertise rather than extraction scale alone.
| Leading Market Players |
|---|
| Xian Yuensun Biological Co., Ltd |
| Kirkman Group |
| Jarrow Formulas GmbH |
| Brightol |
| Wincobel |
| Nutra Canada |
| Seagate Products |
| Interherb Ltd. |
| Native Extracts |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between REACH-registered European extractors and unregistered importers manifests in both pricing premiums and supply chain control structures, with compliant suppliers capturing pharmacy-channel margins while spot-market buyers absorb third-party testing costs and customs delays.
Pricing Analysis
Short lead-time premiums for EFSA Novel Food-certified glucoraphanin concentrates command substantial markups over spot inventory sourced through Shaanxi trading houses. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with practitioner-grade brands paying least price sensitivity for batch-level chromatographic documentation. Pricing pressure stems from synthetic antioxidant substitution in cost-sensitive therapeutic categories, forcing mid-tier extractors toward biopesticide diversification. Contract manufacturers with captive analytical laboratories exhibit lowest price sensitivity; commodity biomass processors face highest margin compression.
Supply Chain Analysis
Freight cost volatility from Shaanxi and Gansu provinces to European ports is reshaping sourcing economics for glucosinolate concentrates, with Rotterdam and Hamburg logistics hubs absorbing disproportionate cost inflation. Geographic supply concentration centers on China, Belgium, and Germany, with Dutch agricultural zones feeding Brussels sprout feedstock and Baden-Württemberg hosting chromatographic standardization. Raw material dependencies include brassica seed stock, cold-press extraction equipment, and myrosinase stabilization reagents. Single-source vulnerability from Shaanxi climate exposure threatens biomass security. Distribution runs through practitioner-channel direct sales and pharmacy networks, displacing traditional health food retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as REACH batch-testing mandates and EFSA Novel Food documentation requirements force smaller extractors toward exit or acquisition, with compliant mid-tier players becoming attractive targets for integrated operators seeking regulatory moats.
For Market Incumbents: Hedge against synthetic bioactive substitution by deepening backward integration into Shaanxi cultivation zones and securing long-term brassica seed supply agreements. Prioritize machine learning-driven metabolite fingerprinting investments to compress standardization cycles and defend practitioner-channel positioning against emerging AI-enabled analytical houses. Regulatory documentation depth remains the priority lever for margin retention. For New Entrants and Emerging Players: Capture white-space in Indian functional food expansion where FSSAI regulatory clarity on glucosinolate fortification remains underexploited by incumbent extractors. Target Ayurveda-influenced wellness consumers in Maharashtra and Karnataka through joint venture structures with domestic dairy processors. Direct-to-practitioner distribution offers fastest penetration pathway for clinically substantiated formulations. For Investors and Strategic Acquirers: Re-rating potential sits with REACH-registered mid-tier extractors possessing captive GC-MS capabilities given accelerating ECHA enforcement timelines and importer displacement dynamics. Long-term viability over the coming decade favors operators with integrated extraction-to-formulation infrastructure and pharmacy network density. Signal to monitor: EPA biopesticide registration velocity for brassica-derived nematicides as synthetic fumigant cancellation pressure mounts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Zones | Upstream control over Shaanxi and Gansu biomass secures supply against climate-induced yield variability. |
| Machine Learning-Driven Metabolite Fingerprinting | AI-enabled batch consistency compresses standardization cycles for complex multi-source glucosinolate profiles. |
| EFSA Novel Food Registration Acceleration | Streamlined safety assessments shorten market access timelines for standardized sulforaphane formulations. |
| Practitioner-Channel Direct Sales Expansion | Pharmacy network density in Germany captures premium pricing through physician-adjacent dispensing protocols. |
| Biopesticide Registration Diversification | EPA fast-track pathways for brassica-derived nematicides open margin pools as synthetic fumigants face cancellation. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with extraction plant managers, nutraceutical formulators, regulatory affairs leads at EFSA-registered suppliers, pharmacy procurement officers in German Apotheken networks, and agricultural biopesticide developers. ECHA substance evaluation databases, FDA GRAS notification repositories, FSSAI fortification guidelines, and Shaanxi provincial export statistics provided triangulation anchors. Bottom-up volume modeling across extraction matrices converged with top-down market sizing from import-export flows.
Granularity-level modeling applied country-specific regulatory pathway timelines, brassica origin bioactive yield differentials, and channel-specific margin structures across the projection horizon. Segmentation dimensions included product type extraction matrix, application regulatory complexity tier, end-user procurement sophistication, and distribution channel margin retention. CAGRs derived from fitted growth curves incorporating clinical validation velocity and pharmacovigilance framework evolution. Industry-specific inputs encompassed myrosinase stabilization technology adoption rates and practitioner-channel consolidation patterns.
The model holds under stable REACH enforcement intensity and continued EFSA Novel Food pathway operation; deviation in EPA biopesticide registration velocity or Shaanxi climate patterns would shift volume trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Homosalate Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
Lactic Acid Blend Market
Specialty Chemicals
Cholesteryl Isostearate Market
Specialty Chemicals
Silicone Acrylate Market
Specialty Chemicals
2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market
Specialty Chemicals
Ytterbium Fluoride Market
Specialty Chemicals
AEA Salicylic Acid Market
Specialty Chemicals
Marine Hyaluronic Acid Market
Specialty Chemicals
Croscarmellose Sodium Market
Specialty Chemicals
Europe Non-Phthalate Plasticizers Market
Specialty Chemicals
Sizing and Thickening Market
Specialty Chemicals
Global Blowing Agent Market
Specialty Chemicals
Barium Sulfate Market
Specialty Chemicals
Acrylic Powder Market
Specialty Chemicals
Germany Starch Derivatives Market