
 Phenyl Trimethicone Market | 2026-2036
Phenyl Trimethicone Market Size, Share, and Industry Trends Forecast 2026-2036
Phenyl Trimethicone Market Analytics
China is reconfiguring regional supply dynamics through expanded silicone intermediate capacity in Jiangsu and Zhejiang provinces. Dow leverages integrated silicone manufacturing to sustain cost advantages across phenyl trimethicone derivatives. Elkem Silicones anchors European supply security with specialized high-purity grades for cosmetic applications. Innospec competes through differentiated conditioning agent portfolios targeting premium hair care brands.
Phenyl trimethicone is a phenyl-substituted trimethylsiloxy-terminated silicone fluid with refractive index typically ranging from 1.46 to 1.48 and viscosity between 20 and 25 centistokes, valued for imparting shine, lubricity, and water repellency in topical formulations. Cosmetic grade phenyl trimethicone dominates value generation due to stringent purity requirements and brand-certified supply chains, while pharmaceutical grade represents the fastest-expanding segment as topical drug delivery systems adopt silicone excipients for enhanced skin penetration and stability. Personal care brands command the largest end-user share, though contract manufacturers are capturing margin pools through toll-processing agreements with emerging direct-to-consumer labels.
REACH registration requirements in Europe and FDA oversight of cosmetic ingredients in the United States constrain market entry for uncertified producers, while China's NMPA and GB standards for cosmetic raw materials impose additional testing protocols on imported silicone fluids. The EU Green Deal's chemical sustainability targets are pressuring reformulation away from certain persistent silicone variants, though phenyl trimethicone retains favorable regulatory standing relative to cyclic alternatives. Stakeholders must monitor evolving biocompatibility standards and regional clean beauty certifications to preserve formulation eligibility across key export markets.
Market Dynamics
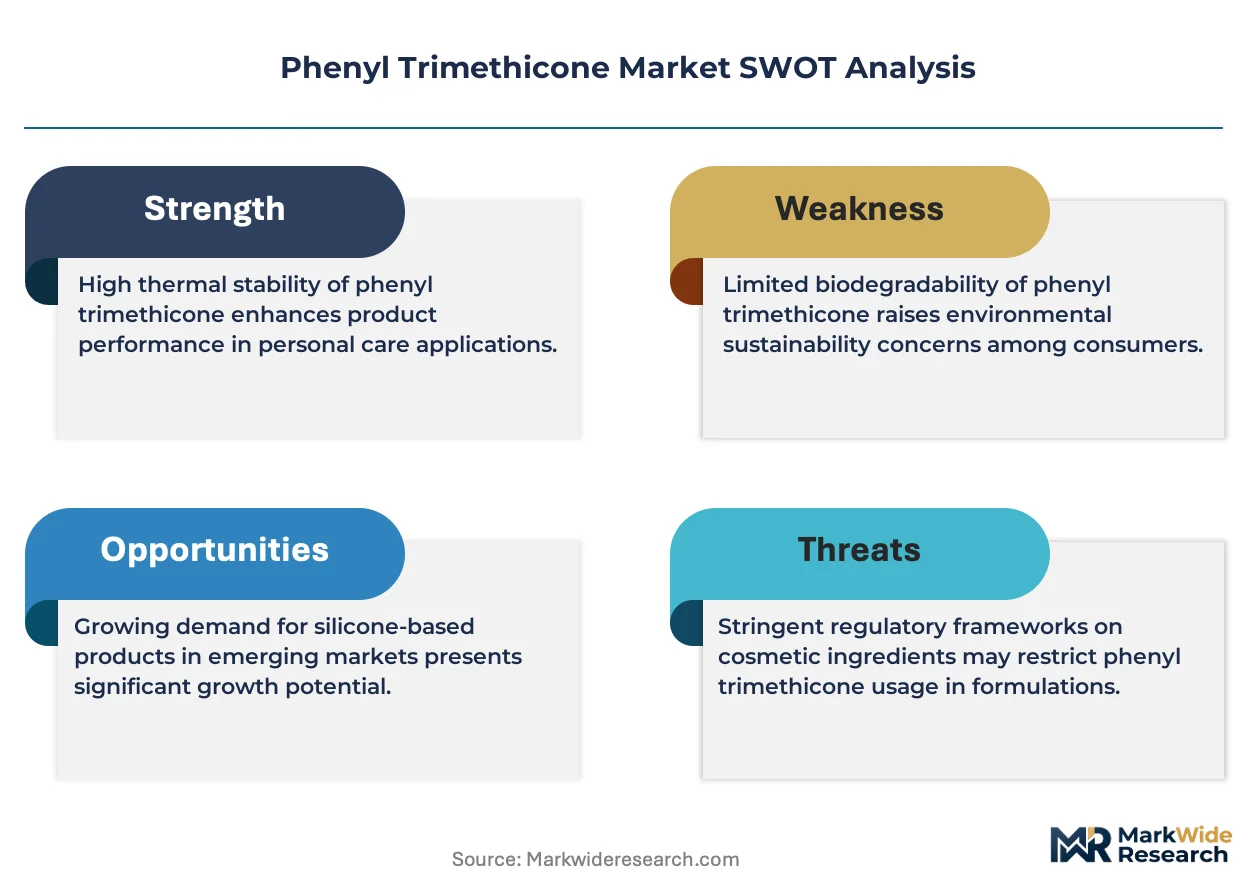
Clean beauty certification requirements and silicone disclosure mandates are forcing reformulation investments across cosmetic supply chains, compressing margins for uncertified phenyl trimethicone producers while rewarding brand-certified supply chain partners.
Growth Catalysts
- EU Green Deal chemical sustainability targets:REACH-compliant phenyl trimethicone retains favorable standing versus cyclic silicone alternatives, redirecting formulation budgets toward compliant phenyl-substituted grades in European personal care manufacturing.
- Premium hair care serums:Personal care brands are expanding phenyl trimethicone formulations for enhanced spreadability and gloss, particularly in leave-in conditioning products targeting professional salon channels.
- China's NMPA cosmetic raw material standards:Domestic manufacturers scaling premium silicone-based product lines are driving import substitution and local phenyl trimethicone capacity expansion in Jiangsu and Zhejiang provinces.
Market Restraints
- Silicone intermediate feedstock volatility:Phenyl chlorosilane and methyl chlorosilane price swings compress derivative margins unpredictably, especially for non-integrated compounders lacking captive chlorosilane supply.
- European supply concentration:High-purity cosmetic grades depend on a limited set of specialized European producers, creating vulnerability to regional energy cost spikes and logistics disruptions.
- Cyclic dimethicone substitution:Lower-cost dimethicone alternatives with comparable sensory profiles threaten phenyl trimethicone volume in mass-market hair care where shine performance is deprioritized.
Strategic Opportunities
- Pharmaceutical grade silicone excipients:Topical drug delivery systems are adopting phenyl trimethicone for enhanced skin penetration and API stability, opening higher-margin segments beyond cosmetics.
- Toll-processing agreements:Contract manufacturers are capturing margin pools through toll-processing partnerships with emerging direct-to-consumer labels seeking flexible batch sizes and rapid formulation iteration.
- India's PLI scheme for specialty chemicals:Domestic production incentives are attracting investment in silicone intermediate capacity, potentially reshaping Asia-Pacific supply sourcing for Indian cosmetic formulators.
Industry Challenges
- Biocompatibility testing protocols:Evolving ISO 10993 standards and regional clean beauty certifications require continuous toxicological investment, extending new product qualification timelines.
- Legacy formulation integration:Substituting phenyl trimethicone into established product lines demands stability revalidation and sensory matching, complicating rapid reformulation responses to regulatory pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenyl Trimethicone Market |
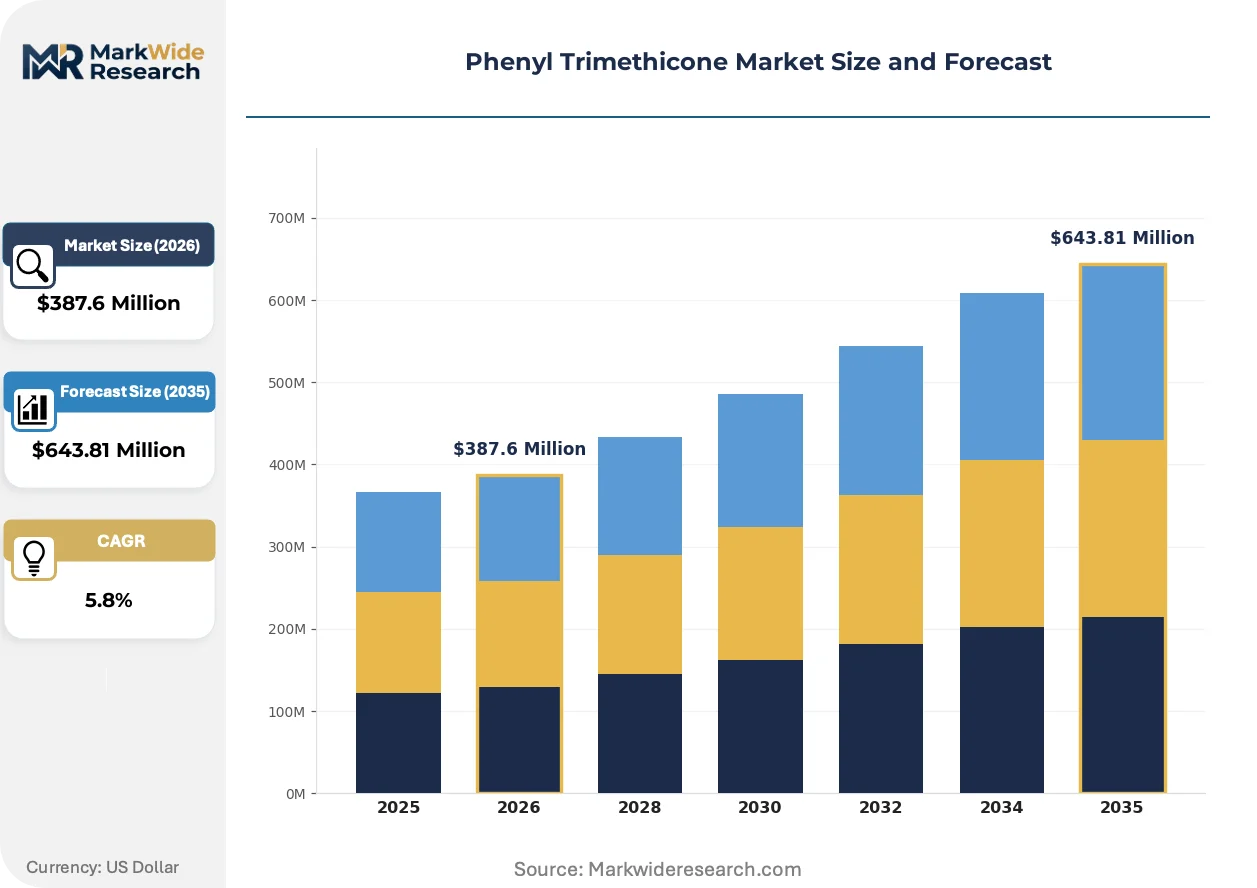
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetic Grade, Industrial Grade, Pharmaceutical Grade, Personal Care Grade Application: Skin Care, Hair Care, Makeup, Conditioning Agents End User: Cosmetic Manufacturers, Personal Care Brands, Pharmaceutical Companies, Contract Manufacturers Distribution Channel: Online Retail, Specialty Retail Stores, Distributors, Direct Sales |
| Companies Covered | BASF, Dow, Elkem Silicones, Innospec, AB Specialty Silicones, BRB International BV, BioMax Si&F, KCC Beauty, Chemyunion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenyl Trimethicone Market Evolving Landscape
Silicone fluid technology is bifurcating between high-purity specialty grades for regulated applications and commoditized alternatives for mass-market personal care, with regulatory compliance emerging as the primary axis of competitive differentiation.
Low-viscosity phenyl trimethicone variants with refractive indices above 1.47 are rendering obsolete traditional high-viscosity dimethicone in premium hair oil formulations. Prestige hair care brands in South Korea and Japan are adopting these grades for superior light reflection without heaviness. The shift is compressing demand for older silicone generations in Asia-Pacific professional salon channels.
REACH registration dossier updates under ECHA's substance evaluation program are tightening impurity disclosure thresholds for phenyl-substituted silicones used in leave-on cosmetic products. Compounders must now document phenyl siloxane oligomer content below 100 ppm, increasing analytical testing burdens. European formulators are responding by consolidating supplier bases to pre-certified specialty chemical partners with established regulatory data packages.
Direct-to-consumer beauty brands are unbundling traditional distributor relationships in favor of ingredient-traceable supply chains with documented sustainability credentials. These buyers are bypassing regional chemical distributors to contract directly with phenyl trimethicone producers offering blockchain-verified batch records. The pattern is most visible in North American and Western European markets where clean beauty certification carries premium pricing power.
Phenyl Trimethicone Market Segmentation
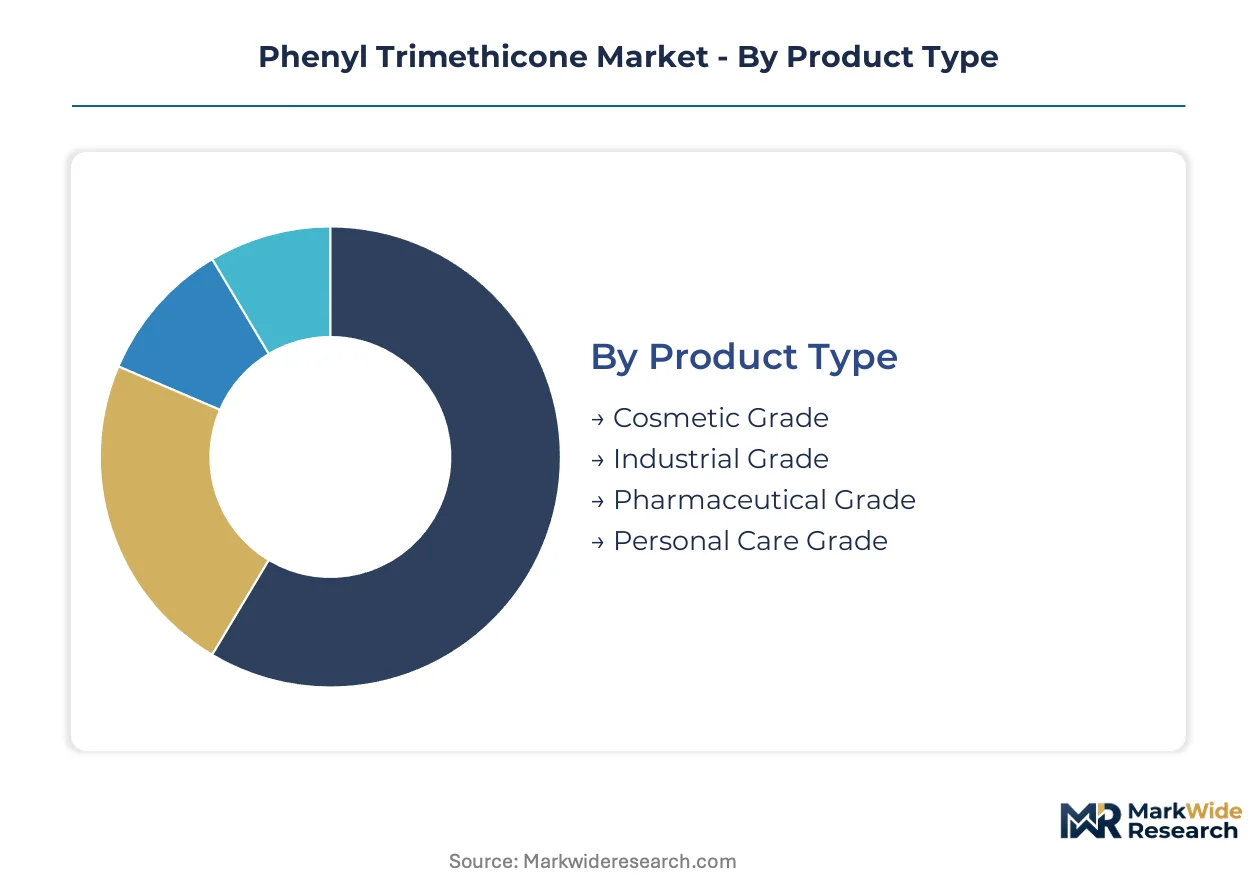
Phenyl trimethicone formulations vary dramatically in purity thresholds and certification requirements across end-use applications. Segment boundaries determine pricing power, regulatory burden, and supplier qualification timelines for compounders and brands.
Product Type:
Cosmetic grade commands the longest production cycles due to brand-certified supply chain audits, while industrial grade turns inventory fastest through standardized bulk specifications.
- Cosmetic Grade:Phenyl trimethicone with refractive index 1.46–1.48 and viscosity 20–25 centistokes, refined to sub-100 ppm phenyl siloxane oligomer content per REACH updates. European personal care manufacturers consolidate supplier bases to pre-certified specialty partners with established ECHA dossiers.
- Pharmaceutical Grade:High-purity silicone excipients meeting ISO 10993 biocompatibility protocols for topical drug delivery systems. Contract manufacturers in North America adopt these grades for enhanced API stability and skin penetration in dermatological formulations.
- Industrial Grade:Standardized fluid specifications for lubricant and coating applications without cosmetic or pharmaceutical certification overhead.
- Personal Care Grade:Intermediate purity tier serving mass-market hair care and skin care formulations with streamlined testing protocols.
Cosmetic grade anchors the volume base while pharmaceutical grade gains share at the steepest rate.
Application:
Leave-in hair care products absorb the highest formulation volumes, whereas professional salon serums concentrate value through premium positioning.
- Hair Care:Low-viscosity phenyl trimethicone variants with refractive indices above 1.47 displace traditional dimethicone in premium hair oils. South Korean and Japanese prestige brands adopt these grades for superior light reflection without sensory heaviness.
- Skin Care:Silicone fluids enhance spreadability and water repellency in moisturizers and sun care. China's NMPA-compliant domestic manufacturers scale these formulations for premium product lines targeting professional channels.
- Makeup:Phenyl trimethicone imparts gloss and longevity to color cosmetics through film-forming properties.
- Conditioning Agents:Functional silicone additives for rinse-off and leave-in conditioning products across mass and prestige tiers.
Hair care dominates absolute volume while skin care applications expand most quickly.
End User:
Contract manufacturers operate on compressed batch cycles for direct-to-consumer brands, while pharmaceutical companies endure extended qualification timelines for excipient validation.
- Cosmetic Manufacturers:Integrated formulators with in-house compounding capabilities and established raw material qualification systems.
- Personal Care Brands:Brand owners specifying silicone grades for outsourced production, increasingly demanding blockchain-verified batch records and sustainability credentials.
- Pharmaceutical Companies:Drug developers incorporating phenyl trimethicone as functional excipients in topical delivery systems, subject to FDA oversight and ISO 10993 testing protocols.
- Contract Manufacturers:Toll-processing specialists capturing margin pools through flexible batch sizes and rapid formulation iteration for emerging direct-to-consumer labels.
Personal care brands anchor the volume base while contract manufacturers gain share at the steepest rate.
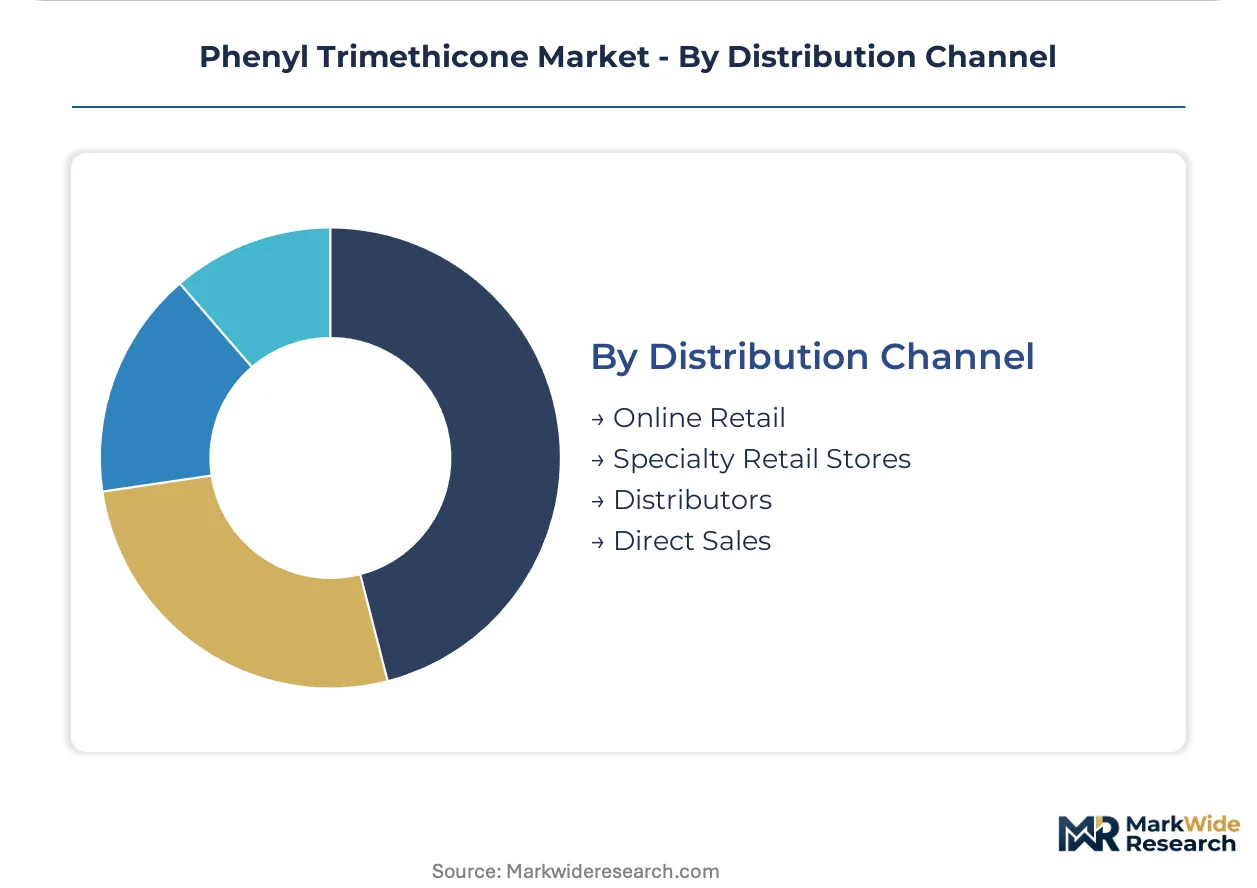
Distribution Channel:
Direct sales relationships require the longest procurement cycles for regulatory documentation, whereas online retail enables rapid spot purchasing for small-scale formulators.
- Direct Sales:Producer-to-formulator relationships with embedded technical service and custom specification development.
- Distributors:Regional chemical distributors holding inventory for mid-tier cosmetic manufacturers with standardized grade requirements.
- Specialty Retail Stores:Niche channels serving artisanal and independent formulators with small-pack silicone fluids.
- Online Retail:E-commerce platforms enabling ingredient-traceable supply chains, particularly visible in North American and Western European markets where clean beauty certification carries premium pricing power.
Distributors anchor the volume base while direct sales gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical liquid bulk terminals anchor European silicone fluid distribution, while Shanghai Yangshan深水港 enables China's dominance in phenyl-substituted silicone intermediates. These maritime gateways determine regional cost structures and supply security.
China
Domestic cosmetic manufacturers in Jiangsu and Zhejiang provinces are scaling premium silicone-based product lines for professional salon channels. NMPA cosmetic raw material standards impose additional testing protocols on imported silicone fluids, accelerating local phenyl trimethicone capacity expansion. The Yangtze River Delta chemical cluster hosts integrated silicone intermediate plants serving both domestic formulators and export markets.
United States
Contract manufacturers in New Jersey and California are capturing margin pools through toll-processing agreements with direct-to-consumer beauty brands. FDA oversight of cosmetic ingredients constrains market entry for uncertified phenyl trimethicone producers. The Gulf Coast petrochemical corridor supplies methyl chlorosilane feedstock to specialty silicone compounders.
Germany
High-purity cosmetic grades depend on specialized producers concentrated in North Rhine-Westphalia and Bavaria. REACH registration requirements under ECHA's substance evaluation program tighten impurity disclosure thresholds for leave-on cosmetic applications. The BASF Ludwigshafen complex anchors integrated silicone manufacturing serving European personal care formulators.
South Korea
Prestige hair care brands in Seoul are adopting low-viscosity phenyl trimethicone variants with refractive indices above 1.47 for superior light reflection. MFDS cosmetic regulations align with ISO 10993 biocompatibility protocols for premium formulations. The Songdo free economic zone hosts contract manufacturing facilities serving regional beauty exporters.
India
Domestic production incentives under the PLI scheme for specialty chemicals are attracting investment in silicone intermediate capacity. CDSCO oversight of cosmetic ingredients parallels FDA frameworks, extending qualification timelines for imported excipients. The Gujarat chemical cluster is emerging as a regional hub for silicone fluid toll-processing serving South Asian cosmetic formulators.
Phenyl Trimethicone Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The phenyl trimethicone market structures around three tiers: integrated petrochemical majors with captive chlorosilane supply, mid-scale specialty silicone compounders, and toll-processing contract manufacturers. Two strategic archetypes dominate competitive positioning: backward-integrated producers leveraging feedstock cost advantages, and formulation-focused specialists competing through regulatory certification depth. Capacity expansion in Asia-Pacific and strategic partnerships for clean beauty certification represent the dominant competitive moves.
Among integrated petrochemical majors, Dow and BASF exemplify the backward-integrated archetype with captive silicone intermediate production. Elkem Silicones and Innospec occupy positions within the specialty compounder tier, competing through differentiated high-purity grades and established ECHA regulatory dossiers. These four companies represent the competitive spectrum from commodity-scale silicone manufacturing to boutique cosmetic-grade certification.
| Leading Market Players |
|---|
| BASF |
| Dow |
| Elkem Silicones |
| Innospec |
| AB Specialty Silicones |
| BRB International BV |
| BioMax Si&F |
| KCC Beauty |
| Chemyunion |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta chemical cluster in Jiangsu and Zhejiang provinces anchors global phenyl trimethicone intermediate capacity, and its expansion dynamics directly compress or inflate downstream formulation costs for cosmetic compounders across Asia-Pacific and European export markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified cosmetic grades from personal care intermediates and uncertified industrial fluids. Price differentiation hinges on ECHA dossier completeness and phenyl siloxane oligomer testing below 100 ppm thresholds. Pricing pressure stems from methyl chlorosilane feedstock volatility squeezing non-integrated compounders. Mass-market hair care brands exhibit highest price sensitivity, while pharmaceutical excipient buyers absorb premiums for ISO 10993 compliance.
Supply Chain Analysis
Tariff exposure between China and Western cosmetic formulators dominates supply chain risk calculus for phenyl trimethicone distributors. Production concentrates in China, Germany, and the United States, with raw material flows drawing from Gulf Coast petrochemical corridors and Yangtze River Delta chlorosilane plants. Single-source vulnerability persists for high-purity cosmetic grades dependent on North Rhine-Westphalia specialty producers. Distribution runs through direct producer-to-formulator relationships for certified grades, with regional chemical distributors serving mid-tier manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean beauty certification fragmentation creates niche entry points for specialized compounders, as direct-to-consumer brands demand blockchain-verified supply chains and documented sustainability credentials that legacy distributors cannot provide.
For Market Incumbents: Build regulatory data package moats by consolidating ECHA dossier investments and expanding REACH-compliant capacity in Zhejiang province. Defensive moves include acquiring toll-processing specialists serving emerging direct-to-consumer labels and embedding technical service teams within premium hair care brand R&D facilities. Cyclic dimethicone substitution in mass-market channels threatens volume erosion. For New Entrants and Emerging Players: Pursue pharmaceutical-grade silicone excipient qualification as the most penetrable white-space target, where ISO 10993 compliance barriers deter commodity producers. India's PLI scheme for specialty chemicals offers geographic entry with domestic production incentives. Go-to-market positioning should emphasize rapid batch customization for contract manufacturers serving dermatological formulations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors backward-integrated compounders with captive chlorosilane supply and established clean beauty certifications. Long-term viability rests on regulatory compliance depth rather than commodity scale. Acquisition targets include specialty silicone producers with pre-certified ECHA dossiers. The signal to watch is NMPA cosmetic raw material standard tightening accelerating import substitution in China.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Feedstock | Dow and BASF leverage captive methyl chlorosilane supply to defend margin compression from raw material volatility. |
| REACH Dossier Consolidation Partnership | Elkem Silicones anchors European supply security through specialized high-purity grades with established ECHA regulatory packages. |
| Pharmaceutical Grade Excipient Qualification | Contract manufacturers in New Jersey adopt ISO 10993-compliant phenyl trimethicone for enhanced API stability in dermatological delivery systems. |
| Toll-Processing Capacity Expansion | Specialty compounders capture margin pools through flexible batch agreements with direct-to-consumer beauty brands seeking rapid formulation iteration. |
| Clean Beauty Certification Investment | Innospec competes through differentiated conditioning agent portfolios targeting premium hair care brands with blockchain-verified batch records. |
Research Methodology
A standing panel of silicone plant managers, cosmetic procurement leads at personal care brands, distribution channel partners, and technical R&D directors provided ongoing calibration across primary interview rounds. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated petrochemical majors, and ECHA substance evaluation dossiers. Bottom-up volume modeling triangulated against top-down market sizing across grade tiers and end-use applications.
Scenario-bracketing framed analytical outputs across the projection horizon, with CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers. Segmentation dimensions modeled included purity grade tier, end-use industry, cosmetic versus pharmaceutical application, and regional production hub classification. Industry-specific forecast inputs incorporated phenyl chlorosilane price indices and clean beauty certification adoption curves.
Sensitivities concentrate around NMPA regulatory tightening timelines and EU Green Deal chemical sustainability target revisions. Forecasts reflect assumptions about silicone intermediate feedstock cost trajectories and biocompatibility testing protocol evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Tetrahexyldecyl Ascorbate Market
Specialty Chemicals
Precipitated Barium Sulfate Market
Specialty Chemicals
Fatty Acid Methyl Ester Market
Specialty Chemicals
Bio-Wax Market
Specialty Chemicals
Global 1,5-Cyclooctadiene Market
Specialty Chemicals
Chromium Polynicotinate Market
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
Methyl Salicylate Market
Specialty Chemicals
Glucono Delta Lactone Market
Specialty Chemicals
Global Salicylic Acid Market
Specialty Chemicals
Phenoxycycloposphazene Market
Specialty Chemicals
Keratin Products Market
Specialty Chemicals
Titanium Fluoride Phosphate Market
Specialty Chemicals
Carnauba Wax Market
Specialty Chemicals
Europe Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Chemicals
Diindolylmethane Market