
 Bond Breaker Market | 2026-2036
Bond Breaker Market Size, Share, and Industry Trends Forecast 2026-2036
Bond Breaker Market Insights
A capital-intensity divergence between integrated chemical conglomerates and specialty construction chemical producers is reorganizing competitive dynamics in bond breakers. BASF SE leverages its upstream polymer synthesis capabilities to control raw material costs across polyurethane-based formulations. Sika AG anchors its position through deep specification relationships with European engineering firms and captive distribution networks. Fosroc International Limited competes in emerging markets by specializing in site-applied paste systems for infrastructure projects.
Bond breakers are interfacial release agents applied between concrete pours or molding surfaces to prevent adhesion and enable clean separation, typically formulated with active silicone resins, hydrocarbon carriers, and surfactant packages at viscosities between 50 and 500 centipoise for spray or brush application. Their primary purpose is eliminating surface preparation costs in multi-stage concrete construction and protecting mold integrity in repetitive manufacturing cycles. Silicone-based products dominate specification-driven commercial construction where ASTM C309 compliance governs curing compound compatibility, while methacrylate-based systems occupy high-temperature automotive injection molding where thermal stability exceeds 200°C. Liquid formulations lead volume consumption due to ease of spray application, though paste grades capture margin pools in vertical and overhead concrete casting where sag resistance determines product selection.
EPA VOC emission regulations under 40 CFR Part 59 constrain solvent-based formulation options, pushing manufacturers toward water-borne and 100% solids technologies. OSHA Hazard Communication Standard requirements mandate updated SDS documentation and worker exposure controls for chlorinated polyethylene variants in industrial settings. ASTM International maintains performance testing protocols that shape product certification and market access for construction-specified bond breakers. Stakeholders must monitor evolving state-level low-VOC mandates and assess whether backward integration into silicone resin production offers sustainable cost protection against feedstock volatility.
Market Dynamics
Silicone resin supply concentration and EPA VOC enforcement are compressing formulation choices while pushing manufacturers toward water-borne alternatives and captive raw material sourcing.
Growth Catalysts
- ASTM C309 Compliance Mandates:Commercial construction specifications in the United States increasingly require certified curing-compatibility, locking silicone-based bond breakers into multi-year infrastructure contracts.
- Precast Manufacturing Cluster Expansion:Germany's concrete component producers are scaling automated molding lines that demand high-cycle release agents with thermal stability above 180°C.
- China Infrastructure Stimulus:Provincial governments are accelerating highway and rail casting programs that specify paste-grade bond breakers for vertical concrete applications.
Market Restraints
- Silicone Monomer Price Volatility:Feedstock costs for polydimethylsiloxane fluctuate with Asian petrochemical output, squeezing margin pools on mid-tier liquid formulations.
- 40 CFR Part 59 Compliance Burden:EPA solvent-emission thresholds force reformulation investments that disproportionately burden small regional blenders lacking R&D scale.
- Alternative Release Technologies:Plasma-sprayed ceramic coatings in automotive tooling are displacing methacrylate bond breakers in high-temperature injection molding above 220°C.
Strategic Opportunities
- India Highway Construction Pipeline:National infrastructure corridors under the Ministry of Road Transport's expressway program create first-mover potential for site-applied paste systems.
- EU Green Deal Procurement Rules:Public construction tenders increasingly weight lifecycle carbon metrics, favoring water-borne and bio-based formulations with verified environmental product declarations.
- Digital Specification Platforms:Engineering software integrations enable direct-to-contractor technical documentation, bypassing traditional distributor markup layers in commercial construction.
Industry Challenges
- Formulation Chemist Talent Scarcity:Specialized expertise in silicone-polymer compatibility and surfactant stabilization is concentrating at integrated chemical conglomerates, constraining independent producer innovation cycles.
- Multi-Jurisdiction SDS Harmonization:OSHA Hazard Communication Standard updates, EU CLP classification revisions, and state-level California Prop 65 disclosure requirements create documentation complexity for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bond Breaker Market |
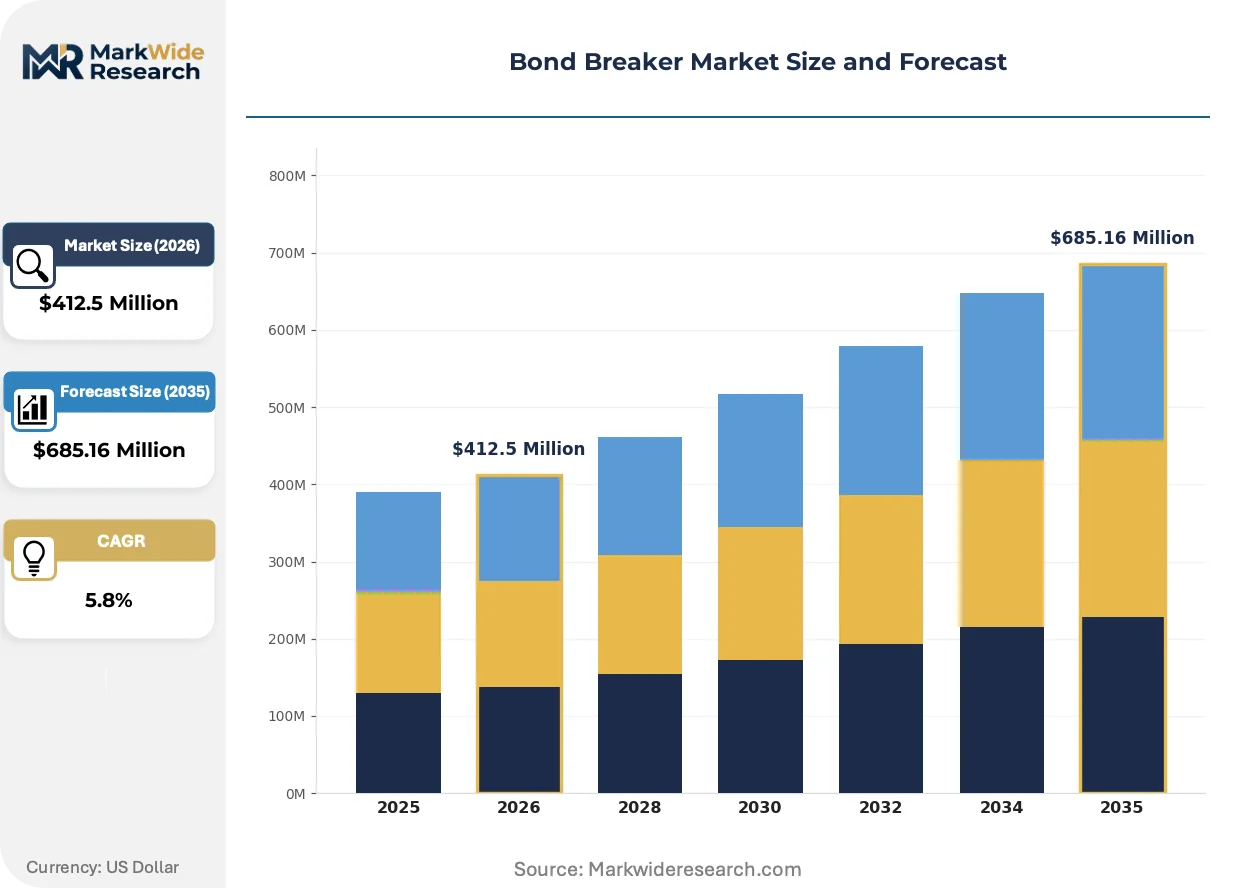
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone-Based, Acrylic-Based, Methacrylate-Based, Polyurethane-Based, Chlorinated Polyethylene Application: Injection Molding, Concrete Casting, Coating Formulations, Sealants, Adhesives End User Industry: Construction Firms, Automotive Suppliers, Packaging Manufacturers, Electronics Producers, Aerospace Engineers Form: Liquid, Paste, Powder, Film, Sheet |
| Companies Covered | Sika AG, BASF SE, Fosroc International Limited, Saint-Gobain Weber, The Euclid Chemical Company, Dayton Superior Corporation, WR Meadows, Specified Technologies Inc, TCC Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bond Breaker Market Trends and Innovations
Water-borne emulsion technologies and digital specification workflows are restructuring how bond breaker products reach end-users and how performance is validated in the field.
Hybrid silicone-acrylic emulsion chemistry is fragmenting the traditional solvent-silicone dominance in commercial construction. Large-scale precast producers in the United States are piloting these systems at 40% reduced VOC content to meet tightening state air-quality mandates. The technology is fragmenting competitive positioning between integrated resin manufacturers and regional compounders lacking emulsion polymerization capabilities.
REACH SVHC candidate list expansions are forcing European formulators to phase out legacy hydrocarbon carriers containing naphthalene derivatives. Industrial mold-release applications in Germany and France face reformulation deadlines that compress product development timelines. Construction-specified grades are responding fastest through accelerated partnerships with bio-based solvent suppliers.
Specification decisions are migrating from distributor relationships toward direct engineering-firm engagement. Major infrastructure contractors in China and the United States now require manufacturer-provided performance data packages for bond-curing compatibility testing. This shift is most visible in transportation infrastructure verticals where liability exposure drives documentation rigor.
Bond Breaker Market Segmentation
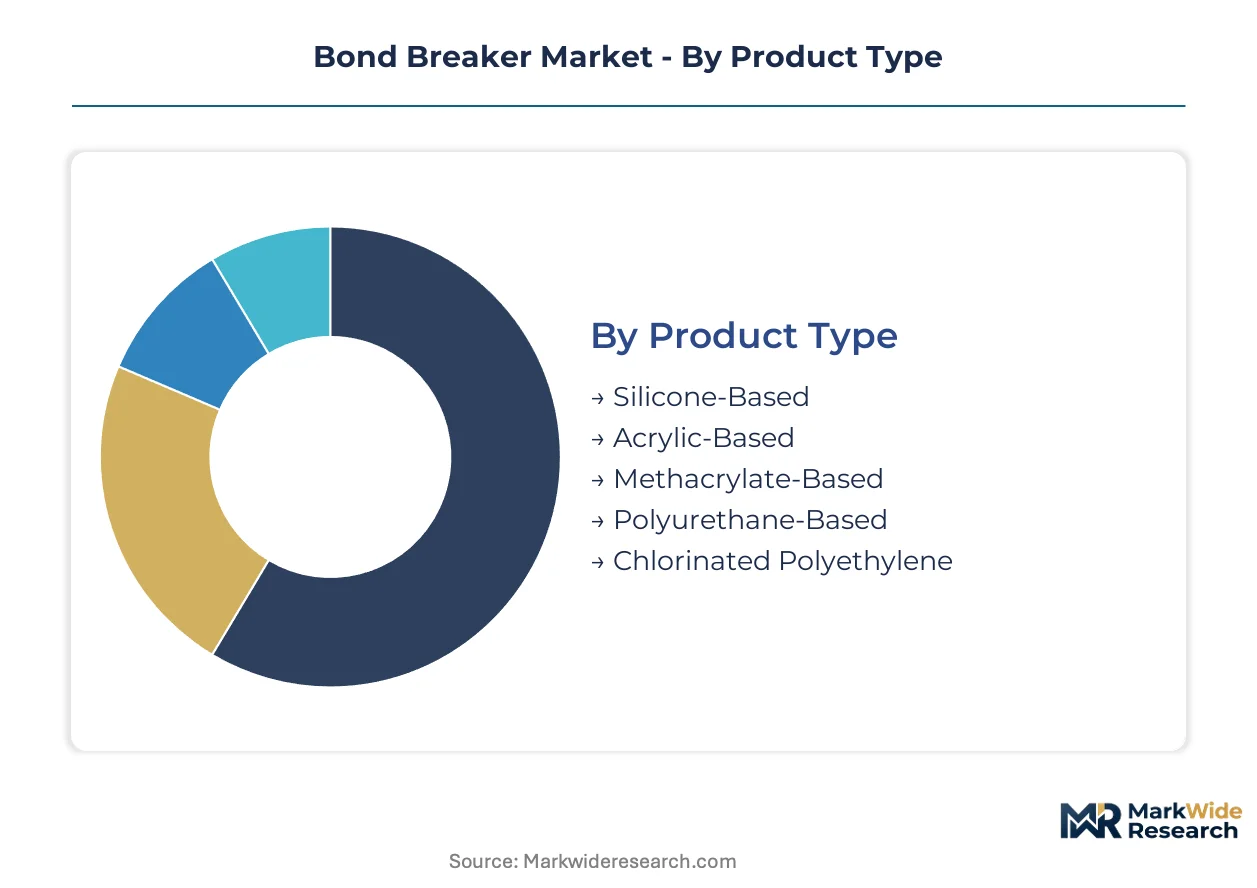
Bond breaker segmentation reveals how formulation chemistry, physical state, and end-use specifications create distinct competitive arenas with varying substitution pressures from alternative release technologies.
Product Type:
Substitution threats concentrate in solvent-borne segments where EPA VOC thresholds and REACH SVHC expansions are forcing rapid chemistry migration.
- Silicone-Based:Formulated with polydimethylsiloxane resins and hydrocarbon carriers at 50-500 centipoise viscosity for spray application. Demand concentrates in United States commercial construction where ASTM C309 curing-compatibility certification governs specification. EPA 40 CFR Part 59 compliance costs squeeze mid-tier blenders lacking captive resin production.
- Acrylic-Based:Hybrid emulsion systems combining silicone-acrylic copolymers at 40% reduced VOC content versus solvent predecessors. Germany's precast manufacturers are piloting these for automated molding lines above 180°C operating temperatures. ECHA REACH naphthalene derivative restrictions accelerate European adoption curves.
- Methacrylate-Based:Thermal stability exceeds 200°C for automotive injection molding tooling.
- Polyurethane-Based:BASF SE leverages upstream polymer synthesis for cost-controlled supply.
- Chlorinated Polyethylene:OSHA Hazard Communication Standard mandates updated SDS documentation for industrial applications.
Silicone-based formulations retain volume leadership; acrylic-based alternatives hold the steepest expansion curve.
Application:
Cost tier stratification separates specification-driven construction grades from price-sensitive industrial mold-release categories.
- Concrete Casting:Multi-stage horizontal pours and vertical wall applications requiring sag-resistant paste grades. China's provincial highway and rail casting programs specify these systems for infrastructure stimulus projects. Compatibility testing with curing compounds adds qualification layers that favor established suppliers.
- Injection Molding:High-temperature automotive tooling above 220°C where plasma-sprayed ceramic coatings are displacing methacrylate bond breakers. Germany's automotive supplier clusters demand thermal stability documentation for repetitive manufacturing cycles. Alternative release technologies threaten methacrylate positioning in premium temperature segments.
- Coating Formulations:Interfacial release for industrial surface protection systems.
- Sealants:Construction joint applications requiring ASTM C309 compliance verification.
- Adhesives:Manufacturing process separation for bonded assembly operations.
Concrete casting retains volume leadership; injection molding faces the steepest substitution pressure from ceramic coating alternatives.
End User Industry:
Customer type concentration determines specification complexity and documentation requirements across liability-exposed versus commodity procurement patterns.
- Construction Firms:Infrastructure contractors in China and the United States now require manufacturer-provided performance data packages for bond-curing compatibility testing. Direct engineering-firm engagement is displacing traditional distributor relationships in transportation infrastructure verticals. Liability exposure drives documentation rigor that favors integrated chemical conglomerates.
- Automotive Suppliers:Tooling engineers specify thermal stability above 200°C for repetitive injection molding cycles. Germany's automotive component producers anchor European demand for high-performance release agents. Ceramic coating substitution threatens methacrylate-based formulations in temperature-critical applications.
- Packaging Manufacturers:Food-contact compliance requirements govern formulation selection.
- Electronics Producers:Precision molding applications requiring clean-release surface integrity.
- Aerospace Engineers:Certification-intensive procurement with extended qualification timelines.
Construction firms retain volume leadership; automotive suppliers face the steepest technology displacement risk from alternative release systems.
Form:
Supply concentration in liquid production contrasts with margin capture in specialized physical states for restricted application geometries.
- Liquid:Spray-applied formulations at 50-500 centipoise viscosity dominating volume consumption through ease of application. United States commercial construction specifications lock silicone-based liquids into multi-year infrastructure contracts. Water-borne emulsion technologies are fragmenting competitive positioning between integrated resin manufacturers and regional compounders.
- Paste:Sag-resistant grades for vertical and overhead concrete casting where viscosity determines product selection. India's Ministry of Road Transport expressway program creates first-mover potential for site-applied paste systems. Margin pools exceed liquid formulations due to application-specific performance requirements.
- Powder:Dry-blend systems for specialized industrial mold-release applications.
- Film:Pre-formed interfacial barriers for repetitive manufacturing cycles.
- Sheet:Laminated release surfaces for large-scale precast component production.
Liquid formulations retain volume leadership; paste grades hold the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in bond breakers track silicone resin availability and infrastructure investment cycles. The United States runs a modest trade deficit in specialty formulations, offset by German and Chinese manufacturing scale. Regional demand clusters reflect precast concrete production gravity and highway construction pipelines.
United States
ASTM C309 certification requirements lock silicone-based bond breakers into federal and state infrastructure contracts. EPA 40 CFR Part 59 enforcement accelerates water-borne formulation adoption in California and Northeast corridor markets. Texas and Florida precast manufacturing clusters absorb paste-grade volumes for vertical wall casting in highway expansion projects.
Germany
Automated precast molding lines above 180°C operating temperatures drive specification-grade silicone resin consumption. ECHA REACH SVHC restrictions on naphthalene derivatives force reformulation timelines for industrial mold-release applications. Bavaria's concrete component producers anchor European demand for high-cycle release agents with thermal stability documentation.
China
Provincial highway and rail casting programs under infrastructure stimulus directives specify paste-grade bond breakers for vertical concrete applications. The Ministry of Ecology and Environment enforces dual carbon goals that constrain solvent-based formulation options in Yangtze River Delta manufacturing zones. Sichuan-Chongqing construction corridors represent the fastest-growing consumption nodes for site-applied systems.
India
The Ministry of Road Transport's national expressway program creates first-mover positioning for site-applied paste systems in highway construction. BIS standards for construction chemicals remain under development, creating specification uncertainty for imported formulations. Maharashtra and Gujarat infrastructure corridors concentrate demand from contractor procurement pools.
United Arab Emirates
Mega-project concrete casting for NEOM and Red Sea developments imports specification-grade silicone formulations from European suppliers. The Emirates Authority for Standardization and Metrology governs construction chemical imports through conformity assessment protocols. Dubai and Abu Dhabi precast yards operate as regional distribution hubs for Gulf Cooperation Council markets.
Bond Breaker Market Competitive Landscape
Concentration sits with integrated chemical conglomerates controlling upstream silicone resin supply. Specialty construction chemical producers occupy mid-tier positions through specification relationships with engineering firms. Regional compounders compete on paste-grade formulations for infrastructure verticals. Dominant competitive moves include backward integration into resin production and direct-to-contractor digital specification platforms.
Among Swiss and German chemical conglomerates, Sika AG and BASF SE exemplify integrated archetypes with captive polymer synthesis capabilities. Fosroc International Limited occupies a position within the specialty infrastructure tier. These three anchors represent distinct strategic postures: resin-backed cost control, specification-driven distribution depth, and emerging-market site-application focus.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| Fosroc International Limited |
| Saint-Gobain Weber |
| The Euclid Chemical Company |
| Dayton Superior Corporation |
| WR Meadows |
| Specified Technologies Inc |
| TCC Materials |
| Others |
Pricing and Supply Chain Analysis
Ninety-day silicone resin inventory cycles at major formulators compress margin flexibility during Asian petrochemical volatility, concentrating pricing power with integrated producers while fragmenting regional compounders across incompatible cost structures. This lead-time compression shapes how construction chemical distributors negotiate annual contracts with infrastructure contractors.
Pricing Analysis
The customization-premium spread between ASTM C309-certified silicone formulations and uncertified commodity grades runs three-to-one in United States federal highway contracts. Three-tier pricing structure across premium certification, standard compliance, and economy solvent-borne levels reflects downstream liability exposure rather than raw material cost. Price differentiation hinges on curing-compatibility documentation and captive resin production. Margins are tightening in mid-tier liquid segments as EPA 40 CFR Part 59 compliance costs accumulate. Construction firms with multi-year infrastructure contracts exhibit lowest price sensitivity; small regional precast yards show highest.
Supply Chain Analysis
Strategic-stockpile preferences dominate silicone resin procurement, with integrated producers maintaining six-month polydimethylsiloxane forward positions against Asian monomer volatility. Supply concentrates in Germany, China, and the United States for specialty resin synthesis. Formulation draws from silicone monomers, hydrocarbon carriers, and surfactant packages. Single-source vulnerability sits with Asian petrochemical feedstocks. Distribution runs through specification-engineering relationships and captive distribution networks rather than open merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital specification platforms are restructuring this market toward platform-economics dynamics, where direct-to-contractor technical documentation bypasses traditional distributor markup layers and creates winner-take-most positioning for integrated data providers.
For Market Incumbents: Compound specification depth through ASTM C309 certification lock-in with United States infrastructure contractors, while accelerating backward integration into silicone resin production to neutralize Asian feedstock volatility. Ceramic coating substitution in automotive injection molding above 220°C threatens methacrylate-based revenue pools; defend through thermal stability documentation partnerships with German automotive suppliers. Prioritize emulsion polymerization capabilities to capture water-borne formulation share as EPA VOC enforcement tightens. For New Entrants and Emerging Players: Lead with site-applied paste systems for India's Ministry of Road Transport expressway corridors, where BIS standards underdevelopment create specification windows for qualified imports. White-space concentrates in vertical concrete casting for provincial Chinese rail programs and EU Green Deal procurement-weighted carbon metrics. Anchor go-to-market through engineering software integrations that embed performance data packages directly into contractor workflows. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded construction chemical divisions lacking digital specification capabilities. Long-term viability favors integrated resin producers with captive silicone supply and direct contractor relationships over regional compounders exposed to feedstock volatility. Watch for inflection when state-level low-VOC mandates cross 50% coverage of United States construction spend.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Resin | Captive supply of polydimethylsiloxane neutralizes Asian petrochemical price volatility for integrated formulators. |
| Digital Specification Platform Launch | Direct-to-contractor technical documentation bypasses distributor markup layers in United States commercial construction. |
| Water-Borne Emulsion Capacity Expansion | Hybrid silicone-acrylic systems capture share as EPA 40 CFR Part 59 enforcement accelerates solvent-phaseout. |
| ASTM C309 Certification Investment | Certified curing-compatibility locks silicone-based formulations into multi-year federal infrastructure contracts. |
| Site-Applied Paste System Partnership | India's national expressway program creates first-mover positioning for sag-resistant vertical casting grades. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC construction chemical segment disclosures, EPA enforcement records, and ASTM certification registries. Interviews with technical R&D directors at integrated resin manufacturers, procurement leads at United States infrastructure contractors, distribution channel partners in German precast clusters, and plant managers at Chinese provincial casting facilities inform demand-side validation. Bottom-up volume estimates triangulate against top-down chemical industry production data.
Segmentation dimensions modeled span formulation chemistry, physical state, end-use application, and customer procurement archetype across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating infrastructure stimulus timing and regulatory compliance cost trajectories. Forecast inputs include silicone monomer price volatility indices and state-level VOC mandate adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure spending levels or accelerated ceramic coating substitution rates would require recalibration. Forecasts reflect documented assumptions regarding EPA enforcement intensity and REACH SVHC expansion timelines. Revision becomes warranted when water-borne formulation cost-parity crosses solvent-based alternatives in commercial construction specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Natural Insect Repellent Market
Specialty Chemicals
Global Mannosylerythritol Lipids Market
Specialty Chemicals
Divinylbenzene (DVB) Market
Specialty Chemicals
Eco-Friendly Plasticizers Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Bemotrizinol Market
Specialty Chemicals
4-ADPA Market
Specialty Chemicals
Sizing and Thickening Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Multichannel Reagent Reservoir Market
Specialty Chemicals
Asia-Pacific UV Stabilizers Market
Specialty Chemicals
Alkylene Carbonates Market
Specialty Chemicals
Silver Sulfate Market
Specialty Chemicals
Isoeicosane Market
Specialty Chemicals
Monomethyl Acetoacetamide Market
Specialty Chemicals
Global Curing Agents Market