
 Disodium Adenosine Triphosphate Market | 2026-2036
Disodium Adenosine Triphosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Disodium Adenosine Triphosphate Market Outlook
The direct-to-laboratory distribution channel is narrowing as bulk procurement contracts consolidate purchasing power among institutional buyers. Thermo Fisher Scientific leverages its global logistics network to sustain volume leadership across North American research corridors. Merck KGaA anchors European supply through its life sciences distribution infrastructure, while Lonza Group specializes in cGMP-grade ATP production for pharmaceutical clients.
Disodium adenosine triphosphate is a disodium salt of adenosine triphosphate, a nucleotide composed of adenine, ribose, and three phosphate groups that serves as the primary intracellular energy carrier in biochemical systems. The compound functions industrially as a critical reagent in cell-based assays, fermentation processes, and therapeutic formulation development. Pharmaceutical grade material commands premium positioning due to stringent endotoxin and purity specifications required for injectable applications. Laboratory grade products compete on catalog breadth and turnaround speed rather than certification depth. Nutritional supplementation applications show expanding volume as sports science and functional food formulations incorporate bioenergetic compounds.
FDA cGMP guidelines and EMA GMP Annex 1 standards govern sterile ATP manufacturing for parenteral use, while ISO 13485 certification shapes supplier qualification for diagnostic device integration. REACH registration requirements in Europe constrain non-compliant import volumes and elevate documentation burdens for industrial grade entrants. Stakeholders must monitor evolving pharmacopeial monographs and cell therapy guidance documents to anticipate specification shifts before contract renegotiation cycles.
Market Dynamics
Cell therapy manufacturing workflows are consolidating ATP procurement around cGMP-certified suppliers as FDA and EMA purity requirements tighten for injectable-grade material, compressing the vendor base and elevating documentation burdens for industrial-grade entrants.
Growth Catalysts
- FDA Cell Therapy Guidance:Updated purity specifications for parenteral ATP are forcing therapeutic developers to source pharmaceutical-grade material exclusively, eliminating laboratory-grade alternatives from clinical workflows.
- German Biologics Clusters:Concentrated demand from Heidelberg and Munich cell therapy facilities anchors European procurement volumes and sustains premium pricing for endotoxin-tested product.
- Continuous Bioprocessing:Perfusion-based cell culture systems require steady ATP supplementation, embedding the compound into next-generation manufacturing platforms.
Market Restraints
- Raw Material Concentration:High-purity adenine and ribose precursors concentrate among Japanese and Chinese specialty chemical suppliers, exposing ATP manufacturers to input cost volatility and geographic supply risk.
- REACH Registration Burden:ECHA documentation requirements for industrial-grade ATP imports constrain low-volume European entrants and elevate compliance costs for catalog distributors.
- Enzymatic ATP Regeneration:In-house enzymatic synthesis systems at large biopharma facilities threaten to displace commercial ATP purchases for internal R&D consumption.
Strategic Opportunities
- Indian CDMO Expansion:CDSCO-aligned manufacturing investments by Indian contract developers create demand for import-certified ATP as domestic cell therapy capacity scales.
- Sports Nutrition Formulation:Functional food and beverage applications in Japan and South Korea represent underpenetrated volume channels beyond traditional pharmaceutical and laboratory segments.
- ISO 13485 Diagnostic Integration:ATP-dependent luminescence assays for point-of-care devices create certification-driven demand from IVD manufacturers seeking qualified reagent suppliers.
Industry Challenges
- cGMP Talent Scarcity:Qualified personnel for sterile ATP manufacturing and quality documentation remain concentrated among established pharmaceutical suppliers, constraining new facility ramp-up.
- Endotoxin Testing Bottlenecks:LAL assay capacity limitations and validation timelines extend release cycles for pharmaceutical-grade lots, compressing effective supply responsiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disodium Adenosine Triphosphate Market |
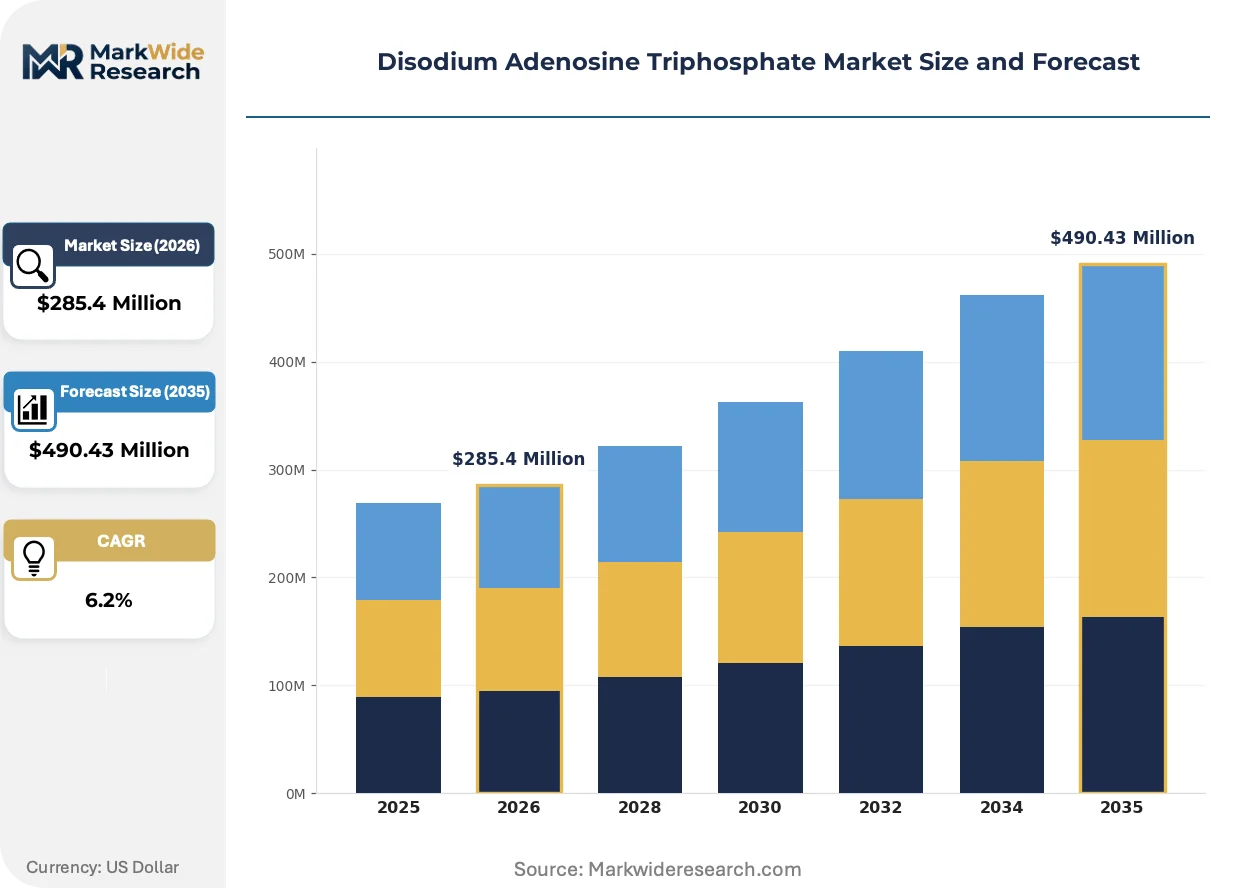
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $490.43 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Food Grade, Industrial Grade, Laboratory Grade Application: Biochemical Research, Food Preservation, Nutritional Supplementation, Pharmaceutical Manufacturing Delivery Mode: Oral, Injectable, Intravenous, Topical End User: Pharmaceutical Companies, Research Institutions, Nutraceuticals, Biotechnology Firms |
| Companies Covered | Lonza Group, Merck KGaA, Thermo Fisher Scientific Inc., Cayman Chemical Company, Abcam plc, Santa Cruz Biotechnology Inc., Bio-Techne Corporation, Kyowa Hakko Bio Co., Ltd., Enzo Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disodium Adenosine Triphosphate Market Strategic Shifts
Synthetic biology approaches to ATP production are intersecting with regulatory harmonization efforts and procurement centralization to reshape competitive positioning across the value chain.
Cell-free enzymatic synthesis platforms using purified kinase cascades are achieving pharmaceutical-grade purity without fermentation-derived contaminants. Thermo Fisher and Lonza are piloting these systems for high-value therapeutic batches. The technology is rendering obsolete traditional yeast fermentation routes for premium applications.
EMA GMP Annex 1 revisions on sterile manufacturing are mandating closed-system processing for parenteral excipients including ATP. European suppliers are retrofitting isolator technology and continuous monitoring systems. Pharmaceutical-grade ATP destined for EU markets faces the steepest compliance escalation.
Consolidated procurement through group purchasing organizations is displacing direct laboratory ordering for institutional buyers. Academic medical centers and national research institutes in the United States and Germany are centralizing ATP contracts. This concentration is most visible among NIH-funded cell therapy consortia seeking volume discounts and audit simplification.
Disodium Adenosine Triphosphate Market Segmentation
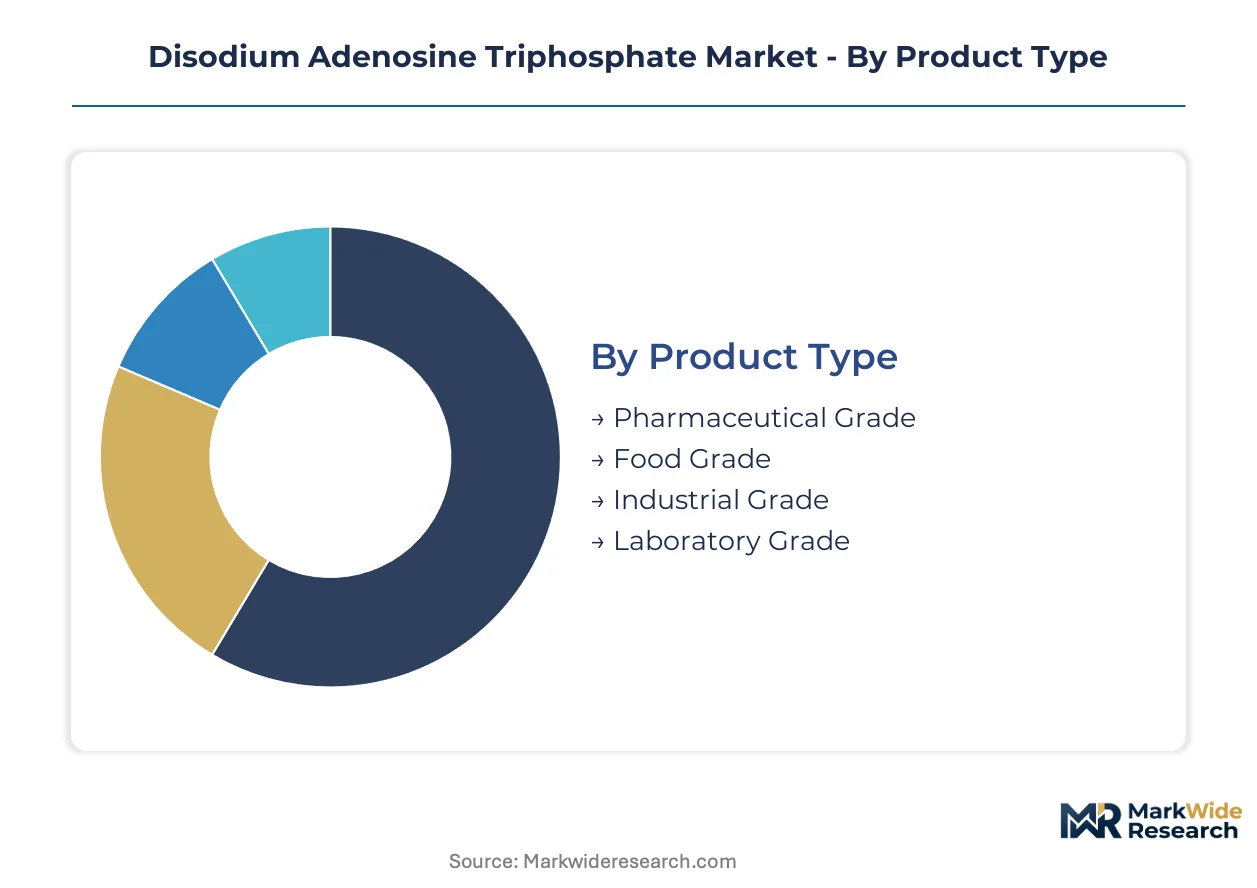
ATP grade specifications govern procurement cycles across therapeutic manufacturing, with cGMP certification requirements creating distinct inventory turnover patterns between clinical-grade and research-grade material. Delivery mode selection directly constrains sterilization validation timelines and release bottlenecks for parenteral applications.
Product Type:
Cycle times compress sharply from laboratory-grade spot purchasing to pharmaceutical-grade validated lot releases, with endotoxin testing and documentation extending procurement lead times by multiples.
- Pharmaceutical Grade:Stringent endotoxin limits below 0.06 EU/mg and sterility assurance levels of 10^-6 govern injectable ATP for cell therapy parenteral formulations. Heidelberg and Munich biologics clusters anchor European procurement volumes as FDA guidance tightens purity specifications.
- Laboratory Grade:Catalog breadth and turnaround speed compete for research assay workflows rather than certification depth. Thermo Fisher sustains volume leadership across North American research corridors through direct-to-laboratory distribution.
- Food Grade:FSSAI and FDA food additive regulations constrain purity thresholds for nutritional supplementation applications in sports science formulations.
- Industrial Grade:REACH registration requirements in Europe constrain non-compliant import volumes and elevate documentation burdens for fermentation process inputs.
Pharmaceutical Grade anchors the volume base while Laboratory Grade gains share at the steepest rate as distributed research assays proliferate.
Application:
Cost tier stratification separates premium therapeutic formulations from commodity research consumables, with reimbursement pathways determining viable price floors.
- Pharmaceutical Manufacturing:cGMP-certified ATP integrates into cell therapy workflows as FDA and EMA guidelines reshape purity requirements for injectable applications. Continuous bioprocessing systems embed steady ATP supplementation into next-generation manufacturing platforms.
- Biochemical Research:ATP-dependent luminescence assays drive catalog demand from academic medical centers and national research institutes centralizing procurement through group purchasing organizations.
- Nutritional Supplementation:Sports science and functional food formulations in Japan and South Korea incorporate bioenergetic compounds for expanding volume channels.
- Food Preservation:ATP bioluminescence testing for microbial contamination monitoring constrains specification requirements for industrial-grade material.
Pharmaceutical Manufacturing commands the premium tier while Nutritional Supplementation expands most quickly as functional food applications mature.
Delivery Mode:
Volume concentration clusters around parenteral routes where sterility assurance demands consolidate procurement around qualified suppliers.
- Injectable:Closed-system processing mandates under EMA GMP Annex 1 revisions retrofit European suppliers with isolator technology for sterile ATP destined for EU markets.
- Intravenous:LAL assay capacity limitations extend release cycles for pharmaceutical-grade lots, compressing effective supply responsiveness for therapeutic developers.
- Oral:Sports nutrition formulations bypass sterility requirements, enabling faster procurement cycles for nutritional supplementation applications.
- Topical:Cosmetic and dermatological applications occupy niche positioning with reduced regulatory burden relative to parenteral routes.
Injectable dominates value concentration while Oral scales volume fastest as functional food markets deepen.
End User:
Customer type determines contract structure, with institutional buyers consolidating purchasing power through multi-year agreements.
- Pharmaceutical Companies:In-house enzymatic synthesis systems at large biopharma facilities threaten to displace commercial ATP purchases for internal R&D consumption. CDSCO-aligned Indian CDMO expansion creates demand for import-certified ATP as domestic cell therapy capacity scales.
- Research Institutions:NIH-funded cell therapy consortia centralize contracts seeking volume discounts and audit simplification across academic medical centers.
- Biotechnology Firms:Cell-free enzymatic synthesis platforms using purified kinase cascades achieve pharmaceutical-grade purity without fermentation-derived contaminants.
- Nutraceuticals:Functional food and beverage manufacturers in East Asian markets represent underpenetrated volume channels beyond traditional pharmaceutical segments.
Pharmaceutical Companies sustain the contract base while Biotechnology Firms climb fastest as synthetic biology production platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cell therapy guidance revisions and EMA GMP Annex 1 updates are redirecting procurement flows toward certified suppliers in established pharmaceutical manufacturing corridors. National regulators are tightening purity specifications for parenteral-grade material, compressing vendor qualification timelines across major demand centers.
United States
NIH-funded cell therapy consortia are centralizing ATP contracts through group purchasing organizations, consolidating demand from academic medical centers and research institutes. FDA cGMP guidelines for sterile manufacturing govern injectable-grade material specifications, eliminating laboratory-grade alternatives from clinical workflows. Greater Boston and San Diego biotech clusters anchor procurement volumes as continuous bioprocessing adoption embeds steady ATP supplementation into manufacturing platforms.
Germany
Heidelberg and Munich cell therapy facilities sustain premium pricing for endotoxin-tested pharmaceutical-grade ATP through concentrated biologics manufacturing demand. EMA GMP Annex 1 revisions mandate closed-system processing and isolator technology retrofits for sterile ATP destined for EU markets. Baden-Württemberg pharmaceutical suppliers are expanding cGMP-certified capacity to capture contract manufacturing organization procurement flows.
Japan
PMDA guidance on regenerative medicine products is accelerating qualification requirements for ATP suppliers supporting induced pluripotent stem cell therapy manufacturing. METI industrial biotechnology programs subsidize domestic fermentation capacity expansion for high-purity nucleotide production. Kanto and Kansai pharmaceutical corridors concentrate demand from large-scale cell culture facilities and point-of-care diagnostic device manufacturers.
India
CDSCO-aligned manufacturing investments by contract developers are creating import-certified ATP demand as domestic cell therapy capacity scales. PLI scheme incentives for pharmaceutical manufacturing are attracting multinational biologics producers to establish regional supply chains. Maharashtra and Gujarat pharmaceutical clusters are consolidating procurement around qualified suppliers capable of documentation compliance for export markets.
South Korea
MFDS cell and gene therapy product guidelines are reshaping supplier qualification standards for ATP integration into chimeric antigen receptor T-cell manufacturing workflows. Government biotechnology development funds support domestic raw material production capabilities for therapeutic nucleotides. Seoul Capital Area biopharma facilities anchor procurement concentration as functional food applications in sports nutrition expand volume channels.
Disodium Adenosine Triphosphate Market Competitive Environment
On the supply side, the industry is consolidating around cGMP-certified manufacturers capable of endotoxin-tested pharmaceutical-grade production, compressing the vendor base as regulatory documentation burdens eliminate industrial-grade entrants. Three strategic archetypes dominate: diversified life sciences conglomerates with global distribution infrastructure, specialized biochemical suppliers focused on nucleotide chemistry, and contract manufacturing organizations integrating ATP into vertically controlled cell therapy workflows. Capacity expansion and strategic partnerships represent the dominant competitive moves, with suppliers securing long-term raw material agreements and co-development arrangements with therapeutic developers.
Among diversified conglomerates, Thermo Fisher Scientific Inc. and Merck KGaA occupy positions spanning research-grade catalog distribution through pharmaceutical-grade sterile manufacturing, while Lonza Group exemplifies the contract manufacturing organization archetype with concentrated cGMP-grade ATP production capabilities. These three entities anchor competitive positioning across North American and European procurement corridors, with their geographic footprints and certification portfolios determining contract eligibility for institutional buyers.
| Leading Market Players |
|---|
| Lonza Group |
| Merck KGaA |
| Thermo Fisher Scientific Inc. |
| Cayman Chemical Company |
| Abcam plc |
| Santa Cruz Biotechnology Inc. |
| Bio-Techne Corporation |
| Kyowa Hakko Bio Co., Ltd. |
| Enzo Life Sciences |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific freight corridors from Yokohama to Long Beach transmit raw material cost volatility directly into pharmaceutical-grade ATP pricing, while endotoxin certification requirements create divergent price bands that stratify procurement across research and therapeutic manufacturing tiers.
Pricing Analysis
Certification level creates the primary spread between laboratory-grade spot purchases and cGMP-validated pharmaceutical lots. Three-tier pricing structure across premium, standard, and economy levels separates endotoxin-tested injectable material from research-grade catalog products and industrial fermentation inputs. Pricing pressure stems from consolidated group purchasing organization contracts at academic medical centers, compressing margins for catalog distributors. Biotechnology firms show least price sensitivity for clinical-grade material, while research institutions centralizing procurement through NIH consortia drive hardest volume negotiations.
Supply Chain Analysis
Lonza Group and Thermo Fisher Scientific hold dominant cGMP manufacturing capacity for pharmaceutical-grade ATP, with Merck KGaA anchoring European supply through life sciences distribution infrastructure. High-purity adenine and ribose precursors concentrate among Japanese and Chinese specialty chemical suppliers, exposing ATP manufacturers to input cost volatility. Single-source vulnerability in enzymatic precursor supply creates geographic concentration risk for sterile manufacturing operations. Distribution runs through direct-to-laboratory channels for research-grade material and bulk procurement contracts for institutional pharmaceutical buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell therapy manufacturing workflows are consolidating around qualified ATP suppliers as interoperability between cGMP documentation systems and FDA submission platforms becomes the decisive procurement filter.
For Market Incumbents: Entrench cGMP certification depth as the primary defensive moat against cell-free enzymatic synthesis platforms threatening to displace commercial ATP purchases. Expand isolator technology retrofits at European facilities ahead of EMA GMP Annex 1 enforcement timelines. Secure long-term raw material agreements with Japanese and Chinese adenine suppliers to hedge against geographic supply risk.
For New Entrants and Emerging Players: Build out sports nutrition formulation capabilities targeting South Korean and Japanese functional food markets as the most penetrable volume channel beyond traditional pharmaceutical segments. Prioritize CDSCO-aligned manufacturing investments to capture Indian CDMO procurement flows as domestic cell therapy capacity scales. Lead with import-certified documentation packages to bypass incumbent group purchasing organization lock-in.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life sciences conglomerates seeking to divest non-core nucleotide chemistry operations. Long-term viability hinges on synthetic biology production platform adoption and regulatory harmonization across FDA, EMA, and PMDA jurisdictions. Watch for LAL assay capacity bottlenecks extending pharmaceutical-grade release cycles as the signal for supply-constrained pricing inflection.
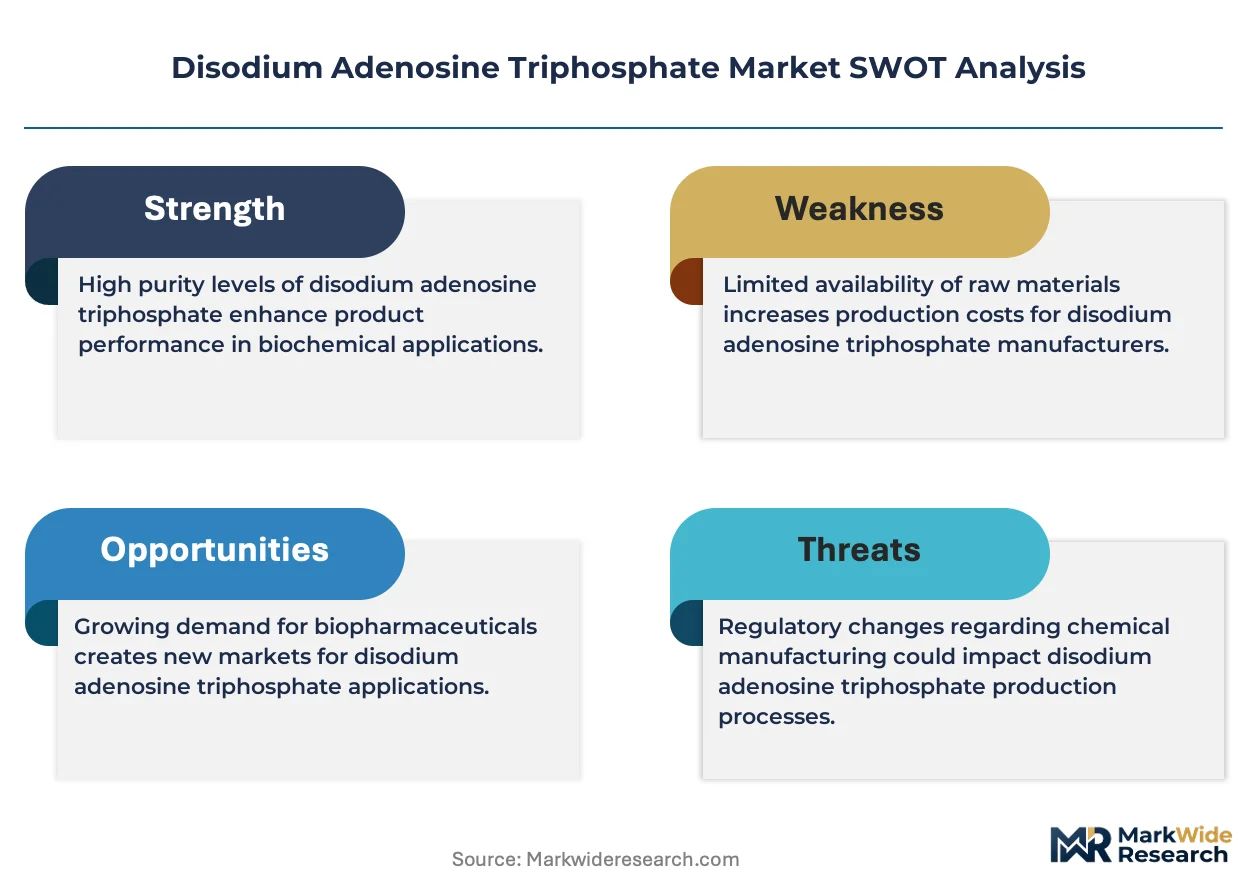
| Strategic Initiative | Industry Significance |
|---|---|
| cGMP Certification Investment | EMA GMP Annex 1 compliance secures EU market access for sterile injectable material. |
| Backward Integration into Precursors | Captive adenine and ribose supply hedges against Japanese and Chinese input volatility. |
| Cell-Free Enzymatic Platform Deployment | Purified kinase cascade synthesis eliminates fermentation-derived contaminant risks. |
| Group Purchasing Organization Partnership | NIH-funded consortia contracts consolidate institutional demand and audit simplification. |
| Sports Nutrition Channel Expansion | East Asian functional food applications unlock underpenetrated volume beyond therapeutics. |
Study Parameters
A spread of perspectives from cell therapy manufacturing executives, regulatory affairs leads at ATP suppliers, pharmaceutical procurement managers, and academic research facility directors converged on the working assumptions. Primary interviews combined with secondary validation from FDA guidance documents, EMA GMP Annex 1 revisions, CDSCO manufacturing alignment notifications, and PMDA regenerative medicine guidance. Bottom-up demand modeling across grade tiers and top-down supply capacity assessments were triangulated against customs trade data and pharmaceutical facility expansion announcements.
Demand-supply balance dynamics shaped the analytical framework across the analysis window, with segmentation by certification grade, delivery mode, application category, and regional regulatory cluster. CAGRs were derived from installed base growth in continuous bioprocessing systems and cell therapy manufacturing capacity expansion. Forecast inputs incorporated endotoxin testing capacity constraints, enzymatic synthesis platform adoption curves, and group purchasing organization contract concentration trends.
Practitioners should monitor LAL assay capacity utilization rates, synthetic biology production platform pilot announcements, and CDSCO manufacturing investment disclosures for early signals of supply constraint or technology displacement. Forecasts reflect documented assumptions about regulatory harmonization timelines and raw material supply stability. Quarterly review of pharmaceutical-grade inventory turnover and research-grade catalog pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Taurine Market
Specialty Chemicals
Sizing and Thickening Market
Specialty Chemicals
Global Mannosylerythritol Lipids Market
Specialty Chemicals
India Prussian Blue Market
Specialty Chemicals
Toner Spray Market
Specialty Chemicals
Global Mandelic Acid Market
Specialty Chemicals
Sol-Gel Processing Market
Specialty Chemicals
Sodium Adipate Market
Specialty Chemicals
Flame-Retardant Synergist Systems with Low Smoke Toxicity Market
Specialty Chemicals
Bismuth Oxychloride Market
Specialty Chemicals
1 - 4 - Cyclohexanedimethanol Dibenzoate Market
Specialty Chemicals
Phytosphingosine Market
Specialty Chemicals
Natural Ingredient Insect Repellent Market
Specialty Chemicals
Cyclomethicone Market
Specialty Chemicals
Europe Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Chemicals
Demethylase Inhibitor Market