
 Sodium Adipate Market | 2026-2036
Sodium Adipate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Adipate Market Analytics
Aftermarket technical service revenue is reconfiguring margin capture across the sodium adipate value chain. Sigma-Aldrich (Merck KGaA) leverages its analytical standards portfolio to anchor premium positioning in pharmaceutical-grade supply. Parchem Fine & Specialty Chemicals sustains broad SKU coverage across industrial and food-grade categories. Dr. Paul Lohmann specializes in high-purity mineral salts for pharmaceutical and nutritional applications, occupying a defensible niche in European excipient supply.
Sodium adipate, the sodium salt of adipic acid with formula NaOOC(CH2)4COONa, functions primarily as a buffering agent, acidity regulator, and chelating intermediate in formulated products. Food-grade sodium adipate serves as a pH control agent in processed meat and dairy systems, while pharmaceutical-grade material meets USP-NF and EP monograph specifications for tablet and capsule formulations. Pharmaceutical-grade material commands the strongest margin pool due to certification burdens and batch documentation requirements. Industrial-grade volumes dominate tonnage flows through chemical processing channels, though cosmetic-grade demand from premium skincare formulators is expanding fastest on a percentage basis.
REACH registration requirements in Europe, USP-NF monograph enforcement by the FDA, and FSSAI food additive standards in India collectively shape product specifications and market access conditions for sodium adipate suppliers. FDA oversight of pharmaceutical excipients through the Inactive Ingredient Database directly influences qualification timelines and customer switching costs. Stakeholders must monitor evolving monograph harmonization between USP-NF and EP standards, as divergence in heavy metal or impurity limits could fragment formulation strategies across regulatory zones.
Market Dynamics
Contract manufacturing organizations in pharmaceutical excipient supply are consolidating purchase volumes around certified suppliers, compressing qualification timelines and reshaping supplier switching economics across the sodium adipate value chain.
Growth Catalysts
- REACH registration compliance:ECHA's tightened substance evaluation protocols are filtering out non-compliant suppliers, concentrating demand among registered producers with full dossier documentation.
- Processed meat pH stabilization:Food-grade sodium adipate demand from European meat processing corridors is accelerating as clean-label buffering replaces synthetic phosphate alternatives.
- Ludwigshafen chemical cluster:Production gravity around BASF's adipic acid precursor supply is shortening logistics lead times for downstream sodium salt conversion.
Market Restraints
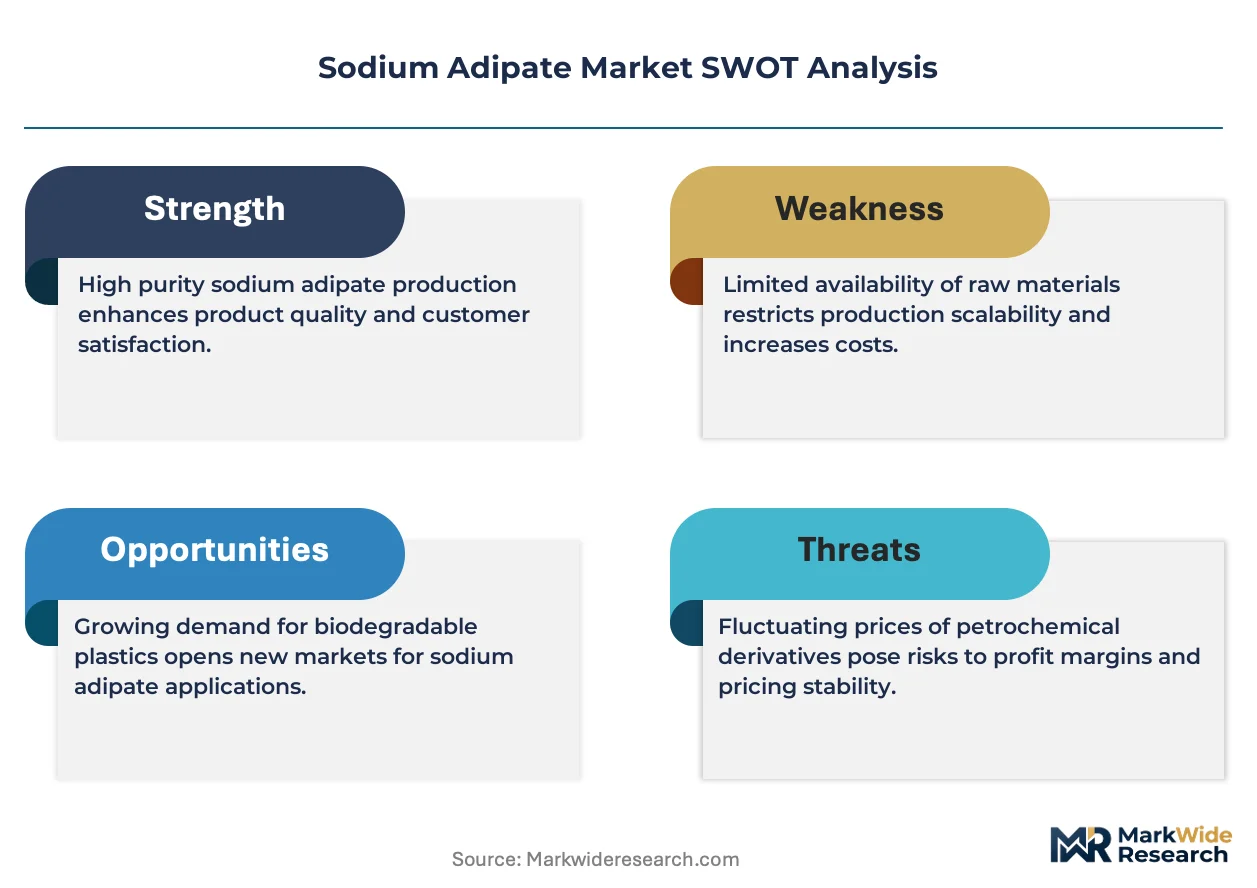
- Adipic acid feedstock volatility:Cyclohexane oxidation route inputs fluctuate with benzene pricing, compressing margin predictability for sodium adipate converters.
- Chinese industrial-grade oversupply:Shandong and Jiangsu province producers are flooding commodity channels, pressuring pricing power in non-pharmaceutical segments.
- Heavy metal impurity limits:Divergence between USP-NF and EP monograph specifications on lead and arsenic thresholds is forcing dual-batch production for cross-Atlantic supply.
Strategic Opportunities
- Indian pharmaceutical excipient qualification:CDSCO's harmonization with IPEC-PQG guidelines is opening pathway for European suppliers to displace local unregistered producers.
- Cosmetic-grade chelation demand:Premium skincare formulators in South Korea are specifying sodium adipate for pH buffering in acid-based exfoliant systems.
- Green chemistry procurement mandates:EU Green Deal sustainable chemistry incentives are favoring bio-based adipic acid routes for sodium salt downstream production.
Industry Challenges
- Analytical method transfer delays:Cross-laboratory validation of heavy metal testing protocols between supplier QC and customer QA is extending qualification timelines.
- Batch documentation digitization:Pharmaceutical customers are demanding eCTD-compatible certificate of analysis formats, forcing legacy ERP system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Adipate Market |
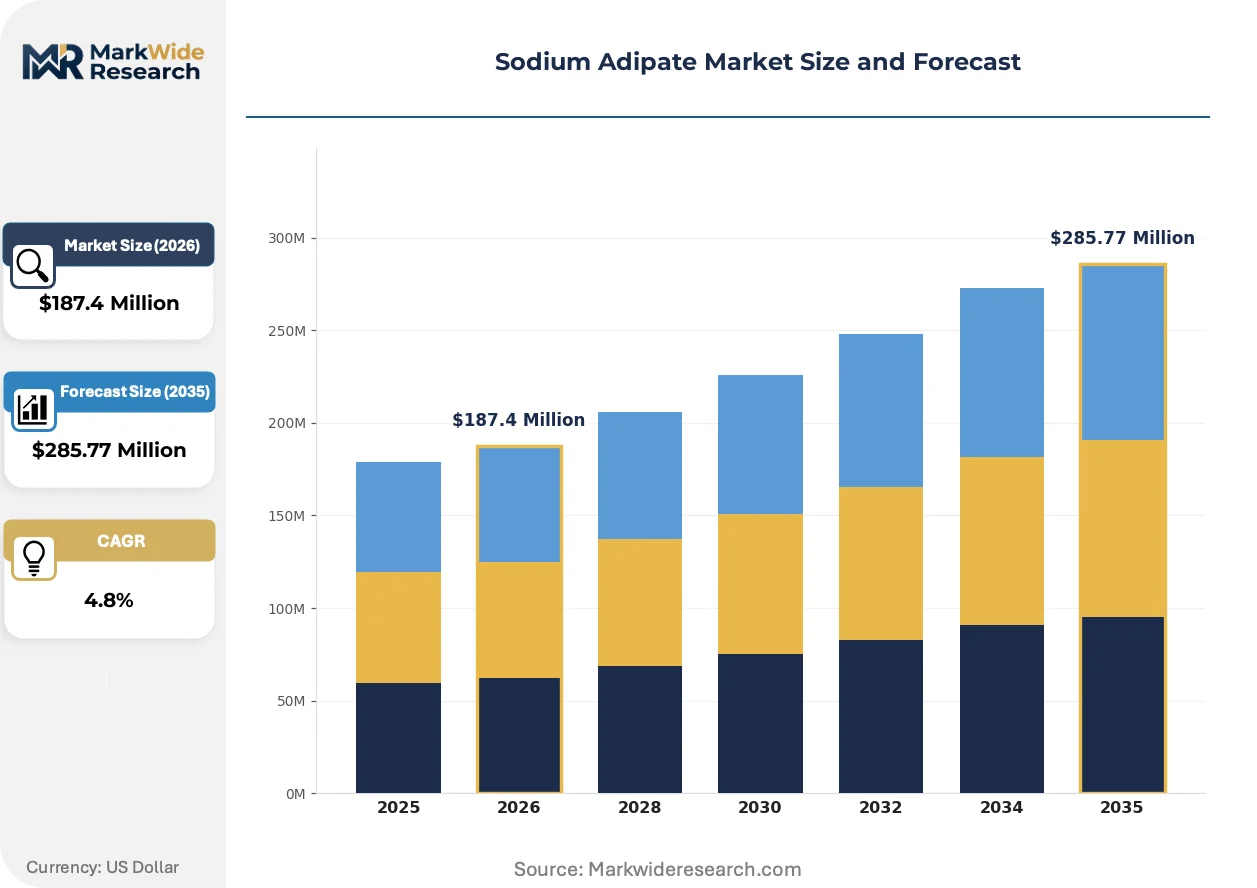
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Cosmetic Grade Application: Food Preservation, Cosmetic Formulations, Pharmaceutical Excipients, Industrial Chemicals End User: Food Industry, Cosmetics Manufacturers, Pharmaceutical Companies, Chemical Processing Packaging Type: Bags, Drums, Containers, Bulk |
| Companies Covered | Parchem Fine & Specialty Chemicals, AquaPhoenix Scientific, Inc., Sigma-Aldrich (Merck KGaA), Dr. Paul Lohmann, Spectrum Chemical Manufacturing Corp., Thermo Fisher Scientific, MP Biomedicals, LLC, Micxy, Hawkins, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Adipate Market Evolving Landscape
Continuous processing technologies and regulatory data integrity requirements are converging to reshape how sodium adipate is manufactured, tested, and qualified across pharmaceutical and food-grade supply tiers.
Continuous flow crystallization systems are replacing batch-mode sodium adipate production in pharmaceutical-grade facilities. Merck KGaA and specialized CDMOs are installing micro-reactor trains that reduce solvent consumption and tighten particle size distribution. This technology is collapsing the traditional batch-release testing bottleneck by enabling real-time process analytical technology verification.
REACH substance evaluation under ECHA's 2023-2025 work program is intensifying scrutiny on adipic acid salt impurities. The industrial consequence is mandatory updated safety data sheets and extended one-generation reproductive toxicity studies for registration dossier maintenance. Pharmaceutical-grade suppliers in Germany and the Netherlands are absorbing these compliance costs while industrial-grade competitors face registration non-renewal risk.
Certification-driven supplier consolidation is compressing procurement decision cycles among pharmaceutical excipient buyers. Large CMOs are reducing approved supplier lists from multiple regional sources to single qualified partners with dual-site manufacturing. This pattern is most visible in the US Northeast pharmaceutical corridor, where FDA Inactive Ingredient Database qualification status has become a binary filter in vendor selection.
Sodium Adipate Market Segmentation
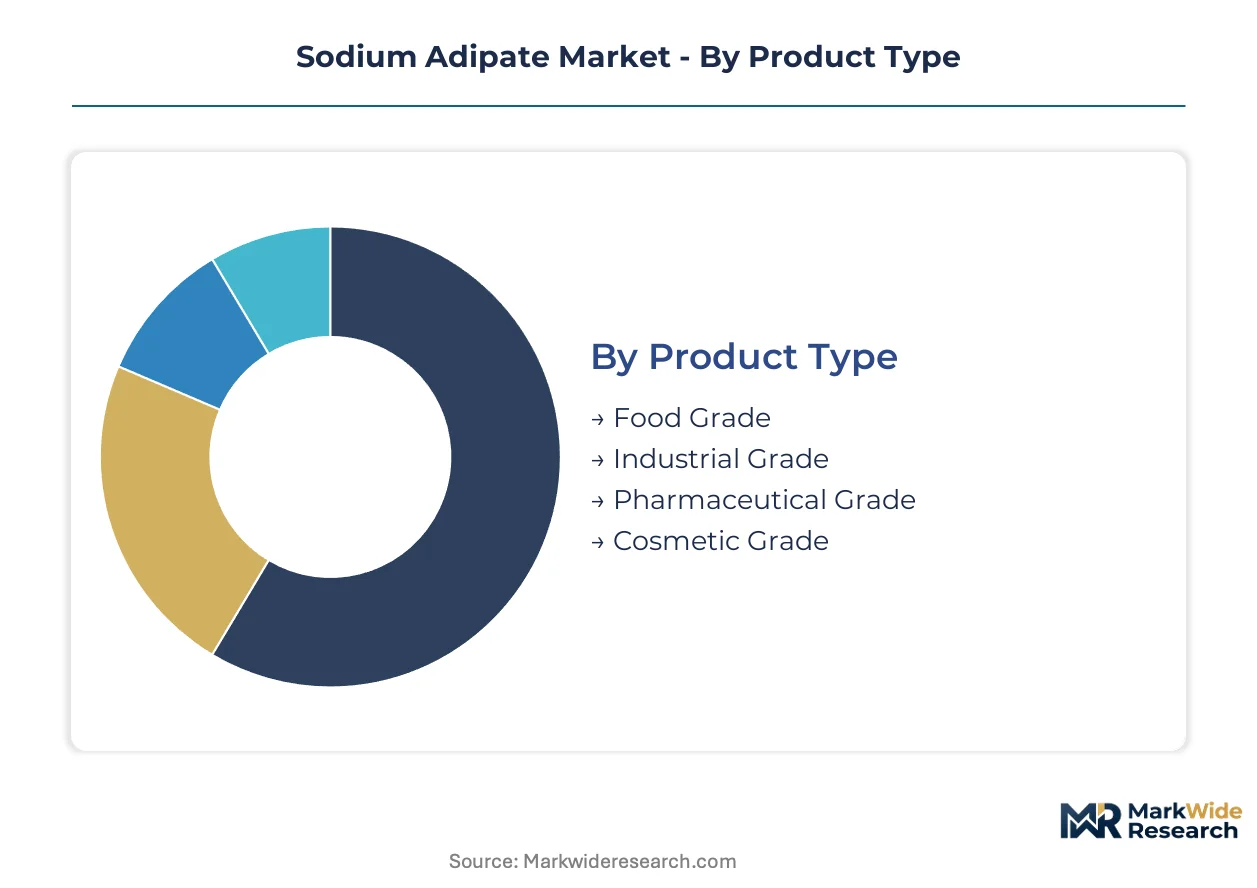
Sodium adipate specifications diverge sharply across end-use tiers, with pharmaceutical certification requirements creating insurmountable entry barriers for commodity producers. Segmentation logic follows purity thresholds and documentation burdens rather than molecular differences.
Product Type:
Use-case spectrum spans pH buffering in processed meats to chelation in premium skincare, with each tier demanding distinct impurity profiles and batch documentation.
- Pharmaceutical Grade:Meets USP-NF and EP monograph specifications with full heavy metal testing and certificate of analysis documentation. Demand concentrates among contract manufacturing organizations in Germany's Ludwigshafen-Leverkusen corridor, where REACH-registered suppliers anchor excipient supply chains amid tightening ECHA substance evaluation protocols.
- Food Grade:Functions as a pH control agent and buffering intermediate in processed meat and dairy systems under FSSAI and EFSA standards. European clean-label formulation trends are displacing synthetic phosphate alternatives, concentrating procurement among meat processing corridors in Germany and the Netherlands.
- Industrial Grade:Serves as a chemical intermediate and chelating agent in bulk chemical processing with lower purity tolerances.
- Cosmetic Grade:Targets premium skincare formulators specifying sodium adipate for pH buffering in acid-based exfoliant systems, with South Korean demand expanding most quickly.
Established volume favors Industrial Grade; emerging adoption favors Cosmetic Grade.
Application:
Functional role determines margin capture, with excipient qualification timelines stretching procurement cycles for pharmaceutical uses.
- Pharmaceutical Excipients:Tablet and capsule buffering applications demand full regulatory dossiers and FDA Inactive Ingredient Database qualification. Large CMOs are consolidating approved supplier lists to single qualified partners with dual-site manufacturing, compressing switching economics.
- Food Preservation:pH stabilization in processed meat systems operates under divergent FSSAI, EFSA, and USDA standards, with European clean-label momentum accelerating phosphate replacement.
- Cosmetic Formulations:Premium skincare chelation and pH buffering in acid-based exfoliant systems.
- Industrial Chemicals:Bulk chemical processing and intermediate synthesis with minimal documentation requirements.
Margin concentration sits with Pharmaceutical Excipients; volume scale sits with Industrial Chemicals.
End User:
Customer type shapes procurement sophistication, from commodity tenders to multi-year qualification partnerships.
- Pharmaceutical Companies:Demand eCTD-compatible certificate of analysis formats and real-time process analytical technology verification, forcing legacy ERP upgrades among suppliers. FDA oversight through the Inactive Ingredient Database creates binary vendor selection filters.
- Food Industry:European meat processors are consolidating sodium adipate procurement around REACH-registered suppliers with full dossier documentation.
- Cosmetics Manufacturers:Premium formulators in South Korea specifying chelation-grade material.
- Chemical Processing:Bulk industrial consumers facing oversupply pressure from Shandong and Jiangsu province producers.
Procurement leverage concentrates in Pharmaceutical Companies; price pressure concentrates in Chemical Processing.
Packaging Type:
Logistics configuration tracks shipment scale and contamination risk across grade tiers.
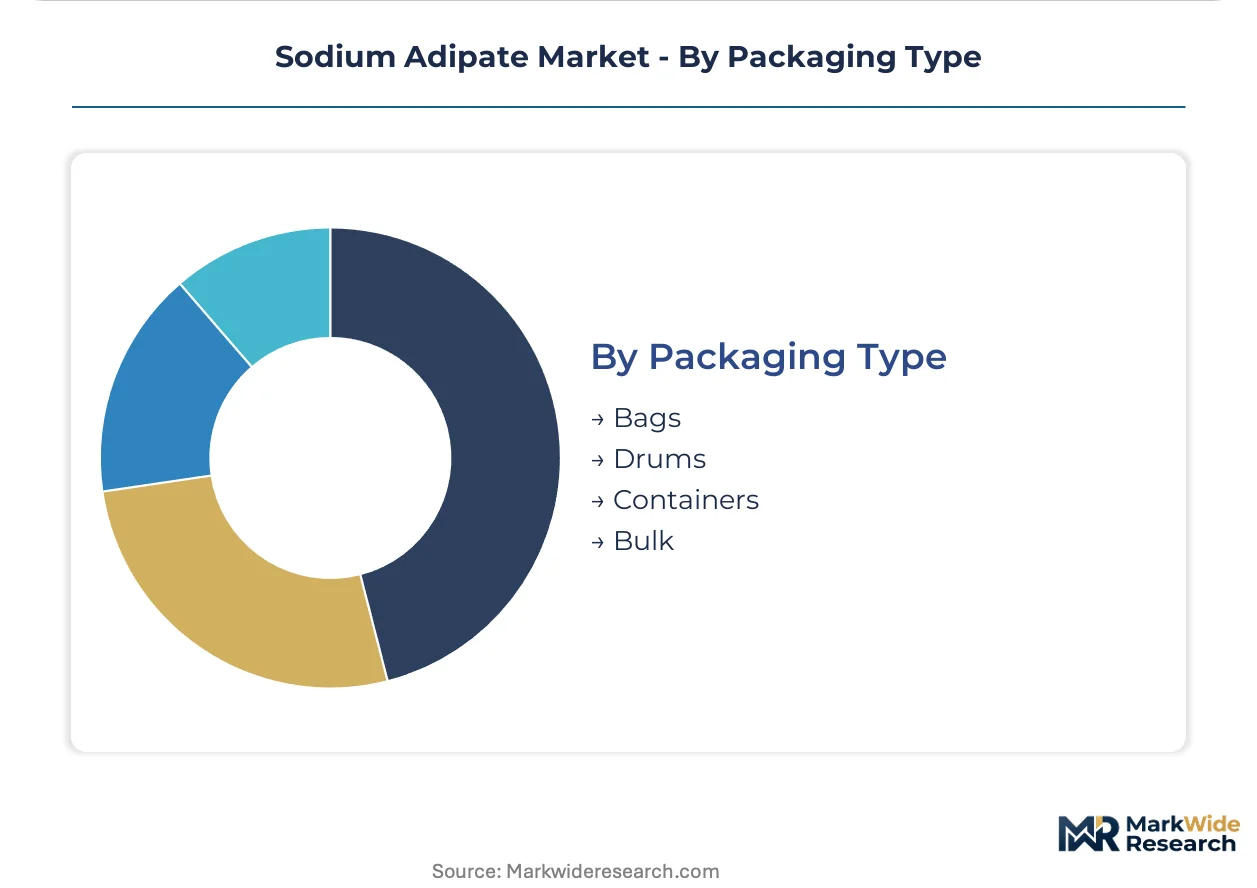
- Bulk:Tanker and silo delivery for industrial-grade volumes with minimal handling requirements.
- Drums:Standard pharmaceutical-grade containment with full batch traceability and tamper-evident sealing.
- Bags:Intermediate food-grade packaging for meat processing facilities.
- Containers:Cosmetic-grade shipments requiring humidity control and contamination prevention.
Unit economics favor Bulk; traceability requirements favor Drums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Adipic acid precursor supply from the Ludwigshafen chemical cluster anchors sodium adipate manufacturing across Western Europe. REACH-registered producers leverage this feedstock proximity to serve pharmaceutical and food-grade demand corridors. Regulatory divergence between USP-NF and EP monographs is fragmenting batch production strategies for cross-border suppliers.
Germany
Pharmaceutical excipient demand from contract manufacturing organizations concentrates around Ludwigshafen and Leverkusen. ECHA's tightened substance evaluation protocols filter out non-registered suppliers, concentrating procurement among dossier-compliant producers. The Rhine-Neckar chemical processing corridor shortens logistics lead times for sodium salt conversion from BASF's adipic acid supply.
United States
FDA Inactive Ingredient Database qualification creates binary vendor selection filters for large CMOs in the Northeast pharmaceutical corridor. USP-NF monograph enforcement shapes heavy metal impurity thresholds distinct from European standards. New Jersey and Massachusetts-based formulators consolidate approved supplier lists to single qualified partners with dual-site manufacturing.
India
CDSCO harmonization with IPEC-PQG guidelines opens pathways for European suppliers to displace unregistered local producers in pharmaceutical excipient supply. FSSAI food additive standards govern pH control agent applications in processed meat systems. Maharashtra and Gujarat-based meat processors consolidate procurement around REACH-registered suppliers with full documentation.
China
Shandong and Jiangsu province producers flood industrial-grade commodity channels, pressuring pricing power in non-pharmaceutical segments. SAMR oversight of food additive standards operates alongside evolving GB specifications for chemical purity. The Yangtze River Delta hosts bulk chemical processing capacity serving domestic industrial demand with minimal certification requirements.
South Korea
Premium skincare formulators specify cosmetic-grade sodium adipate for pH buffering in acid-based exfoliant systems. MFDS cosmetic safety standards govern chelation-grade material imports from European suppliers. Seoul-based beauty manufacturers drive fastest-percentage demand expansion across all grade tiers.
Sodium Adipate Market Competitive Landscape
Specialized excipient suppliers and diversified chemical distributors split the market along certification-intensity lines. Tier-one pharmaceutical-grade producers anchor premium positioning through USP-NF and EP monograph compliance, while commodity converters compete on adipic acid feedstock access. Three archetypes dominate: REACH-registered European specialists with full dossier documentation, North American analytical standards providers leveraging distribution scale, and Asian industrial-grade volume producers. Competitive moves concentrate on supplier list consolidation by large CMOs and dual-site manufacturing investments to hedge qualification risk.
Within the European specialist tier, Dr. Paul Lohmann exemplifies high-purity mineral salt positioning for pharmaceutical and nutritional applications. Sigma-Aldrich, operating as Merck KGaA's analytical standards division, anchors premium market presence through its certification portfolio. Parchem Fine & Specialty Chemicals occupies the diversified distributor archetype with broad SKU coverage spanning industrial and food-grade categories.
| Leading Market Players |
|---|
| Parchem Fine & Specialty Chemicals |
| AquaPhoenix Scientific, Inc. |
| Sigma-Aldrich (Merck KGaA) |
| Dr. Paul Lohmann |
| Spectrum Chemical Manufacturing Corp. |
| Thermo Fisher Scientific |
| MP Biomedicals, LLC |
| Micxy |
| Hawkins, Inc. |
| Others |
Value Network & Pricing Analysis
Ludwigshafen's adipic acid precursor capacity anchors downstream sodium salt conversion economics, concentrating margin capture among REACH-registered producers with full dossier documentation. Pharmaceutical-grade certification burdens insulate premium tiers from industrial-grade price erosion originating in Shandong and Jiangsu province oversupply.
Pricing Analysis
Aftermarket technical service revenue drives lifetime value capture across the sodium adipate value chain. Three-tier pricing structure across pharmaceutical, food, and industrial grades reflects certification intensity and batch documentation burdens. Pricing pressure stems from Chinese industrial-grade oversupply flooding commodity channels. Chemical processing buyers exhibit highest price sensitivity; pharmaceutical CMOs prioritize qualification status over unit cost.
Supply Chain Analysis
Adipic acid feedstock volatility between benzene and cyclohexane oxidation routes dominates supply chain risk exposure. Production concentrates in Germany, China, and India. Raw material dependencies center on adipic acid precursors, sodium carbonate, and purification solvents. Distribution runs through REACH-registered chemical distributors for pharmaceutical tiers and bulk commodity traders for industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified excipient supply sits as a scarce capability, with USP-NF and EP monograph compliance separating premium-positioned producers from commodity converters. Dossier documentation expertise and heavy metal testing infrastructure represent the critical asset gaps.
For Market Incumbents: Harden regulatory dossier maintenance capabilities against ECHA's tightened substance evaluation protocols. Invest in dual-site manufacturing to hedge qualification risk as large CMOs consolidate approved supplier lists. Deepen backward integration into adipic acid precursor supply to compress feedstock volatility exposure. For New Entrants and Emerging Players: Establish a beachhead in cosmetic-grade chelation demand from South Korean premium skincare formulators. Target Indian pharmaceutical excipient supply as CDSCO-IPEC-PQG harmonization displaces unregistered local producers. Lead with eCTD-compatible certificate of analysis formats to bypass legacy ERP upgrade barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because certification intensity creates insurmountable barriers for commodity entrants. Acquisition targets should display REACH registration status with full dossier documentation and established FDA Inactive Ingredient Database qualification. The signal to watch is CMO supplier list consolidation velocity in the US Northeast pharmaceutical corridor.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Maintenance Investment | ECHA's tightened substance evaluation protocols filter non-compliant suppliers from European pharmaceutical supply. |
| Dual-Site Manufacturing Expansion | Large CMOs consolidate approved supplier lists to single qualified partners with geographic redundancy. |
| Continuous Flow Crystallization Adoption | Micro-reactor trains reduce solvent consumption and enable real-time process analytical technology verification. |
| Indian Pharmaceutical Excipient Qualification | CDSCO harmonization with IPEC-PQG guidelines opens pathways for European suppliers to displace local producers. |
| Green Chemistry Procurement Alignment | EU Green Deal sustainable chemistry incentives favor bio-based adipic acid routes for downstream sodium salt production. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical excipient procurement managers, contract manufacturing organization supply chain directors, food-grade chemical buyers at European meat processors, and REACH regulatory affairs specialists. Secondary validation drew from ECHA registration dossiers, FDA Inactive Ingredient Database filings, USP-NF and EP monograph standards, and customs trade flow data. Bottom-up volume estimates triangulated against top-down market sizing across grade tiers.
Calibration against historical price realizations and qualification timeline data anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included grade tier, end-use application, packaging format, and regional production hub. CAGRs derived from fitted growth curves applied to each segment. Forecast inputs incorporated adipic acid feedstock pricing volatility indices and CMO supplier consolidation patterns.
Sensitivities concentrate around ECHA substance evaluation protocol changes, USP-NF and EP monograph divergence on heavy metal thresholds, and Chinese industrial-grade capacity additions. Forecasts reflect assumptions about regulatory harmonization trajectories and clean-label formulation momentum in European food processing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Specialty Oxidants Market
Specialty Chemicals
Toner Spray Market
Specialty Chemicals
Calcium D-Pantothenate Market
Specialty Chemicals
Sphingolipids Market
Specialty Chemicals
Catharanthine Market
Specialty Chemicals
Global Chitin Market
Specialty Chemicals
Protein Purification Resin Market
Specialty Chemicals
Immunochemistry Products Market
Specialty Chemicals
PPG-20 Methyl Glucose Ether Market
Specialty Chemicals
Ursolic Acid Market
Specialty Chemicals
Releasing Agents Market
Specialty Chemicals
Monoaluminum Phosphate Market
Specialty Chemicals
Bemotrizinol Market
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Non-Commercial Acrylic Paints Market
Specialty Chemicals
GLDA Market