
 Fatliquoring Agents Market | 2026-2036
Fatliquoring Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Fatliquoring Agents Market Analytics
Aftermarket service revenue for leather chemical formulations is tilting toward technical assistance and customized blending solutions. Lanxess AG leverages its integrated polymer backbone to dominate synthetic fatliquor supply. Stahl Holdings B.V. anchors its position through water-based technology leadership in automotive finishing. TFL Ledertechnik GmbH specializes in chrome-free tanning auxiliaries that reduce environmental compliance costs.
Fatliquoring agents are surface-active chemical compounds, typically comprising sulfited oils, phospholipids, or synthetic esters, that restore suppleness to tanned collagen matrices by lubricating fiber bundles and preventing embrittlement during drying. Synthetic product types occupy the largest volume share due to batch consistency and cost predictability, though bio-based alternatives are gaining fastest in premium footwear and automotive segments where REACH restricts certain petrochemical inputs. Liquid forms lead total consumption because pumpable emulsions integrate directly into drum processing lines, while paste variants retain niche positions in artisanal furniture and fashion leather operations.
REACH in Europe and EPA guidelines in the United States constrain volatile organic compound and heavy metal content in leather chemicals, compelling reformulation investments. BIS standards in India and China's GB specifications for industrial chemicals create parallel compliance tracks that fragment product portfolios. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and determine where regional production assets justify dedicated formulation lines.
Market Dynamics
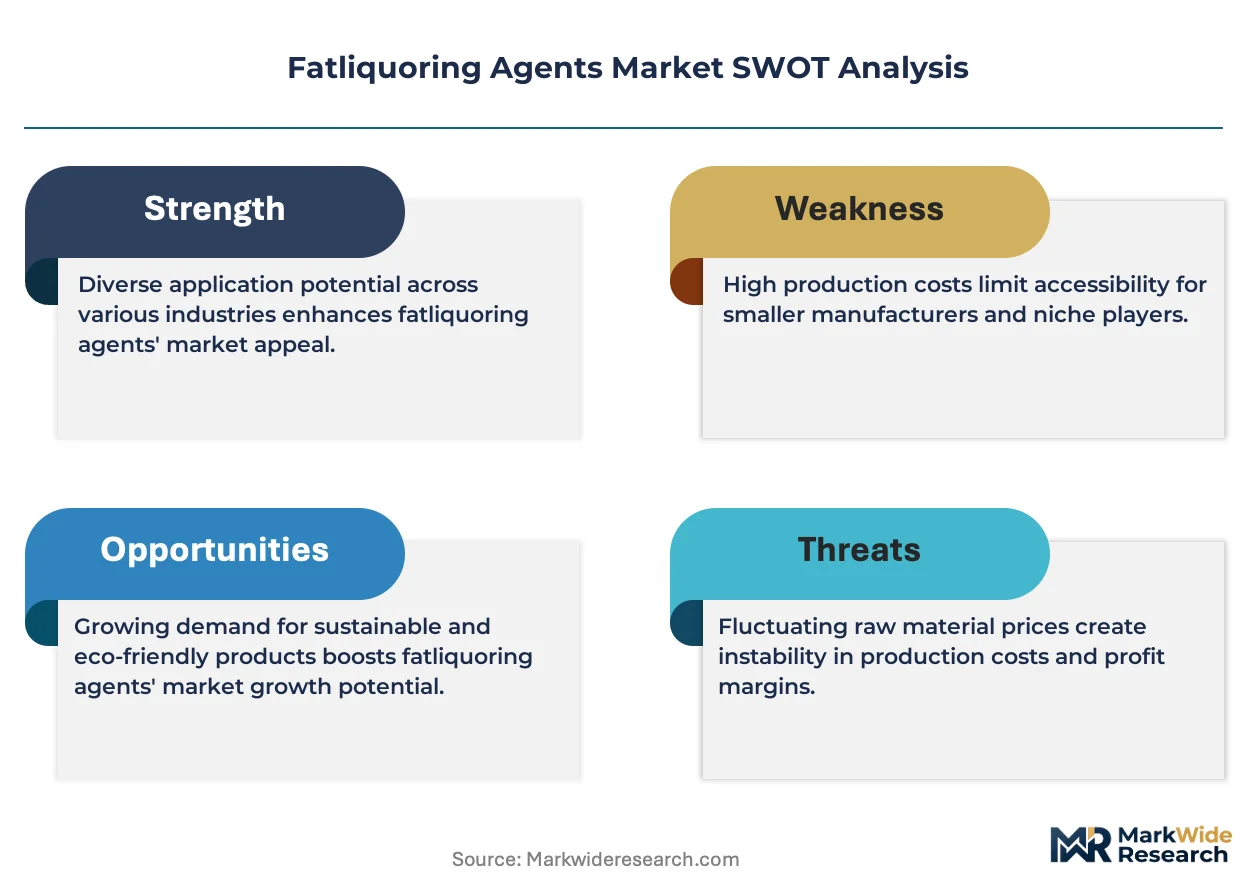
REACH compliance in Europe is forcing wholesale reformulation of petrochemical-based fatliquors, redirecting R&D budgets toward bio-based emulsions and sulfited natural oil derivatives that satisfy restricted substance lists while maintaining fiber lubrication performance.
Growth Catalysts
- Automotive leather specifications:German and Italian OEMs mandate softer, lighter-weight interiors that require higher fatliquor loading per square meter of hide.
- REACH Annex XVII restrictions:European tanneries face phased limits on alkylphenol ethoxylates, accelerating substitution demand for compliant synthetic alternatives.
- Water-based finishing convergence:Drum-processing lines across premium footwear clusters in Portugal and Spain now specify pumpable liquid emulsions that integrate with existing aqueous coating systems.
Market Restraints
- Raw material concentration:Sulfited fish oil and phospholipid supply concentrates in Peruvian and Chilean marine processing, exposing formulators to catch variability and El Niño disruptions.
- Technical performance ceiling:Bio-based emulsions still fail to match synthetic esters on heat resistance above 120°C, limiting adoption in automotive seating applications.
- Regulatory fragmentation:BIS standards in India and China's GB specifications for industrial chemicals create incompatible certification tracks that fragment product portfolios and inflate inventory costs.
Strategic Opportunities
- Underpenetrated premium footwear in Vietnam:Export-oriented tanneries around Ho Chi Minh City lack technical assistance partnerships for customized fatliquor blending, creating service-revenue white space.
- Chrome-free tanning tailwind:EU Green Deal sourcing requirements for automotive leather are compressing chrome tanning share, expanding addressable demand for fatliquors compatible with vegetable and synthetic tanning auxiliaries.
- Direct-to-tannery digital distribution:Specialty chemical platforms are disintermediating traditional distributor networks in fragmented furniture leather segments across Poland and Romania.
Industry Challenges
- Formulation chemist scarcity:European tanneries report 18-month lead times to hire specialists capable of balancing bio-based content with performance specifications under REACH.
- Legacy drum line incompatibility:Paste-format fatliquors require manual dosing systems that conflict with automated liquid emulsion infrastructure, forcing capital-intensive retrofit decisions.
- Cross-certification timeline compression:Simultaneous BIS, GB, and EPA registration requirements for global chemical suppliers are extending product launch cycles by 14-22 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fatliquoring Agents Market |
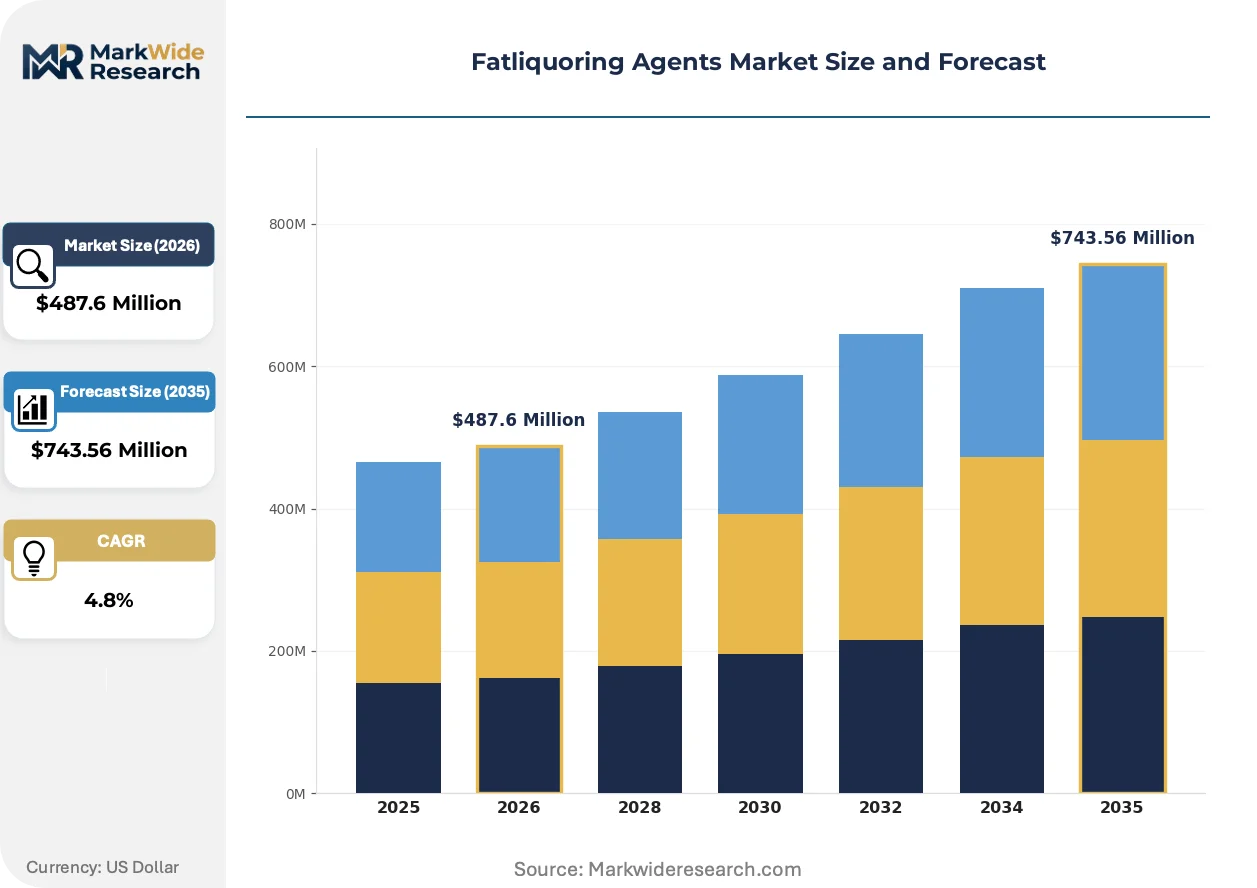
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Animal-based, Plant-based, Synthetic, Bio-based Application: Leather Tanning, Textile Processing, Industrial Lubricants, Adhesives End User: Footwear, Automotive, Furniture, Fashion Form: Liquid, Paste, Powder, Emulsion |
| Companies Covered | Lanxess AG, Stahl Holdings B.V., Clariant International Ltd., TFL Ledertechnik GmbH, BASF SE, Pulcra Chemicals GmbH, Smit & Zoon B.V., Zschimmer & Schwarz GmbH & Co KG, Buckman Laboratories International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fatliquoring Agents Market Evolving Landscape
Formulation science is virtualizing traditional fatliquor chemistry through predictive modeling and bio-based platform molecules, compressing development cycles while regulatory pressure accelerates the obsolescence of legacy petrochemical architectures.
Enzymatic modification of natural triglycerides is virtualizing conventional sulfited oil production by enabling precise molecular weight control without thermal degradation. Automotive leather finishers in Germany and the United States are piloting these enzymatic grades at 15-20% volume substitution rates. The technology is virtualizing capital allocation away from high-pressure sulfonation reactors toward biotechnology fermentation assets.
EPA guidelines on volatile organic compound emissions from leather finishing operations are compelling reformulation of solvent-borne fatliquor carriers in North American automotive supply chains. Tanneries serving Detroit-based OEMs now face phased reporting requirements that favor water-based emulsion technologies. The regulatory pressure is most acute in seating applications, where heat-aged odor specifications already exclude high-VOC legacy products.
Specification-driven procurement is consolidating buyer power among tier-one automotive leather suppliers, compressing switching cycles and unbundling after-sales technical service from chemical supply contracts. Italian and German finishers now source fatliquors through centralized polymer platforms that bundle lubrication, waterproofing, and coating functions. This concentration is most visible in Bavaria and Lombardy, where three automotive leather processors account for regional formulation demand.
Fatliquoring Agents Market Segmentation
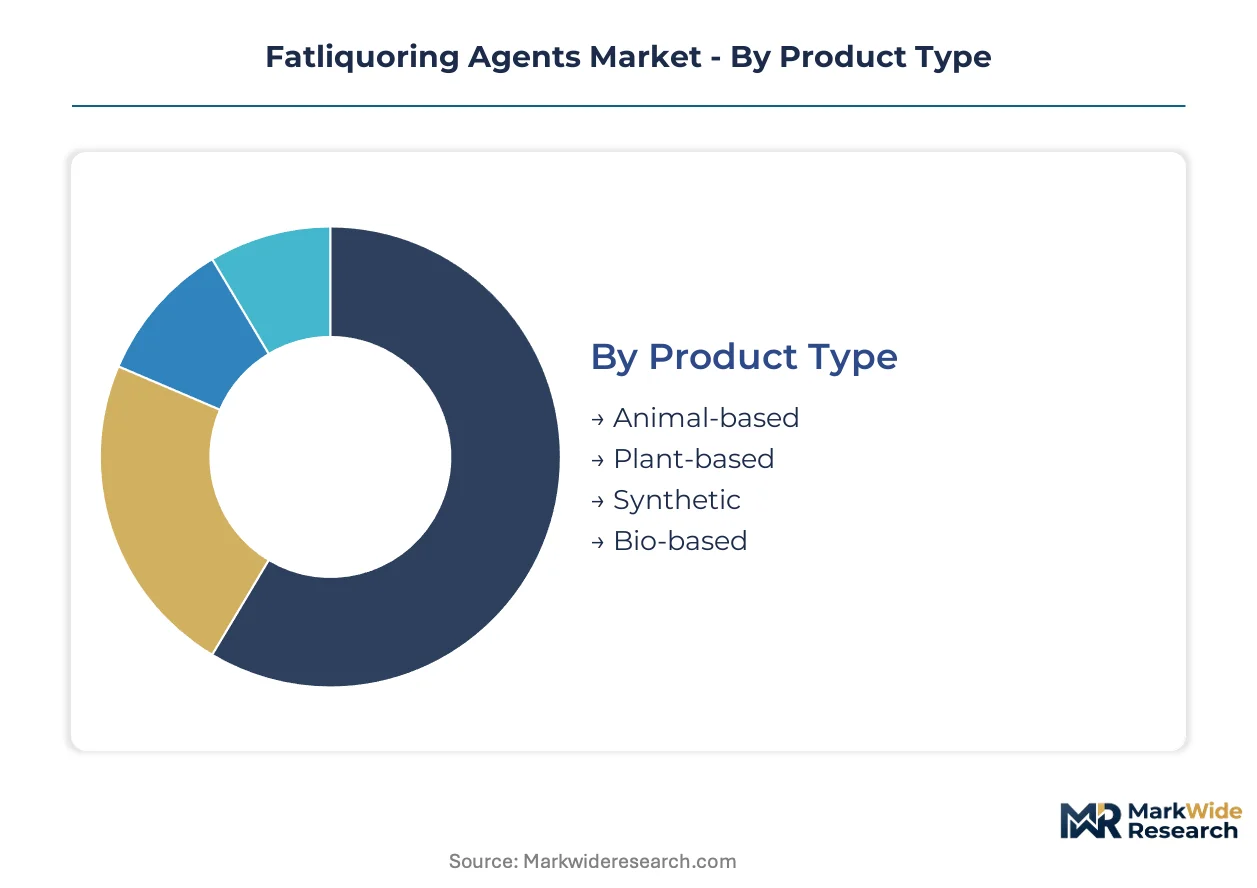
Fatliquoring agent procurement cycles vary dramatically across product architectures and end-use specifications. Automotive OEMs lock in synthetic formulations through multi-year supply agreements while artisanal furniture tanneries rotate natural oil grades seasonally based on hide availability.
Product Type:
Synthetic fatliquors turn inventory fastest in drum-processing operations due to batch consistency and predictable performance windows. Bio-based alternatives face longer qualification cycles as tanneries validate REACH compliance documentation.
- Animal-based:Derived from sulfited fish oils and marine phospholipids, these formulations deliver superior fiber lubrication for premium upholstery applications. Italian furniture tanneries around Solofra specify these grades for high-end contract seating despite supply volatility from Peruvian anchovy catch fluctuations.
- Synthetic:Petroleum-derived esters and sulfonated oils dominate automotive leather production through controlled molecular weight distribution. German OEMs in Bavaria mandate these grades for heat-resistant seating specifications above 120°C where natural alternatives embrittle.
- Plant-based:Sulfited vegetable oils from rapeseed and castor sources serve mid-tier footwear manufacturers seeking partial bio-content without full premium pricing.
- Bio-based:Enzymatically modified triglycerides from fermentation platforms are gaining traction in Portuguese footwear clusters where water-based finishing convergence demands pumpable emulsion compatibility.
Synthetic fatliquors anchor the volume base while bio-based alternatives gain share at the steepest rate.
Application:
Cost tier stratification separates commodity leather tanning from specification-driven automotive finishing where formulation services command premium pricing.
- Leather Tanning:The core application consumes fatliquors during the retanning phase to restore suppleness after chrome or vegetable tanning. Drum-processing lines across tanneries in Vietnam's Binh Duong province specify liquid emulsions for automated dosing integration.
- Textile Processing:Niche application for synthetic fiber softening in technical apparel where phospholipid derivatives reduce static accumulation.
- Industrial Lubricants:Sulfited natural oils serve biodegradable metalworking fluid formulations where EPA discharge regulations constrain petroleum alternatives.
- Adhesives:Fatliquoring chemistry modifies protein-based glues for leather goods assembly, particularly in Romanian furniture manufacturing clusters.
Leather tanning generates the dominant revenue pool while automotive finishing commands the highest margin per kilogram.
End User:
Customer type fragmentation creates divergent procurement patterns between specification-captive automotive suppliers and price-sensitive commodity footwear producers.
- Automotive:Tier-one leather finishers serving German and Italian OEMs operate under strict material approval systems. Heat-aged odor specifications and REACH Annex XVII compliance documentation extend qualification timelines to 18-24 months.
- Footwear:Export-oriented tanneries around Ho Chi Minh City and Porto rotate formulations seasonally based on fashion cycle demands and hide characteristics.
- Furniture:Artisanal producers in Poland and Romania favor paste-format fatliquors requiring manual dosing incompatible with automated lines.
- Fashion:Luxury leather goods manufacturers in Milan specify custom-blended grades where technical assistance partnerships differentiate chemical suppliers.
Footwear anchors absolute volume consumption while automotive applications expand most quickly on a value basis.
Form:
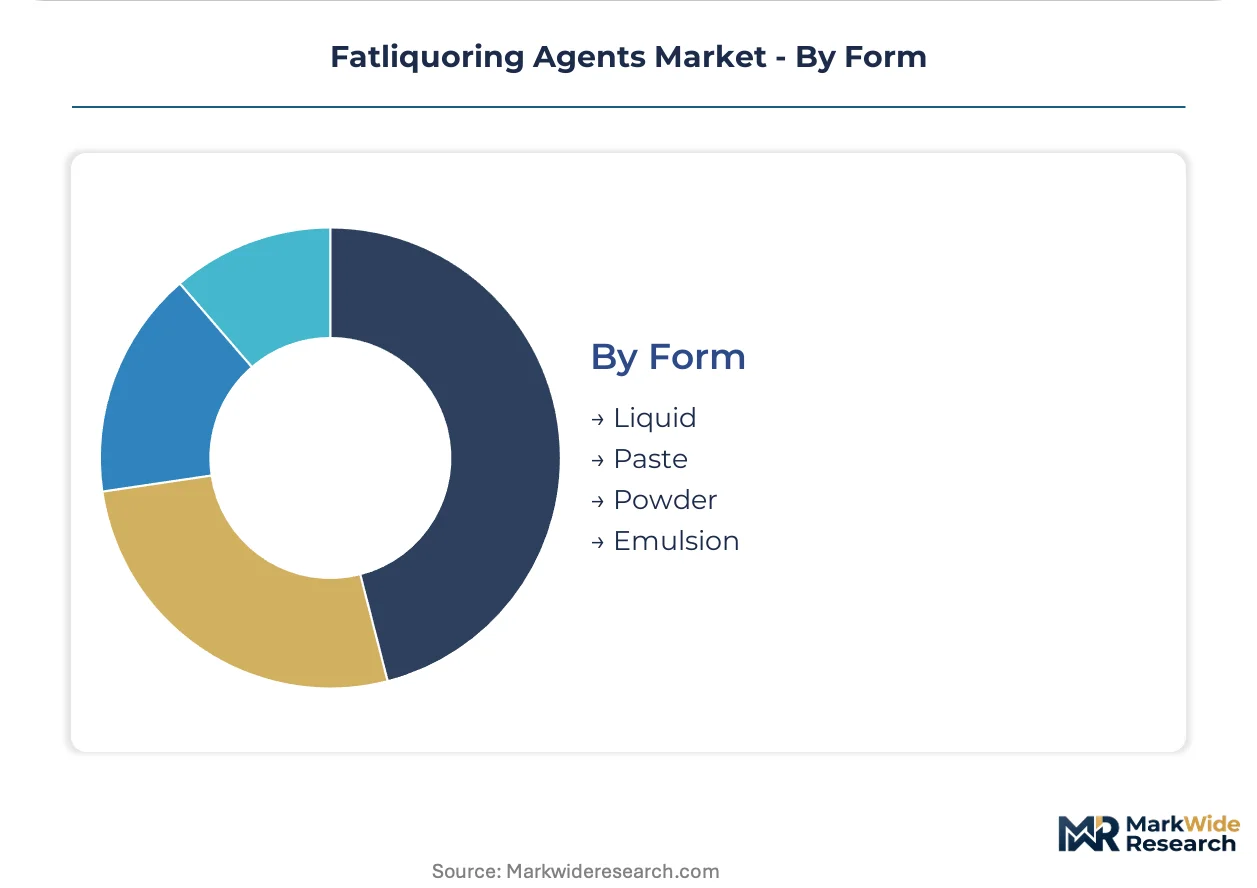
Supply concentration in liquid emulsion production reflects capital intensity advantages of continuous reactor systems over batch paste manufacturing.
- Liquid:Pumpable emulsions integrate directly into automated drum-processing lines. Water-based formulations from Stahl Holdings and Lanxess dominate Portuguese and Spanish footwear clusters where finishing convergence demands aqueous system compatibility.
- Emulsion:Pre-stabilized colloidal dispersions reduce tannery blending labor and improve batch consistency for mid-volume operators.
- Paste:High-concentration formats retain niche demand in artisanal furniture segments where manual dosing persists and capital retrofit costs deter automation.
- Powder:Spray-dried variants serve remote tanneries lacking liquid storage infrastructure, particularly in Indian leather clusters around Kanpur.
Liquid formats dominate installed processing capacity while emulsion variants climb the fastest as water-based finishing standards harden across European automotive supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive leather finishers consume synthetic fatliquors at triple the bio-based ratio seen in Italian furniture clusters, while Vietnamese footwear tanneries run almost exclusively on liquid emulsion formats incompatible with paste-dependent Polish artisans.
Germany
Bavarian automotive leather processors serving Munich-based OEMs specify heat-resistant synthetic esters for seating applications exceeding 120°C performance thresholds. REACH Annex XVII restrictions on alkylphenol ethoxylates compel reformulation of legacy petrochemical fatliquors across tanneries in the Stuttgart region. The Baden-Württemberg leather finishing corridor concentrates procurement through centralized polymer platforms bundling lubrication and coating functions.
Italy
Solofra furniture tanneries around Naples sustain demand for sulfited fish oil derivatives despite Peruvian anchovy supply volatility disrupting phospholipid availability. EU Green Deal sourcing requirements compress chrome tanning share, expanding vegetable-tanning-compatible fatliquor demand across Lombardy automotive finishers. Milan luxury leather goods manufacturers specify custom-blended grades where technical assistance partnerships differentiate chemical suppliers.
United States
Detroit-area automotive seating suppliers face EPA phased reporting requirements favoring water-based emulsion technologies over solvent-borne carriers. Heat-aged odor specifications already exclude high-VOC legacy products from tier-one OEM approval systems. Georgia and Tennessee furniture leather clusters retain paste-format manual dosing incompatible with automated liquid infrastructure.
Vietnam
Export-oriented tanneries around Ho Chi Minh City lack technical assistance partnerships for customized fatliquor blending, creating service-revenue white space for specialty chemical platforms. BIS standards compliance requirements fragment product portfolios for suppliers serving both Indian and Vietnamese procurement channels. Binh Duong province drum-processing lines specify pumpable liquid emulsions for automated dosing integration.
China
GB specifications for industrial chemicals create incompatible certification tracks with REACH and BIS standards, extending product launch cycles for multinational formulators. Zhejiang and Guangdong leather clusters drive volume consumption of mid-tier synthetic fatliquors in footwear export manufacturing. The country's dual carbon goals accelerate scrutiny of petrochemical-derived processing chemicals without yet mandating bio-based substitution.
Fatliquoring Agents Market Competitive Landscape
Capability concentration sits with integrated polymer specialists; scale advantage sits with diversified chemical conglomerates. The market structures around three tiers: multinational diversifieds with leather chemical divisions, mid-cap leather-focused specialists, and regional distributors with blending capabilities. Dominant competitive moves include backward integration into sulfited oil raw material sourcing and technology licensing partnerships for enzymatic modification platforms.
Within the integrated specialist tier, Lanxess AG and Stahl Holdings B.V. exemplify divergent strategic positioning—one anchored in synthetic polymer backbone integration, the other in water-based finishing technology leadership. TFL Ledertechnik GmbH occupies a position representing chrome-free tanning auxiliary specialization. Among diversified chemical conglomerates, BASF SE and Clariant International Ltd. sit within broader industrial chemical portfolios where leather chemicals represent a segment rather than core focus. German-origin GmbH and AG structures dominate the specialist tier, while Dutch B.V. entities concentrate in finishing technology and Belgian distribution networks.
| Leading Market Players |
|---|
| Lanxess AG |
| Stahl Holdings B.V. |
| Clariant International Ltd. |
| TFL Ledertechnik GmbH |
| BASF SE |
| Pulcra Chemicals GmbH |
| Smit & Zoon B.V. |
| Zschimmer & Schwarz GmbH & Co KG |
| Buckman Laboratories International, Inc. |
| Others |
Value Network & Pricing Analysis
Peruvian anchovy catch volatility determines both the premium spread for sulfited fish oil derivatives and the geographic shape of raw material sourcing networks. REACH Annex XVII restrictions on alkylphenol ethoxylates compress the viable supplier base for compliant synthetic esters, forcing automotive finishers into longer-term offtake arrangements that insulate against phospholipid supply interruptions.
Pricing Analysis
Long-term supply agreements dominate procurement between tier-one automotive leather finishers and synthetic fatliquor formulators, insulating Bavarian OEM suppliers from spot market volatility in sulfited oil feedstocks. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden differentiation, with REACH-compliant bio-based emulsions commanding premium positioning over legacy petrochemical grades. Cost compression in mid-tier footwear applications is intensifying because Vietnamese export tanneries rotate formulations seasonally without technical assistance contracts. Price sensitivity concentrates among artisanal furniture producers in Poland and Romania, while automotive specification-captive buyers exhibit inelastic demand for heat-resistant synthetic esters.
Supply Chain Analysis
Export control regimes on enzymatic modification technology limit flow of precision fermentation platforms from German and Dutch specialty chemical firms to unlicensed tanneries in emerging production clusters. Raw material sourcing draws from Peruvian marine processing for sulfited fish oils, German petrochemical complexes for synthetic esters, and Indian castor cultivation for vegetable oil derivatives. Single-source vulnerability concentrates in phospholipid supply from Chilean and Peruvian anchovy fisheries exposed to El Niño disruption patterns. Distribution runs through centralized polymer platforms bundling lubrication and coating functions for automotive finishers, while fragmented footwear clusters retain traditional distributor networks with blending capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical assistance and customized blending solutions expand faster than commodity chemical supply, creating service-attach revenue pools that now exceed base product margins in premium footwear and automotive specification segments.
For Market Incumbents: Harden formulation chemist retention through captive training pipelines and certification sponsorship, addressing the 18-month hiring lead times that constrain European tannery R&D velocity. Deepen backward integration into sulfited oil raw material sourcing through equity stakes in Peruvian marine processing cooperatives, mitigating catch variability exposure that threatens phospholipid-dependent product lines. For New Entrants and Emerging Players: Pursue technical assistance partnerships with export-oriented tanneries around Ho Chi Minh City, where service-revenue white space exists for customized fatliquor blending capabilities absent from incumbent distributor networks. Target Portuguese footwear clusters piloting enzymatic modification grades at 15-20% substitution rates, leveraging water-based finishing convergence demand for pumpable emulsion compatibility as the primary go-to-market wedge. For Investors and Strategic Acquirers: REACH Annex XVII phased restrictions on alkylphenol ethoxylates reshape the acquisition landscape toward bio-based emulsion specialists with compliant synthetic alternative pipelines. Five-to-ten year viability favors integrated polymer platforms bundling lubrication, waterproofing, and coating functions over standalone fatliquor formulators exposed to unbundling pressure. Watch for EPA phased reporting requirements on VOC emissions as the inflection signal compressing solvent-borne carrier valuations in North American automotive supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfited Oil Sourcing | Captive supply of Peruvian marine phospholipids insulates formulators from El Niño-driven raw material volatility. |
| Enzymatic Modification Platform Licensing | Technology partnerships with German biotechnology fermentation assets accelerate bio-based emulsion development cycles. |
| Water-Based Emulsion Capacity Expansion | Portuguese and Spanish footwear cluster demand for aqueous system compatibility drives pumpable liquid format investments. |
| Chrome-Free Tanning Auxiliary Development | EU Green Deal sourcing requirements expand addressable demand for vegetable-tanning-compatible fatliquor formulations. |
| Direct-to-Tannery Digital Distribution | Specialty chemical platforms disintermediate traditional distributor networks in fragmented Polish and Romanian furniture segments. |
Research Methodology
A standing panel of tannery technical directors, leather chemical procurement managers, automotive OEM material specification engineers, and REACH compliance consultants provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA restricted substance list updates, BIS industrial chemical standards documentation, customs trade data on sulfited oil imports, and SEC filings of diversified chemical conglomerates with leather chemical divisions. Bottom-up tannery consumption estimates triangulated against top-down polymer platform revenue allocations.
Scenario-bracketing anchored the analytical framework across the projection horizon, modeling demand trajectories under varying REACH enforcement intensities and bio-based substitution elasticities. Segmentation dimensions included product architecture (synthetic, bio-based, animal-derived), end-use specification tier (automotive OEM, premium footwear, artisanal furniture), and regional regulatory cluster (REACH-compliant Europe, EPA-regulated North America, BIS/GB-fragmented Asia). CAGRs derived from regression analysis of historical formulation loading rates against hide processing volumes, with explicit modeling of enzymatic modification adoption curves and chrome-free tanning penetration assumptions.
Macroeconomic conditions sit as an overlay; deviation in automotive production schedules, hide availability from livestock cycles, or marine catch yields would shift the trajectory. Forecasts reflect documented assumptions on regulatory phase-in timelines and technology substitution elasticities. Material shifts in EPA VOC reporting requirements or EU Green Deal implementation pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Optical Whitening Agents Market
Specialty Chemicals
Insoluble Fibers Market
Specialty Chemicals
Special Boiling Point Solvents Market
Specialty Chemicals
Vulcanization Accelerators Market
Specialty Chemicals
Dimethylolpropionic Acid (DMPA) Market
Specialty Chemicals
GLDA Market
Specialty Chemicals
Silicone Derivative Market
Specialty Chemicals
Aerosol Cans Market
Specialty Chemicals
1,2 Hexanediol Market
Specialty Chemicals
Caryophyllene Market
Specialty Chemicals
Toner Spray Market
Specialty Chemicals
Global Sodium Hyaluronate-Based Products Market
Specialty Chemicals
Taurine Market
Specialty Chemicals
Precast Gels Market
Specialty Chemicals
Global Spray Polyurethanes Foam Market
Specialty Chemicals
Glucosinolates Market