
 Fuel Additives Market | 2026-2036
Fuel Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Additives Market Analysis
Specialty chemical distribution is fragmenting as regional blenders and national oil companies build direct sourcing relationships with additive suppliers. BASF SE leverages its integrated detergent and cetane improver portfolio to sustain long-term supply contracts with European refiners. Afton Chemical Corporation anchors its position through deep technical service relationships with fleet operators seeking customized treat-rate solutions. Chevron Oronite Company LLC competes by controlling captive base oil and additive manufacturing assets across multiple continents.
Fuel additives are chemical compounds blended into petroleum-derived and alternative fuels at concentrations typically ranging from ten to several thousand parts per million to enhance combustion efficiency, protect engine hardware, or ensure fuel stability during storage and transport. Their primary commercial purpose is to enable refiners and fuel marketers to meet performance specifications and regulatory requirements without reformulating the base fuel stock. Detergents command the largest product-type revenue pool due to mandatory deposit-control standards in automotive gasoline markets across the United States, Europe, and China. Aviation applications generate the highest per-unit margins among end-use segments because jet fuel specifications impose stringent thermal stability and icing-inhibitor requirements that limit supplier competition. Fleet operators represent the fastest-growing end-user channel as logistics companies internalize fuel quality management to reduce maintenance downtime and extend engine overhaul intervals.
The United States Environmental Protection Agency enforces Tier 3 gasoline sulfur and particulate standards that directly mandate minimum detergent treat rates, while California's CARB rules impose additional requirements that shape formulation decisions for suppliers serving the North American market. Europe's REACH regulation and F-Gas Regulation constrain the use of certain halogenated deposit-control chemistries, redirecting R&D investment toward nitrogen-based and polyetheramine detergent technologies. India's BIS and CDSCO-aligned fuel quality oversight under the BS-VI framework is tightening cetane number and polycyclic aromatic hydrocarbon limits, forcing domestic refiners to import advanced additive packages or license foreign formulations. Stakeholders must monitor how carbon-border adjustment mechanisms and renewable-fuel blending mandates in major economies reshape the addressable market for conventional petroleum fuel additives versus biofuel-compatible chemistries.
Market Dynamics
Refinery upgrade cycles across Saudi Arabia, India, and China are compressing formulation windows as national oil companies demand additive packages that simultaneously satisfy multiple sulfur, cetane, and deposit-control specifications without separate blending lines.
Growth Catalysts
- BS-VI emission norms:India's tightening polycyclic aromatic hydrocarbon and cetane number limits force domestic refiners to import advanced additive packages, redirecting formulation demand toward cetane improvers and detergents.
- Aviation hub expansion:Saudi Arabia's aviation infrastructure buildout is accelerating procurement of thermal stability additives and icing inhibitors by Middle Eastern fuel suppliers meeting stricter sulfur-content rules.
- NMPA-aligned standards:China's fuel quality framework is redirecting gasoline additive demand toward nitrogen-based detergent chemistries as halogenated alternatives face restriction.
Market Restraints
- Base oil supply concentration:Captive production of Group II/III base stocks by integrated refiners in the US Gulf Coast and Middle East limits third-party additive blender access to consistent feedstock quality.
- REACH chemical restrictions:Europe's F-Gas Regulation and REACH constraints on halogenated deposit-control chemistries force costly R&D redirection toward polyetheramine alternatives with longer qualification timelines.
- Renewable fuel incompatibility:Fatty acid methyl ester and hydrotreated vegetable oil blends degrade conventional petroleum-optimized additive performance, requiring reformulation investment ahead of confirmed biofuel mandate scales.
Strategic Opportunities
- Fleet operator channel development:Logistics companies internalizing fuel quality management create direct procurement relationships with additive suppliers, bypassing traditional refinery intermediaries for customized treat-rate solutions.
- Carbon-border adjustment preparation:EU CBAM implementation is incentivizing additive suppliers to develop biofuel-compatible chemistries that qualify imported fuels for lower carbon-intensity ratings.
- Dual carbon goal alignment:China's MEE and MIIT frameworks are creating demand for combustion-improver additives that reduce particulate emissions without compromising engine efficiency in legacy vehicle fleets.
Industry Challenges
- Multi-jurisdiction formulation complexity:Additive suppliers must maintain parallel product lines satisfying EPA Tier 3, CARB, REACH, and BIS specifications simultaneously, straining quality assurance and inventory management systems.
- Treat-rate optimization expertise gap:Fleet operators and independent blenders lack in-house tribology and combustion chemistry capabilities to specify optimal additive concentrations for variable fuel quality and operating conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Additives Market |
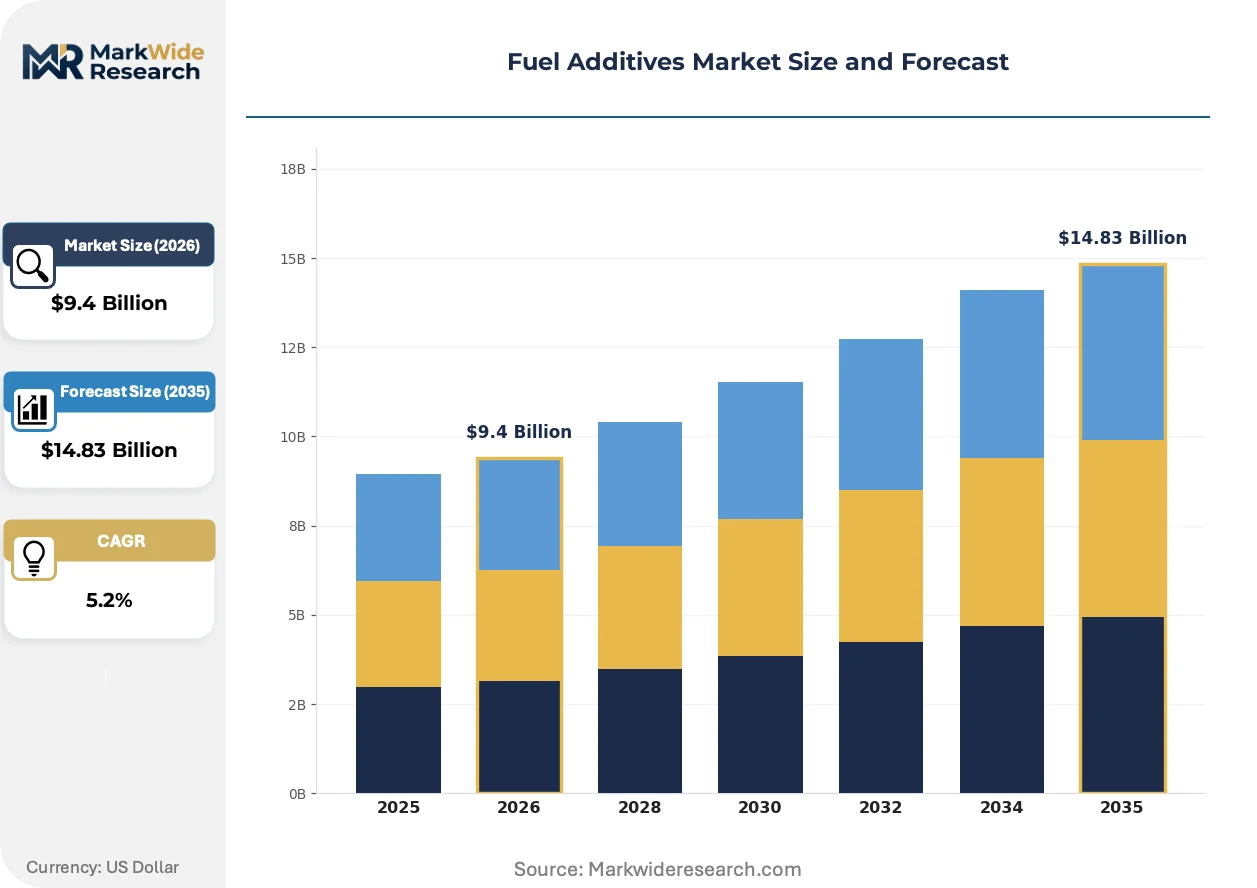
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $14.83 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Detergents, Cetane Improvers, Corrosion Inhibitors, Antioxidants Application: Automotive, Aviation, Marine, Industrial End User: OEMs, Fleet Operators, Fuel Retailers, Maintenance Providers Distribution Channel: Direct Sales, Online Sales, Retail Outlets, Distributors |
| Companies Covered | TotalEnergies SE, Afton Chemical Corporation, BASF SE, Infineum International Limited, Chevron Oronite Company LLC, Evonik Industries AG, Lubrizol Corporation, Clariant AG, Innospec Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Additives Market Emerging Trajectories
Formulation science is converging with digital fuel quality monitoring as real-time engine performance data reshapes how treat rates are specified and validated across distributed supply chains.
Polyetheramine detergent technologies are collapsing the performance gap between nitrogen-based and legacy halogenated deposit-control chemistries. European refiners under REACH pressure are accelerating adoption of these reformulated packages. The technology is collapsing supplier margins on conventional detergent lines while compressing qualification timelines for new market entrants.
California's CARB rules are extending beyond federal EPA Tier 3 baselines to mandate additional particulate and evaporative emission controls. This regulatory layering forces additive suppliers serving North America to maintain California-specific formulation variants. Gasoline marketers in the state are responding by consolidating procurement with suppliers offering integrated detergent-cetane-oxygenate packages that satisfy both federal and state requirements.
Direct sourcing relationships between fleet operators and additive manufacturers are displacing traditional refinery-mediated distribution channels. Logistics companies with centralized fuel procurement functions are negotiating technical service contracts that include real-time treat-rate adjustment based on telematics feedback. This pattern is most visible in the US long-haul trucking sector where maintenance cost visibility drives specification precision.
Fuel Additives Market Segmentation
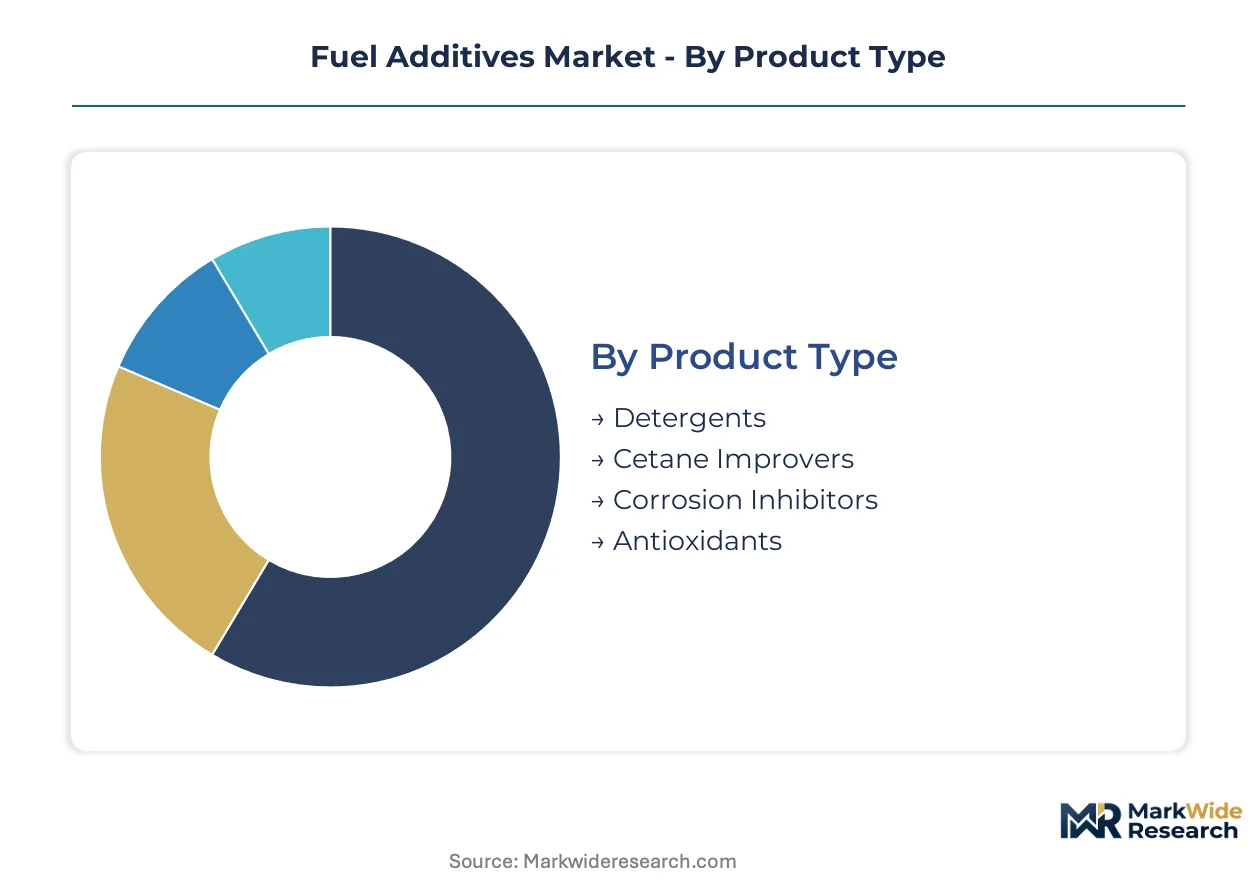
Additive suppliers configure technical service intensity and treat-rate calibration protocols differently across each segment boundary. Product chemistry, application environment, and procurement channel together determine qualification timelines and margin structures.
Product Type:
After-sales service intensity peaks with detergent and cetane improver formulations requiring continuous treat-rate optimization and engine deposit monitoring.
- Detergents:Nitrogen-based and polyetheramine chemistries prevent intake valve and combustion chamber deposits in gasoline direct-injection engines. Demand concentrates in US and European automotive markets where EPA Tier 3 and REACH deposit-control standards mandate minimum treat rates. Fleet operators in California negotiate technical service contracts incorporating real-time telematics feedback for treat-rate adjustment.
- Cetane Improvers:2-ethylhexyl nitrate and di-tert-butyl peroxide compounds accelerate diesel ignition delay reduction. India's BS-VI emission norms and tightening polycyclic aromatic hydrocarbon limits force domestic refiners to import advanced packages, redirecting formulation demand toward these chemistries.
- Corrosion Inhibitors:Polar compounds adsorb onto metal surfaces in aviation fuel systems and marine storage tanks, protecting against electrochemical degradation from water contamination.
- Antioxidants:Hindered phenols and aromatic amines interrupt free-radical chain reactions in biodiesel blends and long-term storage applications.
Detergents hold the largest share; momentum sits with cetane improvers as diesel emission standards tighten across India and China.
Application:
Cost tier differentiation separates aviation specification-grade additives from commodity automotive formulations.
- Automotive:Gasoline and diesel fuel additives address deposit control, cetane enhancement, and cold-flow improvement for passenger and commercial vehicles. China's NMPA-aligned standards redirect demand toward nitrogen-based detergent chemistries as halogenated alternatives face restriction under MEE frameworks.
- Aviation:Jet fuel thermal stability additives and icing inhibitors meet stringent ASTM D1655 and DEF STAN 91-091 specifications. Saudi Arabia's aviation hub expansion accelerates procurement by Middle Eastern fuel suppliers confronting stricter sulfur-content rules.
- Marine:Bunker fuel treatments manage cat fines, sludge dispersion, and combustion improver functions for residual fuel oils in international shipping.
- Industrial:Power generation and heating oil applications require stability additives for long-term storage and combustion efficiency in stationary engines.
Automotive commands volume concentration; aviation generates the steepest expansion trajectory in per-unit margin terms.
End User:
Customer type determines specification authority and procurement centralization.
- OEMs:Vehicle manufacturers specify first-fill additive packages and warranty-compliant aftermarket chemistries, requiring extensive engine test validation.
- Fleet Operators:Logistics companies with centralized fuel procurement functions internalize fuel quality management to reduce maintenance downtime. US long-haul trucking fleets negotiate direct technical service contracts with additive manufacturers, bypassing traditional refinery intermediaries.
- Fuel Retailers:Branded and unbranded fuel marketers select additive packages to differentiate on deposit-control performance claims.
- Maintenance Providers:Independent service shops dispense aftermarket fuel system cleaners and performance additives through retail and workshop channels.
Fleet operators are gaining share fastest as logistics companies build in-house tribology capabilities and telematics integration.
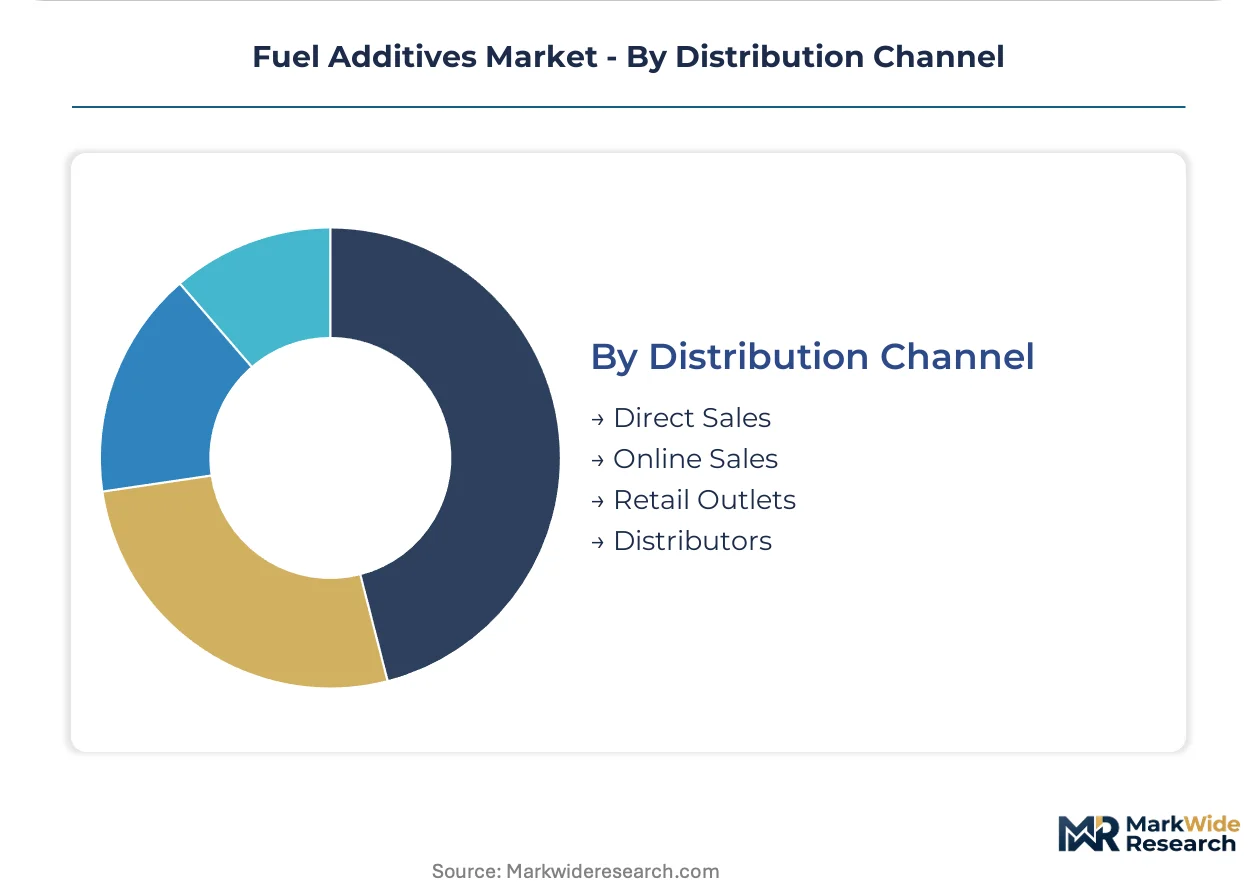
Distribution Channel:
Supply concentration varies by channel, with direct sales capturing formulation-intensive accounts.
- Direct Sales:Additive suppliers maintain technical service teams for refinery and national oil company accounts requiring customized treat-rate solutions and joint formulation development.
- Online Sales:E-commerce platforms serve independent blenders and small fleet operators seeking standardized additive packages with documented treat-rate guidance.
- Retail Outlets:Automotive aftermarket channels distribute consumer-facing fuel system cleaners and performance additives through service stations and parts retailers.
- Distributors:Regional chemical distributors aggregate demand from independent blenders and maintenance providers, managing inventory and local technical support.
Direct sales anchor the channel structure; online platforms are climbing the fastest as procurement digitization penetrates mid-size fleet accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's BS-VI emission norms and China's NMPA-aligned fuel quality standards are redirecting formulation demand toward cetane improvers and nitrogen-based detergents. Saudi Arabia's aviation hub expansion accelerates procurement of thermal stability additives. The United States maintains stringent EPA Tier 3 standards that mandate minimum detergent treat rates.
United States
California's CARB rules extend beyond federal EPA Tier 3 baselines to mandate additional particulate controls. Fleet operators in the state consolidate procurement with suppliers offering integrated detergent-cetane packages. The US long-haul trucking sector in the Midwest and Southeast negotiates direct technical service contracts with additive manufacturers.
China
MEE frameworks restrict halogenated deposit-control chemistries, redirecting gasoline additive demand toward nitrogen-based alternatives. The dual carbon goals under MIIT frameworks create demand for combustion-improver additives. Yangtze River Delta refiners import advanced additive packages to meet NMPA-aligned polycyclic aromatic hydrocarbon limits.
India
Domestic refiners face tightening BS-VI cetane number and polycyclic aromatic hydrocarbon limits that force import of advanced additive packages. BIS and CDSCO-aligned fuel quality oversight redirects formulation demand toward cetane improvers. Gujarat and Maharashtra refining clusters upgrade processing units to accommodate higher detergent treat rates.
Germany
REACH regulation and F-Gas Regulation constrain halogenated deposit-control chemistries, redirecting R&D investment toward polyetheramine detergent technologies. The KBA enforces stringent automotive emission standards that shape formulation decisions. Bavaria-based chemical clusters accelerate adoption of reformulated nitrogen-based detergent packages.
Saudi Arabia
Aviation infrastructure buildout accelerates procurement of thermal stability additives and icing inhibitors by fuel suppliers. Stricter sulfur-content rules imposed by national regulators redirect additive formulation demand. The Eastern Province refining and aviation hub expansion concentrates procurement relationships with international additive suppliers.
Fuel Additives Market Vendor Landscape
On the supply side, the industry is consolidating around integrated chemical conglomerates with captive base oil and additive manufacturing assets. The vendor base separates into three strategic archetypes: diversified chemical majors with detergent-cetane portfolios, specialty additive houses with deep technical service capabilities, and refinery-captive blenders with direct sourcing relationships. Dominant competitive moves include backward integration into base stock production and technology licensing partnerships for biofuel-compatible formulations.
Within the diversified chemical major tier, BASF SE and Evonik Industries AG exemplify integrated players controlling multiple chemistries across continents. Afton Chemical Corporation occupies a specialist position anchoring technical service relationships with fleet operators seeking customized treat-rate solutions. Chevron Oronite Company LLC represents the refinery-integrated archetype with captive manufacturing assets.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Afton Chemical Corporation |
| BASF SE |
| Infineum International Limited |
| Chevron Oronite Company LLC |
| Evonik Industries AG |
| Lubrizol Corporation |
| Clariant AG |
| Innospec Inc. |
| Others |
Supply Flow & Price Mechanics
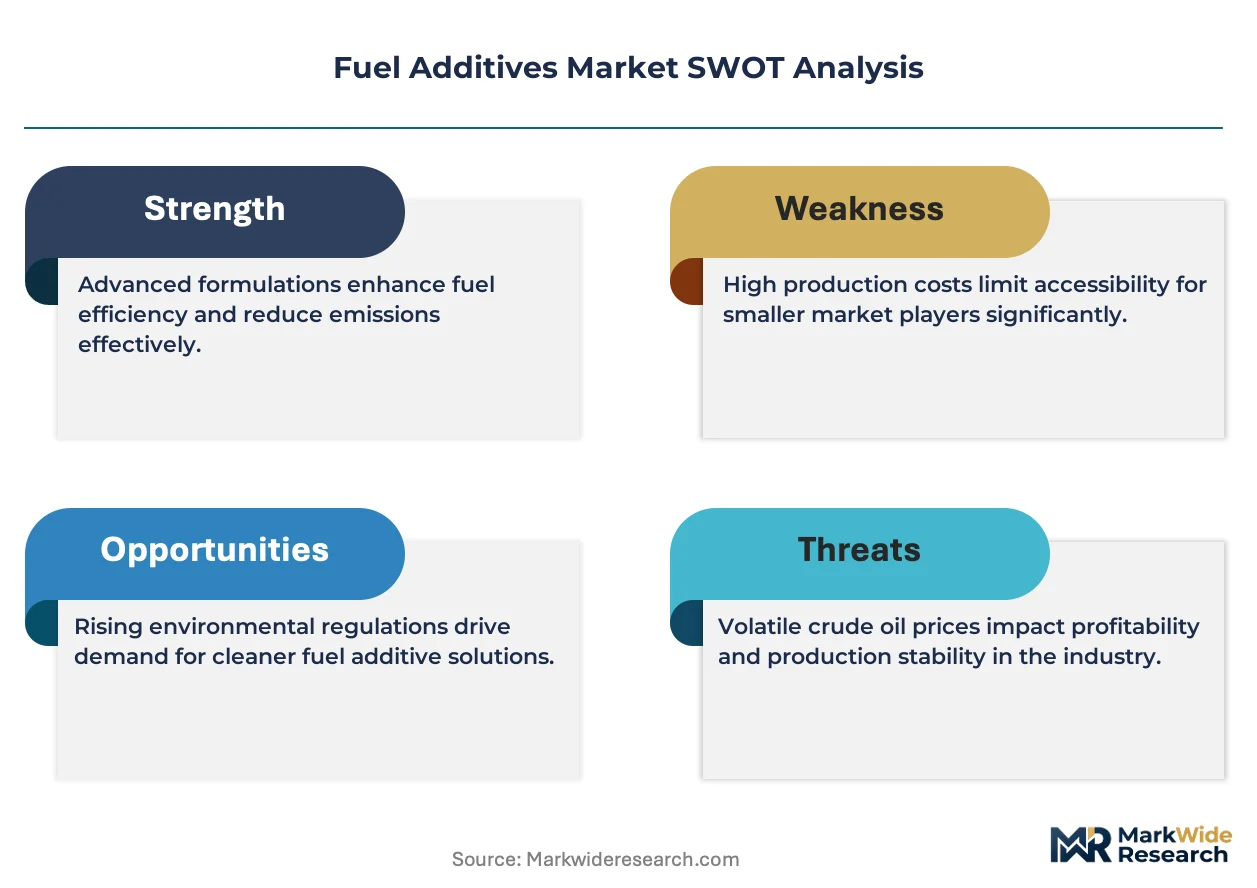
REACH chemical restrictions on halogenated deposit-control chemistries determine both the widening spread between polyetheramine-certified premium formulations and legacy economy tiers and the geographic restructuring of additive manufacturing assets toward nitrogen-based chemistry hubs.
Pricing Analysis
Certification level against REACH and EPA Tier 3 standards creates the primary spread between premium nitrogen-based detergent packages and economy-grade halogenated alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects treat-rate precision, technical service bundling, and qualification timeline compression. Cost compression in the standard tier is intensifying as European refiners accelerate polyetheramine adoption and compress margins on legacy lines. Fleet operators with centralized procurement functions exhibit lowest price sensitivity due to maintenance cost visibility, while independent blenders in emerging markets face acute budget constraints.
Supply Chain Analysis
Export-control regimes limiting dual-use chemical manufacturing equipment constrain technology transfer to certain jurisdictions and fragment global additive production networks. Manufacturing concentrates in Germany, the United States, and China as integrated chemical majors maintain captive base oil and additive synthesis assets. The supply chain draws from specialized 2-ethylhexyl nitrate precursors, polyetheramine intermediates, and hindered phenol antioxidant feedstocks. Single-source vulnerability concentrates around European polyetheramine capacity as REACH deadlines approach. Distribution runs through direct technical service teams for refinery accounts and regional chemical distributors for independent blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty chemical distribution fragmentation creates white-space opportunities as fleet operators bypass traditional refinery intermediaries and demand customized treat-rate solutions with embedded technical service.
For Market Incumbents: Harden formulation portfolios against biofuel incompatibility risks by accelerating R&D investment in fatty acid methyl ester-compatible chemistries ahead of mandate scale confirmation. Consolidate backward integration into Group II/III base stock production in the US Gulf Coast and Middle East to defend margin position against captive refinery blenders. Deepen technical service relationships with logistics companies internalizing fuel quality management. For New Entrants and Emerging Players: Build out digital treat-rate optimization platforms targeting mid-size fleet operators in the US long-haul trucking sector where procurement digitization penetration remains incomplete. India's BS-VI-driven import dependency for advanced cetane improver packages offers the most penetrable geography. Pursue joint formulation development partnerships with national oil companies in Saudi Arabia's aviation hub expansion. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated chemical majors with detergent-cetane portfolios and captive manufacturing assets. Long-term viability over the next decade hinges on biofuel-compatible chemistry pipelines and carbon-border adjustment qualification capabilities. Monitor EU CBAM implementation timelines as the critical inflection signal for biofuel additive demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Stock Production | Captive Group II/III supply secures feedstock quality consistency for integrated refiners in the US Gulf Coast. |
| Polyetheramine R&D Acceleration | REACH-compliant nitrogen-based detergent development redirects European refiner procurement away from halogenated alternatives. |
| Fleet Operator Direct Channel Buildout | Technical service contracts with logistics companies bypass traditional refinery intermediaries for treat-rate customization. |
| Biofuel-Compatible Formulation Licensing | Technology partnerships with renewable fuel producers address fatty acid methyl ester degradation of conventional additive performance. |
| Carbon-Border Adjustment Certification Investment | EU CBAM-aligned chemistry qualification enables lower carbon-intensity ratings for imported fuel additive packages. |
Methodological Framework
Cross-validation between primary interviews with refinery procurement directors, additive technical service managers, fleet operator fuel quality leads, and national oil company supply planners and secondary validation through customs/trade data, ACC and Cefic industry reports, and SEC 10-K filings anchors the qualitative findings. Bottom-up segmentation modeling triangulates against top-down market sizing approaches.
Calibration against historical formulation adoption curves and regulatory deadline impacts shapes the analytical framework across the projection horizon. Segmentation dimensions include product chemistry type, application environment, end-user procurement centralization, and regional regulatory cluster. CAGRs derive from treat-rate expansion trajectories, refinery upgrade cycle timing, and fleet operator channel penetration rates. Industry-specific inputs incorporate BS-VI and NMPA-aligned standard implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by integrated Middle Eastern refiners or accelerated biofuel mandate scaling would shift outcomes. Material shifts in REACH enforcement timelines or carbon-border adjustment scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Glycol Acetate Market
Additives
Cement Grinding Aid and Performance Enhancers Market
Additives
Global UV Absorbers Market
Additives
Sodium Caprylate Market
Additives
Material Shrinkage-reducing Agents Market
Additives
Propyl Gallate Market
Additives
Global Ester Gum Market
Additives
Global Scale Inhibitors Market
Additives
Asia Pacific Silage Additives Market
Additives
United States Citric Acid Market
Additives
Global Silica-Based Matting Agents Market
Additives
Benzoates Market
Additives
Impact Modifier Market
Additives
2-Ethylhexyl Nitrate (2EHN) Market
Additives
Global UV Stabilizers Market
Additives
South America Sodium Reduction Agents Market