
 Superoxide Dismutase Market | 2026-2036
Superoxide Dismutase Market Size, Share, and Industry Trends Forecast 2026-2036
Superoxide Dismutase Market Outlook
ISO 9001 certification for biologics manufacturing is reorganizing competitive access in the Superoxide Dismutase Market, as contract manufacturers without current Good Manufacturing Practice alignment face exclusion from pharmaceutical supply chains. Thermo Fisher Scientific leverages its analytical instrumentation portfolio to anchor quality control workflows for SOD producers. Merck KGaA sustains European production capacity for recombinant enzymes through its Darmstadt operations. Douglas Laboratories competes in the premium nutraceutical segment with specialized superoxide dismutase formulations.
Superoxide dismutase is a metalloenzyme that catalyzes the dismutation of superoxide radicals into oxygen and hydrogen peroxide, operating with copper-zinc, manganese, or iron cofactors depending on cellular location. The enzyme requires cold-chain stabilization below eight degrees Celsius for parenteral grades and serves primarily as an active pharmaceutical ingredient for oxidative stress modulation in inflammatory disorders. Recombinant SOD dominates value capture due to batch consistency advantages in injectable applications, while liposomal SOD represents the fastest-expanding delivery format as cosmetic manufacturers seek enhanced dermal penetration. Natural SOD sourced from bovine liver maintains entrenched positions in oral nutraceuticals where cost sensitivity limits synthetic alternatives.
FDA biologics licensing requirements and EMA's enzyme purity monographs under the European Pharmacopoeia collectively determine which SOD grades qualify for pharmaceutical procurement, creating a dual-track market split between clinical-grade and cosmetic-grade supply. The EPA monitors fermentation waste streams from recombinant production facilities, adding compliance layers for North American manufacturers. Stakeholders must monitor evolving pharmacopeial standards for liposomal encapsulation efficiency metrics as this delivery mode expands beyond cosmetics into parenteral inflammation therapies.
Market Dynamics
Pharmaceutical-grade enzyme certification requirements are bifurcating supplier tiers, as contract manufacturers lacking current Good Manufacturing Practice alignment face exclusion from parenteral drug supply chains while nutraceutical-grade producers compete on cost.
Growth Catalysts
- EMA Enzyme Purity Monographs:Tightening European Pharmacopoeia standards for recombinant enzymes are accelerating qualification investments among contract manufacturers serving pharmaceutical clients.
- Liposomal Encapsulation:Cosmetic formulators in South Korea and France are driving demand for enhanced dermal penetration formats, expanding addressable applications beyond traditional therapeutics.
- United States:Contract manufacturing organizations in Massachusetts and California serve both domestic nutraceutical brands and export-oriented pharmaceutical clients, consolidating procurement volume.
Market Restraints
- Cold-Chain Infrastructure:Parenteral-grade SOD requires stabilization below eight degrees Celsius, limiting distribution reach to regions with reliable temperature-controlled logistics.
- Bovine Liver Supply Concentration:Natural SOD sourcing depends on livestock byproduct streams concentrated in Argentina and Brazil, exposing processors to agricultural commodity volatility.
- Recombinant Production Waste:EPA monitoring of fermentation effluent streams adds compliance layers and capital intensity for North American recombinant enzyme facilities.
Strategic Opportunities
- India:CDSCO's evolving biologics pathway and domestic PLI scheme incentives create entry points for contract manufacturers establishing local recombinant enzyme capacity.
- Inflammatory Disorder Parenterals:Liposomal SOD delivery is expanding from cosmetics into parenteral inflammation therapies, opening higher-margin pharmaceutical applications.
- ISO 9001 Convergence:Biologics manufacturers integrating quality management certification with pharmacopeial alignment can access dual-track clinical and cosmetic supply contracts.
Industry Challenges
- Metalloenzyme Purification Expertise:Copper-zinc cofactor retention during recombinant production requires specialized chromatography talent scarce outside established enzyme hubs.
- Dual Pharmacopeial Compliance:Producers serving both FDA and EMA markets must maintain parallel validation protocols, extending certification timelines and audit burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superoxide Dismutase Market |
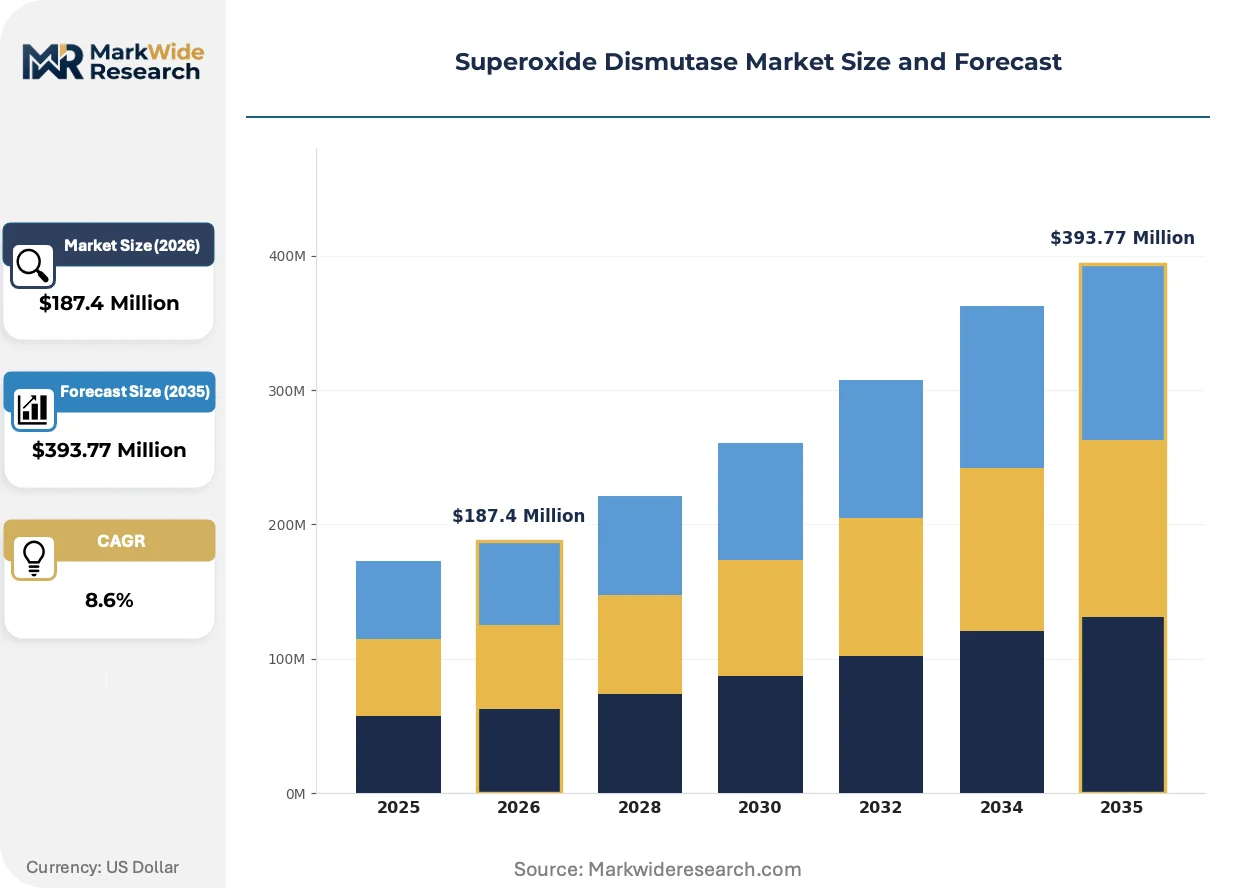
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant SOD, Natural SOD, Liposomal SOD, Enzymatic SOD Application: Cosmetics, Pharmaceuticals, Nutraceuticals, Food Additives End User: Healthcare Institutions, Research Laboratories, Cosmetic Manufacturers, Dietary Supplement Providers Delivery Mode: Injectable, Oral, Topical, Intranasal |
| Companies Covered | Douglas Laboratories, Calzyme Laboratories, Worthington Biochemical Corporation, Merck KGaA, Thermo Fisher Scientific, BASF, DSM Nutritional Products, Cayman Chemical Company, Sigma-Aldrich Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superoxide Dismutase Market Strategic Shifts
Delivery technology convergence and regulatory harmonization pressures are restructuring how superoxide dismutase moves from fermentation tanks to end-use formulations across pharmaceutical and cosmetic value chains.
Recombinant expression systems utilizing Pichia pastoris and CHO cell lines are decomposing batch-to-batch variability that has historically constrained parenteral drug applications. Large-molecule drug sponsors in Germany and Switzerland are qualifying these platforms for Phase III inflammation trials. The technology is decomposing cost premiums previously attached to bovine-derived enzyme consistency guarantees.
REACH registration requirements for novel enzyme formulations are forcing cosmetic-grade producers to submit full toxicological dossiers before EU market entry. ECHA's substance evaluation workflow adds twelve to eighteen months to product launch timelines. Small-batch nutraceutical suppliers without dedicated regulatory affairs functions are retreating from European distribution.
Direct procurement relationships between pharmaceutical formulators and recombinant enzyme producers are compressing distributor margins historically captured by specialty chemical intermediaries. Large CMOs in the United States and Ireland are establishing captive supply agreements with fermentation specialists. This pattern is most visible in parenteral anti-inflammatory development programs where traceability requirements exceed standard chemical sourcing protocols.
Superoxide Dismutase Market Segmentation
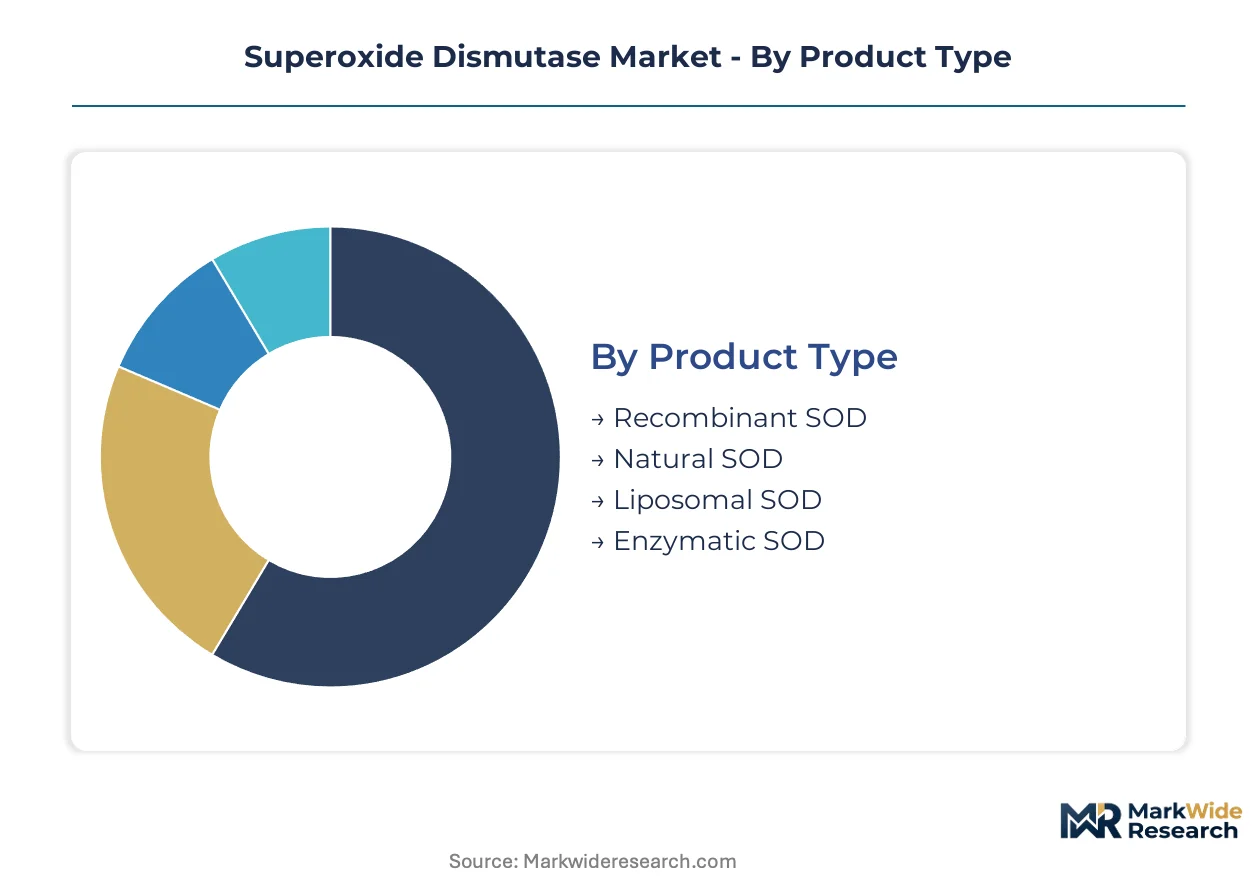
Superoxide dismutase procurement patterns diverge sharply across product grades and delivery formats, with pharmaceutical certification requirements creating pricing tiers that separate parenteral-grade suppliers from cosmetic-grade competitors. Understanding where margin pools concentrate within each dimension enables suppliers to prioritize qualification investments.
Product Type:
Recombinant production platforms command the steepest margin premiums due to batch consistency guarantees required for FDA biologics licensing.
- Recombinant SOD:Engineered expression systems in Pichia pastoris or CHO cell lines deliver metalloenzyme with controlled copper-zinc cofactor ratios. Massachusetts and California contract manufacturing organizations serve Phase III inflammation trials requiring traceable fermentation records. FDA biologics guidance tightens further with each revision.
- Liposomal SOD:Phospholipid encapsulation enhances dermal penetration for cosmetic applications while protecting enzymatic activity from gastric degradation. South Korean formulators in Seoul and Busan drive qualification demand for enhanced stability metrics. ECHA REACH registration timelines extend twelve to eighteen months for novel liposomal formulations.
- Natural SOD:Bovine liver extraction maintains cost advantages in oral nutraceutical segments where cold-chain infrastructure remains limited.
- Enzymatic SOD:Catalytic variants with modified active sites target specialized research applications requiring substrate specificity adjustments.
The dominant share belongs to Recombinant SOD, while Liposomal SOD is closing the gap fastest.
Application:
Volume concentration tracks regulatory pathway complexity, with pharmaceutical applications demanding proportionally higher quality management investment per kilogram.
- Pharmaceuticals:Parenteral anti-inflammatory therapies require current Good Manufacturing Practice alignment and pharmacopeial validation under FDA and EMA monographs. Darmstadt fermentation specialists anchor European supply for injectable enzyme APIs. EMA enzyme purity standards accelerate quarterly.
- Cosmetics:Antioxidant claims in premium skincare formulations leverage liposomal delivery for dermal penetration advantages. French formulators in Lyon and Paris specify encapsulation efficiency above eighty-five percent. REACH compliance costs filter small-batch competitors from EU distribution.
- Nutraceuticals:Oral supplements in capsule and tablet formats tolerate wider potency variation than parenteral grades.
- Food Additives:Preservation applications in packaged goods face EFSA novel food authorization requirements for enzyme-based shelf-life extension.
Pharmaceuticals generates the highest value per unit, though Cosmetics is expanding most quickly.
End User:
Procurement sophistication separates institutional buyers with captive quality audit teams from commercial formulators relying on supplier documentation.
- Healthcare Institutions:Hospital pharmacy departments source parenteral SOD for inflammatory disorder protocols requiring cold-chain custody documentation. Major medical centers in Boston and San Francisco maintain approved supplier lists with biennial requalification cycles. Joint Commission accreditation standards extend to biologics procurement.
- Cosmetic Manufacturers:Premium skincare brands in Seoul and Paris specify liposomal encapsulation efficiency and particle size distribution. Direct technical service relationships with fermentation specialists replace traditional distributor channels. Stability testing protocols exceed cosmetic-grade norms.
- Research Laboratories:Academic and contract research organizations purchase small-batch enzymatic variants for mechanistic studies.
- Dietary Supplement Providers:Nutraceutical brands prioritize cost position over pharmacopeial alignment for oral superoxide dismutase formulations.
Healthcare Institutions anchor volume commitment, while Cosmetic Manufacturers are gaining share fastest.
Delivery Mode:
Supply chain configuration determines accessible markets, with temperature requirements fragmenting distribution capabilities between parenteral and oral channels.
- Injectable:Intravenous and intramuscular administration requires stabilization below eight degrees Celsius with validated cold-chain documentation. Ireland-based CMOs establish captive fermentation partnerships for traceable API supply. EPA monitoring of production effluent adds compliance layers for North American facilities.
- Topical:Dermal application in cosmetic and dermatological formulations permits ambient distribution with stability testing focused on oxidation resistance. Liposomal encapsulation dominates premium positioning. South Korean cosmetic manufacturers specify enhanced penetration metrics.
- Oral:Capsule and tablet formats tolerate wider temperature excursions, enabling distribution through standard nutraceutical wholesale channels.
- Intranasal:Nasal spray delivery targets rapid systemic absorption for acute inflammatory indications, with limited commercial penetration to date.
Injectable commands the premium tier, though Topical is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold-chain logistics infrastructure at the Port of Rotterdam anchors European distribution for parenteral-grade SOD, while the Port of Busan enables South Korean cosmetic formulators to source liposomal encapsulation materials. These maritime gateways connect fermentation specialists in Germany and France with pharmaceutical clients across three continents.
United States
Contract manufacturing organizations in Massachusetts and California serve Phase III inflammation trials and domestic nutraceutical brands. FDA biologics licensing requirements tighten traceability standards for recombinant enzyme APIs. Greater Boston hosts fermentation specialists supplying parenteral-grade material to hospital pharmacy departments.
Germany
Darmstadt-based production facilities anchor European recombinant enzyme capacity for injectable anti-inflammatory therapies. EMA enzyme purity monographs under the European Pharmacopoeia accelerate quarterly, forcing qualification investments. Bavarian analytical instrumentation clusters support quality control workflows for SOD producers.
South Korea
Cosmetic manufacturers in Seoul and Busan drive demand for liposomal SOD with enhanced dermal penetration specifications. MFDS regulates biologics while the national cosmetic safety framework governs antioxidant claims. The Seoul Capital Area concentrates formulators specifying encapsulation efficiency above eighty-five percent.
India
CDSCO's evolving biologics pathway and domestic PLI scheme incentives attract contract manufacturers establishing recombinant enzyme capacity. Maharashtra and Gujarat host fermentation facilities targeting export-oriented pharmaceutical clients. The national regulator's alignment with ICH guidelines streamlines qualification for Western markets.
France
Premium skincare formulators in Lyon and Paris specify liposomal SOD for antioxidant positioning in luxury cosmetics. ECHA REACH registration requirements extend twelve to eighteen months for novel enzyme formulations. The Auvergne-Rhône-Alpes region anchors phospholipid encapsulation expertise serving dermal delivery applications.
Superoxide Dismutase Market Competitive Environment
Listed leaders compete with private specialists across certification tiers, with public companies leveraging capital markets to fund cGMP alignment while family-owned fermenters retain flexibility in nutraceutical segments. The supplier base stratifies into pharmaceutical-grade certifiers, cosmetic-grade formulators, and research-grade distributors. Three archetypes dominate: diversified life science conglomerates with analytical instrumentation synergies, dedicated enzyme houses with metalloprotein purification expertise, and nutraceutical specialists with cost-optimized bovine extraction. Competitive moves concentrate on captive supply agreements between CMOs and fermentation specialists, plus backward integration into recombinant expression platform development.
Among diversified life science conglomerates, Thermo Fisher Scientific and Merck KGaA exemplify the analytical-to-biologics integration archetype, leveraging instrumentation portfolios to anchor quality control workflows for SOD producers. Douglas Laboratories occupies a position within the premium nutraceutical tier, representing specialized formulation capabilities for oral superoxide dismutase products. These three entities illustrate how scale-driven conglomerates and focused specialists coexist across divergent certification requirements.
| Leading Market Players |
|---|
| Douglas Laboratories |
| Calzyme Laboratories |
| Worthington Biochemical Corporation |
| Merck KGaA |
| Thermo Fisher Scientific |
| BASF |
| DSM Nutritional Products |
| Cayman Chemical Company |
| Sigma-Aldrich Corporation |
| Others |
Value Chain & Pricing Dynamics
FDA biologics licensing requirements and EMA enzyme purity monographs simultaneously gate supply qualification and price differentiation, creating parallel certification-cost barriers that pharmaceutical-grade suppliers exploit for margin protection while nutraceutical-grade competitors race to cost floors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates parenteral-grade recombinant SOD from cosmetic-grade liposomal formulations and oral nutraceutical extracts. Price differentiation hinges on pharmacopeial validation status and cold-chain custody documentation, with Massachusetts CMOs commanding substantial premiums for FDA-aligned traceability. Cost compression in natural SOD extraction intensifies as Argentine livestock byproduct availability fluctuates. Nutraceutical brands exhibit highest price sensitivity, while hospital pharmacy departments prioritize supply security over unit economics.
Supply Chain Analysis
Inventory lead times for parenteral-grade SOD stretch substantially due to fermentation batch validation and metalloenzyme purification cycles. Supply concentrates in Germany, the United States, and South Korea, with Darmstadt fermentation specialists and Massachusetts CMOs anchoring pharmaceutical capacity while Seoul cosmetic formulators drive liposomal encapsulation demand. Raw material flows draw from bovine liver byproduct streams in Argentina, phospholipid suppliers in France, and copper-zinc cofactor reagent distributors in Bavaria. Single-source vulnerability in recombinant expression platform expertise creates qualification bottlenecks. Distribution runs through cold-chain logistics providers serving hospital pharmacy departments and direct technical service relationships replacing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized chromatography talent for metalloenzyme purification remains scarce outside established fermentation hubs, constraining capacity expansion and preserving incumbent pricing power for qualified suppliers.
For Market Incumbents: Secure captive fermentation partnerships with Phase III drug sponsors before CMO consolidation accelerates, and deepen backward integration into Pichia pastoris expression platform development to defend against emerging recombinant specialists. EMA's accelerating enzyme purity monographs threaten audit failures for laggard facilities. For New Entrants and Emerging Players: Lead with liposomal SOD qualification for South Korean cosmetic manufacturers, where encapsulation efficiency specifications above eighty-five percent filter established suppliers lacking dermal delivery expertise. India's CDSCO biologics pathway offers the most penetrable regulatory entry point for contract manufacturers seeking Western market alignment through ICH convergence. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across recombinant enzyme production as EPA effluent monitoring and dual pharmacopeial compliance extend certification timelines. Five-to-ten year viability favors acquiring metalloprotein purification specialists with existing EMA validation rather than greenfield capacity builds. Watch liposomal SOD penetration into parenteral inflammation therapies as the inflection signal for delivery technology convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Massachusetts CMOs expand fermentation capacity to serve Phase III inflammation trials requiring traceable batch records. |
| Regulatory Approval Pathway | CDSCO's evolving biologics guidance attracts contract manufacturers establishing recombinant enzyme capacity in Maharashtra. |
| Backward Integration | Fermentation specialists acquire copper-zinc cofactor reagent production to secure metalloenzyme purification supply. |
| Long-term Supply Agreement | Irish CMOs establish captive partnerships with liposomal encapsulation specialists for parenteral anti-inflammatory APIs. |
| Green Manufacturing Transition | EPA-monitored facilities invest in fermentation waste stream treatment to maintain North American production permits. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with fermentation facility managers, pharmaceutical regulatory affairs leads, hospital pharmacy procurement directors, and cosmetic formulator technical service heads; and secondary validation against FDA biologics guidance documents, EMA enzyme purity monographs, European Pharmacopoeia standards, and customs trade data for bovine liver extract flows. Bottom-up capacity assessments and top-down demand modeling were triangulated.
Across the analysis window, projections incorporate recombinant versus natural sourcing splits, parenteral versus oral delivery mode trajectories, and pharmaceutical versus cosmetic application growth rates. CAGRs were derived from segment-level growth patterning and input cost elasticity modeling. Forecast inputs include EMA monograph revision cadence, cold-chain infrastructure expansion rates, and liposomal encapsulation technology adoption curves.
Forecasts assume regulatory continuity in FDA biologics licensing and EMA enzyme purity standards; material policy shifts would require re-modeling. Outputs reflect assumptions about fermentation yield improvements and metalloenzyme purification efficiency gains. Specific risk factors include Argentine agricultural commodity volatility, REACH registration timeline extensions, and EPA effluent compliance cost inflation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Biodegradable Chelating Agents Market
Specialty Chemicals
Lactic Acid Blend Market
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Flame-Retardant Synergist Systems with Low Smoke Toxicity Market
Specialty Chemicals
Fabric Antibacterial Spray Market
Specialty Chemicals
Africa Lactic Acid Market
Specialty Chemicals
Sphingolipids Market
Specialty Chemicals
Demethylase Inhibitor Market
Specialty Chemicals
Dipentene (Limonene) Market
Specialty Chemicals
Food Grade Paraffin Market
Specialty Chemicals
Fixing Agent Market
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
Natural Insect Repellent Market
Specialty Chemicals
Global Fabric Softener Sheet Market
Specialty Chemicals
Phenylbenzimidazole Sulfonic Acid Market