
 Brominated Flame Retardants Market | 2026-2036
Brominated Flame Retardants Market Size, Share, and Industry Trends Forecast 2026-2036
Brominated Flame Retardants Market Analysis
Multi-source procurement of brominated intermediates is expanding as compounders reduce reliance on single-origin supply chains. Albemarle Corporation leverages its Arkansas bromine extraction assets to sustain captive feedstock for downstream flame retardant output. ICL Industrial Products anchors its position through Dead Sea bromine operations and integrated derivative manufacturing. Jiangsu Yoke Technology competes on cost-optimized tetrabromobisphenol A production serving domestic PCB laminate mills.
Brominated flame retardants comprise organobromine compounds, typically containing 50-85% bromine by weight, that interrupt combustion through radical scavenging in the gas phase and char formation in the condensed phase. Their primary purpose is to delay ignition and reduce flame spread in plastics, textiles, and electronic enclosures where fire safety standards mandate specific reaction-to-fire thresholds. Tetrabromobisphenol A dominates volume flows as the workhorse reactive intermediate for epoxy-based laminates, while brominated polystyrene captures premium positioning in engineered thermoplastics requiring thermal stability above 300°C. Brominated epoxy formulations command margin pools in high-layer-count PCB applications where resin compatibility and dielectric performance constrain substitution.
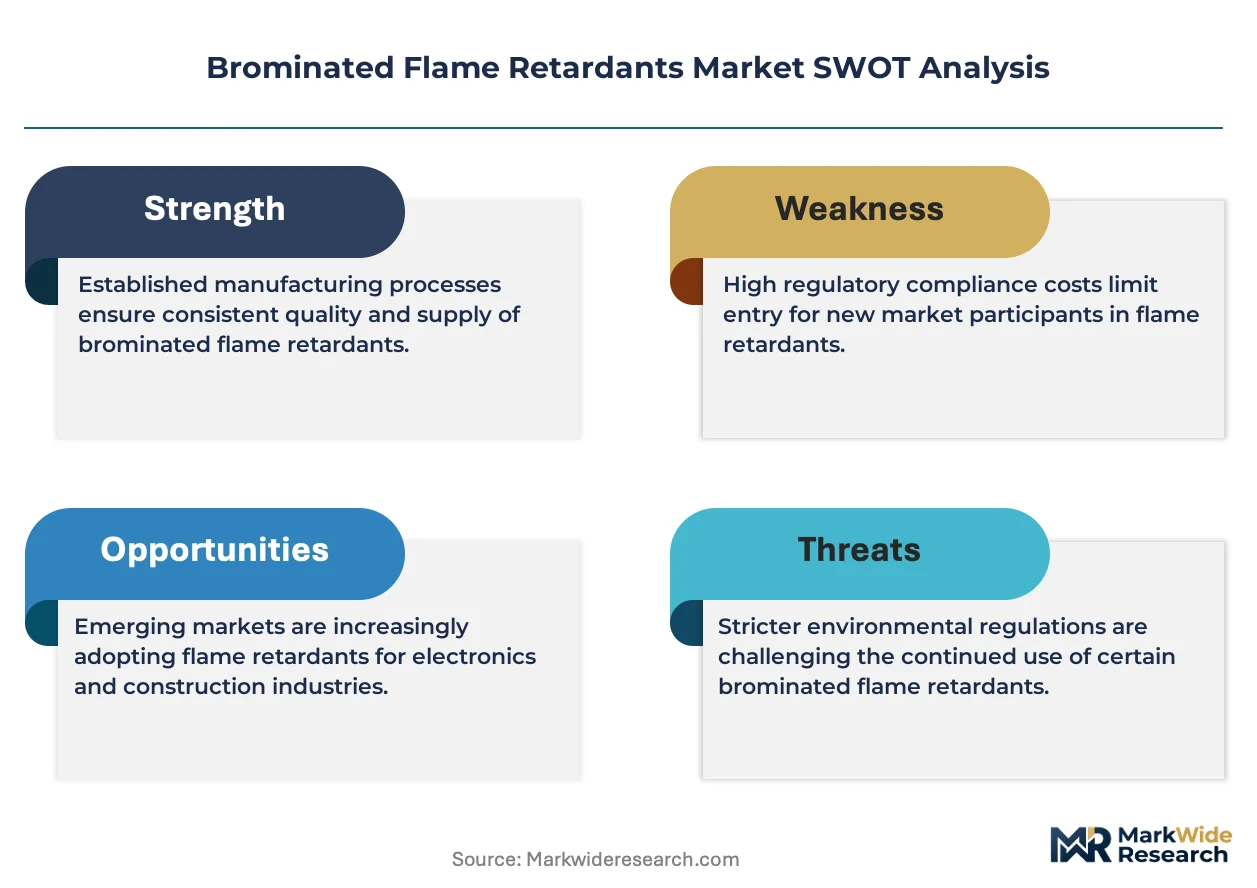
EPA scrutiny of persistent bioaccumulative toxicants under the Toxic Substances Control Act shapes product registration pathways and sunset timelines for legacy formulations. ECHA restrictions on hexabromocyclododecane under REACH Annex XVII have forced reformulation in European construction and textile applications, redirecting demand toward polymeric alternatives. China's MEE enforcement of GB standards for electronic product pollution control creates compliance gatekeeping for imported flame retardant formulations. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where formulation registrations will confer market access versus trigger portfolio obsolescence.
Market Dynamics
REACH restrictions on hexabromocyclododecane are forcing compounders toward polymeric alternatives, while East Asian electronics manufacturers scale brominated epoxy procurement for high-layer-count PCBs. This regulatory-supply tension defines current competitive positioning.
Growth Catalysts
- Construction fire safety mandates:Building codes in China and India now require enhanced flame retardancy in insulation foams and cables, pulling volume toward brominated polystyrene grades.
- 5G infrastructure buildout:Base station manufacturers in South Korea and Taiwan specify low-loss brominated epoxy laminates for millimeter-wave antenna substrates.
- Electric vehicle battery enclosures:Thermal runaway protection standards are accelerating specification of brominated engineering thermoplastics in pack housings and module separators.
Market Restraints
- Bromine feedstock concentration:Dead Sea and Arkansas extraction operations control over 70% of elemental bromine supply, creating vulnerability to geopolitical or climatic disruption.
- ECHA persistent organic pollutant assessments:Ongoing evaluations of tetrabromobisphenol A under REACH threaten registration continuity for legacy formulations in European electronics.
- Phosphorus-nitrogen synergists:Intumescent systems are capturing share in polyolefin wire and cable applications where halogen-free labeling commands procurement preference.
Strategic Opportunities
- Polymeric brominated alternatives:Reformulation toward high-molecular-weight oligomers addresses bioaccumulation concerns while preserving fire performance in European construction textiles.
- India electronics manufacturing:Production-linked incentive schemes for semiconductor and PCB fabrication are creating virgin demand for brominated epoxy intermediates in Gujarat and Tamil Nadu clusters.
- Recycling-compatible flame retardants:Design-for-recycling protocols under EU Ecodesign for Sustainable Products Regulation favor brominated systems that survive mechanical reprocessing without degradation.
Industry Challenges
- Reformulation timeline compression:Sunset dates for restricted substances under REACH Annex XVII leave insufficient validation cycles for alternative qualification in automotive qualification protocols.
- Cross-jurisdictional registration burden:Divergent data requirements between EPA TSCA, China MEE new chemical notification, and ECHA REACH create redundant toxicology expenditure for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brominated Flame Retardants Market |
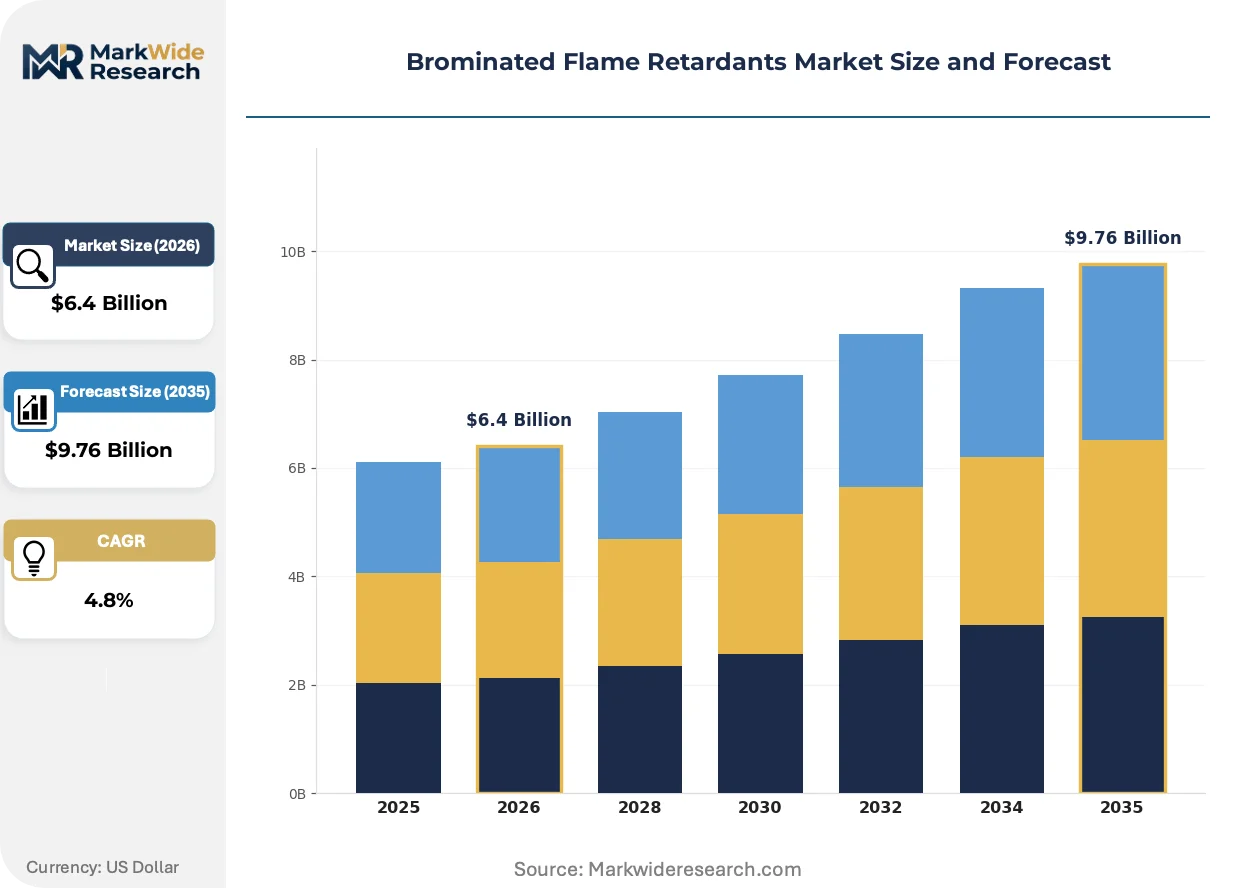
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tetrabromobisphenol A, Hexabromocyclododecane, Brominated Polystyrene, Brominated Epoxy End User: Automotive, Electronics, Construction, Textiles Application: Building Materials, Electrical Equipment, Furnishings, Automotive Parts Formulation: Resin-Based, Thermoplastic, Thermosetting, Coating |
| Companies Covered | Chemtura Corporation, Italmatch Chemicals, Albemarle Corporation, ICL Industrial Products, Velsicol Chemical, ICL, ADEKA Corporation, Jiangsu Yoke Technology, LANXESS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brominated Flame Retardants Market Emerging Trajectories
Reactive brominated intermediates are displacing additive systems in applications where polymer compatibility and permanence determine specification. Three convergent developments are reshaping formulation priorities.
Polymeric brominated flame retardants are absorbing regulatory pressure previously directed at small-molecule alternatives. These high-molecular-weight structures resist migration and leaching while maintaining radical-scavenging efficiency in the gas phase. European textile and construction compounders are accelerating adoption ahead of anticipated ECHA restrictions on lower-molecular-weight analogues. The technology is absorbing compliance investment that would otherwise flow toward non-halogen alternatives.
EPA scrutiny under the Toxic Substances Control Act is intensifying for persistent bioaccumulative toxicants, with brominated diphenyl ethers facing renewed evaluation timelines. Industrial consequence includes accelerated portfolio rationalization among US-based formulators seeking to preempt registration denial. Wire and cable manufacturers serving the North American building sector are responding by dual-qualifying polymeric brominated and phosphorus-based systems to maintain supply continuity.
Compounders in China's Guangdong province are consolidating procurement through direct bromine derivative offtake agreements with Dead Sea and Arkansas producers. This disintermediation bypasses traditional distributor networks that previously managed inventory and technical service. The pattern is most visible among PCB laminate mills serving high-volume consumer electronics, where feedstock cost position determines contract competitiveness.
Brominated Flame Retardants Market Segmentation
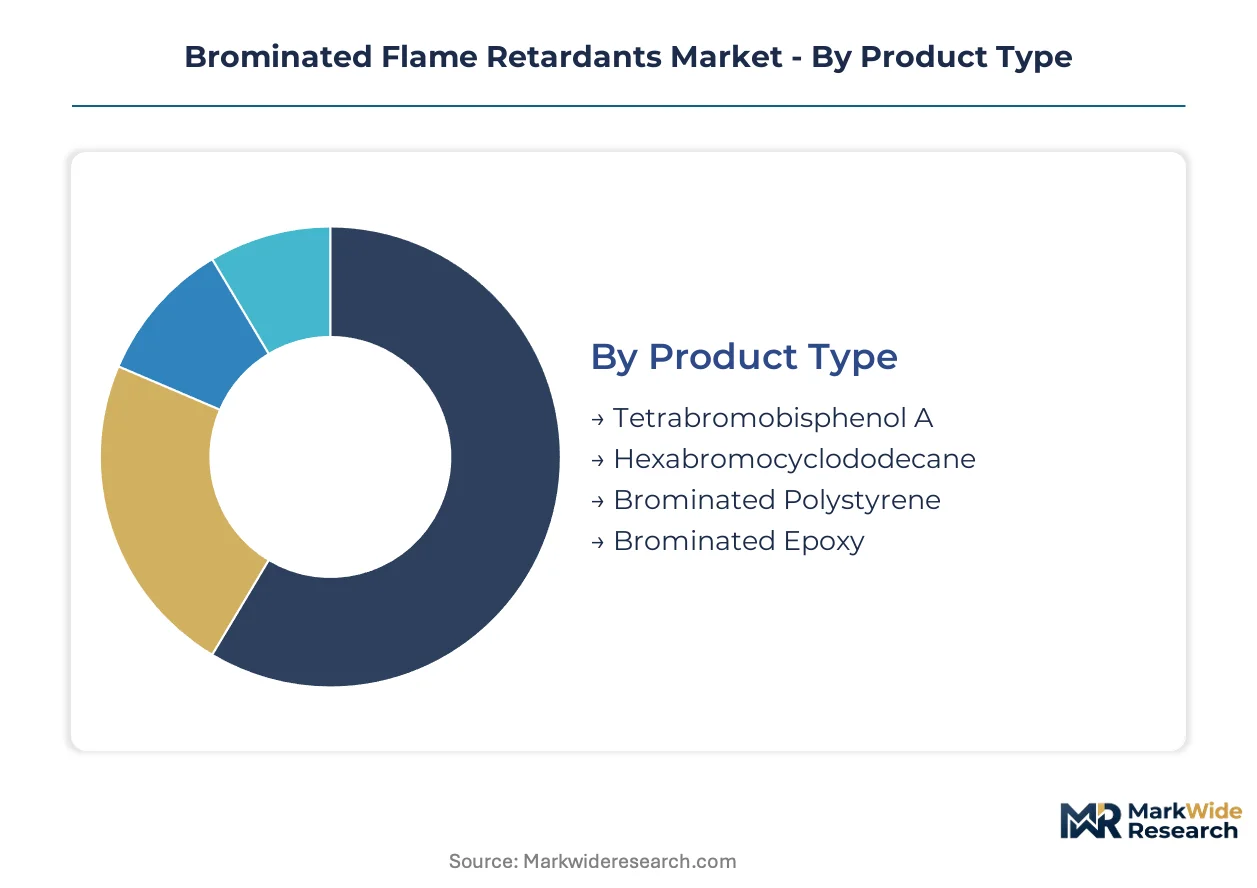
Product differentiation in brominated flame retardants hinges on molecular architecture and integration method. Reactive intermediates command premium positioning in epoxy laminates, while additive systems compete on formulation flexibility and compounder convenience.
Product Type:
Capital intensity varies sharply across molecular classes, with polymeric grades requiring continuous polymerization infrastructure and legacy small-molecule products leveraging depreciated batch assets.
- Tetrabromobisphenol A:Reactive intermediate containing four bromine atoms bonded to a bisphenol A backbone, functioning as a co-monomer in epoxy resin polymerization. Guangdong province PCB laminate mills consume substantial volumes for high-layer-count substrates where dielectric performance and resin compatibility constrain substitution. REACH Annex XVII evaluations threaten registration continuity in European electronics applications.
- Brominated Polystyrene:High-molecular-weight oligomer with bromine content typically exceeding 60% by weight, engineered for thermal stability above 300°C in engineered thermoplastics. Automotive battery pack manufacturers in South Korea specify these grades for thermal runaway protection in module separators and housings, responding to stringent cell-to-cell isolation standards.
- Hexabromocyclododecane:Cycloaliphatic additive with high bromine density, now restricted under REACH and subject to sunset timelines in European construction and textile uses.
- Brominated Epoxy:Pre-reacted oligomeric systems combining flame retardancy with resin matrix integration, favored in millimeter-wave 5G antenna substrates for low-loss dielectric properties.
Tetrabromobisphenol A absorbs the bulk of installed capacity; brominated polystyrene is expanding most quickly.
End User:
Customer concentration patterns reflect divergent procurement power, with electronics OEMs consolidating through direct bromine derivative offtake while construction compounders fragment across regional distributors.
- Electronics:PCB fabricators and laminate mills specifying reactive intermediates for printed circuit board substrates. Taiwan and South Korea base station manufacturers drive demand for low-loss brominated epoxy grades in 5G infrastructure.
- Automotive:Battery enclosure and wiring harness suppliers responding to thermal runaway protection mandates. OEM qualification protocols in Germany and Japan impose extended validation cycles that favor incumbent formulations.
- Construction:Insulation foam and cable compounders in China and India pulling volume toward brominated polystyrene as building codes tighten fire safety requirements.
- Textiles:European upholstery and drapery manufacturers reformulating toward polymeric alternatives ahead of anticipated ECHA restrictions on lower-molecular-weight analogues.
Electronics commands the largest share of formulation R&D investment; automotive is climbing the fastest on electrification tailwinds.
Application:
Performance thresholds and certification requirements create distinct margin tiers across use cases, with electrical equipment demanding the most stringent thermal and dielectric specifications.
- Electrical Equipment:Circuit boards, connectors, and enclosures where UL 94 V-0 ratings and IEC 61215 thermal cycling tests govern specification. High-layer-count PCBs for server and telecommunications infrastructure concentrate demand in China's Pearl River Delta.
- Building Materials:Insulation foams, roofing membranes, and cable sheathing subject to national fire codes. India's Bureau of Indian Standards has tightened flame spread indices for commercial construction, redirecting specification toward brominated polystyrene grades.
- Automotive Parts:Battery pack housings, module separators, and high-voltage connectors requiring thermal runaway containment. South Korean cell manufacturers specify brominated engineering thermoplastics meeting 10-minute propagation resistance standards.
- Furnishings:Upholstery foams and textiles where smolder resistance and open-flame ignition standards apply. California's TB 117-2013 technical bulletin shapes North American procurement patterns despite state-level variation.
Electrical equipment absorbs the majority of technical service resources; automotive parts are gaining share fastest on EV penetration.
Formulation:
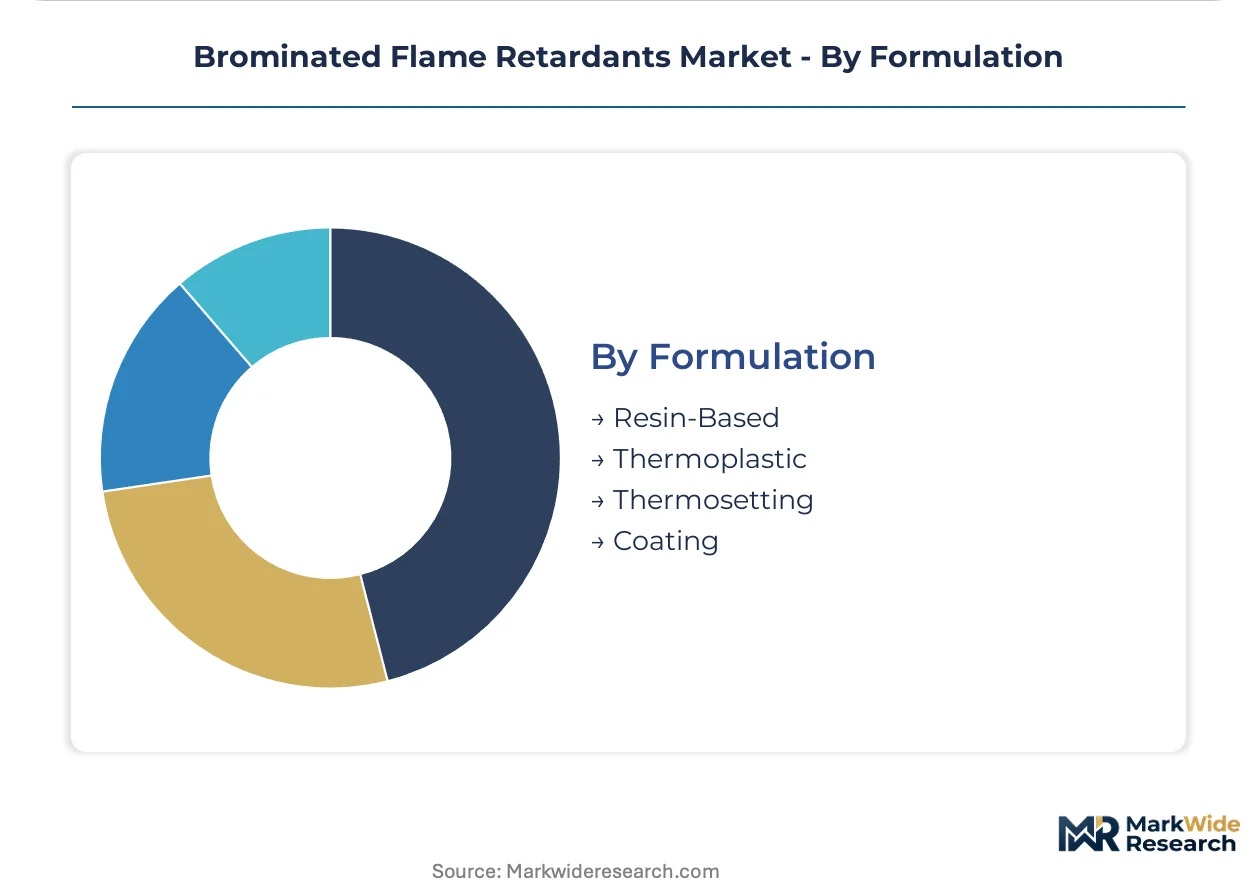
Processing method determines capital deployment and technical barrier height, with thermosetting systems requiring curing infrastructure and coating formulations demanding solvent handling compliance.
- Thermosetting:Cross-linked epoxy and phenolic systems where brominated intermediates participate in polymerization. PCB laminate mills in China's Guangdong province operate continuous treaters optimized for tetrabromobisphenol A integration.
- Thermoplastic:Compounding into polyolefins, styrenics, and engineering resins via extrusion. German automotive suppliers favor brominated polystyrene masterbatches for battery housing injection molding.
- Resin-Based:Liquid and solid epoxy formulations for potting, encapsulation, and adhesive applications. Taiwan electronics assemblers specify these for semiconductor packaging thermal management.
- Coating:Solvent-borne and water-dispersed intumescent and non-intumescent systems. European construction applicators face VOC constraints under EU Solvent Emissions Directive.
Thermosetting formulations dominate installed reactor capacity; thermoplastic compounding is expanding most quickly on automotive electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dead Sea bromine extraction in Israel and Arkansas brine operations in the United States anchor elemental feedstock supply for derivative manufacturing clusters across three continents.
China
Guangdong province PCB laminate mills consume substantial tetrabromobisphenol A volumes for high-layer-count substrates serving consumer electronics OEMs. MEE enforcement of GB standards for electronic product pollution control creates compliance gatekeeping for imported formulations. Shenzhen and Dongguan fabrication clusters are consolidating procurement through direct bromine derivative offtake agreements with Middle Eastern and North American producers.
United States
Arkansas bromine extraction operations sustain captive feedstock for downstream flame retardant output serving domestic wire and cable compounders. EPA scrutiny under the Toxic Substances Control Act shapes product registration pathways and sunset timelines for legacy formulations. Gulf Coast chemical manufacturing corridors are absorbing reformulation investment as compounders seek to preempt registration denial for persistent bioaccumulative chemistries.
Germany
Automotive battery enclosure suppliers in Baden-Württemberg specify brominated engineering thermoplastics for thermal runaway protection in electric vehicle pack housings. ECHA restrictions on hexabromocyclododecane under REACH Annex XVII have forced construction and textile compounders toward polymeric alternatives. Bavarian automotive OEM qualification protocols impose extended validation cycles that favor incumbent brominated polystyrene formulations.
South Korea
Base station manufacturers specify low-loss brominated epoxy laminates for millimeter-wave 5G antenna substrates. MFDS chemical safety assessments align with broader OECD testing protocols while maintaining national notification requirements for new substance introductions. Seoul-Incheon electronics corridors are scaling procurement of brominated epoxy formulations as telecommunications infrastructure buildout accelerates.
India
Production-linked incentive schemes for semiconductor and PCB fabrication are creating virgin demand for brominated epoxy intermediates in Gujarat and Tamil Nadu clusters. BIS has tightened flame spread indices for commercial construction, redirecting insulation foam and cable specification toward brominated polystyrene grades. Ahmedabad and Chennai manufacturing zones are attracting compounder investment to serve domestic electronics assembly growth.
Brominated Flame Retardants Market Vendor Landscape
Capacity expansion dominates the current landscape as bromine extractors integrate downstream into derivative manufacturing. The competitive structure concentrates around three player archetypes: integrated bromine-to-derivative producers controlling captive feedstock, regional compounders optimizing cost positions for specific end-use segments, and specialty chemical houses developing polymeric alternatives for regulatory-constrained applications. M&A activity and backward integration into brine extraction assets represent the dominant competitive moves as participants defend margin position against feedstock volatility.
Within the integrated producer tier, Albemarle Corporation and ICL Industrial Products exemplify the captive-feedstock archetype through their control of Arkansas and Dead Sea bromine extraction assets respectively. Jiangsu Yoke Technology occupies a position among Asia-Pacific compounders competing on cost-optimized derivative output for domestic electronics manufacturing clusters. These three anchors span the geographic and structural spectrum of competitive positioning in brominated flame retardant supply.
| Leading Market Players |
|---|
| Chemtura Corporation |
| Italmatch Chemicals |
| Albemarle Corporation |
| ICL Industrial Products |
| Velsicol Chemical |
| ICL |
| ADEKA Corporation |
| Jiangsu Yoke Technology |
| LANXESS |
| Others |
Supply Flow & Price Mechanics
Polymeric-versus-small-molecule grade bifurcation separates premium thermal stability formulations from commodity tetrabromobisphenol A, with the former commanding captive supply arrangements and the latter trading through spot markets vulnerable to Dead Sea brine output fluctuations.
Pricing Analysis
Technical service bundling separates integrated producers from distributors, with Albemarle and ICL embedding formulation support into long-term offtake contracts while regional traders compete on unbundled spot pricing. Three-tier pricing structure across polymeric specialty, reactive intermediate, and additive commodity levels tracks bromine content and thermal performance thresholds. Cost compression in standard-grade tetrabromobisphenol A intensifies as Guangdong laminate mills consolidate procurement through direct Middle Eastern supply agreements. Electronics OEMs exhibit lowest price sensitivity given qualification lock-in, while construction compounders in India and China drive aggressive volume negotiation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Taiwan and South Korea base station manufacturers, bypassing traditional distributor networks. Elemental bromine extraction concentrates in Israel and the United States, with downstream derivative manufacturing clustered in China, Germany, and South Korea. Feedstock supply draws from Dead Sea solar evaporation operations and Arkansas brine fields, with finished formulations resting on epoxy resin and styrenic polymer intermediates. Single-source vulnerability concentrates in elemental bromine, where climatic disruption or geopolitical friction could constrain global derivative output.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around feedstock control, with REACH sunset timelines and ECHA persistent organic pollutant assessments forcing subscale compounders toward exit or acquisition.
For Market Incumbents: To counter phosphorus-nitrogen synergist displacement in wire and cable applications, secure captive bromine supply through upstream brine asset acquisition or joint venture, while accelerating polymeric alternative R&D ahead of anticipated tetrabromobisphenol A registration restrictions. For New Entrants and Emerging Players: Enter via India electronics manufacturing clusters, where PLI schemes for semiconductor and PCB fabrication create virgin demand absent entrenched supplier relationships. Target brominated epoxy intermediate supply to Gujarat and Tamil Nadu laminate mills, leveraging technical service partnerships with domestic compounders to bypass qualification barriers. For Investors and Strategic Acquirers: Re-rating potential sits with integrated bromine-to-derivative producers given regulatory compression on small-molecule alternatives and feedstock scarcity premiums. Monitor ECHA persistent organic pollutant assessment timelines as inflection indicator for portfolio rationalization urgency among legacy formulation holders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Assets | Captive bromine supply insulates margin from Dead Sea output volatility and trade friction. |
| Polymeric Alternative Development | High-molecular-weight oligomers preempt REACH registration denial for legacy small-molecule formulations. |
| Long-term Supply Agreement | Direct offtake contracts with Guangdong PCB laminate mills lock volume against distributor competition. |
| Joint Venture in India | Local production presence captures PLI-linked electronics manufacturing growth in Gujarat and Tamil Nadu. |
| Green Manufacturing Transition | Recycling-compatible flame retardant design aligns with EU Ecodesign for Sustainable Products Regulation requirements. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with bromine extraction operators, flame retardant plant managers, PCB laminate procurement leads, and automotive Tier 1 supplier technical directors. ECHA restriction notifications, EPA TSCA dockets, China MEE GB standard enforcement records, and SEC 10-K disclosures provided public-source validation. Bottom-up volume modeling triangulated against top-down market sizing across product type, end-use industry, and regional production hub dimensions.
Segment-level granularity modeled reactive intermediates, additive systems, and polymeric grades separately, with end-use splits across electronics, automotive, construction, and textile applications. CAGRs derived from regression analysis of historical bromine derivative trade flows and forward projection of PCB laminate output, EV battery enclosure demand, and 5G infrastructure deployment. Pricing trajectories incorporated bromine feedstock cost curves and reformulation investment cycles.
Revisions become necessary when ECHA persistent organic pollutant assessments accelerate, Dead Sea extraction operations face climatic disruption, or phosphorus-nitrogen synergist penetration exceeds baseline substitution assumptions. Periodic stress-testing of base assumptions against regulatory announcement timelines and feedstock supply continuity scenarios is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Photoinitiators Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Cellulose Esters and Ethers Market
Specialty Chemicals
Coconut Derived Emollients Market
Specialty Chemicals
Cellulose Ether Market
Specialty Chemicals
Australia and New Zealand Aerosol Market
Specialty Chemicals
Crystal Hard Wax Market
Specialty Chemicals
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market
Specialty Chemicals
Ethyl Ascorbic Acid Market
Specialty Chemicals
Europe Non-Phthalate Plasticizers Market
Specialty Chemicals
Dehazer Market
Specialty Chemicals
Cholesteryl Isostearate Market
Specialty Chemicals
Immunochemistry Products Market
Specialty Chemicals
Ethyl Polysilicate Market
Specialty Chemicals
Ytterbium Fluoride Market
Specialty Chemicals
North America Aerosol Cans Market