
 Preparative and Process Chromatography Market | 2026-2036
Preparative and Process Chromatography Market Size, Share, and Industry Trends Forecast 2026-2036
Preparative and Process Chromatography Market Intelligence
Good Manufacturing Practice (GMP) compliance for biopharmaceutical production is redrawing the competitive landscape for chromatography system suppliers. This requirement favors established vendors with validated systems and extensive documentation support. Danaher Corporation leverages its comprehensive bioprocess portfolio to serve large-scale manufacturing clients. Sartorius differentiates through its focus on single-use technologies and advanced filtration solutions, while Merck KGaA sustains a strong position via its integrated life science offerings.
Preparative and process chromatography is a purification technique used to isolate and collect target molecules from complex mixtures at a large scale, handling sample loads from grams to kilograms. Its principal industrial function is the high-purity isolation of active pharmaceutical ingredients and biologics. The biopharmaceutical processing application commands the largest share of the market, driving significant investment in liquid chromatography systems and columns. Within technology segments, affinity chromatography provides high-margin opportunities due to its specificity in purifying complex proteins.
Regulatory bodies including the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) set strict purity standards for therapeutic products. These regulations compel manufacturers to adopt validated and highly efficient purification methods. The NMPA in China is also aligning its bioprocessing standards, influencing equipment choices in that market. Stakeholders must now evaluate the long-term cost-benefit of transitioning from traditional batch systems to integrated continuous chromatography platforms.
Market Dynamics
The imperative for biopharmaceutical manufacturers to accelerate drug development timelines while adhering to stringent GMP standards is the central force shaping the preparative and process chromatography market. This pressure drives the transition from conventional batch processing to more efficient continuous manufacturing models.
Growth Catalysts
- Continuous Bioprocessing:The adoption of continuous and integrated bioprocessing platforms enhances productivity and reduces facility footprints, creating sustained demand for automated chromatography systems and compatible consumables in biopharma.
- Biologic Pipeline Expansion:A growing clinical pipeline of complex biologics, particularly monoclonal antibodies and cell therapies, requires high-purity purification, directly fueling investment in advanced chromatography columns and resins.
- Regulatory Purity Mandates:Strict purity and safety standards set by the FDA, EMA, and China's NMPA compel drug manufacturers to utilize validated, high-performance chromatography methods for commercial production.
Market Restraints
- High Capital Investment:The significant upfront cost of acquiring advanced continuous chromatography systems and the associated infrastructure presents a substantial barrier to entry for smaller companies and academic research labs.
- Process Development Complexity:Developing, optimizing, and validating robust chromatography processes for new biologic entities is a time-consuming and technically challenging endeavor requiring specialized expertise.
- Specialized Resin Costs:High-performance resins, especially for affinity chromatography, are a major operational expense and are often sourced from a concentrated group of suppliers, creating price sensitivity.
Strategic Opportunities
- Emerging Therapeutic Modalities:The rise of mRNA-based vaccines and viral vector-based gene therapies creates new purification challenges and opens opportunities for novel chromatography media and system designs.
- Biopharma Hub Expansion:Increasing investment in biomanufacturing capacity in South Korea and India, supported by regulators like the MFDS and CDSCO, represents a key geographic growth vector.
- Multi-modal Chromatography:Development of resins that combine multiple separation modes (e.g., ion exchange and hydrophobic interaction) into a single step offers a path to streamline purification workflows.
Industry Challenges
- Skilled Workforce Scarcity:A shortage of process engineers and scientists with hands-on experience in modern chromatography techniques and continuous manufacturing systems hinders technology adoption and operational efficiency.
- System Integration Hurdles:Integrating new, automated chromatography skids with existing plant-wide control systems and data historians often proves complex and costly for established manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preparative and Process Chromatography Market |
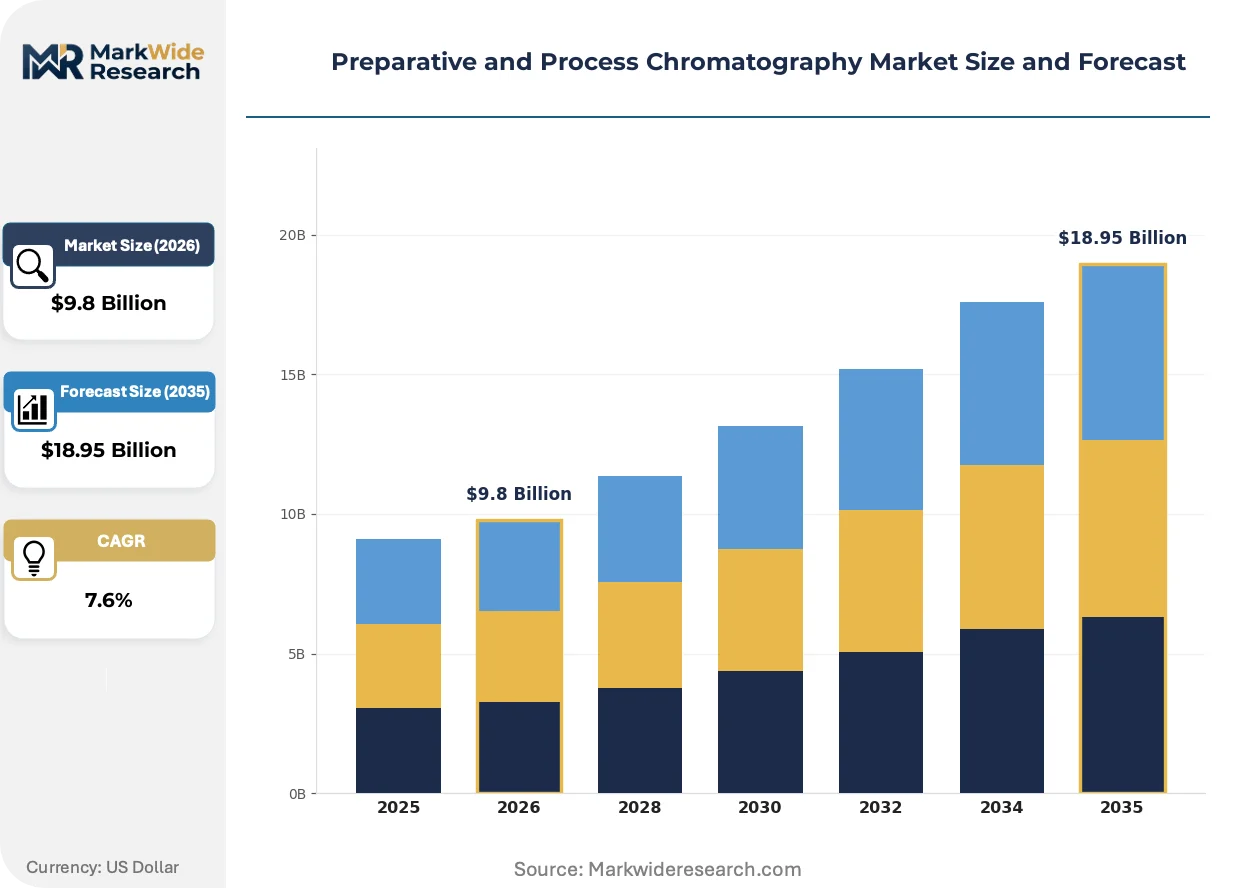
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $18.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Chromatography Systems, Chromatography Columns, Detectors, Fraction Collectors, Pumps Technology: High Performance Liquid Chromatography, Flash Chromatography, Ion Exchange, Size Exclusion, Affinity, Adsorption Chromatography Application: Pharmaceutical Compound Purification, Biopharmaceutical Processing, Chemical Synthesis, Food Additive Refinement, Environmental Sample Preparation End User: Biotech Firms, Contract Manufacturing Organizations, Academic Research Institutes, Agrochemical Developers |
| Companies Covered | Danaher Corporation, Thermo Fisher Scientific, Merck KGaA, Agilent Technologies, Waters Corporation, Bio-Rad Laboratories, GE Healthcare, Sartorius, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preparative and Process Chromatography Market Strategic Shifts & Innovations
Process intensification and the integration of advanced analytics are reshaping equipment design and operational strategy. The market is moving toward more automated, flexible, and data-centric purification platforms to meet the demands of modern biomanufacturing for speed and quality.
Single-use chromatography systems provide pre-sterilized, disposable fluid paths that eliminate cleaning validation and reduce cross-contamination risk. Biopharmaceutical developers, particularly for clinical trial materials and personalized medicines, are rapidly adopting these solutions. This technology is displacing traditional stainless-steel equipment in multi-product facilities where flexibility and rapid changeover are critical operational advantages.
Regulatory guidance, such as the ICH Q13 framework for continuous manufacturing, actively encourages the adoption of advanced production methods. This policy shift incentivizes manufacturers to invest in Process Analytical Technology (PAT) to enable real-time monitoring and control of purification processes. Large-scale biologics producers are most affected, now building the extensive data packages required by the FDA and EMA to validate these innovative platforms.
A shift toward demanding integrated, end-to-end purification platforms from a single supplier is altering procurement patterns. This challenges the traditional model of sourcing columns, resins, and hardware from multiple specialized vendors, favoring suppliers with a complete portfolio. This trend is most visible among major biopharmaceutical firms in the United States and Switzerland seeking to de-risk their supply chain and simplify technology transfer.
Preparative and Process Chromatography Market Segmentation
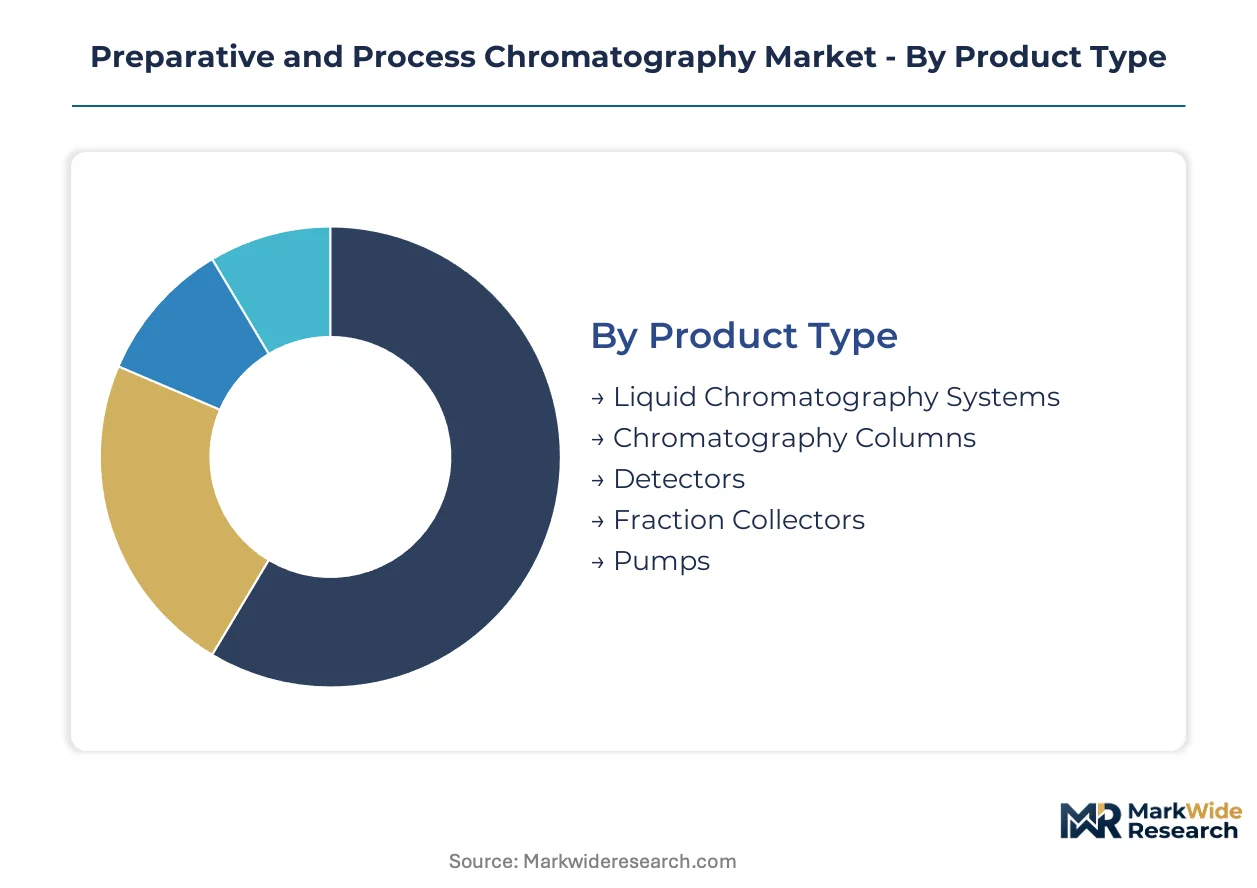
Understanding the distinct components within the preparative and process chromatography market is essential for strategic planning. This market's segmentation highlights the varied technological approaches and end-user requirements driving purification advancements in biopharmaceutical production.
Product Type:
Regulatory bodies like the FDA and EMA heavily influence the selection of product types, demanding validated systems and consumables for therapeutic manufacturing.
- Liquid Chromatography Systems:These integrated instruments perform the physical separation of compounds using a liquid mobile phase and a stationary phase. Biopharmaceutical manufacturers in the United States increasingly invest in automated systems to enhance throughput and ensure GMP compliance for large-scale biologic production.
- Chromatography Columns:These are critical components containing the stationary phase, directly impacting separation efficiency and resolution. Demand for pre-packed, validated columns is high among biopharma companies in Switzerland, seeking to reduce process development time and improve batch consistency.
- Detectors:These devices monitor the eluent from the column, identifying and quantifying separated components. Pharmaceutical research labs utilize advanced detectors for real-time process monitoring and quality control.
- Fraction Collectors:These automated units collect separated components into discrete fractions based on detector signals or time. Biotech firms employ them for high-purity isolation of active pharmaceutical ingredients.
- Pumps:These components control the flow rate and pressure of the mobile phase through the chromatography system. Continuous manufacturing platforms rely on robust and precise pumps for stable operation.
Liquid Chromatography Systems handles the majority of throughput; Chromatography Columns is the fastest mover on share.
Technology:
Application-driven requirements dictate the choice of chromatography technology, with specific separation needs influencing adoption patterns.
- High Performance Liquid Chromatography:This widely adopted technique offers high resolution and sensitivity for separating complex mixtures. Pharmaceutical companies in Europe utilize HPLC for quality control and purification of small molecule drugs.
- Flash Chromatography:This rapid, low-pressure technique is primarily used for quick purification of synthetic compounds. Contract research organizations frequently deploy flash chromatography for early-stage drug discovery and chemical synthesis.
- Ion Exchange:This method separates molecules based on their net charge, commonly used for protein purification. Biologic developers employ ion exchange for capturing and polishing monoclonal antibodies.
- Size Exclusion:This technique separates molecules based on their hydrodynamic volume. Academic research institutes use size exclusion chromatography for protein characterization and buffer exchange.
- Affinity:This highly specific technique uses biological interactions for purification, offering exceptional purity for target molecules. Biopharmaceutical firms leverage affinity chromatography for purifying complex proteins like recombinant enzymes and gene therapy vectors.
- Adsorption Chromatography:This method separates compounds based on their differential adsorption to a stationary phase. Chemical synthesis labs apply adsorption chromatography for purifying organic compounds.
High Performance Liquid Chromatography technologies maintain the largest installed base; Affinity methods are gaining share due to their specificity.
Application:
End-user demand shapes the application landscape, with distinct industry sectors driving specific purification needs.
- Pharmaceutical Compound Purification:This involves isolating active pharmaceutical ingredients (APIs) and intermediates from reaction mixtures. Drug manufacturers in India use preparative chromatography to ensure the purity of small molecule APIs.
- Biopharmaceutical Processing:This application focuses on purifying biologics such as monoclonal antibodies, vaccines, and cell therapies. Biopharmaceutical firms in South Korea are heavily investing in chromatography for large-scale therapeutic protein purification.
- Chemical Synthesis:This segment involves purifying synthesized chemical compounds for various industrial uses. Specialty chemical companies utilize chromatography to achieve high purity for their products.
- Food Additive Refinement:This application purifies and concentrates food additives and natural extracts. Food and beverage manufacturers employ chromatography to enhance product quality and safety.
- Environmental Sample Preparation:This involves isolating target analytes from complex environmental matrices for analysis. Environmental testing laboratories use chromatography for contaminant detection.
Biopharmaceutical Processing generates the highest revenue; Pharmaceutical Compound Purification exhibits the fastest expansion.
End User:
Market penetration within different end-user segments reveals varying levels of adoption and investment in chromatography solutions.
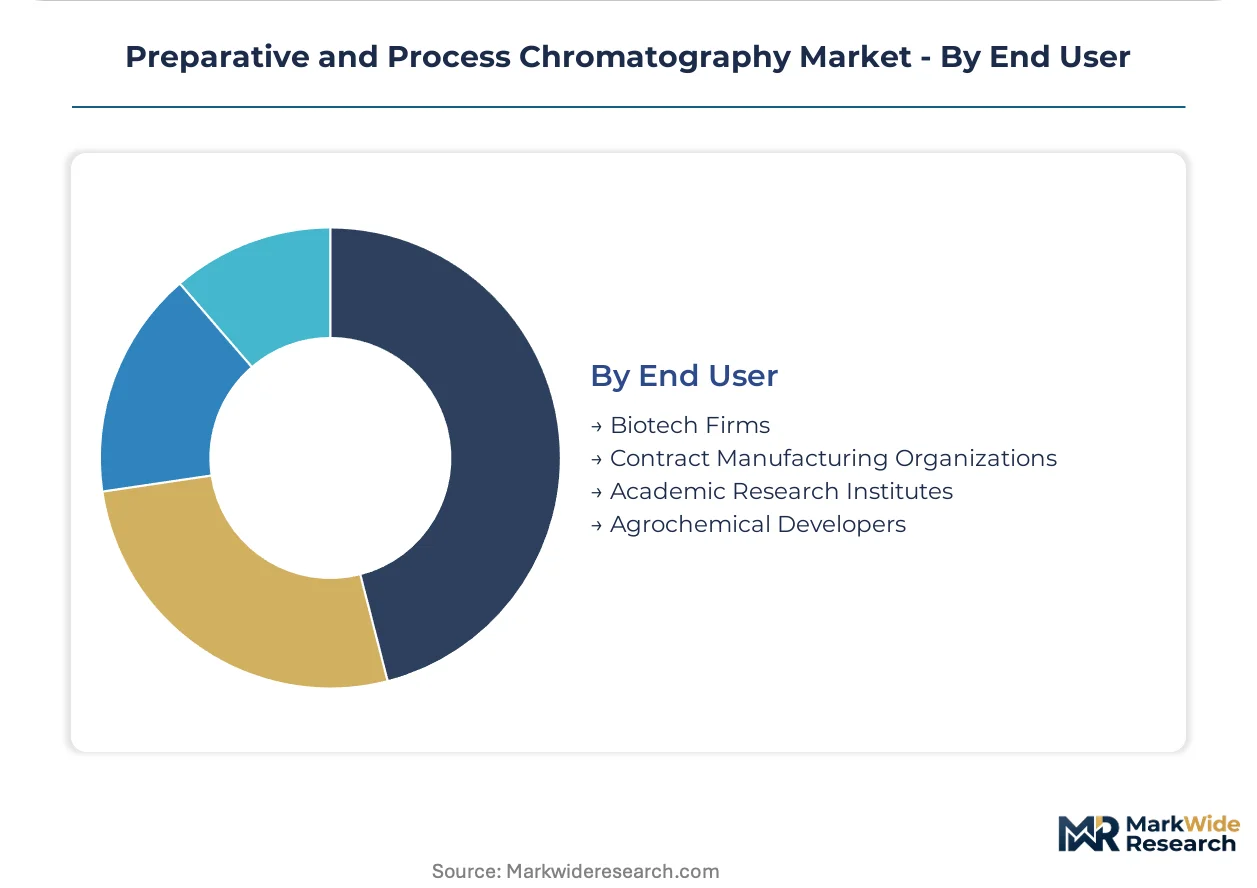
- Biotech Firms:These companies specialize in developing and manufacturing biologics and novel therapies. Biotech firms drive demand for advanced chromatography systems to support their innovative product pipelines.
- Contract Manufacturing Organizations:CMOs provide manufacturing services for pharmaceutical and biopharmaceutical companies, often handling diverse product portfolios. CMOs adopt flexible chromatography platforms to serve multiple clients and product types.
- Academic Research Institutes:These institutions conduct fundamental research in biology, chemistry, and medicine. Academic labs use chromatography for analytical and small-scale preparative purification in their studies.
- Agrochemical Developers:These companies develop pesticides, herbicides, and other agricultural chemicals. Agrochemical developers utilize chromatography for purifying active ingredients and ensuring product efficacy.
Biotech Firms represent the primary consumer base; Contract Manufacturing Organizations are rapidly expanding their operational capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global biopharmaceutical supply chain, underwritten by extensive air freight and cold chain logistics networks, facilitates the distribution of advanced therapeutic products requiring high-purity processing. This infrastructure supports the specialized manufacturing demands of the preparative and process chromatography market. Key regions are investing heavily in biomanufacturing capabilities to meet rising global demand.
United States
Demand for advanced chromatography systems stems from a robust biopharmaceutical pipeline and significant R&D investment. The FDA's stringent purity standards compel manufacturers to adopt validated purification methods for new drug submissions. Biopharma clusters in Boston and San Francisco are expanding capacity for large-scale biologic production.
Switzerland
Swiss biopharmaceutical firms prioritize rapid process development and consistent batch quality, driving demand for pre-packed chromatography columns. Swissmedic regulations emphasize product quality and manufacturing efficiency for therapeutic proteins. The Basel life sciences hub attracts substantial investment in specialized bioprocessing technologies.
South Korea
Investment in biomanufacturing capacity fuels demand for chromatography solutions, particularly for therapeutic protein purification. The MFDS actively supports the growth of the domestic biopharmaceutical industry through favorable policies. Incheon's Bio-Complex is rapidly expanding its production footprint for biologics.
India
Drug manufacturers in India use preparative chromatography to ensure the purity of small molecule APIs and biologics. The CDSCO's focus on quality standards for pharmaceutical exports influences equipment choices. Hyderabad's Genome Valley continues to attract investment in pharmaceutical and biotechnology manufacturing.
Germany
European pharmaceutical companies utilize high-performance liquid chromatography for quality control and small molecule purification. The EMA's regulatory framework for biopharmaceuticals encourages adoption of efficient purification techniques. The Munich biotech cluster is a center for advanced bioprocessing innovation and development.
Preparative and Process Chromatography Market Key Industry Players
Listed leaders compete with private specialists across the full spectrum of preparative and process chromatography solutions. The market exhibits a tiered structure, with established global suppliers alongside niche technology providers. Archetypes include integrated solution providers, single-use technology innovators, and specialized resin manufacturers. Dominant competitive moves involve strategic partnerships for technology co-development and continuous portfolio diversification to meet evolving biopharma needs.
Within the integrated solution provider archetype, Danaher Corporation exemplifies a comprehensive bioprocess portfolio catering to large-scale manufacturing clients. Sartorius AG, a German-based company, occupies a position focused on single-use technologies and advanced filtration solutions. Merck KGaA, also a German-based life science company, anchors its strong market presence through integrated life science offerings that span research to production. These entities represent distinct approaches to serving the complex needs of the biopharmaceutical industry.
| Leading Market Players |
|---|
| Danaher Corporation |
| Thermo Fisher Scientific |
| Merck KGaA |
| Agilent Technologies |
| Waters Corporation |
| Bio-Rad Laboratories |
| GE Healthcare |
| Sartorius |
| Shimadzu Corporation |
| Others |
Cost & Logistics Intelligence
Single-use chromatography systems, replacing traditional stainless-steel equipment, simultaneously reshape the supply geography for consumables and influence the pricing economics of purification workflows. This shift impacts both component suppliers and end-user biopharmaceutical manufacturers.
Pricing Analysis
Volume-based discount structures characterize the pricing of preparative and process chromatography solutions. Price differentiation stems from the quality grade of resins and the certification level required for GMP biopharmaceutical production. Pricing softness for standard systems reflects increased competition and broader adoption of more cost-effective solutions. Smaller academic research labs and emerging biotech firms exhibit the highest price sensitivity for initial system acquisition.
Supply Chain Analysis
Germany and the United States anchor the production of advanced chromatography systems, columns, and specialized resins. The supply chain draws from highly specialized inputs like porous silica, polymer beads, and affinity ligands. Single-source vulnerability for high-performance affinity resins represents a structural supply chain risk. Distribution runs through a combination of direct sales channels for large biopharmaceutical clients and specialized distributors for smaller laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bioprocessing sector faces a critical shortage of specialized expertise in continuous manufacturing and advanced chromatography techniques. This capability gap limits the rapid adoption of innovative purification platforms across the industry.
For Market Incumbents: Compound market leadership by aggressively investing in integrated continuous chromatography platforms and related process analytical technologies. Form strategic partnerships with biopharmaceutical firms in key hubs like Boston and Switzerland to co-develop validated end-to-end solutions. This defends against emerging niche players and regulatory pressure for faster drug development timelines.
For New Entrants and Emerging Players: Anchor in unmet purification needs for novel therapeutic modalities such as mRNA vaccines and viral vector gene therapies. The most penetrable segment lies within smaller contract development and manufacturing organizations (CDMOs) and specialized biotechs in South Korea and India. A go-to-market angle focused on flexible, modular, and single-use chromatography solutions offers a distinct competitive advantage.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed technology innovators specializing in advanced resins or automated continuous chromatography skids. The long-term viability of this market depends on the sustained expansion of the biologics pipeline and increasing regulatory incentives for process intensification. A signal to watch is the increasing number of regulatory approvals for biopharmaceuticals manufactured using continuous purification processes.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Novel Affinity Resins | Expands purification capabilities for complex biologics like gene therapies and bispecific antibodies. |
| Invest in Integrated Bioprocessing Platforms | Streamlines workflows and enhances productivity for large-scale biopharmaceutical manufacturing operations. |
| Expand Single-Use System Manufacturing Capacity | Addresses the growing demand for flexible, disposable solutions in multi-product facilities. |
| Acquire Advanced Analytics Software Firms | Enables real-time process monitoring and control for continuous chromatography systems. |
| Obtain Regulatory Approvals for Continuous Systems | Validates innovative purification technologies for commercial biopharmaceutical production. |
Research Approach
Desk research of regulatory filings, scientific literature, and industry reports preceded structured interviews with biopharma R&D executives, process development scientists, and procurement managers. This primary data collection was triangulated with secondary sources including FDA guidance documents, EMA submissions, and BIO industry reports. The analysis combined both bottom-up and top-down approaches to ensure comprehensive market sizing.
Variance decomposition analysis informed the forecast framework, assessing the impact of key market drivers and restraints across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional biopharma investment. Compound annual growth rates were derived from historical trends, market drivers, and expert projections, with biopharmaceutical R&D spending and new biologic entity approvals serving as critical forecast inputs.
Material uncertainties—shifts in global biopharma investment and unforeseen regulatory changes—sit outside the modeled envelope of this study. Forecasts reflect assumptions documented through extensive primary and secondary research. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Asia Pacific Aerosol Cans Market
Specialty Chemicals
Bio Polyol and Green Polyol Market
Specialty Chemicals
Germany Starch Derivatives Market
Specialty Chemicals
Distarch Phosphate Market
Specialty Chemicals
Global Blowing Agent Market
Specialty Chemicals
Sodium Adipate Market
Specialty Chemicals
Contouring Products Market
Specialty Chemicals
Specialty Biocides Market
Specialty Chemicals
Metominostrobin Market
Specialty Chemicals
Copovidone Market
Specialty Chemicals
Sulfonated Melamine Formaldehyde Market
Specialty Chemicals
Cellulose Ether Market
Specialty Chemicals
Polyglycerol Sebacate (PGS) Market
Specialty Chemicals
CMIT/MIT Market
Specialty Chemicals
Dimethicone Market
Specialty Chemicals
Xanthene Derivatives Market