
 Europe Hydroxypropyl Methylcellulose (HPMC) Market | 2026-2036
Europe Hydroxypropyl Methylcellulose (HPMC) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hydroxypropyl Methylcellulose (HPMC) Market Intelligence
Specialty chemical distribution across Europe is reconfiguring as regional formulators seek shorter supply chains for cellulose ether derivatives. Dow Chemical Company leverages its integrated propylene oxide feedstock position to stabilize HPMC supply continuity for pharmaceutical clients. Ashland Global Holdings Inc. anchors its competitive stance through specialized pharmaceutical-grade production capabilities at European facilities. SE Tylose GmbH & Co. dominates regional supply for construction-grade HPMC, benefiting from proximity to German building chemical formulators.
Hydroxypropyl methylcellulose is a semi-synthetic polymer produced by alkali treatment of cellulose followed by etherification with propylene oxide and methyl chloride, yielding a water-soluble polymer with thermal gelation properties between 50°C and 70°C. Its primary industrial purpose centers on controlled-release matrix formation in oral pharmaceuticals, cement hydration retardation, and food emulsion stabilization. Pharmaceutical grade HPMC commands the deepest margin pools due to stringent certification requirements and long qualification cycles with drug manufacturers. Industrial grade supply competes primarily on viscosity specifications and lot-to-lot consistency for construction applications. Food grade demand tracks reformulation trends in plant-based meat alternatives across European processing facilities.
EMA guidelines for excipient quality and the EU REACH framework governing chemical substance registration collectively elevate barrier-to-entry for new HPMC suppliers serving pharmaceutical and food sectors. CE marking requirements for construction chemicals indirectly influence industrial grade specification standards across member states. Stakeholders must monitor evolving EFSA purity thresholds and potential F-Gas Regulation extensions that could alter solvent recovery economics in HPMC manufacturing processes.
Market Dynamics
Pharmaceutical formulators in Germany and France are consolidating HPMC procurement around fewer, REACH-certified suppliers to reduce qualification burden and secure excipient traceability for controlled-release oral solid dosage forms.
Growth Catalysts
- Controlled-release matrix adoption:Oral solid dosage manufacturers across Western Europe are expanding HPMC use in hydrophilic matrix systems for extended drug release, driven by patient compliance requirements and EMA guidelines for bioequivalence.
- EU REACH purity escalation:The tightening registration, evaluation, authorization and restriction of chemicals framework is disqualifying uncertified cellulose ether imports, creating protected demand pools for compliant European producers serving food contact and medical applications.
- Construction chemical corridors:German building chemical formulators concentrated around the Rhine-Main and Rhine-Neckar regions are sustaining industrial-grade HPMC demand through cement hydration retardation specifications for warm-weather concreting.
Market Restraints
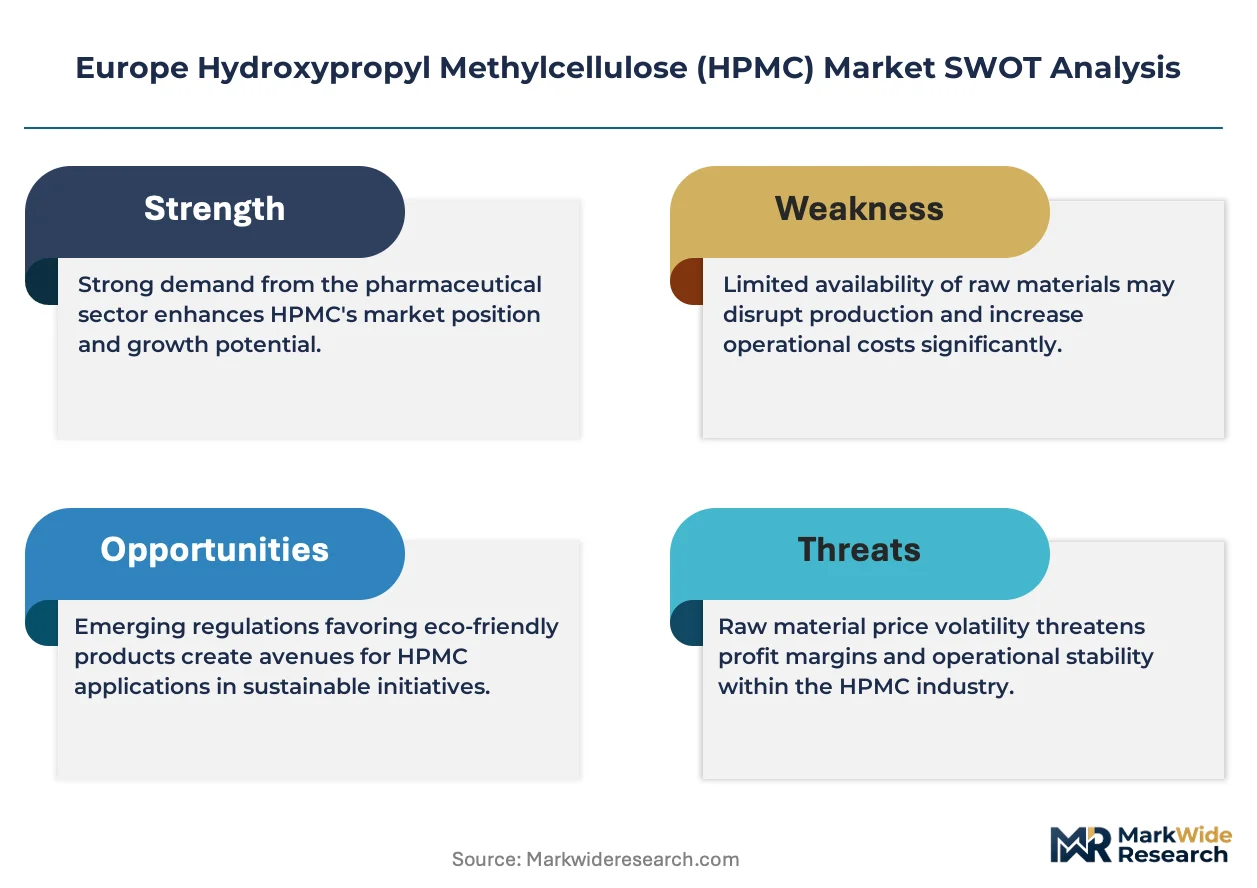
- Propylene oxide feedstock volatility:HPMC manufacturers face margin compression from propylene oxide price swings tied to European crackers and propylene supply disruptions, with limited pass-through to long-term pharmaceutical contracts.
- Specialized reactor capacity concentration:Pharmaceutical-grade HPMC production requires stainless steel etherification vessels with solvent recovery systems concentrated among three integrated chemical groups, creating supply bottleneck risk for qualified volumes.
- Ethyl cellulose substitution:Film-coating applications in oral dosage forms face partial displacement from ethyl cellulose aqueous dispersions where faster dissolution profiles are acceptable, pressuring HPMC coating-grade pricing.
Strategic Opportunities
- Plant-based meat formulation:Spanish and Dutch food processors are reformulating meat analogues with HPMC for fat-mimetic texture and thermal gelation, creating food-grade volume growth outside traditional stabilizer applications.
- F-Gas Regulation solvent recovery:The European Union's fluorinated greenhouse gases framework is incentivizing capital investment in closed-loop methylene chloride recovery systems, lowering operating costs for compliant HPMC producers versus import competitors.
- 3D printed pharmaceutical excipients:Convergence of powder bed fusion and semi-synthetic polymer processing is enabling HPMC-based personalized dosage geometries, with early adoption at university hospital pharmacies in Switzerland and Belgium.
Industry Challenges
- Excipient master file compilation:Pharmaceutical-grade suppliers must assemble drug master file documentation for EMA centralized procedures, requiring 18-24 month timelines and specialized regulatory affairs personnel scarce in mid-scale chemical operations.
- Legacy ERP integration:Construction-grade distributors migrating to lot-level traceability systems face data migration friction with decades-old inventory platforms, delaying real-time viscosity certificate delivery to ready-mix concrete formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hydroxypropyl Methylcellulose (HPMC) Market |
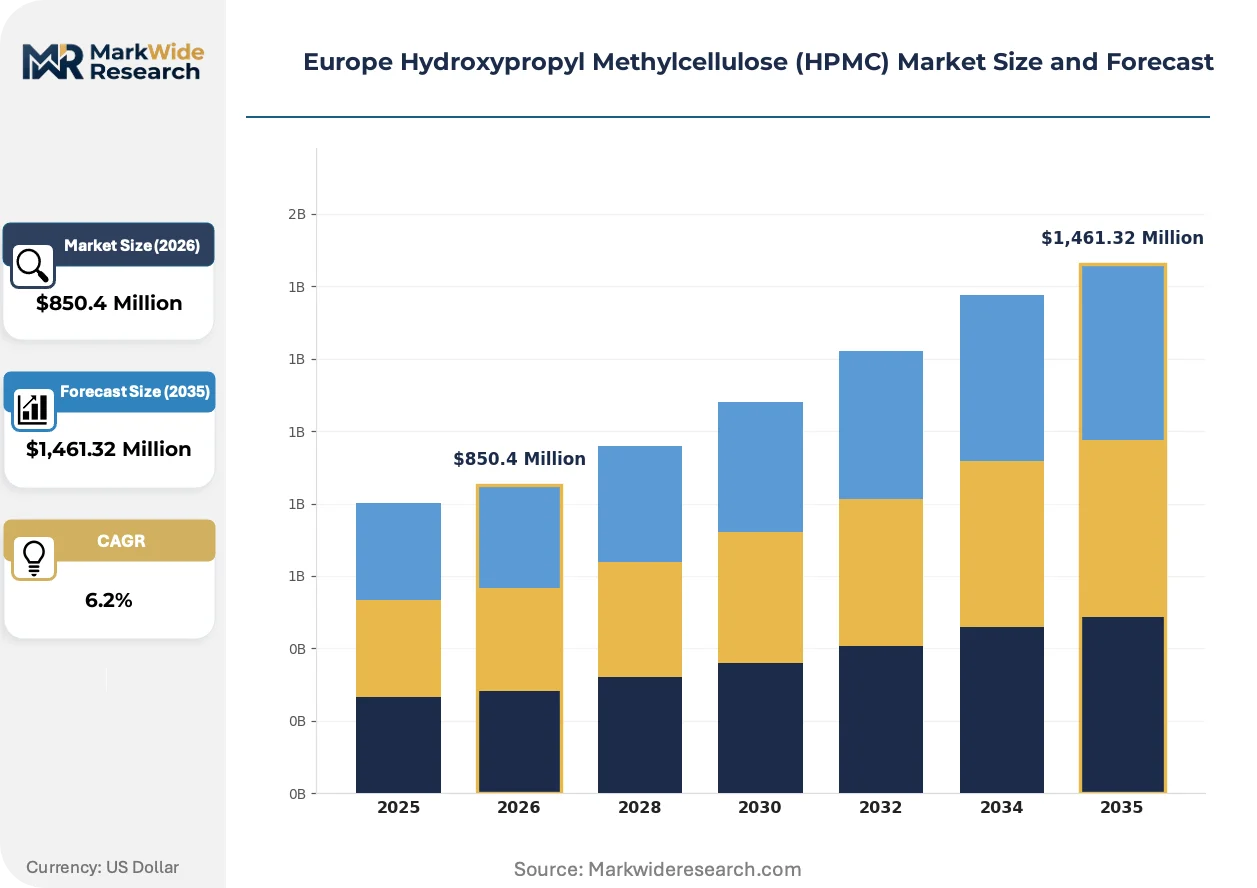
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $1,461.32 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Food Grade, Industrial Grade, Cosmetic Grade Application: Thickening Agent, Binder, Film Former, Dispersant End User: Pharmaceuticals, Food & Beverages, Cosmetics, Construction Form: Powder, Granules, Pellets, Solutions |
| Companies Covered | Dow Chemical Company, Ashland Global Holdings Inc., Shin-Etsu Chemical Co., Ltd., SE Tylose GmbH & Co., Merck KGaA, Avantor, Inc., Celanese Corporation, JRS Pharma, Shandong Head Europe BV, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hydroxypropyl Methylcellulose (HPMC) Market Strategic Shifts & Innovations
Digital formulation platforms and closed-loop manufacturing controls are compressing development cycles for cellulose ether derivatives across pharmaceutical and food applications in Europe.
Continuous manufacturing equipment for HPMC matrix tablet production is virtualizing batch-scale quality testing. Oral dosage manufacturers in Ireland and Denmark are installing direct compression lines with integrated near-infrared spectroscopy for real-time HPMC distribution verification. This technology is virtualizing traditional three-month stability studies into in-process release decisions, cutting working capital requirements for generic drug launches.
The EU F-Gas Regulation phase-down schedule is forcing solvent recovery retrofits across cellulose ether production facilities. Methylene chloride containment systems now require 99.5% recovery efficiency for operating permits in Germany and France. Pharmaceutical-grade producers with existing closed-loop infrastructure are capturing displaced volume from construction-grade competitors facing stranded asset risk.
Formulator procurement teams are consolidating excipient supplier panels to reduce audit burden. Multi-source qualification for HPMC is contracting to dual-source or sole-source arrangements with REACH-registered producers offering combined pharmaceutical-food-construction grade portfolios. This concentration is most visible among Benelux generic drug manufacturers seeking simplified supply base management for oral solid dosage programs.
Europe Hydroxypropyl Methylcellulose (HPMC) Market Segmentation
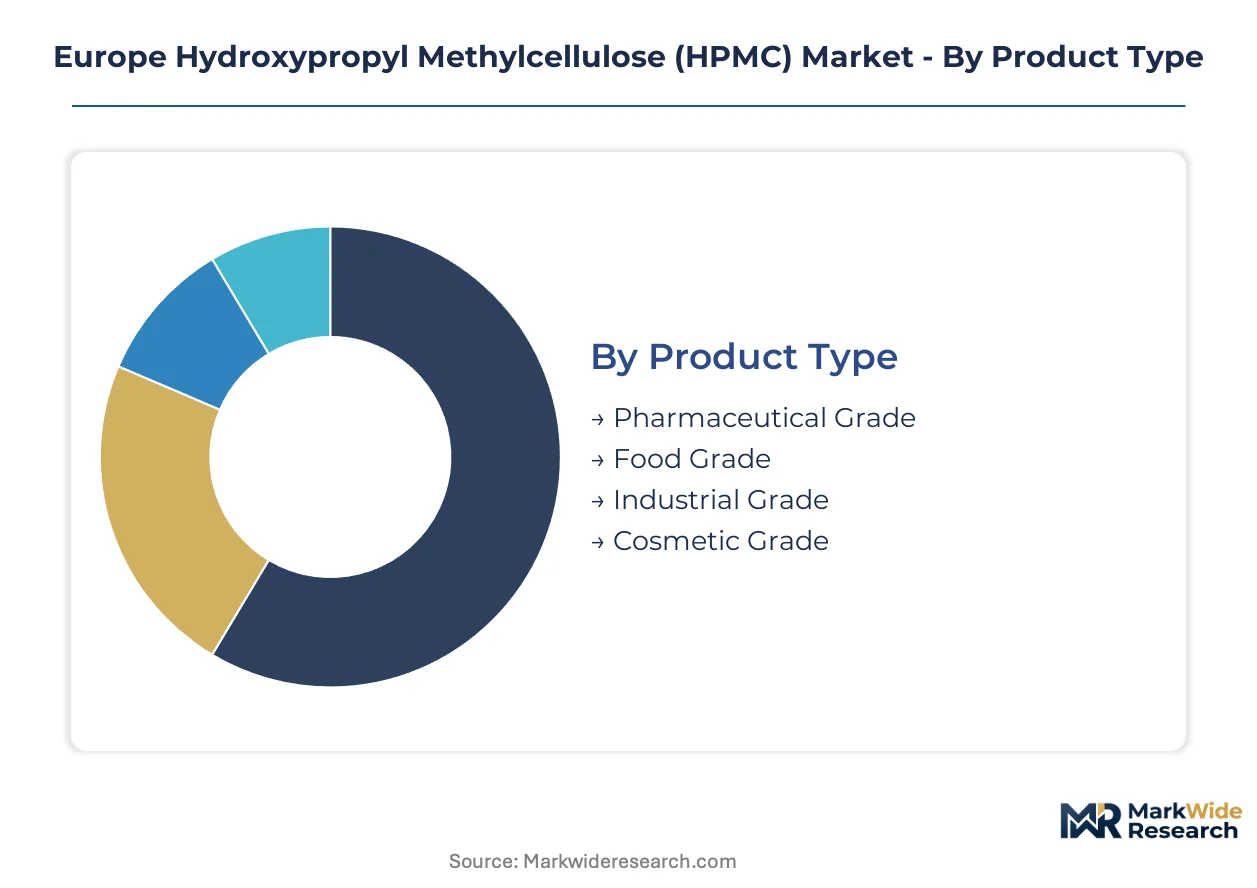
Segmentation in the Europe HPMC market reveals how purity specifications, regulatory pathways, and end-use performance requirements partition value pools across pharmaceutical, food, and industrial applications. Understanding these divides exposes where margin concentration and qualification barriers create defensible competitive positions.
Product Type:
After-sales service intensity varies sharply across grades, with pharmaceutical customers demanding batch-specific certificates of analysis and regulatory query response within 48 hours, while industrial buyers prioritize viscosity consistency over technical support depth.
- Pharmaceutical Grade:Manufactured under GMP conditions with residual solvent limits below 50 ppm and endotoxin controls meeting EMA excipient guidelines. German and Swiss generic drug manufacturers dominate procurement, driven by EMA centralized procedure master file requirements that lock in supplier relationships for 5-7 year drug approval cycles.
- Food Grade:EFSA-compliant purity with methoxyl and hydroxypropyl substitution ratios optimized for thermal gelation in plant-based meat systems. Dutch and Spanish food processors are expanding reformulation programs, constrained by EFSA additive re-evaluation timelines that delay new product launches.
- Industrial Grade:Viscosity-graded for cement hydration control with less stringent residual monomer limits than pharmaceutical specifications.
- Cosmetic Grade:Lower volume specialty with sensory and rheology profiles tailored for personal care emulsions.
Pharmaceutical Grade holds the largest share; momentum sits with Food Grade as plant-based protein processors accelerate HPMC adoption for texture engineering.
Application:
Application selection dictates reactor configuration and solvent recovery capital requirements, with film-forming and binding functions demanding higher substitution uniformity than simple thickening.
- Thickening Agent:Leverages HPMC's pseudoplastic rheology for viscosity build at low shear. Construction-grade demand concentrates in German ready-mix concrete formulators seeking warm-weather workability extension.
- Film Former:Requires precise molecular weight distribution for uniform coating thickness in oral dosage forms. Irish and Danish solid dose manufacturers are installing continuous coating lines with integrated HPMC film verification, displacing batch-scale aqueous coating operations.
- Binder:Granulation aid for wet and dry compression processes with compressibility profiles varying by substitution chemistry.
- Dispersant:Stabilizes particulate suspensions in ceramic and polymer systems with lower purity thresholds than pharmaceutical applications.
Thickening Agent commands volume leadership; Film Former is climbing the fastest as continuous manufacturing adoption accelerates coating-grade specification tightening.
End User:
End-user concentration patterns reflect regional industrial clustering, with pharmaceutical corridors around Frankfurt and Basel generating disproportionate premium-grade demand relative to construction density.
- Pharmaceuticals:Controlled-release matrix and coating applications with EMA excipient master file documentation requirements. REACH-registered suppliers capture procurement consolidation as formulators reduce audit burden through sole-source arrangements.
- Construction:Cement hydration retardation and tile adhesive water retention. German building chemical formulators in Rhine-Main and Rhine-Neckar regions sustain demand through warm-weather concreting specifications.
- Food & Beverages:Emulsion stabilization and fat-mimetic texture in meat alternatives.
- Cosmetics:Secondary volume in personal care rheology modification.
Pharmaceuticals dominates value capture; Food & Beverages shows the steepest expansion trajectory as Dutch and Spanish processors scale plant-based formulation programs.
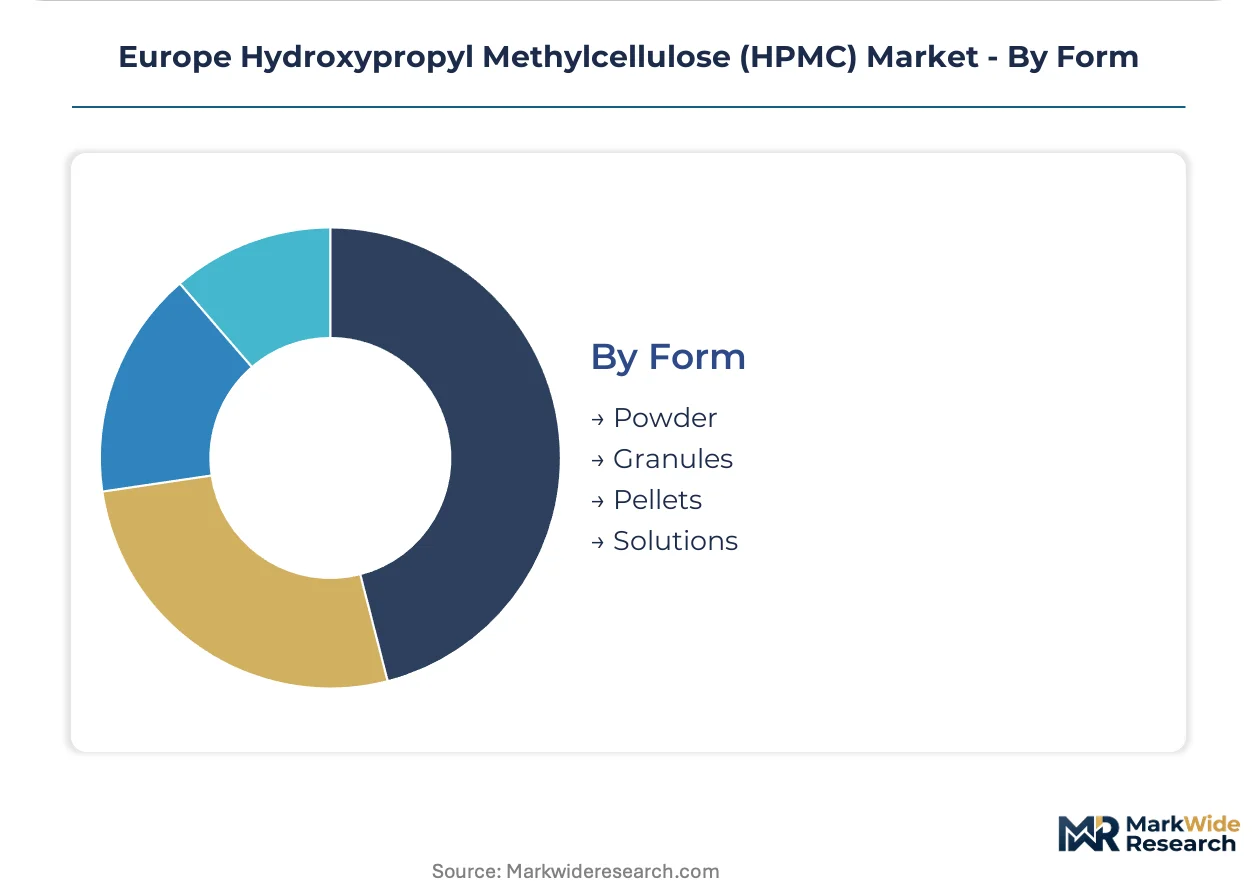
Form:
Physical form selection determines handling economics and dissolution kinetics, with powder dominating bulk shipments and solutions commanding premium for ready-to-use convenience.
- Powder:Standard bulk delivery format with particle size distribution optimized for dust-free handling and rapid hydration. Pharmaceutical and construction customers across Germany, France, and Benelux specify powder for in-house dissolution control.
- Solutions:Pre-dispersed aqueous concentrates eliminating hydration time for food and cosmetic processors. Belgian and Dutch formulators are adopting solution formats to compress batch cycle times in high-mix plant-based meat operations.
- Granules:Intermediate flowability for direct compression tableting with reduced dust exposure.
- Pellets:Specialized extrusion-spheronization feedstock for multi-unit pellet systems.
Powder retains the dominant position; Solutions are gaining share fastest as food processors prioritize formulation speed over raw material cost minimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA guidelines anchor pharmaceutical-grade demand concentration across Western Europe, with REACH compliance requirements creating protected supply zones for certified cellulose ether producers serving drug manufacturers and food processors.
Germany
Frankfurt and Basel pharmaceutical corridors drive controlled-release matrix procurement for oral solid dosage forms. ECHA REACH registration mandates disqualify uncertified imports, consolidating procurement around domestic producers. Rhine-Main and Rhine-Neckar building chemical clusters sustain industrial-grade consumption for cement hydration retardation specifications.
France
Paris-region generic drug manufacturers expand HPMC use in hydrophilic matrix systems for extended-release formulations. ANSM oversight of excipient quality aligns with EMA centralized procedure requirements. Lyon-based food processors accelerate plant-based meat reformulation programs utilizing thermal gelation properties.
Switzerland
Basel pharmaceutical manufacturing anchors premium-grade excipient demand for international drug export programs. Swissmedic guidelines reinforce EMA-equivalent purity thresholds for cellulose ethers. Zurich and Geneva university hospital pharmacies pioneer 3D printed personalized dosage geometries employing HPMC-based powder bed fusion.
Netherlands
Rotterdam and Amsterdam food processing facilities scale HPMC adoption for fat-mimetic texture engineering in meat alternatives. EFSA additive re-evaluation timelines constrain new product launch velocity. Eindhoven construction chemical distributors migrate to lot-level traceability systems for ready-mix concrete formulator certification.
Spain
Barcelona and Madrid plant-based protein processors reformulate meat analogues with HPMC for thermal gelation and emulsion stabilization. Spanish national food safety agency alignment with EFSA purity standards governs import qualification. Valencia ceramic tile adhesive manufacturers sustain industrial-grade viscosity-specification demand.
Europe Hydroxypropyl Methylcellulose (HPMC) Market Key Industry Players
Integrated chemical conglomerates and specialized cellulose ether producers split the market between captive feedstock advantages and pharmaceutical-grade certification depth. Three structural tiers emerge: propylene oxide-integrated multinationals, regional etherification specialists with REACH registration, and construction-grade volume suppliers. Dominant competitive moves include solvent recovery retrofit investments under F-Gas Regulation compliance and dual-source consolidation by pharmaceutical formulators reducing audit burden.
Among integrated chemical groups, Dow Chemical Company and Ashland Global Holdings Inc. exemplify the feedstock-integrated archetype with European production infrastructure. SE Tylose GmbH & Co. occupies the regional specialist position with proximity advantages to German building chemical formulators. These three anchors demonstrate how REACH certification and propylene oxide supply continuity determine competitive positioning across pharmaceutical and industrial grade segments.
| Leading Market Players |
|---|
| Dow Chemical Company |
| Ashland Global Holdings Inc. |
| Shin-Etsu Chemical Co., Ltd. |
| SE Tylose GmbH & Co. |
| Merck KGaA |
| Avantor, Inc. |
| Celanese Corporation |
| JRS Pharma |
| Shandong Head Europe BV |
| Others |
Cost & Logistics Intelligence
German propylene oxide supply concentration anchors margin distribution across European HPMC tiers, with integrated crackers near Ludwigshafen and Rotterdam determining feedstock cost pass-through to pharmaceutical-grade producers. Pharmaceutical formulators absorb premium pricing for REACH-certified excipients, while construction-grade buyers face volatility from spot propylene oxide markets.
Pricing Analysis
Geographic price spreads between Western European pharmaceutical corridors and Southern European industrial markets reflect certification-grade stratification. Three-tier pricing structure across pharmaceutical, food, and industrial levels differentiates by EMA master file status and residual solvent thresholds. Pricing pressure stems from propylene oxide cost volatility limiting margin recovery in long-term construction contracts. Industrial-grade buyers exhibit highest price sensitivity, while pharmaceutical procurement teams prioritize supply security over unit cost.
Supply Chain Analysis
EU F-Gas Regulation solvent recovery mandates restrict methylene chloride handling technology transfers, constraining new entrant reactor commissioning timelines. Manufacturing concentrates in Germany, the Netherlands, and Switzerland, with etherification capacity clustered around propylene oxide pipeline networks. Production draws from cellulose pulp, methyl chloride, and propylene oxide feedstocks. Single-source vulnerability persists for pharmaceutical-grade stainless steel reactor vessels with integrated solvent recovery. Distribution runs through specialty chemical distributors serving regional formulator clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty cellulose ether demand fragments across plant-based protein, personalized pharmaceutical, and green construction niches, creating multiple entry vectors beyond traditional volume competition. Plant-based meat reformulation in the Netherlands and Spain generates specialty-grade volume pockets outside incumbent pharmaceutical strongholds.
For Market Incumbents: Build regulatory moat depth through simultaneous EMA excipient master file expansion and EFSA food additive re-evaluation engagement. Secure dual-source consolidation benefits by offering combined pharmaceutical-food-construction grade portfolios that reduce buyer audit burden. Defend against ethyl cellulose substitution in film-coating by investing in continuous manufacturing compatibility certification. Prioritize F-Gas Regulation-compliant solvent recovery retrofit completion to capture displaced volume from stranded construction-grade competitors. For New Entrants and Emerging Players: Establish a beachhead in Spanish and Dutch food-grade HPMC for plant-based meat texture engineering, where EFSA re-evaluation timelines create qualification windows for compliant producers. Target solution-format supply to Belgian high-mix processors seeking batch cycle compression. Leverage REACH registration as a service to pharmaceutical formulators consolidating supplier panels, positioning as a compliant secondary source for non-critical oral solid dosage programs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade HPMC due to F-Gas Regulation solvent recovery mandates and stainless steel reactor requirements. Long-term viability favors producers with captive propylene oxide integration and existing closed-loop infrastructure. Acquisition target archetype: regional etherification specialists with REACH registration but lacking pharmaceutical-grade certification depth. Watch EMA centralized procedure master file submission velocity as inflection indicator for supplier relationship lock-in duration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Dow's Ludwigshafen crackers stabilize feedstock costs for pharmaceutical contract continuity. |
| Pharmaceutical-Grade Capacity Expansion | Ashland's specialized reactor investments capture EMA master file-driven procurement consolidation. |
| Food-Grade Certification Acceleration | SE Tylose leverages proximity to Dutch processors for plant-based meat formulation partnerships. |
| F-Gas Compliance Retrofit | Closed-loop methylene chloride recovery lowers operating costs versus import competitors. |
| Continuous Manufacturing Partnership | Irish direct compression line integration virtualizes batch-scale quality testing for generic launches. |
Research Approach
The analysis maps pharmaceutical-grade, food-grade, and industrial-grade HPMC sub-sectors, each validated through procurement directors at generic drug manufacturers, technical R&D leads at building chemical formulators, and regulatory affairs managers at food processors. Primary interview insights triangulate against EMA excipient guidelines, EFSA additive re-evaluations, Cefic chemical industry reports, and REACH registration databases. Bottom-up volume estimates by grade tier and application cross-check against top-down European cellulose ether production capacity assessments.
Assumptions held fixed include EMA centralized procedure master file requirements, EU REACH purity thresholds, and F-Gas Regulation phase-down schedules; variables tested include propylene oxide price trajectories and plant-based meat reformulation adoption rates. Segmentation models incorporate grade tier, end-use industry, physical form, and regional production hub dimensions. CAGRs derive from elasticity-adjusted demand projections across pharmaceutical controlled-release matrix expansion, construction warm-weather concreting specifications, and food thermal gelation adoption curves.
Macroeconomic conditions sit as an overlay; deviation in European construction activity indices or pharmaceutical R&D expenditure trends would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory compliance timelines and feedstock cost pass-through mechanisms. Material shifts in EMA excipient master file documentation requirements or F-Gas Regulation enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Acrylic Powder Market
Specialty Chemicals
Global Prepacked Chromatography Columns Market
Specialty Chemicals
Carbocernaite Market
Specialty Chemicals
Medical Propellants Market
Specialty Chemicals
Asia-Pacific Niacinamide Market
Specialty Chemicals
Enzyme Inhibitors Market
Specialty Chemicals
Keratin Products Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Microcrystalline Wax Market
Specialty Chemicals
Epoxidized Soybean Oil Market
Specialty Chemicals
Precipitated Barium Sulfate Market
Specialty Chemicals
Tetrabromobisphenol a (TBBPA) Market
Specialty Chemicals
Copper Ammonium Carbonate Market
Specialty Chemicals
Monomethylsilanetriol Market
Specialty Chemicals
Multichannel Reagent Reservoir Market
Specialty Chemicals
Insoluble Fibers Market