
 Stationary Catalytic Systems Market | 2026-2036
Stationary Catalytic Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Stationary Catalytic Systems Market Analysis
The premium catalyst tier is consolidating around proprietary zeolite formulations and extended service intervals, while commodity honeycomb substrates face margin compression from standardized supply. BASF SE leverages its integrated rare earth supply chain to dominate high-temperature diesel oxidation catalysts. Johnson Matthey anchors the European power plant retrofit segment through dense channel substrate engineering. Umicore competes aggressively in the Asian industrial boiler market with copper-zeolite SCR formulations.
Stationary catalytic systems are fixed-bed reactors containing ceramic or metallic substrates coated with platinum-group metals, transition metal oxides, or zeolites, operating at temperatures between 150°C and 600°C to facilitate chemical transformation without catalyst consumption. Selective catalytic reduction systems command the largest installed base across coal-fired and gas turbine power generation, though oxidation catalysts for chemical synthesis are capturing faster replacement cycles. Heterogeneous catalysis occupies the dominant technology position due to its mechanical durability in high-dust flue gas streams, while photocatalysis remains confined to niche waste treatment applications with limited thermal tolerance.
EPA Mercury and Air Toxics Standards in the United States, MEE emission limits in China, and EU Industrial Emissions Directive with BAT-associated emission levels collectively mandate NOx and CO reduction thresholds that force continuous catalyst replacement and upgrade cycles. The EU F-Gas Regulation and REACH chemical restrictions further constrain catalyst formulation choices, elevating compliance costs for non-European suppliers. Stakeholders must monitor regulatory divergence between jurisdictions as divergent metal recovery requirements and emission testing protocols reshape sourcing decisions and localization strategies.
Market Dynamics
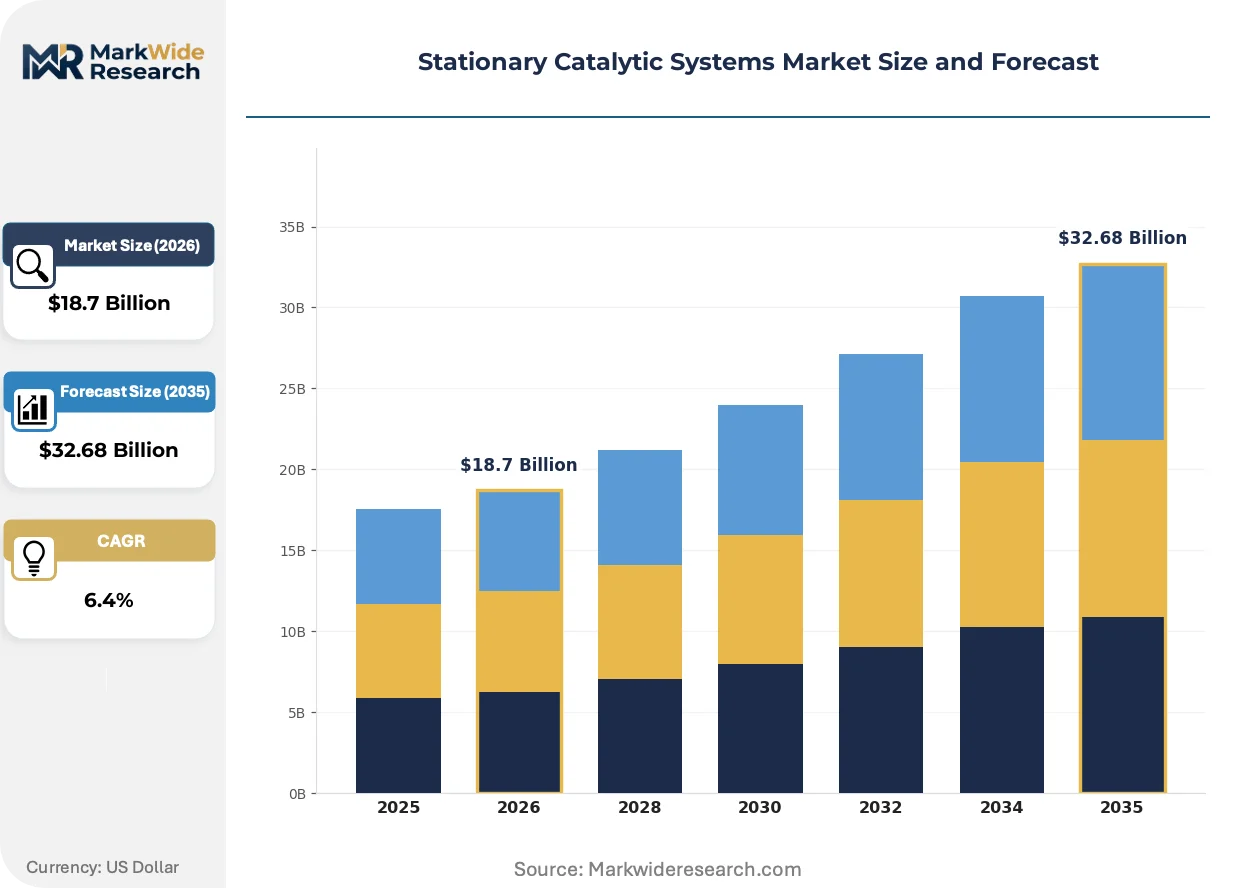
Retrofit obligations under China's MEE standards and the EU Industrial Emissions Directive are forcing continuous catalyst replacement cycles across coal-fired power and chemical synthesis installations, compressing procurement timelines and elevating technical service intensity.
Growth Catalysts
- MEE emission standards:China's Ministry of Ecology and Environment mandates selective catalytic reduction retrofits at coal-fired power plants, sustaining replacement demand for vanadium-titanium and zeolite formulations.
- Chemical synthesis expansion:Petrochemical complexes in India and the Middle East are commissioning oxidation catalyst trains for methanol and ammonia production, extending addressable unit volume.
- Heterogeneous catalysis durability:Ceramic honeycomb substrates withstand high-dust flue gas streams in cement and steel applications where homogeneous alternatives degrade rapidly.
Market Restraints
- Platinum-group metal volatility:Palladium and rhodium price swings from South African and Russian supply concentration compress catalyst margins and complicate long-term contracting.
- REACH chemical restrictions:ECHA substance authorization requirements constrain cerium and cobalt oxide formulations, elevating compliance costs for non-European suppliers serving EU power plant operators.
- Photocatalysis thermal limitation:Titanium dioxide-based systems degrade above 200°C, excluding them from boiler and turbine exhaust streams where operating temperatures exceed 350°C.
Strategic Opportunities
- India industrial boiler segment:State pollution control board mandates in Maharashtra and Gujarat are accelerating first-time SCR installations at textile and food processing facilities.
- Hydrogen combustion adaptation:Ammonia-fired turbine pilots in Japan and South Korea require novel deNOx catalyst formulations tolerant to fuel-bound nitrogen and variable hydrogen blends.
- Copper-zeolite convergence:Low-temperature activity below 200°C enables compact reactor designs for distributed combined heat and power units in urban district heating networks.
Industry Challenges
- Catalyst characterization expertise:Shortage of engineers trained in BET surface area analysis and mercury porosimetry delays qualification of replacement formulations at utility procurement departments.
- Legacy system integration:Dense-channel substrate retrofits into 1980s-era reactor housings require custom flow distribution modifications, extending project timelines and site labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stationary Catalytic Systems Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxidation Catalysts, Reduction Catalysts, Three-Way Catalysts, Selective Catalytic Reduction End User: Power Plants, Oil Refineries, Chemical Plants, Industrial Boilers Technology: Homogeneous Catalysis, Heterogeneous Catalysis, Photocatalysis, Biocatalysis Application: Emission Control, Chemical Synthesis, Fuel Processing, Waste Treatment |
| Companies Covered | Johnson Matthey, BASF SE, Umicore, Hug Engineering, Kwangsung Co. Ltd., DCL International Inc., Hitachi Zosen Corporation, CECO Environmental, Cormetech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stationary Catalytic Systems Market Emerging Trajectories
Digital catalyst health monitoring and modular reactor architectures are compressing maintenance intervals and enabling predictive replacement scheduling across power generation and chemical processing fleets.
Automated regeneration systems using thermal and chemical washing protocols are automating catalyst life extension decisions at German and Japanese coal-fired installations. Plant operators deploy continuous pressure-drop and conversion-efficiency sensors to trigger regeneration cycles rather than calendar-based replacement. This automation is compressing annual catalyst consumption per megawatt of installed capacity while elevating service revenue for technical specialists.
EPA Mercury and Air Toxics Standards enforcement timelines are accelerating oxidation catalyst upgrades at US coal-fired units ahead of compliance deadlines. The regulation mandates co-benefit particulate and acid gas reductions that require integrated catalyst and sorbent injection systems. Coal-heavy Midwestern utilities are responding with bundled procurement contracts covering multi-year catalyst supply and guaranteed performance outcomes.
After-sales service unbundling is separating catalyst supply from installation and performance guarantees at European power plant operators. Asset owners now procure ceramic substrates from one supplier and contract commissioning and warranty management to specialized technical service firms. This pattern is most visible in Germany and Poland where independent power producers lack in-house catalyst engineering capabilities.
Stationary Catalytic Systems Market Segmentation
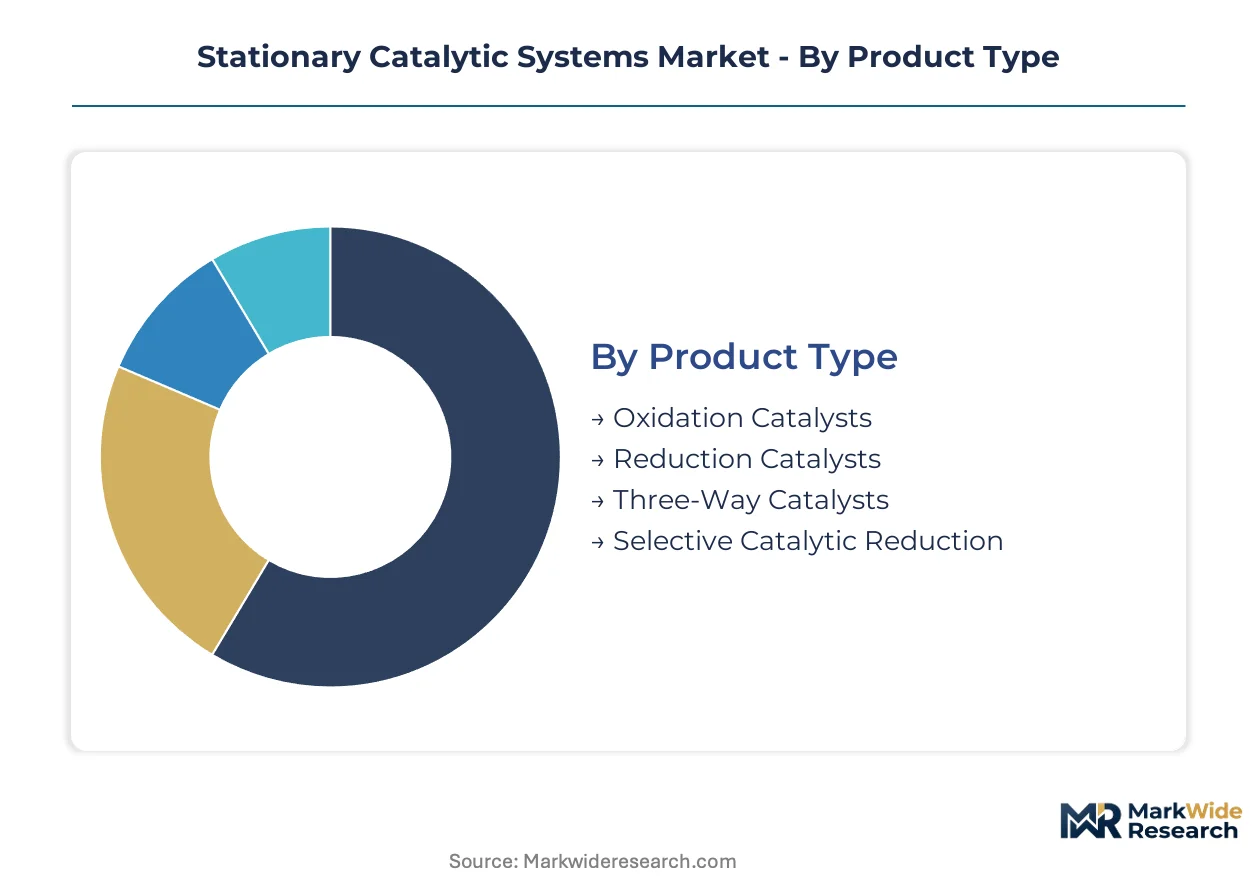
Stationary catalytic systems fragment across four distinct dimensions, each reflecting divergent supply chain configurations and procurement behaviors. Product type concentration determines formulation complexity and precious metal exposure. End-user segmentation reveals retrofit intensity versus greenfield deployment patterns.
Product Type:
Supply concentration tilts toward vanadium-titanium and zeolite formulations where rare earth access creates procurement leverage.
- Selective Catalytic Reduction:Ceramic honeycomb substrates coated with vanadium pentoxide or copper-zeolite enable NOx reduction at 300-400°C in coal-fired flue gas streams. China's MEE standards are sustaining replacement cycles at utilities across Shandong and Shanxi provinces.
- Oxidation Catalysts:Platinum-palladium coatings on metallic foil substrates convert CO and hydrocarbons at 200-550°C. US EPA Mercury and Air Toxics Standards are accelerating upgrades at Midwestern coal units ahead of compliance deadlines.
- Reduction Catalysts:Nickel-molybdenum formulations serve hydrogenation duties in refinery hydrocrackers.
- Three-Way Catalysts:Combined platinum-rhodium-palladium coatings address simultaneous NOx, CO, and hydrocarbon oxidation in gas turbine exhaust.
Selective Catalytic Reduction absorbs the bulk of installed capacity; Oxidation Catalysts are expanding most quickly.
End User:
Cost tier stratification separates continuous replacement utilities from cyclical chemical processors with lumpy procurement.
- Power Plants:Coal-fired and gas turbine installations require continuous catalyst replacement every 3-5 years under EPA, MEE, and EU Industrial Emissions Directive mandates. Germany's RWE and Uniper operate dense-channel retrofits demanding specialized substrate engineering.
- Industrial Boilers:Textile, food processing, and district heating units in Maharashtra and Gujarat are commissioning first-time SCR systems under state pollution control board orders.
- Oil Refineries:Hydrocracking and hydrotreating units consume nickel-based catalysts with 2-3 year replacement cycles tied to crude slate changes.
- Chemical Plants:Methanol and ammonia synthesis trains drive oxidation catalyst demand at Middle Eastern and Indian petrochemical complexes.
Power Plants command the deepest replacement backlog; Industrial Boilers are climbing the fastest on first-time installation mandates.
Technology:
Volume concentration favors mechanically durable substrates that withstand high-dust flue gas abrasion.
- Heterogeneous Catalysis:Solid-phase catalysts on ceramic or metallic supports dominate industrial applications due to thermal stability above 500°C and mechanical durability in particulate-laden streams. Cement and steel producers specify alumina-titania formulations for kiln exhaust treatment.
- Photocatalysis:Titanium dioxide coatings activated by UV irradiation degrade organic pollutants in aqueous waste streams below 200°C, excluding boiler and turbine exhaust applications.
- Homogeneous Catalysis:Liquid-phase systems serve specialty chemical synthesis with precise temperature control.
- Biocatalysis:Enzyme-based systems remain confined to pharmaceutical and fine chemical applications with stringent purity requirements.
Heterogeneous Catalysis holds the dominant installed base; Photocatalysis is gaining share fastest in niche water treatment segments.
Application:
Customer type bifurcation separates regulated utilities with mandated replacement schedules from discretionary industrial processors.
- Emission Control:NOx and CO reduction systems at power generation, cement, and steel facilities operate under enforceable concentration limits. EU F-Gas Regulation and REACH constraints elevate formulation costs for non-European suppliers.
- Chemical Synthesis:Oxidation and hydrogenation catalysts for methanol, ammonia, and specialty chemical production follow commodity cycle investment patterns.
- Fuel Processing:Hydrogen production and fuel cell feedstock purification employ palladium membrane and platinum-based reforming catalysts.
- Waste Treatment:VOC destruction and hazardous waste incineration utilize platinum-group metal catalysts in regenerative thermal oxidizers.
Emission Control represents the largest addressable volume; Chemical Synthesis follows the steepest expansion trajectory on petrochemical capacity additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province's industrial corridor dominates selective catalytic reduction retrofit activity as Chinese power operators rush to comply with MEE emission deadlines. The regional landscape fragments across five distinct regulatory jurisdictions, each enforcing divergent NOx and particulate thresholds that reshape procurement localization.
China
Coal-fired utilities across Shanxi and Shandong provinces are replacing vanadium-titanium catalysts on compressed three-year cycles under MEE enforcement timelines. The Ministry of Ecology and Environment mandates continuous emission monitoring systems at 1,000-plus megawatt plants. Zhengzhou and Xi'an industrial clusters are absorbing the bulk of copper-zeolite formulation demand from domestic fabricators.
Germany
RWE and Uniper operate dense-channel substrate retrofits requiring specialized engineering for 1980s-era reactor housings. The EU Industrial Emissions Directive with BAT-associated emission levels forces continuous catalyst replacement at lignite-burning stations. The Rhine-Ruhr industrial belt concentrates technical service demand for automated regeneration systems using thermal washing protocols.
United States
Midwestern coal-heavy utilities are bundling multi-year catalyst supply contracts ahead of EPA Mercury and Air Toxics Standards deadlines. The regulation mandates co-benefit particulate reductions requiring integrated catalyst and sorbent injection systems. Ohio River Valley power operators are accelerating oxidation catalyst upgrades at aging subcritical units.
India
Maharashtra and Gujarat state pollution control boards are mandating first-time SCR installations at textile and food processing facilities. The Central Electricity Authority guidelines for thermal power NOx limits are extending replacement demand to industrial boiler segments. Surat and Ahmedabad industrial zones are commissioning compact reactor designs for distributed combined heat and power units.
Japan
Ammonia-fired turbine pilots in Yokohama and Nagoya require novel deNOx formulations tolerant to fuel-bound nitrogen and variable hydrogen blends. METI hydrogen combustion roadmaps are driving catalyst adaptation for 2040 carbon-neutral power targets. Chubu Electric and JERA are testing copper-zeolite convergence below 200°C for urban district heating networks.
Stationary Catalytic Systems Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and rare earth supply chain control. The vendor base stratifies into three tiers: integrated chemical conglomerates with captive rare earth access, specialized substrate engineers with dense-channel retrofit expertise, and regional fabricators competing on standardized honeycomb pricing. Strategic archetypes include integrated material-science conglomerates, dense-channel engineering specialists, and low-cost ceramic substrate producers. Competitive moves concentrate on backward integration into rare earth refining and technology licensing partnerships for localized regeneration service networks.
Among European chemical conglomerates, Johnson Matthey and BASF SE exemplify divergent strategic positioning within the premium tier. Johnson Matthey anchors dense-channel substrate engineering capabilities for power plant retrofit segments. BASF SE occupies a position shaped by integrated rare earth supply chain control for high-temperature oxidation formulations. Umicore represents the copper-zeolite specialization archetype competing aggressively in Asian industrial boiler procurement cycles. These three entities collectively illustrate how formulation expertise and material access create defendable positioning against commodity substrate competition.
| Leading Market Players |
|---|
| Johnson Matthey |
| BASF SE |
| Umicore |
| Hug Engineering |
| Kwangsung Co. Ltd. |
| DCL International Inc. |
| Hitachi Zosen Corporation |
| CECO Environmental |
| Cormetech |
| Others |
Supply Flow & Price Mechanics
Palladium and rhodium feedstock costs cascade through catalyst manufacturing tiers, with platinum-group metal volatility compressing margins at commodity honeycomb producers while integrated rare earth suppliers defend premium pricing for zeolite formulations. Procurement officers at European utilities and Asian industrial boiler operators face divergent cost structures based on backward integration depth.
Pricing Analysis
Performance-guaranteed uptime contracts anchor value-based pricing for power plant SCR retrofits, with Johnson Matthey and BASF SE commanding premium tiers through extended service intervals and dense-channel engineering. Price differentiation separates proprietary copper-zeolite formulations from standardized vanadium-titanium substrates, with certification under EU REACH and MEE emission standards elevating compliance-grade premiums. Pricing pressure stems from South African and Russian supply concentration in platinum-group metals, squeezing margins at non-integrated fabricators. Cyclical chemical processors exhibit highest price sensitivity due to lumpy procurement tied to commodity cycles, while regulated utilities under EPA Mercury and Air Toxics Standards show lower elasticity given mandated replacement schedules.
Supply Chain Analysis
Rare earth oxide supply rests on Chinese refining dominance and Australian mining concentration, with lanthanum and cerium inputs feeding zeolite catalyst production for low-temperature applications. Ceramic honeycomb substrates draw from Japanese and German advanced materials producers, while metallic foil supports source from South Korean and US specialty steel mills. Supply chain risk centers on single-source vulnerability in rare earth separation capacity, with non-Chinese catalyst fabricators exposed to export quota fluctuations. Distribution runs through technical service partnerships rather than direct OEM supply, with regeneration and installation capabilities increasingly unbundled from substrate procurement at European power operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with players pursuing captive rare earth supply chains to escape platinum-group metal volatility and defend formulation margins against commodity substrate competition.
For Market Incumbents: Anticipate copper-zeolite convergence below 200°C by securing low-temperature formulation IP and expanding technical service networks in Maharashtra and Gujarat industrial corridors. Backward integration into rare earth refining in Australia or North America reduces Chinese supply exposure. Dense-channel retrofit expertise at RWE and Uniper installations creates switching costs that defend against modular reactor disruptors. For New Entrants and Emerging Players: Digital-channel regeneration service platforms offer white-space entry, with automated catalyst health monitoring and predictive replacement scheduling underserved at independent power producers in Poland and India. Target first-time SCR installations at Surat and Ahmedabad textile facilities, where state pollution control board mandates outrun incumbent technical service capacity. Bundle compact reactor design with performance guarantees to bypass established substrate supply relationships. For Investors and Strategic Acquirers: Ammonia-fired turbine pilot results at Chubu Electric and JERA are the leading indicator that hydrogen combustion catalyst adaptation will reshape R&D allocation and acquisition premiums. Long-term viability favors vertically integrated players with rare earth access and dense-channel engineering capabilities. Watch MEE enforcement intensity in Shanxi Province as the signal for Chinese replacement cycle compression and domestic fabricator consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Refining | Captive lanthanum and cerium supply secures copper-zeolite formulation margins against Chinese export policy shifts. |
| Automated Regeneration Service Networks | Thermal washing protocol deployment at German coal installations compresses maintenance intervals and elevates recurring revenue. |
| Low-Temperature Formulation Licensing | Copper-zeolite IP partnerships enable compact reactor designs for urban district heating networks in Japan and South Korea. |
| Performance Guarantee Unbundling | Separate substrate supply from installation contracts to capture independent power producer demand in Poland and India. |
| Hydrogen Combustion Catalyst Development | Ammonia-tolerant deNOx formulations for JERA and Chubu Electric pilots address 2040 carbon-neutral power targets. |
Methodological Framework
Document review covered EPA enforcement timelines, MEE emission standard filings, EU Industrial Emissions Directive BAT guidance, and customs trade data for platinum-group metal flows, complemented by interviews with utility procurement directors, catalyst plant managers, and technical service specialists at regeneration facilities. Secondary validation drew from SEC 10-K filings of chemical conglomerates, ECHA substance authorization databases, and power sector capex disclosures. Bottom-up unit volume estimates from retrofit installation counts triangulated against top-down market sizing from rare earth consumption patterns.
Installed capacity projections across coal-fired power, industrial boilers, and chemical synthesis trains segmented by substrate material, operating temperature range, and regional regulatory framework. CAGRs derived from replacement cycle compression under MEE and EPA mandates, with hydrogen combustion adaptation scenarios modeled as contingent demand. Industry-specific inputs included vanadium-titanium versus copper-zeolite formulation adoption curves and automated regeneration penetration rates at German and Japanese utilities.
The model holds under continuous enforcement of EPA Mercury and Air Toxics Standards and MEE emission deadlines; deviation in regulatory delay or platinum-group metal supply disruption would shift replacement timing and procurement localization. Forecasts reflect assumptions regarding rare earth supply continuity and heterogeneous catalysis durability advantages. A small set of named triggers—ammonia turbine pilot outcomes, REACH authorization expansions, and Indian state pollution control board mandate acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Homogeneous Catalyst Market
Catalysts
Biodiesel Catalyst Market
Catalysts
Inorganic Catalyst Market
Catalysts
Catalase Market
Catalysts
Organic Catalyst Market
Catalysts
Fluid Catalytic Cracking Catalyst Market
Catalysts
Biorenewable Catalysts Market
Catalysts
Solid Acid Catalysts Market
Catalysts
Hydrotreating Catalyst Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
Rhodium Carbon Catalyst Market
Catalysts
Europe Refining Catalysts Market
Catalysts
Platinum-Based Catalysts Market
Catalysts
Catalyst Handling Services Market
Catalysts
FCC Catalyst Additive Market
Catalysts
Precious Metal Catalysts Market