
 Multifunctional Cleaner Market | 2026-2036
Multifunctional Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Multifunctional Cleaner Market Insights
The premium-commodity split in multifunctional cleaners is repositioning around surfactant concentration and certification density. Procter & Gamble Co. (P&G) leverages its R&D scale to anchor EPA Safer Choice portfolios across North American retail. Henkel AG & Co. KGaA competes through concentrated refill systems that reduce plastic intensity per cleaning cycle. Seventh Generation Inc. differentiates via plant-derived surfactant chemistry and transparent ingredient labeling.
Multifunctional cleaners are formulated aqueous or solvent-based solutions combining surfactants, chelating agents, and pH buffers to degrease, disinfect, and polish across hard surfaces in a single application, typically requiring dilution ratios between 1:32 and 1:256 depending on soil load. Their primary commercial purpose is labor reduction through elimination of product-switching downtime in janitorial and industrial maintenance workflows. All-purpose cleaner formulations occupy the largest volume share due to universal surface compatibility, while spray bottle packaging commands premium shelf positioning in retail channels even as refill pouch formats gain traction in subscription e-commerce. Automotive cleaning applications represent the fastest-growing demand pool as detailing shops adopt waterless multifunctional concentrates to comply with municipal wastewater discharge rules.
EPA Safer Choice, EU Ecolabel, and REACH compliance collectively determine which chemistries manufacturers can deploy across transatlantic markets, directly constraining quaternary ammonium compound formulations and volatile organic solvent content. The EU F-Gas Regulation and state-level California Cleaning Product Right to Know Act add layered disclosure obligations that favor producers with dedicated regulatory affairs functions. Stakeholders must monitor emerging per- and polyfluoroalkyl substance restrictions in cleaning formulations, as these compounds face accelerating phase-out timelines that will force reformulation investments across legacy product lines.
Market Dynamics
Concentrated formulation chemistry is compressing logistics costs while forcing capital reallocation toward dilution-system infrastructure and regulatory compliance documentation across transatlantic supply chains.
Growth Catalysts
- EPA Safer Choice certification:North American hospitality procurement now mandates verified safer chemistry, pulling reformulated concentrates into hotel chain specifications.
- Waterless concentrate technology:Automotive detailing shops in California and Germany adopt ultra-low water formulations to meet municipal discharge ordinances.
- German facility management consolidation:Single-product cleaning protocols reduce janitorial training hours and inventory SKUs in bundled service contracts.
Market Restraints
- Quaternary ammonium compound restrictions:REACH and state-level antimicrobial registration requirements limit legacy disinfectant chemistries.
- Surfactant feedstock volatility:Palm kernel and coconut oil derivative prices fluctuate with Southeast Asian agricultural yields.
- Concentrated product switching costs:End-users face capital expenditure for dilution-control equipment and staff retraining.
Strategic Opportunities
- Subscription e-commerce refill models:Pouch-to-bottle systems bypass retail shelf-space constraints and build recurring revenue.
- EU F-Gas Regulation compliance services:Formulation consulting for solvent-based cleaner manufacturers facing volatile organic compound phase-outs.
- Per- and polyfluoroalkyl substance replacement R&D:First-mover advantage in fluorine-free surfactant chemistry ahead of anticipated restrictions.
Industry Challenges
- Cross-functional regulatory expertise scarcity:Few chemists possess simultaneous fluency in EPA Safer Choice, EU Ecolabel, and REACH dossier preparation.
- Legacy equipment incompatibility:High-concentration formulations corrode older dilution systems designed for 1:32 ratios rather than 1:256.
- Ingredient disclosure timeline compression:California Cleaning Product Right to Know Act mandates strain documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multifunctional Cleaner Market |
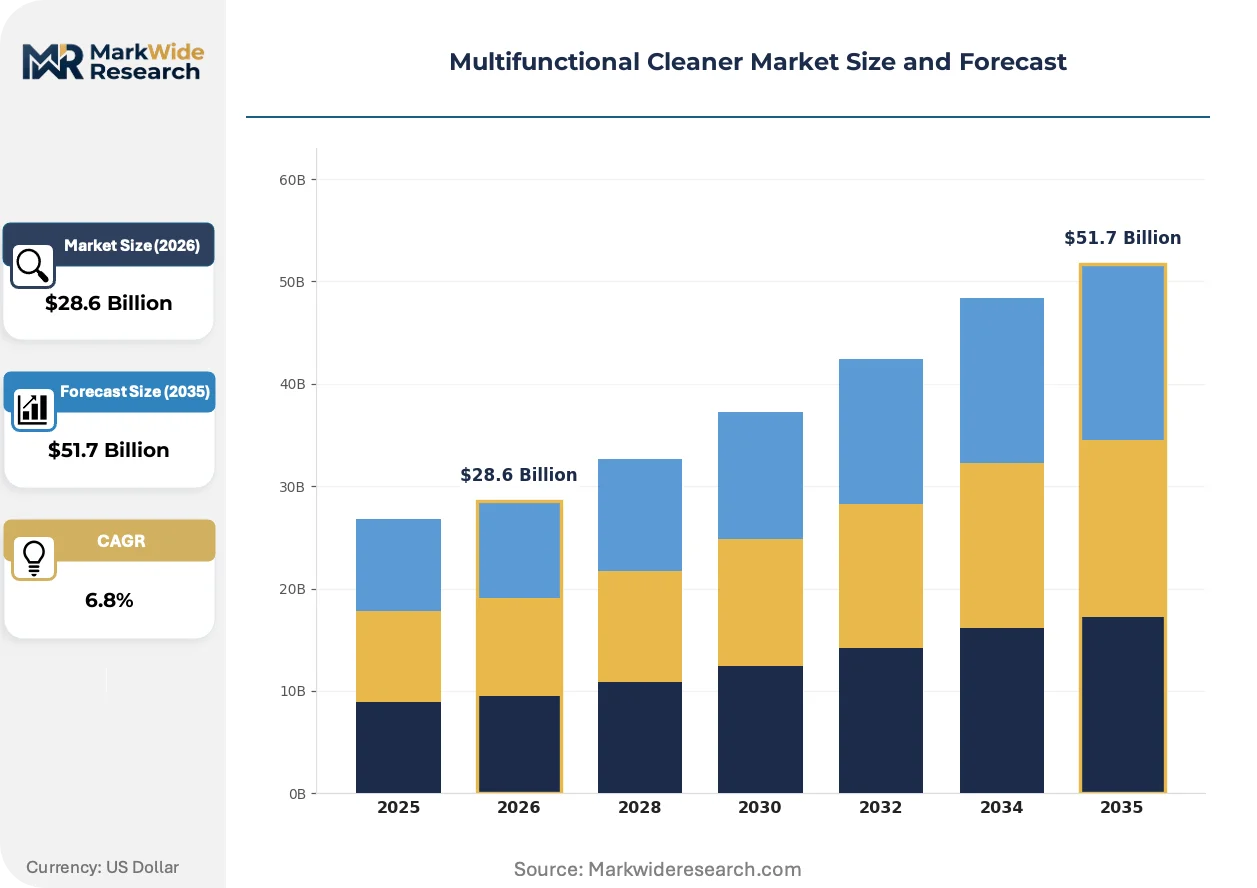
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Purpose Cleaner, Glass Cleaner, Bathroom Cleaner, Floor Cleaner Application: Household Use, Commercial Use, Industrial Use, Automotive Cleaning Packaging Type: Spray Bottle, Refill Pouch, Bulk Container, Wipe Pack Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Suppliers |
| Companies Covered | The Clorox Company, Colgate-Palmolive Company, Procter & Gamble Co. (P&G), Zep Inc., Church & Dwight Co. Inc., Reckitt Benckiser Group plc, SC Johnson & Son Inc., Seventh Generation Inc., Henkel AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multifunctional Cleaner Market Trends and Innovations
Formulation transparency and concentration economics are restructuring competitive advantage away from brand recognition toward technical documentation and supply-chain integration capabilities.
Enzymatic cleaning technology is decentralizing soil-breakdown functions from high-temperature mechanical scrubbing to ambient-temperature chemical catalysis. Food processing facilities in the Netherlands and Wisconsin deploy lipase and protease blends for grease removal without steam equipment. This shift is decentralizing capital investment from centralized wash stations to portable spray applications.
REACH Annex XVII restrictions on microplastic-containing products are forcing reformulation of abrasive scrubbing agents in European all-purpose cleaners. Manufacturers substitute cellulose-based or mineral abrasives, increasing raw material costs but securing market access. The household retail segment absorbs these costs through premium positioning rather than volume sacrifice.
Facility management procurement departments now require environmental product declarations and health product declarations as standard bid prerequisites. Third-party certification bodies in Germany and California verify these documents, creating a documentation bottleneck. This behavioral shift favors suppliers with dedicated sustainability teams over commodity chemical distributors.
Multifunctional Cleaner Market Segmentation
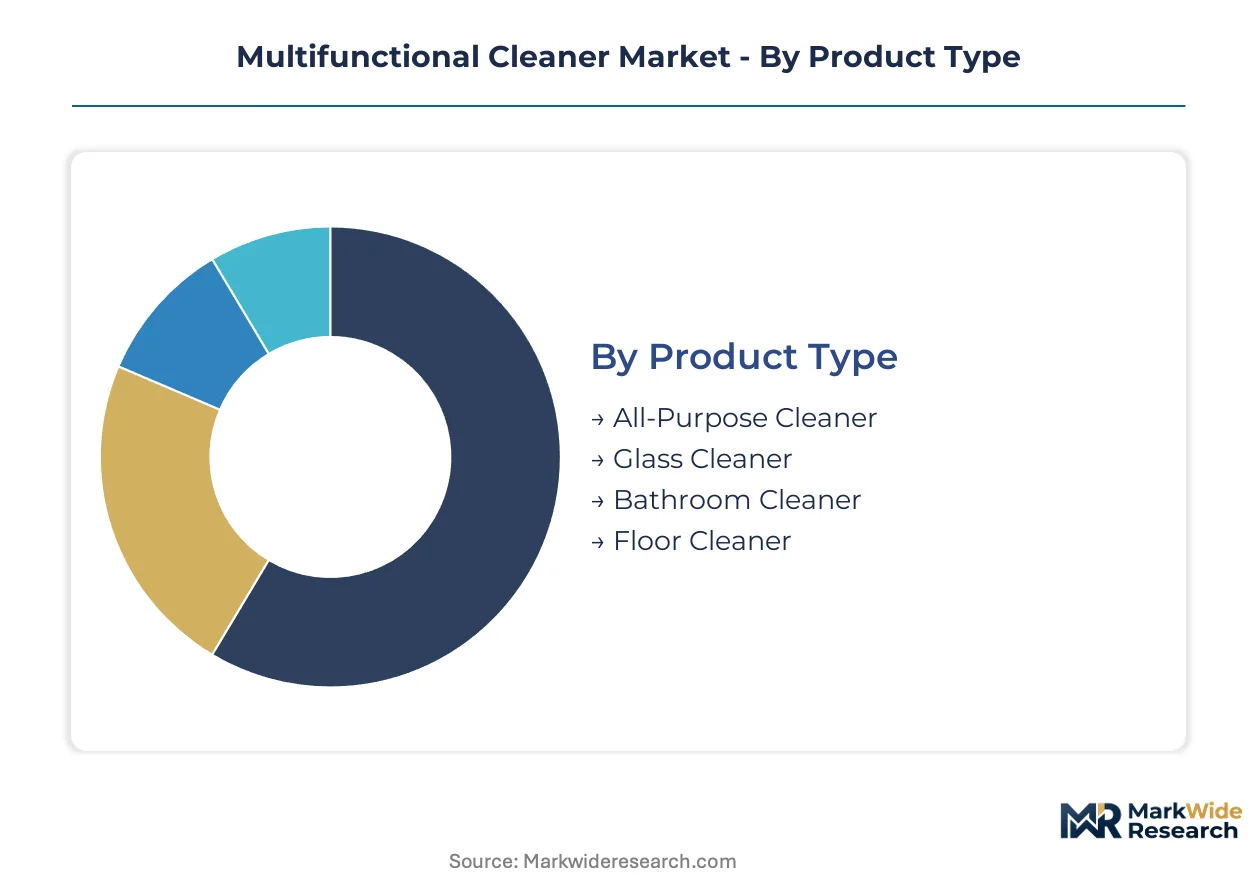
Multifunctional cleaner procurement splits sharply between volume buyers optimizing labor costs and retail consumers prioritizing convenience. Segmentation reveals where formulation chemistry, packaging format, and channel access create divergent margin pools across institutional and household demand.
Product Type:
Surface compatibility requirements drive product selection more than price in commercial contracts.
- All-Purpose Cleaner:Surfactant-based formulations with pH buffers between 6.5 and 9.0 handle countertops, walls, and fixtures without residue. Facility managers in Germany specify these for single-product protocols that cut training hours and inventory complexity.
- Glass Cleaner:Ammonia-free and vinegar-based variants prevent streaking on coated surfaces. Demand concentrates in North American hospitality chains where guest-facing transparency standards mandate spot-free finishes on lobby glasswork.
- Bathroom Cleaner:Acidic formulations with chelating agents dissolve calcium and soap scum deposits. Scale-prone municipal water supplies in the US Midwest and UK hard-water regions sustain replacement rates.
- Floor Cleaner:Low-foaming surfactant systems compatible with auto-scrubber machines dominate. Industrial maintenance contracts in automotive plants and food processing facilities specify dilution ratios optimized for mechanized application.
Volume sits with all-purpose formulations; growth tilts toward bathroom cleaners as hard-water regions expand treatment frequency.
Application:
Labor cost structures determine whether buyers accept capital expenditure for concentrate dilution systems.
- Household Use:Trigger-spray convenience and fragrance profiles dominate purchase decisions. Subscription e-commerce in California and New York accelerates refill pouch adoption over single-use bottles.
- Commercial Use:Janitorial service contracts bundle cleaning chemicals with labor pricing. EPA Safer Choice certification has become a mandatory bid prerequisite for hotel and office building procurement in the United States.
- Industrial Use:Heavy-duty degreasing with solvent-based or high-alkaline chemistry addresses manufacturing equipment maintenance. REACH compliance documentation requirements favor suppliers with dedicated regulatory affairs functions.
- Automotive Cleaning:Waterless concentrate technology expands fastest as California and German municipal discharge ordinances restrict wastewater volumes from detailing operations.
Commercial use commands the largest volume base; automotive cleaning climbs fastest on regulatory pressure.
Packaging Type:
Packaging selection trades shelf presence against logistics cost compression and plastic intensity reduction.
- Spray Bottle:Trigger mechanisms and ergonomic grips secure premium retail positioning. Supermarkets allocate eye-level shelf space to recognized brands despite higher per-ounce pricing than bulk alternatives.
- Refill Pouch:Flexible film packaging reduces plastic weight per cleaning cycle by 70-80% versus rigid bottles. Henkel and Seventh Generation compete through concentrated refill systems that lock in recurring revenue via subscription models.
- Bulk Container:Five-gallon pails and drum formats serve institutional buyers with dilution-control equipment. Capital expenditure for dispensing infrastructure limits adoption to facilities with dedicated janitorial management.
- Wipe Pack:Pre-saturated nonwoven substrates eliminate dilution errors and cross-contamination risks. Healthcare and food service applications in the United States favor these for rapid disinfection protocols.
Bulk containers dominate institutional volume; refill pouches expand fastest through e-commerce subscription mechanics.
Distribution Channel:
Channel selection reflects buyer urgency, technical support requirements, and contract bundling preferences.
- Online Retail:Direct-to-consumer platforms bypass shelf-space constraints and enable subscription automation. Amazon and specialized cleaning supply sites capture refill pouch and concentrated concentrate demand from sustainability-motivated households.
- Supermarkets:Mass merchandisers rely on brand recognition and impulse placement for spray bottle formats. Price promotions and multi-pack bundling drive volume in suburban and rural markets.
- Specialty Stores:Janitorial supply distributors provide technical consultation and equipment compatibility verification. Independent operators in Germany and the United States maintain relationships with facility management contractors.
- Wholesale Suppliers:Bulk pricing and consolidated logistics serve multi-location hospitality and healthcare chains. Group purchasing organizations negotiate multi-year supply agreements with certified formulation guarantees.
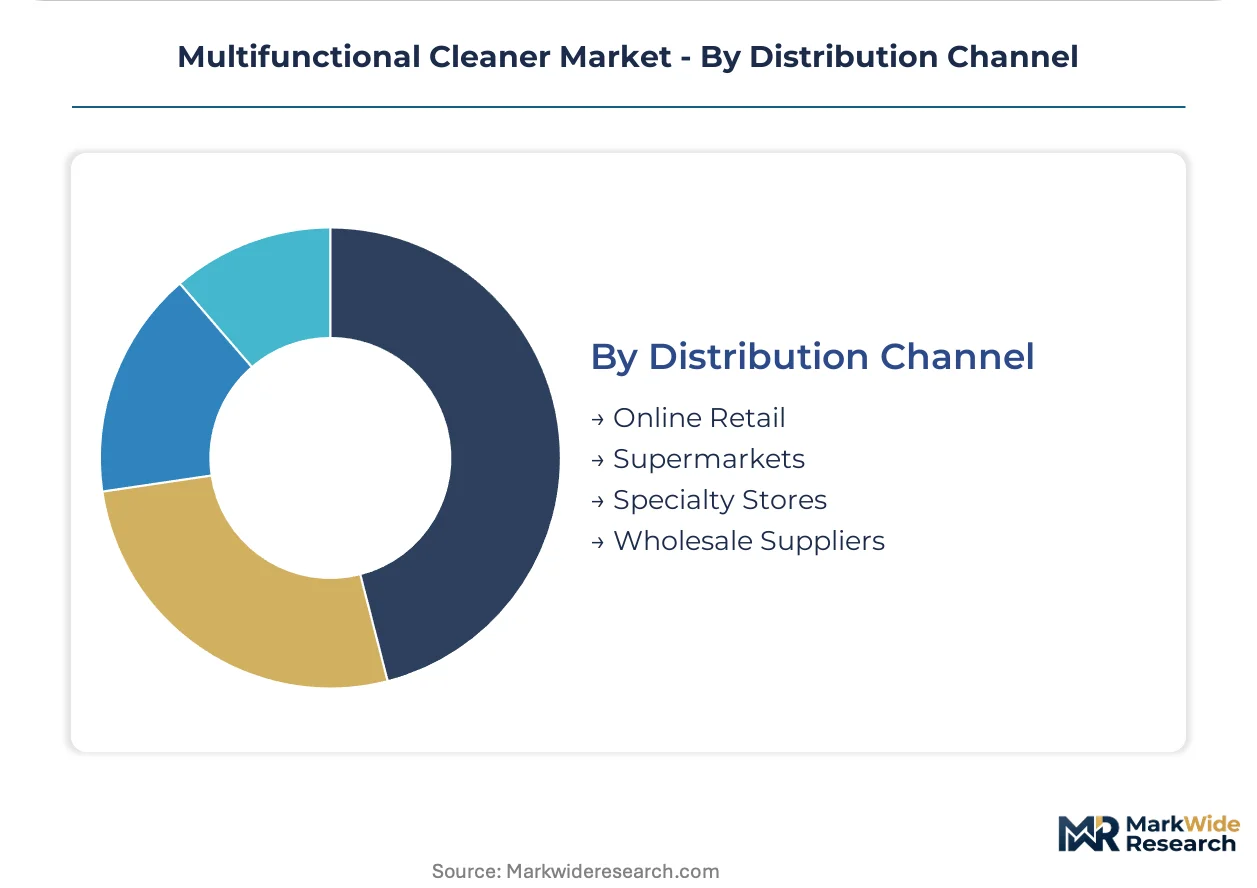
Wholesale suppliers anchor commercial volume; online retail climbs fastest on subscription model expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan region anchors European demand for concentrated multifunctional cleaners, where facility management contractors specify single-product protocols to reduce janitorial training complexity across industrial parks and logistics hubs.
United States
California's automotive detailing sector drives waterless concentrate adoption as municipal discharge ordinances tighten wastewater restrictions. EPA Safer Choice certification has become mandatory for hospitality procurement contracts in Las Vegas and Orlando hotel corridors. The Midwest's hard-water regions sustain acidic bathroom cleaner demand through scale-prone municipal supplies.
Germany
Facility management consolidation across Bavaria and North Rhine-Westphalia prioritizes inventory SKU reduction through universal all-purpose formulations. EU Ecolabel compliance documentation determines supplier eligibility for federal building maintenance contracts. Berlin's public transit authority mandates concentrated refill systems to cut storage footprint in underground maintenance depots.
China
Yangtze River Delta manufacturing zones deploy heavy-duty degreasing formulations for automotive equipment maintenance workflows. The country's national chemical regulator enforces volatile organic compound limits that reshape solvent-based cleaner formulations. Shenzhen's electronics assembly plants specify low-residue surface cleaners for precision component handling.
Japan
Kanto region food processing facilities adopt enzymatic cleaning technology to reduce steam equipment capital expenditure. METI efficiency standards push concentrate dilution ratios toward 1:256 for logistics cost compression. Osaka's hospitality sector imports EPA Safer Choice certified products for international hotel chain compliance.
United Kingdom
London's commercial real estate sector bundles cleaning chemicals with janitorial service contracts to optimize labor pricing transparency. REACH Annex XVII microplastic restrictions force abrasive scrubber reformulation in household retail channels. Manchester's healthcare procurement clusters specify pre-saturated wipe formats for rapid disinfection protocols in NHS facilities.
Multifunctional Cleaner Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification density and surfactant concentration tiers. The vendor base stratifies between multinational formulators with dedicated regulatory affairs functions and regional distributors competing on logistics proximity. Three archetypes dominate: R&D-scaled certifiers, concentrated-system specialists, and plant-derived transparency marketers. Capacity expansion and subscription e-commerce infrastructure represent the dominant competitive vectors.
Among US-based consumer goods conglomerates, The Clorox Company and Procter & Gamble Co. occupy positions exemplifying the R&D-scaled certifier archetype through EPA Safer Choice portfolio anchoring. Henkel AG & Co. KGaA represents the concentrated-system specialist model with refill infrastructure investments. Seventh Generation Inc. sits within the plant-derived transparency tier.
| Leading Market Players |
|---|
| The Clorox Company |
| Colgate-Palmolive Company |
| Procter & Gamble Co. (P&G) |
| Zep Inc. |
| Church & Dwight Co. Inc. |
| Reckitt Benckiser Group plc |
| SC Johnson & Son Inc. |
| Seventh Generation Inc. |
| Henkel AG & Co. KGaA |
| Others |
Pricing and Supply Chain Analysis
EPA Safer Choice certification mandates from North American hospitality procurement departments are compressing margins for uncertified formulators while rewarding suppliers with dedicated regulatory affairs infrastructure, forcing supply-side consolidation around documentation-capable producers.
Pricing Analysis
Labor-cost reduction per cleaning cycle anchors value-based pricing for concentrated multifunctional formulations. Three-tier pricing structure across premium certified, standard compliant, and economy private-label levels stratifies the market, with EPA Safer Choice and EU Ecolabel tiers commanding sustained premiums. Cost compression in economy segments is intensifying because surfactant feedstock volatility from Southeast Asian agricultural yields feeds through to base chemical costs. Institutional buyers with dilution-control equipment exhibit lowest price sensitivity; household retail consumers show highest elasticity to per-ounce comparisons.
Supply Chain Analysis
Surfactant feedstock supply rests on Malaysian and Indonesian palm kernel oil processors, German specialty chemical producers for chelating agents, and Chinese manufacturers of pH buffer compounds. Key inputs include coconut oil derivatives, phosphonate chelators, and citric acid buffers. Single-source vulnerability concentrates in Southeast Asian oleochemical processing exposed to El Niño agricultural disruption. Distribution runs through janitorial supply distributors in Germany, wholesale group purchasing organizations in the United States, and specialized e-commerce platforms for refill pouch subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around regulatory documentation capabilities, with REACH and EPA Safer Choice compliance costs forcing smaller commodity distributors toward acquisition or exit.
For Market Incumbents: Deepen backward integration into surfactant feedstock processing to buffer against Southeast Asian agricultural price spikes. Anchor EPA Safer Choice portfolio expansion through dedicated regulatory affairs team scaling, as emerging plant-derived surfactant specialists threaten premium positioning with transparency-first branding.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for concentrated refill pouch models targeting California and New York sustainability-motivated households. White-space exists in EU F-Gas Regulation compliance consulting services for solvent-based cleaner manufacturers facing volatile organic compound phase-outs, with first-mover advantage in fluorine-free surfactant chemistry ahead of anticipated restrictions.
For Investors and Strategic Acquirers: The window for entry favors mid-sized formulators with existing EPA Safer Choice or EU Ecolabel certification infrastructure. Long-term viability hinges on regulatory documentation capabilities rather than brand equity alone. Watch for per- and polyfluoroalkyl substance restriction announcements as the inflection trigger forcing legacy product line reformulation investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Feedstock | Captive supply of palm kernel and coconut oil derivatives insulates margin from Southeast Asian agricultural volatility. |
| EPA Safer Choice Portfolio Expansion | Mandatory certification for North American hospitality procurement contracts locks in multi-year supply agreements. |
| Subscription E-Commerce Infrastructure | Refill pouch automation builds recurring revenue streams while bypassing retail shelf-space constraints. |
| Fluorine-Free Surfactant R&D Investment | First-mover chemistry ahead of anticipated per- and polyfluoroalkyl substance restrictions secures reformulation lead time. |
| EU F-Gas Compliance Consulting Services | Formulation advisory for solvent-based manufacturers facing volatile organic compound phase-outs captures service revenue. |
Research Methodology
Multi-period observation of EPA Safer Choice certification adoption rates, concentrated formulation dilution ratios, and refill pouch subscription growth anchored the trend analysis, supplemented by interviews with facility management procurement directors, janitorial supply distributors, chemical plant operations managers, and regulatory affairs specialists at formulators. Secondary validation drew from EPA Safer Choice certified product listings, EU Ecolabel registry data, REACH Annex XVII restriction updates, and trade association chemical shipment reports. Bottom-up segment sizing triangulated against top-down market value estimates.
Segment-weighting across product type, application, packaging format, and distribution channel dimensions structured the analytical framework. CAGRs were derived from modeled volume and value trajectories across the projection horizon, incorporating surfactant feedstock price elasticity, regulatory compliance cost pass-through assumptions, and dilution-system capital expenditure penetration curves specific to institutional buyer segments.
The model holds under stable regulatory enforcement timelines and intact agricultural supply chains; deviation in per- and polyfluoroalkyl substance restriction acceleration or Southeast Asian climate disruption would shift volume and value trajectories. A small set of named triggers—REACH Annex XVII expansion, California Cleaning Product Right to Know Act enforcement intensity, and El Niño agricultural yield impacts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Industrial and Institutional (Iandi) Cleaning Chemicals Market
Cleaning Chemicals
Southeast Asia Surface Treatment Chemicals Market
Cleaning Chemicals
Coating Removal System Market
Cleaning Chemicals
Soap and Detergent Market
Cleaning Chemicals
Green Floor Care Chemical Systems for Commercial Facilities Market
Cleaning Chemicals
Fabric Conditioner Market
Cleaning Chemicals
Cleanroom Consumables Market
Cleaning Chemicals
US Institutional Cleaning Ingredients Market
Cleaning Chemicals
Cleaning Chemicals Market
Cleaning Chemicals
Europe Metal Cleaning Chemicals Market
Cleaning Chemicals
Surface Cleaning Products Market
Cleaning Chemicals
Bleaching Chemicals Market
Cleaning Chemicals
High-Performance Descaling and Deliming Chemicals for HoReCa Equipment Market
Cleaning Chemicals
Multi-Residue Detoxifying Field Wash Aid Market
Cleaning Chemicals
Floor Wax Market
Cleaning Chemicals
Sanitizing Agents Market