
 Global Performance Additives Market | 2026-2036
Global Performance Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Performance Additives Market Intelligence
Custom formulation support as a bundled service is rebalancing the value proposition beyond mere volume sales of additives. BASF SE leverages its vast R&D infrastructure to offer tailored solutions for complex end-use applications. Evonik Industries AG specializes in high-performance additives for niche markets, while Dow competes on its global manufacturing scale and broad portfolio integration.
Performance additives are chemical substances incorporated in small quantities into a base polymer or material to enhance specific properties. These additives can improve characteristics such as thermal stability, UV resistance, flame retardancy, or processing efficiency during manufacturing. Stabilizers and impact modifiers constitute mature product segments, while demand for advanced flame retardants is growing in electronics and automotive applications. The automotive and packaging end-use sectors represent the largest consumption volumes.
Compliance with chemical safety regulations, such as Europe's REACH and the US EPA's Toxic Substances Control Act, governs market access. In Asia, China's GB standards and MEE environmental protection laws dictate product formulation and permissible substance levels. Suppliers must now navigate a fragmented regulatory landscape while investing in sustainable, bio-based alternatives to secure future market share.
Market Dynamics
The performance additives market is pivoting from a volume-driven model to one centered on application-specific solutions. This structural shift is propelled by the dual pressures of stringent environmental regulations and intense performance demands from advanced manufacturing sectors like automotive and electronics.
Growth Catalysts
- Automotive Lightweighting:Demand for high-strength, lightweight plastics in electric vehicles to extend battery range and improve efficiency requires advanced impact modifiers and stabilizers.
- Stringent Safety Regulations:Evolving fire safety codes for building materials and electronics in Europe and North America are expanding the market for non-halogenated, high-performance flame retardants.
- Asian Manufacturing Expansion:Continued industrialization and a policy-driven shift towards higher-value products in China and India create concentrated regional demand for processing aids and functional additives.
Market Restraints
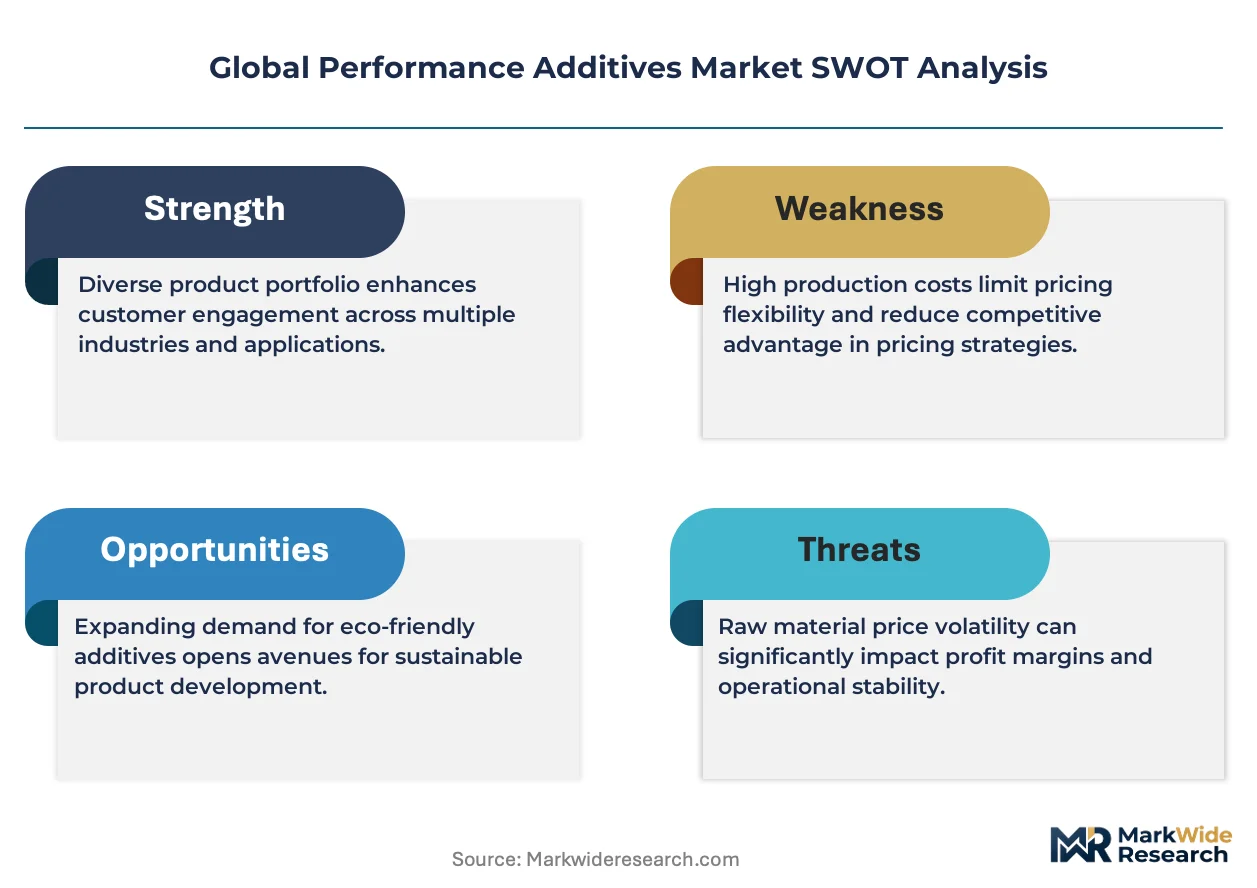
- Feedstock Price Volatility:The market's heavy reliance on petrochemical derivatives creates exposure to price fluctuations in crude oil and natural gas, impacting formulation costs and margins.
- Fragmented Regulatory Compliance:Navigating disparate chemical control laws, such as Europe's REACH and the US EPA's TSCA, adds significant cost, complexity, and time to new product introductions.
- Threat of Material Substitution:The development of inherently functional polymers and advanced composites that require fewer or no additives presents a long-term substitution risk in certain applications.
Strategic Opportunities
- Bio-Based Formulations:Developing additives derived from renewable feedstocks offers a path to meet sustainability mandates and appeal to brands focused on circular economy principles, especially in packaging.
- Multifunctional Additives:Creating single-additive solutions that provide multiple benefits, such as UV stability and flame retardancy, simplifies customer formulations and offers a distinct value proposition.
- Renewable Energy Applications:The expansion of wind and solar energy infrastructure creates new demand for specialized additives, including UV stabilizers for solar panel backsheets and processing aids for composite wind turbine blades.
Industry Challenges
- Complex Certification Pathways:The lengthy and costly process for achieving regulatory approval, particularly for additives used in food-contact plastics or medical devices, acts as a barrier to innovation.
- Formulation Expertise Scarcity:A shortage of polymer scientists and chemical engineers skilled in developing solutions that meet both high-performance metrics and strict environmental profiles constrains product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Performance Additives Market |
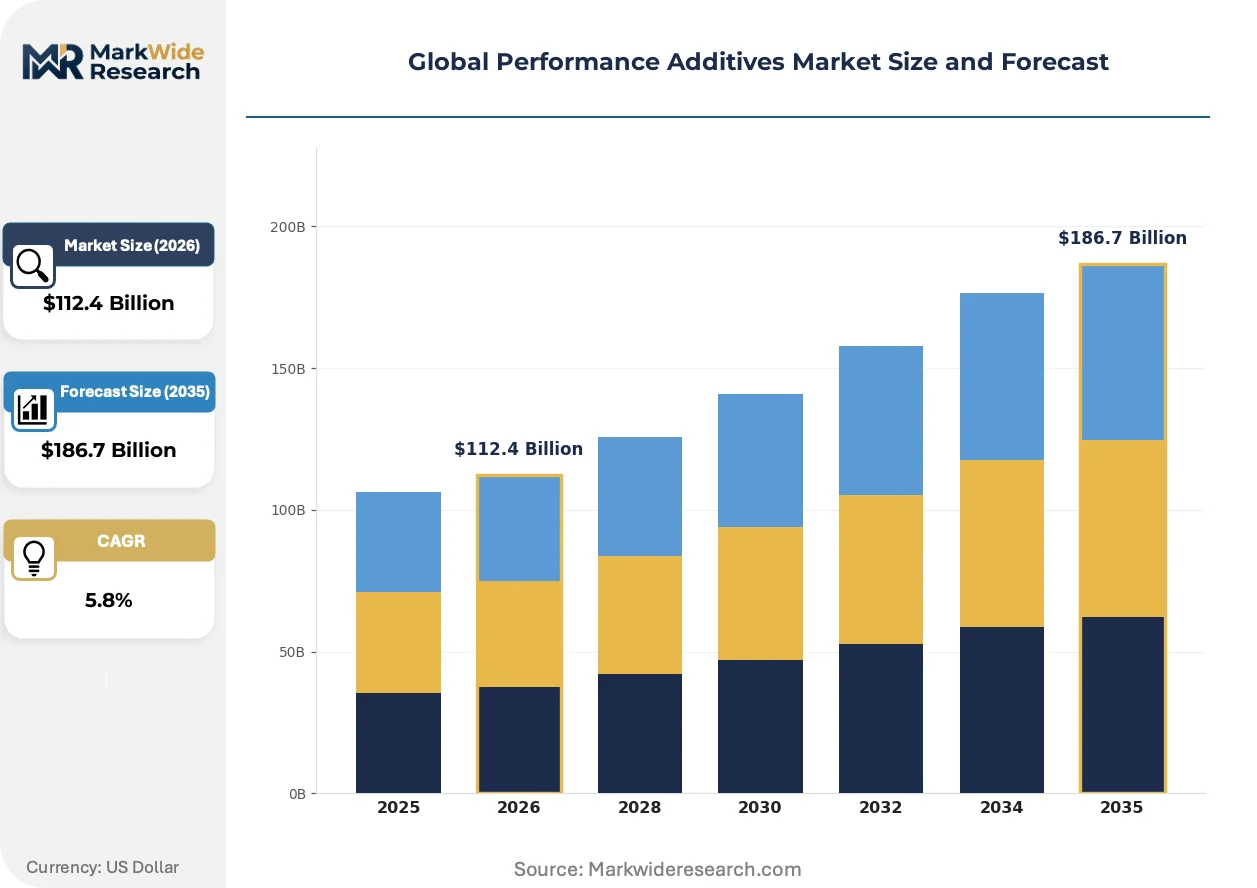
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $186.7 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Impact Modifiers, Processing Aids, Stabilizers, Dispersants End Use Industry: Automotive, Construction, Packaging, Electronics Formulation Type: Water-Based, Solvent-Based, Powdered, Granular Functionality: Flame Retardants, Antioxidants, Anti-Static Agents, Others |
| Companies Covered | BASF SE, Evonik Industries AG, Clariant, Solvay, Arkema, Dow, LANXESS, Akzo Nobel N.V., Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Performance Additives Market Strategic Shifts & Innovations
The core value proposition in the market is shifting from supplying chemical inputs to delivering integrated material performance. This evolution is driven by end-user demand for tailored properties that solve complex challenges in sustainability and product durability, forcing a change in supplier business models.
Digital formulation platforms using artificial intelligence are emerging as a critical research and development tool. These systems predict how different additive combinations will perform in a polymer matrix, drastically reducing trial-and-error lab work. Adoption is accelerating within the R&D centers of specialty chemical producers and OEMs, where speed to market is paramount. This technology is decentralizing formulation knowledge, enabling application engineers to develop bespoke solutions directly with customers.
Europe's Corporate Sustainability Reporting Directive (CSRD) is compelling a new level of transparency across the chemical supply chain. The regulation requires detailed disclosure of a product's environmental lifecycle, including its carbon footprint and raw material origins. Additive manufacturers are most affected, as they must now provide validated sustainability data, which in turn influences their sourcing towards bio-based and recycled feedstocks to maintain market access.
Purchasing behavior is evolving from transactional, price-based orders to collaborative co-development frameworks. This shift is bypassing traditional distributors in favor of direct partnerships between additive specialists and end-product manufacturers. The model allows for the creation of unique solutions for specific challenges, a trend most visible within the German automotive industry and Japanese electronics sector, where deep supplier integration is a competitive advantage.
Global Performance Additives Market Segmentation
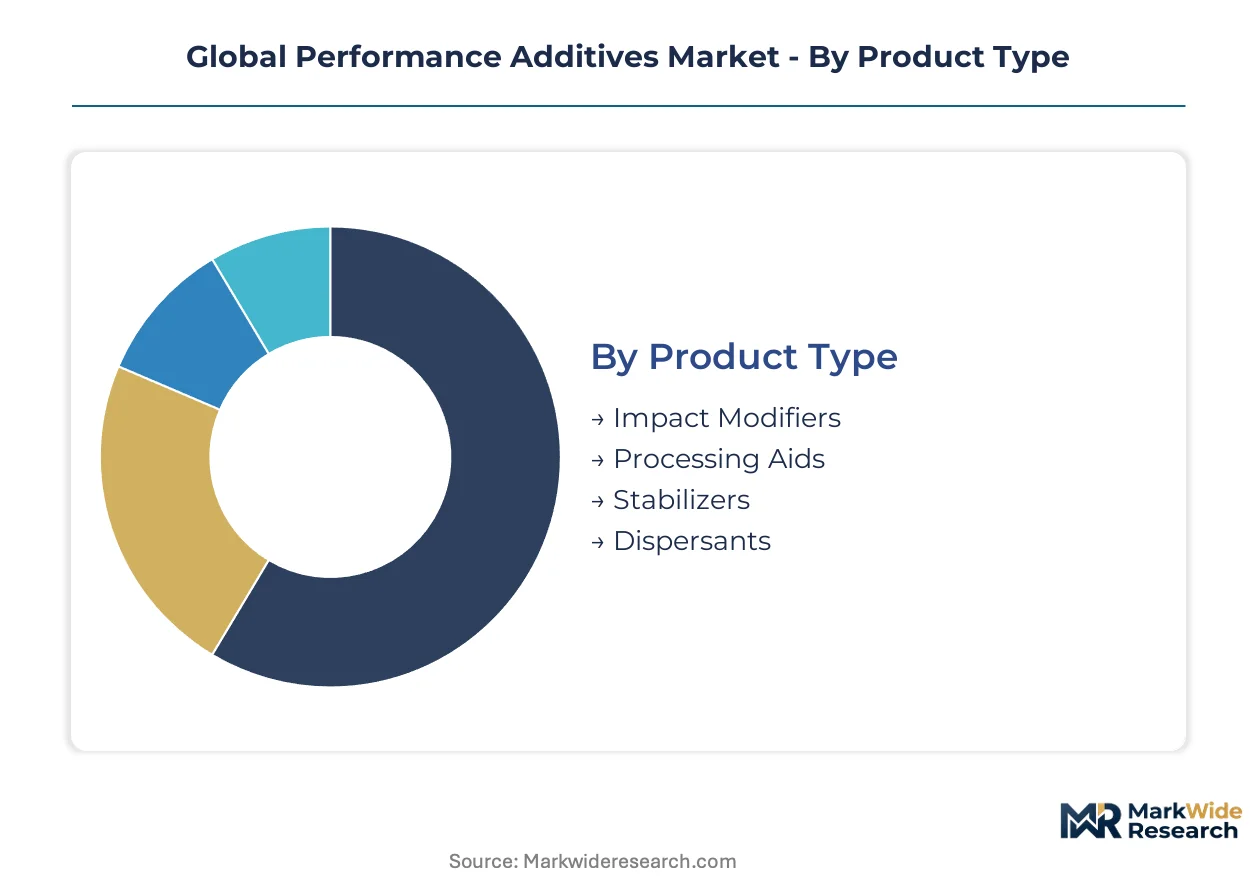
The global performance additives market differentiates across various dimensions, reflecting the specialized demands of diverse end-use applications. Understanding these distinct segments provides clarity on where innovation and investment are concentrating to meet evolving material science challenges.
Product Type:
Performance additive product types are characterized by their primary chemical function and material interaction.
- Impact Modifiers:These substances enhance the ductility and toughness of polymers, particularly in rigid plastics, preventing brittle fracture. Demand from the automotive sector for lightweight plastic components in electric vehicles drives significant consumption.
- Stabilizers:Compounds that protect polymers from degradation caused by heat, UV radiation, or oxidation, thereby extending product lifespan. Packaging applications utilize these extensively to maintain food integrity and extend shelf life under various environmental conditions.
- Processing Aids:These additives improve the melt flow, surface finish, and overall processability of polymers during manufacturing.
- Dispersants:Chemical agents that facilitate the uniform distribution of pigments, fillers, or other particles within a polymer matrix.
Mature deployment sits with Stabilizers. Newer deployment is concentrated in Impact Modifiers.
End Use Industry:
Consumption patterns for performance additives are primarily driven by specific application requirements within key industries.
- Automotive:Additives enhance the performance of plastic components in vehicles, improving durability, reducing weight, and meeting safety standards. The push for lightweighting in electric vehicles to improve battery range creates concentrated demand for advanced solutions.
- Packaging:This sector utilizes additives to improve material properties such as barrier protection, printability, and recyclability for both flexible films and rigid containers. Brands focused on circular economy principles increasingly seek bio-based formulations.
- Construction:Performance additives improve the mechanical strength, weather resistance, and fire safety of building materials like pipes, profiles, and insulation.
- Electronics:Additives enhance the thermal stability, flame retardancy, and electrical insulation properties of plastics used in electronic devices.
The automotive sector commands significant volumes, while electronics applications are expanding most quickly.
Formulation Type:
The physical form of performance additives reflects diverse processing needs and environmental considerations.
- Water-Based:These formulations use water as the primary solvent or carrier, reducing volatile organic compound (VOC) emissions and environmental impact. Regulatory push for sustainable coatings and adhesives drives their preference in Europe and North America.
- Powdered:Solid additive forms that are easy to blend with polymer resins during compounding, offering precise dosing and reduced handling hazards. This type is favored for its compatibility with various dry blending processes.
- Solvent-Based:Formulations where organic solvents are used as carriers, providing specific solubility and film-forming properties for demanding applications.
- Granular:Additives processed into small, uniform particles, offering dust-free handling and consistent flow properties in bulk manufacturing operations.
Water-based formulations are gaining share fastest, reflecting sustainability mandates. Powdered additives maintain consistent demand for ease of integration.
Functionality:
Specific functionalities of additives address critical performance gaps and regulatory compliance in end products.
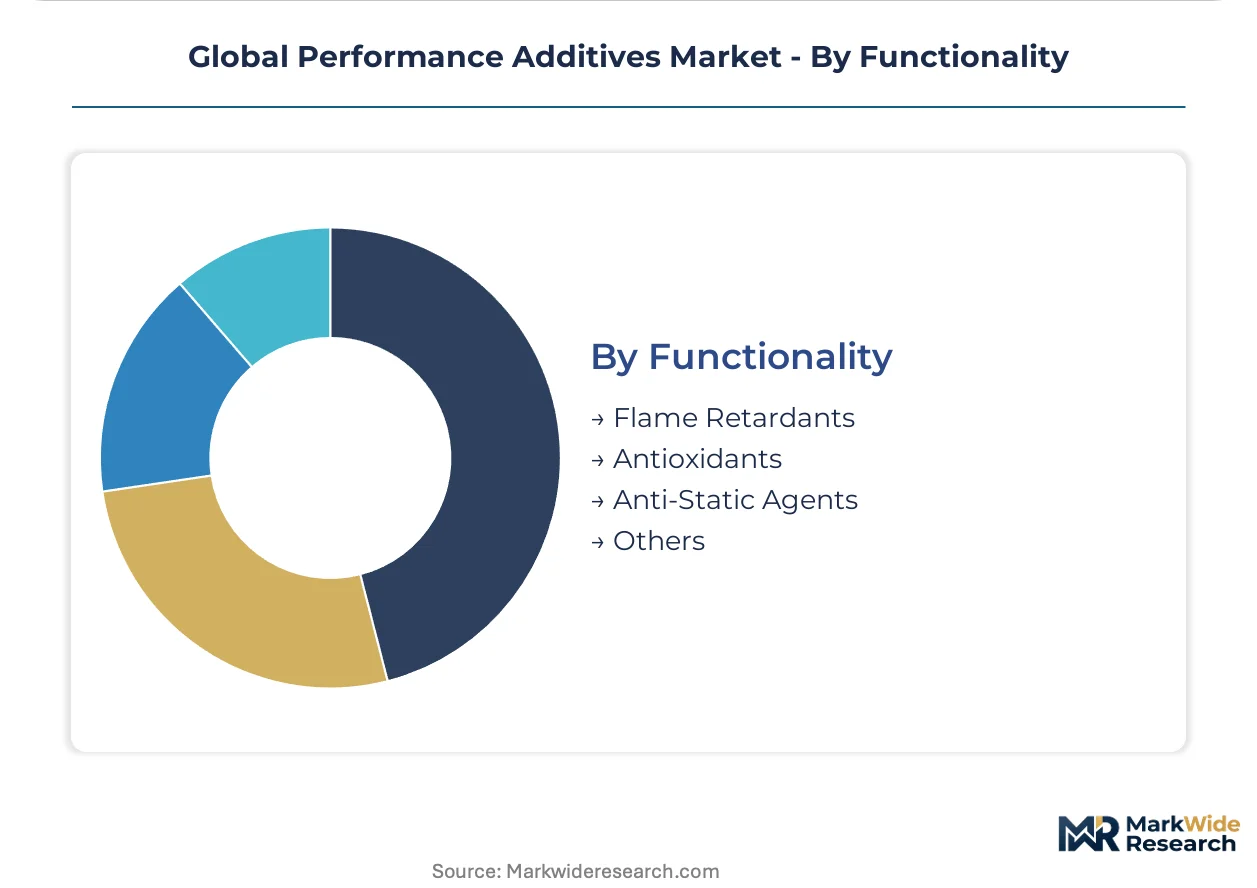
- Flame Retardants:These substances inhibit or suppress combustion, reducing the flammability of materials in electronics and building applications. Evolving fire safety codes in Europe and North America are expanding demand for non-halogenated variants.
- Antioxidants:Chemicals designed to prevent oxidative degradation in polymers caused by heat, light, or air, thereby extending material lifespan. They are crucial in packaging for food contact and automotive under-hood components.
- Anti-Static Agents:Additives that reduce the buildup of static electricity on plastic surfaces, important for sensitive electronic applications and packaging.
- Others:This broad category includes specialized additives such as UV stabilizers, optical brighteners, and anti-fogging agents, addressing niche performance requirements.
Antioxidants maintain a foundational role. Flame retardants exhibit the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial corridor connecting Shanghai and Nanjing in China leads the global performance additives market, driven by extensive manufacturing expansion. This region benefits from significant investments in advanced materials production. Demand for specialized additives is high due to robust automotive and electronics sectors.
China
Shanghai's chemical manufacturing hubs drive demand for processing aids and functional additives, supporting its vast industrial output. China's GB standards and MEE environmental protection laws govern product formulation. The Yangtze River Delta region sees concentrated demand from electronics and packaging industries.
Germany
Munich's automotive and advanced engineering sectors require high-performance impact modifiers and stabilizers for electric vehicle components. Europe's REACH regulations compel manufacturers to adopt sustainable formulations. The Rhine-Main region focuses on developing bio-based additive solutions.
United States
The Detroit automotive cluster fuels demand for lightweight plastics and advanced flame retardants in new vehicle designs. The US EPA's Toxic Substances Control Act dictates chemical safety and market access. Texas's petrochemical industry contributes significantly to domestic production and consumption.
Japan
Nagoya's automotive industry and Tokyo's electronics manufacturing centers are key consumers of thermal stabilizers and anti-static agents. Japan's METI policies encourage innovation in sustainable materials. The Kansai region specializes in high-performance additives for niche applications.
India
The manufacturing clusters in Pune and Chennai drive demand for additives in automotive and construction sectors due to rapid industrialization. India's PLI scheme promotes local production, increasing the need for processing aids. Gujarat's chemical industry is expanding, creating a focal point for regional consumption.
Global Performance Additives Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share in performance additives. The market structure exhibits consolidation among established chemical giants, alongside fragmentation with numerous specialized formulators. Strategic archetypes include integrated chemical conglomerates, niche solution providers, and regional specialists. Companies pursue capacity expansion and strategic partnerships to broaden their market reach.
Within the integrated chemical conglomerate tier, BASF SE and Dow exemplify companies leveraging vast R&D infrastructure and global manufacturing scale. BASF SE offers tailored solutions for complex end-use applications, showcasing its deep technical expertise in polymer science. Dow competes on its extensive global manufacturing footprint and broad portfolio integration, serving diverse industries from packaging to automotive. Evonik Industries AG occupies a position as a niche solution provider, specializing in high-performance additives for specific, high-value markets. These companies collectively anchor the market with their extensive product offerings and custom formulation capabilities, influencing material performance across various sectors and setting industry benchmarks.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Clariant |
| Solvay |
| Arkema |
| Dow |
| LANXESS |
| Akzo Nobel N.V. |
| Lubrizol Corporation |
| Others |
Cost & Logistics Intelligence
Automotive OEMs and electronics manufacturers are shifting away from transactional purchasing towards collaborative co-development, anchoring pricing to custom formulation support and long-term material performance outcomes.
Pricing Analysis
Value-based pricing, tied directly to enhanced product durability and processing efficiency, defines the performance additives market. Price differentiation stems from the customization level offered and the specific regulatory certifications achieved, such as REACH or TSCA compliance. Pricing softness reflects volatility in petrochemical feedstock prices and the increasing complexity of navigating disparate regulatory frameworks. The packaging sector, often driven by cost, exhibits higher price sensitivity compared to the automotive and electronics industries which prioritize performance.
Supply Chain Analysis
Direct partnerships between additive specialists and end-product manufacturers handle the growing demand for tailored solutions. Geographic supply concentration for performance additives centers on China's industrial corridor, Germany's advanced chemical clusters, and the US petrochemical industry in Texas. The market relies heavily on petrochemical derivatives like crude oil and natural gas. Commodity price volatility represents a significant structural risk, impacting formulation costs and margins. Distribution runs through both direct channels and specialized distributors for niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is evolving into a vertical-integration race, with players increasingly pursuing upstream control over bio-based feedstock production to secure future supply and meet sustainability mandates.
For Market Incumbents: To counter the threat of material substitution by inherently functional polymers, incumbents must accelerate investment in advanced R&D for multifunctional additives. Capacity expansion in China, particularly for processing aids, will reinforce regional market share. Investing in robust certification pathways, like those required by Europe's REACH and US EPA's TSCA, strengthens market access and defends premium positioning.
For New Entrants and Emerging Players: Digital formulation platforms offer a technology-first wedge into the market by enabling rapid prototyping and tailored solutions. White-space opportunities exist in bio-based formulations for the packaging sector and non-halogenated flame retardants for electronics. Europe's sustainable coatings market presents a penetrable segment, leveraging a go-to-market angle focused on environmental compliance and reduced VOC emissions.
For Investors and Strategic Acquirers: The window for entry favors specialized additive firms with strong intellectual property in bio-based or multifunctional technologies. Long-term viability over a 5-10 year horizon depends on deep technical expertise and strong customer co-development relationships. An acquisition target archetype includes niche solution providers with proven track records in high-growth segments like electric vehicle components. Accelerated adoption of digital formulation platforms signals market readiness for innovative, asset-light players.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Increases supply of processing aids and functional additives for regional manufacturing hubs in China and India. |
| Green Manufacturing Transition | Aligns production processes with sustainability mandates, reducing environmental footprint and appealing to eco-conscious brands. |
| Long-term Supply Agreement | Secures critical raw material inputs, mitigating exposure to feedstock price volatility and ensuring supply stability. |
| Joint Venture for Bio-based R&D | Accelerates development of sustainable additive solutions, leveraging combined expertise and shared investment risk. |
| Digital Formulation Platform Launch | Reduces product development cycles and enables rapid customization, meeting end-user demand for tailored performance. |
Research Approach
Multi-period observation of automotive lightweighting trends, regulatory compliance shifts, and bio-based material adoption anchored the trend analysis, supplemented by interviews. Primary research included discussions with technical R&D directors, procurement leads at automotive OEMs, regulatory affairs specialists, and distribution channel partners. Secondary sources such as REACH documentation, US EPA mandates, China's GB standards, and corporate sustainability reports provided external validation and context for bottom-up and top-down triangulation.
Segment-weighting across product type, end-use industry, formulation type, and functionality informed the analytical framework over the projection horizon. CAGRs were derived from historical growth patterns and projected technological shifts in polymer science and manufacturing processes. Industry-specific forecast inputs included electric vehicle production forecasts and evolving building safety code updates, influencing demand for specialized additives across key segments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of unforeseen geopolitical events or rapid material science breakthroughs. Forecasts reflect assumptions regarding raw material price stability and consistent regulatory enforcement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Cement Grinding Aid and Performance Enhancers Market
Additives
Polysorbate-80 Market
Additives
Canada Anti-Caking Market
Additives
Low-Carbon Concrete Shrinkage-Reduction Additives Market
Additives
Choline Chloride Market
Additives
Global Butylated Hydroxytoluene Market
Additives
Anti-Creasing Agent Market
Additives
Microcrystalline Cellulose (MCC) Market
Additives
Fluoropolymer Additives Market
Additives
Global Sodium Acetate Market
Additives
Plastics Modifiers Market
Additives
Global Formulation Additives Market
Additives
Material Shrinkage-reducing Agents Market
Additives
Wax Additives Market
Additives
Feedstuff Additives Market
Additives
Global Sizing Agents Market