
 Highly Reactive Polyisobutylene (HR-PIB) Market | 2026-2036
Highly Reactive Polyisobutylene (HR-PIB) Market Size, Share, and Industry Trends Forecast 2026-2036
Highly Reactive Polyisobutylene (HR-PIB) Market Analysis
Conventional polyisobutylene is decoupling from premium lubricant formulations as HR-PIB delivers superior succinic anhydride grafting efficiency at lower treat rates. Lubrizol leverages backward integration into HR-PIB feedstock to secure additive intermediate supply. INEOS anchors European volume through its Antwerp polymer complex. DAELIM Industrial Co. Ltd. dominates Asian merchant supply with dedicated HR-PIB trains at its Yeosu facility.
Highly reactive polyisobutylene denotes a terminally unsaturated polymer with vinylidene content exceeding 80 percent, produced via cationic polymerization in liquid-phase reactors to enable direct functionalization without prior depolymerization. Its primary purpose centers on manufacturing ashless dispersants and viscosity modifiers for crankcase lubricants, plus sealant and adhesive modifiers where reactive end-groups enable crosslinking. Low molecular weight grades command the largest volume share in lubricant additive applications, while rubber-grade variants represent the fastest-expanding margin pool as tire makers adopt solution-based processing. Liquid-phase production technology concentrates among integrated petrochemical operators who control both feedstock butene streams and polymerization catalyst supply.
EPA fuel economy standards tighten lubricant performance benchmarks, pushing OEMs toward lower-viscosity oils that rely on HR-PIB-derived dispersants for deposit control. REACH registration requirements in Europe impose substance identity thresholds that favor producers with analytical capabilities to certify vinylidene content above 85 percent. China's GB standards for gasoline engine oils incorporate dispersancy tests that HR-PIB additives pass more reliably than conventional PIB alternatives. Stakeholders must track how evolving OEM factory-fill specifications and regional chemical registration deadlines reshape supplier qualification timelines.
Market Dynamics
REACH compliance in Europe is compressing molecular-weight thresholds for sealant-grade HR-PIB formulations, forcing producers to recertify substance identity at vinylidene content above 85 percent while lubricant blenders in China simultaneously expand captive additive capacity.
Growth Catalysts
- EPA Fuel Economy Standards:Tightening benchmarks push OEMs toward lower-viscosity crankcase oils that require HR-PIB-derived dispersants for deposit control, expanding factory-fill specification adoption.
- China GB Standards:National gasoline engine oil protocols incorporate dispersancy tests that HR-PIB additives pass more reliably than conventional PIB alternatives, biasing blender procurement.
- Solution-Based Tire Processing:Rubber-grade HR-PIB variants enable crosslinking in tire manufacturing without depolymerization steps, accelerating adoption among tire makers transitioning from emulsion processes.
Market Restraints
- Isobutylene Feedstock Volatility:C4 stream availability fluctuates with ethylene cracker operating rates, exposing polymerization economics to olefin market cycles beyond producer control.
- Antwerp Supply Concentration:European volume anchors at a single integrated polymer complex, creating geographic vulnerability to regional logistics disruptions or unplanned maintenance events.
- Conventional PIB Substitution:Lower-cost, lower-reactivity PIB grades retain share in non-dispersant applications where terminal unsaturation delivers marginal performance benefit.
Strategic Opportunities
- India Lubricant Blending Expansion:Domestic capacity growth among state-owned oil marketing companies creates merchant HR-PIB demand as additive formulators localize production under PLI scheme incentives.
- Adhesive Crosslinking Applications:Reactive end-group chemistry enables sealant modifiers for construction and automotive assembly, opening volume outside traditional lubricant channels.
- Carbon Border Adjustment Mechanism:EU CBAM implementation favors producers with verified low-carbon cationic polymerization processes, rewarding integrated operators with feedstock-to-polymer carbon accounting.
Industry Challenges
- Analytical Certification Bottlenecks:REACH substance identity thresholds demand specialized chromatographic capabilities to certify vinylidene content above 85 percent, constraining qualification timelines for smaller merchant suppliers.
- Catalyst Supply Concentration:Liquid-phase cationic polymerization relies on proprietary Lewis acid systems controlled by integrated petrochemical operators, limiting technology access for independent market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Highly Reactive Polyisobutylene (HR-PIB) Market |
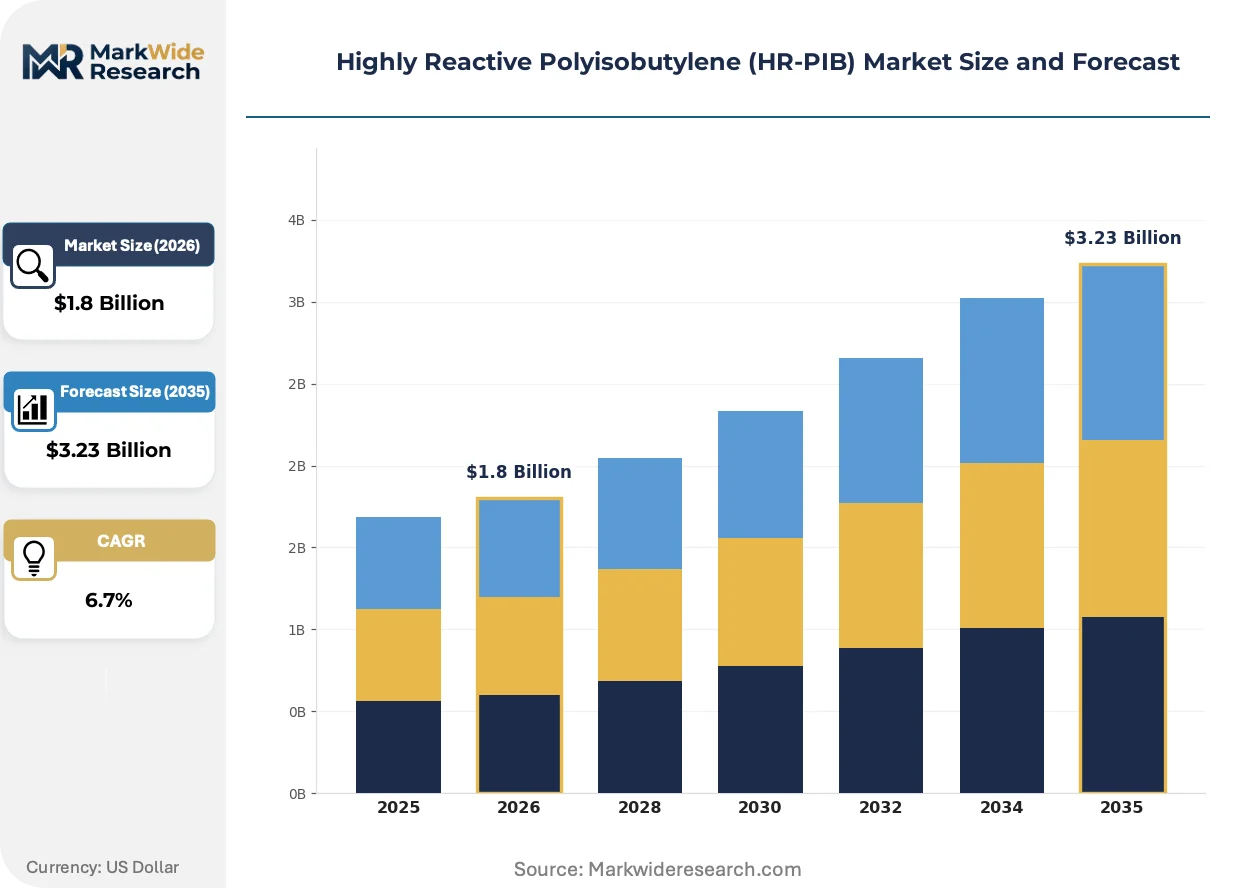
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Molecular Weight, High Molecular Weight, Liquid-Phase, Rubber-Grade End Use Industry: Automotive, Construction, Adhesives, Coatings Packaging Type: Drums, Bags, Bulk Containers, Pails Application: Sealants, Lubricants, Binders, Elastomers |
| Companies Covered | Lubrizol, DAELIM Industrial Co. Ltd., TPC Group, Zhejiang Shunda New Material Company Ltd., Chevron, RB Products Inc., INEOS, KEMAT Polybutenes, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Highly Reactive Polyisobutylene (HR-PIB) Market Emerging Trajectories
Functionalization chemistry and regulatory substance identity requirements are compressing the technology gap between conventional and highly reactive PIB grades, while procurement patterns among lubricant blenders shift toward backward-integrated additive supply.
Liquid-phase cationic polymerization with controlled chain-transfer agents is consolidating as the dominant production pathway for terminally unsaturated HR-PIB. Tire manufacturers adopting solution-based rubber processing are absorbing expanded rubber-grade capacity at the fastest clip. This technology consolidation is compressing the addressable market for older gas-phase processes that cannot achieve vinylidene content above 80 percent without downstream depolymerization.
REACH registration deadlines in Europe impose substance identity thresholds that favor producers with in-house analytical capabilities to certify vinylidene content above 85 percent. The industrial consequence is a bifurcation between integrated operators who control both catalyst supply and certification infrastructure versus merchant suppliers dependent on third-party testing. Sealant-grade formulations face the tightest compliance pressure, with producers in Antwerp and Yeosu investing in dedicated analytical laboratories to maintain registration validity.
Blender procurement is gravitating toward long-term offtake agreements with integrated HR-PIB producers rather than spot-market merchant purchases. Major lubricant formulators in China and the US are locking in additive intermediate supply directly at the polymer train level, displacing traditional distributor channels. This channel compression is most visible in Asia-Pacific, where domestic capacity expansion allows blenders to bypass historical merchant import dependencies.
Highly Reactive Polyisobutylene (HR-PIB) Market Segmentation
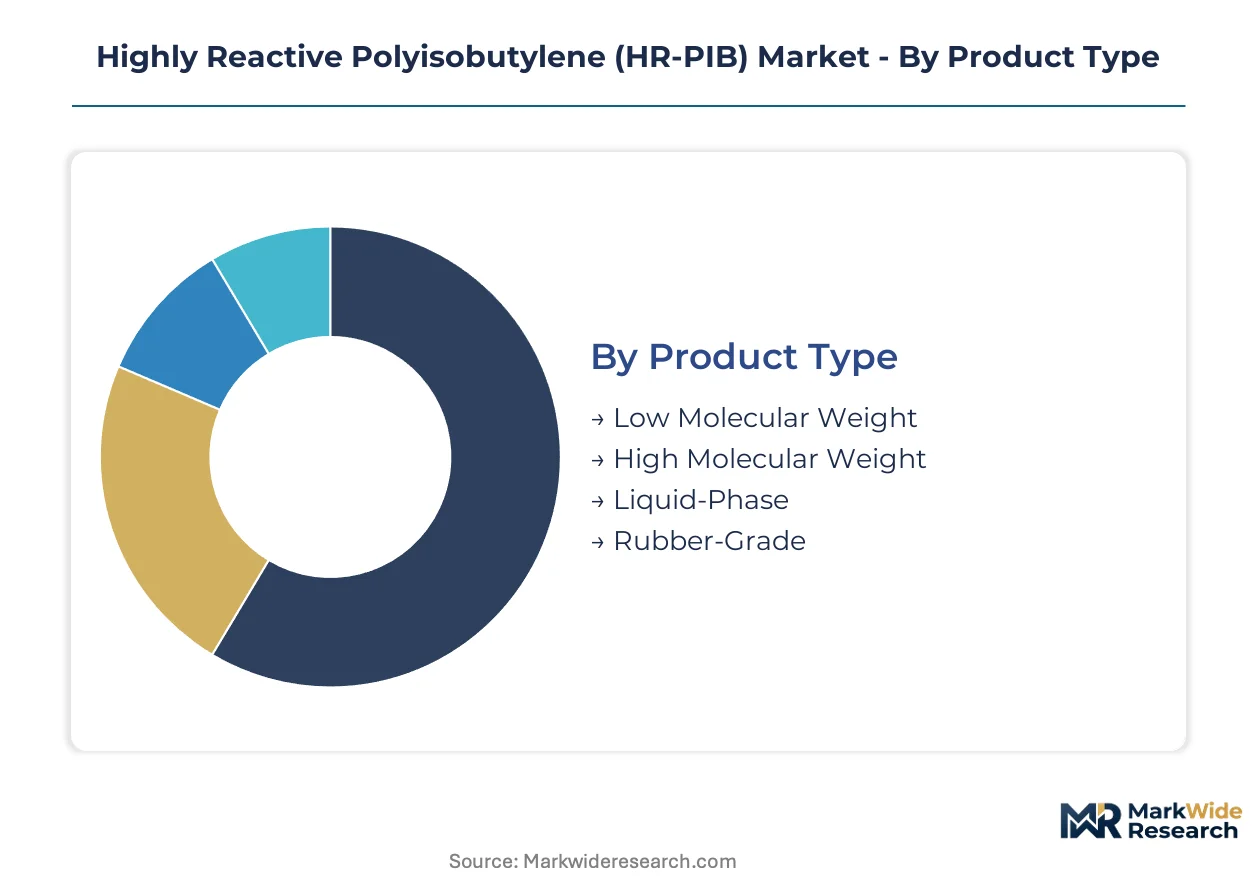
Segmentation in HR-PIB markets reflects the tension between standalone functionalization and embedded additive systems. Product architecture determines whether polymers ship as merchant intermediates or integrate directly into captive additive trains.
Product Type:
Integration depth varies sharply across molecular architectures, with some grades engineered for immediate downstream reaction and others requiring preprocessing.
- Low Molecular Weight:Terminally unsaturated chains below 1000 daltons enable direct succinic anhydride grafting without depolymerization. Lubricant additive manufacturers in China absorb the largest volumes as domestic blenders expand captive dispersant capacity.
- High Molecular Weight:Extended polymer chains above 5000 daltons demand specialized catalyst systems for controlled chain transfer. Demand concentrates in European sealant applications where REACH substance identity thresholds above 85 percent vinylidene content constrain supplier qualification.
- Liquid-Phase:Produced via cationic polymerization in continuous reactors with Lewis acid catalysts, this grade dominates merchant supply channels.
- Rubber-Grade:Engineered for solution-based tire processing with reactive end-group crosslinking chemistry.
Low Molecular Weight leads volumes today; Rubber-Grade is gaining share fastest.
End Use Industry:
Cost tier stratification separates premium-specification applications from commodity absorption channels.
- Automotive:Crankcase lubricant formulations consume HR-PIB dispersants for deposit control in lower-viscosity factory-fill oils. EPA fuel economy standards tighten performance benchmarks, pushing OEM procurement toward higher-vinylidene grades.
- Construction:Sealant and adhesive modifiers leverage reactive end-group chemistry for crosslinking in structural bonding applications. Demand clusters in urban infrastructure projects across China and India.
- Adhesives:Pressure-sensitive and structural adhesive formulators value terminal unsaturation for grafting efficiency.
- Coatings:Protective and industrial coating applications employ HR-PIB as binder modifiers for enhanced adhesion and weathering resistance.
Automotive commands the largest revenue pool; Construction is expanding most quickly.
Packaging Type:
Volume scale and handling economics dictate packaging selection across merchant and captive supply chains.
- Drums:Standard 200-liter steel drums serve mid-scale additive formulators with batch processing requirements. European distributors favor drum packaging for REACH-registered material traceability.
- Bags:Multi-layer polymer bags accommodate solid-grade rubber-PIB for tire compounders with automated handling systems.
- Bulk Containers:ISO tank containers and flexitanks move liquid-phase grades from integrated polymer trains directly to blender facilities.
- Pails:Smaller-volume pails target specialty adhesive and sealant compounders with limited storage infrastructure.
Bulk Containers dominate integrated supply chains; Drums retain the broadest merchant penetration.
Application:
Supply concentration in integrated petrochemical operators shapes application-specific availability and pricing structures.
- Sealants:Reactive end-groups enable moisture-cure crosslinking in construction and automotive assembly sealants. REACH compliance in Europe compresses molecular-weight thresholds, forcing recertification of sealant-grade formulations at elevated vinylidene content.
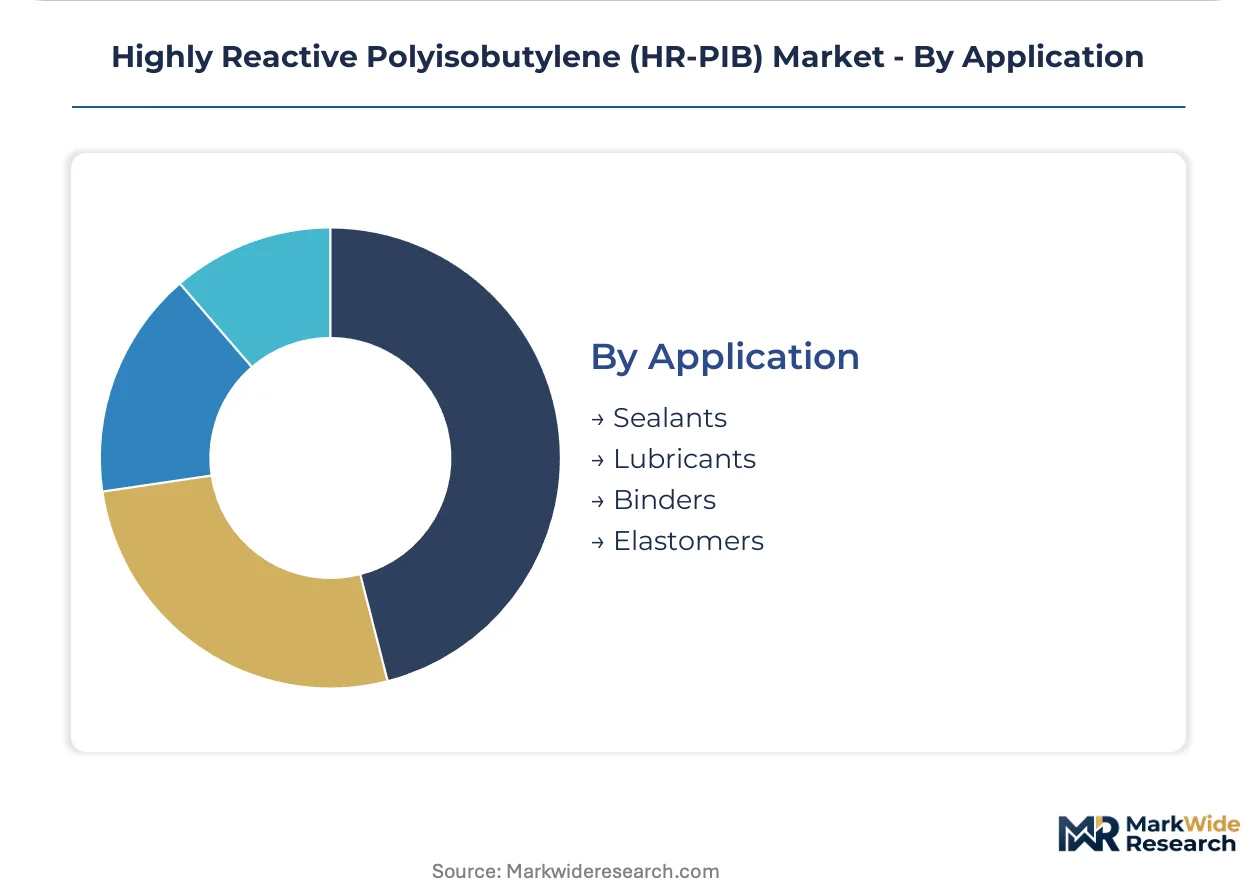
- Lubricants:Ashless dispersants and viscosity modifiers for crankcase oils represent the foundational demand anchor. China's GB standards incorporate dispersancy tests that bias blender procurement toward HR-PIB over conventional PIB alternatives.
- Binders:Adhesive and coating binder applications exploit grafting efficiency for polymer modification.
- Elastomers:Tire manufacturers adopting solution-based processing absorb rubber-grade HR-PIB for crosslinking without depolymerization steps.
Lubricants anchor volume today; Elastomers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yeosu petrochemical cluster anchors Asian HR-PIB supply, with integrated polymer trains serving lubricant additive manufacturers across East Asia. Regional demand patterns diverge sharply between mature regulatory environments and capacity-expansion markets.
China
Domestic lubricant blenders in Ningbo and Shanghai expand captive additive capacity under GB standards that favor HR-PIB dispersants for gasoline engine oil certification. MIIT industrial policy prioritizes import substitution in specialty chemicals. The Yangtze River Delta concentrates new polymerization capacity as state-owned oil companies backward-integrate into additive intermediates.
United States
EPA fuel economy standards tighten factory-fill specifications for lower-viscosity crankcase oils, expanding HR-PIB consumption at Gulf Coast lubricant compounders. The Houston Ship Channel corridor hosts integrated petrochemical operators controlling C4 feedstock streams. Texas and Louisiana polymer complexes supply dispersant manufacturers serving Detroit-area OEM procurement.
Germany
REACH substance identity thresholds above 85 percent vinylidene content constrain sealant-grade formulation supply, favoring producers with in-house analytical certification. The Antwerp-Rotterdam-Rhine-Ruhr corridor concentrates European HR-PIB volume at integrated polymer facilities. Baden-Württemberg automotive suppliers drive specification adoption for next-generation lubricant systems.
India
State-owned oil marketing companies expand domestic lubricant blending capacity under PLI scheme incentives, creating merchant HR-PIB demand for additive formulators localizing production. The Gujarat chemical belt attracts polymerization investments serving Mumbai-Pune industrial corridors. Reliance Industries and public sector refiners anchor procurement concentration in western India.
Japan
METI energy efficiency standards for automotive lubricants bias blender procurement toward high-vinylidene dispersant grades. The Chubu-Nagoya petrochemical complex maintains specialized HR-PIB production for domestic tire and sealant manufacturers. Kansai-based adhesive compounders absorb rubber-grade volumes for automotive assembly applications.
Highly Reactive Polyisobutylene (HR-PIB) Market Vendor Landscape
Global majors compete with regional champions across feedstock access and certification infrastructure, producing a tiered structure where integrated petrochemical operators hold supply-side leverage. The vendor base stratifies between captive producers serving affiliated additive businesses and merchant suppliers dependent on spot C4 feedstock markets. Three archetypes dominate: integrated oil majors with backward-integrated polymer trains, Asian petrochemical conglomerates with dedicated HR-PIB units, and European specialty chemical houses with analytical certification capabilities. Competitive moves concentrate on capacity expansion in high-growth Asian markets and strategic partnerships to secure long-term offtake agreements with lubricant blenders.
Among integrated petrochemical operators, INEOS exemplifies the European archetype with Antwerp-based polymer complex concentration, while DAELIM Industrial Co. Ltd. anchors Asian merchant supply from its Yeosu facility. Lubrizol represents the backward-integrated additive house model, securing feedstock-to-dispersant control across North American and Asian markets. These three companies occupy positions that reflect the industry's structural dependence on both C4 feedstock access and downstream additive formulation relationships.
| Leading Market Players |
|---|
| Lubrizol |
| DAELIM Industrial Co. Ltd. |
| TPC Group |
| Zhejiang Shunda New Material Company Ltd. |
| Chevron |
| RB Products Inc. |
| INEOS |
| KEMAT Polybutenes |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Lubricant additive manufacturers in China and the United States concentrate procurement power through long-term offtake agreements, locking in contract-based pricing structures that insulate integrated producers from spot C4 feedstock volatility while exposing merchant suppliers to margin compression.
Pricing Analysis
Isobutylene cost pass-through from ethylene cracker operating rates anchors the dominant pricing model, with contract-based long-term offtake structures commanding premium stability over spot-market transactions. Price differentiation separates REACH-certified grades above 85 percent vinylidene content from standard merchant supply, with certification level and volume scale as primary tiering drivers. Pricing pressure intensifies as conventional PIB grades retain share in non-dispersant applications where terminal unsaturation delivers marginal performance benefit. Small-batch sealant compounders exhibit highest price sensitivity, while integrated lubricant blenders with captive additive capacity demonstrate lowest sensitivity due to backward integration economics.
Supply Chain Analysis
Freight costs from the Antwerp-Rotterdam-Rhine-Ruhr corridor and the Yeosu petrochemical cluster shape landed cost structures for European and Asian buyers respectively. Geographic supply concentration centers on Belgium, South Korea, and the United States Gulf Coast, with raw material dependencies on C4 raffinate streams, proprietary Lewis acid catalyst systems, and analytical certification infrastructure. Single-source vulnerability at the Antwerp polymer complex creates structural exposure to unplanned maintenance or regional logistics disruptions. Distribution runs through direct polymer-train-to-blender bulk containers for integrated operators, while merchant channels rely on drum-packaged material through distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HR-PIB market represents a late-cycle quality story as EPA fuel economy standards and REACH substance identity thresholds simultaneously shift blender procurement toward premium vinylidene grades above 85 percent.
For Market Incumbents: Acquire analytical certification laboratories to secure REACH registration validity as substance identity thresholds tighten, while expanding rubber-grade capacity to capture tire manufacturer demand from solution-based processing transitions. Threat of conventional PIB substitution in non-dispersant applications demands defensive grade differentiation through in-house chromatographic capabilities. Backward integration into C4 feedstock streams remains the critical lever for margin defense against isobutylene price volatility. For New Entrants and Emerging Players: REACH registration deadlines in Europe open a window for specialized analytical service providers supporting smaller merchant suppliers through qualification bottlenecks. The most penetrable white space sits in sealant-grade formulations for construction applications across India and Southeast Asia, where GB-style dispersancy standards have not yet fully propagated. A technical partnership with established catalyst suppliers offers the strongest go-to-market angle given proprietary Lewis acid system concentration. For Investors and Strategic Acquirers: Integrated lubricant additive houses are the most active acquirer in this space, seeking captive HR-PIB supply to secure dispersant intermediate availability. Long-term viability rests on the durability of lower-viscosity crankcase oil specifications across multiple regulatory jurisdictions. Acquisition targets should display verified low-carbon cationic polymerization processes ahead of EU CBAM implementation. The signal to monitor is OEM factory-fill specification adoption rates for next-generation lubricant systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C4 Feedstock | Secures isobutylene supply for polymerization economics independent of spot olefin markets. |
| REACH Analytical Certification Investment | Enables substance identity verification above 85 percent vinylidene content for European sealant-grade registration. |
| Rubber-Grade Capacity Expansion | Captures tire manufacturer demand from solution-based processing transitions away from emulsion methods. |
| Long-Term Offtake Agreements with Blenders | Locks in volume commitments from Chinese and US lubricant formulators expanding captive additive capacity. |
| Low-Carbon Polymerization Process Verification | Positions integrated operators for EU CBAM compliance through feedstock-to-polymer carbon accounting. |
Methodological Framework
Bottom-up lubricant additive modeling reconciled against top-down polymerization capacity tracking forms the analytical core of this study. Primary interviews with plant managers at integrated petrochemical complexes, procurement leads at downstream lubricant blenders, distribution channel partners, and technical R&D directors in catalyst systems provided operational validation. Secondary sources included customs and trade flow data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and REACH registration databases maintained by ECHA.
Input-output matrices mapping isobutylene feedstock availability against HR-PIB polymerization yields and downstream dispersant absorption generated volume and value estimates across the projection horizon. Segmentation dimensions encompassed molecular weight tier, end-use industry, packaging format, and regional production hub. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific forecast inputs incorporated EPA fuel economy standard implementation timelines and MIIT industrial policy directives on specialty chemical import substitution.
Revisions become necessary when ethylene cracker operating rates shift materially, REACH substance identity thresholds tighten beyond current certification capabilities, or OEM factory-fill specifications diverge from modeled adoption curves. Forecasts reflect documented assumptions on catalyst yield improvements and blender backward integration rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Acrylic Styrene Acrylonitrile Resin Market
Polymers & Resins
Amorphous Polyolefin Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
Thermoplastic Polyolefin Market
Polymers & Resins
Polyethylene Furanoate (PEF) Barrier Resin Market
Polymers & Resins
Europe Polyolefin Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
Lactic Acid and Polylactic Acid Market
Polymers & Resins
Polyetherketone Market
Polymers & Resins
Africa Polyamide Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
Virgin Resin Market
Polymers & Resins
Photocurable Resins Market
Polymers & Resins
Water-Borne Epoxy Resins Market
Polymers & Resins
1-Hexene Based Polyethylene Market
Polymers & Resins
South America Epoxy Resins Market