
 Polycarboxylate Ethers (Pces) Market | 2026-2036
Polycarboxylate Ethers (Pces) Market Size, Share, and Industry Trends Forecast 2026-2036
Polycarboxylate Ethers (Pces) Market Analytics
Capital-intensity divergence between integrated polymer producers and formulation specialists is rotating competitive advantage toward backward-integrated players. BASF SE leverages captive ethylene oxide supply chains to control raw material costs across European and Asian plants. Sika AG anchors its position through construction-channel density and on-site technical service networks. Mapei S.P.A. differentiates via specialized formulations for tunneling and precast concrete segments where performance premiums persist.
Polycarboxylate ethers are comb-shaped copolymers with polyethylene glycol side chains grafted onto polymethacrylic acid backbones, typically synthesized through free-radical aqueous polymerization at controlled temperatures to achieve target molecular weights of 20,000–70,000 g/mol. These superplasticizers disperse cement particles through steric hindrance, enabling high-performance concrete with water-to-cement ratios below 0.30 while maintaining workability for over two hours. Liquid formulations dominate volume flows due to ease of dosing at ready-mix plants, though powder grades command margin premiums in dry-mix mortar applications where logistics costs favor solid form factors. Water reducer functionality captures the largest share of value given its centrality to commercial and infrastructure concrete specifications, while retarder variants are gaining share in hot-climate pours and mass concrete placements where thermal cracking control is critical.
REACH registration requirements in Europe govern monomer residuals and environmental fate testing for PCE imports, while China's GB 8076 standard sets minimum water-reduction ratios and slump-retention benchmarks for domestic admixture certification. India's BIS marking scheme enforces quality consistency for infrastructure-tender eligibility, creating compliance barriers for unqualified suppliers. Stakeholders must monitor evolving low-carbon concrete codes that reward cement reduction through higher admixture dosages, as regulatory pressure on embodied carbon redefines product value propositions irrespective of raw material cost cycles.
Market Dynamics
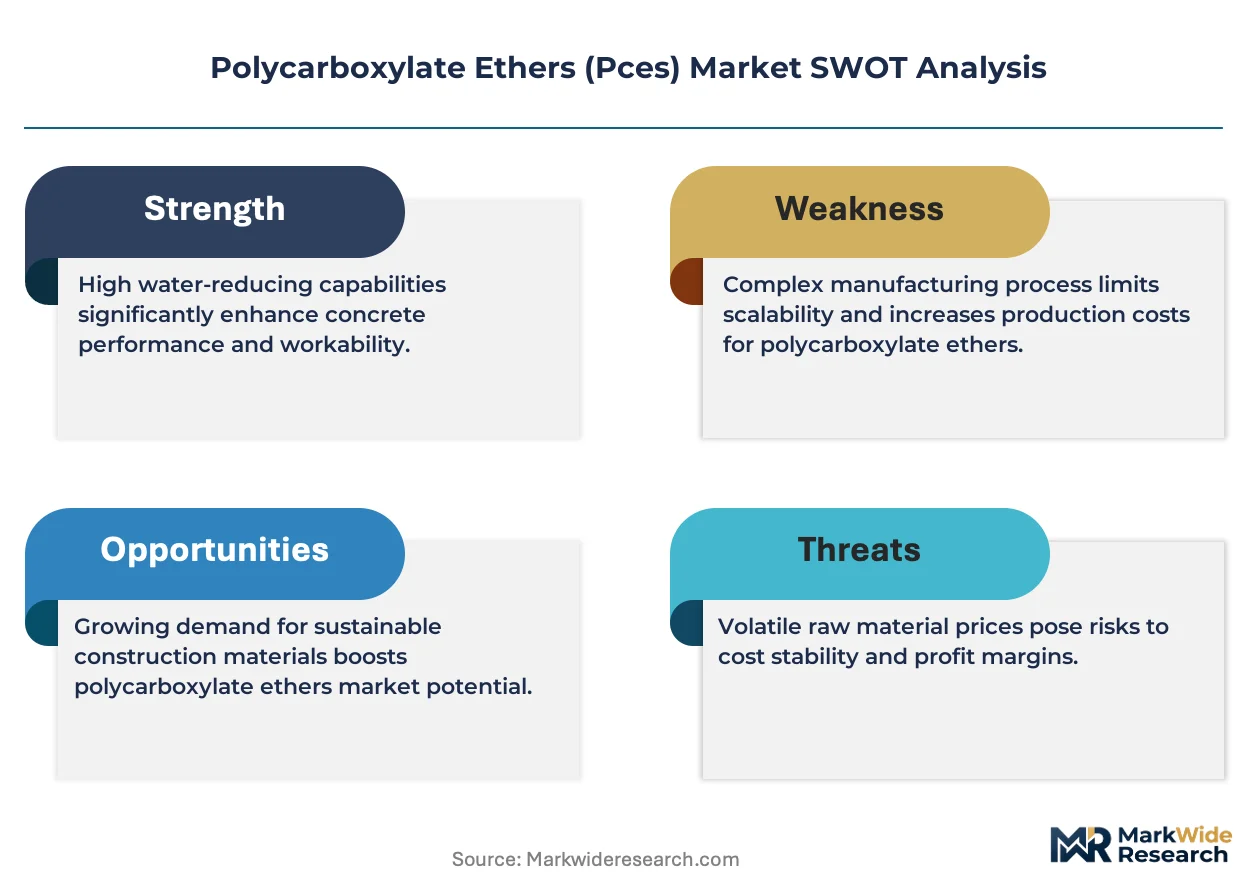
China's GB 8076 standard tightening water-reduction benchmarks is compressing margins for formulation-only suppliers while rewarding backward-integrated polymer producers with captive ethylene oxide supply.
Growth Catalysts
- GB 8076 Compliance Mandate:China's upgraded admixture certification requirements are disqualifying unqualified suppliers and consolidating procurement toward certified producers with testing infrastructure.
- Southeast Asia Infrastructure Pipeline:Construction megaprojects across Indonesia, Vietnam, and Thailand are specifying high-performance water reducers for mass concrete placements with extended workability windows.
- Low-Carbon Concrete Codes:Embodied carbon regulations in multiple jurisdictions reward cement reduction through higher PCE dosages, reframing admixtures as carbon abatement tools rather than cost inputs.
Market Restraints
- Ethylene Oxide Supply Concentration:Captive production of this critical monomer sits with integrated petrochemical majors, exposing independent formulators to feedstock volatility and allocation risk.
- REACH Registration Burden:ECHA's monomer residual and environmental fate testing requirements for PCE imports create fixed compliance costs that disproportionately burden smaller exporters.
- Alternative Superplasticizer Competition:Naphthalene and melamine-based admixtures retain cost advantage in price-sensitive ready-mix segments where specification tolerance permits.
Strategic Opportunities
- India Western Corridor Acceleration:Infrastructure investment concentration across Maharashtra and Gujarat is creating demand pockets where technical service density remains underdeveloped.
- Tunneling Specialization:Performance premiums persist in sprayed concrete and precast segments where rheology control under pressure commands formulation expertise.
- Dry-Mix Mortar Channel Expansion:Powder-grade PCE logistics advantages in remote construction sites favor solid form factors with higher margin profiles than liquid bulk.
Industry Challenges
- Polymer Synthesis Talent Scarcity:Free-radical aqueous polymerization expertise at 20,000–70,000 g/mol molecular weight targets requires specialized chemists concentrated at integrated producers.
- BIS Certification Timeline Compression:India's infrastructure-tender eligibility requirements demand quality consistency documentation that stretches smaller suppliers' analytical capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycarboxylate Ethers (Pces) Market |
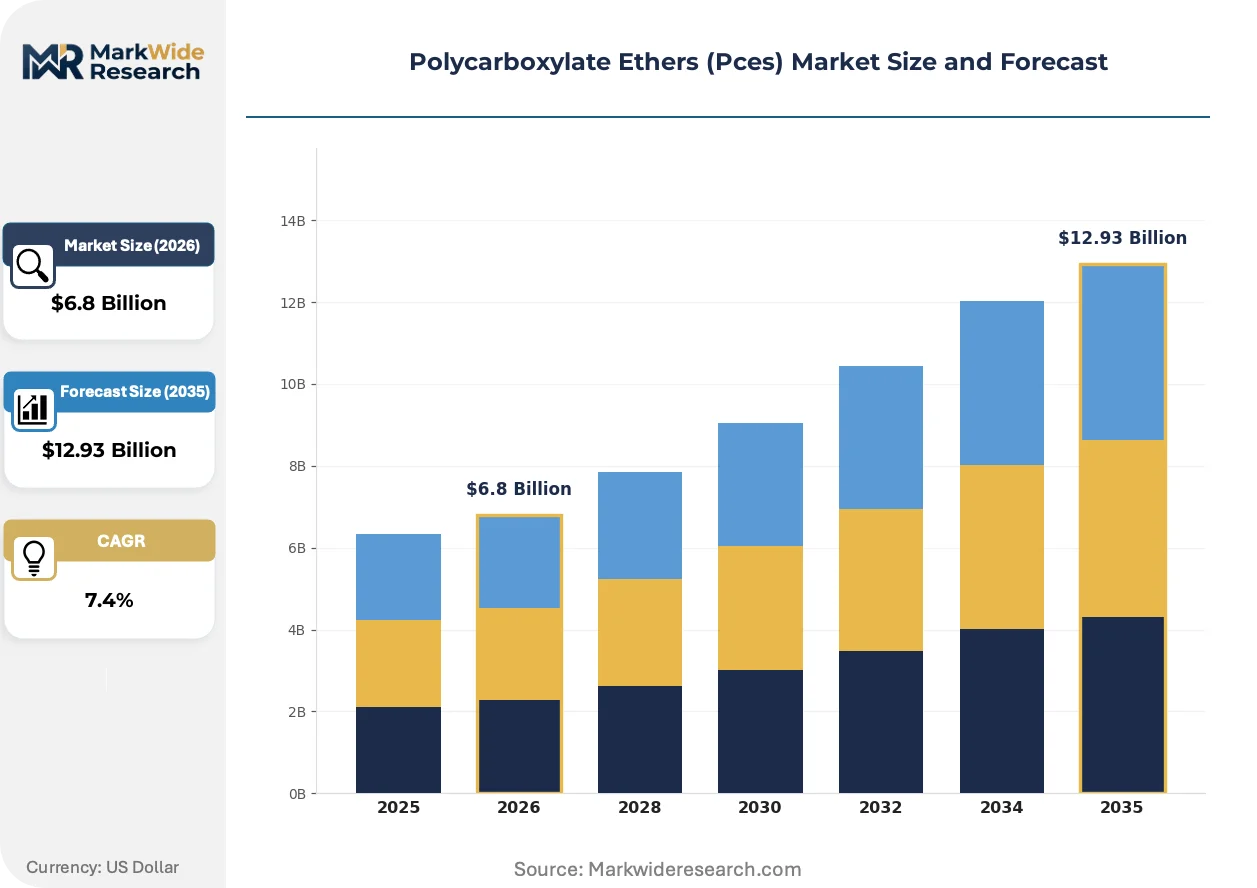
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Paste End Use Industry: Construction, Coatings, Adhesives, Textile Functionality: Dispersant, Fluidity Agent, Retarder, Water Reducer Grade: High Performance, Standard, Premium, Others |
| Companies Covered | BASF SE, Sika AG, Mapei S.P.A., Arkema SA, Fosroc International Ltd, KAO Corporation, Sakshi Chem Sciences Private Ltd, Ruia Chemicals, Euclid Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycarboxylate Ethers (Pces) Market Evolving Landscape
Formulation chemistry is pivoting toward molecular architecture optimization as regulatory pressure on embodied carbon redefines performance metrics beyond traditional water-reduction ratios.
Targeted molecular weight distribution through controlled radical polymerization is miniaturizing batch-to-batch variability in PCE performance. Precast concrete producers with automated dosing systems are adopting these grades fastest. The technology is compressing quality assurance costs for specification-critical applications.
REACH registration requirements governing monomer residuals and environmental fate testing are tightening entry barriers for non-European suppliers. ECHA's evolving substance evaluation protocols demand expanded toxicological datasets. Asian exporters with dedicated regulatory affairs teams are securing preferential access to formulation partnerships.
Specification-driven procurement is consolidating ready-mix plant supplier lists around certified producers with on-site technical service. Large infrastructure contractors are displacing spot purchasing with framework agreements linking volume commitments to performance guarantees. This pattern concentrates most visibly in India's western corridor where project scale justifies dedicated admixture engineering support.
Polycarboxylate Ethers (Pces) Market Segmentation
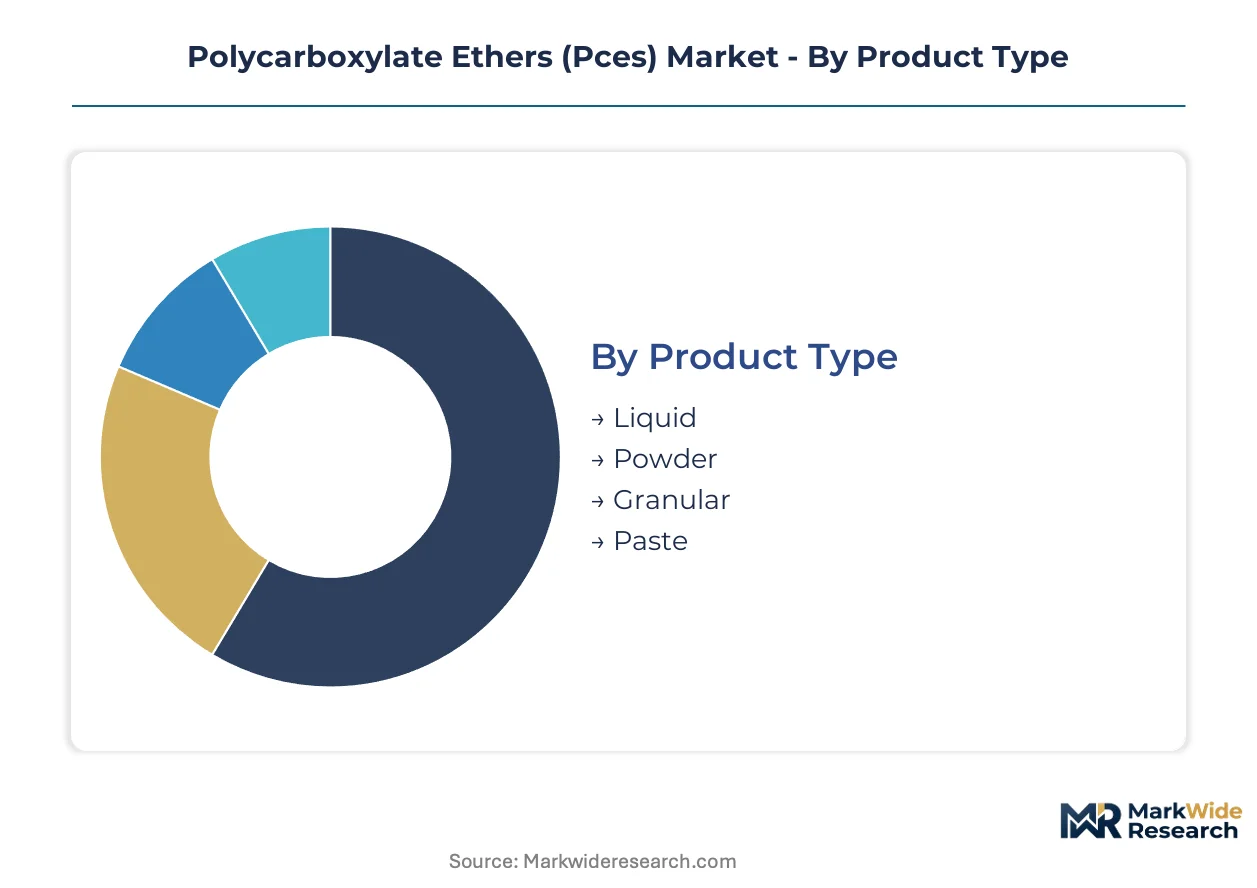
PCE segmentation maps directly to specification pressure and logistics economics. Regulatory thresholds on water-reduction ratios and embodied carbon codes are fragmenting demand across form factors and performance tiers.
Product Type:
REACH registration requirements in Europe and China's GB 8076 standard create divergent compliance burdens that favor specific physical forms in each jurisdiction.
- Liquid:Aqueous solutions with 20-40% active polymer content dominate ready-mix plant dosing through automated pumping systems. Construction megaprojects in Indonesia and Vietnam specify liquid grades for continuous pour operations where slump retention beyond two hours is mandatory.
- Powder:Spray-dried formulations with 95%+ active content command logistics advantages in remote construction zones. India's western corridor infrastructure builds favor powder for dry-mix mortar applications where water availability is constrained.
- Granular:Agglomerated solid forms with controlled dissolution rates serve precast concrete producers with batch mixing systems.
- Paste:High-viscosity concentrates target specialized tunneling applications where precise rheology control under pressure is required.
Liquid handles the majority of throughput; powder is the fastest mover on share.
End Use Industry:
Application economics separate volume-driven commodity demand from specification-critical premium placements.
- Construction:Commercial concrete, infrastructure, and precast segments absorb the bulk of PCE volume. Mass concrete placements with thermal cracking constraints specify retarder-functionalized grades.
- Coatings:Cementitious waterproofing and decorative finishes require dispersant grades with compatibility across binder chemistries.
- Adhesives:Tile adhesives and repair mortars specify fluidity agents with extended open time for trowel application.
- Textile:Dye dispersant applications in synthetic fiber processing represent a specialized outlet with distinct molecular weight requirements.
Construction anchors absolute volume; coatings is expanding most quickly as decorative concrete finishes penetrate residential markets.
Functionality:
Performance premiums concentrate where specification tolerance tightens and failure costs escalate.
- Water Reducer:Core superplasticizer functionality enabling water-to-cement ratios below 0.30 while maintaining workability. GB 8076 certification mandates minimum reduction benchmarks that disqualify substandard formulations.
- Retarder:Delayed set functionality critical for hot-climate pours and mass concrete where thermal gradients threaten cracking. Southeast Asian infrastructure specifications increasingly mandate retarder inclusion.
- Dispersant:Particle stabilization across cement, pigment, and filler systems in dry-mix and coating applications.
- Fluidity Agent:Self-leveling and self-compacting concrete enablers for complex formwork geometries.
Water reducer commands the value share; retarder is climbing the fastest as climate-adaptive specifications spread.
Grade:
Certification tiers separate tender-eligible suppliers from spot-market participants.
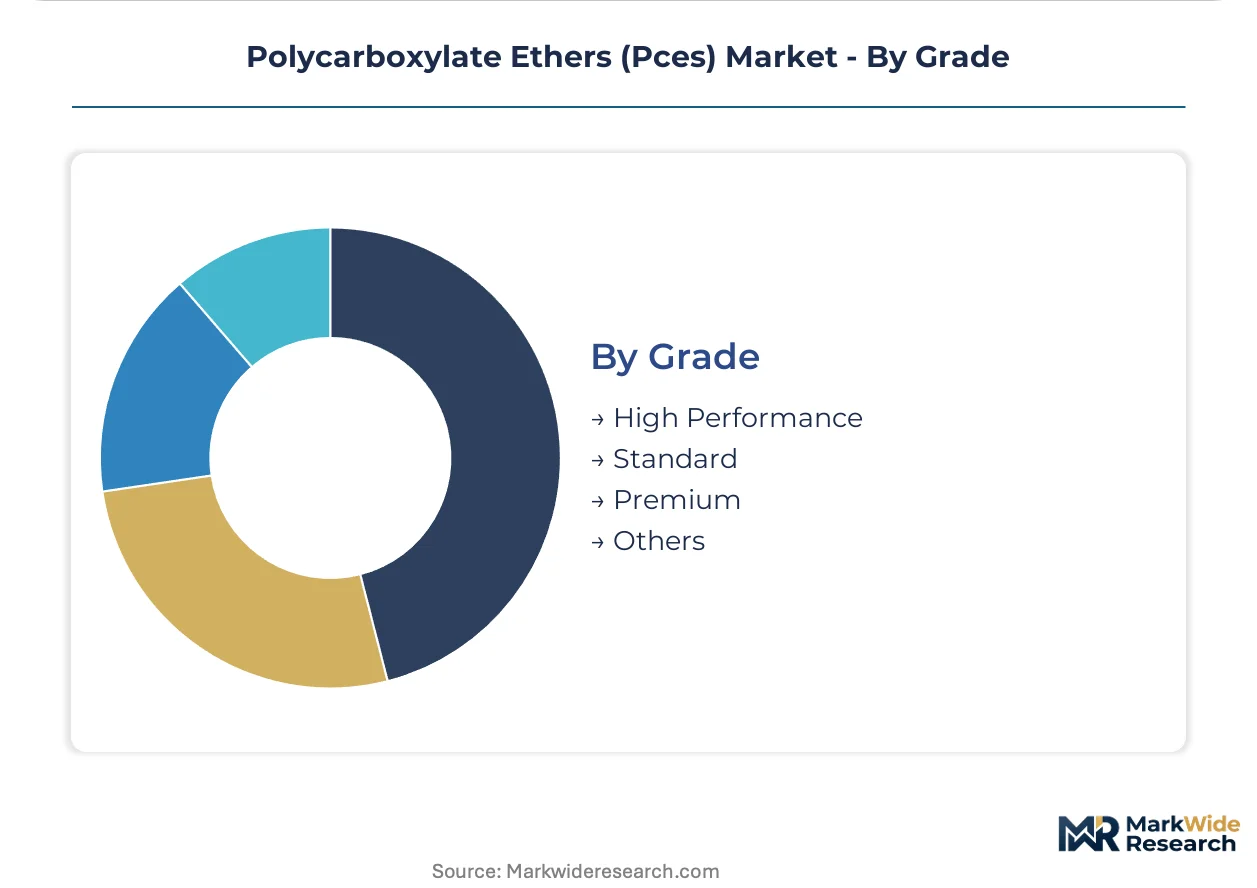
- High Performance:Molecular architectures with controlled radical polymerization achieving batch-to-batch consistency below 5% variability. Precast automated dosing systems adopt these grades for quality assurance compression.
- Premium:Specialized tunneling and sprayed concrete formulations with rheology modifiers for pressure pumping applications.
- Standard:Conventional free-radical polymerization grades serving price-sensitive ready-mix where specification tolerance permits.
- Others:Custom molecular weights and side-chain densities for proprietary customer specifications.
High performance handles the majority of certified procurement; premium is gaining share fastest in infrastructure frameworks with performance guarantees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across procurement contexts. Infrastructure tenders in India and Southeast Asia prioritize certified supply chains over unit cost, while Latin American ready-mix segments remain acutely sensitive to admixture pricing.
China
Construction megaprojects along the Yangtze River Delta absorb high-performance water reducers for extended workability. GB 8076 standard tightening disqualifies formulation-only suppliers lacking captive ethylene oxide. Shanghai's precast concrete cluster adopts molecular-architecture-optimized grades for automated dosing systems.
India
Infrastructure acceleration across Maharashtra and Gujarat concentrates demand for BIS-certified admixtures. The Bureau of Indian Standards marking scheme enforces quality consistency for tender eligibility. Mumbai's commercial high-rise pipeline specifies retarder-functionalized grades for mass concrete thermal control.
United States
Low-carbon concrete codes in California and New York reward cement reduction through higher PCE dosages. EPA environmental fate documentation requirements shape import compliance strategies. The Texas Gulf Coast petrochemical corridor supplies ethylene oxide feedstock to backward-integrated admixture producers.
Germany
REACH registration requirements govern monomer residuals and environmental fate testing for PCE formulations. ECHA substance evaluation protocols demand expanded toxicological datasets. The Rhine-Ruhr industrial zone hosts integrated polymer producers with captive ethylene oxide supply chains.
Indonesia
Jakarta-Bandung high-speed rail and new capital city construction specify liquid PCE grades for continuous pour operations. National infrastructure procurement frameworks increasingly mandate slump-retention benchmarks. Java's ready-mix plant network consolidates supplier lists around certified producers with technical service capability.
Polycarboxylate Ethers (Pces) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in polycarboxylate ethers supply. Backward-integrated polymer producers with captive ethylene oxide supply chains command margin resilience against feedstock volatility. Formulation specialists compete through construction-channel density and application-specific technical service. Strategic moves concentrate on geographic expansion into underdeveloped service territories and portfolio diversification toward powder-grade logistics advantages.
Within the integrated chemical conglomerate tier, BASF SE and Arkema SA exemplify backward-integrated positioning with upstream control over critical monomer supply. Among construction-specialist admixture suppliers, Sika AG occupies a position defined by on-site technical service networks. Mapei S.P.A. represents the formulation-focused archetype differentiated through specialized applications.
| Leading Market Players |
|---|
| BASF SE |
| Sika AG |
| Mapei S.P.A. |
| Arkema SA |
| Fosroc International Ltd |
| KAO Corporation |
| Sakshi Chem Sciences Private Ltd |
| Ruia Chemicals |
| Euclid Chemical Company |
| Others |
Value Network & Pricing Analysis
Capacity utilization at ethylene oxide crackers in the Texas Gulf Coast and Rhine-Ruhr corridor shapes margin floors across formulation tiers. Integrated producers with captive monomer supply command pricing power that independent formulators cannot match when feedstock allocation tightens.
Pricing Analysis
Technical service contracts and performance guarantees drive lifetime value beyond commodity polymer sales. Three-tier pricing structure across premium, standard, and economy levels separates certified high-performance grades from spot-market commodity offerings. Pricing pressure stems from GB 8076 compliance investments that smaller formulators cannot absorb. Infrastructure contractors show lowest price sensitivity due to performance-guarantee requirements, while Latin American ready-mix segments remain acutely cost-conscious.
Supply Chain Analysis
China and Germany anchor ethylene oxide production through integrated petrochemical complexes serving regional PCE synthesis. Formulation draws from polyethylene glycol, methacrylic acid, and initiator chemicals with concentrated specialty chemical production. Single-source vulnerability runs through ethylene oxide allocation during cracker maintenance cycles. Distribution runs through construction-channel partners with on-site dosing equipment and technical service capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among infrastructure megaproject contractors is shifting bargaining power toward certified suppliers with framework agreement capacity. Tender eligibility rules in India and Indonesia disqualify fragmented spot-market participants.
For Market Incumbents: Shield margin position through backward integration into ethylene oxide where feedstock concentration threatens allocation security. Deepen construction-channel density in India's western corridor where technical service networks remain underdeveloped against accelerating infrastructure investment.
For New Entrants and Emerging Players: BIS certification fast-track through Mumbai analytical partnerships unlocks tender eligibility in Maharashtra infrastructure builds. Target dry-mix mortar powder grades where logistics economics favor solid form factors and formulation expertise barriers are lower than liquid-grade polymer synthesis.
For Investors and Strategic Acquirers: Formulation specialists with tunneling application expertise represent acquisition targets where performance premiums persist and customer switching costs are elevated. Monitor low-carbon concrete code adoption as signal for cement-reduction admixture demand inflection across California and New York regulatory frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive ethylene oxide supply locks in margin resilience against petrochemical volatility cycles. |
| Certification Investment | GB 8076 and BIS marking schemes disqualify unqualified competitors from infrastructure tenders. |
| Technical Service Expansion | On-site admixture engineering support secures framework agreements with megaproject contractors. |
| Powder-Grade Capacity Addition | Spray-dried formulations capture logistics advantages in remote construction zones with water constraints. |
| Joint Venture | Regional production partnerships with local distributors overcome REACH registration burdens for Asian exporters. |
Research Methodology
The analysis maps liquid-grade, powder-grade, and specialty paste formulations, each validated through technical directors at ready-mix producers, procurement leads at infrastructure contractors, and regulatory affairs specialists at admixture suppliers. Primary interviews with plant managers, distribution channel partners, and construction project engineers combined with customs trade data, SEC filings of integrated chemical producers, and national standards body documentation. Bottom-up volume builds triangulated against top-down construction spending allocations.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. Segmentation dimensions modeled include product form factor, functionality tier, end-use industry vertical, and regional regulatory cluster. CAGRs derived from demand elasticity analysis relative to construction investment cycles and cement consumption trajectories. Forecast inputs incorporated ethylene oxide capacity expansion announcements and infrastructure procurement pipeline disclosures.
Decision-makers should treat outputs as directional under stable regulatory certification timelines and construction investment continuity assumptions; material deviation would warrant model refresh. Specific risks that could revise trajectories include abrupt ethylene oxide supply disruptions, accelerated low-carbon concrete code adoption beyond modeled penetration rates, and BIS certification timeline extensions. Recalibration cycles align with material shifts in infrastructure procurement frameworks and petrochemical feedstock pricing regimes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Tetrabromobisphenol a (TBBPA) Market
Specialty Chemicals
Catharanthine Market
Specialty Chemicals
Food Grade Paraffin Market
Specialty Chemicals
North America Non-Phthalate Plasticizers Market
Specialty Chemicals
Calcium D-Pantothenate Market
Specialty Chemicals
Natural Insect Repellent Market
Specialty Chemicals
Hyaluronic Acid Products Market
Specialty Chemicals
Ubiquinone Market
Specialty Chemicals
India Prussian Blue Market
Specialty Chemicals
South Korea Cleanroom Disposable Gloves Market
Specialty Chemicals
Phenyl Trimethicone Market
Specialty Chemicals
Esterquats Market
Specialty Chemicals
Anhydroxylitol Market
Specialty Chemicals
Non-Commercial Acrylic Paints Market
Specialty Chemicals
Zinc Ricinoleate Market
Specialty Chemicals
Monomethyl Acetoacetamide Market