
 Petroleum Jelly Market | 2026-2036
Petroleum Jelly Market Size, Share, and Industry Trends Forecast 2026-2036
Petroleum Jelly Market Intelligence
Capital-intensity divergence between integrated refiners and specialty blenders is bifurcating competitive returns in petroleum jelly production. Exxon Mobil Corporation leverages captive crude streams and downstream integration to sustain cost-advantaged pharmaceutical-grade output. Sonneborn LLC anchors its position through specialized refining capabilities that differentiate on color stability and low-polycyclic-aromatic-hydrocarbon specifications for cosmetic applications.
Petroleum jelly is a semi-solid mixture of hydrocarbons derived from petroleum refining, with melting points typically ranging from 38°C to 60°C and viscosity controlled through selective dewaxing and hydrogenation processes; it functions primarily as an occlusive barrier, lubricant, and moisture-retention vehicle across industrial and consumer formulations. Pharmaceutical-grade material commands premium positioning due to USP compliance burdens and batch-certification requirements that constrain supply elasticity. Cosmetic-grade volumes dominate absolute consumption but face margin compression from natural-alternative substitution in skin-care and hair-care channels across European and North American personal-care manufacturers.
FDA pharmaceutical cGMP standards, REACH substance-registration thresholds, and India's BIS certification mandates collectively elevate compliance costs for new market entrants while reinforcing incumbent quality hierarchies. The EU F-Gas Regulation indirectly affects petroleum-jelly-adjacent aerosol propellant formulations in cosmetic packaging, redirecting some lubricant demand toward pump-dispensed jar formats. Stakeholders must monitor evolving pharmacopeial monograph revisions and regional purity-grade harmonization to anticipate specification-driven contract migrations between integrated refiners and specialty compounders.
Market Dynamics
Pharmaceutical-grade purity mandates are compressing supply elasticity as integrated refiners absorb hydrogenation and dewaxing capacity expansion costs to meet tightening USP and REACH specifications for low-polycyclic-aromatic-hydrocarbon output.
Growth Catalysts
- Pharmaceutical cGMP enforcement:FDA batch-certification requirements for topical excipients are locking in long-term contracts between compounders and certified refiners, stabilizing offtake volumes.
- India PLI scheme incentives:Domestic pharmaceutical excipient production subsidies are accelerating local petroleum jelly consumption for ointment and cream manufacturing.
- Occlusive barrier functionality:Wound-care and dermatology formulation standards preserve petroleum jelly's irreplaceable moisture-retention properties against water-based alternatives.
Market Restraints
- Crude-linked feedstock volatility:Vacuum gas oil and slack wax pricing swings directly compress blending margins for non-integrated specialty producers.
- Natural emollient substitution:Shea butter, squalane, and plant-derived occlusives are displacing cosmetic-grade volumes in European and North American skin-care channels.
- REACH registration thresholds:ECHA substance-volume compliance burdens create fixed-cost barriers for sub-scale entrants seeking European pharmaceutical-grade market access.
Strategic Opportunities
- ASEAN pharmaceutical manufacturing:Thailand and Vietnam excipient demand is outpacing local refining capacity, creating import substitution openings for certified exporters.
- Sustainable hydrogenation pathways:Renewable hydrogen feedstock integration offers differentiation for cosmetic-grade output targeting clean-beauty certification schemes.
- Pump-dispensed packaging pivot:EU F-Gas Regulation aerosol restrictions are redirecting lubricant and barrier-product demand toward jar and tube formats requiring higher-viscosity base stocks.
Industry Challenges
- Pharmacopeial monograph synchronization:Divergent USP, EP, and IP purity specifications force multi-standard batch testing, extending certification timelines.
- Hydrogenation catalyst supply:Specialized nickel and palladium catalyst procurement constraints limit capacity ramp speed for pharmaceutical-grade output expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Petroleum Jelly Market |
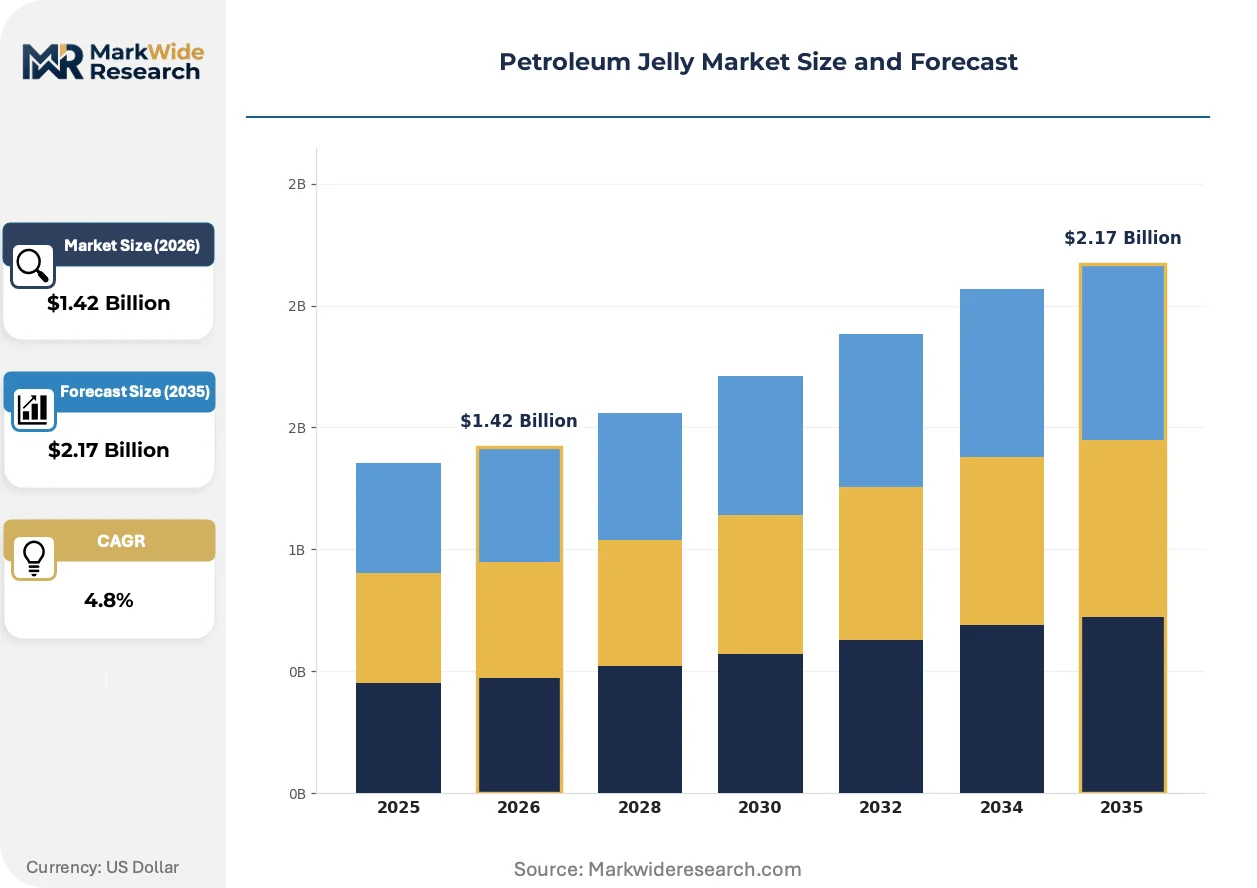
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Petroleum Jelly, Semi-Refined, Microcrystalline, Pharmaceutical Grade, Cosmetic Grade, Industrial Grade Application: Skin Care, Lubrication, Protective Coating, Hair Care, Medical Ointment, Adhesive Component End User: Personal Care Manufacturers, Pharmaceutical Companies, Mechanical Workshops, Packaging Firms, Cosmetic Factories, Chemical Suppliers Packaging Type: Jars, Tubes, Sachets, Tins, Plastic Containers, Glass Jars |
| Companies Covered | Sonneborn LLC, Calumet Specialty Products Partners LP, Exxon Mobil Corporation, Repsol S.A., PJSC LUKOIL, Shell Inc., Sasol Wax Group, Teva Pharmaceuticals Inc., Unilever plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Petroleum Jelly Market Strategic Shifts & Innovations
Formulation science and regulatory chemistry are converging to redefine grade boundaries, with hydrogenation precision and carbon-accounting transparency emerging as the primary axes of competitive differentiation.
Advanced selective dewaxing is decomposing the traditional premium-mid-economy grade hierarchy by enabling continuous viscosity tuning for batch-specific pharmaceutical applications. Specialty compounders in India and Germany are adopting these systems to produce color-stable, low-PAH output without dedicated campaign changeovers. This flexibility is compressing minimum order quantities and enabling contract manufacturing for mid-tier topical brands previously locked out of pharmaceutical-grade supply.
REACH substance evaluation under ECHA's 2023-2025 rolling action plan is tightening polycyclic-aromatic-hydrocarbon reporting thresholds for petroleum-derived cosmetic ingredients. Refiners serving European personal-care manufacturers must now implement gas-chromatography-mass-spectrometry batch testing protocols that add fixed analytical costs. Cosmetic-grade suppliers with pre-existing pharmaceutical certification infrastructure are absorbing these requirements faster than pure-play cosmetic compounders.
Direct-to-manufacturer sampling programs are displacing traditional distributor-led specification-matching for pharmaceutical excipient procurement. Formulation chemists at topical drug developers now request sealed USP-grade samples with certificates of analysis before engaging volume negotiations, compressing the traditional three-tier channel structure. This pattern is most pronounced in India's Maharashtra and Gujarat pharmaceutical clusters, where domestic compounders maintain in-house analytical laboratories for same-day certification verification.
Petroleum Jelly Market Segmentation
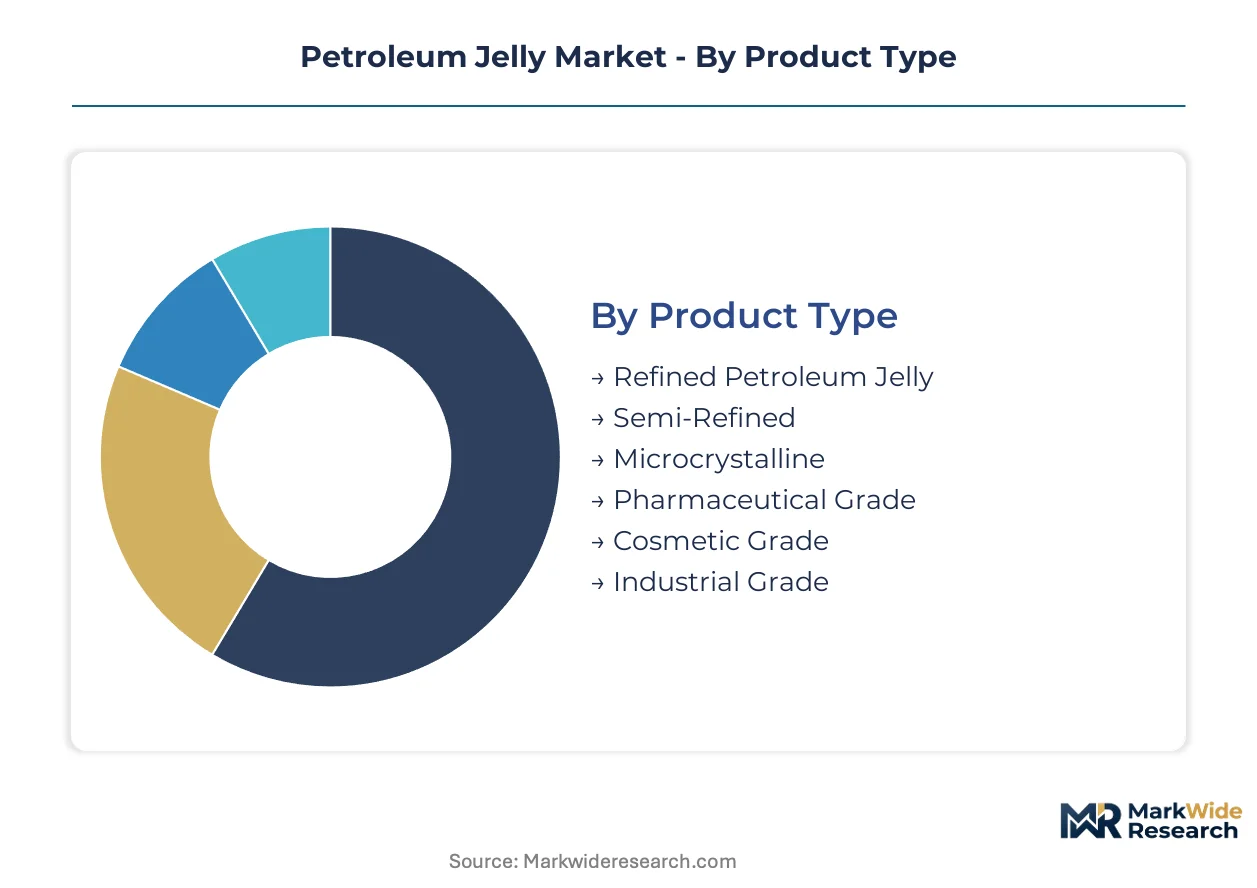
Grade differentiation and end-use certification requirements fragment petroleum jelly procurement patterns across the value chain. Specification hierarchies determine pricing power, minimum order quantities, and geographic sourcing flexibility for compounders and formulators.
Product Type:
Domestic consumption concentrates on pharmaceutical and cosmetic grades in India, while export flows favor industrial and semi-refined categories to Southeast Asian manufacturing hubs.
- Refined Petroleum Jelly:Achieves color stability below 0.5 YI through multi-stage hydrogenation and clay filtration. Indian pharmaceutical excipient manufacturers under the PLI scheme absorb rising volumes for topical ointment production, though hydrogenation catalyst procurement constraints limit supply elasticity.
- Pharmaceutical Grade:USP monograph compliance mandates batch-level polycyclic-aromatic-hydrocarbon certification via gas-chromatography-mass-spectrometry testing. Maharashtra and Gujarat formulation clusters source exclusively from refiners with dedicated pharmaceutical campaign infrastructure, locking in multi-year supply agreements.
- Semi-Refined:Intermediate purity for industrial lubricant and rust-prevention applications where color specifications relax below cosmetic thresholds.
- Microcrystalline:Higher melting-point wax structure for specialized adhesive and cable-filling compounds requiring elevated temperature stability.
- Cosmetic Grade:Low-odor, low-color output for skin-care and hair-care formulations facing natural-emollient substitution pressure in European channels.
- Industrial Grade:Unhydrogenated base stock for machinery lubrication and metal-protection coatings with minimal regulatory compliance burden.
Pharmaceutical Grade commands the established base. The steepest expansion runs through Refined Petroleum Jelly.
Application:
Cost stratification separates medical and skin-care applications with certification overhead from industrial uses with commodity pricing dynamics.
- Skin Care:Occlusive barrier functionality in moisturizers and lip balms preserves petroleum jelly's formulation role against water-based alternatives. European clean-beauty certification schemes are accelerating natural-emollient displacement in premium positioning tiers.
- Medical Ointment:Wound-care and dermatology formulations require USP-grade excipient certification with documented batch stability data. Indian CDSCO enforcement of topical drug cGMP standards is expanding pharmaceutical-grade offtake from domestic refiners.
- Lubrication:Machinery and component protection across mechanical workshops with specification flexibility enabling semi-refined and industrial grade substitution.
- Protective Coating:Rust inhibition and moisture barrier applications in metal fabrication and electronics packaging.
- Hair Care:Pomade and conditioner formulations facing shea butter and squalane displacement in North American and European natural-positioned product lines.
- Adhesive Component:Hot-melt and pressure-sensitive adhesive formulations leveraging microcrystalline wax compatibility.
Medical Ointment anchors volume concentration. Skin Care is climbing the fastest amid formulation science convergence with pharmaceutical standards.
End User:
Customer scale determines procurement channel structure, with large pharmaceutical companies bypassing distributors for direct refiner relationships while mid-tier cosmetic factories rely on compounder intermediaries.
- Pharmaceutical Companies:Batch-certification requirements and USP documentation needs lock in long-term contracts with hydrogenation-capable refiners. Direct sampling programs with certificate-of-analysis pre-qualification are displacing traditional distributor relationships in Indian clusters.
- Personal Care Manufacturers:Cosmetic-grade volume demand dominates absolute consumption but faces margin compression from natural-alternative substitution and REACH analytical cost absorption.
- Mechanical Workshops:Price-sensitive industrial-grade procurement with minimal specification requirements and spot-market purchasing patterns.
- Packaging Firms:Lubricant and protective coating applications for machinery maintenance and corrosion prevention.
- Cosmetic Factories:Mid-tier formulators without in-house analytical capabilities dependent on compounder certification and smaller minimum order quantities.
- Chemical Suppliers:Distribution intermediaries consolidating sub-scale demand from regional manufacturers.
Pharmaceutical Companies represent the most entrenched demand pool. Personal Care Manufacturers are gaining share fastest through pump-dispensed format pivots.
Packaging Type:
Format selection tracks end-use viscosity requirements and regulatory constraints on aerosol propellant systems.
- Jars:Wide-mouth containers for high-viscosity pharmaceutical and cosmetic applications. EU F-Gas Regulation restrictions on aerosol formats are redirecting lubricant and barrier-product demand toward jar formats requiring thicker base stock consistency.
- Tubes:Collapsible aluminum and laminate structures for topical ointment and hand-cream dispensing with controlled dosing precision.
- Sachets:Single-use pouches for travel-size and sample distribution in personal care channels.
- Tins:Traditional metal packaging for industrial lubricant and protective coating applications.
- Plastic Containers:Polypropylene and polyethylene vessels for cost-optimized cosmetic and mechanical workshop segments.
- Glass Jars:Premium-positioned cosmetic packaging with chemical inertness for sensitive formulations.
Jars hold the dominant format position. Tubes are expanding most quickly through pharmaceutical dispensing standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates pharmaceutical-grade consumption through government-backed excipient manufacturing incentives, while European and North American markets diverge toward cosmetic applications facing natural-emollient substitution pressure.
United States
FDA cGMP batch-certification requirements for topical drug excipients lock pharmaceutical compounders into long-term refiner contracts. The agency's tightened enforcement on polycyclic-aromatic-hydrocarbon documentation elevates hydrogenation-capable suppliers. New Jersey and Pennsylvania pharmaceutical clusters source exclusively through direct sampling programs with certificate-of-analysis pre-qualification.
Germany
ECHA's 2023-2025 rolling action plan on REACH substance evaluation tightens PAH reporting thresholds for petroleum-derived cosmetic ingredients. Gas-chromatography-mass-spectrometry batch testing protocols add fixed analytical costs that cosmetic-grade suppliers absorb faster than pure-play compounders. The North Rhine-Westphalia chemical corridor hosts refiners with dual pharmaceutical-cosmetic certification infrastructure.
India
CDSCO enforcement of topical drug cGMP standards expands pharmaceutical-grade offtake from domestic refiners. The PLI scheme for pharmaceutical excipients accelerates local petroleum jelly consumption for ointment and cream manufacturing. Maharashtra and Gujarat formulation clusters now maintain in-house analytical laboratories for same-day USP-grade certification verification.
China
NMPA pharmaceutical-grade registration requirements align progressively with USP and EP monograph standards, compressing supply elasticity for imported excipients. Domestic hydrogenation capacity expansion targets low-PAH output for topical drug export manufacturing. The Yangtze River Delta pharmaceutical belt concentrates formulation demand for certified refiner supply.
Brazil
ANVISA pharmaceutical excipient import regulations favor certified refiners with established South American distribution infrastructure. Cosmetic-grade consumption dominates absolute volume through personal care manufacturing for regional consumer markets. São Paulo state anchors formulation demand for skin-care and hair-care production.
Petroleum Jelly Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in petroleum jelly production. Captive crude streams and downstream hydrogenation infrastructure separate the top tier from non-integrated compounders. Strategic archetypes include integrated oil majors with pharmaceutical-grade campaign capabilities, specialty refiners with color-stability differentiation, and regional compounders serving mid-tier cosmetic brands. Dominant competitive moves center on hydrogenation capacity expansion and direct-to-manufacturer sampling programs that displace traditional distributor channels.
Within the integrated leader tier, Exxon Mobil Corporation and Shell Inc. exemplify upstream-downstream control over pharmaceutical-grade output. Sonneborn LLC occupies a specialist position representing specialized refining capabilities for low-PAH cosmetic applications. Calumet Specialty Products Partners LP anchors a mid-scale archetype with flexible campaign infrastructure serving both pharmaceutical and industrial grade demand.
| Leading Market Players |
|---|
| Sonneborn LLC |
| Calumet Specialty Products Partners LP |
| Exxon Mobil Corporation |
| Repsol S.A. |
| PJSC LUKOIL |
| Shell Inc. |
| Sasol Wax Group |
| Teva Pharmaceuticals Inc. |
| Unilever plc |
| Others |
Cost & Logistics Intelligence
REACH substance-registration thresholds and FDA pharmaceutical-grade specifications simultaneously gate supply qualification and stratify price tiers across the petroleum jelly value chain. Certification burdens compress supply elasticity for pharmaceutical-grade output while enabling premium positioning that non-integrated compounders cannot replicate.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical-grade procurement as FDA batch-certification requirements lock compounders into multi-year supply agreements with hydrogenation-capable refiners. Spot-market purchasing persists for industrial-grade applications where color and purity specifications relax. Price differentiation rests on USP compliance tier and volume scale, with Maharashtra and Gujarat formulation clusters absorbing premium positioning for certified output. Cost compression in cosmetic-grade channels is intensifying because shea butter and squalane substitution erodes pricing power in European clean-beauty segments. Mechanical workshops exhibit highest price sensitivity, while pharmaceutical companies accept premium positioning for documented batch stability data.
Supply Chain Analysis
Inventory lead times for specialized nickel and palladium hydrogenation catalysts extend certification timelines and constrain capacity ramp speed for pharmaceutical-grade output expansion. Supply concentrates in India, the United States, and Germany, with Maharashtra and Gujarat clusters feeding domestic pharmaceutical excipient demand. Raw material dependencies draw from vacuum gas oil, slack wax, and renewable hydrogen feedstocks. Single-source vulnerability sits with catalyst procurement constraints that limit supply elasticity. Distribution runs through direct-to-manufacturer sampling programs displacing traditional three-tier channel structures in Indian pharmaceutical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certificate-of-analysis verification services and same-day batch certification represent recurring-revenue layers expanding faster than base petroleum jelly production as formulation chemists demand pre-qualified sampling protocols.
For Market Incumbents: Secure hydrogenation capacity expansion in India to capture PLI scheme incentives before catalyst procurement constraints tighten further. Lock in multi-year supply agreements with Maharashtra and Gujarat pharmaceutical clusters through dedicated analytical laboratory partnerships. Natural emollient substitution in European cosmetic channels threatens margin stability in non-pharmaceutical grades. For New Entrants and Emerging Players: Differentiate on renewable hydrogen feedstock integration for cosmetic-grade output targeting clean-beauty certification schemes in European personal care channels. White-space opportunities concentrate in ASEAN pharmaceutical manufacturing, where Thailand and Vietnam excipient demand outpaces local refining capacity. Direct sampling programs with in-house GC-MS batch testing capabilities offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade hydrogenation infrastructure as REACH and FDA specifications tighten simultaneously. Long-term viability favors integrated refiners with captive crude streams and downstream campaign capabilities over non-integrated compounders exposed to feedstock volatility. Acquisition targets should display dual pharmaceutical-cosmetic certification infrastructure. The signal to watch is ECHA rolling action plan implementation pace for polycyclic-aromatic-hydrocarbon threshold adjustments.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogenation Capacity Expansion | Captures PLI scheme incentives in India while meeting tightening USP and REACH low-PAH specifications. |
| Backward Integration into Catalyst Supply | Mitigates nickel and palladium procurement constraints that limit pharmaceutical-grade output ramp speed. |
| Direct-to-Manufacturer Sampling Programs | Displaces distributor channels in Maharashtra and Gujarat through same-day certificate-of-analysis verification. |
| Renewable Hydrogen Feedstock Integration | Enables clean-beauty certification positioning for cosmetic-grade output in European substitution-pressured channels. |
| Dual Pharmaceutical-Cosmetic Certification Infrastructure | Absorbs REACH analytical cost burdens faster than pure-play cosmetic compounders under ECHA evaluation timelines. |
Research Approach
Cross-validation between primary interviews with refinery operations managers, pharmaceutical formulation chemists, and cosmetic procurement leads and secondary sources anchors the qualitative findings. Secondary validation draws from CDSCO cGMP enforcement records, ECHA substance evaluation documentation, SEC filings from integrated oil majors, and Indian PLI scheme disbursement data. Bottom-up segmentation modeling triangulates against top-down macroeconomic drivers across the analysis window.
Sensitivity analysis around hydrogenation capacity expansion timelines and catalyst procurement constraints tests forecast robustness across the projection horizon. The analytical framework segments by grade tier, end-use application, packaging format, and regional production hub. CAGRs derive from elasticity-adjusted demand curves incorporating crude-linked feedstock volatility and natural emollient substitution rates. Industry-specific inputs include CDSCO enforcement intensity indices and ECHA rolling action plan implementation schedules.
Material uncertainties — pharmacopeial monograph synchronization delays, catalyst supply disruptions, and abrupt clean-beauty certification scheme adoption — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement trajectories and substitution elasticity parameters. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Fabric Softener Sheet Market
Specialty Chemicals
Biobased Propylene Glycol Market
Specialty Chemicals
Fatty Alcohol Alkoxylates Market
Specialty Chemicals
Colloidal Gold Suspension Market
Specialty Chemicals
Ytterbium Fluoride Market
Specialty Chemicals
Medical Propellants Market
Specialty Chemicals
Multichannel Reagent Reservoir Market
Specialty Chemicals
Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Explosives and Pyrotechnics Market
Specialty Chemicals
Global Chemical Vapor Deposition (CVD) Market
Specialty Chemicals
Immunochemistry Products Market
Specialty Chemicals
Acesulfame K Market
Specialty Chemicals
Epoxidized Soybean Oil Market
Specialty Chemicals
India Prussian Blue Market
Specialty Chemicals
Bromocyclopentane Market
Specialty Chemicals
Methyltrimethoxysilane Market