
 Global Smartphone Operating System (OS) Market | 2026-2036
Global Smartphone Operating System (OS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smartphone Operating System (OS) Market Intelligence
China's domestic OS development push is reconfiguring the established market duopoly. Google leverages its open-source Android model and vast developer community to command significant volume across multiple device manufacturers. Apple sustains its premium market segment by controlling the entire stack, from silicon to its iOS software. Meanwhile, Huawei accelerates its HarmonyOS ecosystem as a direct alternative, particularly within its domestic market and allied regions.
A smartphone operating system is the core software that manages hardware components and provides foundational services for applications. It handles process scheduling, memory management, and delivers the graphical user interface. The dominant Operating System segment is a duopoly between Android and iOS, creating two distinct ecosystems. OS features are also stratified by Device Type, with Flagship Phones receiving advanced capabilities ahead of Mid-Range or Budget Phones.
Regulations like the EU's Digital Markets Act (DMA) and scrutiny from the US Department of Justice target app store policies and OS pre-installation practices. Concurrently, China's Ministry of Industry and Information Technology (MIIT) guides the development of domestic standards, impacting foreign and local OS providers. Success for platform owners will hinge on their ability to navigate this increasingly complex and fragmented global regulatory environment.
Market Dynamics
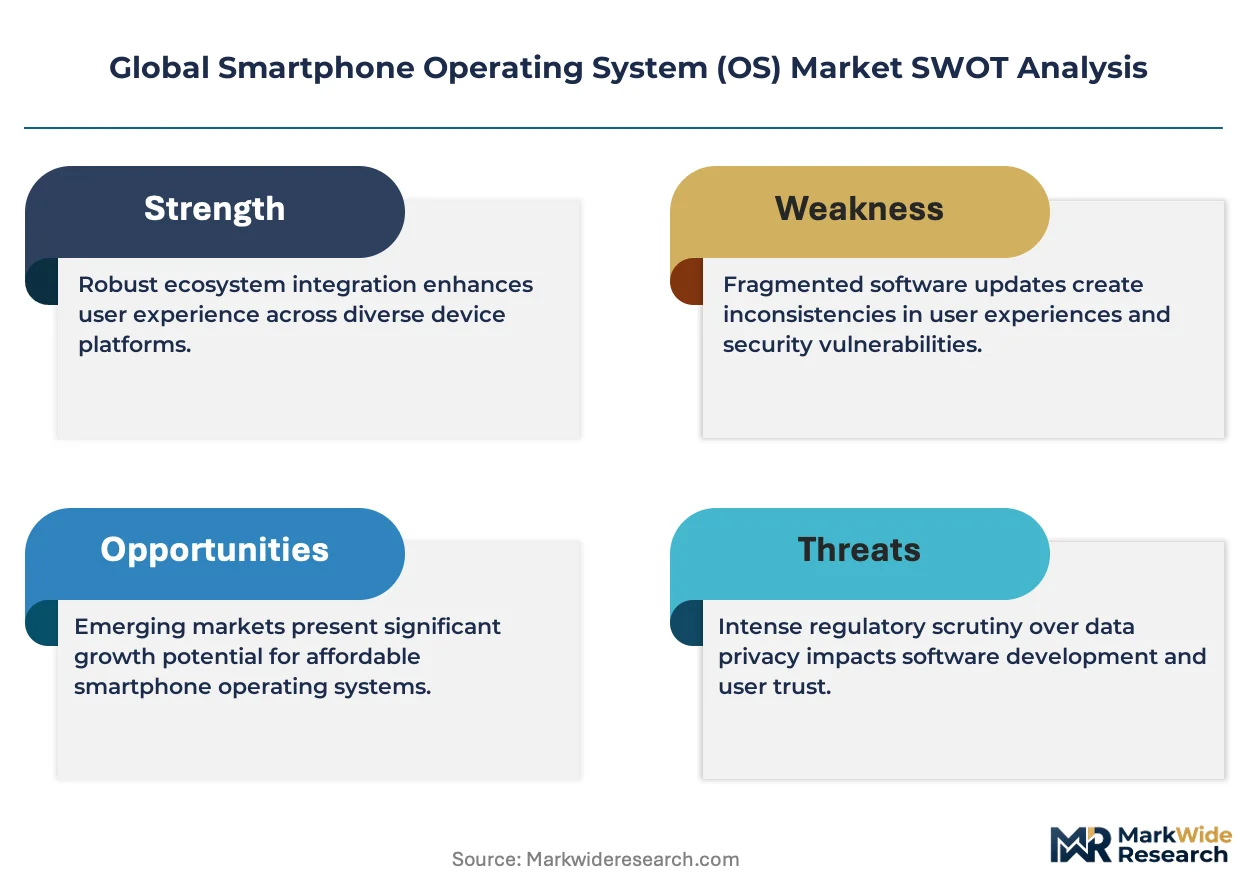
The central force shaping the smartphone OS market is geopolitical fragmentation, where national and regional digital sovereignty initiatives, particularly from the EU and China, are challenging the established global duopoly and forcing platform owners to re-architect for compliance.
Growth Catalysts
- Corporate Demand:Enterprise clients are driving demand for operating systems with robust security frameworks, advanced mobile device management (MDM) APIs, and containerization features to separate corporate and personal data on employee devices.
- First-Time Smartphone Adoption:The expanding consumer base in India and other parts of Southeast Asia upgrading from feature phones to their first smartphones creates a significant volume opportunity for lightweight, data-efficient operating systems.
- EU Digital Markets Act (DMA):This regulation compels dominant gatekeepers to open their ecosystems, creating opportunities for third-party app stores, alternative payment systems, and deeper integration for competing services, potentially spurring new software innovation.
Market Restraints
- Ecosystem Lock-In:The powerful network effects of the dominant Android and iOS ecosystems, including their vast application libraries and developer communities, create formidable barriers to entry for any new or competing operating system.
- Hardware Fragmentation:OS developers for open platforms like Android face the immense technical challenge of ensuring stability and performance across thousands of different hardware configurations, which can slow the rollout of new features.
- Semiconductor Dependency:The OS feature roadmap is intrinsically tied to the development cycles of a few key silicon providers; limitations in chip architecture or delayed product cycles directly constrain the capabilities an OS can support.
Strategic Opportunities
- Specialized Device Verticals:There is a significant opportunity to adapt and license smartphone OS cores for adjacent markets, such as in-vehicle infotainment systems, industrial handhelds, and smart home hubs, which require a mature software foundation.
- On-Device AI Integration:The convergence of neural processing units (NPUs) with OS schedulers allows for new classes of proactive, context-aware applications and significant improvements in power efficiency, creating a new axis for competition.
- Ultra-Lightweight OS for Emerging Markets:Developing and deploying highly optimized OS versions for devices with minimal RAM and storage can unlock volume in price-sensitive regions across Africa and Latin America that are currently underserved.
Industry Challenges
- Patent Thicket Complexity:Navigating the dense web of patents and cross-licensing agreements related to fundamental mobile technologies, such as wireless communication and user interface elements, presents a constant legal and financial challenge.
- Regulatory Compliance Overhead:Platform owners face the operational burden of simultaneously complying with divergent and sometimes contradictory regulations, from the EU's DMA to China's MIIT data localization rules, increasing engineering costs.
- Scarcity of Kernel Developers:A persistent shortage of software engineers with deep expertise in OS kernel development, low-level security, and driver optimization hampers the ability of all platform owners to innovate and secure their core codebases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smartphone Operating System (OS) Market |
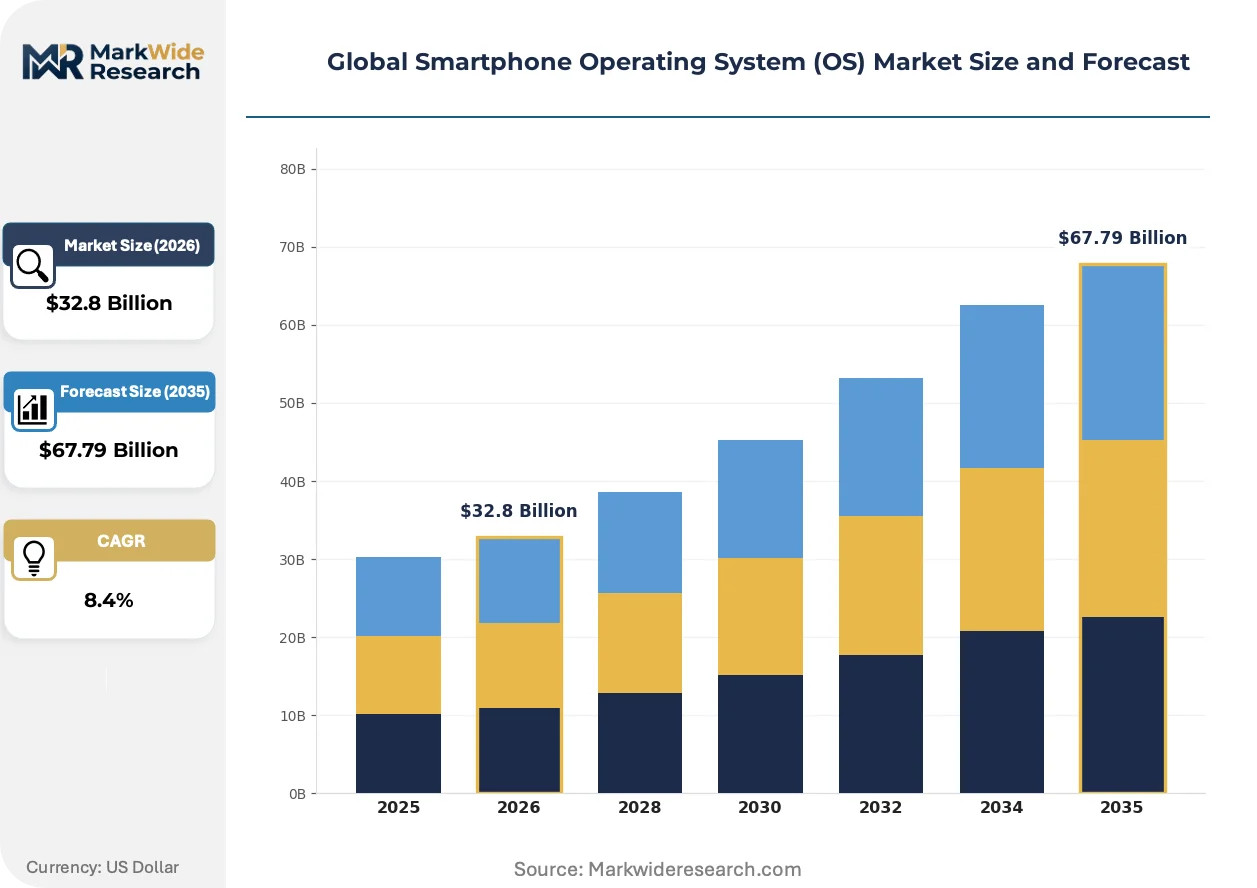
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Operating System: Android, iOS, HarmonyOS, KaiOS, Sailfish OS Device Type: Flagship Phones, Mid-Range Phones, Budget Phones, Foldable Phones, Rugged Phones Distribution Channel: Online Retail, Carrier Stores, Third-Party Retailers, Direct Manufacturer Sales, Specialty Electronics Stores End User: Individual Consumers, Small Business Owners, Corporate Clients, Educational Institutions, Government Agencies |
| Companies Covered | Samsung, Oppo, Google, OnePlus, Vivo, Apple, Xiaomi, Sony, Huawei, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smartphone Operating System (OS) Market Strategic Shifts & Innovations
The market is defined by a fundamental architectural evolution away from monolithic, one-size-fits-all operating systems. Platforms are becoming more modular, AI-native, and context-aware to serve a diversifying set of hardware capabilities and user expectations for privacy and performance.
On-device artificial intelligence is a core function being integrated directly into the OS scheduler and power management subsystems. Flagship and premium device segments are rapidly adopting this capability to enable features like real-time language translation and computational photography without relying on the cloud. This trend is hybridizing the operating system, blending traditional process management with predictive, AI-driven resource allocation to improve responsiveness and extend battery life.
China's Ministry of Industry and Information Technology (MIIT) is actively guiding the creation of domestic OS standards to foster a self-reliant software ecosystem. This policy incentivizes local device manufacturers to adopt and contribute to national platforms, creating a protected market. Foreign OS providers are most impacted, as they must adapt to stringent data governance and interoperability mandates, which often require substantial platform modifications for the Chinese market.
Enterprise procurement behavior now prioritizes the underlying OS manageability and security over consumer-facing device features. This shift disrupts the traditional feature-driven upgrade cycle, placing a premium on platforms that offer robust security APIs, zero-touch deployment capabilities, and granular policy controls. The change is most pronounced in regulated sectors like finance and healthcare, particularly within North America and Europe.
Global Smartphone Operating System (OS) Market Segmentation
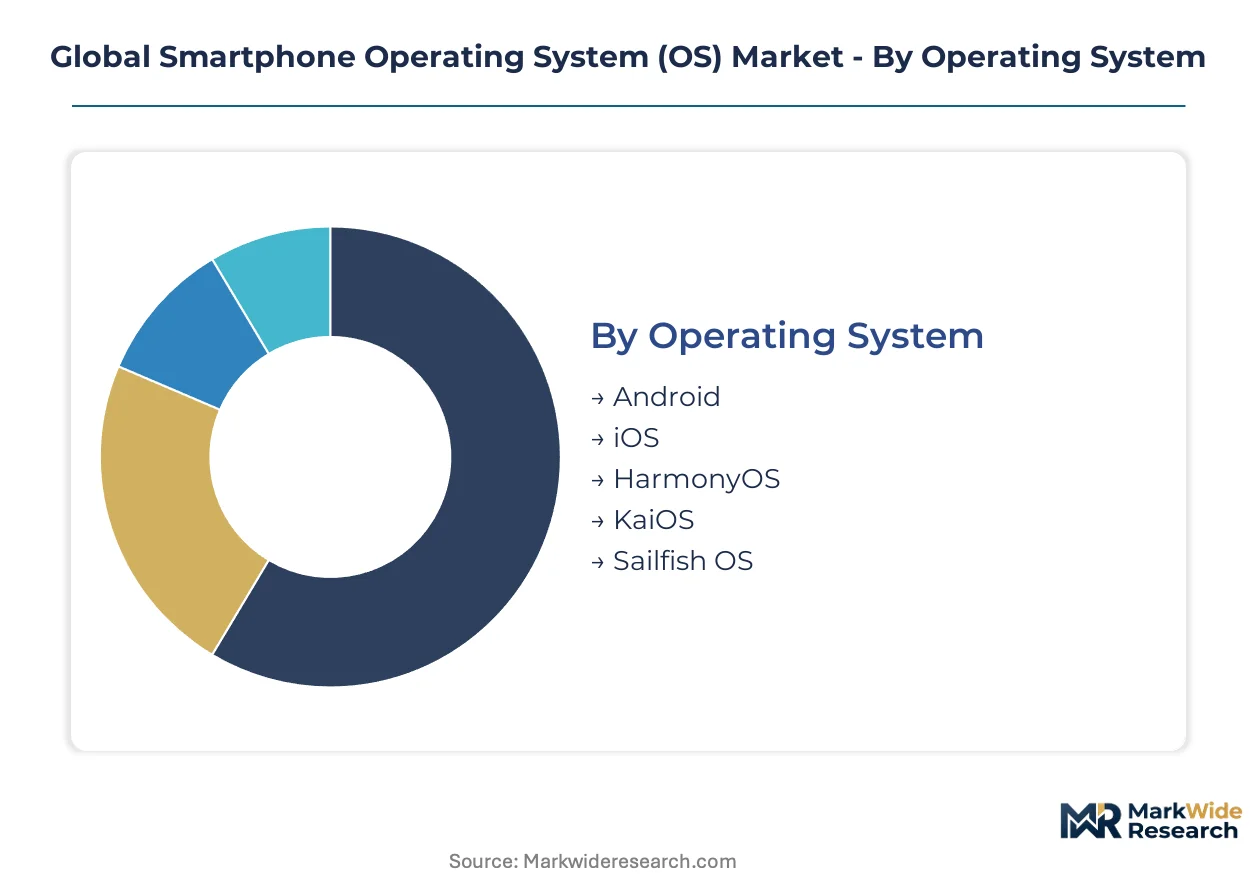
Smartphone OS market segmentation reveals how diverse user needs, device capabilities, and distribution strategies shape platform development and adoption. Understanding these distinct segments allows providers to tailor features, security, and market approaches. This analysis illuminates varied competitive landscapes within the broader ecosystem.
Operating System:
The operating system landscape presents a clear maturity spectrum, with established players dominating volume and emerging alternatives seeking niche penetration.
- Android:Android is an open-source, Linux-based OS known for extensive customization and a vast application ecosystem. Its flexible architecture supports wide hardware configurations. Demand concentrates heavily in emerging markets like India, driven by affordability and diverse device availability.
- iOS:iOS operates as a closed-source, proprietary OS exclusively for Apple's hardware, emphasizing seamless user experience and robust security. Its tightly integrated software and hardware ecosystem targets the premium segment. Demand remains strong in developed regions like North America and Western Europe, where users prioritize performance.
- HarmonyOS:Huawei's proprietary OS, HarmonyOS, developed as a direct alternative, particularly within China and allied regions.
- KaiOS:KaiOS is a lightweight, web-based OS for smart feature phones, gaining traction in price-sensitive emerging markets across Africa.
- Sailfish OS:Sailfish OS is an open-source, Linux-based mobile OS, focused on privacy and customization for niche European users.
Android retains volume leadership; HarmonyOS holds the steepest expansion curve within its domestic sphere.
Device Type:
Device type stratification reflects distinct cost tiers and hardware innovation cycles, influencing OS feature sets and optimization priorities.
- Flagship Phones:Flagship phones represent the premium segment, integrating cutting-edge processors, advanced camera systems, and high-resolution displays. Their operating systems receive advanced AI integration and security. Demand is robust in markets with high disposable income, such as Germany and Japan.
- Budget Phones:Budget phones prioritize affordability and essential functionality, offering basic processing power and limited storage. Their operating systems require extreme optimization for data efficiency and lightweight performance. Demand is substantial in high-volume, price-sensitive markets like Indonesia and Nigeria.
- Mid-Range Phones:Mid-range phones balance features and cost, providing a solid user experience, appealing to a broad consumer base globally.
- Foldable Phones:Foldable phones feature innovative, flexible displays, requiring specialized OS adaptations for multi-window management and unique user interfaces.
- Rugged Phones:Rugged phones are built for durability and harsh environments, often used in industrial or outdoor settings, with OS features optimized for enterprise applications.
Flagship phones command the highest margin per unit; Budget phones drive the largest overall unit volume.
Distribution Channel:
Distribution channels delineate distinct customer access points and purchasing behaviors, each presenting unique opportunities for OS providers to reach their target demographics.
- Online Retail:Online retail encompasses e-commerce platforms and brand websites, offering vast product selections, competitive pricing, and user reviews. This channel caters to tech-savvy consumers who prefer independent research and convenience. Demand is particularly high in digitally mature markets like the United Kingdom and South Korea.
- Carrier Stores:Carrier stores provide direct sales through mobile network operators, often bundling devices with service contracts and offering financing. This channel leverages brand loyalty and provides in-person customer support. Demand for carrier-bundled devices is significant in the United States and Canada.
- Third-Party Retailers:Third-party retailers include large electronics chains and department stores, offering a wide range of brands and models.
- Direct Manufacturer Sales:Direct manufacturer sales involve purchasing directly from the brand's own stores or websites, allowing for exclusive offers and direct customer relationships.
- Specialty Electronics Stores:Specialty electronics stores focus on specific product categories, providing expert advice and hands-on demonstrations.
Online retail is rapidly gaining share; Carrier stores maintain strong influence over consumer purchasing decisions.
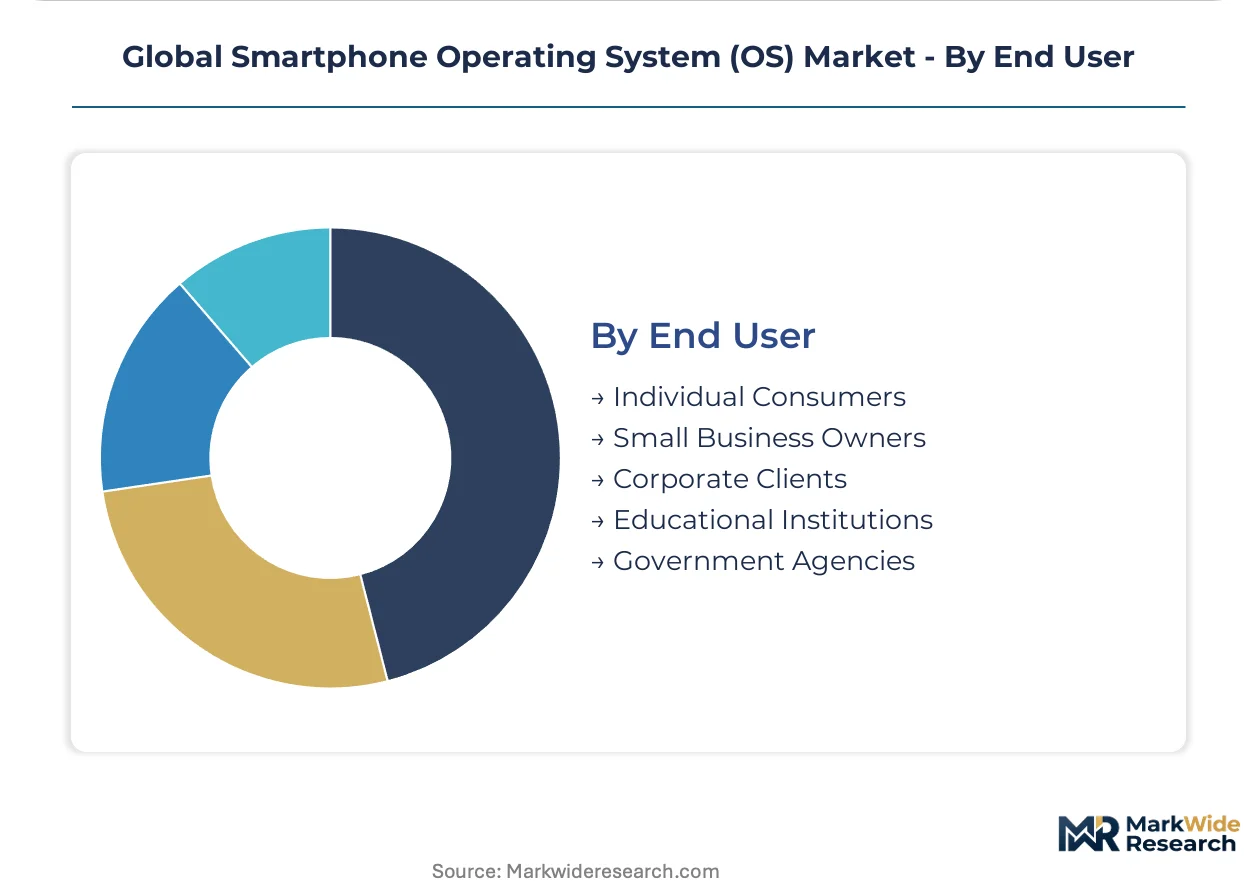
End User:
End-user categories highlight diverse procurement drivers, ranging from individual preference and entertainment to stringent corporate security and manageability requirements.
- Individual Consumers:Individual consumers purchase smartphones for personal communication, entertainment, social networking, and daily productivity. Their OS preferences often hinge on user interface intuitiveness and app availability. This segment represents the largest volume driver across all global regions.
- Corporate Clients:Corporate clients procure smartphones for employee use, prioritizing robust security, mobile device management (MDM) capabilities, and seamless integration with enterprise systems. OS selection is critical for data protection. Demand is concentrated in regulated industries within France and Australia.
- Small Business Owners:Small business owners seek cost-effective smartphones supporting productivity apps and basic communication, often blurring personal and professional use.
- Educational Institutions:Educational institutions deploy smartphones for learning platforms and administrative tasks, requiring OS features that facilitate content management and student safety.
- Government Agencies:Government agencies demand highly secure and often customized OS solutions for sensitive communications and data, adhering to strict national security protocols.
Individual consumers remain the primary volume driver; Corporate clients exhibit the most stringent OS feature requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global smartphone operating system market exhibits a supply-side concentration around key technology hubs. These regions drive both advanced OS development and high-volume device manufacturing. Geopolitical factors and regulatory frameworks significantly influence platform adoption and market dynamics across different continents.
China
China's demand for smartphone operating systems centers on domestic innovation and a vast consumer base. The Ministry of Industry and Information Technology (MIIT) actively guides national OS standards to foster self-reliance. The Yangtze River Delta region, including Shanghai and Hangzhou, drives significant smartphone manufacturing and OS development efforts.
India
India presents a substantial volume opportunity driven by first-time smartphone adoption and upgrades from feature phones. The PLI scheme supports local electronics manufacturing, encouraging domestic device production. Bengaluru's vibrant tech ecosystem fosters app development tailored for Android and emerging local OS platforms.
United States
The United States market is characterized by strong demand from corporate clients for secure mobile environments and a significant premium segment for flagship devices. The US Department of Justice scrutinizes app store policies and pre-installation practices. Silicon Valley remains a global hub for core OS innovation and platform development.
Germany
Germany exhibits high demand for flagship phones and robust corporate client interest in advanced security and mobile device management. The EU's Digital Markets Act (DMA) compels platform holders to open their ecosystems for greater competition. Munich's tech sector focuses on enterprise mobility solutions and secure OS integrations.
South Korea
South Korea demonstrates strong consumer adoption of advanced smartphone technology and significant domestic hardware manufacturing capabilities. National telecommunications regulators influence device pre-installation practices and data privacy standards. Seoul's digital innovation centers contribute to advanced OS features and hardware integration.
Global Smartphone Operating System (OS) Market Key Industry Players
Ecosystem giants and domestic challengers split the market for smartphone operating systems. The established duopoly maintains market share through extensive application libraries and developer communities. New entrants leverage national digital sovereignty initiatives to gain traction. Platform owners primarily focus on regulatory compliance and on-device AI integration as competitive moves.
Among the established platform holders, Google, with its open-source Android model, commands significant volume across diverse device manufacturers. Apple sustains its premium market segment by controlling the entire stack, from silicon to its iOS software. Huawei, a Chinese technology giant, accelerates its HarmonyOS ecosystem as a direct alternative, particularly within its domestic market and allied regions.
| Leading Market Players |
|---|
| Samsung |
| Oppo |
| OnePlus |
| Vivo |
| Apple |
| Xiaomi |
| Sony |
| Huawei |
Cost & Logistics Intelligence
Geopolitical fragmentation in OS development drives supplier behavior and pricing posture. This fragmentation forces platform owners to invest heavily in localized compliance, impacting their global pricing strategies.
Pricing Analysis
The EU's Digital Markets Act dictates the pricing tier structure for app store access and pre-installed services. Licensing and royalty fees represent the dominant pricing model for core OS components. Brand premium and advanced security features drive price differentiation for flagship devices. Pricing softness reflects intense competition in emerging markets. Corporate clients exhibit the least price sensitivity, prioritizing robust MDM and security.
Supply Chain Analysis
US export controls on advanced semiconductor technology limit the flow of critical components for high-performance devices. The smartphone OS supply chain concentrates heavily in China, Taiwan, and South Korea for silicon and display manufacturing. Key dependencies include advanced chipsets, memory modules, and display panels. Regulatory restrictions present a significant structural risk. Distribution runs through direct partnerships with device manufacturers and global carrier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smartphone OS market is undergoing a platform-economics inflection, driven by the EU's Digital Markets Act compelling greater interoperability and ecosystem openness. This shift reshapes competitive dynamics for established players and new entrants.
For Market Incumbents: Entrench core platform advantages by expanding on-device AI capabilities and securing long-term silicon partnerships. Develop modular OS architectures to meet diverse regional regulatory requirements, particularly around data governance. Huawei's HarmonyOS presents a significant domestic threat in China, necessitating strategic alliances or localized adaptation. Investing in kernel developer talent remains a critical R&D lever for core OS stability.
For New Entrants and Emerging Players: Underpenetration in ultra-lightweight OS solutions for price-sensitive regions like Africa and Latin America offers significant opportunity. Target specialized device verticals such as industrial handhelds or in-vehicle infotainment systems with tailored OS versions. The most penetrable segment remains budget phones in high-volume, emerging markets. A go-to-market angle emphasizing data efficiency and privacy features can attract early adopters.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform owners with robust licensing models and strong developer ecosystems. Long-term viability hinges on companies demonstrating adaptability to geopolitical fragmentation and regulatory pressures over the next decade. Acquisition targets should include firms with proprietary low-level OS technologies or specialized AI integration expertise. Adoption rates of alternative app stores serve as a key signal to watch for ecosystem disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular OS Architecture Development | This enables platform owners to comply with diverse regional regulations and cater to specialized device requirements. |
| Deepen On-Device AI Integration | This improves user experience, power efficiency, and enables new context-aware applications for flagship devices. |
| Expand Developer Ecosystem Engagement | This attracts third-party app development, strengthening platform network effects against competing operating systems. |
| Secure Semiconductor Supply Agreements | This ensures access to critical chipsets, mitigating supply chain risks and enabling advanced OS features. |
| Localize OS for Emerging Markets | This captures volume opportunities in price-sensitive regions with lightweight, data-efficient operating system versions. |
Research Approach
Desk research of industry reports, government policy documents, and patent databases preceded structured interviews with CTOs, OS architects, and regulatory compliance officers. This approach combined primary insights from device manufacturers and platform developers with secondary validation. Bottom-up data aggregation and top-down market sizing provided comprehensive triangulation for market estimates.
Assumptions regarding geopolitical stability and technological innovation were held fixed, while regulatory changes and market adoption rates varied across the modeling period. The analytical framework integrated segmentation dimensions including OS type, device type, end-user, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected future demand. Smartphone shipment forecasts and anticipated regulatory policy shifts served as key inputs.
Practitioners should monitor geopolitical shifts, major technological breakthroughs, and new regulatory mandates for early signals of market disruption. Forecasts reflect assumptions documented at the time of analysis, acknowledging inherent uncertainties. Material shifts in global trade policies or core silicon development would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Medical E-Commerce Software Market
Software & Services
Global Test Data Management Market
Software & Services
Global Recruiting Software Market
Software & Services
Online Lottery Software Market
Software & Services
Software Release Management Tools Market
Software & Services
Global Molecular Modeling Software for Chemistry Market
Software & Services
Avionics Software Market
Software & Services
Balance Sheet Management Software Market
Software & Services
Software Testing Tools Market
Software & Services
Europe Business Software Market
Software & Services
Patent Management Software Market
Software & Services
Screen and Video Capture Software Market
Software & Services
Electronic Data Interchange (EDI) Software Market
Software & Services
Global Plumbing Software Market
Software & Services
Global Localization Software Market
Software & Services
Europe Integration Platform As a Service Market