
 Screen and Video Capture Software Market | 2026-2036
Screen and Video Capture Software Market Size, Share, and Industry Trends Forecast 2026-2036
Screen and Video Capture Software Market Analytics
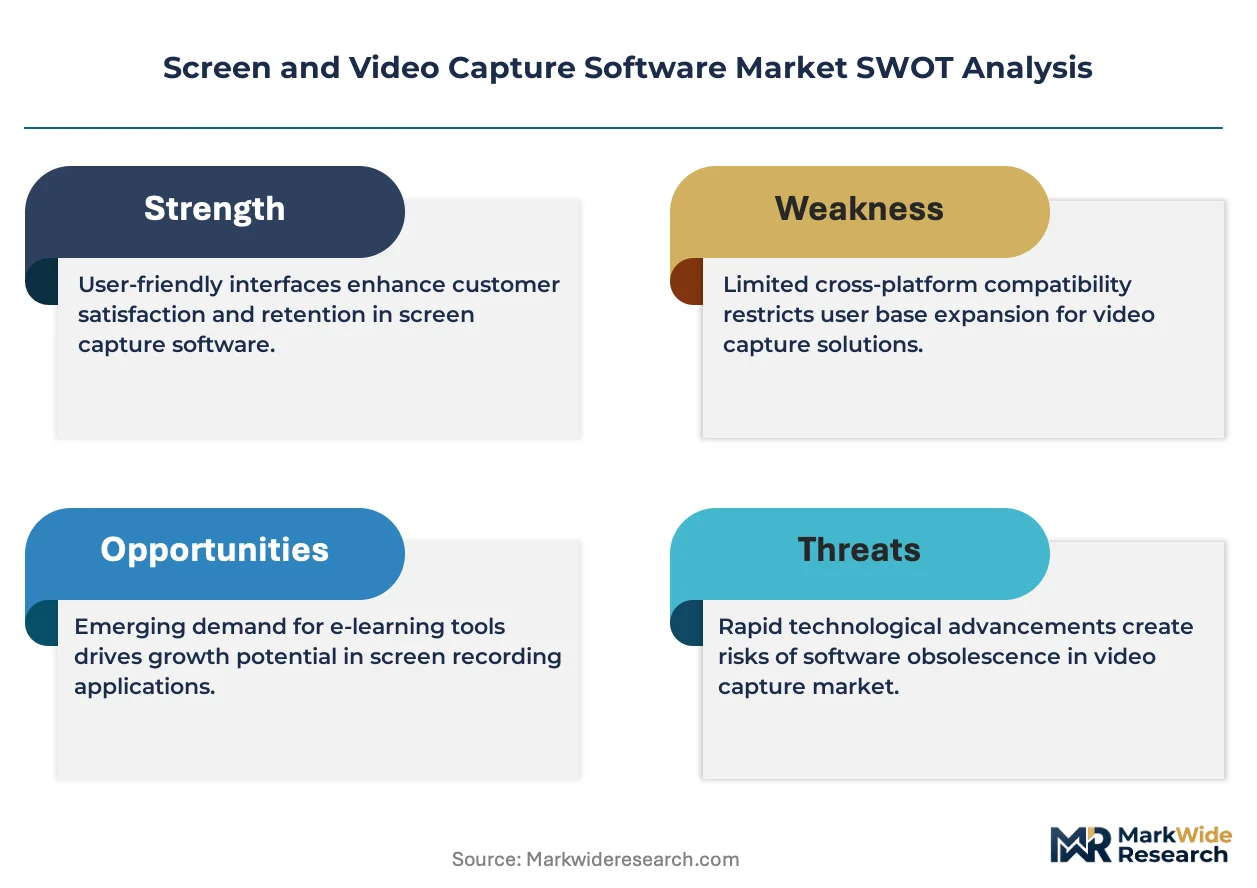
Shortage of instructional design talent is redrawing competitive dynamics as vendors race to embed AI-assisted editing and automated captioning. TechSmith Corporation sustains its position through deep specialization in workplace training documentation. Adobe Inc. leverages its Creative Cloud ecosystem to cross-sell screen capture into existing creative workflows. Wondershare Technology anchors its growth in the Asia-Pacific freelancer segment with localized pricing and payment infrastructure.
Screen and video capture software encompasses applications that record, edit, and distribute visual content from computing devices, typically supporting frame rates from 30 to 60 frames per second and output formats including MP4, AVI, and WebM for interoperability across enterprise systems. Cloud-based solutions are capturing the fastest expansion as IT departments prioritize centralized license management and zero-install deployment, while desktop software retains the largest installed base among power users requiring offline processing and local storage control. The SaaS deployment model is consolidating margin pools through recurring revenue structures that reduce customer acquisition costs over multi-year contracts.
GDPR compliance requirements in Europe, FCC net neutrality frameworks in the United States, and China's GB standards for data localization collectively shape where vendors architect their server infrastructure and consent management flows. The EU AI Act introduces additional scrutiny for automated transcription and facial recognition features embedded in capture tools. Stakeholders must evaluate whether their platform architecture can adapt to diverging data sovereignty regimes without fragmenting the user experience.
Market Dynamics
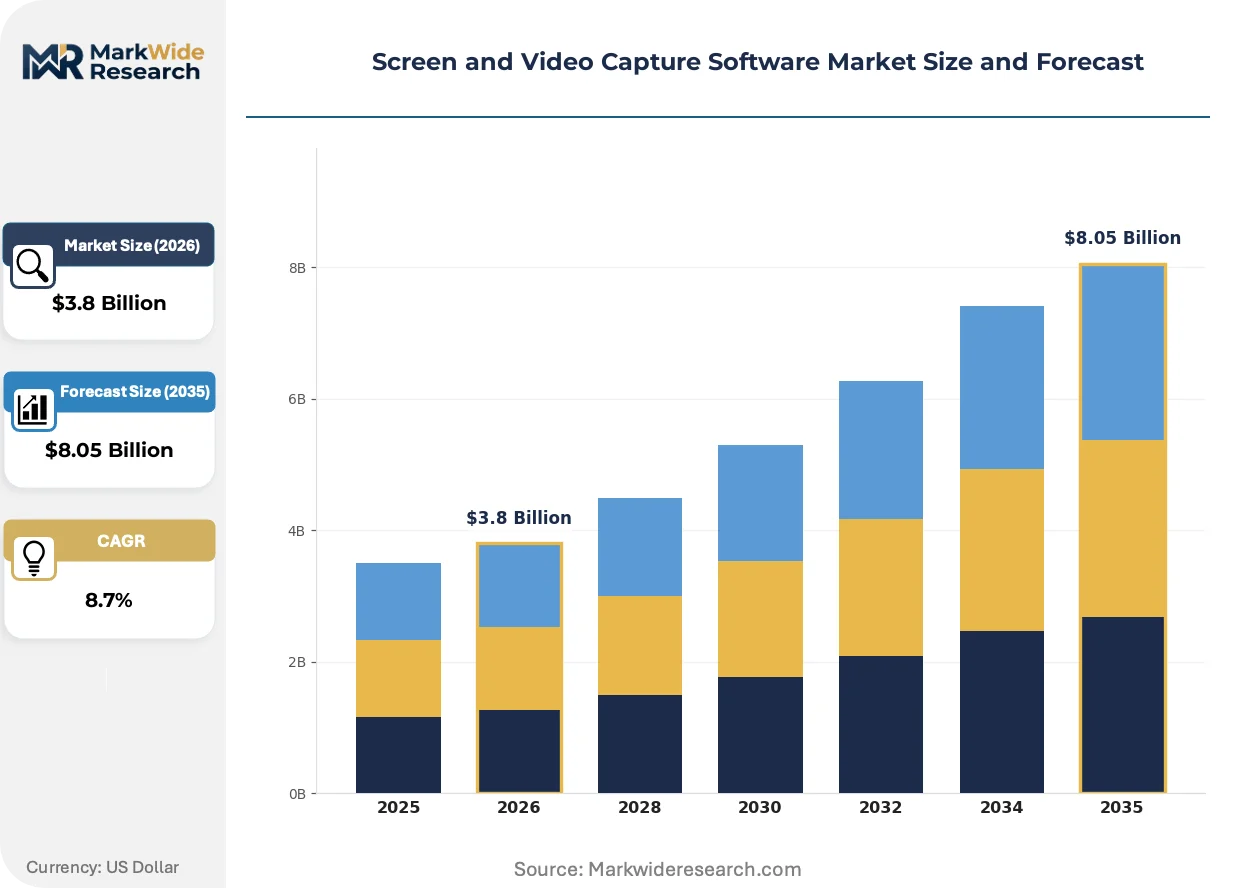
The screen and video capture software market is being fundamentally restructured by the migration from perpetual licensing to SaaS subscription models, which is compressing revenue recognition timelines while expanding total addressable user bases through lower entry price points.
Growth Catalysts
- GDPR-Driven Consent Infrastructure:European data protection mandates are forcing enterprises to deploy audit-ready capture systems with embedded consent logging, creating mandatory replacement cycles for legacy tools.
- AI-Assisted Post-Production:Automated transcription and smart editing features are reducing video production timelines from days to hours, accelerating adoption among lean corporate communications teams.
- Freelancer Platform Integration:Upwork and Fiverr's native screen capture requirements are standardizing tool selection across the gig economy, concentrating demand in browser-based solutions.
Market Restraints
- GPU Cost Volatility:Real-time encoding and AI processing features tie vendor margins to NVIDIA and AMD semiconductor pricing, which fluctuates with cryptocurrency mining demand cycles.
- Cloud Infrastructure Concentration:Three hyperscalers control over seventy percent of global server capacity, creating single-point-of-failure risk for multi-tenant capture platforms.
- Browser Security Sandboxing:Chrome and Safari's progressive restriction of screen recording APIs is degrading functionality for web-native tools versus desktop alternatives.
Strategic Opportunities
- India's PLI Scheme for Software:Production-linked incentives for IT exports are enabling cost-competitive R&D centers that can serve price-sensitive emerging markets.
- Telehealth Documentation Mandates:US state-level requirements for recorded patient consultations are creating a regulated vertical with compliance-driven purchasing power.
- Edge-Cloud Hybrid Architectures:Local preprocessing with selective cloud sync addresses data sovereignty concerns while preserving collaboration features for multinational enterprises.
Industry Challenges
- Instructional Design Talent Scarcity:The gap between capture tool capability and internal expertise to produce effective training content is widening, forcing vendors to build managed services arms.
- ISO 27001 Certification Timelines:Enterprise procurement gates now require completed audits, extending sales cycles by six to twelve months for uncertified vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screen and Video Capture Software Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Software, Mobile App, Cloud-based Solution, Browser Extension Deployment: On-premises, SaaS, Hybrid, Public Cloud End User: Educational Institutions, Corporations, Content Creators, Freelancers Feature: Editing Tools, Live Streaming, Screen Recording, Annotation Tools |
| Companies Covered | TechSmith Corporation, Adobe Inc., Wondershare Technology Group Co., Ltd., Atlassian (Loom), Zoom, Microsoft, Google, OBS Project, Riverside, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screen and Video Capture Software Market Evolving Landscape
Browser-based capture architectures are overtaking desktop installations as the dominant delivery mechanism, fundamentally altering how vendors monetize, update, and support their user bases across distributed workforces.
AI-generated chapter markers and searchable transcripts are supplanting manual metadata tagging in enterprise knowledge management workflows. Learning and development departments at technology firms are deploying these tools at scale within eighteen-month refresh cycles. The shift is compressing post-production labor costs while raising expectations for instant content discoverability.
The EU AI Act's risk classification framework for biometric analysis is forcing vendors to segregate facial recognition capabilities into separately governed modules. Industrial consequence includes mandatory human-in-the-loop review for automated identity verification features. European enterprise buyers are now demanding explicit opt-in architectures that US and Asian competitors must retrofit to maintain market access.
Consumption patterns among software buyers are fragmenting from centralized IT procurement to departmental credit-card purchases. Individual team leads now evaluate and adopt tools without enterprise architecture review, displacing traditional vendor-of-record relationships. This shift is most pronounced in North American technology sector employers with flat organizational hierarchies and pre-approved SaaS budgets.
Screen and Video Capture Software Market Segmentation
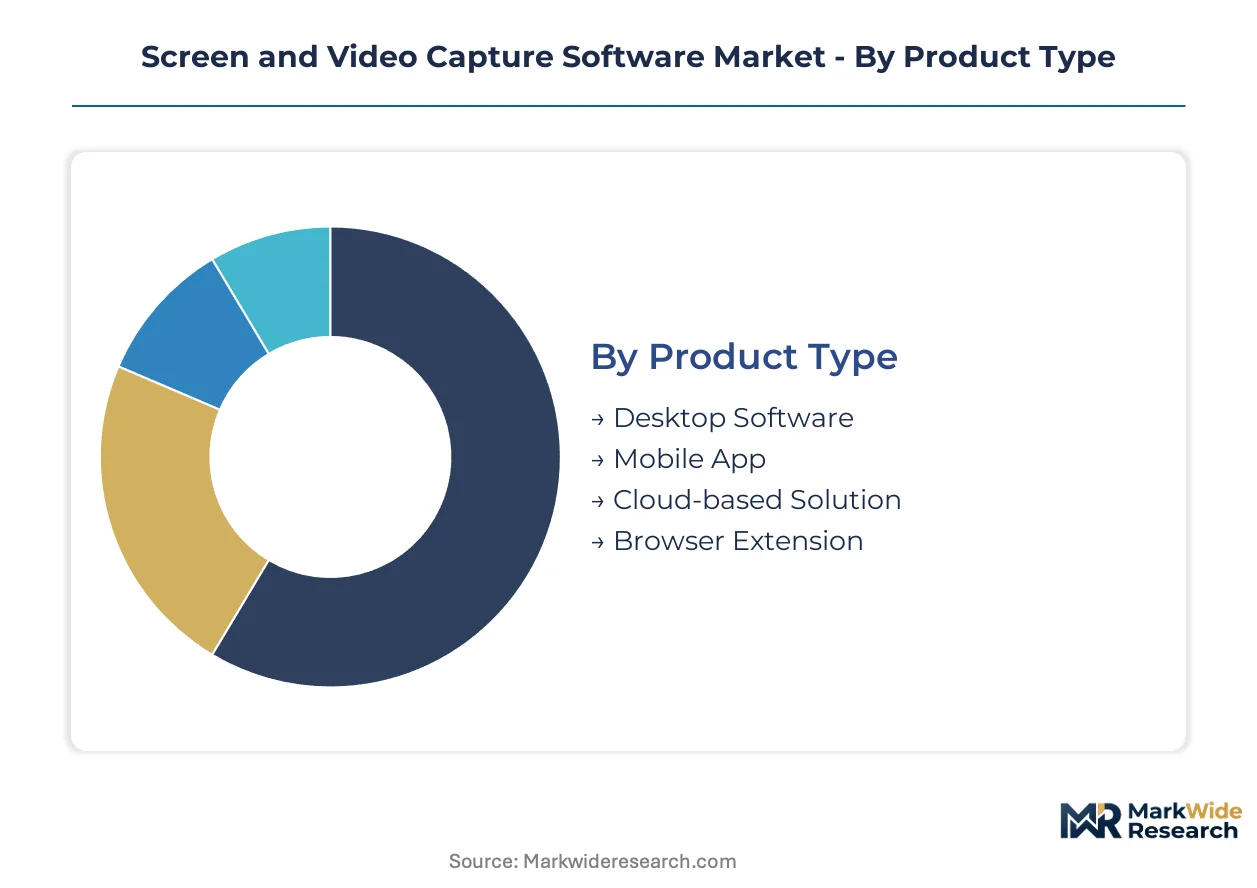
Segmentation in screen and video capture software determines how vendors architect distribution, pricing, and feature roadmaps. Channel preferences vary sharply across deployment models and user sophistication levels, forcing parallel go-to-market strategies.
Product Type:
Desktop software flows through direct download and perpetual license channels, while cloud-based solutions concentrate in SaaS marketplaces and enterprise procurement platforms.
- Desktop Software:Native applications install locally with full codec control and offline processing capability. Technology sector employers with distributed workforces in the United States favor this segment for IP-sensitive workflows requiring local storage control.
- Cloud-based Solution:Browser-delivered platforms with centralized license management and zero-install deployment. European Union Digital Services Act compliance requirements are accelerating enterprise migration toward this architecture for audit-ready consent logging.
- Mobile App:iOS and Android native tools targeting field documentation and asynchronous communication.
- Browser Extension:Lightweight capture utilities distributed through Chrome Web Store and Firefox Add-ons.
Desktop software dominates installed base. Cloud-based solution is where expansion concentrates.
Deployment:
Cost tier alignment shapes deployment selection, with SaaS commanding premium recurring pricing and on-premises retaining total cost of ownership advantages at scale.
- SaaS:Multi-tenant subscription delivery with automatic updates and usage-based scaling. Corporations prioritize this model for reduced customer acquisition costs over multi-year contracts and centralized IT governance.
- On-premises:Self-hosted infrastructure with full data sovereignty and custom security hardening. GDPR compliance mandates in Europe sustain demand here for organizations requiring complete consent management control.
- Hybrid:Edge-cloud architectures with local preprocessing and selective cloud sync.
- Public Cloud:Single-tenant deployments on hyperscaler infrastructure with managed service overlays.
On-premises retains margin stability. SaaS captures volume expansion.
End User:
Application intensity varies by organizational maturity, with educational institutions prioritizing accessibility and corporations demanding integration depth.
- Corporations:Enterprise learning and development teams deploying video-first communication tools at scale. AI-assisted editing and automated captioning address instructional design talent scarcity within internal training departments.
- Freelancers:Independent professionals on Upwork and Fiverr platforms with standardized tool requirements. Asia-Pacific price sensitivity drives preference for localized payment infrastructure and regional server presence.
- Educational Institutions:Universities and K-12 systems with accessibility mandates and limited procurement flexibility.
- Content Creators:YouTube, Twitch, and podcast producers requiring broadcast-grade output formats.
Corporations anchor revenue per seat. Freelancers represent the steepest expansion trajectory.
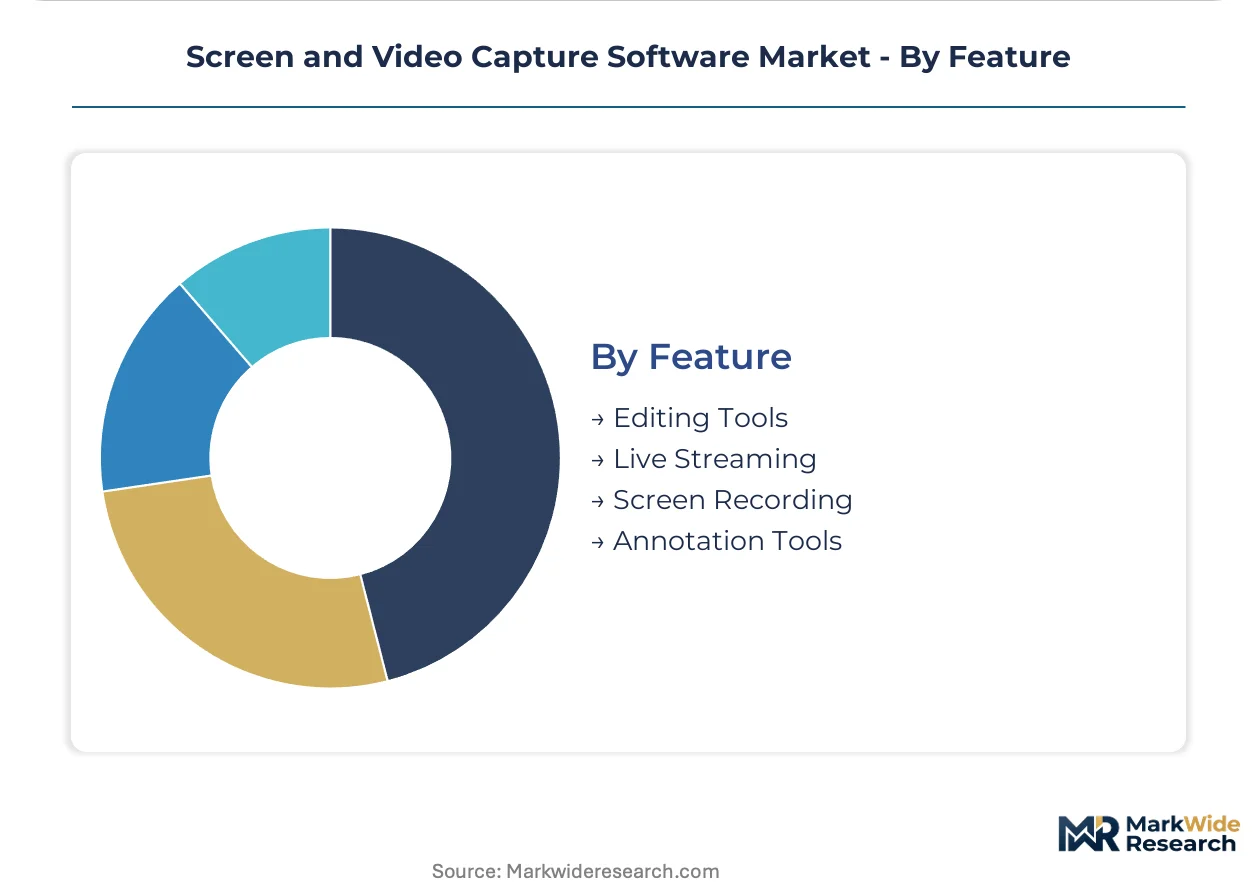
Feature:
Feature bundling correlates with customer lifetime value, with advanced tools commanding higher retention and expansion revenue.
- Screen Recording:Core capture functionality supporting 30 to 60 frames per second with MP4, AVI, and WebM output interoperability. All user segments treat this as table stakes, compressing standalone pricing power.
- Editing Tools:AI-generated chapter markers and searchable transcript capabilities. Learning and development departments at technology firms deploy these features to compress post-production timelines from days to hours.
- Live Streaming:Real-time broadcast to platforms including YouTube Live, Twitch, and enterprise webinar systems.
- Annotation Tools:Overlay drawing, text insertion, and cursor highlighting for instructional clarity.
Screen recording saturates base tiers. Editing tools drive upgrade conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while cost-sensitive deployment patterns dominate India. German and Japanese buyers prioritize compliance architecture over subscription economics. Australia's remote workforce density creates unique feature requirements.
United States
Technology sector employers with distributed workforces drive premium-tier adoption of AI-assisted editing suites. FCC net neutrality frameworks influence vendor cloud infrastructure placement decisions. Seattle and San Francisco Bay Area clusters house headquarters of dominant platform providers shaping enterprise procurement standards.
Germany
Industrial training departments require ISO 27001-certified capture systems with embedded consent logging. GDPR and the EU AI Act mandate segregated biometric processing modules for facial recognition features. Munich and Stuttgart manufacturing hubs sustain demand for on-premises deployment with full data sovereignty controls.
India
Freelancer platforms and gig economy professionals anchor volume expansion through localized payment infrastructure. The PLI scheme for software exports enables cost-competitive R&D centers serving price-sensitive emerging markets. Bangalore and Hyderabad technology corridors concentrate browser-based solution development for regional price points.
Japan
Corporate learning teams demand broadcast-grade output formats with JIS-standard accessibility compliance. METI guidelines for workplace digitalization subsidize training content production tool procurement. Tokyo and Osaka metropolitan areas concentrate enterprise adoption of hybrid edge-cloud architectures.
United Kingdom
Financial services compliance teams require audit-ready capture systems with immutable transcript storage. The Information Commissioner's Office enforces strict consent management for cloud-hosted employee monitoring. London's fintech cluster drives demand for real-time annotation tools supporting regulatory documentation workflows.
Screen and Video Capture Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure. Consolidation pressure intensifies as SaaS recurring revenue models reward scale economies in customer acquisition. Three archetypes dominate: creative ecosystem incumbents, workplace documentation specialists, and browser-native challengers. M&A activity concentrates on AI-assisted editing capabilities, while geographic expansion targets India's PLI-advantaged development centers.
Within the creative ecosystem tier, Adobe Inc. exemplifies cross-platform integration strategies. TechSmith Corporation and Wondershare Technology Group Co., Ltd. occupy positions on opposite ends of the specialization spectrum—deep workplace training focus versus Asia-Pacific freelancer price optimization. Atlassian's Loom acquisition represents the browser-native challenger archetype.
| Leading Market Players |
|---|
| TechSmith Corporation |
| Adobe Inc. |
| Wondershare Technology Group Co., Ltd. |
| Atlassian (Loom) |
| Zoom |
| Microsoft |
| OBS Project |
| Riverside |
| Others |
Value Network & Pricing Analysis
Hyperscaler server capacity utilization above seventy percent creates margin pressure that cascades through SaaS subscription tiers and compresses price floors for desktop alternatives. GPU cost volatility from NVIDIA and AMD semiconductor pricing cycles feeds directly into vendor operating models, forcing tiered pricing structures that segment buyers by processing intensity requirements.
Pricing Analysis
The customization-premium spread separates enterprise-configured deployments with ISO 27001 certification and consent-logging architecture from standard SaaS tiers with shared infrastructure. Three-tier pricing structure across premium, standard, and economy levels aligns with deployment complexity, with GDPR-compliant on-premises configurations commanding the widest spreads. Price differentiation hinges on AI-assisted editing feature depth and automated transcription accuracy tiers. Cost compression in the freelancer segment intensifies because browser-native challengers commoditize base screen recording functionality. Asia-Pacific independent professionals exhibit highest price sensitivity; United States technology sector employers with distributed workforces show lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Strait of Malacca submarine cable transit underwrites latency-critical cloud synchronization for Asia-Pacific capture platform users. Geographic supply concentrates in the United States for hyperscaler infrastructure, Taiwan for advanced GPU fabrication, and Ireland for European data residency compliance. Raw material dependencies span NVIDIA A100/H100 accelerators, high-bandwidth memory modules, and subsea fiber capacity. Single-source vulnerability in GPU supply creates procurement risk for AI-enabled transcription features. Distribution runs through direct enterprise sales for on-premises deployments and SaaS marketplaces for browser-native solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among enterprise learning and development teams with centralized SaaS procurement authority, fragmenting from traditional IT gatekeepers toward departmental credit-card purchasers with pre-approved tool budgets.
For Market Incumbents: Secure ISO 27001 certification completion to close six-to-twelve-month sales cycle gaps against audit-ready competitors. Invest in managed services arms addressing instructional design talent scarcity, converting software margin into recurring consulting revenue. Channel control through exclusive freelancer platform partnerships on Upwork and Fiverr defends against browser-native challengers. For New Entrants and Emerging Players: ISO 27001 fast-track completion opens enterprise procurement gates currently closed to uncertified vendors. India's PLI scheme for software exports enables cost-competitive R&D centers serving price-sensitive emerging markets with localized payment infrastructure. Telehealth documentation mandates in United States state regulations create a compliance-driven vertical with concentrated purchasing power and limited incumbent saturation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among browser-native challengers with departmental land-and-expand models. Five-to-ten-year viability favors platforms with edge-cloud hybrid architectures addressing data sovereignty divergence without user experience fragmentation. Acquisition target archetype: AI-assisted editing specialists with searchable transcript capabilities deployed at technology firms. The signal to watch is European enterprise buyer migration toward explicit opt-in architectures under EU AI Act biometric processing rules.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Adobe Creative Cloud ecosystem cross-sell embeds screen capture into existing creative workflows. |
| Acquisition of Specialist Firm | Atlassian's Loom purchase demonstrates browser-native challenger consolidation for distributed workforce tooling. |
| Geographic Expansion | India's PLI scheme enables cost-competitive development centers serving Asia-Pacific freelancer price points. |
| Strategic Partnership | Upwork and Fiverr native screen capture requirements standardize tool selection across gig economy platforms. |
| Product Launch | Edge-cloud hybrid architectures address GDPR and EU AI Act compliance while preserving collaboration features. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with learning and development directors, IT procurement officers, platform engineers, and freelance content creators. Secondary validation drew from SEC filings, hyperscaler capex disclosures, App Annie mobile download data, and EU regulatory filings. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against SaaS marketplace transaction data anchored value estimates.
Across the analysis window, projections model deployment model, organization size, vertical integration complexity, and regional adoption pattern segmentation. CAGRs derive from installed base migration rates and new subscriber acquisition curves calibrated against cloud infrastructure expansion timelines. AI-assisted editing penetration curves and browser-native solution displacement rates inform growth trajectory assumptions.
The analysis sits within stated boundaries; outcomes outside sustained GPU supply normalization and stable hyperscaler pricing would require recalibration. Forecasts reflect documented assumptions regarding enterprise SaaS transition velocity and regulatory compliance timeline adherence. Practitioners should keep alternative scenarios live as EU AI Act enforcement patterns and FCC net neutrality framework evolution reshape vendor architecture requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Data Center Backup and Recovery Software Market
Software & Services
Global Voip Software Market
Software & Services
Grant Management Software Market
Software & Services
Know Your Customer Software Market
Software & Services
Global Appointment Reminder Software Market
Software & Services
Global Performance Appraisal Software Market
Software & Services
India HR Payroll Software Market
Software & Services
Mobile Device Management (MDM) Market
Software & Services
Global Data Quality Software Market
Software & Services
Global Cloud Enterprise Resource Planning Market
Software & Services
Service Scheduling Software Market
Software & Services
Global Advanced Planning and Scheduling (APS) Software Market
Software & Services
Global Jewelry Store Management Software Market
Software & Services
Global Application Performance Monitoring (APM) Market
Software & Services
POS Software Market
Software & Services
AR Remote Collaboration Software Market